
 Luxury Sunglass Market | 2026-2036
Luxury Sunglass Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Sunglass Market Foresight
The capital-intensity divergence between vertically integrated manufacturers and brand-licensing operators is rotating competitive advantage toward those controlling in-house acetate milling and lens coating facilities. EssilorLuxottica leverages its integrated supply chain from raw material to retail shelf. Kering Eyewear anchors its position through selective licensing with hard luxury maisons. Safilo Group competes by sustaining long-term manufacturing partnerships with heritage European brands.
Luxury sunglasses are precision optical accessories combining UV-filtering lenses with haute couture frames, typically manufactured through multi-stage acetate lamination or CNC-milled titanium processes to achieve both ANSI Z80.3 optical standards and aesthetic distinction. The aviator and wayfarer silhouettes remain margin-dominant classics, while cat-eye frames capture faster growth among female demographics in Asia-Pacific markets. Titanium construction commands the highest material-tier pricing due to its strength-to-weight ratio and hypoallergenic properties, though acetate retains volume leadership across accessible luxury and super premium tiers.
The EU's REACH chemicals framework and FDA's impact resistance requirements for prescription-ready sunglass lenses shape material selection and testing protocols for brands accessing transatlantic markets. CE marking under the EU's Personal Protective Equipment Regulation further governs UV protection claims and optical clarity standards. Stakeholders must monitor tightening disclosure obligations under the EU Green Deal's product environmental footprint rules, which will force material provenance transparency without grandfathering existing inventory lines.
Market Dynamics
EU Green Deal disclosure mandates are forcing immediate material provenance transparency across acetate and titanium supply chains, eliminating grandfathering for existing inventory lines and compressing reformulation timelines for heritage manufacturers.
Growth Catalysts
- Affluent Traveler Segment Expansion:Resort-goers and luxury hospitality guests are elevating sunglasses from accessory to essential travel gear, with destination retail capturing higher conversion rates than traditional channels.
- EU Green Deal Pressure:The product environmental footprint rules are accelerating supplier consolidation toward certified sustainable material sources, advantaging early-compliant manufacturers.
- Titanium Fabrication Advances:CNC milling precision improvements are reducing waste rates in hypoallergenic frame production, expanding accessibility of premium material-tier offerings.
Market Restraints
- Acetate Supply Concentration:Italian milling clusters control premium cellulose acetate sheet production, creating single-source vulnerability for non-integrated brands.
- REACH Chemical Friction:ECHA substance restrictions on plasticizers and solvents are forcing reformulation of legacy frame lamination processes without ready substitutes.
- Prescription-Ready Impact Standards:FDA 21 CFR 801.410 impact resistance requirements add testing cost layers for brands pursuing optical dual-use positioning.
Strategic Opportunities
- Asia-Pacific Female Demographics:Cat-eye frame preferences among professional women in South Korea and Japan represent underpenetrated demand for specialized silhouette development.
- Repair and Resale Channels:Circular economy service models are emerging as distinct revenue streams, with authentication and refurbishment capabilities differentiating heritage houses.
- CE Marking PPE Alignment:The EU's Personal Protective Equipment Regulation UV protection claims pathway offers premium positioning for clinically validated lens technologies.
Industry Challenges
- Master Craftsman Scarcity:Multi-stage acetate lamination and hand-finishing expertise concentrates among aging artisans in Northern Italy, with limited apprenticeship pipeline replacement.
- Lens Coating Capital Intensity:Anti-reflective and mirror deposition equipment requires seven-figure facility investments, constraining independent brand verticalization.
- Dual Certification Timelines:Parallel FDA and CE marking pathways for prescription-capable sunglasses extend time-to-market by 8-14 months for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Sunglass Market |
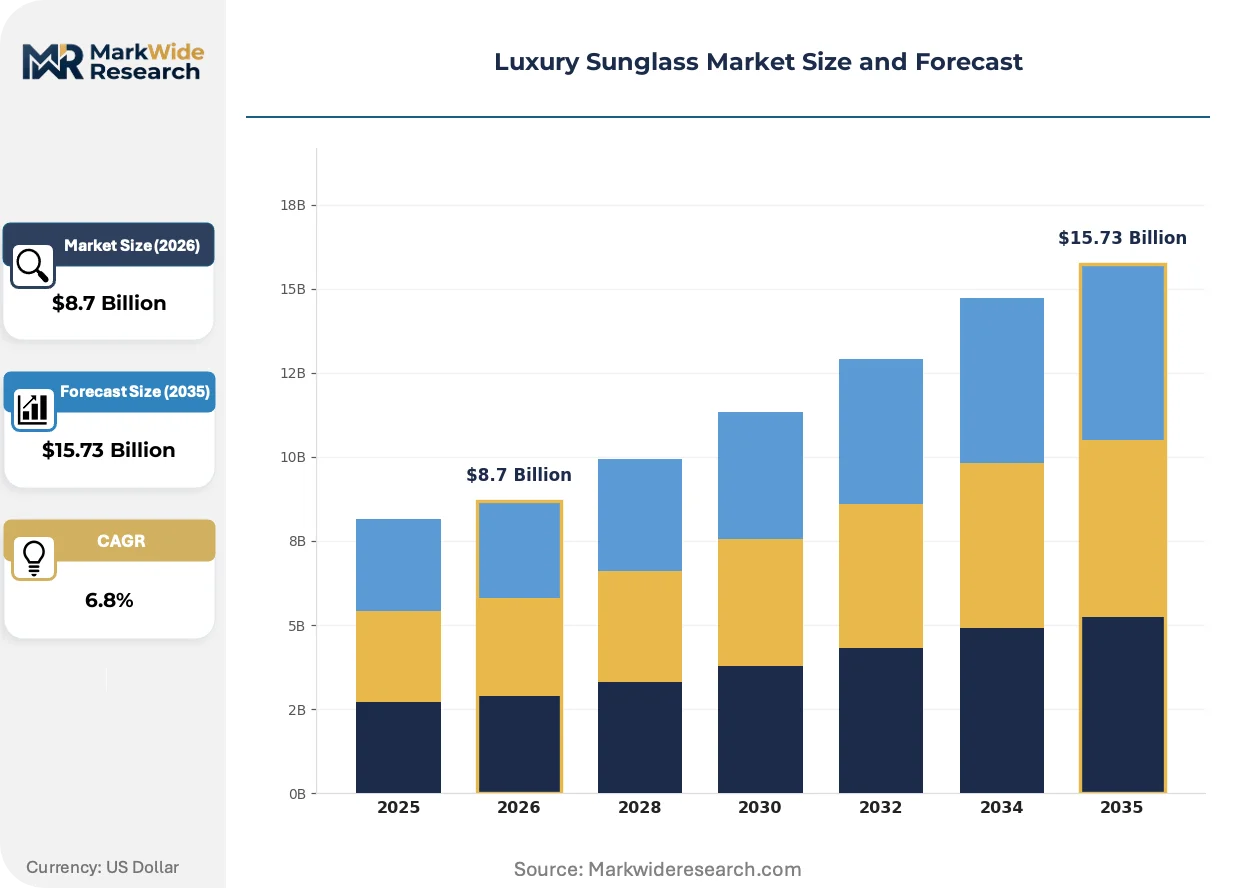
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cat Eye, Round, Aviator, Wayfarer Material: Acetate, Metal, Titanium, Polycarbonate Customer Type: Men, Women, Unisex, Kids Price Tier: Premium, Super Premium, Accessible Luxury, Discounted Luxury |
| Companies Covered | EssilorLuxottica, Kering Eyewear, Safilo Group, Tom Ford, Gucci, Prada, Chanel, Versace, Cartier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Sunglass Market Shifts & Advancements
Bio-based material substitution, regulatory disclosure automation, and direct-to-consumer authentication technologies are converging to reshape competitive requirements across the value chain.
Plant-derived acetate alternatives derived from wood pulp and cotton linter are decomposing petroleum-based cellulose dominance in premium frame production. Milan-based design houses and Japanese precision manufacturers are adopting these materials at pilot scale. The shift is compressing reliance on traditional petrochemical supply chains while introducing new batch-consistency challenges.
REACH SCIP database integration is mandating automated substance-of-concern disclosure across EU-bound product lines. Manufacturers must now trace and report candidate list chemicals through every production tier. Smaller licensing operators lacking ERP integration face compliance cost disadvantages against integrated supply chain owners.
Resort and airport duty-free channels are fragmenting as younger affluent buyers prioritize brand-owned digital flagship experiences over traditional travel retail. Authentication-enabled resale platforms are capturing post-purchase engagement previously owned by authorized dealers. This behavioral pivot is most pronounced among South Korean and Chinese consumers purchasing titanium-tier products.
Luxury Sunglass Market Segmentation
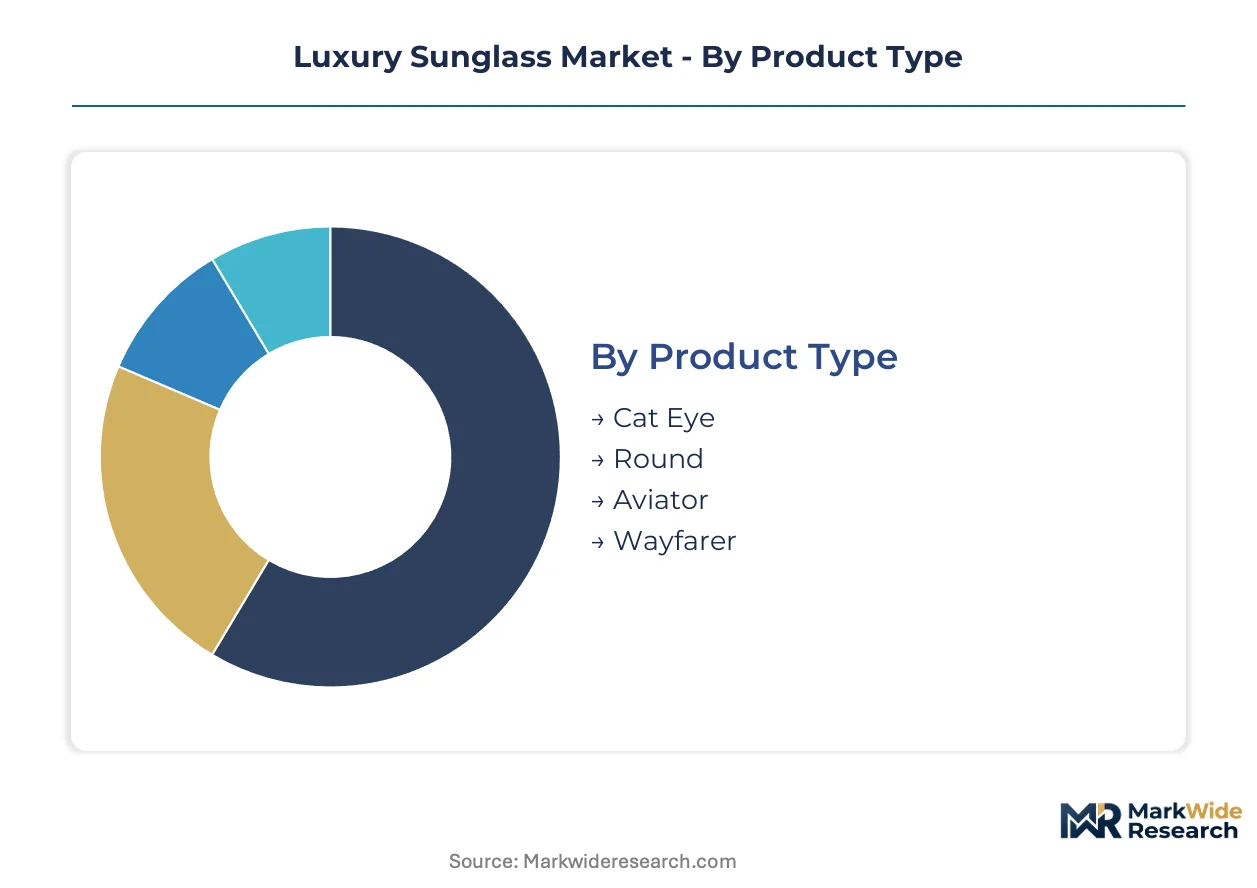
Segmentation in luxury sunglasses reveals how channel strategy, material sourcing, and demographic targeting create distinct competitive arenas. Each dimension carries specific margin implications and regulatory exposure that shape manufacturer positioning.
Product Type:
Channel distribution varies sharply by silhouette, with duty-free retail favoring classic shapes while direct-to-consumer platforms drive experimental designs.
- Aviator:Teardrop-shaped metal frames with double bridge construction originated as military pilot equipment. Resort retail in the Maldives and Dubai captures the highest conversion rates for titanium-grade aviators among male business travelers.
- Wayfarer:Trapezoidal acetate frames with signature rivet detailing define accessible luxury tier aesthetics. Italian design houses in Milan sustain volume leadership through heritage licensing partnerships with hospitality groups.
- Cat Eye:Upward-sweeping temples and angular rims target professional women in South Korea and Japan, where specialized silhouette development commands price premiums over unisex alternatives.
- Round:Circular lens mounts in metal or acetate construction appeal to vintage-inspired segments, with strongest traction in Berlin and Copenhagen design retail circuits.
Aviator and wayfarer silhouettes dominate installed base. Cat eye is where expansion concentrates.
Material:
Cost tier stratification aligns with fabrication complexity and capital requirements, from commodity injection molding to seven-figure CNC milling investments.
- Acetate:Multi-stage cellulose lamination enables color layering and hand-polished finishes. Northern Italian milling clusters control premium sheet production, creating single-source vulnerability for non-integrated brands facing REACH plasticizer restrictions.
- Titanium:Hypoallergenic CNC-milled frames achieve superior strength-to-weight ratios. Japanese precision manufacturers lead deposition coating integration for mirror and anti-reflective finishes.
- Metal:Stainless steel and monel alloy constructions balance durability with mid-tier pricing, dominating airport duty-free volumes through heritage brand licensing.
- Polycarbonate:Injection-molded frames serve entry accessible luxury tiers with limited UV protection certification pathways under CE marking PPE rules.
Acetate commands volume leadership across premium tiers. Titanium is climbing the fastest on margin contribution.
Customer Type:
Volume concentration and margin capture diverge between gender-targeted design development and unisex scaling economies.
- Women:Specialized silhouette R&D including cat-eye and oversized rounds drives highest per-unit margins. South Korean and Japanese professional demographics sustain above-average replacement frequency.
- Men:Classic aviator and wayfarer preferences favor heritage brand loyalty with lower SKU proliferation requirements. Resort retail conversion exceeds digital channels for this segment.
- Unisex:Scaled production across neutral silhouettes reduces per-style inventory risk. Direct-to-consumer authentication platforms capture growing share of post-purchase engagement.
- Kids:Limited prescription-ready impact certification and smaller addressable volume constrain dedicated product development outside licensed character collaborations.
Women's specialized designs dominate margin contribution. Unisex scaling is where volume expansion concentrates.
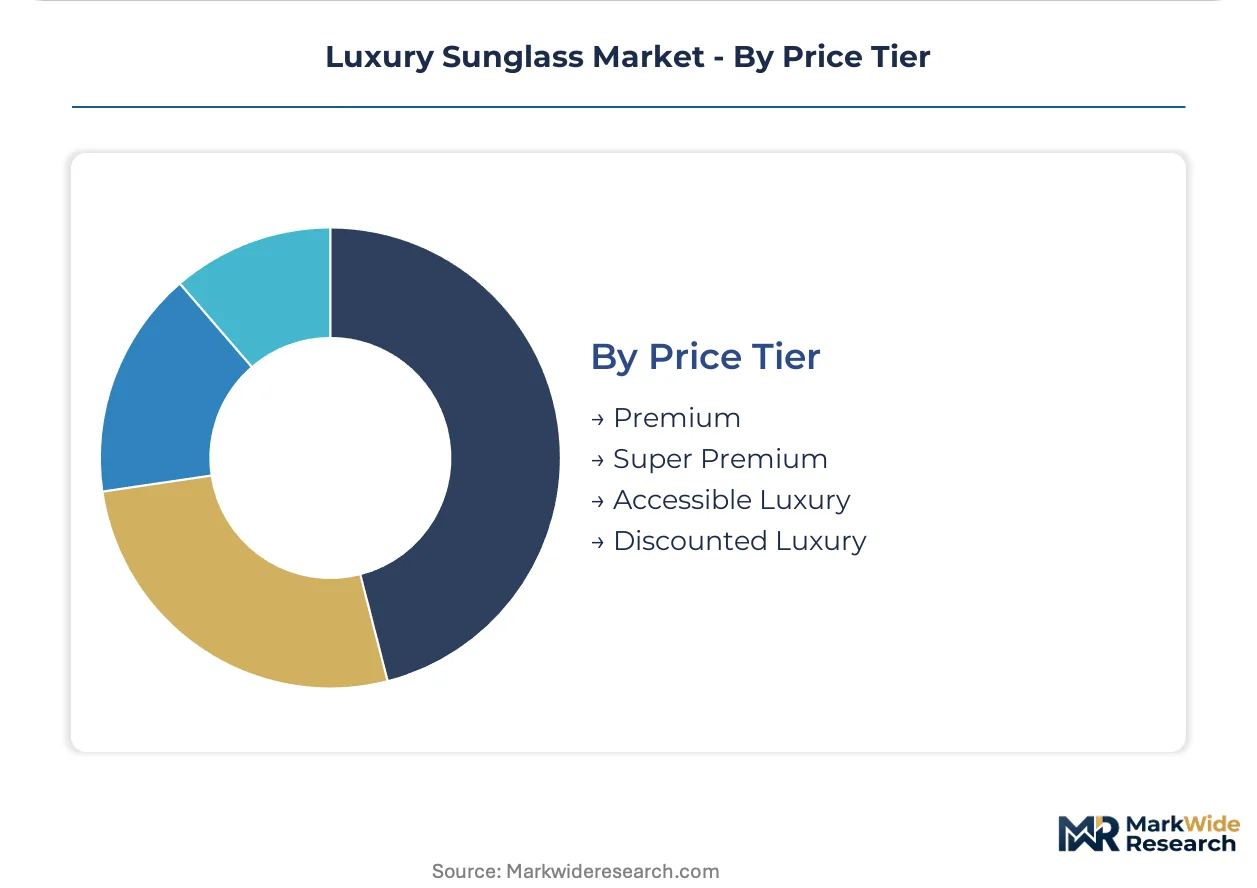
Price Tier:
Certification grade and material provenance transparency create sharp stratification under EU Green Deal disclosure mandates.
- Super Premium:Titanium construction with clinical lens validation and hand-finished acetate variants. Milan-based maisons and Japanese precision manufacturers anchor positioning through controlled scarcity.
- Premium:Italian-milled acetate and metal alloy frames with full UV protection certification. Heritage licensing partnerships with European fashion houses sustain channel access.
- Accessible Luxury:Polycarbonate and standard acetate constructions targeting first-time luxury purchasers. Digital flagship experiences capture younger affluent buyers abandoning traditional travel retail.
- Discounted Luxury:Prior-season inventory and authentication-enabled resale platforms. Circular economy service models emerge as distinct revenue streams with refurbishment capabilities.
Premium and super premium tiers dominate installed base. Accessible luxury digital channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Italian manufacturing clusters while Asian markets capture volume expansion through specialized silhouette demand. Regulatory divergence between REACH-mandated EU transparency and FDA prescription-ready standards creates compliance arbitrage across transatlantic supply chains.
United States
Resort retail in Miami and Scottsdale drives titanium-tier conversion among domestic business travelers. FDA 21 CFR 801.410 impact resistance requirements add testing layers for prescription-capable product lines. Los Angeles-based design studios pilot direct-to-consumer authentication platforms for circular economy resale channels.
Italy
Milan's design houses anchor super-premium positioning through controlled scarcity of hand-finished acetate variants. EU Green Deal product environmental footprint rules force immediate material provenance disclosure without grandfathering existing inventory. The Lombardy manufacturing corridor concentrates multi-stage lamination expertise among aging artisan networks with limited apprenticeship pipelines.
Japan
Professional women in Tokyo and Osaka sustain above-average replacement frequency for specialized cat-eye silhouettes. METI standards govern precision manufacturing protocols for hypoallergenic frame production. Osaka-based fabricators lead CNC milling integration with deposition coating capabilities for mirror and anti-reflective finishes.
South Korea
Seoul's professional demographics drive fastest-growing demand for titanium construction among female purchasers. MFDS cosmetic-grade material standards influence frame biocompatibility certification pathways. Gangnam district flagship stores capture shifting preference toward brand-owned digital experiences over traditional duty-free channels.
France
Parisian heritage houses leverage licensing partnerships for accessible luxury tier penetration. ANSM oversight of consumer product safety intersects with REACH SCIP database mandates for substance-of-concern tracing. The Île-de-France region concentrates brand headquarters functions while manufacturing relies on Italian acetate milling supply.
Luxury Sunglass Market Competitive Landscape
Concentration sits with vertically integrated optical conglomerates controlling raw material through retail shelf positioning. EssilorLuxottica exemplifies this archetype through captive acetate milling and lens coating facilities. Kering Eyewear occupies the selective licensing tier partnering with hard luxury fashion houses. Safilo Group sustains relevance through long-term manufacturing partnerships with heritage European brands. Competitive moves center on supplier consolidation for EU Green Deal compliance and direct-to-consumer channel expansion bypassing traditional wholesale.
Among Italy-anchored integrated operators, EssilorLuxottica represents the full-value-chain archetype from material sourcing to retail network control. Kering Eyewear and Safilo Group exemplify contrasting positioning strategies within the same geographic cluster. Kering Eyewear sits within the luxury licensing tier leveraging fashion house brand equity. Safilo Group occupies the manufacturing partnership tier sustaining production relationships with established European labels.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Kering Eyewear |
| Safilo Group |
| Tom Ford |
| Gucci |
| Prada |
| Chanel |
| Versace |
| Cartier |
| Others |
Supply & Pricing Matrix
Plant-derived acetate alternatives displacing petroleum-based cellulose are simultaneously shifting procurement geography toward Nordic pulp suppliers and compressing material-tier pricing differentials that once favored Italian petrochemical-sourced sheet stock. Buyers now face recalibrated cost structures where bio-based batch inconsistency introduces new quality-grade premiums alongside traditional certification markups.
Pricing Analysis
Configured-to-order hand-finishing commands spreads of 40-60% above standard production runs for identical base silhouettes. Pricing stratifies across super-premium titanium with clinical lens validation, premium Italian-milled acetate with full UV certification, and accessible luxury polycarbonate tiers. Cost compression in mid-tier metal alloys is intensifying because Japanese precision manufacturers are expanding CNC milling capacity. Resort retail buyers show lowest price sensitivity; digital-first accessible luxury purchasers exhibit highest elasticity.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes are extending inbound logistics timelines for titanium billet shipments from Japanese fabricators to Lombardy finishing facilities. Concentrated supply rests on Italian acetate milling clusters, Japanese CNC precision manufacturers, and Chinese lens substrate foundries. Raw material dependencies span cellulose acetate sheet stock, titanium aerospace-grade billet, and rare-earth coating deposition materials. Single-source vulnerability concentrates in Northern Italian lamination expertise. Distribution runs through duty-free resort channels, brand-owned flagships, and authentication-enabled resale platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among vertically integrated optical conglomerates controlling captive retail networks, fragmenting negotiating leverage for independent licensing operators dependent on wholesale access.
For Market Incumbents: Secure captive acetate milling capacity before EU Green Deal disclosure mandates eliminate grandfathering for existing inventory lines. Deepen backward integration into bio-based material pilot programs to preempt Nordic supplier consolidation. Lens coating equipment ownership represents the critical defensive lever against margin erosion from shared-fabrication competitors. For New Entrants and Emerging Players: Anchor in Seoul and Tokyo's underserved professional female demographics where specialized cat-eye silhouettes command price premiums over unisex alternatives. Target authentication-enabled resale platform partnerships as the most penetrable channel bypassing heritage brand wholesale gatekeeping. Direct-to-consumer flagship experiences offer the clearest go-to-market angle for titanium-tier positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed licensing operators lacking ERP integration for REACH SCIP database compliance. Five-to-ten year viability hinges on regulatory adaptation speed rather than brand equity alone. Watch for ECHA substance restriction announcements as the inflection indicator forcing distressed consolidation among non-compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Material Transition | Milan design houses adopting wood-pulp acetate preempt EU Green Deal penalties. |
| Direct-to-Consumer Flagship Expansion | Seoul Gangnam stores capture affluent buyers abandoning airport duty-free channels. |
| Authentication-Enabled Resale Platform Launch | Heritage houses monetize circular economy engagement previously owned by dealers. |
| REACH SCIP Database Integration | Automated disclosure compliance separates integrated manufacturers from licensing operators. |
| Titanium CNC Capacity Expansion | Japanese fabricators reduce waste rates while expanding hypoallergenic frame accessibility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs records, and hospitality retail audit data across the projection horizon. Primary interviews engaged supply chain directors at Italian milling clusters, licensing operators in Paris and Milan, and procurement leads at Japanese precision fabricators. Secondary sources encompassed ECHA REACH substance databases, EU CE marking PPE registration logs, and FDA 21 CFR optical device filings. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates.
Segmentation dimensions modeled span material tier, silhouette category, distribution channel, and customer gender targeting across the analysis window. CAGRs derived from historical volume trajectories adjusted for regulatory phase-in schedules and material substitution elasticities. Forecast inputs incorporated EU Green Deal compliance cost pass-through assumptions and titanium fabrication yield improvement curves.
Material uncertainties — ECHA substance list expansions, bio-based acetate batch consistency failures, and resort retail demand volatility — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory grandfathering deadlines and artisan apprenticeship pipeline replacement rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Smart Eyewear Market
Eyewear
Europe Eyewear Market
Eyewear
Spectacles Market
Eyewear
Reading Glasses Market
Eyewear
Smart Sunglasses Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market
Eyewear
Face and Ear Bow Market
Eyewear
3D Printing in Eyewear Market
Eyewear
United States Eyewear Market
Eyewear
Latin America Eyewear Market
Eyewear
Eyeglass Market
Eyewear
Sunglasses Market
Eyewear
Wooden Eyewear Market
Eyewear
Asia-Pacific Eyewear Market
Eyewear
North America Eyewear Market