
 Blue Light Glasses Market | 2026-2036
Blue Light Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Blue Light Glasses Market Analysis
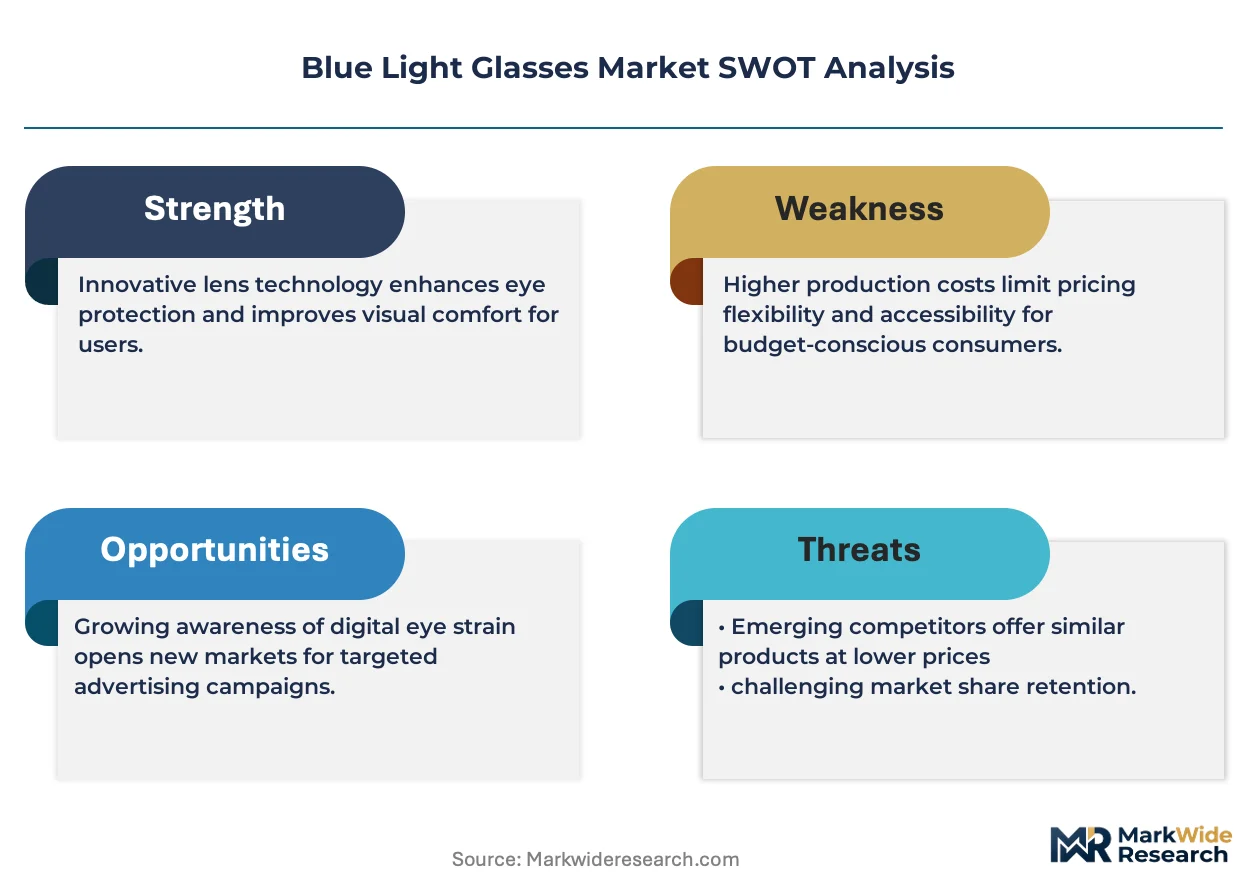
Bundle configurations that pair blue light lenses with blue light screen filters and ergonomic accessories is pivoting how employers and individual buyers evaluate value. Zenni Optical leverages its vertically integrated online platform to anchor volume in the non-prescription segment. Felix Gray specializes in fashion-forward frames that compete on aesthetic differentiation rather than clinical positioning alone.
Blue light glasses are optical eyewear incorporating lens coatings or substrates engineered to attenuate high-energy visible light in the 400–450 nanometer range, primarily serving to reduce digital eye strain and circadian rhythm disruption from prolonged screen exposure. Polycarbonate lenses dominate material selection due to impact resistance and lightweight properties, while Trivex occupies a premium niche for users prioritizing optical clarity alongside blue light filtration. Prescription glasses command the deepest margin pools as optometric channels bundle vision correction with protective coatings, whereas clip-ons represent a fast-growing entry point for consumers reluctant to purchase dedicated frames.
FDA oversight of medical device claims and FTC advertising standards constrain how manufacturers position health benefits, while OSHA ergonomic guidelines indirectly validate employer-subsidized procurement. The EU's REACH regulation and CE marking requirements for personal protective equipment create divergent compliance obligations across Atlantic supply chains. Stakeholders must monitor whether emerging ophthalmology research validates or narrows the therapeutic claims that currently justify premium pricing tiers.
Market Dynamics
Employer-subsidized procurement programs are restructuring volume flows toward B2B channels, while REACH-mandated coating reforms are forcing upstream material substitutions across European supply chains.
Growth Catalysts
- OSHA-aligned occupational guidelines:Screen-time health advisories in the United States validate employer-funded protective eyewear programs for remote and hybrid workforces.
- Polycarbonate substrate innovation:Impact-resistant, lightweight lens materials reduce unit costs while maintaining optical performance standards for mass-market penetration.
- EU Green Deal procurement mandates:Public and corporate purchasing frameworks increasingly require recyclable frame materials and elimination of hazardous surface coatings.
Market Restraints
- Petrochemical feedstock volatility:Polycarbonate and Trivex resin prices fluctuate with crude oil derivatives, compressing margin stability for lens manufacturers.
- East Asian coating chemical concentration:Specialized anti-reflective and blue-filter coating production clusters in China and South Korea create single-source dependencies.
- FDA medical device claim constraints:Therapeutic positioning for circadian rhythm benefits faces evidentiary scrutiny, limiting premium pricing justification.
Strategic Opportunities
- Underpenetrated Indian white-collar workforce:IT services and business process outsourcing sectors in Bangalore and Hyderabad present untapped B2B volume potential.
- Convergence of blue light filtration with photochromic technology:Dual-function lenses address indoor screen use and outdoor light sensitivity in single SKUs.
- Corporate wellness program expansion:Fortune 500 HR departments are bundling protective eyewear with ergonomic workstation subsidies as retention tools.
Industry Challenges
- Ophthalmic optician certification bottlenecks:Prescription lens fitting requires licensed professionals, constraining direct-to-consumer scaling.
- CE marking timeline compression:Personal protective equipment reclassification under EU MDR extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blue Light Glasses Market |
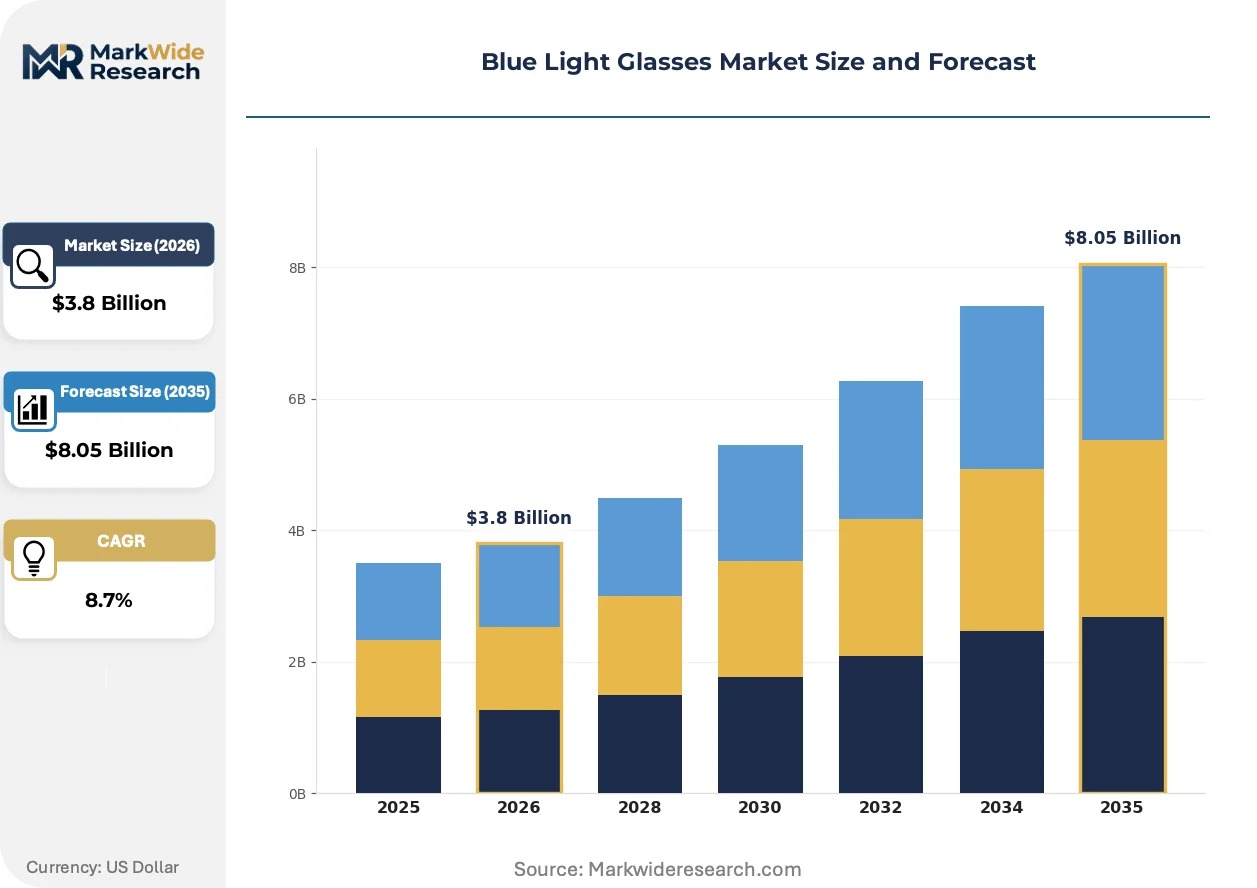
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Glasses, Non-Prescription Glasses, Clip-Ons, Lenses Material: Polycarbonate, Glass, Plastic, Trivex End User: Consumers, Professionals, Students, Gamers Distribution Channel: Online Retail, Optical Stores, Supermarkets, Pharmacies |
| Companies Covered | Tijn, BlockBlueLight, Benicci, Peepers, Zenni Optical, Felix Gray, Gunnar, Pixel Eyewear, Warby Parker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blue Light Glasses Market Emerging Trajectories
Material science advances and regulatory chemistry reforms are redefining product architecture, while employer purchasing behavior is shifting volume toward bundled occupational health solutions.
Trivex substrate technology is overtaking conventional polycarbonate in premium prescription segments due to superior optical clarity and comparable impact resistance. High-income individual buyers and specialized occupational health programs are absorbing the 30-40% unit cost premium. This displacement is compressing mid-tier positioning and forcing volume players to defend margin through coating differentiation rather than substrate innovation.
REACH authorization requirements for chromium and nickel compounds in metal frame plating are eliminating legacy electroplating processes across EU manufacturing footprints. ECHA substance restriction timelines are accelerating adoption of bio-based acetates and recycled titanium alloys. German and French frame producers are restructuring supplier relationships to secure compliant material streams ahead of 2027 sunset dates.
Employer reimbursement models are displacing individual out-of-pocket purchasing as the dominant transaction structure in professional segments. Corporate benefits administrators are negotiating direct contracts with optical retailers, bypassing traditional insurance intermediaries. This concentration is most visible in United States technology and financial services sectors, where remote work policies have normalized screen-time mitigation as standard occupational health provision.
Blue Light Glasses Market Segmentation
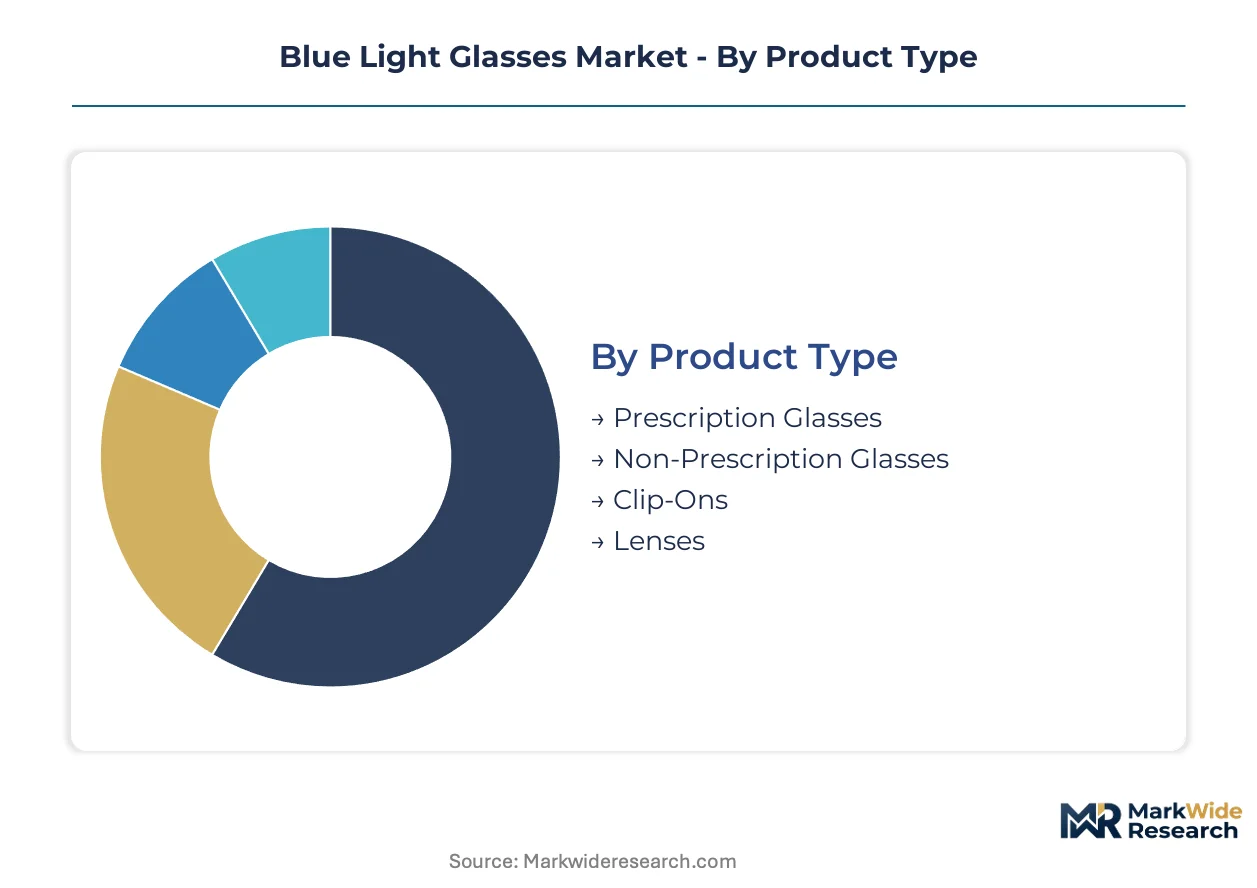
Segmentation in blue light eyewear reveals divergent margin profiles and capital requirements across prescription fulfillment, material substrates, and channel economics. Understanding these divisions clarifies where coating innovation, regulatory compliance, and B2B procurement create sustainable competitive positions.
Product Type:
Prescription fulfillment demands the heaviest upfront investment due to optometric network integration and lens customization infrastructure.
- Prescription Glasses:These combine vision correction with blue light filtration through integrated lens coatings or substrate modifications. Corporate wellness programs in the United States subsidize these through direct optical retailer contracts, bypassing traditional insurance intermediaries. Optometric channel bundling with eye exams sustains premium positioning.
- Non-Prescription Glasses:Mass-market SKUs target screen-time mitigation without vision correction, competing on frame aesthetics and coating efficacy claims. Zenni Optical's vertically integrated online platform dominates volume through aggressive pricing and rapid fulfillment.
- Clip-Ons:Entry-point accessory converting existing eyewear with detachable blue-filter lenses. Budget-conscious consumers and occasional screen users favor this minimal-commitment format.
- Lenses:Replacement lens sales for frame retention, requiring precise optical measurements and coating compatibility verification.
Prescription Glasses absorb the bulk of installed capacity; Clip-Ons are expanding most quickly as employers distribute them as low-cost remote work provisions.
Material:
Substrate selection stratifies across optical clarity, impact resistance, and petrochemical input exposure.
- Polycarbonate:Dominant lens material combining lightweight properties with shatter resistance. Mass-market penetration depends on stable crude derivative pricing for resin feedstocks.
- Trivex:Premium alternative delivering superior optical clarity with comparable impact resistance. High-income individual buyers and specialized occupational health programs absorb the 30-40% unit cost premium, compressing mid-tier positioning for volume players.
- Glass:Traditional substrate with exceptional scratch resistance but weight penalties limiting extended wear comfort.
- Plastic:Cost-driven generic formulations serving entry-tier price points with reduced durability trade-offs.
Polycarbonate commands current volume leadership; Trivex claims the steepest expansion trajectory as premium prescription segments prioritize optical performance.
End User:
User categories reflect distinct procurement mechanisms and screen exposure intensity.
- Consumers:Individual purchasers responding to sleep quality concerns and digital eye strain symptoms through discretionary retail channels.
- Professionals:Employer-subsidized acquisition dominates, with OSHA-aligned occupational guidelines validating protective eyewear as standard remote work provision in United States technology and financial services sectors.
- Students:Educational institutional procurement remains fragmented, with university health services piloting limited distribution programs.
- Gamers:Esports and streaming demographics prioritize frame comfort during marathon sessions, driving specialized ergonomic designs.
Professionals channel the highest per-unit revenue through corporate benefits administrators; Gamers are gaining share fastest as peripheral manufacturers cross-sell eyewear with hardware ecosystems.
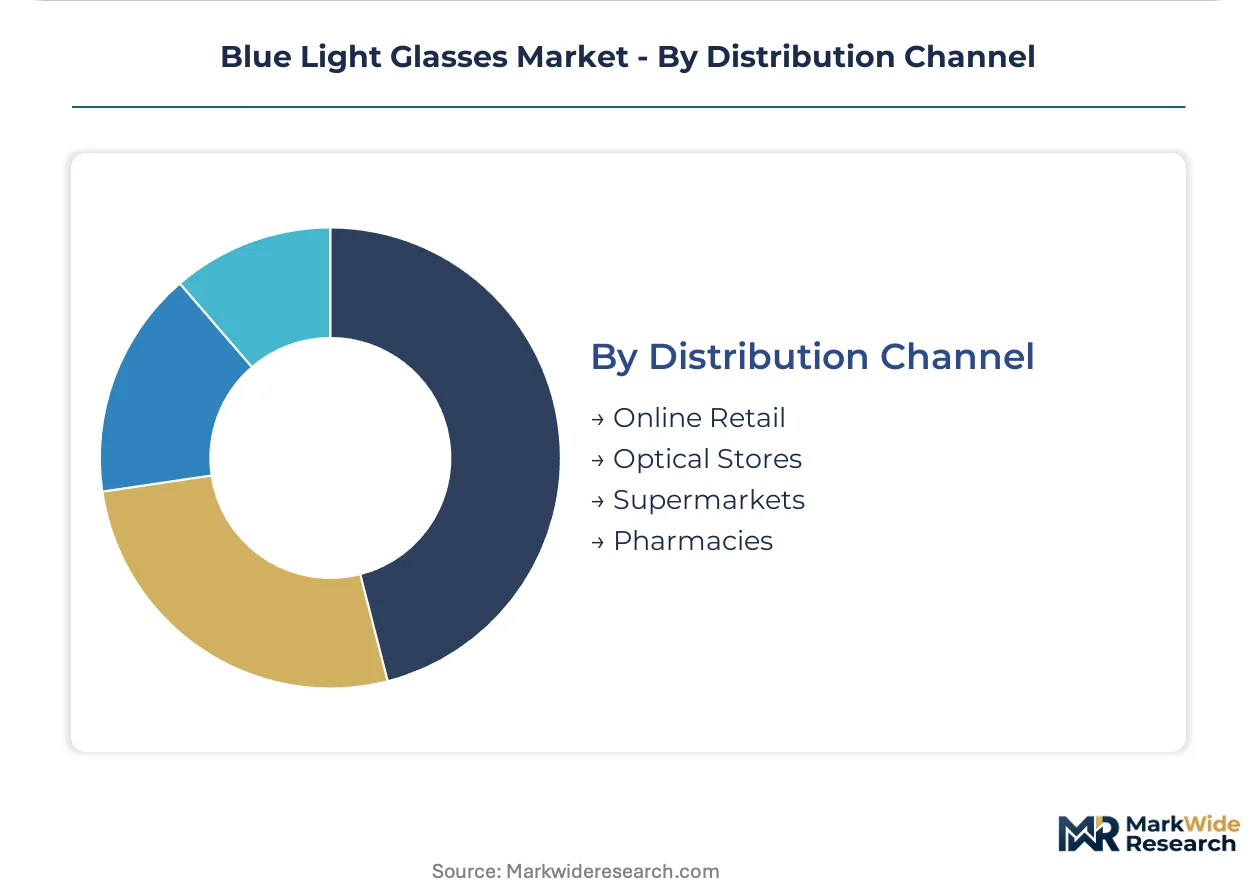
Distribution Channel:
Channel economics determine margin capture and customer acquisition cost structures.
- Online Retail:Direct-to-consumer platforms leverage virtual try-on technology and rapid fulfillment to displace traditional optical intermediaries. Felix Gray competes here on fashion-forward aesthetic differentiation.
- Optical Stores:Licensed optician presence enables prescription verification and lens fitting, sustaining premium pricing despite higher overhead.
- Supermarkets:Mass merchandisers stock limited non-prescription assortments targeting impulse purchases and seasonal promotions.
- Pharmacies:Health-and-wellness positioning aligns with sleep aid and supplement adjacencies, though optical expertise remains minimal.
Online Retail concentrates volume growth; Optical Stores defend margin through prescription bundling and professional fitting services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian coating chemical clusters while consumption tilts toward North American and European professional segments. Remote work normalization and occupational health regulations are redrawing procurement geography.
United States
Employer-subsidized protective eyewear programs dominate volume, with OSHA-aligned screen-time advisories validating corporate wellness spending. FTC advertising standards constrain therapeutic claims for circadian rhythm benefits. Technology and financial services firms in San Francisco and New York Metro negotiate direct optical retailer contracts, bypassing traditional insurance channels.
Germany
REACH-mandated coating reforms are eliminating chromium and nickel compounds from metal frame plating ahead of 2027 sunset dates. ECHA substance restrictions accelerate bio-based acetate adoption. Frame producers in Munich and Stuttgart restructure supplier relationships to secure compliant material streams for EU Green Deal procurement mandates.
China
Specialized anti-reflective and blue-filter coating production clusters in Jiangsu and Guangdong provinces supply global lens manufacturers. MIIT standards for optical product quality create domestic compliance layers. NMPA oversight of medical device claims limits therapeutic positioning for local brands targeting export markets.
India
IT services and business process outsourcing sectors in Bangalore and Hyderabad present untapped B2B volume potential. BIS certification requirements for eyewear quality create entry barriers for unorganized producers. White-collar workforce expansion in Telangana and Karnataka drives employer-funded protective eyewear pilots.
Japan
Corporate health management programs subsidize blue light filtration for remote workers under METI occupational guidelines. JIS standards for optical performance differentiate premium positioning. Precision manufacturing clusters in Nagoya supply high-clarity Trivex substrates for regional prescription fulfillment.
Blue Light Glasses Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across prescription fulfillment, fashion positioning, and gaming peripherals. Market structure tilts toward fragmentation as direct-to-consumer platforms erode traditional optical retail concentration. Three archetypes dominate: vertically integrated online retailers, fashion-forward lifestyle brands, and occupational health specialists. Competitive moves center on B2B corporate contract acquisition and coating technology differentiation rather than substrate innovation.
Within the online retail archetype, Zenni Optical anchors volume positioning through platform integration. Felix Gray exemplifies aesthetic differentiation competing on frame design rather than clinical claims alone. Gunnar occupies the gaming-specialist tier, cross-selling eyewear with peripheral hardware ecosystems. These three represent distinct strategic vectors: price-accessibility, fashion-premium, and performance-specialist.
| Leading Market Players |
|---|
| Tijn |
| BlockBlueLight |
| Benicci |
| Peepers |
| Zenni Optical |
| Felix Gray |
| Gunnar |
| Pixel Eyewear |
| Warby Parker |
| Others |
Supply Flow & Price Mechanics
Premium-mid-economy pricing differentiation separates Trivex prescription lenses from polycarbonate mass-market SKUs from clip-on accessories, with each tier sourcing through distinct coating chemical clusters and frame material supplier networks. REACH-mandated coating reforms in Germany and France compress margin pools for metal frame producers while bio-based acetate suppliers capture pricing power.
Pricing Analysis
Margin tightening in prescription fulfillment reflects optometric channel bundling with eye exams and licensed fitting services. Three-tier pricing structure across premium, standard, and economy levels tracks substrate selection and coating certification tiers. Cost-down pressure on polycarbonate mass-market units accelerates because Zenni Optical's vertically integrated platform anchors price ceilings. Individual consumers show highest price sensitivity; corporate benefits administrators absorb premium tiers through occupational health budgets.
Supply Chain Analysis
Workforce availability constraints in Jiangsu and Guangdong provinces limit coating chemical output expansion for anti-reflective and blue-filter formulations. Manufacturing draws from South Korean specialty chemical producers and Chinese resin compounders for polycarbonate and Trivex substrates. Single-source vulnerability concentrates in East Asian coating clusters. Distribution runs through direct optical retailer contracts for corporate wellness programs, bypassing traditional insurance intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH authorization timelines and ECHA substance restrictions erect barrier-to-entry moats for frame producers with secured bio-based acetate supply chains.
For Market Incumbents: Acquire compliant material streams ahead of 2027 sunset dates for chromium and nickel compounds. Frame producers in Munich and Stuttgart should lock bio-based acetate supplier relationships before REACH-mandated reforms eliminate legacy electroplating. Capacity addition in Nagoya for Trivex substrate production defends premium positioning against polycarbonate commoditization.
For New Entrants and Emerging Players: Corporate benefits administrators represent the most penetrable channel partner type for bypassing traditional insurance intermediaries. White-collar IT services sectors in Bangalore and Hyderabad offer untapped B2B volume. Gaming peripheral cross-selling with esports hardware ecosystems provides lowest-friction customer acquisition.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated online platforms given employer reimbursement model displacement of individual purchasing. Five-to-ten year viability favors direct-to-consumer specialists with captive coating technology. Watch FDA evidentiary scrutiny of circadian rhythm therapeutic claims as inflection indicator for premium pricing justification.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Technology Acquisition | REACH-compliant anti-reflective formulations secure EU market access ahead of 2027 deadlines. |
| Corporate Wellness Partnership | Direct contracts with Fortune 500 HR departments bypass insurance intermediary margin extraction. |
| Bio-Based Material Transition | Recyclable acetate and recycled titanium alloys satisfy EU Green Deal procurement mandates. |
| Photochromic Convergence R&D | Dual-function lenses addressing indoor screen use and outdoor sensitivity expand addressable SKU base. |
| Indian B2B Market Entry | Bangalore and Hyderabad IT services employers pilot protective eyewear for remote workforces. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with optical retailer procurement directors, corporate benefits administrators, frame manufacturing plant managers, and ophthalmic optician network coordinators validated volume assumptions. ECHA substance restriction databases, FDA medical device registration files, and EU Green Deal procurement disclosure records provided regulatory boundary conditions. Bottom-up SKU-level modeling triangulated against top-down employer spending estimates.
Segmentation-level granularity modeled product type, material substrate, end-user category, and distribution channel dimensions across the analysis window. CAGRs derived from employer reimbursement program adoption curves and coating technology substitution rates. Trivex penetration trajectories in premium prescription segments and clip-on volume expansion in remote work provisions informed growth rate calibration.
Several conditions sit outside the modeled scope, including NMPA regulatory shifts affecting Chinese export positioning and BIS certification timeline changes for Indian market entry. Forecasts reflect assumptions about OSHA guideline alignment with employer wellness spending. Material deviation in ophthalmology research validating or narrowing therapeutic claims warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Eyewear Market
Eyewear
Europe Eyewear Market
Eyewear
Latin America Eyewear Market
Eyewear
Polarized Sunglasses Market
Eyewear
Reading Glasses Market
Eyewear
Smart Eyewear Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Luxury Sunglass Market
Eyewear
Goggles Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Anti-Fog Lens Market
Eyewear
Glasses Frame Market
Eyewear
Smart Sunglasses Market
Eyewear
Ultralight Eyeglass Frames Market
Eyewear
Wooden Eyewear Market
Eyewear
Spectacles Market