
 Sunglasses Pouch Market | 2026-2036
Sunglasses Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Sunglasses Pouch Market Analysis
China is reconfiguring sunglasses pouch supply chains through concentrated microfiber and neoprene production in Wenzhou and Wuxi. Wuxi Xinya Micro Fibrous Co. Ltd. leverages its fibrous material expertise to anchor the microfiber segment with consistent export quality. Wenzhou Classic Packing Co. Ltd. sustains cost-competitive leather and fabric pouch lines through integrated regional tooling networks. Decathlon SA competes on volume by controlling direct-to-retail channel access across its global sporting goods footprint.
A sunglasses pouch is a protective enclosure, typically constructed from microfiber, neoprene, leather, or woven fabric with closure mechanisms such as drawstrings, zippers, or magnetic fasteners, designed to prevent lens scratching and frame damage during transport and storage. Manufacturing employs die-cutting, ultrasonic sealing, and stitched seam construction with thickness tolerances optimized for crush resistance and moisture wicking. Microfiber and neoprene material categories dominate current volume due to their balance of unit cost and protective performance, while leather pouches command higher margin pools in premium eyewear channels. The sports enthusiasts target customer segment shows the fastest structural expansion as athletic eyewear brands bundle protective accessories with performance sunglasses.
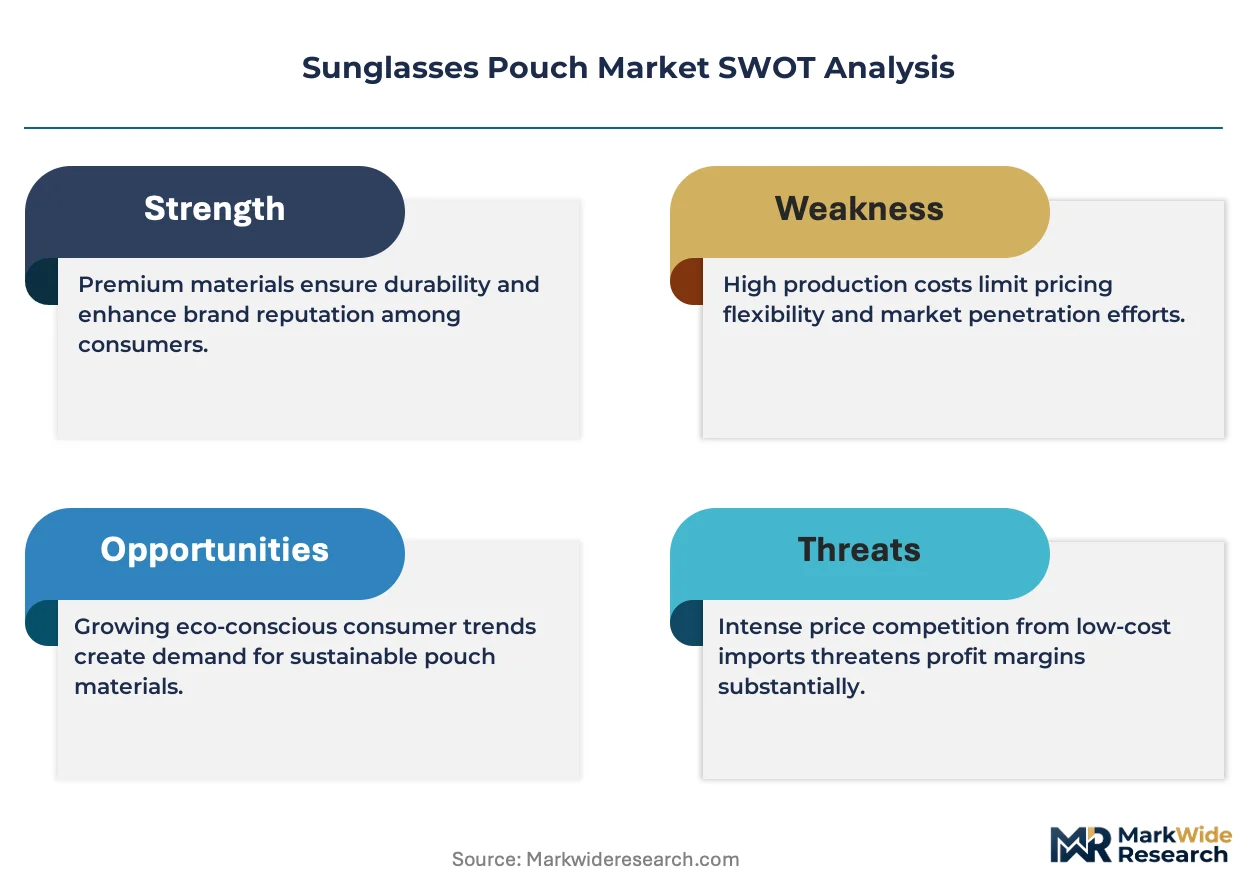
EU REACH and RoHS frameworks restrict hazardous substance content in synthetic pouch materials, compelling Asian exporters to certify dye and adhesive chemistries before European market access. The US Consumer Product Safety Commission monitors small-part choking hazards in children-targeted pouch closures, influencing magnetic and zipper design specifications. Stakeholders must monitor evolving material certification requirements and closure safety standards to maintain cross-border shipment eligibility without supply interruption.
Market Dynamics
Wenzhou and Wuxi manufacturing clusters now control the majority of global sunglasses pouch volume, creating supply-side concentration that shapes pricing power and procurement risk for downstream eyewear brands.
Growth Catalysts
- REACH and RoHS frameworks:European chemical compliance mandates are accelerating certified synthetic material adoption, pushing Asian suppliers toward verified dye and adhesive chemistries that unlock premium channel access.
- Athletic eyewear bundling:Sports enthusiasts represent the fastest-expanding customer segment as performance sunglasses brands integrate protective pouches into standard product packaging.
- Microfiber substrate innovation:Recycled microfiber production advances in Wuxi industrial zones are lowering unit costs while maintaining lens-scratch protection standards demanded by optical retailers.
Market Restraints
- Petrochemical input volatility:Neoprene and synthetic microfiber production remains exposed to oil-derived feedstock price swings, compressing margin stability for mid-tier pouch manufacturers.
- Single-region supply concentration:Overreliance on Wenzhou tooling networks creates vulnerability to regional logistics disruptions or trade policy adjustments affecting Zhejiang export corridors.
- Leather alternative performance gaps:Plant-based and lab-grown leather substitutes still fail to match genuine leather's tactile premium perception in luxury eyewear channels, limiting material transition speed.
Strategic Opportunities
- India domestic market expansion:BIS certification alignment and rising sunglass consumption in Mumbai and Delhi create white space for localized pouch production serving South Asian eyewear distributors.
- Direct-to-retail channel bypass:E-commerce platform integration allows specialized pouch manufacturers to capture margin previously allocated to sporting goods wholesale intermediaries.
- EU Green Deal circularity incentives:Recycled content mandates and extended producer responsibility frameworks reward suppliers with verified closed-loop microfiber recovery systems.
Industry Challenges
- REACH certification timeline compression:European chemical safety documentation requirements demand 12-18 month pre-market validation cycles that strain smaller supplier cash conversion periods.
- Ultrasonic sealing technician scarcity:Specialized equipment operation and die-cutting precision skills concentrate in aging Wenzhou workforce pools, constraining production scaling for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sunglasses Pouch Market |
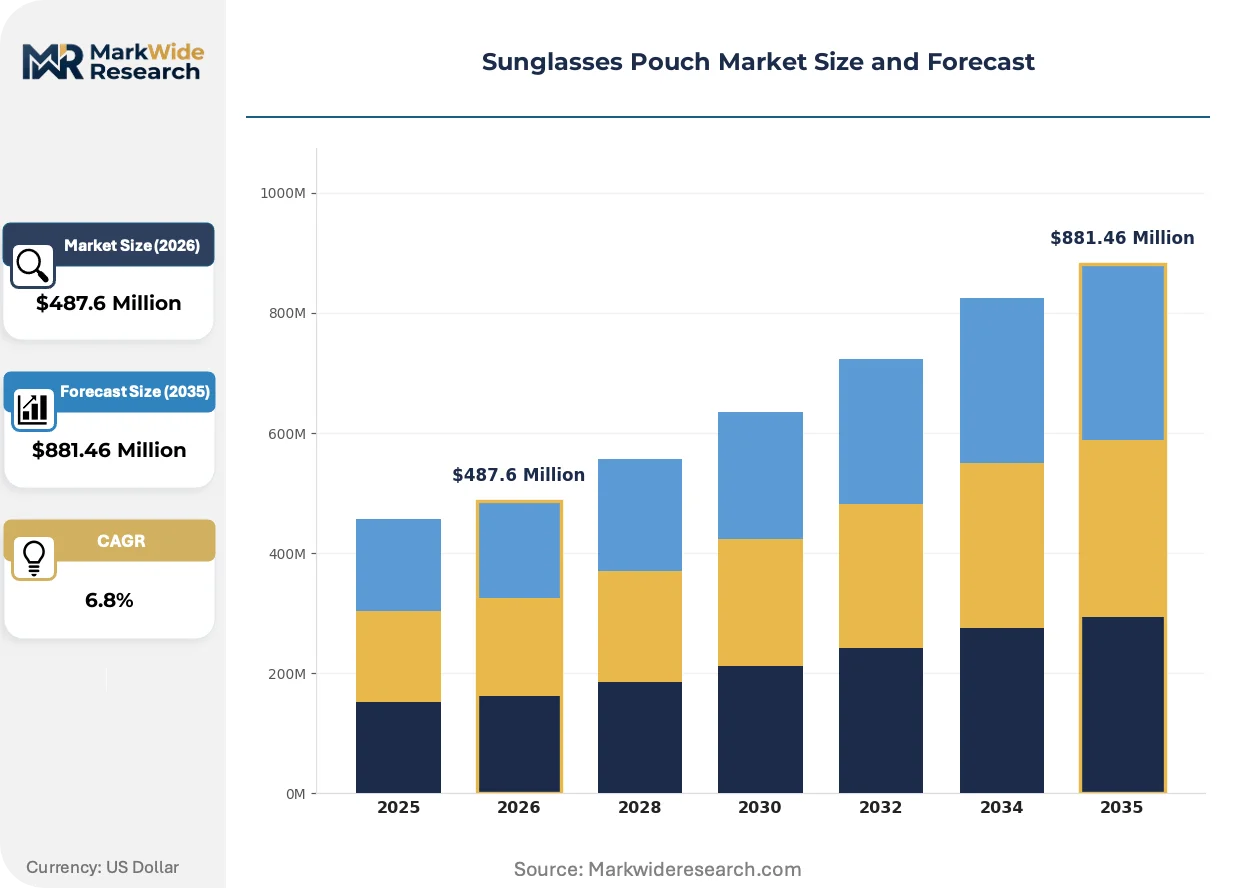
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Leather, Fabric, Neoprene, Microfiber Closure Type: Drawstring, Zipper, Velcro, Magnetic Size: Small, Medium, Large, Extra Large Target Customer: Men, Women, Kids, Sports Enthusiasts |
| Companies Covered | Celyfos, Hide and Sleek Leather Goods, Hesh Opto Lab Private Limited, Interpol Eyewear, Wenzhou Classic Packing Co. Ltd., North End Bag Company, Talfourd Jones LLC, Wuxi Xinya Micro Fibrous Co. Ltd., Decathlon SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sunglasses Pouch Market Emerging Trajectories
Digital traceability systems and sustainable material science are restructuring how sunglasses pouches are specified, verified, and distributed across fragmented eyewear supply chains.
Blockchain-enabled material provenance tracking is digitizing supply chain transparency for microfiber and neoprene substrates. Premium eyewear brands in Germany and Italy now require lot-level fiber origin documentation. This technology is digitizing compliance verification workflows that previously relied on paper certificate chains, compressing supplier onboarding cycles from quarters to weeks.
ECHA substance database expansions under REACH are tightening restricted chemical lists for textile dyes and adhesive formulations used in pouch closure assembly. Asian exporters must now pre-certify each color variant through accredited EU laboratories. Small-batch leather pouch producers in Wenzhou face disproportionate testing cost burdens relative to microfiber volume manufacturers.
Buyers are consolidating pouch procurement under centralized eyewear brand accessory programs rather than fragmented regional supplier relationships. This pattern concentrates order volume with manufacturers capable of multi-material, multi-closure SKU flexibility. The shift is most visible in North American sporting goods retail, where private-label pouch specifications now travel through single-source vendor managed inventory agreements.
Sunglasses Pouch Market Segmentation
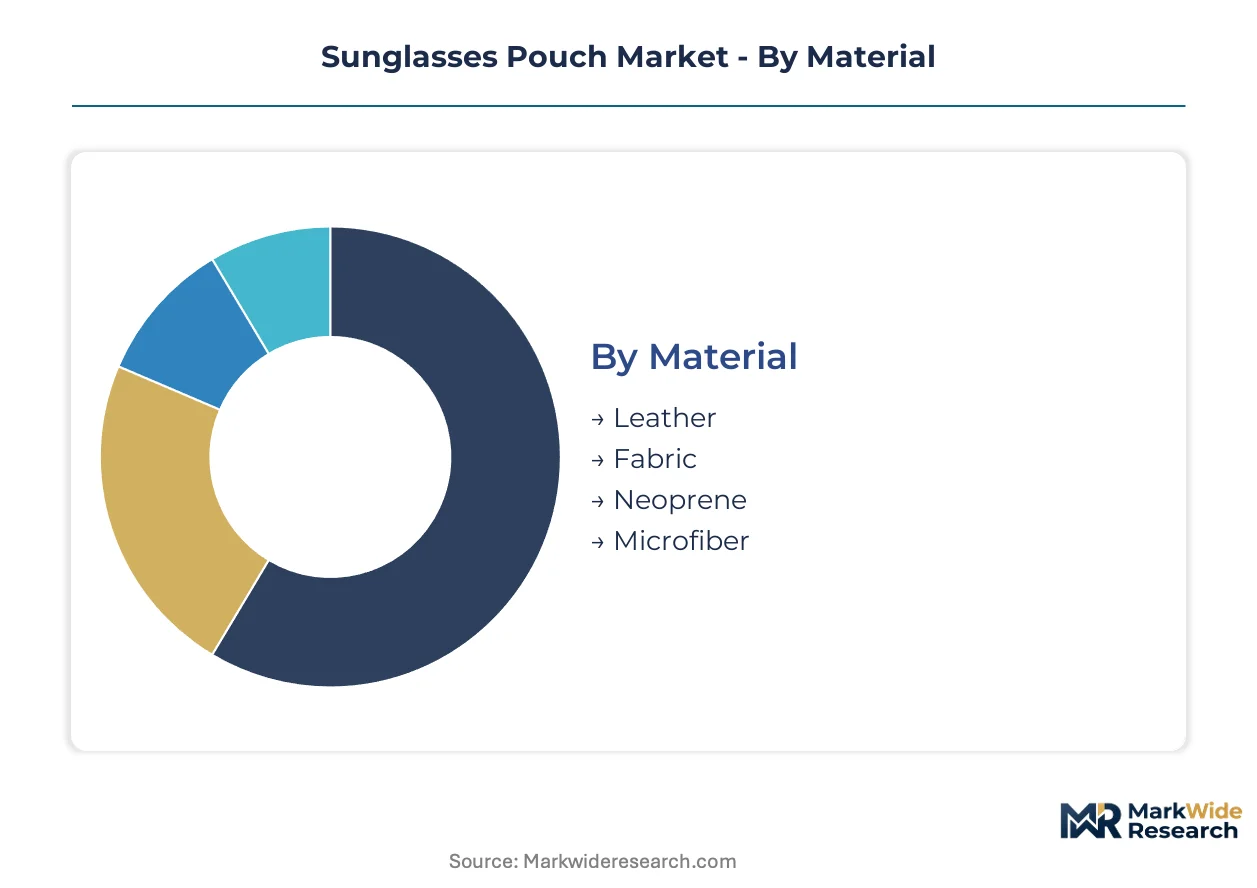
Sunglasses pouch segmentation reveals how material selection, closure mechanics, and sizing specifications map to distinct channel economics and replacement cycle patterns. Each dimension carries implications for inventory turns, warranty exposure, and aftermarket revenue capture.
Material:
After-sales service intensity varies sharply across material tiers, with premium substrates demanding specialized cleaning protocols and defect remediation that extend brand touchpoints beyond the initial sale.
- Microfiber:Synthetic filament construction delivers lens-safe surface contact through ultra-fine fiber density below 1 denier. Wenzhou and Wuxi manufacturing clusters supply the majority of global volume, with recycled substrate variants gaining traction under EU Green Deal circularity incentives. By volume, microfiber leads. By growth pace, recycled microfiber grades are expanding most quickly.
- Neoprene:Chloroprene rubber foam provides crush resistance and moisture insulation for athletic and marine eyewear applications. Petrochemical feedstock exposure creates margin volatility that mid-tier manufacturers struggle to pass through sporting goods procurement contracts.
- Leather:Tanned hide substrates command premium positioning in optical retail channels, with Italian and Argentine sourcing dominating luxury tier specifications. REACH dye certification requirements impose 12-18 month validation cycles on small-batch producers.
- Fabric:Woven cotton and synthetic blends occupy economy positioning through die-cut simplicity and ultrasonic sealing compatibility, serving promotional and fast-fashion eyewear bundling programs.
Material selection directly determines warranty claim rates and return logistics complexity across distribution channels.
Closure Type:
Closure mechanism engineering shapes unit economics through assembly labor content and small-part safety compliance burdens, particularly in children-targeted product lines.
- Drawstring:Cord-and-bead mechanisms offer lowest unit cost and highest production velocity in Wenzhou tooling networks. CPSC monitoring of bead detachment hazards has tightened design specifications for youth SKUs.
- Zipper:Coil and metal zipper assemblies add durability for high-frequency access patterns in professional and athletic use cases. ECHA restrictions on nickel-plated slider components are forcing stainless steel substitutions in EU-bound shipments.
- Magnetic:Neodymium or ferrite magnetic clasps enable single-hand operation for driving and cycling applications. Closure strength calibration must balance accessibility against accidental opening during transport.
- Velcro:Hook-and-loop fastening suits adjustable sizing requirements and temporary storage scenarios, though fiber contamination limits adoption for precision optical surfaces.
Closure complexity correlates with average selling price tier, though magnetic mechanisms are gaining share fastest in performance eyewear channels.
Size:
Dimensional standardization reflects eyewear frame geometry diversity and retail packaging cube optimization for e-commerce fulfillment economics.
- Small:Compact enclosures for slim wire-frame and reading glass formats, minimizing material waste and shipping dimensional weight charges.
- Medium:Universal fit specifications accommodating mainstream acetate and metal frames, dominating wholesale volume through one-size-fits-most procurement efficiency.
- Large:Oversized constructions for aviator, shield, and fashion-forward frame profiles with extended temple lengths.
- Extra Large:Bulk storage and multi-pouch travel configurations serving collector and professional athlete inventory management needs.
Medium sizing commands the volume base, while extra-large formats are climbing fastest through travel retail and direct-to-consumer gifting segments.
Target Customer:
Demographic targeting aligns pouch aesthetics and functional claims with eyewear category purchasing patterns and replacement frequency.
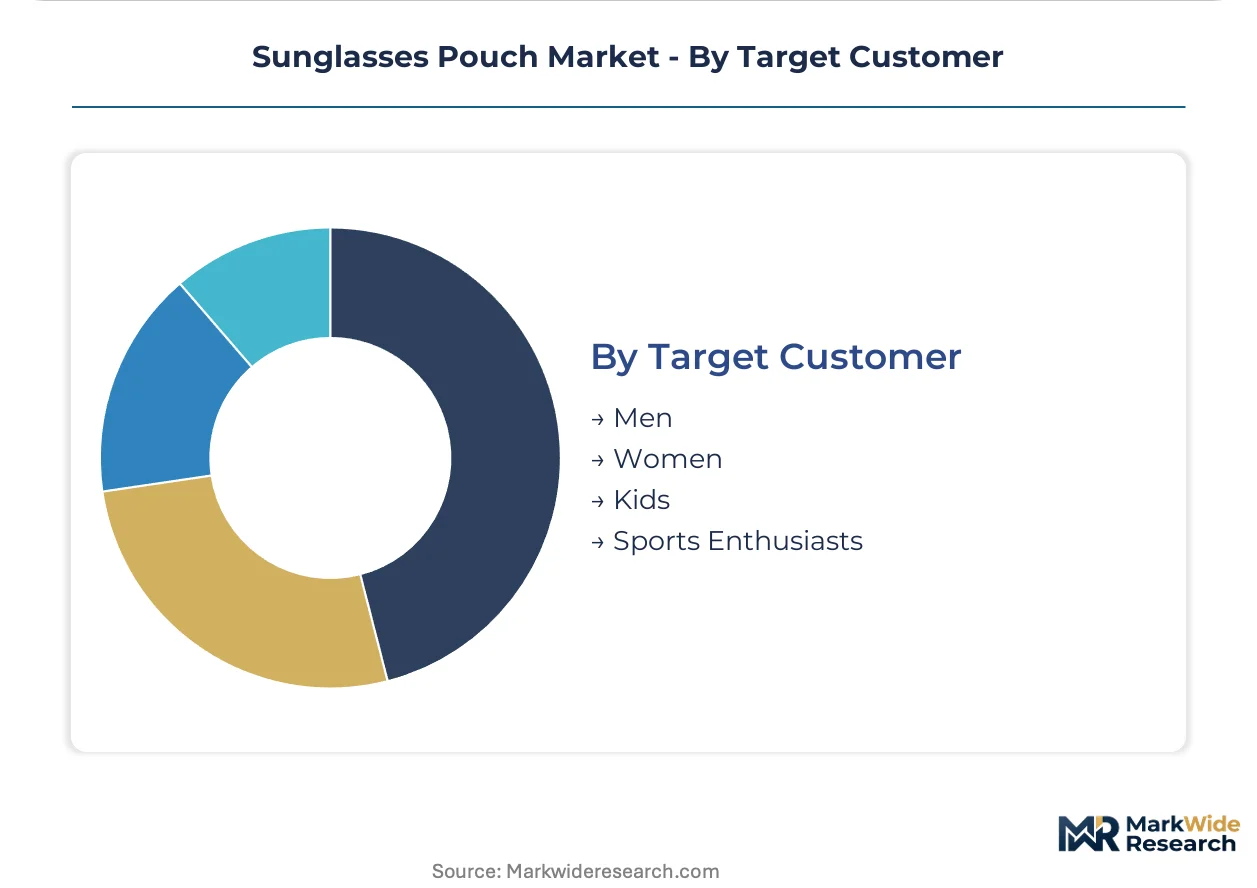
- Sports Enthusiasts:Performance-oriented designs integrate moisture-wicking liners and carabiner attachments for kit bag integration. Athletic eyewear brands bundle protective accessories as standard packaging, making this the steepest expansion trajectory.
- Women:Fashion-forward colorways and compact clutch-compatible dimensions align with accessory purchasing behavior in optical retail and department store channels.
- Men:Neutral palettes and minimalist construction dominate business and casual eyewear accessory programs, with leather and canvas textures preferred.
- Kids:Bright coloration and character licensing drive appeal, with closure safety certification requirements under CPSC and EN 71 standards adding compliance overhead.
Sports enthusiasts represent the fastest-growing customer segment, while women maintain the highest per-unit margin contribution through premium material uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH compliance anchors European procurement standards, while Chinese manufacturing clusters supply the majority of global pouch volume. Wenzhou and Wuxi industrial zones dominate microfiber and neoprene production, with regulatory frameworks in Germany and the United States shaping material certification requirements for export-bound shipments.
China
Wenzhou and Wuxi manufacturing clusters control the majority of global sunglasses pouch volume through integrated tooling networks and fibrous material expertise. MEE environmental standards and dual carbon goals are pushing Zhejiang Province suppliers toward certified synthetic substrates and recycled microfiber production. Wuxi Xinya Micro Fibrous Co. Ltd. anchors microfiber segment quality consistency for optical retailers worldwide.
Germany
Premium eyewear brands in Munich and Hamburg drive demand for REACH-certified pouch materials with lot-level fiber origin documentation. ECHA substance database expansions under REACH tighten restricted chemical lists for textile dyes and adhesive formulations, compelling Asian exporters to pre-certify each color variant through accredited EU laboratories. Berlin-based distributors consolidate procurement under centralized accessory programs.
United States
Sporting goods retailers and athletic eyewear brands bundle protective pouches as standard packaging for performance sunglasses. CPSC monitors small-part choking hazards in children-targeted pouch closures, influencing magnetic and zipper design specifications for youth SKUs. California and New York Metro optical retail channels maintain premium leather pouch positioning.
India
Rising sunglass consumption in Mumbai and Delhi creates white space for localized pouch production serving South Asian eyewear distributors. BIS certification alignment requirements shape domestic manufacturing entry barriers for microfiber and neoprene substrates. Maharashtra and Gujarat industrial corridors attract contract manufacturers targeting regional brand accessory programs.
Italy
Luxury eyewear channels in Milan and Florence command premium leather pouch specifications with Italian and Argentine hide sourcing. REACH dye certification requirements impose validation cycles on small-batch producers supplying optical retail. Blockchain-enabled material provenance tracking digitizes compliance verification workflows for premium brand suppliers.
Sunglasses Pouch Market Vendor Landscape
Capability concentration sits with specialized microfiber and leather fabricators; scale advantage sits with sporting goods retailers controlling direct-to-retail channel access. The vendor base spans Wenzhou-based integrated manufacturers, Wuxi fibrous material specialists, and European premium leather goods producers. Three archetypes dominate: microfiber volume manufacturers, leather premium specialists, and retail-captive accessory bundlers. Competitive moves center on REACH certification pre-positioning and e-commerce platform integration bypassing wholesale intermediaries.
Among Chinese fabricators, Wenzhou Classic Packing Co. Ltd. and Wuxi Xinya Micro Fibrous Co. Ltd. represent the integrated manufacturing archetype with regional tooling network access. Decathlon SA occupies a position exemplifying retail-captive scale advantage through global sporting goods footprint control. These three anchors illustrate how geographic specialization and channel integration shape competitive positioning across material tiers and closure specifications.
| Leading Market Players |
|---|
| Celyfos |
| Hide and Sleek Leather Goods |
| Hesh Opto Lab Private Limited |
| Interpol Eyewear |
| Wenzhou Classic Packing Co. Ltd. |
| North End Bag Company |
| Talfourd Jones LLC |
| Wuxi Xinya Micro Fibrous Co. Ltd. |
| Decathlon SA |
| Others |
Supply Flow & Price Mechanics
REACH certification timeline compression determines both pricing tier spreads and supply chain shape by forcing smaller Wenzhou leather pouch producers into extended 12-18 month validation cycles that microfiber volume manufacturers avoid. This regulatory chokepoint stratifies supplier economics and concentrates procurement relationships with certified synthetic substrate specialists.
Pricing Analysis
Geographic price spreads between EU-bound REACH-certified pouches and domestic China-market equivalents reflect certification cost absorption and dye chemistry validation overhead. Pricing stratifies across premium leather, certified microfiber, and economy fabric tiers, with differentiation driven by material grade and closure complexity. Cost compression in neoprene segments stems from petrochemical feedstock volatility that mid-tier manufacturers struggle to pass through sporting goods contracts. Price-sensitive promotional eyewear brands prioritize drawstring fabric pouches, while optical retailers show lowest sensitivity to leather premium positioning.
Supply Chain Analysis
Export-control regime friction under EU REACH substance restrictions limits flow of non-certified dye formulations and adhesive chemistries from Zhejiang Province suppliers. Production gravity centers on China, with Wenzhou tooling networks and Wuxi fibrous material zones supplying global volume. Raw material dependencies span chloroprene rubber feedstocks, synthetic filament substrates, and tanned hide inputs. Single-region concentration creates vulnerability to Zhejiang logistics disruptions. Distribution runs through centralized eyewear brand accessory programs rather than fragmented regional supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sunglasses pouch market functions as a defensive-moat story anchored in regulatory entrenchment. REACH certification pre-positioning creates switching costs that lock premium eyewear brands into validated supplier relationships.
For Market Incumbents: Build certification moats by accelerating REACH pre-validation for recycled microfiber grades before ECHA substance database expansions tighten restricted chemical lists. Add ultrasonic sealing capacity in Wuxi industrial zones to capture athletic eyewear bundling growth. Defend against emerging Indian contract manufacturers by securing multi-year vendor-managed inventory agreements with North American sporting goods retailers. For New Entrants and Emerging Players: Build out localized production serving Mumbai and Delhi optical distributors before BIS certification alignment hardens entry barriers. Target the sports enthusiast segment through moisture-wicking liner innovation and carabiner attachment integration. Penetrate via direct-to-retail e-commerce integration that bypasses wholesale intermediaries and captures margin previously allocated to sporting goods distributors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated microfiber specialists with REACH certification infrastructure and regional tooling network access. Long-term viability hinges on closed-loop microfiber recovery capabilities under EU Green Deal circularity incentives. Watch for ECHA substance database expansion announcements as inflection indicators that would accelerate supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Pre-Positioning | Unlocks premium channel access for Wuxi and Wenzhou manufacturers supplying German optical retailers. |
| Recycled Microfiber Scale-Up | Aligns production with EU Green Deal circularity incentives and lowers unit costs for volume manufacturers. |
| Direct-to-Retail E-Commerce Launch | Enables specialized pouch fabricators to capture margin from sporting goods wholesale intermediaries. |
| Ultrasonic Sealing Capacity Addition | Addresses technician scarcity in Wenzhou workforce pools and supports athletic eyewear bundling demand. |
| India Localization Partnership | Positions entrants to serve rising Mumbai and Delhi sunglass consumption under BIS certification alignment. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through primary interviews with eyewear brand procurement directors, optical retail category managers, Wenzhou-based pouch manufacturers, and athletic eyewear product development leads. Secondary validation drew from ECHA substance database filings, Zhejiang Province environmental compliance records, customs trade data for microfiber and neoprene substrates, and sporting goods retailer accessory program specifications. Bottom-up volume modeling triangulated against top-down eyewear shipment correlations.
Calibration anchored historical shipment patterns to forward projection assumptions across the analysis window. Segmentation dimensions spanned material substrate, closure mechanism, sizing specification, and target customer archetype. CAGRs derived from regression analysis against eyewear category growth rates and accessory bundling penetration curves. Forecast inputs included REACH certification adoption timelines and recycled microfiber production cost trajectories in Wuxi industrial zones.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian contract manufacturers or accelerated ECHA substance restrictions would shift outcomes. Material shifts in petrochemical feedstock pricing or Zhejiang Province logistics policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Spectacles Market
Eyewear
Smart Eyewear Market
Eyewear
North America Eyewear Market
Eyewear
3D Printing in Eyewear Market
Eyewear
United States Eyewear Market
Eyewear
Eyeglass Market
Eyewear
Smart Sunglasses Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market
Eyewear
Reading Glasses Market
Eyewear
Latin America Eyewear Market
Eyewear
Sunglasses Market
Eyewear
Face and Ear Bow Market
Eyewear
Luxury Eyewear Market
Eyewear
Goggles Market
Eyewear
Plano Sunglasses Market
Eyewear
Asia-Pacific Eyewear Market