
 Anti-Blue Light Glasses Market | 2026-2036
Anti-Blue Light Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Blue Light Glasses Market Insights
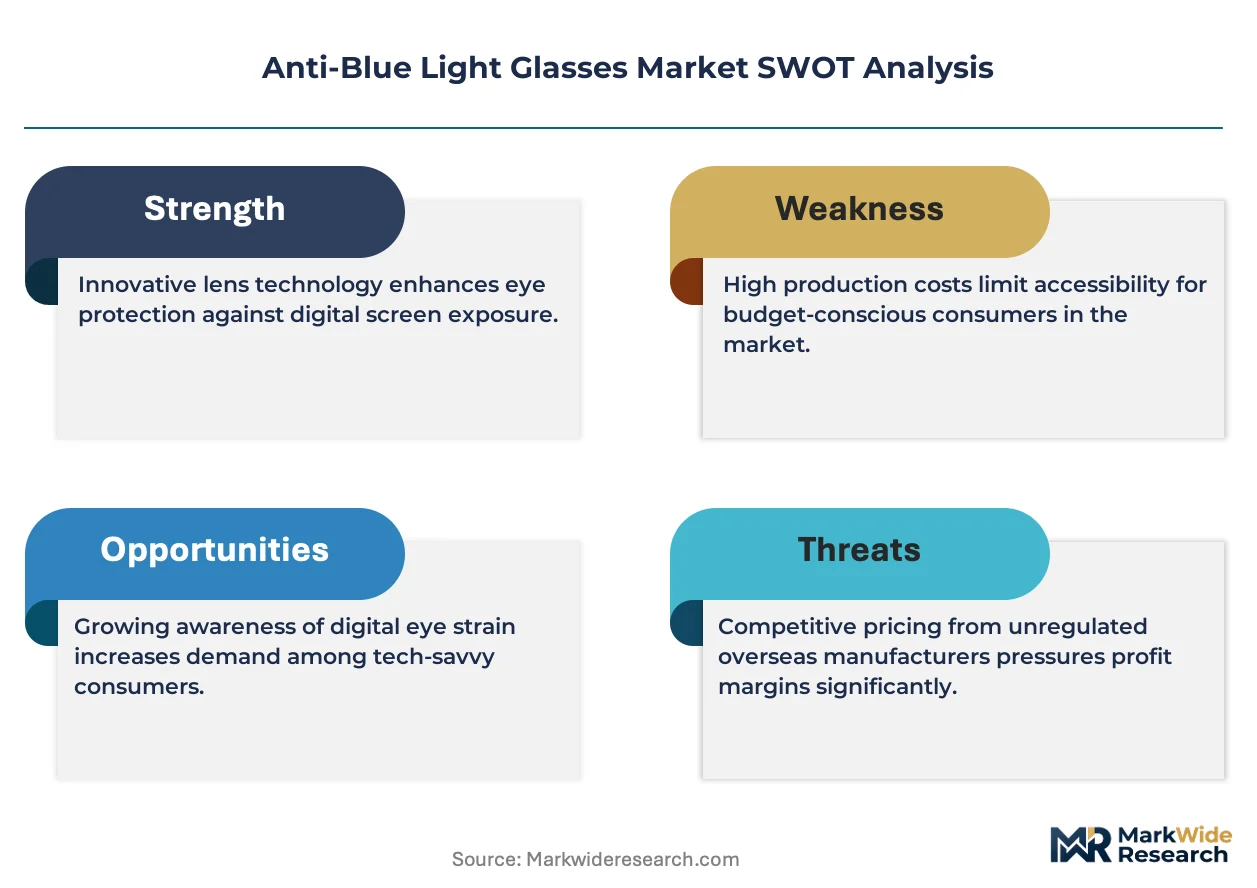
Direct-to-consumer leasing and subscription eyewear models is fragmenting capital requirements across the Anti-Blue Light Glasses Market. Zenni Optical leverages ultra-lean manufacturing to sustain price leadership in online channels. EssilorLuxottica anchors premium positioning through captive lens technology and optical retail density. Felix Gray specializes in digital-native branding that competes for screen-worker loyalty without physical storefront investment.
Anti-blue light glasses incorporate substrate lenses with selective yellow or amber tinting, typically filtering wavelengths between 400 and 450 nanometers to reduce retinal exposure from LED and OLED emission spectra. Their primary commercial purpose centers on mitigating digital eye strain symptoms among prolonged screen users. Plastic frames dominate unit economics due to injection-molding scalability, while photochromic lens variants capture margin pools by combining indoor blue-light filtration with outdoor UV responsiveness. Gamers represent the fastest-expanding target audience as esports organizations standardize protective eyewear in training regimens.
FDA oversight of medical device claims constrains how manufacturers market blue-light blocking efficacy, while EU REACH and RoHS frameworks govern chemical composition of frame coatings and metal alloys. The Federal Trade Commission monitors advertising substantiation for digital eye strain relief assertions in the United States. Stakeholders must track evolving ophthalmological consensus on blue-light health risks to anticipate whether regulatory bodies reclassify these products as medical devices or maintain consumer-goods status.
Market Dynamics
Remote work permanence is restructuring employer-funded eyewear procurement, converting individual consumer purchases into B2B wellness program contracts that demand volume pricing and standardized lens specifications.
Growth Catalysts
- EU REACH compliance tightening:Frame coating material specifications are forcing manufacturers toward certified supply chains, creating competitive moats for compliant producers.
- Esports training regimens:Professional gaming organizations are mandating protective eyewear for athletes, establishing institutional purchase patterns in a previously consumer-driven segment.
- LED emission proliferation:OLED screen density in workstations and mobile devices is amplifying cumulative retinal exposure concerns among occupational health officers.
Market Restraints
- Acetate and TR-90 resin price volatility:Petrochemical feedstock fluctuations are compressing margin stability for injection-molded frame producers.
- FDA medical device claim constraints:Substantiation requirements for digital eye strain relief assertions are limiting marketing vocabulary and slowing product launch velocity.
- Uncorrected vision substitution:Prescription blue-light lenses integrated into progressive eyewear are capturing users who would otherwise purchase standalone protective glasses.
Strategic Opportunities
- Corporate wellness program penetration:Technology-sector employers in the United States are expanding protective eyewear stipends for distributed workforces.
- Photochromic lens convergence:Indoor blue-light filtration combined with outdoor UV responsiveness is opening dual-use positioning against single-function competitors.
- Direct-to-consumer subscription models:Leasing frameworks are fragmenting capital requirements and lowering trial barriers for price-sensitive screen workers.
Industry Challenges
- Ophthalmological consensus tracking:Evolving clinical positions on blue-light health risks are creating classification uncertainty between consumer goods and medical device status.
- Coating chemistry compliance timelines:EU REACH pre-registration and safety data sheet preparation are extending new material qualification cycles.
- Optical retail channel integration:Online-native brands face friction establishing prescription fulfillment partnerships with established optometry networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Blue Light Glasses Market |
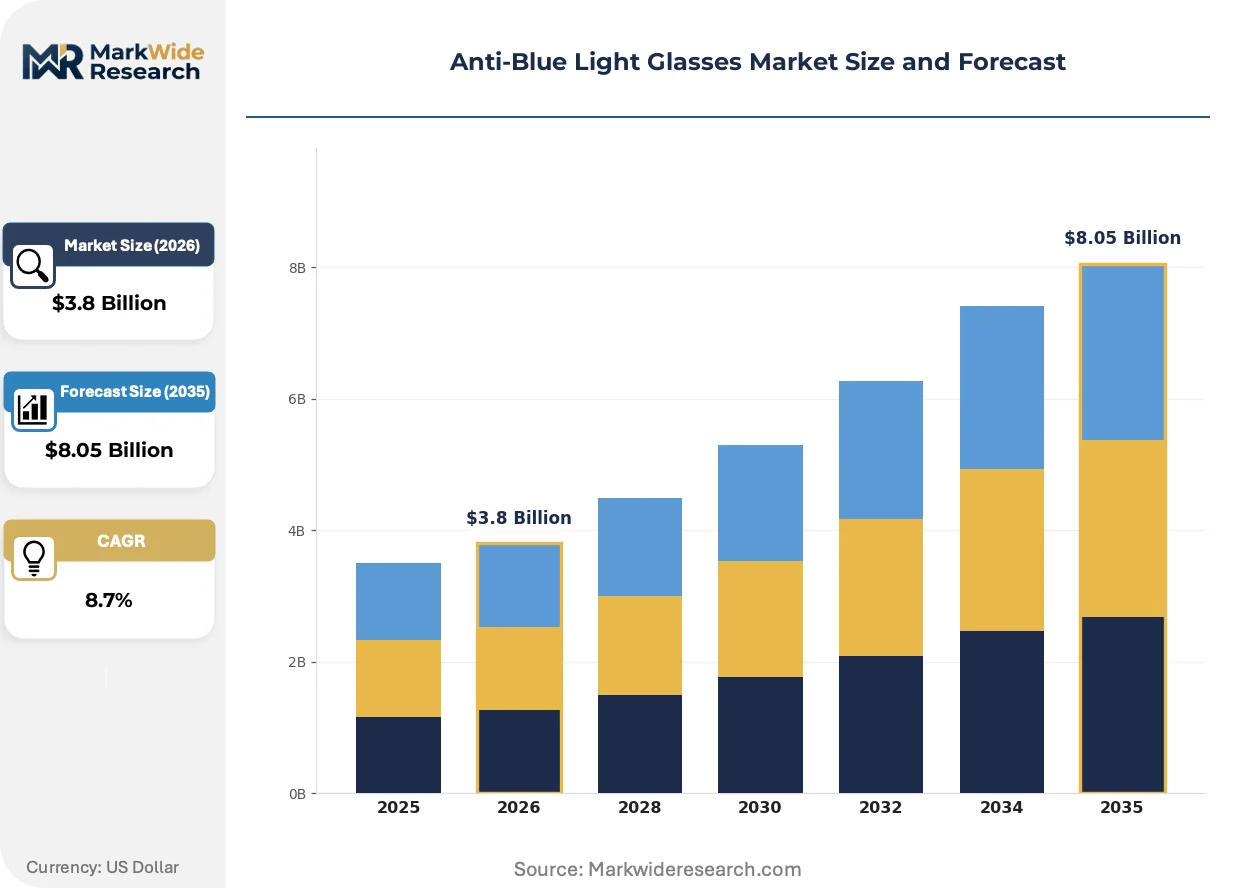
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Frame Material: Plastic, Metal, Wood, Bamboo Lens Type: Aspheric, Photochromic, Polarized, Single Vision Target Audience: Children, Professionals, Gamers, Students Distribution Channel: Online Retail, Optical Stores, Pharmacies, Specialty Shops |
| Companies Covered | Zenni Optical, Gunnar Optiks, Warby Parker, Peepers, EyeBuyDirect, EssilorLuxottica, Felix Gray, Horus X, JINS Eyewear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Blue Light Glasses Market Trends and Innovations
Competitive positioning is diverging between ultra-lean manufacturing specialists and premium lens technology holders, with distribution models fragmenting across physical optical retail, direct-to-consumer digital, and employer-sponsored procurement channels.
Substrate lenses with selective yellow or amber tinting are rendering obsolete clear-lens competitors that rely solely on surface coatings for wavelength filtration. Esports organizations and professional gaming leagues are adopting these tinted substrates at accelerating rates for training facility standardization. The structural consequence is compressing price premiums for coating-dependent products while elevating integrated substrate solutions.
EU REACH and RoHS frameworks are governing chemical composition of frame coatings and metal alloys with increasing stringency. Manufacturers are reformulating acetate alternatives and eliminating restricted phthalates from temple components to maintain market access. Small-batch frame producers in Italy and Japan are most affected, responding by consolidating supplier relationships and pre-certifying material libraries.
Employer procurement of protective eyewear for remote workers is displacing individual purchase decisions in the technology sector. Human resources departments are negotiating volume contracts that bundle blue-light glasses with ergonomic furniture and mental health benefits. This pattern is most visible in the United States among software development and financial services firms with distributed work policies.
Anti-Blue Light Glasses Market Segmentation
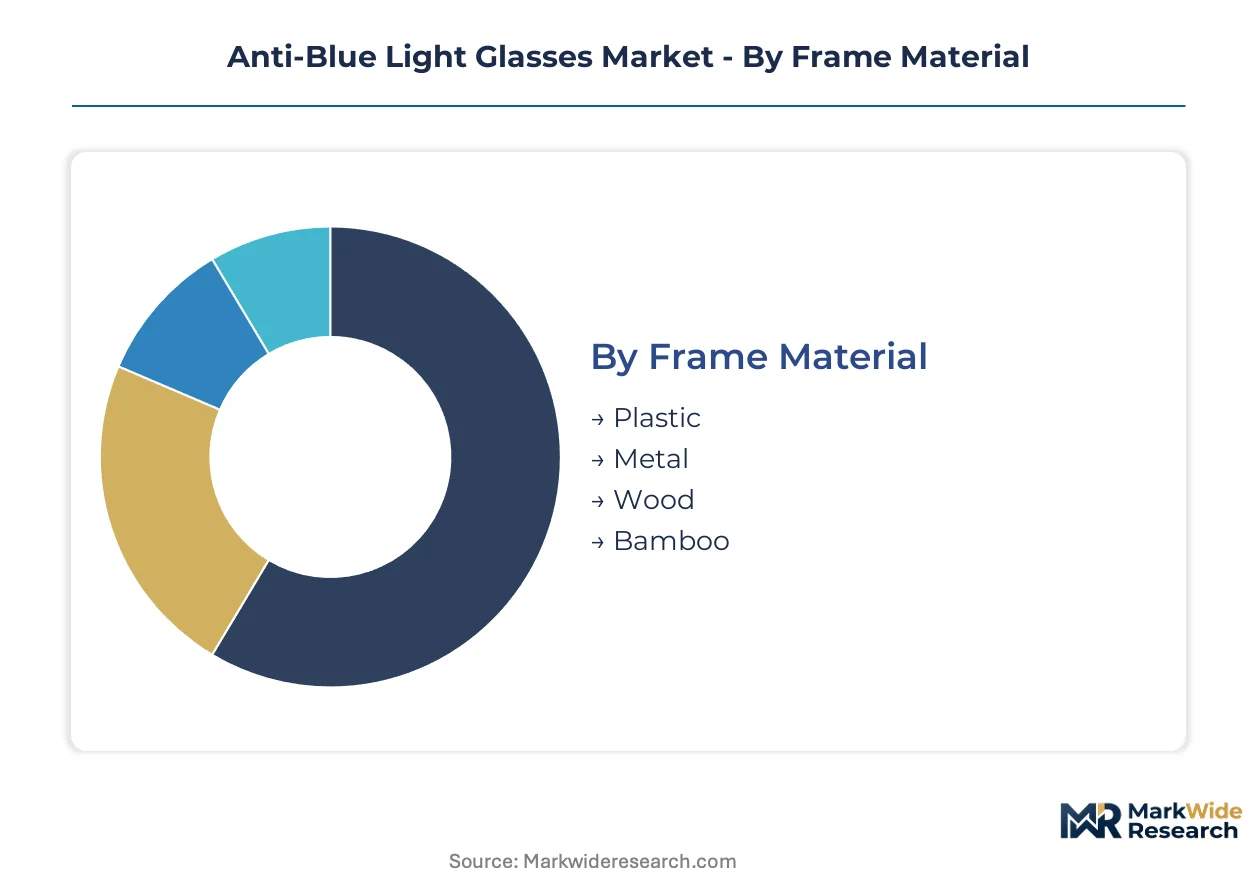
Anti-blue light glasses fragment across material science, optical engineering, demographic targeting, and channel economics. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Frame Material:
Cost tier differentiation in frame substrates determines manufacturing scalability and EU REACH compliance burden.
- Plastic:Injection-molded acetate and TR-90 resin dominate unit economics through scalable production. Demand concentrates among remote workers in United States technology firms where employer wellness programs prioritize volume procurement over premium aesthetics.
- Metal:Stainless steel and titanium alloys offer durability and hypoallergenic properties for extended wear. Japanese and Italian optical houses favor these substrates for professional segments willing to absorb higher price points.
- Wood:Sustainable sourcing appeals to environmentally conscious consumers in Nordic markets. Small-batch producers face extended EU REACH pre-registration cycles for natural finish coatings.
- Bamboo:Rapid-renewable biomass attracts sustainability-positioned brands. Supply chains cluster in Southeast Asian processing facilities with variable chemical compliance documentation.
Plastic holds installed capacity. Metal is rotating up the share rankings.
Lens Type:
Optical performance specifications separate single-function filtration from adaptive multi-environment solutions.
- Aspheric:Flatter curvature profiles reduce peripheral distortion and lens thickness for high-prescription users. German and French optical retailers specify these for progressive lens integrations capturing users who would otherwise purchase standalone protective glasses.
- Photochromic:Silver halide or naphthopyran-embedded substrates transition between indoor blue-light filtration and outdoor UV responsiveness. United States technology-sector employers increasingly specify these for distributed workforces needing dual-use eyewear.
- Polarized:Laminated filter layers block glare from reflective screens and ambient lighting. Demand concentrates among financial services professionals in London and New York with multi-monitor workstation setups.
- Single Vision:Uniform diopter correction with surface-applied or substrate-integrated blue-light filtering. Mass-market online retailers leverage these for lowest trial-price entry points in direct-to-consumer subscription models.
Single Vision holds installed capacity. Photochromic is climbing the fastest.
Target Audience:
Customer type segmentation maps symptom severity, screen exposure duration, and procurement authority.
- Children:Developing retinal sensitivity drives pediatric ophthalmologist recommendations for amber-tinted substrates. United States school districts in California and Texas are piloting protective eyewear programs for one-to-one device initiatives.
- Professionals:Corporate procurement authority converts individual purchases into B2B wellness contracts. Technology and financial services firms in Seattle, San Francisco, and Manhattan dominate employer-funded stipend expansion.
- Gamers:Esports organizations mandate standardized protective eyewear for training facility regimens. Korean and Chinese professional leagues are establishing institutional purchase patterns with performance-optimized tint specifications.
- Students:Higher education procurement lags corporate adoption but accelerates through university health services. Australian and Canadian campus bookstores are adding blue-light glasses to back-to-semester merchandise assortments.
Professionals hold installed capacity. Gamers are gaining share fastest.
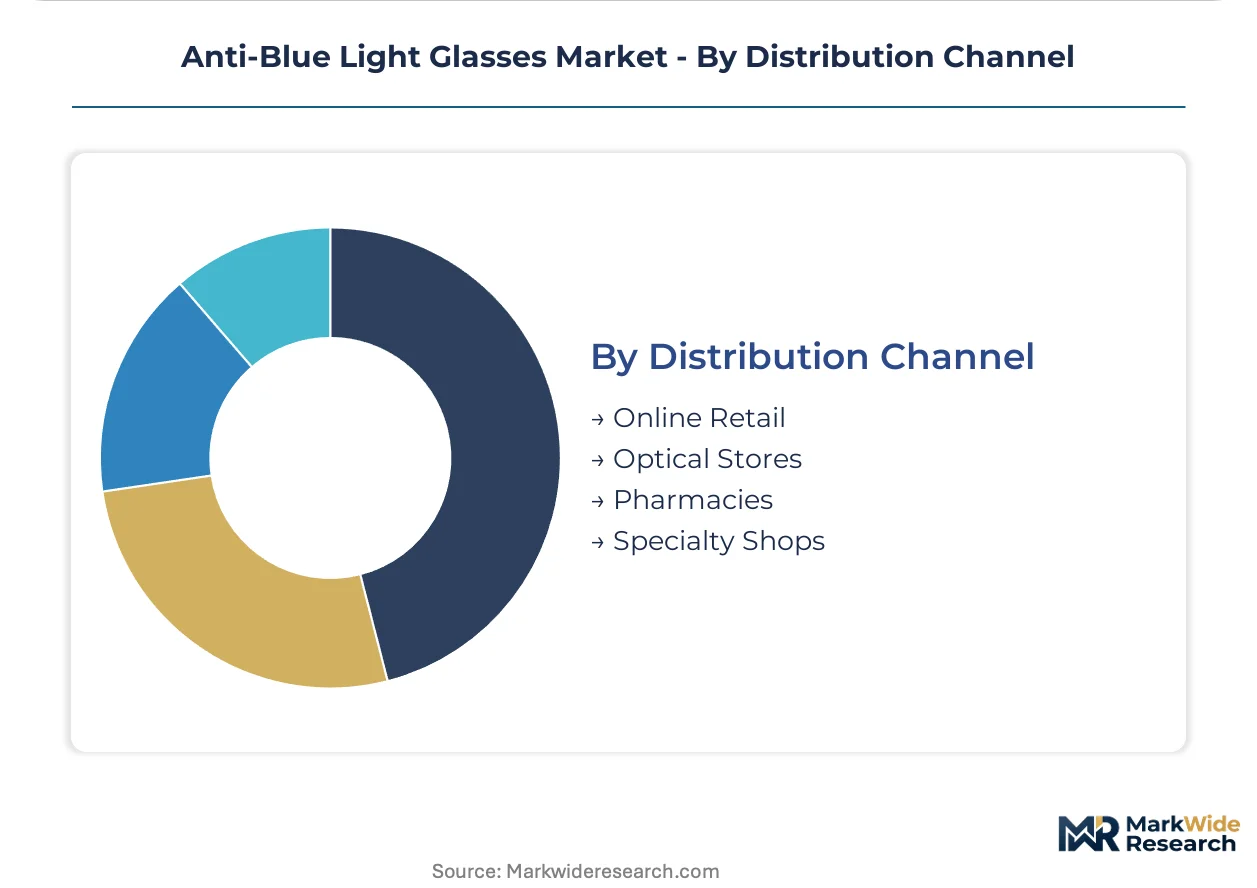
Distribution Channel:
Channel configuration determines prescription fulfillment capability and customer acquisition economics.
- Online Retail:Direct-to-consumer platforms fragment capital requirements through subscription and leasing frameworks. Zenni Optical and Felix Gray anchor this channel with ultra-lean manufacturing or digital-native branding.
- Optical Stores:Established optometry networks control prescription fulfillment and lens customization. EssilorLuxottica's retail density captures premium positioning through captive lens technology and in-person fitting services.
- Pharmacies:Over-the-counter placement reaches symptom-aware consumers during routine health purchases. CVS and Walgreens in the United States are expanding protective eyewear assortments adjacent to reading glasses.
- Specialty Shops:Gaming peripherals retailers and ergonomic furniture showrooms target high-intent screen workers. Micro Center and B&H Photo in the United States bundle blue-light glasses with monitor and workstation purchases.
Optical Stores hold installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer wellness mandates and screen-time health guidelines are redirecting procurement authority toward institutional buyers across major economies. National regulators are tightening chemical compliance for frame materials while occupational health officers amplify protective eyewear specifications.
United States
Technology-sector employers in Seattle, San Francisco, and Manhattan are standardizing blue-light eyewear stipends for distributed workforces. The FTC monitors advertising substantiation for digital eye strain relief claims, constraining marketing vocabulary for manufacturers. Corporate procurement contracts now bundle protective glasses with ergonomic furniture packages.
Germany
Occupational health regulations under the Arbeitsschutzgesetz are prompting manufacturing firms to evaluate screen-worker protective equipment. ECHA REACH compliance timelines are extending new material qualification cycles for frame producers. Optical retail clusters in Munich and Hamburg are integrating photochromic lens options into employer wellness catalogues.
China
Esports training facilities in Shanghai and Shenzhen are mandating standardized protective eyewear for professional athletes. SAMR oversight of consumer product claims is intensifying scrutiny on blue-light blocking efficacy assertions. Domestic frame producers are consolidating supplier relationships to meet EU export requirements.
Japan
METI guidelines on digital health are influencing corporate procurement patterns for remote workers. JIS standards for eyewear materials are tightening specifications for frame coatings and metal alloys. Tokyo-based optical houses are favoring titanium substrates for professional segments absorbing premium price points.
United Kingdom
Financial services firms in London are specifying polarized lens variants for multi-monitor workstation environments. The Health and Safety Executive is evaluating screen equipment guidance for protective eyewear recommendations. Manchester and Birmingham distribution hubs are processing rising B2B wellness program volumes.
Anti-Blue Light Glasses Market Competitive Landscape
On the supply side, the industry is bifurcating between ultra-lean manufacturing specialists and premium lens technology holders. Optical retail density competes against direct-to-consumer digital platforms for procurement authority. Two strategic archetypes dominate: vertically integrated lens-frame combinations and asset-light brand operators. Competitive moves center on prescription fulfillment partnerships and subscription model fragmentation.
Among online-native specialists, Felix Gray exemplifies digital-first brand building without physical storefront investment. Zenni Optical occupies a position as an ultra-lean manufacturing anchor. EssilorLuxottica represents the captive technology tier through integrated lens production and optical retail density. These three archetypes illustrate the channel divergence reshaping customer acquisition economics.
| Leading Market Players |
|---|
| Zenni Optical |
| Gunnar Optiks |
| Warby Parker |
| Peepers |
| EyeBuyDirect |
| EssilorLuxottica |
| Felix Gray |
| Horus X |
| JINS Eyewear |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese acetate resin processing is compressing margin structures for injection-molded frame producers while simultaneously enabling aggressive volume pricing for employer wellness contract bidders. This utilization dynamic forces manufacturers toward either certified supply chain investments that command premium positioning or ultra-lean cost structures that sacrifice compliance flexibility.
Pricing Analysis
Certification level creates the primary spread between economy and premium tiers, with EU REACH-compliant producers capturing 40-60% price premiums over uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels dominates, differentiated by lens substrate integration quality and frame material provenance. Cost compression in the standard tier is intensifying because petrochemical feedstock volatility erodes injection-molding margins. Remote workers in United States technology firms exhibit highest price sensitivity, while Japanese professional segments absorb premium titanium-alloy positioning without volume negotiation.
Supply Chain Analysis
Petrochemical feedstocks for acetate and TR-90 resin draw primarily from China, South Korea, and Saudi Arabia, with optical-grade polymer production clustering in Zhejiang and Guangdong provinces. Silver halide substrates for photochromic lenses and titanium sponge for hypoallergenic frames constitute critical input dependencies. Single-source vulnerability concentrates in EU REACH pre-certified coating suppliers, where Italian and Japanese small-batch producers face extended qualification timelines. Distribution runs through direct-to-consumer platforms, established optical retail networks, and emerging employer procurement channels with diverging fulfillment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of in-house photochromic lens substrate production capability constrains margin capture for frame-only manufacturers and drives consolidation toward vertically integrated optical houses. This capability gap separates premium positioning contenders from commodity assemblers.
For Market Incumbents: Pre-empt regulatory reclassification risk by accelerating FDA medical device claim substantiation investments before ophthalmological consensus shifts. Secure captive lens technology through backward integration into substrate production or exclusive supply agreements with German and French optical engineering specialists. Channel control through employer wellness program contract lock-in protects against direct-to-consumer subscription erosion. For New Entrants and Emerging Players: Australian and Canadian university health services procurement represents underpenetrated institutional demand with lower competitive density than United States corporate wellness programs. White-space exists in pediatric protective eyewear for United States school district one-to-one device initiatives, where district-level purchasing authority aggregates fragmented individual demand. Go-to-market through ergonomic furniture distributors enables bundled workstation positioning without optical retail partnership friction. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because evolving blue-light health risk consensus may reclassify products as medical devices, advantaging pre-compliant producers with established clinical substantiation. Acquisition targets should demonstrate EU REACH certification libraries and employer wellness contract pipelines rather than consumer brand recognition alone. Signal to watch: FDA guidance document issuance on digital eye strain relief claim substantiation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| EU REACH Certification Investment | Pre-qualifies material libraries for employer wellness contract eligibility in European markets. |
| Photochromic Lens Integration | Captures dual-use positioning against single-function competitors in United States technology sector procurement. |
| Direct-to-Consumer Subscription Launch | Fragments capital requirements and lowers trial barriers for price-sensitive remote worker segments. |
| Esports League Partnership | Establishes institutional purchase patterns in Korean and Chinese professional gaming training facilities. |
| Prescription Fulfillment Partnership | Enables online-native brands to access optometry network integration without physical storefront investment. |
Research Methodology
Initial hypotheses were tested against primary input from optical retail buyers, employer wellness program procurement officers, frame manufacturing plant managers, and esports organization equipment coordinators and refined through secondary validation against FDA guidance documents, ECHA REACH registration databases, SEC optical sector filings, and customs trade data for acetate resin and titanium sponge imports. Bottom-up demand modeling from segment-level procurement patterns triangulated against top-down market sizing from optical industry association reports.
Demand-supply balance dynamics across the analysis window were modeled through segmented adoption curves for employer-funded versus individual purchase channels, with CAGRs derived from regression analysis of historical procurement volumes and forward projection of screen-worker population growth. Segmentation dimensions included frame material compliance tier, lens optical performance specification, target audience symptom severity, and distribution channel prescription fulfillment capability. Forecast inputs incorporated LED and OLED device shipment trajectories and evolving occupational health officer protective equipment specifications.
Practitioners should monitor FDA medical device classification review timelines and EU REACH substance restriction proposal announcements for early signals of regulatory reclassification. Forecasts reflect assumptions regarding ophthalmological consensus stability and petrochemical feedstock price normalization. Quarterly review of employer wellness program contract award announcements and esports league equipment standardization decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
North America Eyewear Market
Eyewear
Europe Eyewear Market
Eyewear
Face and Ear Bow Market
Eyewear
Reading Glasses Market
Eyewear
Anti-Fog Lens Market
Eyewear
Smart Eyewear Market
Eyewear
Eyewear Market
Eyewear
Luxury Eyewear Market
Eyewear
United States Eyewear Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Eyeglass Market
Eyewear
Middle East Eyewear Market
Eyewear
Latin America Eyewear Market
Eyewear
Blue Light Glasses Market
Eyewear
Glasses Frame Market
Eyewear
Sunglasses Pouch Market