
 North America Eyewear Market | 2026-2036
North America Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
North America Eyewear Market Intelligence
ISO 12870 certification for spectacle frames is reorganizing competitive access across the North America eyewear landscape, filtering out suppliers unable to meet mechanical stability and nickel-release benchmarks. EssilorLuxottica leverages its vertically integrated lens-finishing network to dominate prescription fulfillment at scale. Warby Parker anchors its position through direct-to-consumer distribution and in-house frame design. Maui Jim differentiates via proprietary polarization technology and premium lens coatings.
Eyewear comprises vision-correcting and protective devices incorporating precisely ground optical lenses mounted in frames engineered to ANSI Z80.1 standards for impact resistance and optical power tolerance, serving refractive correction, UV protection, and occupational safety functions. Prescription glasses and contact lenses capture the largest volume pools, though sports eyewear built from polycarbonate represents the fastest-margin expansion as athletes prioritize ANSI Z87.1-rated impact protection. Online retail channels are displacing traditional optical stores among digitally native consumers, while metal and acetate frame materials command premium positioning over commodity plastics.
The FDA regulates contact lenses and prescription eyewear as Class II medical devices, requiring 510(k) clearance for new lens materials and designs, while the FTC's Eyeglass Rule and Contact Lens Rule mandate prescription release to consumers to enable competitive channel access. ANSI Z80 and Z87 standards further shape product liability exposure and insurance requirements for manufacturers. Stakeholders must monitor state-level scope-of-practice legislation governing online refraction services and automated vision testing, as regulatory fragmentation between jurisdictions will determine which distribution models retain legal viability.
Market Dynamics
The North America eyewear market is restructuring around regulatory enforcement of online prescription verification and the FTC's tightening Contact Lens Rule compliance timelines, which are compressing channel arbitrage opportunities for digital retailers.
Growth Catalysts
- FDA 510(k) pathway for silicone hydrogel lenses:Accelerated material approvals are expanding the addressable base for extended-wear contact lens prescriptions.
- Sun Belt UV exposure patterns:Elevated ultraviolet indices across Arizona, Florida, and Texas are shortening sunglass replacement cycles and driving premium polarization upgrades.
- Progressive lens demand from aging demographics:Presbyopia correction needs among the 55-plus cohort are pulling volume toward multifocal ophthalmic lenses.
Market Restraints
- Acetate and titanium input cost volatility:Frame material prices fluctuate with petrochemical feedstock and rare earth metal supply disruptions.
- Lens finishing equipment concentration:Automated edging and coating systems cluster with a narrow supplier base in Germany and Japan, creating import dependency.
- ANSI Z87.1 certification timeline:Safety eyewear testing protocols extend product launch windows by four to six months versus standard ophthalmic frames.
Strategic Opportunities
- Telehealth-enabled refraction in rural Canada:Provincial scope-of-practice expansions are opening automated vision testing corridors in underserved Prairie provinces.
- Blue-light filtering coatings for remote workers:Occupational eye strain mitigation is creating a reimbursable lens add-on category through employer vision benefit plans.
- FTC Eyeglass Rule prescription portability:Mandated release of pupillary distance and prescription data is lowering switching costs for direct-to-consumer channel migration.
Industry Challenges
- Licensed optician staffing gaps:Dispensing proficiency shortages in frame fitting and progressive lens adaptation are constraining retail expansion velocity.
- ISO 12870 nickel-release testing backlog:Metallurgical compliance verification queues at third-party laboratories are delaying frame collection launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Eyewear Market |
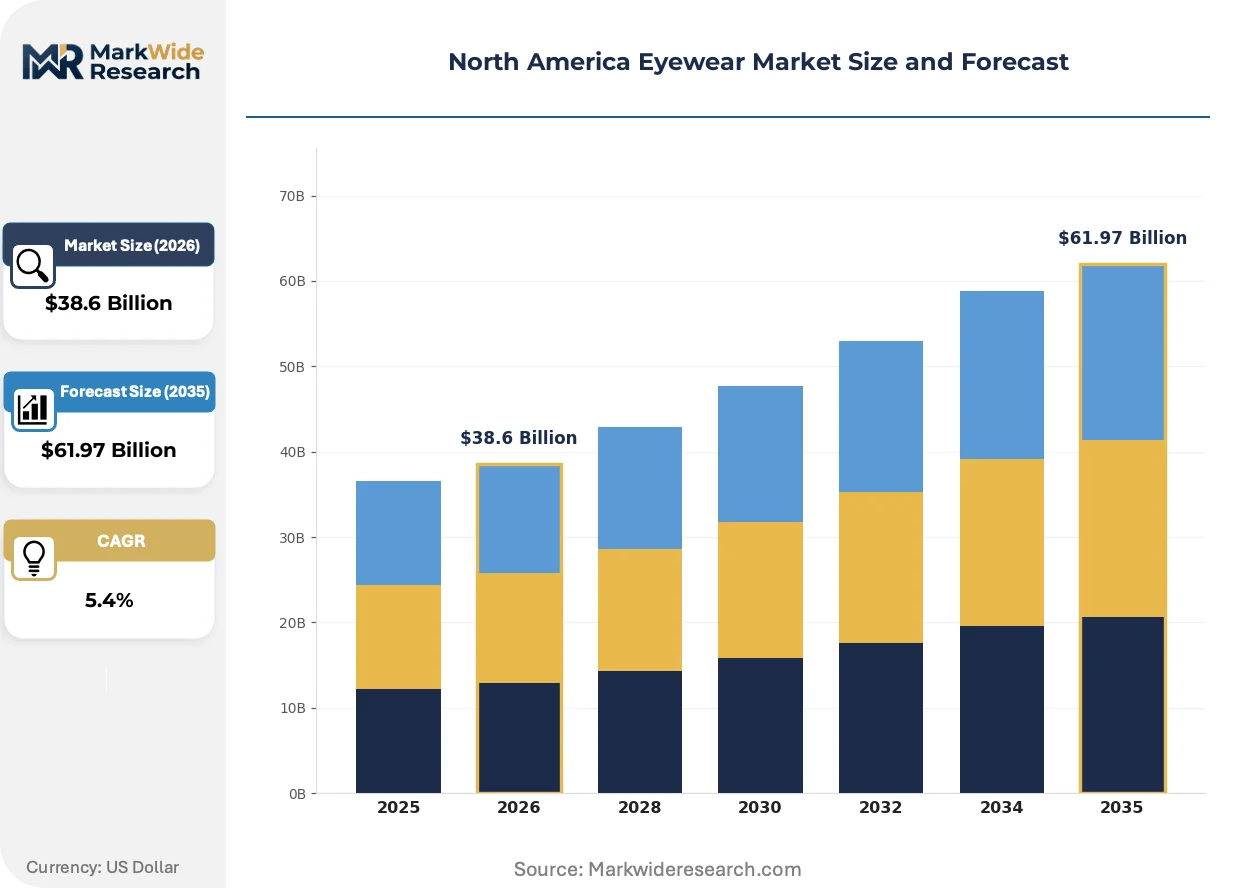
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunglasses, Prescription Glasses, Contact Lenses, Sports Eyewear Material: Plastic, Metal, Glass, Polycarbonate End User: Adults, Children, Teenagers, Seniors Sales Channel: Online Retail, Optical Stores, Supermarkets, Pharmacies |
| Companies Covered | Johnson & Johnson Vision, 1-800 Contacts, EssilorLuxottica, Maui Jim, GlassesUSA, Warby Parker, Luxottica Group, Bausch & Lomb, Safilo Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Eyewear Market Strategic Shifts & Innovations
Digital distribution models are fragmenting the traditional optical retail channel while material science advances and regulatory digitization are rewriting competitive requirements across the value chain.
Freeform lens surfacing technology is bifurcating the prescription fulfillment landscape. High-definition digital back-surface designs now command premium positioning for complex astigmatism corrections. Independent optometrists and regional optical chains are adopting these systems to defend against vertically integrated competitors. The technology is compressing margins on conventional stock lenses while expanding addressable complexity in the custom segment.
FTC Contact Lens Rule amendments are tightening prescription verification protocols for online retailers. Automated robocall verification systems now face explicit consent requirements and documentation standards. Digital-native sellers in the United States are reconfiguring customer acquisition flows to accommodate real-time prescriber confirmation. The regulatory friction is favoring hybrid models with physical exam relationships over pure-play e-commerce entrants.
Subscription-based contact lens replenishment is displacing episodic retail purchasing among younger wearers. Direct-to-home delivery with automated prescription renewal is capturing recurring revenue pools previously held by optical storefronts. This behavioral shift concentrates most visibly in urban United States markets with high digital payment penetration and employer-sponsored vision plan integration.
North America Eyewear Market Segmentation
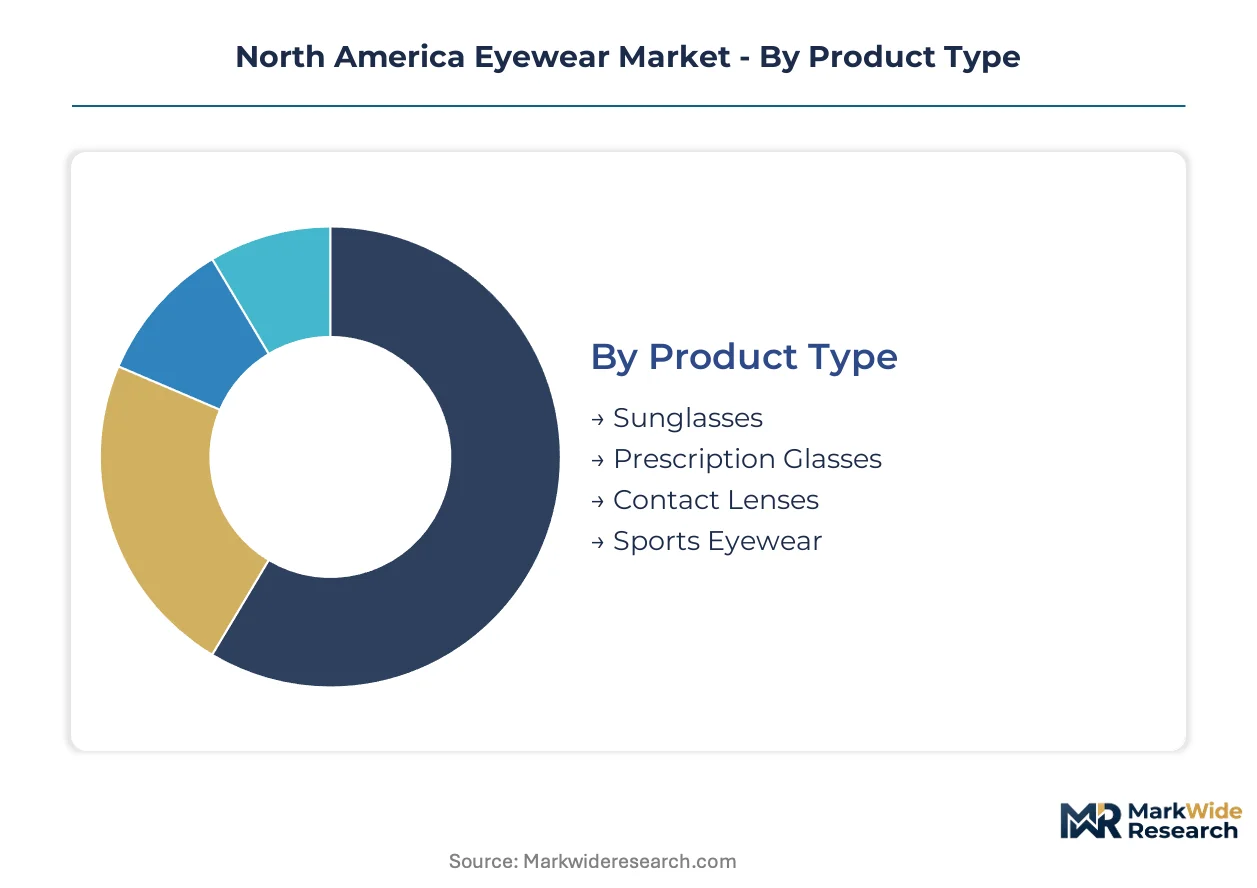
Segmentation in the North America eyewear market reveals divergent growth trajectories across product categories and channel structures. Understanding these splits helps stakeholders allocate capital toward prescription fulfillment networks, material substitution programs, and demographic-targeted collection development.
Product Type:
Domestic demand concentrates in prescription-correcting categories, while export-oriented manufacturing clusters serve specialty protective segments with cross-border certification requirements.
- Prescription Glasses:Custom-ground optical lenses mounted in ANSI Z80.1-certified frames correct refractive errors across single-vision, bifocal, and progressive designs. Demand concentrates in Sun Belt states where aging demographics drive multifocal upgrades, though licensed optician staffing gaps constrain retail velocity in Florida and Arizona corridors.
- Contact Lenses:FDA-regulated Class II medical devices spanning daily disposables through extended-wear silicone hydrogel formulations. Volume expansion runs through subscription replenishment models in urban United States markets with integrated employer vision benefits, while FTC verification protocols tighten channel compliance.
- Sunglasses:UV-protective eyewear with polarization and tint options for recreational and fashion use.
- Sports Eyewear:ANSI Z87.1-rated impact-resistant frames and polycarbonate lenses for athletic protection.
Prescription glasses command the established base. The steepest expansion runs through contact lenses.
Material:
Cost tier differentiation separates premium frame inputs from commodity substitutes, with petrochemical and rare earth metal volatility reshaping procurement strategies.
- Acetate (Plastic):Cellulose-derived thermoplastic offering deep color saturation and hand-polish finish quality for fashion-forward frames. ISO 12870 nickel-release compliance testing backlogs at third-party laboratories delay collection launches, particularly for independent designers sourcing from Italian compound suppliers.
- Titanium (Metal):Hypoallergenic, corrosion-resistant alloy enabling ultra-lightweight frame architectures with superior mechanical stability. Input cost volatility tracks rare earth metal supply disruptions from primary extraction regions, compressing margin predictability for premium positioning.
- Glass:Traditional mineral lens material with superior optical clarity and scratch resistance.
- Polycarbonate:Impact-resistant thermoplastic dominating safety and sports applications for its shatterproof properties.
Plastic derivatives anchor volume manufacturing. Titanium alloys capture the fastest margin expansion.
End User:
Application intensity varies sharply by life stage, with presbyopia onset and occupational screen exposure creating distinct lens complexity requirements.
- Seniors:Progressive and bifocal lens wearers managing presbyopia and concurrent pathologies. Demand concentrates in retirement migration corridors across Arizona, Florida, and Texas where Medicare Advantage vision benefits and high UV indices compound replacement frequency.
- Adults:Working-age corrective lens users spanning single-vision through early presbyopia management.
- Teenagers:Myopia progression management and fashion-conscious frame turnover.
- Children:Early refractive correction with emphasis on durable, adjustable frame designs.
Seniors represent the most concentrated revenue pool. Teenagers show the fastest behavioral shift toward digital-native purchasing.
Sales Channel:
Channel fragmentation accelerates as regulatory digitization and hybrid service models rewrite customer acquisition economics.
- Online Retail:Direct-to-consumer platforms leveraging FTC Eyeglass Rule prescription portability and automated pupillary distance capture. FTC Contact Lens Rule amendments forcing real-time prescriber verification are reconfiguring acquisition flows, favoring hybrid models with physical exam relationships over pure-play entrants.
- Optical Stores:Licensed optician-staffed storefronts providing frame fitting, progressive lens adaptation, and in-person refraction services.
- Supermarkets:Mass-market readers and basic sun protection in high-traffic retail environments.
- Pharmacies:Contact lens replenishment and over-the-counter reading glasses alongside health services.
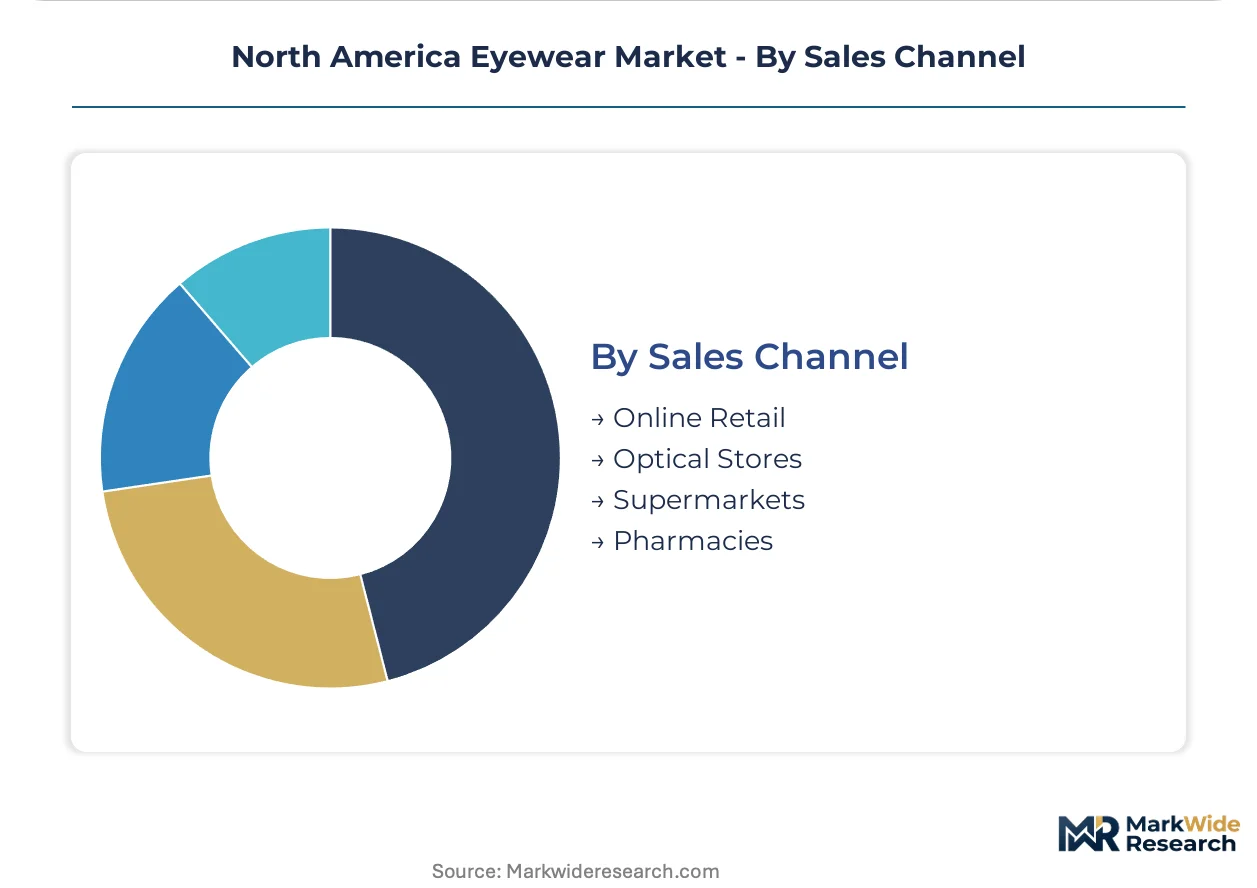
Optical stores retain the installed base. Online retail is gaining share fastest among digitally native cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-35 corridor freight network linking Laredo to Minneapolis underwrites North America's eyewear distribution architecture, connecting Mexican manufacturing clusters to US Sun Belt retail corridors and Canadian provincial healthcare procurement hubs.
United States
Prescription volume concentrates in Arizona, Florida, and Texas where Medicare Advantage vision benefits and elevated UV indices compound replacement frequency. FDA 510(k) oversight of silicone hydrogel lens materials shapes contact lens market entry timelines. Dallas-Fort Worth anchors a regional distribution hub serving independent optometrist practices across the Southwest.
Canada
Provincial scope-of-practice expansions in Alberta and Saskatchewan are opening automated vision testing corridors for telehealth-enabled refraction. Health Canada regulates contact lenses as Class II medical devices under the Medical Devices Regulations. Toronto's optical retail cluster serves as the primary import gateway for European frame collections.
Mexico
Export-oriented manufacturing of acetate frames and metal components supplies US private-label retailers under USMCA tariff preferences. COFEPRIS medical device registration requirements align with FDA standards for cross-border lens shipments. Guadalajara's eyewear production zone specializes in hand-finished acetate temples for premium positioning.
North America Eyewear Market Key Industry Players
Listed leaders compete with private specialists across channel access and prescription fulfillment velocity. The vendor base stratifies between vertically integrated conglomerates controlling lens-finishing networks, direct-to-consumer platforms leveraging regulatory prescription portability, and specialty polarization technology houses. Three archetypes dominate: scale-driven ophthalmic giants, digitally native vertical brands, and premium sunwear specialists. Competitive moves center on backward integration into lens coating capabilities and hybrid physical-digital channel expansion.
Within the scale-driven tier, EssilorLuxottica occupies a position exemplifying captive control over prescription fulfillment infrastructure. Warby Parker represents the digitally native archetype anchoring direct-to-consumer distribution with in-house frame design. Maui Jim sits within the premium specialization tier, exemplifying proprietary polarization technology differentiation.
| Leading Market Players |
|---|
| Johnson & Johnson Vision |
| 1-800 Contacts |
| EssilorLuxottica |
| Maui Jim |
| GlassesUSA |
| Warby Parker |
| Luxottica Group |
| Bausch & Lomb |
| Safilo Group |
| Others |
Cost & Logistics Intelligence
Ninety-day acetate frame inventory cycles at US optical distributors concentrate pricing power with Italian compound suppliers and German lens-finishing equipment makers, compressing margin buffers for independent frame designers while amplifying cost pass-through leverage for vertically integrated conglomerates.
Pricing Analysis
Volume-discount tiering separates EssilorLuxottica's captive lens-finishing networks from independent optometrists purchasing stock lenses in smaller batches. Price differentiation hinges on ISO 12870 certification grade and ANSI Z87.1 safety rating, with premium polarization coatings from Maui Jim commanding substantial markups over commodity tinting. Pricing pressure stems from FTC-mandated prescription portability lowering consumer switching costs. Employer-sponsored vision plan members show lowest price sensitivity; uninsured cash-pay patients in Sun Belt states exhibit highest.
Supply Chain Analysis
Inbound logistics costs from the Port of Los Angeles to Dallas-Fort Worth distribution hubs fluctuate with container availability across the Trans-Pacific trade lane, squeezing landed costs for acetate raw material shipments from Italian suppliers. Manufacturing concentrates in China for titanium alloy processing, Italy for acetate compounding, and Germany for automated edging systems. Raw material dependencies span petrochemical feedstocks for cellulose acetate, rare earth metals for titanium alloys, and optical monomers for silicone hydrogel lenses. Single-source vulnerability clusters with German and Japanese lens-coating equipment makers. Distribution runs through the I-35 corridor freight network linking Mexican frame assembly to US retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based contact lens replenishment represents a service-attach opportunity expanding faster than frame hardware sales, as automated prescription renewal and direct-to-home delivery capture recurring revenue pools previously held by optical storefronts.
For Market Incumbents: Compound defensive positioning through backward integration into blue-light filtering coating capabilities and hybrid physical-digital channel expansion. The FTC's tightening Contact Lens Rule verification timelines threaten pure-play digital retailers, creating acquisition opportunities for incumbents with established prescriber relationships. Priority levers include captive lens-finishing capacity additions in Dallas-Fort Worth and ISO 12870 certification investment to filter out non-compliant competitors.
For New Entrants and Emerging Players: Anchor in telehealth-enabled refraction corridors across Alberta and Saskatchewan where provincial scope-of-practice expansions have opened automated vision testing in underserved Prairie provinces. White-space targets include rural Canadian markets with limited optometrist density and blue-light filtering lens add-ons for remote worker employer benefit plans. Go-to-market angle should emphasize FTC Eyeglass Rule prescription portability to lower consumer acquisition friction.
For Investors and Strategic Acquirers: Long-term, this sits as a demographic-capture play because presbyopia onset across aging Sun Belt populations ensures sustained progressive lens demand regardless of economic cycle positioning. Acquisition target archetype: digitally native vertical brands with established subscription replenishment infrastructure and hybrid physical exam relationships. Signal to watch: state-level scope-of-practice legislation governing online refraction services as inflection indicator for distribution model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Channel Expansion | FTC verification protocols favor physical-digital models over pure e-commerce entrants. |
| Backward Integration into Coatings | Proprietary blue-light and polarization technology differentiates against commodity lens suppliers. |
| Subscription Replenishment Buildout | Automated prescription renewal captures recurring revenue from employer vision benefit integration. |
| Telehealth Refraction Deployment | Provincial scope expansions in Prairie provinces open automated vision testing corridors. |
| ISO 12870 Certification Investment | Mechanical stability and nickel-release compliance filters out non-compliant frame competitors. |
Research Approach
Cross-validation between primary interviews with licensed opticians, independent optometrists, optical retail chain procurement managers, and lens-finishing equipment technicians anchors the qualitative findings against secondary validation from FDA 510(k) filings, FTC regulatory dockets, ANSI standards documentation, and trade data from USMCA corridor freight flows. Bottom-up demand modeling across prescription glasses, contact lenses, and protective eyewear segments triangulates with top-down market sizing from import-export records and employer vision benefit plan disclosures.
Sensitivity analysis around silicone hydrogel material approval timelines, acetate input cost volatility, and licensed optician staffing gaps stress-tests base-case assumptions across the analysis window. Segmentation dimensions modeled include product type, frame material tier, end-user life stage, and sales channel structure. CAGRs derive from regression analysis against demographic aging curves and UV exposure indices. Industry-specific forecast inputs incorporate Medicare Advantage vision benefit penetration rates and provincial telehealth scope-of-practice expansion trajectories.
Material uncertainties — FDA contact lens material approval delays, rare earth metal supply disruptions, and state-level regulatory fragmentation on online refraction — sit outside the modeled envelope. Forecasts reflect documented assumptions about demographic aging, regulatory enforcement intensity, and channel migration velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Sunglasses Market
Eyewear
Goggles Market
Eyewear
Glasses Frame Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Wooden Eyewear Market
Eyewear
United States Eyewear Market
Eyewear
Eyewear Market
Eyewear
Latin America Eyewear Market
Eyewear
Asia-Pacific Eyewear Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Ultralight Eyeglass Frames Market
Eyewear
Smart Sunglasses Market
Eyewear
Middle East Eyewear Market
Eyewear
Spectacles Market
Eyewear
Luxury Eyewear Market