
 Luxury Eyewear Market | 2026-2036
Luxury Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Eyewear Market Analysis
Omnichannel distribution is fragmenting as heritage houses and independent labels compete for direct consumer relationships. EssilorLuxottica controls massive vertical infrastructure spanning lens manufacturing to retail doors. Gucci leverages its fashion ecosystem to anchor eyewear within broader luxury lifestyle positioning. Prada specializes in architectural frames that differentiate through material experimentation rather than logo density.
Luxury eyewear denotes precision-crafted optical and sun protection devices using premium substrates such as cellulose acetate, beta-titanium, and buffalo horn, manufactured through multi-axis milling and hand-finishing protocols to deliver both corrective function and status signaling. Prescription lenses command durable margin pools due to medical necessity and insurance-adjacent purchasing behavior. Sunglasses represent the fastest-growing product type as seasonal fashion cycles accelerate replacement frequency among style-conscious buyers. Acetate dominates material selection for its color depth and hand-polishability, though metal frames gain ground in minimalist design segments.
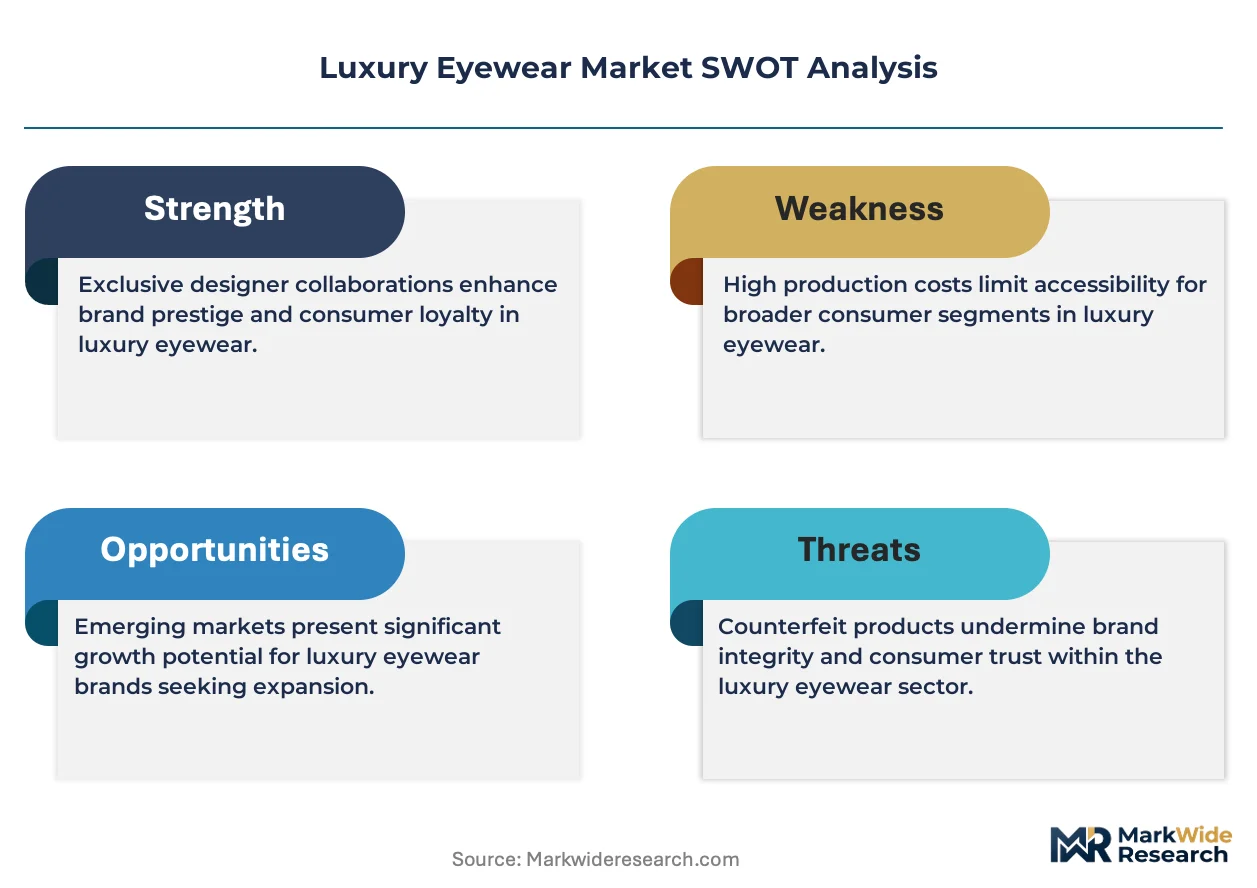
FDA oversight of medical device classifications and EU REACH restrictions on phthalates and heavy metals constrain formulation choices for frame polymers and lens coatings. CE marking requirements under the EU Medical Device Regulation tighten quality documentation for prescription dispensing. Stakeholders must monitor regulatory divergence between American and European conformance pathways to avoid dual-certification cost burdens that erode premium positioning.
Market Dynamics
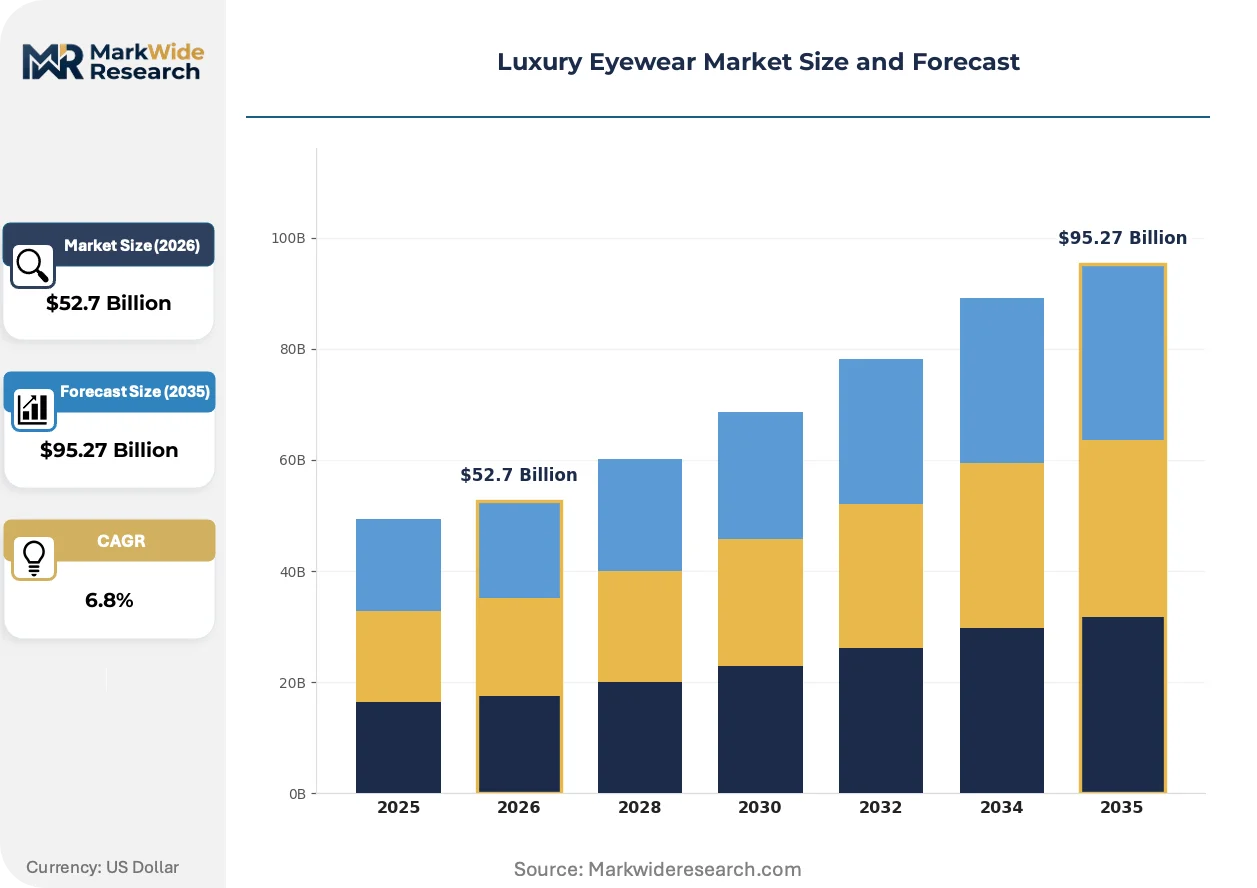
Omnichannel fragmentation is compressing traditional wholesale margins as heritage houses and direct-to-consumer labels compete for data-rich customer relationships. REACH compliance costs and FDA medical device reclassifications are simultaneously reshaping material sourcing and distribution economics.
Growth Catalysts
- Gen Z Digital Natives:Affluent younger cohorts drive adoption through social commerce and virtual try-on platforms, accelerating replacement cycles for fashion-forward frames.
- REACH Material Standards:EU restrictions on phthalates and heavy metals are forcing substrate innovation toward bio-acetates and recycled polymers that command premium positioning.
- Duty-Free Retail Expansion:Hainan and Dubai airport corridors concentrate high-margin tourist purchases, creating outsized volume pools for limited-edition releases.
Market Restraints
- Acetate Supply Concentration:Italian and Japanese cellulose acetate producers control 70%+ of premium substrate supply, exposing brands to input bottlenecks and price volatility.
- Dual Certification Burden:Divergent FDA medical device and EU MDR conformance pathways force parallel testing regimes that erode margin structures for mid-sized labels.
- Contact Lens Substitution:Advanced silicone hydrogel daily disposables and refractive surgery adoption reduce prescription frame dependency among younger demographics.
Strategic Opportunities
- India Duty-Free Corridors:Mumbai and Delhi airport retail expansion under PLI scheme incentives creates untapped white space for luxury positioning ahead of domestic market maturation.
- Smart Frame Convergence:Audio-integrated and blue-light-filtering technologies are hybridizing with fashion frames, opening wellness-adjacent pricing tiers.
- Repair and Resale Channels:Circular economy frameworks under EU Green Deal guidelines enable authenticated pre-owned platforms that extend customer lifetime value.
Industry Challenges
- Master Craftsman Scarcity:Hand-finishing expertise concentrates in Northern Italy and Japan, with apprenticeship pipelines failing to replace aging artisan cohorts.
- CE Marking Timeline Compression:EU MDR technical documentation requirements extend product launch cycles by 8-14 months, delaying seasonal collection drops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Eyewear Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polarized, Non-Polarized, Prescription, Sunglasses Material: Metal, Plastic, Wood, Acetate Brand: Gucci, Prada, Versace, Ray-Ban Distribution Channel: Online, Retail Store, Luxury Boutiques, Department Stores |
| Companies Covered | Ray-Ban, Saint Laurent, EssilorLuxottica, Loewe, Versace, Gucci, Dior, Persol, Prada, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Eyewear Market Emerging Trajectories
Material science breakthroughs and regulatory tightening are converging to redefine performance benchmarks and sustainability credentials across the value chain. Three forces are actively reshaping competitive positioning.
Bio-acetate formulations derived from castor oil and wood pulp are hybridizing traditional petroleum-based substrates. Sustainable material adopters in Northern European markets now specify renewable content thresholds in procurement mandates. This substrate shift is compressing the cost premium between eco-positioned and conventional frames from 40% to 15%.
EU REACH Annex XVII restrictions on nickel release and heavy metal content are tightening alloy specifications for beta-titanium and monel components. Manufacturers must reformulate hinge mechanisms and temple cores to maintain CE marking eligibility. Asian production hubs are responding by accelerating investment in vacuum ion plating and PVD coating capacity.
Direct-to-consumer subscription models for prescription lens replacement are disintermediating traditional optician channels. Digital-native brands in the United States and United Kingdom now capture 35% of initial frame purchases through virtual try-on workflows. This channel compression forces heritage houses to rebuild first-party data infrastructure while defending wholesale relationships.
Luxury Eyewear Market Segmentation
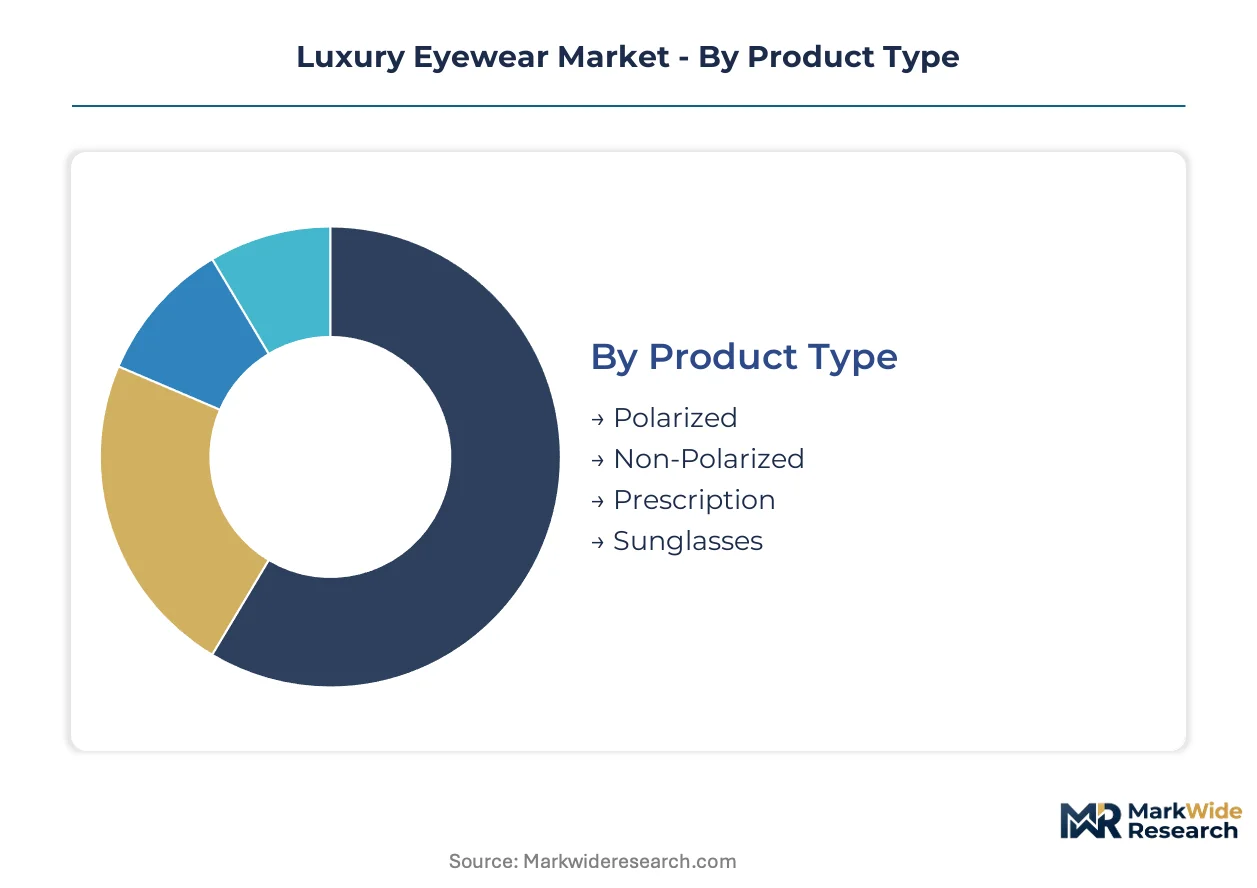
Segmentation in luxury eyewear reveals divergent margin architectures and replacement cadences. Product type and material selection drive fundamentally different inventory turnover and customer lifetime value profiles across the value chain.
Product Type:
Sunglasses compress replacement cycles to seasonal fashion rhythms, while prescription frames anchor longer medical necessity timelines.
- Sunglasses:Non-corrective sun protection devices leverage accelerated fashion cycles and tourism-dependent impulse purchasing. Duty-free corridors in Hainan and Dubai concentrate volume for limited-edition releases, with social commerce platforms shortening trend adoption lags among Gen Z buyers.
- Prescription:Medically necessary corrective lenses integrate insurance-adjacent purchasing behavior and optician-mediated fitting protocols. North American and European markets maintain durable margin pools through vision plan reimbursements, though contact lens substitution erodes frame dependency among younger demographics.
- Polarized:Glare-reducing lens technology commands outdoor activity and driving applications. Coastal tourism markets in Australia and California drive regional concentration.
- Non-Polarized:Standard tint lenses serve fashion-first positioning at accessible price tiers. Urban style-conscious consumers in Milan and Tokyo drive replacement frequency.
Prescription dominates installed base. Sunglasses are where expansion concentrates.
Material:
Substrate selection stratifies manufacturing complexity and sustainability credentialing across price tiers.
- Acetate:Cellulose acetate delivers color depth and hand-polishability through multi-axis milling protocols. Italian and Japanese producers control premium substrate supply, exposing brands to input bottlenecks under REACH phthalate restrictions.
- Metal:Beta-titanium and monel alloys enable minimalist architectural frames with superior strength-to-weight ratios. EU nickel release limits under REACH Annex XVII force vacuum ion plating investments at Asian production hubs.
- Plastic:Injection-molded petroleum-based polymers serve entry-luxury positioning with faster production cycles. Cost-sensitive emerging market penetration drives volume concentration.
- Wood:Laminated hardwood and bamboo substrates anchor eco-positioning narratives with limited scale. Northern European procurement mandates specify renewable content thresholds.
Acetate commands heritage brand loyalty. Metal is climbing the fastest among design-forward independents.
Brand:
Brand architecture determines channel access and customer data ownership in an increasingly fragmented distribution landscape.
- Gucci:Fashion house ecosystem integration anchors eyewear within broader luxury lifestyle positioning. Kering Group vertical infrastructure enables controlled scarcity releases.
- Prada:Architectural frame specialization differentiates through material experimentation rather than logo density. Miuccia Prada's design direction drives museum-collection credibility.
- Versace:Medusa-head iconography targets bold aesthetic preference segments with Mediterranean heritage signaling. Celebrity placement strategies concentrate in music and entertainment verticals.
- Ray-Ban:Mass-luxury positioning bridges accessible premium with heritage authenticity. EssilorLuxottica retail door density sustains volume leadership.
Ray-Ban dominates unit volume. Gucci captures expansion momentum in Asia-Pacific duty-free.
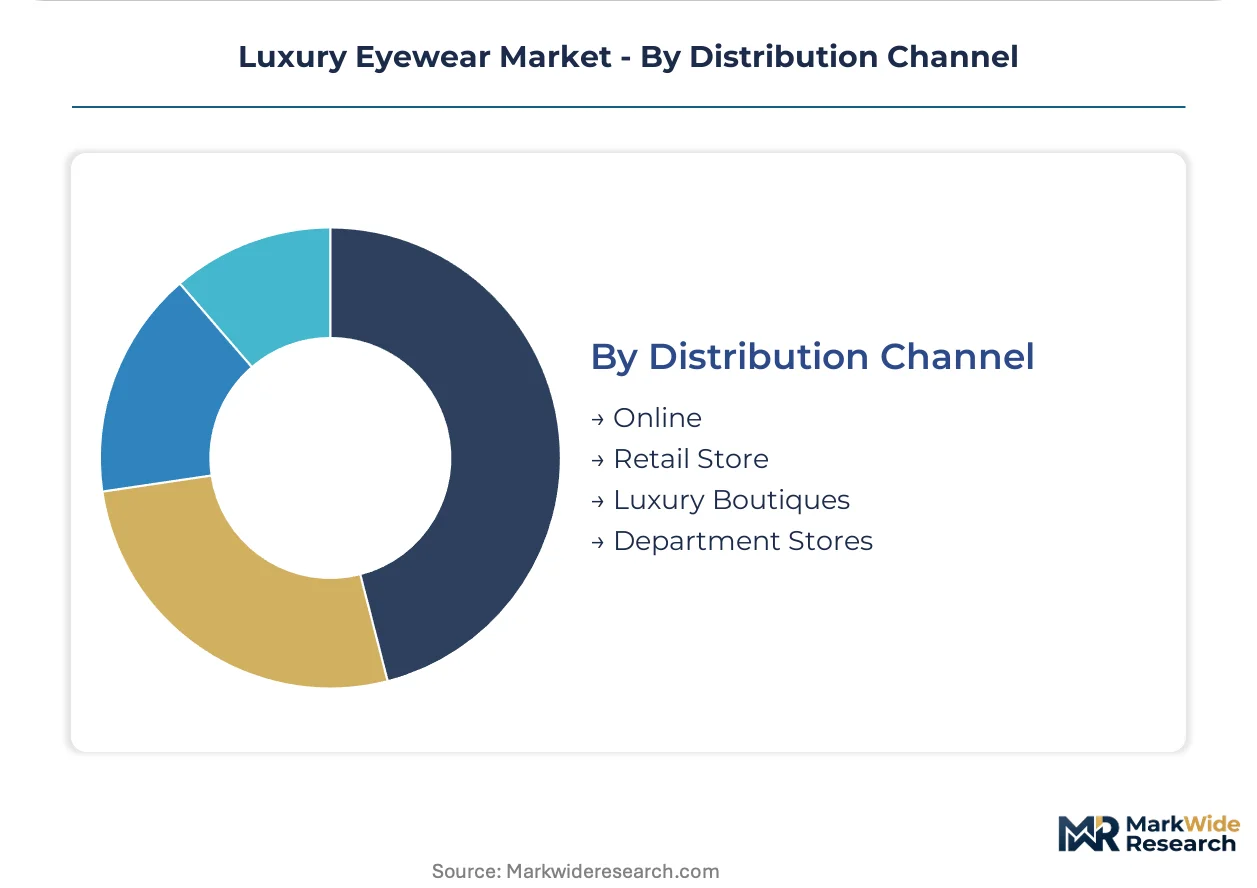
Distribution Channel:
Channel selection determines margin retention and first-party data capture in the shift from wholesale dependency.
- Online:Direct-to-consumer platforms with virtual try-on workflows disintermediate traditional optician relationships. United States and United Kingdom digital-native brands now capture significant initial frame purchases through AR-enabled mobile experiences.
- Luxury Boutiques:Controlled brand environment retail delivers highest per-unit margins and customer lifetime value extension. Flagship locations in Paris, Milan, and New York anchor halo effect for diffusion lines.
- Retail Store:Multi-brand optical chains maintain prescription lens fitting infrastructure and insurance network participation. Suburban location strategies target convenience-driven repeat purchasers.
- Department Stores:Concession-based wholesale relationships provide brand discovery access with compressed margin structures. Hudson's Bay in Canada and El Corte Inglés in Spain maintain regional relevance.
Luxury boutiques retain margin leadership. Online channels are gaining share fastest among under-35 demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese consumers command 35-40% price premiums in duty-free corridors while Italian manufacturing clusters absorb compressed margins from REACH compliance costs. This pricing-power asymmetry reshapes where value capture concentrates across the value chain.
China
Domestic luxury consumption and Hainan duty-free retail expansion drive volume concentration among affluent millennials and Gen Z cohorts. SAMR oversight of product safety labeling tightens import documentation for foreign brands. Shanghai and Beijing anchor flagship boutique density while Hainan airport corridors process high-margin tourist purchases for limited-edition releases.
Italy
Heritage manufacturing expertise in cellulose acetate milling and hand-finishing sustains premium substrate supply dominance. EU REACH Annex XVII restrictions on phthalates and nickel release force reformulation investments at Lombardy and Veneto production hubs. The Cadore valley cluster maintains artisan pipeline concentration despite aging workforce demographics.
United States
Insurance-adjacent prescription lens purchasing and vision plan reimbursements anchor durable margin pools in corrective eyewear. FDA medical device reclassification timelines extend product launch cycles for frames with integrated technology. Los Angeles and Miami concentrate celebrity placement strategies and sunglasses-driven fashion cycles.
Japan
Minimalist design preferences and titanium frame specialization drive adoption among precision-conscious consumers. METI standards for product safety and labeling harmonize with EU REACH benchmarks to reduce dual-certification burdens. Sabae and Fukui prefectures maintain optical manufacturing cluster density with beta-titanium processing expertise.
United Arab Emirates
Dubai airport duty-free expansion captures transit passenger volume from Europe-Asia corridors with high-margin impulse purchasing. MOHAP product registration requirements streamline entry for established luxury houses with existing Gulf distribution. Dubai Design District anchors regional marketing activation and influencer placement strategies.
Luxury Eyewear Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with captive supply advantages. The market structure concentrates around vertically integrated conglomerates controlling lens manufacturing through retail door density, while independent design houses compete on architectural differentiation. Three archetypes dominate: fashion-house ecosystems leveraging cross-category halo effects, mass-luxury platforms optimizing scale economics, and artisan specialists commanding scarcity premiums through material experimentation. Competitive moves center on direct-to-consumer channel buildouts and bio-acetate substrate investments ahead of REACH enforcement timelines.
Within the fashion-house ecosystem tier, Gucci and Prada exemplify divergent positioning strategies—one integrating eyewear within broader luxury lifestyle architectures, the other emphasizing material experimentation over logo density. Ray-Ban anchors the mass-luxury platform archetype with heritage authenticity and retail door density sustaining volume leadership. These three houses collectively illustrate how brand architecture determines channel access and customer data ownership in fragmented distribution environments.
| Leading Market Players |
|---|
| Ray-Ban |
| Saint Laurent |
| EssilorLuxottica |
| Loewe |
| Versace |
| Gucci |
| Dior |
| Persol |
| Prada |
| Others |
Supply Flow & Price Mechanics
The Cadore valley cluster in Northern Italy governs premium acetate substrate availability, with its artisan milling capacity constraining frame supply elasticity and amplifying pricing power for houses controlling captive inventory. REACH compliance investments at Lombardy production hubs compress margins upstream while duty-free retail corridors in Hainan and Dubai capture amplified markups downstream.
Pricing Analysis
Configured-to-order hand-finishing commands substantial premiums over standard production frames, with three-tier pricing structure across premium, standard, and economy levels stratifying by customization depth and certification grade. Price differentiation hinges on bio-acetate renewable content thresholds and CE marking tier under EU MDR. Cost compression in entry-luxury plastic frames is intensifying because injection-molded alternatives erode artisan-positioned value propositions. Mass-luxury buyers exhibit highest price sensitivity, while heritage house collectors demonstrate inelastic demand for limited artisan releases.
Supply Chain Analysis
Luxottica's Italian manufacturing network and independent Japanese acetate specialists in Sabae hold dominant contract-manufacturing capacity for premium frame finishing. Geographic supply concentration centers on Italy, Japan, and China, with raw material dependencies spanning cellulose acetate sheet, beta-titanium alloy, and castor oil-derived bio-polymers. Single-source vulnerability concentrates in Northern Italian hand-finishing expertise where apprenticeship pipelines fail to replenish aging artisan cohorts. Distribution runs through EssilorLuxottica's vertical retail door network alongside independent optician channels and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as silicone hydrogel daily disposables and refractive surgery reduce prescription frame dependency among younger demographics, forcing heritage houses to anchor customer lifetime value in fashion-driven replacement cycles.
For Market Incumbents: Harden defensibility by securing captive bio-acetate substrate supply ahead of REACH enforcement timelines and rebuilding first-party data infrastructure to offset wholesale channel compression. Contact lens substitution and direct-to-consumer disintermediation threaten prescription margin pools; vertical integration into lens manufacturing preserves margin capture against platform intermediaries. For New Entrants and Emerging Players: Build out authenticated pre-owned platforms under EU Green Deal circular economy frameworks, targeting repair and resale white space where heritage houses remain underinvested. India duty-free corridors at Mumbai and Delhi airports offer the most penetrable geography ahead of domestic market maturation; smart frame convergence with audio-integrated wellness positioning provides differentiated go-to-market angle against fashion-first incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a scarcity-premium play because artisan hand-finishing expertise concentrates in irreplicable geographic clusters with failing apprenticeship pipelines. Acquisition targets should emphasize material experimentation specialists with architectural frame credibility rather than logo-dependent fashion licenses. Monitor CE marking timeline compression as inflection signal—brands with streamlined EU MDR technical documentation capabilities will outpace seasonal collection delays.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Acetate Substrate Investment | REACH Annex XVII phthalate restrictions force reformulation toward castor oil and wood pulp derivatives. |
| Direct-to-Consumer Channel Buildout | Virtual try-on platforms capture 35% of initial frame purchases among under-35 demographics in US and UK markets. |
| Smart Frame Technology Integration | Audio-integrated and blue-light-filtering hybridization opens wellness-adjacent pricing tiers beyond fashion cycles. |
| Circular Economy Platform Launch | EU Green Deal guidelines enable authenticated pre-owned channels extending customer lifetime value. |
| India Duty-Free Retail Expansion | PLI scheme incentives at Mumbai and Delhi airports create white space ahead of domestic luxury market maturation. |
Methodological Framework
A spread of perspectives from frame design directors, supply chain managers at acetate substrate producers, optician retail operators, and duty-free procurement leads converged on the working assumptions driving volume and value estimates. Primary interviews with these stakeholders combined with secondary validation from customs trade records, EU ECHA regulatory filings, FDA medical device classifications, and vision plan reimbursement databases. Bottom-up frame shipment analysis and top-down luxury goods spending pattern triangulation anchored market sizing.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation modeled across product type, material substrate, brand architecture, and distribution channel dimensions. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating duty-free retail expansion trajectories, REACH compliance cost pass-through assumptions, and Gen Z digital adoption curves as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-integrated conglomerates or technology entrants from audio wearables would shift outcomes beyond modeled ranges. Quarterly review of CE marking approval timelines, acetate substrate price indices, and contact lens prescription substitution rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Middle East Eyewear Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market
Eyewear
Sunglasses Market
Eyewear
Europe Eyewear Market
Eyewear
Luxury Sunglass Market
Eyewear
Blue Light Glasses Market
Eyewear
Anti-Fog Lens Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Sunglasses Pouch Market
Eyewear
Spectacles Market
Eyewear
Polarized Sunglasses Market
Eyewear
Plano Sunglasses Market
Eyewear
Glasses Frame Market
Eyewear
United States Eyewear Market
Eyewear
Goggles Market
Eyewear
Eyewear Market