
 Latin America Eyewear Market | 2026-2036
Latin America Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Eyewear Market Intelligence
Multi-source procurement is shifting toward vertically integrated manufacturing across Brazil and Mexico. EssilorLuxottica anchors its regional dominance through captive lens production and controlled retail networks. Chilli Beans competes on localized design cycles and aggressive mall-based expansion. Hoya Corporation leverages high-index lens technology to differentiate in the premium prescription segment.
Latin America eyewear comprises vision correction devices, solar protection lenses, and occupational safety frames, typically fabricated from cellulose acetate, titanium alloys, or polycarbonate substrates with anti-reflective and photochromic coatings, serving refractive correction, UV blocking, and impact resistance purposes. Prescription glasses and sunglasses occupy the largest revenue pools, while contact lenses capture above-average margins due to recurring purchase cycles and practitioner-dependent fitting requirements. Online retailers represent the fastest-growing distribution channel, though optical stores sustain the majority of fitting-dependent transactions across the region.
ANVISA governs medical device registration for contact lenses in Brazil, while Mexico's COFEPRIS enforces equivalent safety protocols; both frameworks mandate clinical validation that slows foreign brand entry. The EU- Mercosur trade negotiations could reshape tariff structures for acetate frames and finished lenses. Stakeholders must monitor regulatory harmonization timelines and local content requirements to optimize manufacturing footprints and channel investments.
Market Dynamics
ANVISA's tightened contact lens safety standards in Brazil are forcing importers to absorb elevated compliance costs while redirecting procurement toward vertically integrated regional manufacturers who control captive lens production.
Growth Catalysts
- Fashion-forward consumption:Young consumers across Brazil, Mexico, and Colombia treat eyewear as accessories with seasonal refresh cycles, expanding volume beyond pure vision correction needs.
- COFEPRIS harmonization:Mexico's streamlined medical device registration for contact lenses reduces foreign brand entry timelines, accelerating product variety in optical retail chains.
- High-index materials:Polycarbonate and titanium alloy substrates enable thinner, lighter prescription lenses that command premium positioning in urban markets.
Market Restraints
- Acetate supply concentration:Cellulose acetate frame production depends on Asian chemical suppliers, exposing Latin American fabricators to input cost volatility and currency mismatch risks.
- Clinical validation barriers:ANVISA and COFEPRIS mandate practitioner-dependent fitting protocols for contact lenses, creating structural friction against direct-to-consumer distribution models.
- Optical retail consolidation:Controlled networks in São Paulo and Mexico City concentrate shelf access, squeezing independent frame brands on margin and visibility.
Strategic Opportunities
- Colombian market penetration:Bogotá and Medellín optical chains show underdeveloped premium sunglass segments relative to São Paulo, offering first-mover positioning for design-led entrants.
- Online channel expansion:E-commerce platforms bypass fitting-dependent transactions for non-prescription sunglasses, capturing consumers outside major metropolitan optical corridors.
- EU-Mercosur tariff restructuring:Pending trade negotiations could reduce import duties on finished acetate frames, reshaping cost structures for European brands targeting Brazil.
Industry Challenges
- Licensed optician scarcity:Brazil and Mexico face shortages of certified contact lens fitters, constraining expansion speed for practitioner-dependent lens brands.
- Anti-reflective coating certification:Multi-layer coating technologies require capital-intensive vacuum deposition equipment, elevating break-even thresholds for mid-scale laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Eyewear Market |
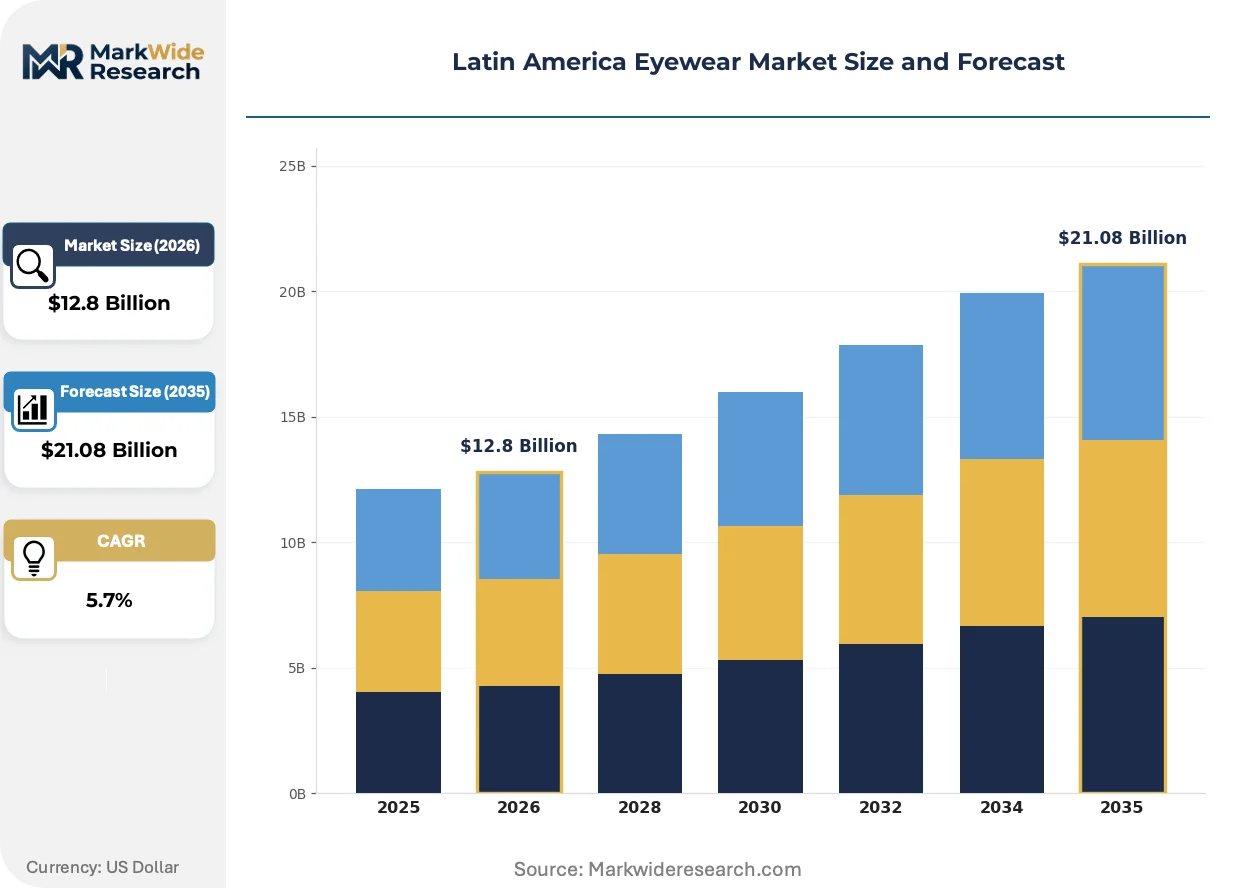
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Glasses, Sunglasses, Contact Lenses, Safety Eyewear, Sports Eyewear Material: Plastic, Metal, Titanium, Acetate, Wood Distribution Channel: Optical Stores, Online Retailers, Department Stores, Specialty Clinics, Pharmacies End User: Adults, Children, Athletes, Industrial Workers, Fashion Enthusiasts |
| Companies Covered | Bausch Health, Carl Zeiss Meditec, EssilorLuxottica, Chilli Beans, Safilo Group, Johnson & Johnson Vision Care, Alcon, Hoya Corporation, CooperVision, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Eyewear Market Strategic Shifts & Innovations
Digital measurement tools and photochromic coating advances are compressing traditional fitting workflows while expanding functional use cases beyond static indoor-outdoor environments.
Freeform lens surfacing technology is integrating computer-controlled diamond-point turning to produce customized progressive prescriptions with reduced peripheral distortion. Urban optical chains in São Paulo and Mexico City are adopting these systems to differentiate on precision fitting. The technology is integrating vertically into captive laboratory networks, compressing reliance on centralized European finishing facilities.
COFEPRIS and ANVISA are tightening post-market surveillance for silicone hydrogel contact lenses, mandating adverse event reporting that elevates ongoing compliance burdens. Foreign manufacturers must maintain local pharmacovigilance representatives, increasing operational fixed costs. Daily disposable lens categories face the steepest documentation requirements, pushing some suppliers toward quarterly replacement modalities with lighter surveillance obligations.
Optical retail procurement is consolidating through exclusive brand arrangements that displace open-frame buying. Mall-based chains in Brazil now demand category-exclusivity contracts from domestic designers, fragmenting shelf access for independent labels. This concentration is most visible in Rio de Janeiro and Buenos Aires, where landlord-controlled shopping centers amplify retailer negotiating leverage over frame suppliers.
Latin America Eyewear Market Segmentation
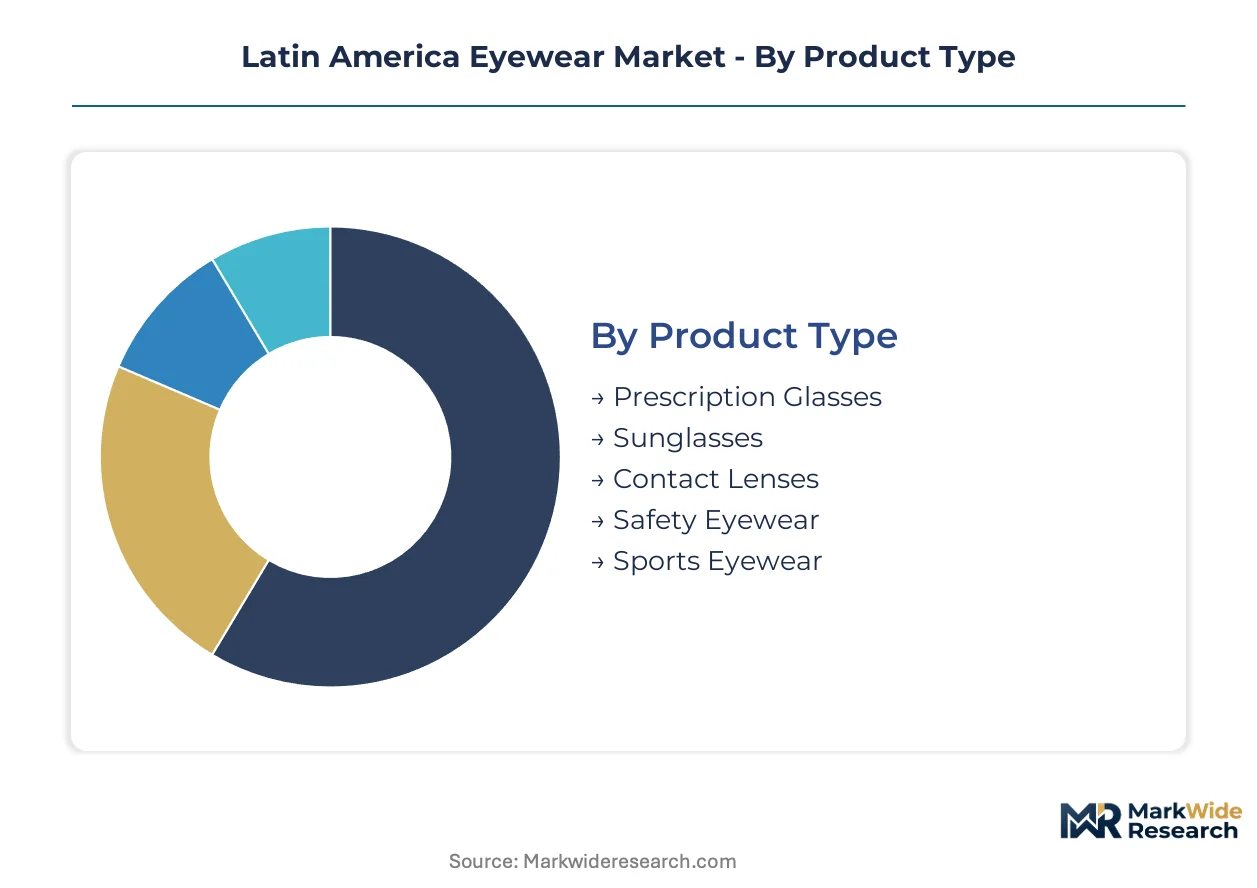
Latin America's eyewear market fragments across five distinct product categories, each commanding separate supply chains and margin structures. Material composition and distribution channel choices determine pricing power and geographic reach across Brazil, Mexico, and Colombia.
Product Type:
Supply concentration varies sharply across product categories, with lens fabrication and frame assembly often splitting between captive manufacturers and independent importers.
- Prescription Glasses:Fabricated from cellulose acetate, titanium alloys, or polycarbonate substrates with anti-reflective coatings. Demand concentrates in São Paulo and Mexico City optical corridors, where ANVISA and COFEPRIS compliance requirements favor established laboratory networks with captive finishing capacity.
- Sunglasses:Solar protection lenses typically use CR-39 or polycarbonate with UV400 filtration and polarized film lamination. Colombian optical chains in Bogotá and Medellín show underdeveloped premium positioning, creating first-mover openings for design-led entrants against Brazilian market saturation.
- Contact Lenses:Silicone hydrogel and daily disposable modalities dominate practitioner-dependent fitting protocols.
- Safety Eyewear:Impact-resistant polycarbonate frames serve occupational mandates in Brazilian manufacturing zones.
- Sports Eyewear:Wraparound designs with photochromic coatings target athlete segments in coastal Brazilian markets.
Prescription glasses absorb the bulk of installed capacity; sports eyewear is expanding most quickly.
Material:
Cost tier stratification separates premium positioning from mass-market penetration, with raw material sourcing determining regional manufacturing feasibility.
- Plastic:Injection-molded TR-90 and polycarbonate frames dominate entry-level price bands across Latin American pharmacy chains.
- Metal:Stainless steel and monel alloys enable mid-tier optical retail positioning in Mexican urban corridors.
- Titanium:Beta-titanium and pure titanium substrates command premium prescription positioning through reduced weight and hypoallergenic properties. Demand clusters in São Paulo's high-income districts, where EssilorLuxottica's captive networks exploit Japanese-sourced alloy supply.
- Acetate:Cellulose acetate sheet production depends on Asian chemical suppliers, exposing Brazilian fabricators to input cost volatility and currency mismatch risks.
- Wood:Sustainable frame alternatives target eco-conscious consumers in Colombian and Argentine boutique optical channels.
Acetate captures the majority of fashion-forward frame production; titanium is climbing the fastest on premium prescription demand.
Distribution Channel:
Volume concentration favors physical retail, though digital penetration is reshaping non-prescription categories.
- Optical Stores:Mall-based chains in Rio de Janeiro and Buenos Aires concentrate shelf access through exclusive brand arrangements. Chilli Beans exploits this channel with localized design cycles and aggressive expansion.
- Online Retailers:E-commerce platforms bypass fitting-dependent transactions for non-prescription sunglasses. Brazilian logistics infrastructure constraints limit rural penetration despite metropolitan success.
- Department Stores:Mid-tier positioning serves occasional purchasers in Mexican and Colombian urban centers.
- Specialty Clinics:Ophthalmologist-affiliated dispensing controls high-margin progressive lens fittings.
- Pharmacies:Over-the-counter reading glasses and basic sunglasses dominate Brazilian drugstore chains.
Optical stores command the largest transaction volume; online retailers are gaining share fastest on sunglasses penetration.
End User:
Customer type segmentation aligns product specification with functional requirement intensity and replacement frequency.
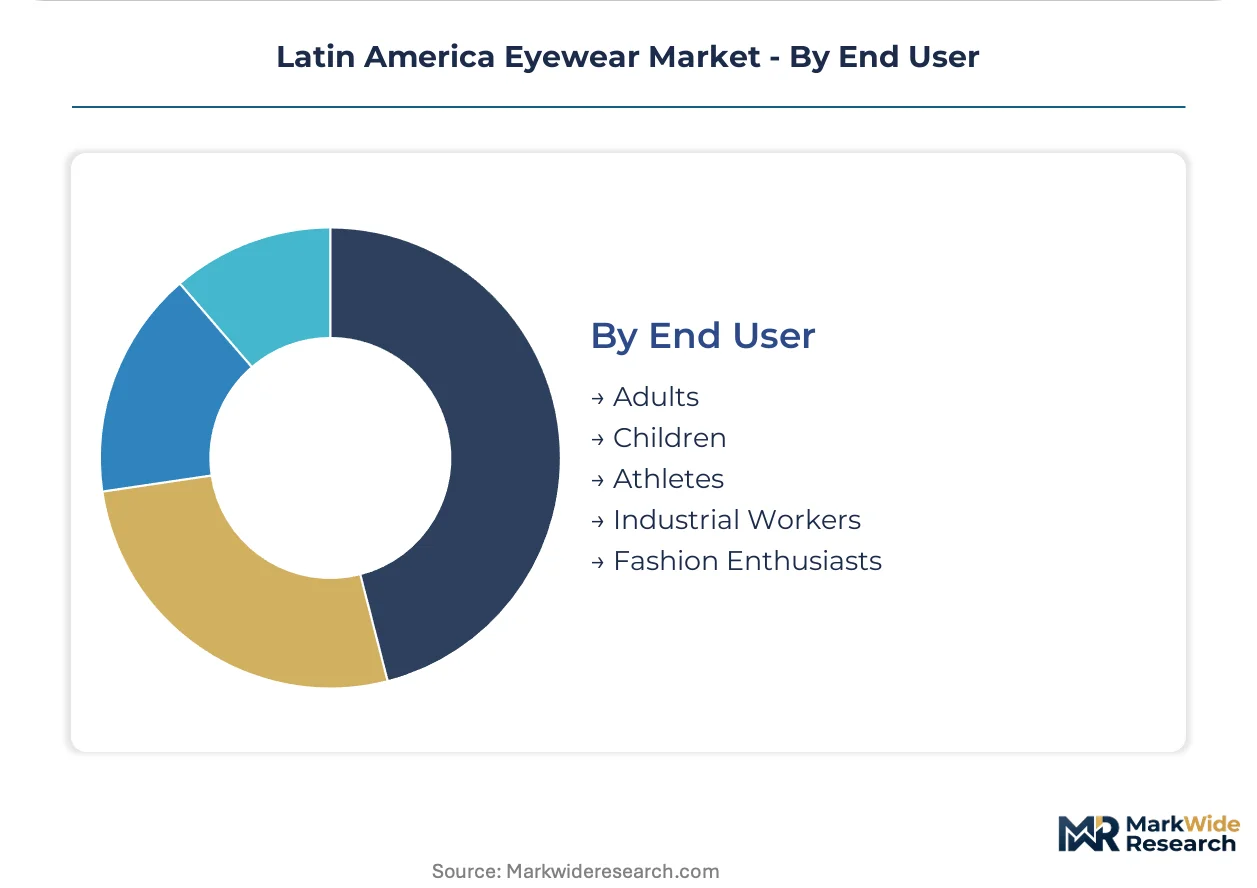
- Adults:Progressive lens demand and multifocal prescriptions drive recurring optical store visits. Brazil's aging demographic expands this segment through presbyopia correction needs.
- Children:Myopia management protocols and impact-resistant polycarbonate requirements shape pediatric specialist channel development.
- Athletes:Performance-oriented frame geometry and interchangeable lens systems serve cycling and running communities in Colombian mountain cities.
- Industrial Workers:ANSI Z87.1 and local equivalent certifications mandate safety eyewear in Brazilian manufacturing.
- Fashion Enthusiasts:Seasonal refresh cycles and accessory-driven purchasing expand volume beyond vision correction. Young consumers across Brazil, Mexico, and Colombia treat frames as apparel complements with quarterly replacement patterns.
Adults represent the deepest installed base; fashion enthusiasts are expanding most quickly on accessory-driven consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil, Mexico, and Colombia, where optical retail chains and fashion consumption drive volume expansion. Urban corridors in São Paulo, Mexico City, and Bogotá absorb premium positioning, while regulatory frameworks in each market reshape competitive access.
Brazil
Fashion enthusiasts and aging demographics fuel prescription and sunglass demand across São Paulo and Rio de Janeiro. ANVISA tightened contact lens safety standards, elevating compliance costs for importers and redirecting procurement toward vertically integrated domestic manufacturers. Mall-based optical chains in Rio de Janeiro concentrate shelf access through exclusive brand arrangements, squeezing independent frame suppliers.
Mexico
COFEPRIS harmonization accelerates foreign brand entry for contact lenses, expanding product variety in optical retail chains. Streamlined medical device registration reduces timelines for silicone hydrogel approvals. Mexico City optical corridors anchor premium eyewear demand, with expanding chains capturing fitting-dependent transactions.
Colombia
Bogotá and Medellín optical chains show underdeveloped premium sunglass segments relative to Brazilian saturation, offering first-mover positioning for design-led entrants. Localized design cycles and aggressive mall-based expansion characterize competitive moves. Colombian boutique optical channels increasingly stock sustainable wood-frame alternatives targeting eco-conscious consumers.
Argentina
Landlord-controlled shopping centers in Buenos Aires amplify retailer negotiating leverage over frame suppliers, consolidating procurement through exclusive brand arrangements. Currency volatility exposes fabricators to input cost pressures on imported acetate substrates. Optical retail networks prioritize established European and regional brands over independent labels.
Chile
Coastal urban markets in Valparaíso and Santiago drive sports eyewear demand with photochromic coatings targeting cycling and running communities. Practitioner-dependent fitting protocols for contact lenses constrain direct-to-consumer distribution expansion. Specialty clinics affiliated with ophthalmologists control high-margin progressive lens fittings in Santiago's affluent districts.
Latin America Eyewear Market Key Industry Players
Vertical integration dominates the current landscape, with captive lens production and controlled retail networks reshaping procurement patterns. The market structure concentrates around multinational conglomerates with backward integration into lens fabrication, mid-scale regional designers competing on localized aesthetics, and specialized contact lens manufacturers dependent on practitioner networks. Three archetypes define positioning: integrated conglomerates with captive laboratories, design-led regional brands with rapid cycle capabilities, and technology-differentiated lens specialists. M&A activity and exclusive retail distribution contracts represent the dominant competitive moves.
Among integrated conglomerates, EssilorLuxottica anchors regional dominance through captive supply chains and controlled optical networks. Chilli Beans exemplifies the design-led regional archetype, competing on localized aesthetics and aggressive mall-based expansion. Hoya Corporation occupies a position within the technology-differentiated tier, leveraging high-index lens capabilities to distinguish premium prescription offerings.
| Leading Market Players |
|---|
| Bausch Health |
| Carl Zeiss Meditec |
| EssilorLuxottica |
| Chilli Beans |
| Safilo Group |
| Johnson & Johnson Vision Care |
| Alcon |
| Hoya Corporation |
| CooperVision |
| Others |
Cost & Logistics Intelligence
ANVISA's post-market surveillance mandates for silicone hydrogel contact lenses gate qualified supply access while elevating compliance burdens that premium-tier manufacturers absorb into pricing structures. This regulatory filter compresses margin elasticity for importers while rewarding vertically integrated domestic producers with captive laboratory networks.
Pricing Analysis
The volume-mass split separates high-turnover pharmacy reading glasses from premium prescription progressives commanding sustained margin capture. Three-tier pricing structure across premium, standard, and economy levels stratifies by lens material index and coating certification tier. Cost compression in entry-level acetate frames intensifies because Asian chemical supplier concentration exposes Brazilian fabricators to currency mismatch risks. Pharmacy chains exhibit acute price sensitivity, while ophthalmologist-affiliated specialty clinics tolerate premium positioning for customized progressive fittings.
Supply Chain Analysis
Licensed optician scarcity in São Paulo and Mexico City constrains manufacturing scale-up for practitioner-dependent contact lens modalities. Raw material sourcing draws from Japanese beta-titanium suppliers, Italian acetate sheet producers, and Chinese polycarbonate substrate manufacturers. Single-source vulnerability concentrates in cellulose acetate chemical precursors from Asian suppliers. Distribution runs through mall-based optical chains in Rio de Janeiro and Buenos Aires that demand exclusive brand arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America eyewear market functions as a vertical-integration race where captive lens production and controlled retail networks determine competitive endurance. Players pursue backward integration into finishing laboratories to escape dependency on centralized European facilities.
For Market Incumbents: To counter COFEPRIS and ANVISA post-market surveillance burdens, EssilorLuxottica and Hoya Corporation should deepen captive laboratory networks in São Paulo and Mexico City while securing exclusive shelf arrangements with landlord-controlled shopping centers. Certification investment in multi-layer anti-reflective coating deposition equipment preserves premium-tier positioning against mid-scale competitors. For New Entrants and Emerging Players: Boutique optical channels in Bogotá and Medellín offer underexploited premium sunglass positioning relative to Brazilian saturation. Design-led regional brands should target Colombian eco-conscious consumers with sustainable wood-frame alternatives while exploiting e-commerce platforms for non-prescription sunglasses outside metropolitan optical corridors. For Investors and Strategic Acquirers: COFEPRIS harmonization reducing foreign brand entry timelines is the leading indicator that Mexican contact lens distribution assets will appreciate as practitioner network anchors. Acquisition targets should concentrate on vertically integrated mid-scale laboratories with captive finishing capacity and established optician training pipelines. Watch ANVISA adverse event reporting frequency as the signal for compliance cost trajectory inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Laboratory Network Expansion | Backward integration into freeform surfacing reduces dependency on European finishing facilities. |
| Exclusive Retail Distribution Contracts | Mall-based chains in Rio de Janeiro and Buenos Aires concentrate shelf access against independents. |
| Regulatory Certification Investment | ANVISA and COFEPRIS compliance elevates barriers against direct-to-consumer contact lens entrants. |
| Localized Design Cycle Acceleration | Seasonal refresh patterns in Brazil and Colombia reward rapid-response frame development capabilities. |
| E-commerce Platform Development | Online channels bypass fitting-dependent transactions for non-prescription sunglasses in secondary cities. |
Research Approach
Trade databases, regulatory filings, and optical industry association reports formed the secondary backbone for this analysis. Primary interviews with optical retail chain procurement directors, licensed contact lens fitters, ophthalmologist clinic administrators, and frame manufacturing plant managers validated demand patterns and pricing dynamics. Bottom-up and top-down triangulation reconciled laboratory capacity estimates with retail transaction volume surveys across São Paulo, Mexico City, and Bogotá corridors.
Bottom-up modeling aggregated segment-level demand across prescription glasses, sunglasses, contact lenses, and safety eyewear categories. Segmentation dimensions included material substrate, distribution channel, and end-user archetype throughout the forecast period. CAGRs derived from fitted trend analysis of historical volume trajectories adjusted for regulatory event impacts and retail network expansion schedules. Forecast inputs incorporated ANVISA compliance cost absorption rates and COFEPRIS approval timeline compression effects.
Several conditions sit outside the modeled scope, including EU-Mercosur trade negotiation outcomes and abrupt currency devaluation events in Argentina or Brazil. Forecasts reflect documented assumptions regarding optician workforce growth and mall-based retail space expansion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Anti-Fog Lens Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Eyewear Market
Eyewear
Spectacles Market
Eyewear
Smart Sunglasses Market
Eyewear
North America Eyewear Market
Eyewear
Goggles Market
Eyewear
Plano Sunglasses Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market
Eyewear
Face and Ear Bow Market
Eyewear
Luxury Eyewear Market
Eyewear
Glasses Frame Market
Eyewear
Middle East Eyewear Market
Eyewear
Asia-Pacific Eyewear Market
Eyewear
Polarized Sunglasses Market