
 Germany DIY Home Improvement Market | 2026-2036
Germany DIY Home Improvement Market Size, Share, and Industry Trends Forecast 2026-2036
Germany DIY Home Improvement Market Foresight
Modular tool and supply bundling is consolidating buyer choice around project-ready kits rather than single-item purchases. OBI leverages its warehouse scale to dominate bundled outdoor and garden categories across German metropolitan zones. Hornbach differentiates through project-center formats that anchor professional contractor traffic alongside homeowner footfall.
Germany DIY home improvement encompasses physical products and installation services for residential modification, repair, and enhancement, spanning power tools with brushless motor specifications, low-VOC paint formulations, and corrosion-resistant fastener grades designed for Central European climate exposure. Its commercial purpose centers on enabling non-professional and semi-professional consumers to execute structural, cosmetic, and functional upgrades to residential properties. Power tools and paints represent mature margin pools where brand loyalty and technical specification density sustain pricing power, while online retailers within distribution channels capture the fastest-growing transaction volume as logistics networks penetrate secondary cities. Specialty stores retain structural importance for high-consideration categories where tactile evaluation and staff consultation drive conversion.
Germany's Federal Ministry for Economic Affairs and Climate Action enforces building energy efficiency standards that mandate thermal insulation and heating system upgrades in existing residential structures, directly stimulating material demand through regulatory obligation. KBA and regional building authorities coordinate product safety certifications for power tools and electrical accessories, shaping market access requirements for domestic and imported inventory. Stakeholders must monitor how the EU Green Deal's embodied carbon tracking requirements will alter sourcing criteria for paints, coatings, and construction fasteners across German retail channels.
Market Dynamics
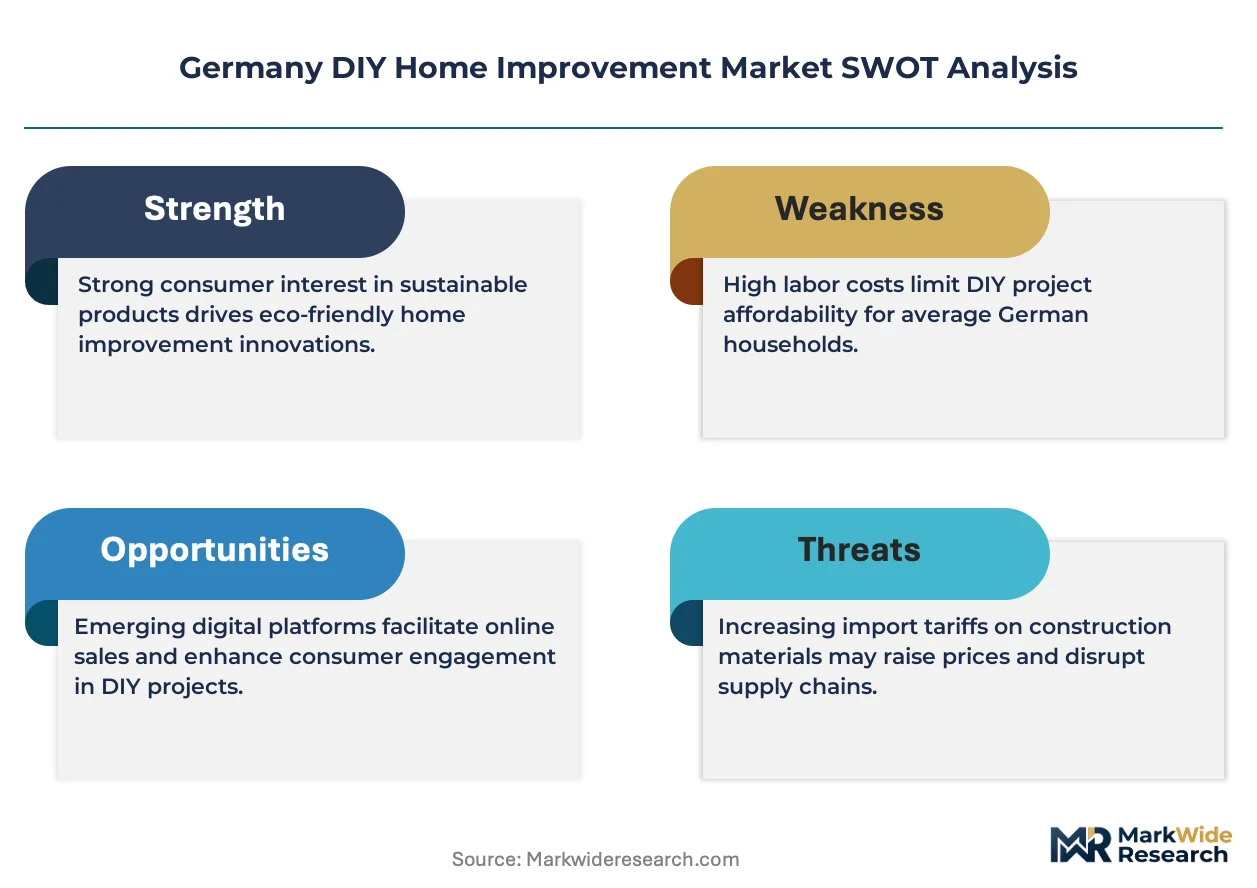
Germany's building energy efficiency mandates are restructuring material demand patterns across the DIY home improvement sector, forcing thermal insulation and heating system upgrades into renovation workflows that previously prioritized cosmetic improvements.
Growth Catalysts
- Building Energy Codes:The Federal Ministry for Economic Affairs and Climate Action enforces thermal insulation mandates in existing residential stock, creating regulatory pull for insulation materials and high-efficiency heating components.
- Bavaria Renovation Concentration:Housing renovation rates in Bavaria and North Rhine-Westphalia exceed other German states, concentrating demand for modular kitchen and bathroom systems in these regions.
- Brushless Motor Adoption:Power tools with brushless motor specifications are penetrating homeowner and semi-professional segments, extending tool lifespan and reducing maintenance intervals.
Market Restraints
- Raw Material Volatility:Copper and rare earth magnet prices for brushless motor production create margin pressure across power tool manufacturing tiers.
- Specialty Retail Concentration:Project-center formats in metropolitan zones dominate high-consideration categories, limiting independent retailer access to professional contractor traffic.
- Low-VOC Formulation Costs:Paint manufacturers face elevated production expenses meeting EU Green Deal embodied carbon tracking requirements for coating formulations.
Strategic Opportunities
- Secondary City Logistics Penetration:Online retailers are capturing transaction volume growth as distribution networks expand beyond Berlin, Munich, and Hamburg into smaller urban centers.
- Modular System Bundling:Project-ready kits consolidating tools, fasteners, and finishing materials present white space for retailers to displace single-item purchasing patterns.
- EU Green Deal Compliance Services:Embodied carbon documentation and sustainable sourcing verification for paints and construction fasteners create advisory revenue streams.
Industry Challenges
- Skilled Installation Labor Scarcity:Thermal insulation and heating system upgrades require certified technician involvement, creating bottlenecks in project completion timelines.
- Multi-Channel Inventory Coordination:Retailers must synchronize stock levels across warehouse-scale formats, project centers, and digital platforms with divergent fulfillment economics.
- Climate-Specification Matching:Fastener and coating suppliers face complexity ensuring corrosion-resistant grades align with Central European humidity and temperature exposure patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany DIY Home Improvement Market |
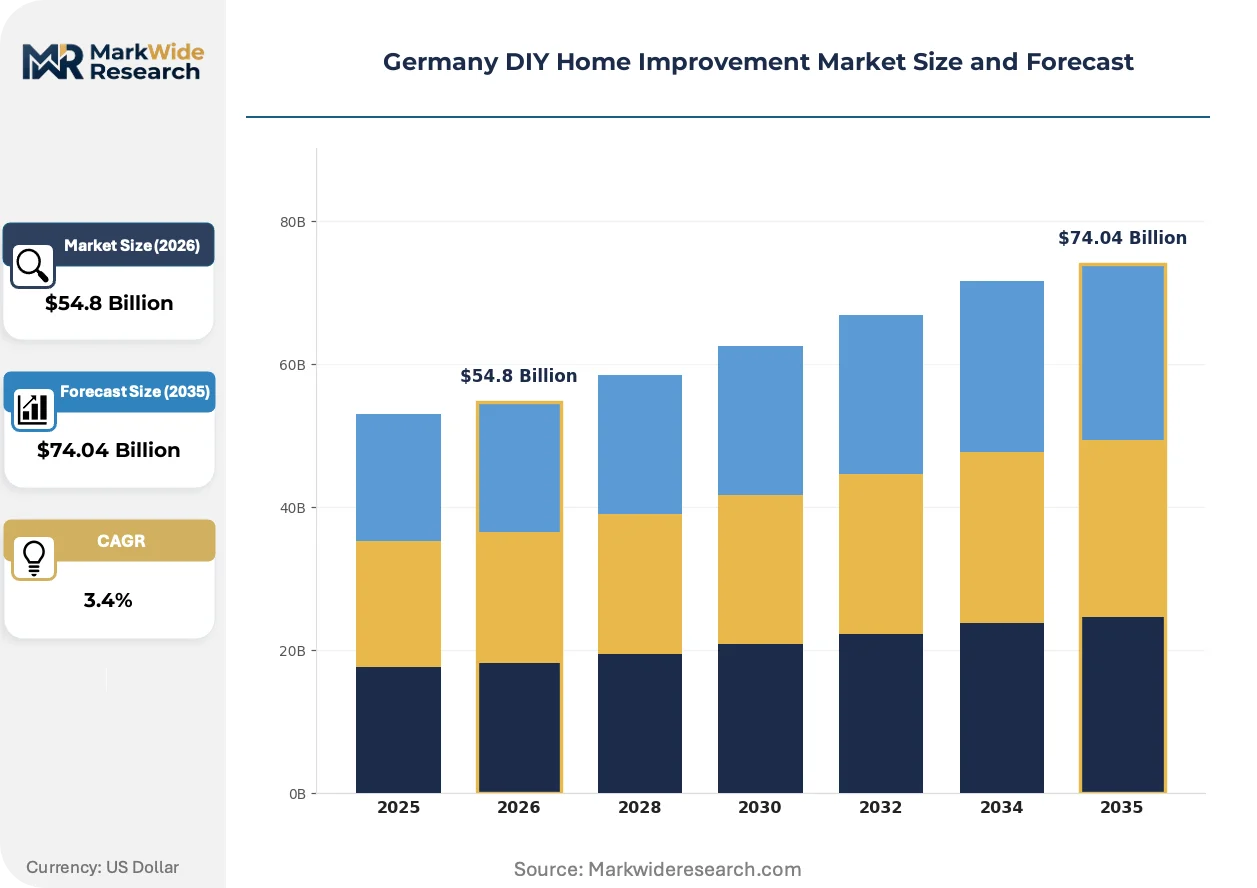
| Market Size in 2026 | $54.8 Billion |
| Market Size in 2035 | $74.04 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Tools, Hand Tools, Paints & Coatings, Fasteners, Plumbing Supplies, Electrical Accessories Customer Type: Homeowners, Renovators, Contractors, Gardeners, Renters Distribution Channel: Specialty Stores, Mass Merchandisers, Online Retailers, Warehouse Clubs, Direct Sales Service Type: Installation, Maintenance, Repair, Customization |
| Companies Covered | Toom Baumarkt, Globus Baumarkt, OBI, BayWa Bau & Garten, Hellweg, Bauhaus, Hagebau, BauSpezi, Hornbach, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany DIY Home Improvement Market Shifts & Advancements
Digital commerce infrastructure and regulatory compliance requirements are converging to reshape how German homeowners and contractors source, evaluate, and install home improvement materials.
Brushless motor technology is expanding into cordless power tool portfolios across drill, saw, and fastening categories. Semi-professional renovators and committed DIY homeowners are adopting these systems for runtime efficiency and reduced maintenance. This motor architecture is compressing the replacement cycle for brushed-motor inventory while elevating price floors in the mid-tier tool segment.
The EU Green Deal's embodied carbon tracking requirements are mandating supply chain documentation for paints, coatings, and construction fasteners sold through German retail channels. Manufacturers must now certify cradle-to-gate emissions data to maintain market access. This regulatory layer disproportionately affects imported product lines, driving domestic and near-shore sourcing adjustments among large-format retailers.
Project-based bundling is displacing single-item purchasing as the dominant transaction pattern among renovation-active households. Specialty retailers and online platforms are assembling kitchen, bathroom, and outdoor project kits with pre-matched specifications. This behavior shift concentrates in Bavaria and North Rhine-Westphalia where renovation rates exceed national averages and buyers prioritize workflow efficiency over component selection autonomy.
Germany DIY Home Improvement Market Segmentation
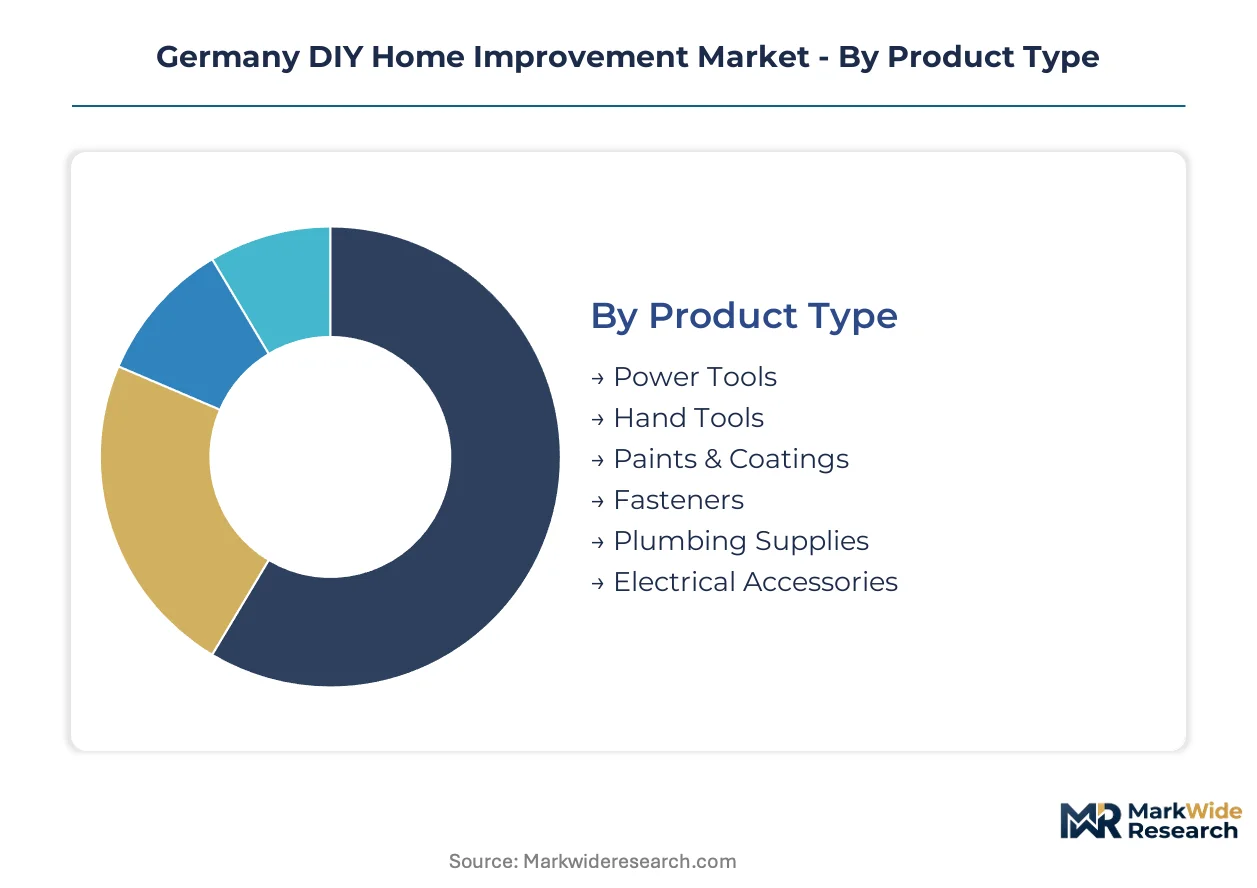
German DIY home improvement demand fragments across distinct buyer workflows, tool specifications, and project complexity tiers. Segmentation reveals how regulatory energy mandates, professional contractor requirements, and e-commerce logistics reshape category economics across the value chain.
Product Type:
Volume concentrates in consumable and entry-tool categories, while premium pricing power clusters around brushless motor systems and low-VOC formulations.
- Power Tools:Brushless motor specifications now dominate cordless drill, saw, and fastening categories. Demand concentrates in Bavaria and North Rhine-Westphalia where renovation rates exceed national averages and semi-professional buyers prioritize runtime efficiency over purchase price.
- Paints & Coatings:Low-VOC formulations face elevated production costs under EU Green Deal embodied carbon tracking requirements. Procurement concentrates through specialty retail channels where tactile evaluation and color-matching consultation drive conversion.
- Hand Tools:Chrome-vanadium and carbon steel grades serve precision assembly and rough construction tasks.
- Fasteners:Corrosion-resistant grades align with Central European humidity exposure patterns.
- Plumbing Supplies:PEX and copper fittings support heating system upgrade mandates.
- Electrical Accessories:KBA-certified components meet safety standards for residential installation.
Mature deployment sits with Hand Tools and Fasteners. Newer deployment is concentrated in Power Tools with brushless architectures.
Customer Type:
Professional proximity determines margin structure, with contractors commanding project-scale pricing and homeowners driving bundled kit adoption.
- Renovators:Active property modification households in Bavaria and North Rhine-Westphalia drive modular kitchen and bathroom system demand. This segment prioritizes workflow efficiency through pre-matched project kits over component selection autonomy.
- Contractors:Certified technicians anchor traffic at project-center retail formats, creating concentrated demand for thermal insulation and high-efficiency heating components under Federal Ministry energy mandates.
- Homeowners:Occasional DIY execution spans cosmetic and minor structural repairs.
- Gardeners:Seasonal outdoor equipment and landscaping material procurement.
- Renters:Restricted-scope improvements favor portable tools and removable fixtures.
Revenue concentration aligns with Renovators and Contractors. Steepest expansion trajectory belongs to Renovators as energy code compliance deepens retrofit activity.
Distribution Channel:
Physical scale versus digital reach creates divergent fulfillment economics across metropolitan and secondary city geographies.
- Online Retailers:Logistics network penetration beyond Berlin, Munich, and Hamburg captures transaction volume growth in smaller urban centers. Digital platforms assemble project-ready kits that displace single-item purchasing patterns among renovation-active households.
- Specialty Stores:Tactile evaluation and staff consultation sustain structural importance for high-consideration categories including power tool specification comparison and paint color matching.
- Mass Merchandisers:Broad SKU availability serves impulse and replenishment purchasing.
- Warehouse Clubs:Volume pricing attracts multi-project contractors and property managers.
- Direct Sales:Manufacturer-controlled channels for professional-grade equipment.
Established infrastructure dominates through Specialty Stores. Fastest share gains are occurring in Online Retailers as distribution density improves.
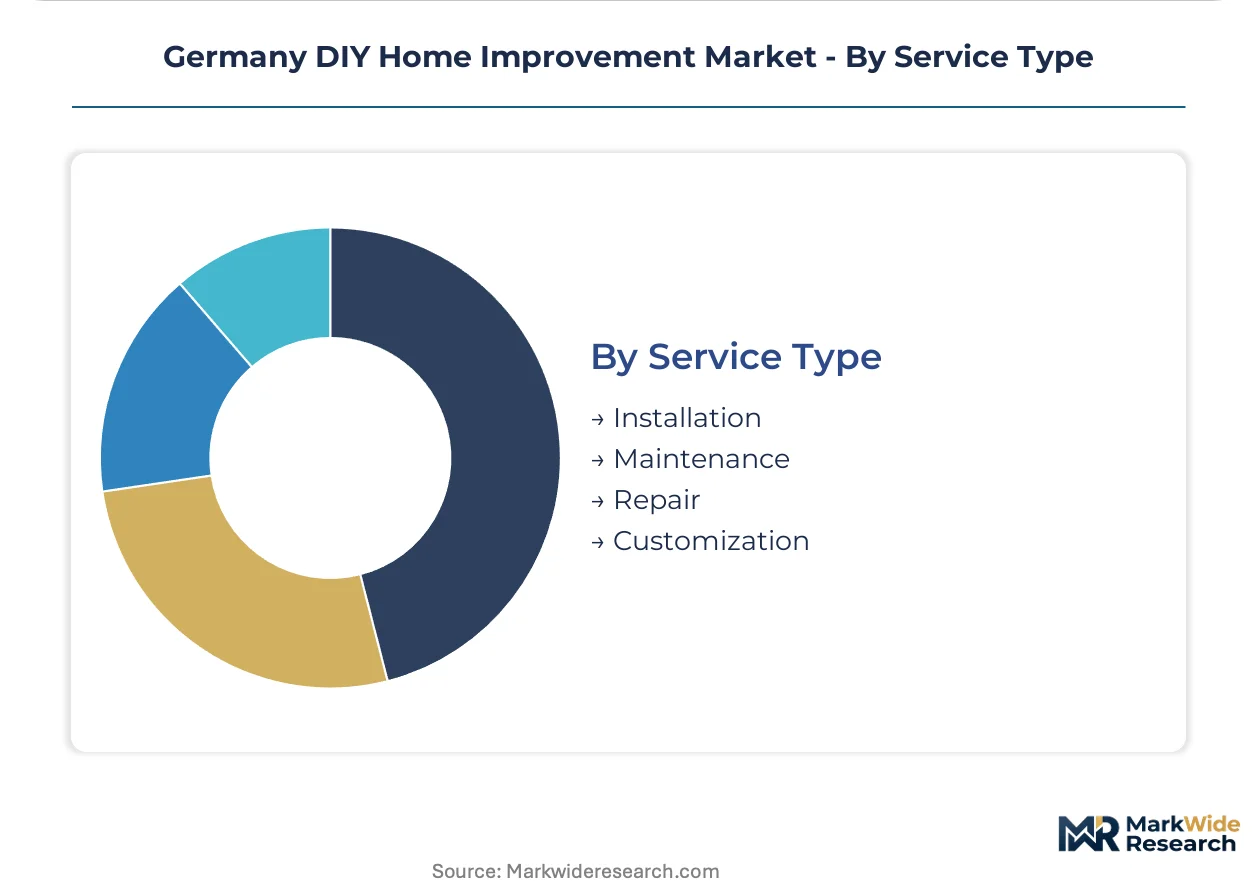
Service Type:
Regulatory complexity and technical certification requirements segment service attachment rates across project types.
- Installation:Thermal insulation and heating system upgrades mandated by Federal Ministry energy codes require certified technician involvement, creating skilled labor scarcity bottlenecks in project completion timelines.
- Maintenance:Brushless motor power tools extend service intervals while creating replacement demand for legacy brushed-motor inventory.
- Repair:Component-level fixes sustain hand tool and fastener demand.
- Customization:Modular kitchen and bathroom system adaptation to existing structural conditions.
Regulatory obligation drives Installation attachment. Maintenance is expanding most quickly as tool technology upgrades accelerate replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's DIY home improvement production concentrates in industrial zones near raw material suppliers, while consumption clusters in states with aging housing stock and elevated renovation activity. The Federal Ministry for Economic Affairs and Climate Action drives demand through energy efficiency mandates that reshape regional material flows.
Bavaria
Renovation rates in Bavaria exceed national averages, driving concentrated demand for modular kitchen and bathroom systems. The Federal Ministry's thermal insulation mandates accelerate retrofit project starts across Munich and Nuremberg metropolitan zones. Industrial tool manufacturing clusters in Upper Bavaria supply brushless motor power tools to regional distribution networks.
North Rhine-Westphalia
Housing renovation intensity in North Rhine-Westphalia matches Bavaria's levels, creating parallel demand for project-ready material kits. KBA-certified electrical accessories move through Cologne-Düsseldorf corridor retail channels serving contractor traffic. The Ruhr industrial legacy supports fastener and coating production facilities supplying regional building supply chains.
Baden-Württemberg
Precision manufacturing heritage in Baden-Württemberg sustains specialty hand tool production for professional and semi-professional buyers. REACH compliance requirements shape paint and coating formulation standards enforced through Stuttgart regional authorities. The state's automotive supplier ecosystem extends into power tool component manufacturing.
Lower Saxony
Agricultural property maintenance generates seasonal demand for outdoor equipment and landscaping materials across Lower Saxony's rural municipalities. Building energy codes apply uniformly to farm structure renovations, expanding insulation material addressable market. Hanover logistics hubs coordinate distribution to secondary cities lacking warehouse-scale retail presence.
Hesse
Frankfurt-Rhine-Main economic density supports premium-tier DIY retail formats targeting high-income renovators. EU Green Deal documentation requirements for embodied carbon tracking concentrate compliance service demand in this financial center. Regional building authorities coordinate product safety certifications across power tool and electrical accessory categories.
Germany DIY Home Improvement Market Competitive Landscape
The competitive structure tilts toward warehouse-scale and project-center formats that consolidate professional and consumer traffic. Specialty retailers and mass merchandisers occupy secondary positions with differentiated service models. Three archetypes dominate: warehouse-scale bundlers, project-center hybrid formats, and cooperative purchasing alliances. Consolidation through cooperative buying agreements and format standardization represent the dominant competitive moves reshaping market structure.
Within the warehouse-scale tier, OBI and Hornbach exemplify divergent positioning strategies. OBI anchors metropolitan zone dominance through outdoor and garden category bundling. Hornbach occupies the project-center vector that merges professional contractor traffic with homeowner footfall. Among cooperative purchasing alliances, Hagebau represents the member-owned model that aggregates independent retailers under shared sourcing and private label programs.
| Leading Market Players |
|---|
| Toom Baumarkt |
| Globus Baumarkt |
| OBI |
| BayWa Bau & Garten |
| Hellweg |
| Bauhaus |
| Hagebau |
| BauSpezi |
| Hornbach |
| Others |
Supply & Pricing Matrix
EU Green Deal embodied carbon tracking mandates for paints, coatings, and construction fasteners force manufacturers toward domestic and near-shore sourcing, compressing margins as compliance documentation layers onto production costs. This regulatory pull reshapes procurement economics across German retail channels, elevating price floors for certified product lines while squeezing non-compliant inventory from shelf space.
Pricing Analysis
Margin tightening in mid-tier power tools reflects copper and rare earth magnet cost volatility for brushless motor production. Three-tier pricing structure across premium brushless systems, standard brushed-motor tools, and economy entry-level equipment dominates the category, with differentiation driven by motor architecture and runtime specifications. Pricing pressure intensifies in paint formulations as low-VOC compliance costs compound with EU Green Deal documentation requirements. Renovators in Bavaria and North Rhine-Westphalia show lowest price sensitivity, prioritizing workflow efficiency through bundled project kits over component-level cost optimization.
Supply Chain Analysis
EU Green Deal local-content preferences and embodied carbon documentation requirements are redirecting sourcing toward German, Polish, and Czech manufacturing hubs for paints, fasteners, and insulation materials. Brushless motor production draws from Chinese rare earth processing and German precision engineering clusters. Single-source vulnerability concentrates in rare earth magnet supply chains. Distribution runs through warehouse-scale formats in metropolitan zones, project-center hybrids for contractor traffic, and expanding logistics networks into secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany DIY home improvement market operates as a cost-of-compliance arena where Federal Ministry energy efficiency mandates and EU Green Deal documentation requirements erect barrier-to-entry moats favoring players with established certification infrastructure and domestic sourcing relationships.
For Market Incumbents: Lock in contractor loyalty through project-center format investments that anchor professional traffic alongside homeowner footfall, while deepening backward integration into brushless motor component supply to offset rare earth price volatility. Prioritize EU Green Deal compliance service offerings that monetize embodied carbon documentation as advisory revenue streams. For New Entrants and Emerging Players: Enter via online project-kit assembly targeting renovation-active households in secondary cities beyond Berlin, Munich, and Hamburg where logistics penetration remains incomplete. White space concentrates in modular bathroom system bundling for North Rhine-Westphalia's aging housing stock, with go-to-market execution through digital-native platforms that displace single-item purchasing patterns. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated paint and coating specialists given EU Green Deal compliance infrastructure as a scarce asset. Long-term viability favors players with captive low-VOC formulation capabilities and established KBA certification pathways. The signal to watch is Federal Ministry enforcement intensity on thermal insulation mandates accelerating retrofit project starts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Mitigates brushless motor cost volatility from Chinese processing concentration. |
| EU Green Deal Compliance Service Launch | Captures advisory revenue from embodied carbon documentation mandates. |
| Project-Center Format Expansion | Consolidates professional contractor traffic alongside homeowner footfall. |
| Secondary City Logistics Network Buildout | Captures transaction volume growth beyond Berlin, Munich, and Hamburg. |
| Modular System Bundling Platform | Displaces single-item purchasing patterns among renovation-active households. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across hardware retail category managers, power tool procurement directors, paint formulation R&D leads, thermal insulation contractor network heads, and Federal Ministry policy officers. Bottom-up SKU-level demand modeling triangulated against top-down macroeconomic indicators and building permit flow data from regional German authorities.
Granularity-level modeling operated at product-type, customer-archetype, distribution-channel, and service-attachment dimensions, with brushless motor penetration rates and EU Green Deal compliance timelines as industry-specific forecast inputs. CAGRs derived from regression analysis against housing renovation intensity indices and energy code enforcement schedules across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Federal Ministry mandate acceleration or rare earth supply disruption scenarios. Assumptions reflect documented regulatory trajectories and documented supply chain configurations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
DIY Home Improvement Products
Asia-Pacific DIY Home Improvement Market
DIY Home Improvement Products
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Sweden DIY Home Improvement Market
DIY Home Improvement Products
Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
France Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Saudi Arabia Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Netherlands DIY Home Improvement Market