
 Wrist Dive Computer Market | 2026-2036
Wrist Dive Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Wrist Dive Computer Market Outlook
Asian contract manufacturers is consolidating assembly capacity for wrist-mounted decompression instruments. Shearwater Research leverages proprietary Bühlmann algorithm implementations to sustain premium positioning in technical diving circles. Garmin Ltd. competes through GPS surface integration that extends utility beyond submerged operation. Suunto anchors European market presence through Finnish design heritage and EN 13319 compliance leadership.
A wrist dive computer is a pressure-resistant wearable instrument that calculates no-decompression limits through real-time depth-time integration, typically rated to 100–200 meters with titanium or reinforced polymer housings. Its primary commercial purpose is to prevent decompression sickness by translating ambient pressure data into actionable tissue-loading metrics for single-gas or multi-gas exposures. Advanced and smart product types command margin concentration where air integration and Bluetooth connectivity enable gas-pressure telemetry and post-dive log synchronization. Recreational divers represent the volume base, while commercial operators generate replacement-cycle premiums through mandatory calibration intervals and ruggedized specification requirements.
ISO 6425 and EN 13319 standards govern depth gauge accuracy and waterproofing validation, with FDA oversight applying to devices marketed with therapeutic decompression claims in the United States. CE marking under the EU MDR framework intensifies conformity assessment burdens for European market access, particularly for units incorporating heart-rate or blood-oxygen sensors. Stakeholders must monitor evolving algorithm validation protocols and regional diver-certification body equipment mandates to anticipate procurement specification shifts.
Market Dynamics
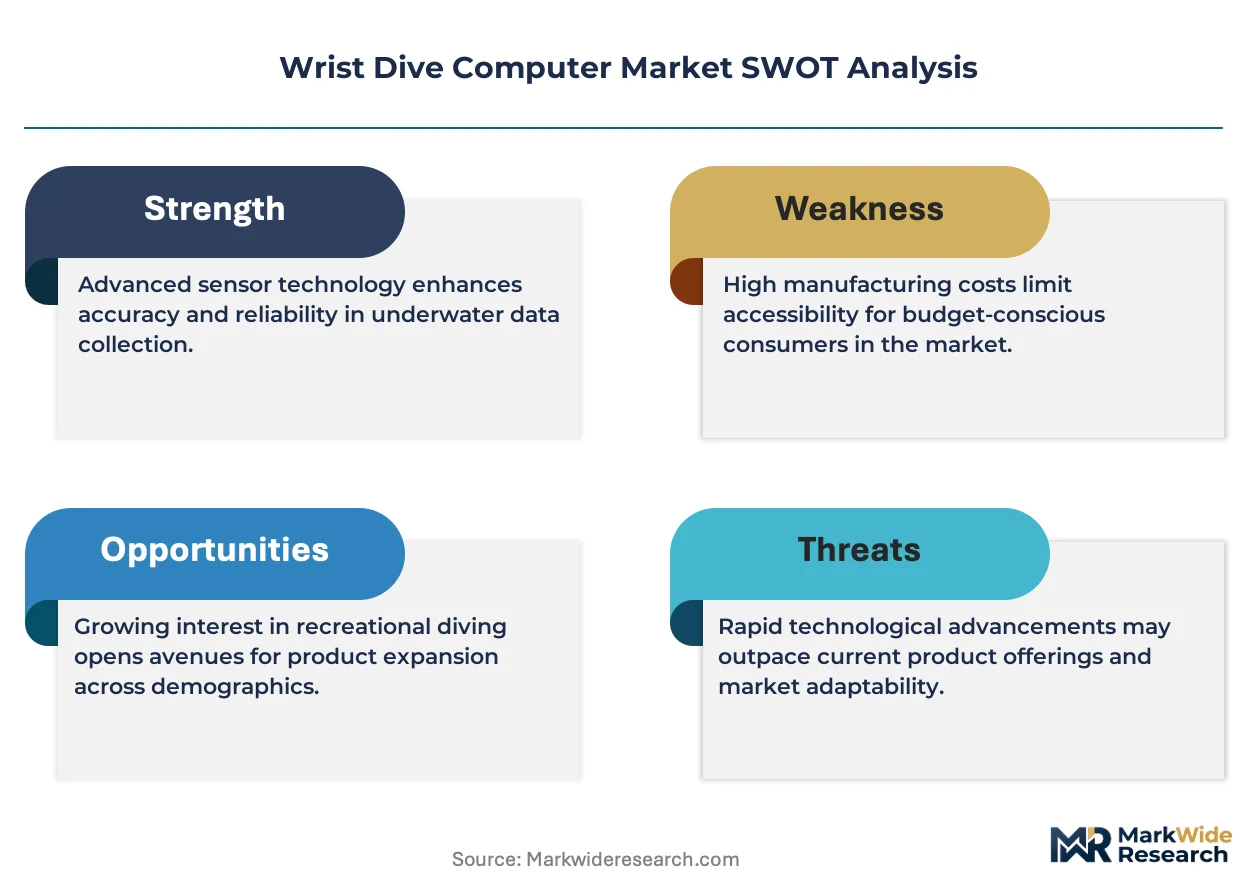
Algorithm standardization across technical diving certification bodies is compressing vendor differentiation, forcing manufacturers to compete on sensor integration and wireless telemetry rather than proprietary decompression mathematics.
Growth Catalysts
- Liveaboard fleet expansion:Thailand's island economies are standardizing multi-diver equipment protocols, creating procurement bundles that favor wrist-mounted decompression instruments with unified data logging.
- EN 13319 depth-accuracy mandates:European safety benchmarks are disqualifying uncertified depth gauges from commercial operator insurance coverage, accelerating replacement cycles.
- Multi-gas technical diving:Nitrox and trimix certification growth is driving demand for programmable Bühlmann ZHL-16C algorithm implementations with configurable gradient factors.
Market Restraints
- Titanium housing cost volatility:Aerospace-grade Ti-6Al-4V supply constraints from Ukrainian and Russian feedstock disruptions are compressing assembly margins.
- ISO 6425 validation bottlenecks:Third-party waterproofing certification queues at accredited test houses extend product launch timelines by 4-7 months.
- Smartwatch substitution pressure:Consumer-grade waterproof wearables with basic depth logging are capturing recreational diver trial purchases below 30-meter operational thresholds.
Strategic Opportunities
- Indonesia's underpenetrated archipelago:Raja Ampat and Komodo liveaboard operators lack standardized fleet equipment, creating first-mover consolidation potential for integrated air-telemetry systems.
- EU MDR sensor convergence:Heart-rate and pulse-oximetry modules eligible for Class IIa medical device designation unlock reimbursement pathways through therapeutic decompression claims.
- Direct-to-operator subscription telemetry:Cloud-based dive-log aggregation services bypass retail channel markups while locking commercial fleets into recurring calibration revenue.
Industry Challenges
- Firmware validation specialist scarcity:Embedded systems engineers with decompression physiology domain knowledge command premium compensation, constraining R&D velocity at mid-tier manufacturers.
- CE marking timeline compression:EU MDR technical documentation requirements for multi-sensor units are extending conformity assessment periods without parallel revenue streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wrist Dive Computer Market |
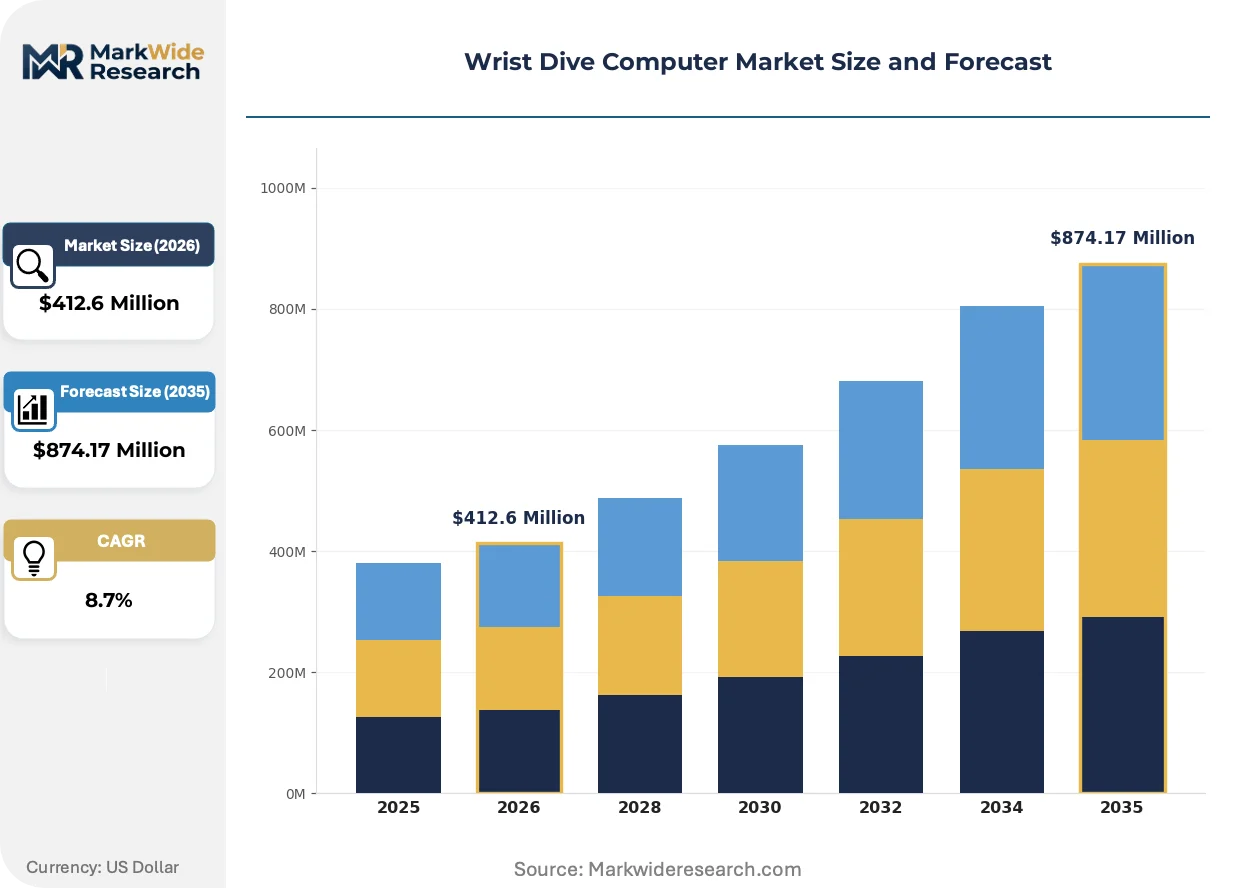
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic, Advanced, Smart, Hybrid Technology: Air Integration, Bluetooth, GPS, Dive Algorithm End User: Recreational Divers, Professional Divers, Commercial Operators, Training Institutes Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Shearwater Research, Suunto, Mares, Cressi, Aqua Lung International, Garmin Ltd., Johnson Outdoors Inc., Scubapro, Oceanic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wrist Dive Computer Market Strategic Shifts
Wireless gas-pressure telemetry and post-dive synchronization protocols are displacing cable-dependent air-integration systems, while regulatory convergence on algorithm transparency is eroding proprietary software moats.
Air-integration transmitter modules operating on 38kHz acoustic or low-power Bluetooth protocols are consolidating recreational and technical diver expectations around real-time tank-pressure visibility. Liveaboard operators in the Andaman Sea are mandating these systems for guide liability reduction. The technology is consolidating vendor R&D roadmaps toward unified wireless ecosystems rather than mixed-signal architectures.
EU MDR Class IIa reclassification for devices incorporating physiological sensors is tightening clinical validation requirements for heart-rate and SpO2 monitoring functions. Finnish and German notified bodies are demanding algorithm traceability documentation that exceeds traditional EN 13319 scope. Technical diving equipment distributors are responding by segregating sensor-equipped units into separate regulatory SKUs with extended labeling.
Certification-driven procurement preferences are shortening replacement cycles among professional dive instructors who must demonstrate current equipment compliance to liability insurers. PADI and SSI training centers in Egypt's Red Sea corridor are requiring staff-owned computers with logged firmware version tracking. This behavioral shift is compressing aftermarket service intervals while elevating factory-authorized calibration networks over independent repair channels.
Wrist Dive Computer Market Segmentation
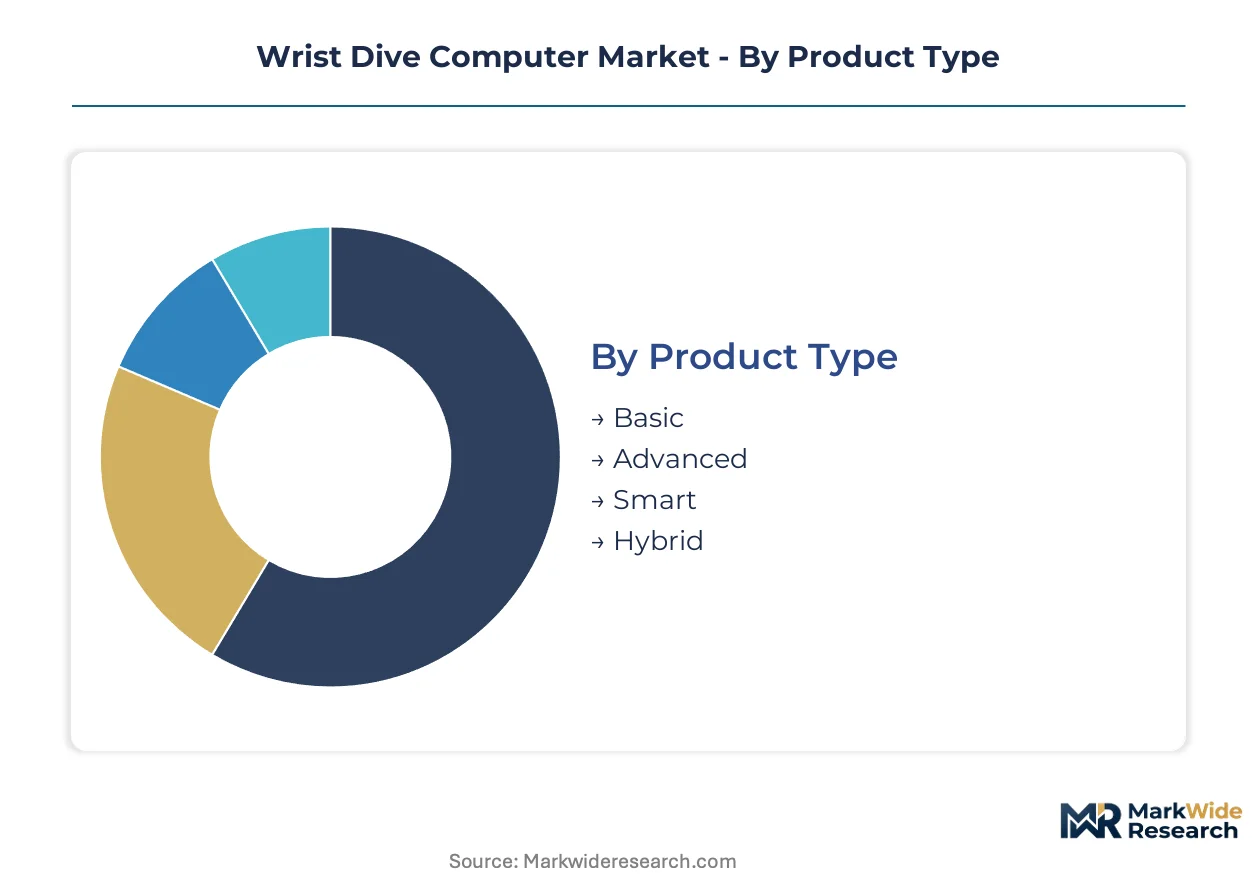
Segmentation in wrist dive computers reveals distinct procurement patterns across certification levels and operational intensity. Diver risk profiles and regulatory compliance obligations create non-overlapping demand clusters that manufacturers must address through differentiated hardware specifications and firmware architectures.
Product Type:
Capital intensity escalates sharply from polymer-housed entry units to titanium-encased technical instruments with multi-gas firmware.
- Basic:Single-gas nitrogen-oxygen decompression calculators with depth-time integration and monochrome LCD displays. Recreational certification programs in Thailand's liveaboard corridors concentrate procurement here for student equipment pools, constrained by EN 13319 compliance costs that disqualify uncertified alternatives from operator insurance coverage.
- Advanced:Multi-gas programmable units implementing Bühlmann ZHL-16C algorithms with configurable gradient factors and optional air-integration transmitters. Technical diving training centers in Egypt's Red Sea corridor drive replacement cycles through firmware version tracking mandates for instructor liability coverage.
- Smart:Bluetooth-enabled post-dive synchronization with smartphone logbook applications and rechargeable lithium-polymer batteries.
- Hybrid:Dual-mode instruments combining dedicated decompression computation with surface GPS navigation and fitness tracking.
Advanced absorbs the bulk of installed capacity; Smart is expanding most quickly.
Technology:
Wireless telemetry modules command premium bill-of-materials costs versus standalone depth-time calculators, shifting margin concentration toward integrated system vendors.
- Air Integration:38kHz acoustic or low-power Bluetooth transmitters relaying cylinder pressure data to wrist units in real time. Andaman Sea liveaboard operators mandate these systems for guide liability reduction, consolidating procurement specifications around unified wireless ecosystems rather than mixed-signal architectures.
- Bluetooth:Post-dive log synchronization protocols enabling cloud-based dive profile aggregation and social sharing functionality.
- GPS:Surface position logging and breadcrumb trail recording for drift-dive exit planning and emergency surface location transmission.
- Dive Algorithm:Proprietary or licensed decompression mathematics implementing Bühlmann, VPM-B, or RGBM tissue-loading models with user-configurable conservatism settings.
Air Integration carries the highest component cost burden; Bluetooth connectivity is climbing the fastest as recreational diver expectations converge with consumer electronics standards.
End User:
Procurement authority and replacement frequency diverge sharply between individually owned recreational equipment and fleet-managed commercial inventories.
- Recreational Divers:Individual enthusiasts purchasing through retail channels for leisure diving below 40 meters, typically replacing units every 5-7 years or upon certification advancement. Indonesia's underpenetrated archipelago markets represent volume expansion potential where first-time diver enrollment is accelerating.
- Professional Divers:Divemasters and instructors subject to employer-mandated equipment compliance with logged firmware tracking for liability insurance.
- Commercial Operators:Fleet procurement managers standardizing multi-diver protocols across liveaboard vessels and shore-based operations, prioritizing unified data logging and bulk calibration scheduling.
- Training Institutes:Certification agencies and dive schools maintaining student equipment pools with durability specifications exceeding retail consumer expectations.
Commercial Operators dominate fleet-level purchasing volume; Training Institutes are gaining share fastest as certification body equipment mandates tighten.
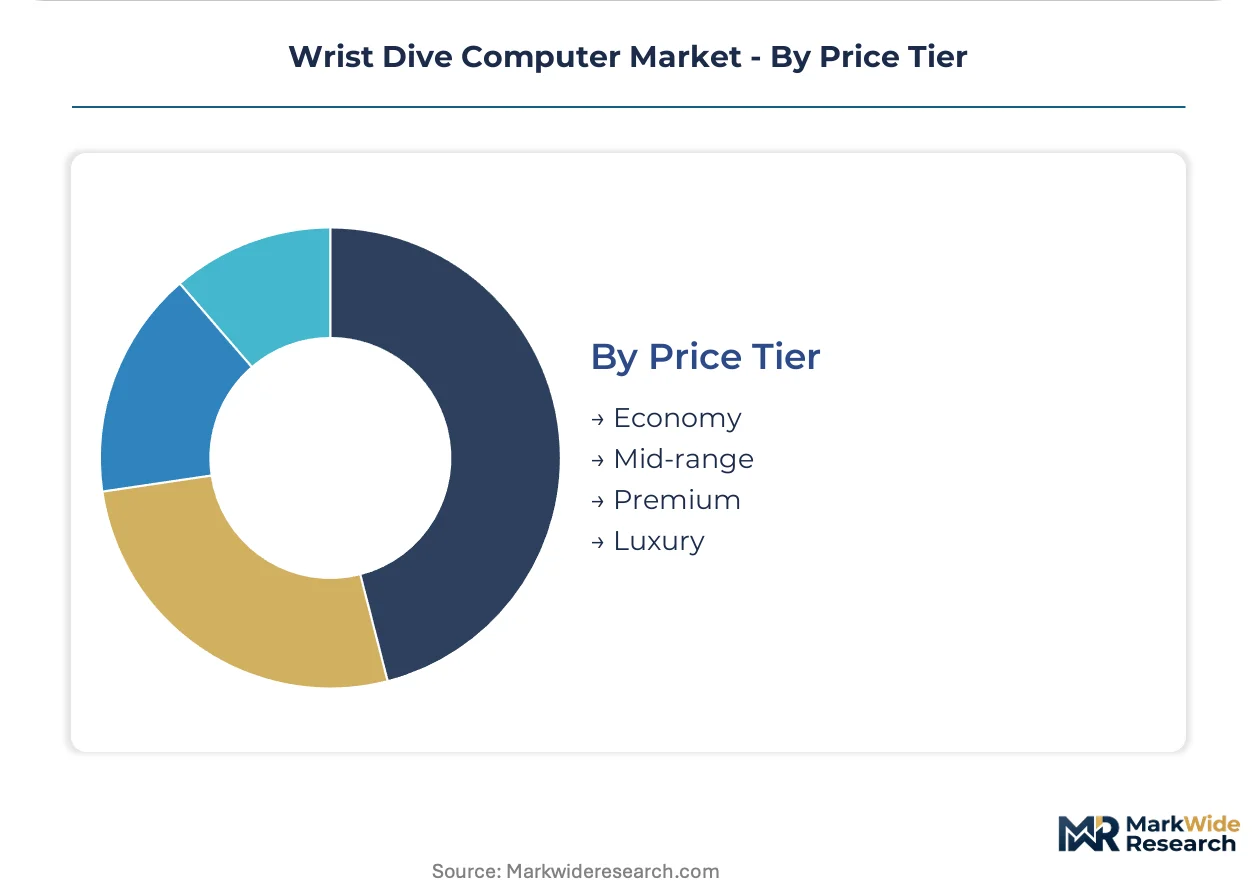
Price Tier:
Margin structures stratify across certification grade requirements and sensor integration depth, with medical-device-designated units commanding substantial premiums.
- Economy:Polymer-housed single-gas computers with fixed conservatism settings and non-replaceable batteries, retailing below the air-integration price threshold.
- Mid-range:Nitrox-capable instruments with user-replaceable batteries and basic PC connectivity, capturing the bulk of recreational diver upgrade cycles.
- Premium:Titanium-encased multi-gas technical computers with wireless air integration and customizable algorithm parameters. EU MDR Class IIa sensor-equipped variants in this tier unlock reimbursement pathways through therapeutic decompression claims, concentrating margin extraction in Finnish and German notified body jurisdictions.
- Luxury:Limited-edition titanium or precious-metal housings with concierge calibration services and exclusive firmware features.
Premium captures the highest per-unit margin; Mid-range maintains the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ukrainian and Russian titanium feedstock disruptions have concentrated aerospace-grade Ti-6Al-4V sourcing pressure on Japanese and Chinese sponge producers, reshaping assembly cost structures for pressure-resistant instrument manufacturers.
United States
Technical diving certification growth in Florida's cave systems and California's kelp forests drives multi-gas computer demand. FDA oversight applies to devices marketed with therapeutic decompression claims, creating compliance bifurcation between recreational and medical-designated units. Miami-Dade County hosts liveaboard fleet operators standardizing wireless air-integration protocols for liability reduction.
Germany
EU MDR Class IIa reclassification for sensor-equipped units tightens clinical validation requirements through German notified bodies. EN 13319 depth-accuracy mandates disqualify uncertified gauges from commercial operator insurance coverage, accelerating replacement cycles. The Bavarian Alps region concentrates technical diving training centers requiring firmware version tracking for instructor liability.
Thailand
Island economies across the Andaman Sea and Gulf of Thailand standardize multi-diver equipment protocols for liveaboard fleet expansion. Tourism board equipment subsidies favor EN 13319-certified instruments in procurement bundles. Phuket and Koh Tao serve as distribution hubs for Southeast Asian recreational diver enrollment growth.
Finland
Finnish design heritage anchors European market presence through EN 13319 compliance leadership. CE marking under EU MDR intensifies conformity assessment burdens for multi-sensor units. The Helsinki-Tampere corridor concentrates R&D activity for algorithm validation and wireless telemetry integration.
Indonesia
Raja Ampat and Komodo liveaboard operators lack standardized fleet equipment, creating first-mover consolidation potential. Underpenetrated archipelago markets represent volume expansion where first-time diver enrollment accelerates. Bali serves as the primary entry point for equipment distribution across the eastern islands.
Wrist Dive Computer Market Competitive Environment
Global majors compete with regional champions across algorithm implementation and certification compliance. The vendor base stratifies into three tiers: premium technical specialists, mid-range recreational full-liners, and economy polymer-housed assemblers. Strategic archetypes include algorithm licensors, sensor integrators, and fleet service providers. Competitive moves concentrate on M&A for algorithm portfolios and capacity expansion in Southeast Asian contract manufacturing.
Among North American precision instrument developers, Shearwater Research exemplifies the technical-specialist archetype through proprietary Bühlmann implementations. Garmin Ltd. occupies a position bridging consumer electronics and dive-specific computation. Suunto anchors European presence through Finnish design heritage and regulatory compliance leadership.
| Leading Market Players |
|---|
| Shearwater Research |
| Suunto |
| Mares |
| Cressi |
| Aqua Lung International |
| Garmin Ltd. |
| Johnson Outdoors Inc. |
| Scubapro |
| Oceanic |
| Others |
Value Chain & Pricing Dynamics
Aerospace-grade Ti-6Al-4V titanium sponge pricing volatility cascades through wrist dive computer assembly tiers, compressing margins on titanium-encased premium units while polymer-housed economy alternatives capture diver enrollment growth in Southeast Asian training centers.
Pricing Analysis
Extended warranty and factory-authorized calibration bundling separates premium-tier vendors from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects EN 13319 certification grade and air-integration telemetry inclusion. Pricing pressure stems from smartwatch substitution in recreational segments below 30 meters, compressing entry-tier margins. Training institutes exhibit highest price sensitivity due to student equipment pool volume procurement, while technical divers demonstrate lowest sensitivity given liability insurance mandates.
Supply Chain Analysis
Titanium feedstock dependency rests on Japanese and Chinese sponge producers following Ukrainian and Russian supply disruptions. Pressure sensor modules draw from German and Swiss precision instrument specialists, while Bluetooth telemetry chipsets source from Taiwanese semiconductor foundries. Single-source vulnerability concentrates in aerospace-grade titanium billet supply. Distribution runs through dive equipment specialty retailers and direct-to-operator fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance narrative where EU MDR Class IIa reclassification erects regulatory moats that favor incumbent manufacturers with notified body relationships and clinical validation capabilities.
For Market Incumbents: Deepen firmware validation specialist retention through algorithm physiology domain expertise premiums, countering R&D velocity constraints from embedded systems engineer scarcity. Expand captive calibration network coverage in Thailand's Andaman Sea corridor to lock liveaboard operators into recurring service revenue streams.
For New Entrants and Emerging Players: Cloud-based dive-log aggregation platforms offer technology-first wedge into Indonesia's underpenetrated archipelago, where Raja Ampat and Komodo liveaboard operators lack standardized fleet equipment. Target direct-to-operator subscription telemetry models that bypass retail channel markups and establish recurring revenue lock-in.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with EN 13319 compliance infrastructure in Southeast Asian contract manufacturing hubs. Long-term viability hinges on algorithm portfolio consolidation and sensor integration capabilities. Watch ISO 6425 validation queue compression at accredited test houses as inflection indicator for product launch velocity recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Portfolio Acquisition | Consolidates Bühlmann ZHL-16C implementations against VPM-B and RGBM competitors. |
| EU MDR Class IIa Certification Investment | Unlocks reimbursement pathways through Finnish and German notified body jurisdictions. |
| Indonesia Fleet Equipment Standardization | Captures first-mover position in Raja Ampat and Komodo liveaboard procurement. |
| Wireless Telemetry Ecosystem Integration | Mandates 38kHz acoustic or Bluetooth protocols for Andaman Sea operator liability reduction. |
| Calibration Service Network Expansion | Locks commercial operators into recurring revenue through mandatory firmware tracking intervals. |
Study Parameters
Trade data from customs authorities, ISO certification registries, and dive training agency equipment manuals formed the secondary backbone, supplemented by SEC filings from precision instrument manufacturers and EU MDR technical documentation databases. Primary fieldwork engaged dive equipment procurement managers at liveaboard operators, firmware validation engineers at notified bodies, and commercial diving fleet managers across Thailand and Indonesia. Bottom-up and top-down triangulation reconciled diver enrollment statistics with manufacturer shipment data.
Bottom-up modeling anchored volume projections on certification body equipment mandates and replacement cycle intervals across recreational, professional, and commercial operator segments. Top-down validation cross-referenced tourism board equipment subsidy programs with dive training agency expansion plans. Segmentation dimensions included product type tier, technology integration depth, end-user procurement authority, and regional regulatory cluster. CAGRs derived from algorithm standardization timelines and EN 13319 compliance adoption curves across the analysis window.
Several conditions sit outside the modeled scope, including unreported gray-market equipment imports and informal diver-to-diver resale channels. Forecasts reflect assumptions around titanium feedstock price stabilization and ISO 6425 validation queue normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
United States Smart TV Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
Europe Smart TV Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
Gaming Phone Market
Consumer Electronics
Vertical Ergonomic Optical Mouse Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
True Wireless Stereo Earbuds Market
Consumer Electronics
Mouse Pad Market
Consumer Electronics
Kid's Wired Earphone and Headphone Market
Consumer Electronics
Dive Computer Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Smart Home Projector Market