
 Eyewear Market | 2026-2036
Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Eyewear Market Analysis
Italian frame manufacturing is shifting toward automated acetate milling and titanium laser cutting. EssilorLuxottica leverages vertical integration across lens casting and retail networks. HOYA Corporation anchors premium free-form progressive lens production in Japan. Carl Zeiss differentiates through precision optics for digital eye strain applications.
Eyewear comprises vision correction devices, solar protection instruments, and occupational safety equipment fabricated from optical-grade plastics, mineral glass, or lightweight alloys with specified refractive indices and impact resistance ratings. Prescription glasses generate the largest revenue pool due to recurring lens replacement cycles, while contact lenses capture faster volume growth among younger demographics seeking aesthetic flexibility. Safety glasses command premium pricing in industrial channels where ANSI Z87.1 compliance is mandatory.
The FDA regulates contact lenses as Class II medical devices requiring premarket notification, while the EU MDR imposes stricter clinical evaluation requirements on corrective eyewear. ISO 12870 sets international benchmarks for frame endurance and nickel release limits. Stakeholders must monitor evolving blue light filtration standards and sustainability mandates affecting acetate sourcing decisions.
Market Dynamics
EU MDR conformity requirements are compressing certification timelines for corrective lens manufacturers, forcing accelerated clinical documentation and stricter post-market surveillance protocols across the value chain.
Growth Catalysts
- EU MDR Clinical Evaluation Mandates:Stricter conformity assessment pathways for corrective eyewear are elevating quality benchmarks and filtering marginal suppliers from the European market.
- Titanium Laser Cutting:Automated precision fabrication in Italian manufacturing clusters is reducing frame production cycle times while enabling complex geometric designs previously unachievable through conventional milling.
- Aging Professional Workforce:Presbyopia prevalence among 45-65 year-old knowledge workers is expanding the addressable base for progressive lens prescriptions with recurring replacement intervals.
Market Restraints
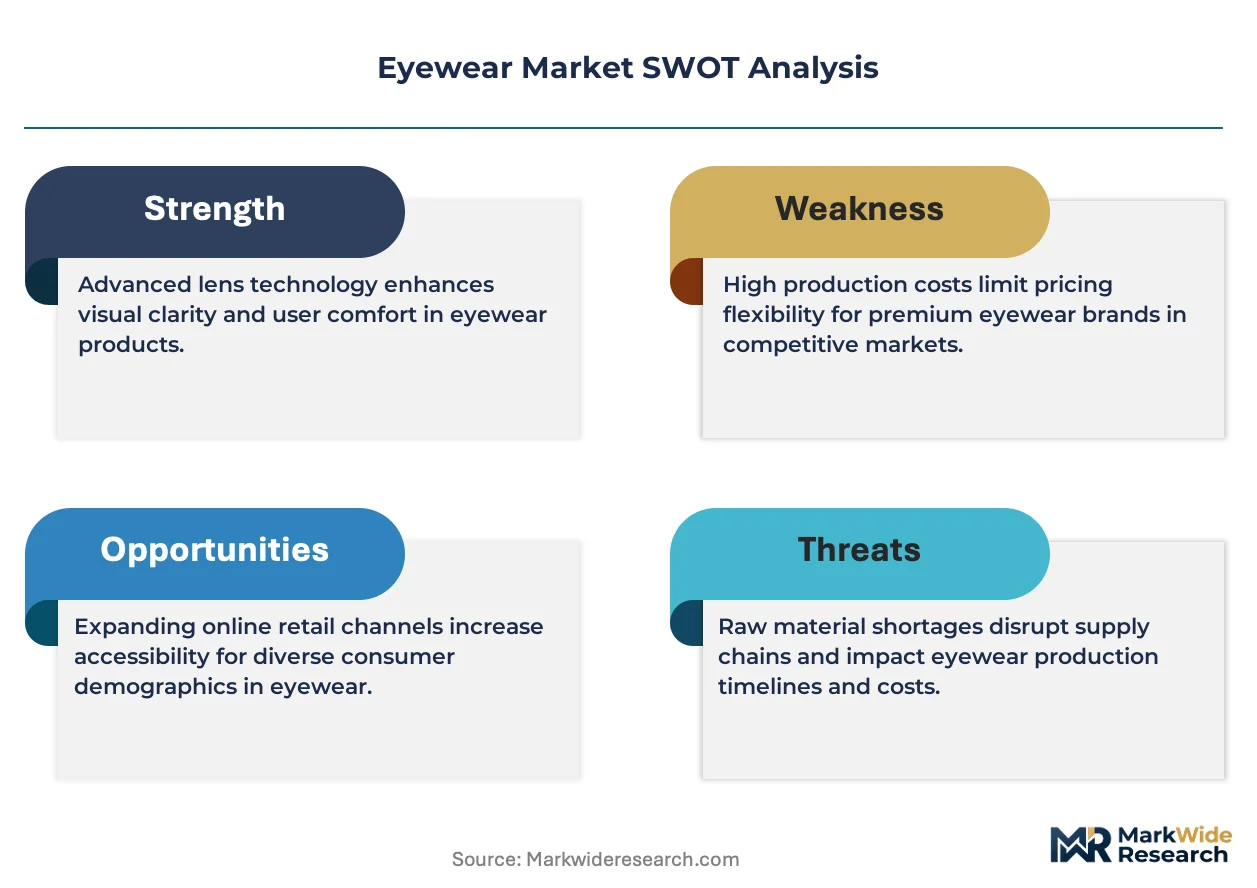
- Acetate Raw Material Concentration:Premium cellulose acetate supply concentrates among Italian and Japanese specialty chemical producers, creating input cost volatility for mid-tier frame manufacturers.
- FDA Class II Device Pathway:Premarket notification requirements for contact lenses impose 12-18 month regulatory timelines that constrain speed-to-market for optical innovators.
- Blue Light Filtration Standard Fragmentation:Absence of harmonized ISO protocols for digital eye strain claims creates compliance confusion and limits cross-border marketing assertions.
Strategic Opportunities
- India PLI Scheme for Medical Devices:Production-linked incentive structures for domestic manufacturing of precision optical instruments are attracting lens casting and coating investments.
- Occupational Safety Channel Expansion:ANSI Z87.1-compliant safety glasses for construction and manufacturing verticals command premium pricing through industrial distributors with mandated procurement programs.
- Free-Form Progressive + Digital Surfacing Convergence:Integration of wavefront-guided lens design with direct-to-consumer virtual try-on platforms is compressing the prescription fulfillment chain.
Industry Challenges
- Optical Metrology Talent Scarcity:Free-form lens design and precision surfacing operations require specialized optometric engineers whose training pipelines lag industry expansion.
- EU MDR Technical Documentation Burden:Clinical evaluation report preparation for corrective eyewear consumes 8-14 months of regulatory affairs capacity, diverting resources from product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eyewear Market |
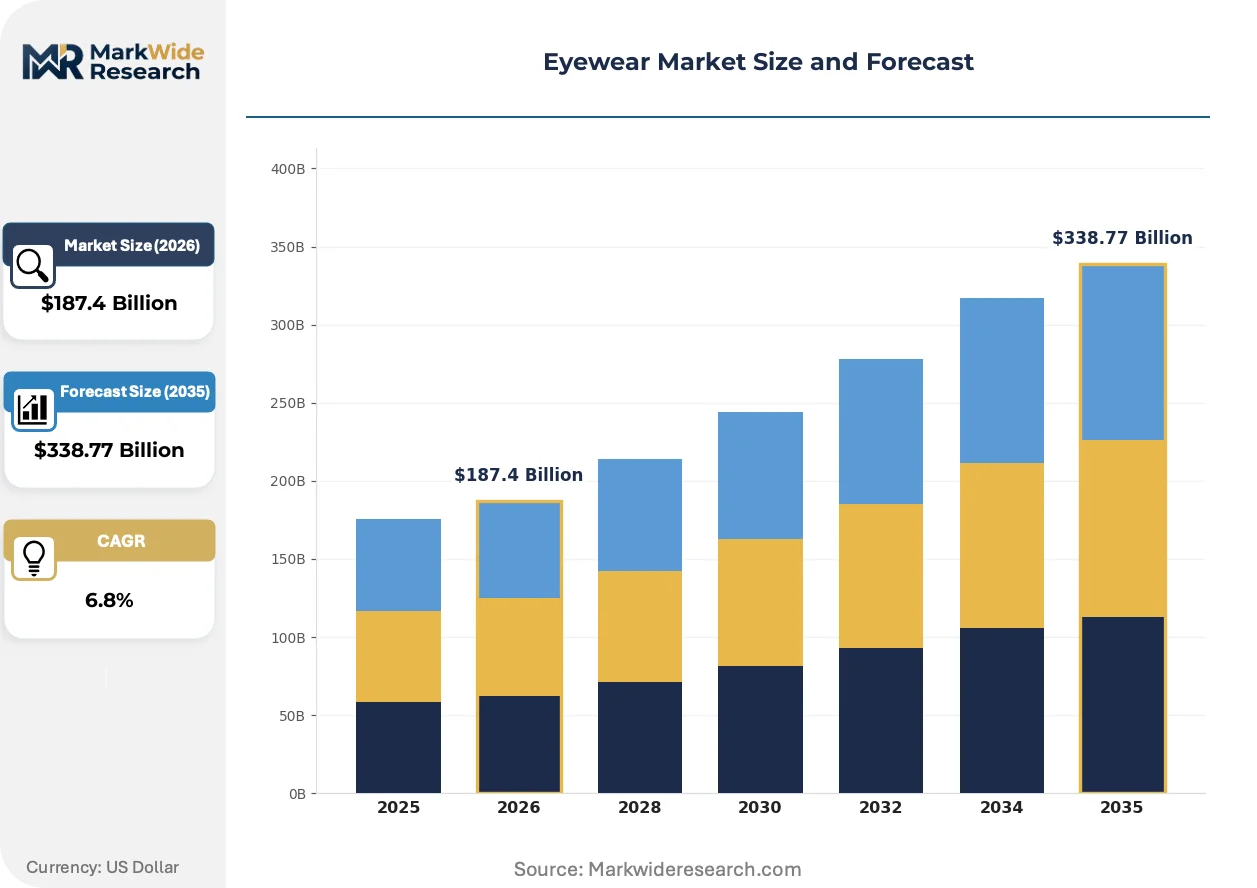
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunglasses, Prescription Glasses, Contact Lenses, Safety Glasses Material: Plastic, Glass, Metal, Polycarbonate Application: Fashion, Sports, Protective, Vision Correction End User: Adults, Children, Seniors, Professionals |
| Companies Covered | EssilorLuxottica, Alcon, Johnson & Johnson Vision Care, Bausch & Lomb, Carl Zeiss, CooperVision, Safilo Group, Warby Parker, HOYA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eyewear Market Emerging Trajectories
Digital surfacing technology and virtual fitting platforms are compressing traditional optical retail models, while regulatory pressure on medical device classification reshapes competitive entry barriers.
Free-form progressive lens manufacturing is electrifying the precision optics segment. Digital surfacing equipment replaces conventional lap tools with point-by-point material removal guided by wavefront aberration maps. Independent optometric practices and online direct-to-consumer platforms are adopting these customized prescriptions at accelerating rates. This capability compression is electrifying margin structures away from standardized stock lenses toward patient-specific designs with 3-4x value capture per unit.
EU MDR post-market surveillance requirements are tightening corrective eyewear compliance obligations. Manufacturers must now maintain systematic clinical follow-up data and periodic safety update reports across their product portfolios. Small-to-mid frame producers without captive regulatory affairs teams face disproportionate compliance cost absorption. Italian and German optical houses are responding by consolidating certification management through specialized third-party notified bodies.
Virtual try-on adoption is altering frame selection behavior among younger prescription buyers. Smartphone-based facial scanning and augmented reality overlay tools are displacing physical showroom visits for initial style exploration. Optical retail chains and independent practices are deploying these platforms to reduce inventory carrying costs while expanding style presentation breadth. This channel migration is most visible in South Korean and Japanese urban markets where mobile commerce penetration exceeds 70 percent among 25-40 year-old consumers.
Eyewear Market Segmentation
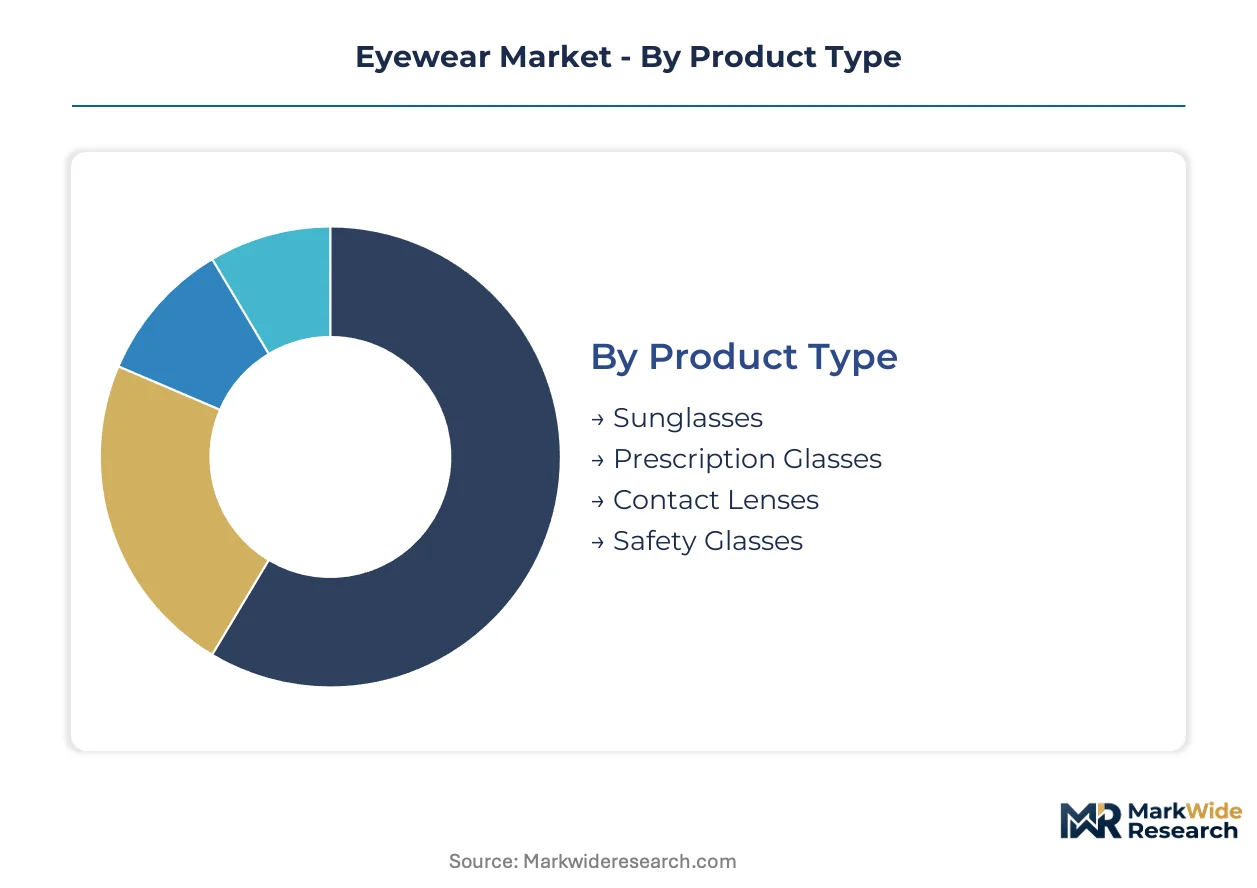
Segmentation in eyewear separates commoditized volume plays from precision medical devices requiring regulatory navigation. Material choices and application contexts determine margin structures, certification burdens, and channel access across the value chain.
Product Type:
Standardization dominates sunglasses and safety categories with certified performance benchmarks, while prescription lenses and contacts demand individualized fabrication workflows.
- Sunglasses:Solar protection instruments combining tinted mineral glass or polycarbonate with UV400 filtration standards. Demand clusters in Italian manufacturing districts serving fashion houses and licensed brand portfolios, where design refresh cycles drive recurring procurement.
- Prescription Glasses:Corrective devices fabricated to patient-specific wavefront measurements with specified refractive indices and prism corrections. Aging knowledge workers in Germany and Japan sustain replacement intervals, while EU MDR documentation burdens filter marginal suppliers from European distribution.
- Contact Lenses:Hydrogel or silicone hydrogel medical devices requiring sterile packaging and FDA Class II premarket clearance. Daily disposable formats gain share among younger demographics prioritizing convenience over extended-wear economics.
- Safety Glasses:ANSI Z87.1-compliant protective equipment for construction and manufacturing environments. Industrial procurement programs in the United States mandate certified suppliers, creating sticky distributor relationships.
Most installed capacity flows through Prescription Glasses. Expansion is steepest in Contact Lenses.
Material:
Cost tier stratification separates premium Italian acetate from commodity injection-molded inputs, with performance applications demanding engineered polymers.
- Plastic:Cellulose acetate and injection-molded polymers dominate fashion-forward frame production. Lombardy-based compounders supply premium grades to luxury houses, while Asian converters serve mass-market channels with shorter lead times.
- Glass:Mineral crown glass delivers superior optical clarity and scratch resistance for high-index prescriptions. Japanese optical glass foundries maintain capacity for specialized ophthalmic applications despite polycarbonate displacement in mainstream segments.
- Metal:Titanium and stainless steel enable thin, durable frame architectures through laser cutting and electroplating. Beta-titanium alloys from Japanese metallurgists command price premiums in premium rimless designs.
- Polycarbonate:Impact-resistant thermoplastic capturing safety and sports applications where ANSI Z87.1 or EN 166 certification is mandatory. Lightweight properties suit pediatric and active-use prescriptions.
Plastic commands the largest production volume. Metal is climbing the fastest among premium positioning strategies.
Application:
Volume concentration sits with vision correction, while protective and sports applications extract premiums through certification requirements and performance specifications.
- Fashion:Style-driven purchases decoupled from medical necessity, licensed through luxury houses and celebrity collaborations. Italian frame houses and Paris-based design studios set seasonal direction.
- Sports:Performance eyewear with anti-fog coatings, interchangeable lenses, and retention systems for cycling, skiing, and water sports. Oakley and specialized German manufacturers anchor technical positioning.
- Protective:Occupational safety equipment meeting ANSI Z87.1 or EN 166 impact standards. Industrial distributors in the United States and Germany bundle procurement with mandated personal protective equipment programs.
- Vision Correction:Medical device classification requiring prescription fulfillment through licensed optometrists or regulated online platforms. EU MDR and FDA pathways shape competitive entry barriers.
Vision Correction absorbs the majority of production capacity. Sports applications show the steepest expansion trajectory.
End User:
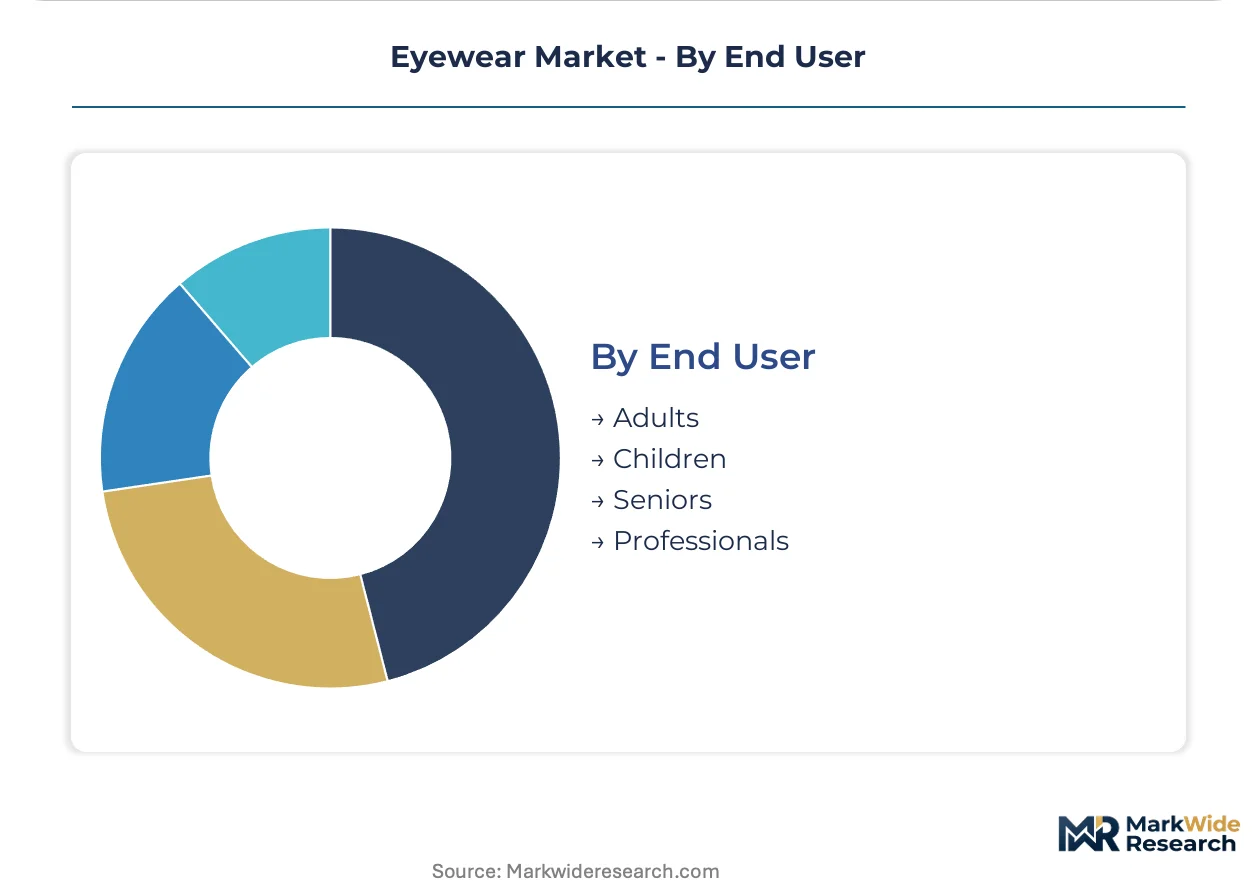
Customer lifecycle stage determines replacement frequency, price sensitivity, and channel preference across the segmentation map.
- Adults:Working-age consumers aged 18-45 driving fashion and contact lens volume. Virtual try-on platforms and direct-to-consumer channels capture initial purchase decisions before professional verification.
- Children:Pediatric prescriptions requiring durable, lightweight materials with growth-accommodating designs. Myopia progression management in East Asian markets stimulates specialized lens demand.
- Seniors:Presbyopic populations aged 65+ requiring progressive addition lenses with wider reading corridors. Japanese and German optometric practices lead free-form customization adoption.
- Professionals:Knowledge workers aged 45-65 with employer-sponsored vision benefits and digital eye strain concerns. Blue light filtration claims attract premium positioning despite fragmented ISO standards.
Adults represent the largest installed user base. Professionals are gaining share fastest through employer benefit expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy concentrates premium frame manufacturing while Japan dominates precision lens optics, yet both face divergent regulatory pressures from Brussels and Tokyo that reshape export competitiveness.
United States
FDA Class II device pathways for contact lenses and employer-sponsored vision benefits for professionals drive prescription volume. OSHA mandates ANSI Z87.1 compliance for industrial safety eyewear procurement. Massachusetts and California anchor direct-to-consumer virtual try-on platform development.
Germany
Free-form progressive lens adoption among presbyopic knowledge workers and statutory health insurance reimbursement structures sustain replacement cycles. EU MDR technical documentation requirements filter smaller frame importers from distribution. Baden-Württemberg hosts precision surfacing equipment manufacturers serving continental optometric practices.
Japan
HOYA Corporation and domestic optical glass foundries supply premium free-form progressive lenses to aging domestic and export markets. METI standards govern blue light filtration claims for digital eye strain products. Nagoya and Osaka metropolitan areas concentrate titanium alloy processing for rimless frame architectures.
India
PLI scheme incentives for medical device manufacturing attract lens casting and coating investments from multinational suppliers. CDSCO regulates contact lens imports while domestic production scales. Gujarat and Maharashtra emerge as precision optical instrument fabrication clusters serving Middle East and African export corridors.
South Korea
Mobile commerce penetration exceeding 70 percent among 25-40 year-old consumers accelerates virtual try-on adoption for initial frame selection. MFDS oversees medical device classification for corrective eyewear imports. Seoul Capital Area optometric chains deploy augmented reality platforms to reduce physical inventory carrying costs.
Eyewear Market Vendor Landscape
Italian producers anchor the premium frame tier; Japanese specialists hold precision lens fabrication. The market structures around consolidated multinational optical houses, mid-tier regional frame assemblers, and direct-to-consumer challengers. Three archetypes dominate: vertically integrated lens-to-retail conglomerates, manufacturing-cluster specialists with captive acetate or titanium supply, and platform-native brands bypassing traditional wholesale. Competitive moves concentrate on M&A for regulatory capability acquisition and automated fabrication capacity expansion.
Within the integrated multinational tier, EssilorLuxottica and HOYA Corporation exemplify archetypes spanning lens casting through retail network control. Carl Zeiss occupies a position representing precision optics specialization for digital eye strain applications. These anchors illustrate how regulatory compliance scale and manufacturing technology depth separate sustainable participants from margin-compressed assemblers.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Alcon |
| Johnson & Johnson Vision Care |
| Bausch & Lomb |
| Carl Zeiss |
| CooperVision |
| Safilo Group |
| Warby Parker |
| HOYA Corporation |
| Others |
Supply Flow & Price Mechanics
Employer-sponsored vision benefit programs concentrate procurement leverage among US and German professional segments, anchoring contract-based pricing for progressive lens replacements while compressing margins on standardized stock lenses through volume aggregation.
Pricing Analysis
Capacity additions in India's Gujarat and Maharashtra precision optical clusters are reshaping price floors for mid-tier prescription lenses. Three-tier pricing structure across premium free-form, standard digital surfacing, and economy stock lenses separates value capture by customization depth and certification grade. Pricing pressure stems from EU MDR compliance cost absorption filtering smaller frame producers from European distribution. Employer benefit administrators demonstrate lowest price sensitivity for premium progressive tiers, while direct-to-consumer buyers drive commoditization of basic single-vision prescriptions.
Supply Chain Analysis
Freight cost volatility from Lombardy acetate compounders to Asian assembly operations is amplifying working capital requirements for mid-tier frame manufacturers. Raw material supply draws from Italian specialty chemical producers for cellulose acetate, Japanese metallurgists for beta-titanium alloys, and German precision surfacing equipment fabricators. Single-source vulnerability concentrates in premium acetate grades where two Lombardy suppliers serve luxury house demand. Distribution runs through industrial safety distributors for ANSI Z87.1-compliant protective eyewear, licensed optometric practices for prescription fulfillment, and direct-to-consumer platforms for virtual try-on conversions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in eyewear hinges on automated digital surfacing cost-down trajectories and professional-tier premiumization through free-form progressive customization, compressing stock lens economics while elevating patient-specific value capture.
For Market Incumbents: Extend regulatory affairs capabilities through specialized third-party notified body partnerships to absorb EU MDR documentation burdens that filter marginal competitors. Deepen captive acetate supply relationships with Lombardy compounders to insulate input cost volatility from Asian converter competition. Prioritize backward integration into titanium laser cutting capacity to defend frame production cycle time advantages against automated milling entrants. For New Entrants and Emerging Players: Launch via direct-to-consumer virtual try-on platforms targeting South Korean and Japanese mobile commerce penetration above seventy percent among twenty-five to forty year-old prescription buyers. Exploit white-space in occupational safety channel expansion for ANSI Z87.1-compliant construction verticals where mandated procurement programs create sticky distributor relationships. Anchor initial positioning through blue light filtration claims for digital eye strain despite fragmented ISO standards, capturing professional segment premium willingness. For Investors and Strategic Acquirers: Vertically integrated multinational optical houses represent the most active acquirer category in this space, targeting regulatory compliance scale and automated fabrication capacity. Long-term viability over the coming decade rests on free-form progressive lens technology depth and captive retail network control. Monitor India PLI scheme medical device incentive utilization rates as inflection signal for precision optical instrument manufacturing migration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Consolidation | Specialized notified body partnerships reduce eight-to-fourteen month clinical evaluation timelines for corrective eyewear. |
| Automated Titanium Laser Cutting Deployment | Italian manufacturing clusters achieve complex geometric frame designs with compressed production cycles. |
| Direct-to-Consumer Virtual Try-On Launch | South Korean mobile commerce penetration enables augmented reality frame selection without physical showroom inventory. |
| Occupational Safety Channel Expansion | ANSI Z87.1 compliance unlocks mandated procurement programs through industrial distributors. |
| Free-Form Progressive Lens Technology Investment | Wavefront-guided design captures three-to-fourfold value per unit against standardized stock lenses. |
Methodological Framework
Direct dialogue with lens casting engineers, optometric practice owners, industrial safety procurement managers, and regulatory affairs specialists at notified bodies grounds qualitative findings. Secondary validation draws from FDA 510(k) premarket notification databases, EU MDR technical documentation guidance, ISO 12870 frame endurance standards, and customs trade records for acetate and titanium alloy flows. Bottom-up prescription volume modeling and top-down market value triangulation ensure cross-verified outputs.
Bottom-up segmentation analysis by product type, material grade, application context, and end-user lifecycle stage structures the analytical framework across the projection horizon. CAGRs derive from installed base replacement interval analysis, demographic presbyopia progression curves, and regulatory compliance cost trajectory modeling. Free-form progressive lens adoption rates and virtual try-on platform penetration serve as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR enforcement intensity shifts or acetate raw material supply disruptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Luxury Sunglass Market
Eyewear
United States Eyewear Market
Eyewear
Smart Eyewear Market
Eyewear
Polarized Sunglasses Market
Eyewear
Europe Eyewear Market
Eyewear
Latin America Eyewear Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Ultralight Eyeglass Frames Market
Eyewear
Spectacles Market
Eyewear
Smart Sunglasses Market
Eyewear
Eyeglass Market
Eyewear
Anti-Fog Lens Market
Eyewear
Face and Ear Bow Market
Eyewear
Middle East Eyewear Market
Eyewear
Sunglasses Pouch Market