
 3D Printing in Eyewear Market | 2026-2036
3D Printing in Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing in Eyewear Market Analysis
Multi-material vat photopolymerization is tilting frame production toward lattice-structured temples and gradient-density nose pads that were previously unmanufacturable. Materialise leverages its software-to-print workflow to dominate medical eyewear prototyping across European optical labs. EOS sustains industrial-grade selective laser sintering capacity for titanium-rich spectacle frames. Luxexcel specializes in inkjet-based lens printing, anchoring a niche where prescription curvature integrates directly with frame geometry.
3D printing in eyewear encompasses additive fabrication of ophthalmic frames, lenses, and complete spectacles through successive layer deposition of photopolymers, powdered metals, or thermoplastic filaments, typically achieving 50-100 micron resolution for surface finish requirements in optical-grade applications. The technology serves commercial purposes ranging from mass-customized consumer spectacles to patient-specific medical devices requiring precise pupillary distance and facial topography matching. Plastic and polyamide materials currently lead unit volume due to cost-efficient selective laser sintering workflows, while metal segments command premium positioning in luxury and medical-grade frames where nickel-free titanium biocompatibility drives purchasing decisions. Customization as a manufacturing stage represents the fastest-expanding margin pool, as direct-to-consumer scan-to-print platforms collapse traditional retail inventory models.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape market access for prescription eyewear, while REACH chemical compliance governs photopolymer resin formulations in European production. The US Occupational Safety and Health Administration and Germany's KBA-aligned workplace standards indirectly influence protective eyewear specifications that 3D printing suppliers must satisfy. Stakeholders should monitor how regulatory divergence between FDA predicate device requirements and EU MDR clinical evidence demands fragments certification costs across Atlantic supply chains.
Market Dynamics
Scan-to-print workflows are collapsing the traditional optical retail inventory model by enabling mass-customized frame production without mold tooling or minimum order quantities. This digitization of fitting geometry is concentrating manufacturing capability around software-integrated production clusters.
Growth Catalysts
- EU Medical Device Regulation:CE marking requirements for prescription eyewear are accelerating certification investments by European optical labs, creating captive demand for validated additive manufacturing workflows.
- Selective laser sintering of titanium:Biocompatible metal printing is displacing conventional milling for luxury and medical-grade frames where nickel-free properties command premium positioning.
- German production clustering:Berlin and Munich anchor specialized supply chains combining optical design software, powder bed fusion capacity, and regulatory consulting for frame manufacturers.
Market Restraints
- Photopolymer resin cost volatility:Specialized optical-grade vat photopolymerization materials carry 3-5x cost premiums over standard formulations, compressing margins for mid-market frame producers.
- Equipment supplier concentration:Industrial-grade selective laser sintering and multi-material vat photopolymerization systems depend on a narrow base of German and Belgian machinery providers.
- Surface finish limitations:Layer resolution constraints at 50-100 microns require secondary post-processing for optical-grade transparency in lens applications.
Strategic Opportunities
- Protective eyewear specification convergence:OSHA workplace standards and Germany's KBA-aligned industrial safety rules are creating unified demand for certified additive-manufactured safety frames.
- India optical retail digitization:Direct-to-consumer scanning platforms are penetrating tier-2 cities where traditional fitting infrastructure remains underdeveloped.
- Lens-frame integration printing:Inkjet-based prescription curvature deposition enables single-build manufacture of complete spectacles, collapsing assembly steps.
Industry Challenges
- Additive manufacturing technician scarcity:Optical-grade frame production requires hybrid skills combining 3D printing parameter optimization with ophthalmic measurement protocols.
- FDA 510(k) predicate device matching:Novel lattice-structured temple designs face extended clearance timelines when no substantially equivalent conventional frame exists.
- Legacy ERP integration friction:Scan-to-print platforms require real-time data exchange with established optical lab management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing in Eyewear Market |
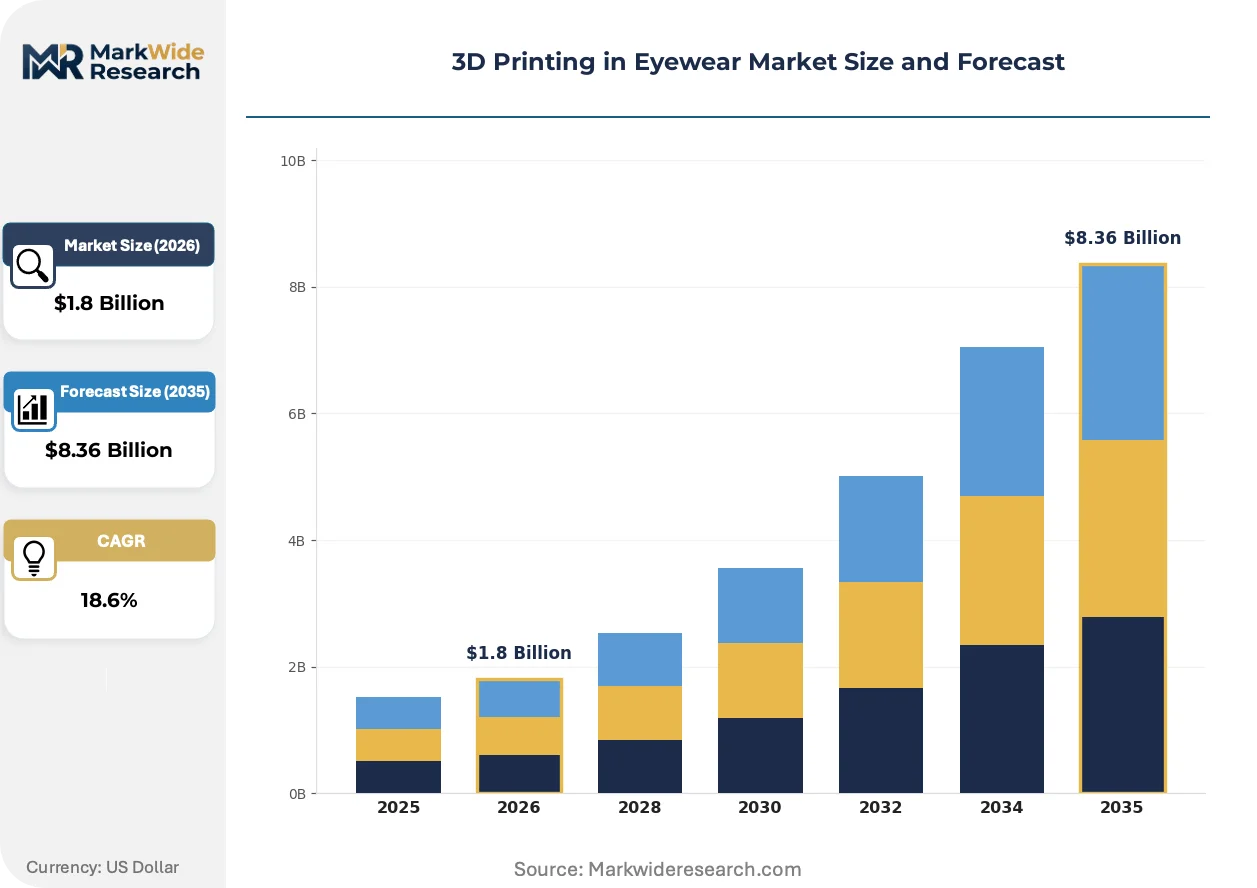
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glasses, Sunglasses, Contact Lenses, Frames Material: Plastic, Metal, Polyamide, Resin Manufacturing Stage: Prototyping, Production, Customization, Design End User: Retailers, Manufacturers, Consumers, Designers |
| Companies Covered | Materialise, EOS, Luxexcel, Essilor International S.A., MYKITA, Formlabs, Carbon, Inc., Hoet, Sculpteo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing in Eyewear Market Emerging Trajectories
Multi-material deposition and computational design are converging to produce geometrically complex eyewear components impossible through injection molding or CNC machining. These capabilities are redrawing competitive boundaries between equipment suppliers, material formulators, and finished frame brands.
Vat photopolymerization with tunable stiffness resins is digitizing the production of gradient-density nose pads and lattice-structured temples. Optical retailers in Germany and the Netherlands are adopting these workflows for same-day custom fitting. The technology is digitizing inventory models by enabling single-unit production economics without mold amortization.
REACH chemical compliance and evolving EU MDR clinical evidence requirements are tightening material traceability mandates for photopolymer formulations used in medical-grade frames. Manufacturers must document biocompatibility testing across complete supply chains. European optical labs are responding by consolidating supplier relationships around certified resin providers with pre-validated regulatory dossiers.
Direct-to-consumer scan-to-print platforms are compressing the traditional optical retail channel by enabling patients to upload facial topography data for remote frame production. This disintermediation is most visible in North American and Australian markets where telehealth optometry regulations have relaxed remote prescription verification. Independent optical retailers are countering by embedding additive manufacturing capacity in-store for immediate fitting adjustments.
3D Printing in Eyewear Market Segmentation
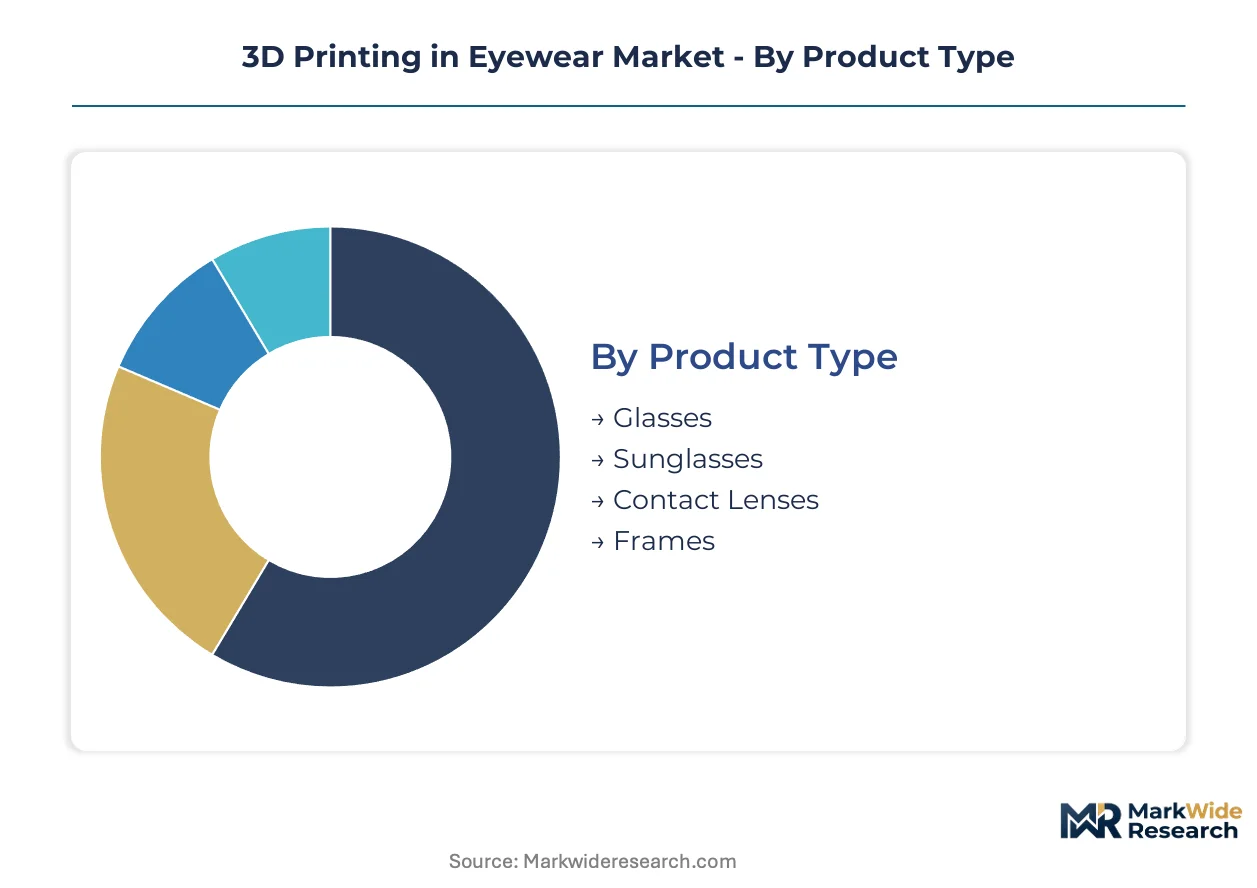
Segmentation in 3D printing eyewear reveals how additive manufacturing fragments across optical applications, material specifications, and value chain positions. Each dimension exposes distinct margin pools, regulatory exposures, and technology requirements that shape supplier strategies.
Product Type:
Use-case spectrum spans vision correction devices to protective accessories, with additive manufacturing penetrating each at different technology readiness levels.
- Frames:Lattice-structured temples and gradient-density nose pads exploit multi-material vat photopolymerization for geometries impossible through injection molding. German optical labs in Berlin and Munich concentrate demand for same-day custom fitting workflows.
- Glasses:Complete prescription spectacles integrate lens curvature with frame geometry through inkjet-based deposition, collapsing traditional assembly steps. North American direct-to-consumer platforms accelerate adoption where telehealth optometry regulations permit remote prescription verification.
- Sunglasses:Fashion-forward frames leverage selective laser sintering of polyamide for complex surface textures without mold tooling costs.
- Contact Lenses:Inkjet printing of prescription curvature remains nascent, constrained by optical-grade transparency requirements and FDA 510(k) biocompatibility thresholds.
The dominant share belongs to Frames, while Glasses is closing the gap fastest.
Material:
Cost tier stratification separates commodity thermoplastics from premium biocompatible metals, with certification requirements widening the gap.
- Polyamide:Selective laser sintering workflows dominate mid-market production, offering cost-efficient powder bed fusion with mechanical durability for daily-wear spectacles. REACH chemical compliance mandates tighten traceability for European optical labs sourcing certified resin providers.
- Metal:Nickel-free titanium biocompatibility commands premium positioning in luxury and medical-grade frames, with EOS industrial-grade selective laser sintering capacity anchoring German production clusters.
- Plastic:Standard photopolymer formulations serve prototyping volumes where surface finish tolerances remain relaxed.
- Resin:Specialized optical-grade vat photopolymerization materials carry cost premiums that compress margins for producers outside certified supply chains.
Polyamide holds volume leadership, though Metal is expanding most quickly in certified medical applications.
Manufacturing Stage:
Customer type determines whether additive manufacturing serves internal R&D, external production, or direct-to-consumer fulfillment.
- Customization:Scan-to-print platforms collapse traditional optical retail inventory models by enabling mass-customized frame production without minimum order quantities. This stage captures the steepest expansion trajectory as digitization of fitting geometry concentrates manufacturing around software-integrated production clusters.
- Production:Validated additive manufacturing workflows serve European optical labs responding to EU Medical Device Regulation CE marking requirements for prescription eyewear.
- Prototyping:Rapid iteration for frame designers reduces time-to-market for seasonal collections, with Materialise software-to-print workflows dominating European medical eyewear prototyping.
- Design:Computational geometry tools enable lattice structures and gradient density before physical fabrication, though legacy ERP integration friction constrains adoption.
Customization leads value creation, while Production is gaining share fastest as regulatory validation matures.
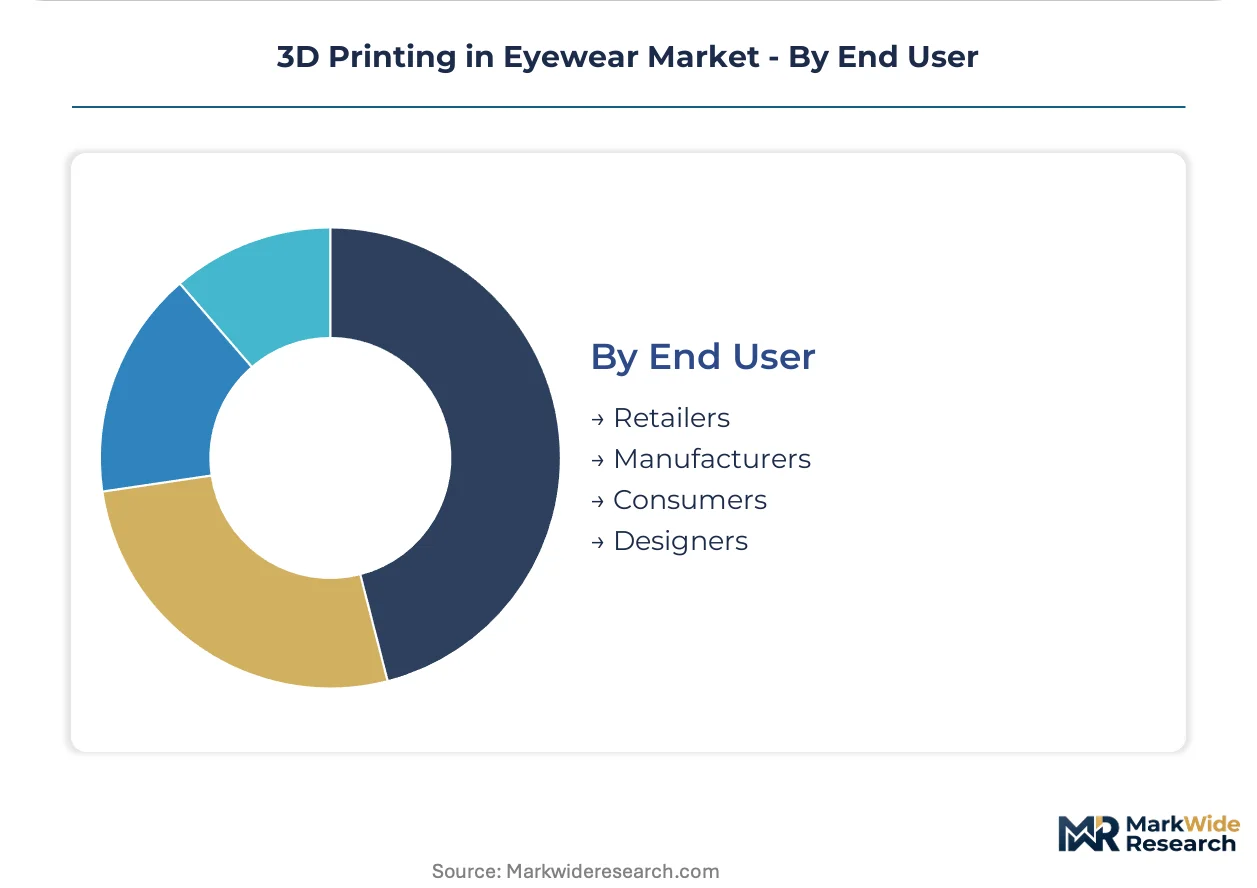
End User:
Volume concentration varies by channel control, with direct-to-consumer platforms disrupting traditional retail intermediation.
- Retailers:Independent optical retailers embed additive manufacturing capacity in-store for immediate fitting adjustments, countering direct-to-consumer disintermediation. German and Dutch retailers adopt multi-material vat photopolymerization for same-day custom fitting.
- Consumers:Direct-to-consumer scan-to-print platforms penetrate tier-2 Indian cities where traditional fitting infrastructure remains underdeveloped, compressing channel margins.
- Manufacturers:Frame brands consolidate supplier relationships around certified resin providers with pre-validated regulatory dossiers for EU MDR compliance.
- Designers:Computational design specialists require hybrid skills combining 3D printing parameter optimization with ophthalmic measurement protocols, creating capability scarcity.
Retailers anchor current volume, though Consumers are climbing the fastest as platform economics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical labs export certified additive manufacturing workflows to North American and Asian markets where FDA and local medical device regulations drive demand for validated production systems. This trade corridor concentrates high-value equipment and software licensing revenue in Berlin and Munich production clusters.
United States
Direct-to-consumer scan-to-print platforms penetrate telehealth-permissive states, collapsing traditional optical retail channels. FDA 510(k) clearance pathways for prescription eyewear tighten predicate device matching requirements for novel lattice-structured designs. Boston and Austin anchor venture-backed platform development clusters competing with German equipment suppliers.
Germany
MYKITA and Materialise production clusters in Berlin drive EU Medical Device Regulation CE marking investments for medical-grade frames. REACH chemical compliance mandates tighten photopolymer resin traceability across Bavarian and North Rhine-Westphalian optical labs. Munich concentrates selective laser sintering capacity for nickel-free titanium biocompatibility certification.
India
Tier-2 city optical retail digitization accelerates as traditional fitting infrastructure remains underdeveloped in Maharashtra and Gujarat. Central Drugs Standard Control Organization oversight of medical device imports creates compliance barriers for uncertified foreign frame suppliers. Bangalore and Hyderabad emerge as software development hubs for facial topography scanning applications.
China
Domestic optical brands pilot inkjet-based lens printing for prescription curvature integration with frame geometry. National Medical Products Administration biocompatibility thresholds for contact lens printing constrain technology readiness. Shenzhen and Dongguan manufacturing zones concentrate mid-market polyamide selective laser sintering capacity for export-oriented sunglass frames.
Japan
Precise pupillary distance matching requirements drive demand for patient-specific medical eyewear in aging demographics. Ministry of Economy, Trade and Industry standards for industrial safety eyewear influence protective frame specifications. Nagoya and Osaka optical districts adopt computational design tools for lattice-structured temple prototyping.
3D Printing in Eyewear Market Vendor Landscape
Channel-controlling players compete with product-specialist players across software-integrated production clusters and standalone equipment supply. The vendor base organizes around three archetypes: software-to-print workflow integrators, industrial-grade powder bed fusion specialists, and inkjet-based lens deposition pioneers. Capacity expansion and strategic partnerships dominate competitive moves as regulatory validation requirements deepen captive customer relationships.
Among European workflow specialists, Materialise and EOS exemplify contrasting scale positions within the certified medical eyewear supply chain. Luxexcel occupies a niche specialization tier where prescription curvature deposition integrates directly with frame geometry. MYKITA represents vertically integrated frame brands that consolidate supplier relationships around pre-validated regulatory dossiers for EU MDR compliance.
| Leading Market Players |
|---|
| Materialise |
| EOS |
| Luxexcel |
| Essilor International S.A. |
| MYKITA |
| Formlabs |
| Carbon, Inc. |
| Hoet |
| Sculpteo |
| Others |
Supply Flow & Price Mechanics
Rotterdam-to-Hamburg freight corridors transmit resin cost volatility directly into German optical lab pricing power, compressing mid-market frame margins while concentrating premium positioning around certified titanium workflows. This logistics-cost feedback loop reinforces three-tier pricing structure across premium medical-grade, standard polyamide, and economy prototyping tiers.
Pricing Analysis
Prior-generation selective laser sintering equipment undercuts current-generation multi-material vat photopolymerization systems by 40-60% on capital cost, though next-generation inkjet lens deposition commands the steepest per-unit premiums. Pricing stratifies across premium FDA-cleared titanium frames, standard REACH-compliant polyamide spectacles, and economy resin prototypes with relaxed surface finish tolerances. Cost compression in mid-market SLS workflows is intensifying because photopolymer resin suppliers consolidate certified formulations under EU MDR traceability mandates. Independent optical retailers exhibit the highest price sensitivity, while hospital procurement committees for patient-specific medical eyewear demonstrate minimal elasticity.
Supply Chain Analysis
Tariff exposure between Chinese powder bed fusion component suppliers and German frame manufacturers dominates supply chain risk planning for European optical labs. Equipment sourcing draws from Belgium, Germany, and the United States for industrial-grade selective laser sintering and multi-material vat photopolymerization systems. Raw material dependencies center on titanium powder from specialized metallurgical suppliers, optical-grade photopolymer resins subject to REACH chemical compliance, and certified polyamide powders for mid-market production. Single-source vulnerability concentrates in specialized nozzle assemblies for inkjet lens deposition. Distribution runs through software-integrated production clusters in Berlin and Munich that export validated workflows to North American and Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software licensing and regulatory dossier subscriptions now expand faster than hardware unit sales, converting capital expenditure relationships into recurring revenue streams for equipment-integrated workflow providers.
For Market Incumbents: Entrench certification moats by pre-validating EU MDR clinical evidence packages for photopolymer resin formulations, locking optical labs into captive supplier relationships. Add selective laser sintering capacity in Munich to anchor nickel-free titanium biocompatibility workflows against emerging Asian equipment competitors. Vertical integration into facial topography scanning software deepens switching costs for retail customers. For New Entrants and Emerging Players: Pursue tier-2 Indian city optical retail digitization where traditional fitting infrastructure gaps create immediate scan-to-print platform demand. Target protective eyewear specification convergence between OSHA workplace standards and Germany's KBA-aligned industrial safety rules as the most penetrable regulatory harmonization opportunity. Lead with direct-to-consumer telehealth integration in telemedicine-permissive North American jurisdictions. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial 3D printing parent companies with undermonetized medical eyewear verticals and dormant FDA 510(k) predicate device libraries. Five-to-ten year viability hinges on regulatory validation asset accumulation rather than pure equipment shipment volume. Monitor EU MDR notified body capacity constraints as the critical inflection signal for certification backlog severity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Accelerates EU Medical Device Regulation compliance for prescription frame workflows in German optical labs. |
| Software Companion Development | Integrates facial topography scanning with print parameter optimization for same-day custom fitting. |
| Hospital System Partnership | Secures patient-specific medical eyewear procurement contracts requiring precise pupillary distance matching. |
| Backward Integration into Resin Formulation | Captures REACH chemical compliance margins and tightens biocompatibility certification control. |
| Platform Integration with Telehealth Optometry | Enables remote prescription verification for direct-to-consumer scan-to-print channel expansion. |
Methodological Framework
Operator-level perspectives from optical lab production managers, additive manufacturing technicians, ophthalmic measurement specialists, and regulatory affairs consultants anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body registers, and REACH chemical compliance filings. Customs records for photopolymer resin imports and optical equipment trade flows supplemented demand-side triangulation. Bottom-up unit economics from scan-to-print platform operators and top-down market sizing from equipment shipment aggregates were reconciled through iterative validation.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, material certification tier, manufacturing stage maturity, and end-user channel control. CAGRs derived from equipment replacement cycles, regulatory adoption curves, and telehealth optometry penetration patterns. Industry-specific forecast inputs incorporated selective laser sintering powder consumption trends and inkjet lens deposition yield improvement trajectories.
Sensitivities concentrate around EU MDR notified body capacity bottlenecks, photopolymer resin biocompatibility test backlog duration, and telehealth optometry regulatory reversals in key North American jurisdictions. Forecasts embed assumptions regarding certification timeline normalization and software-to-print workflow adoption velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Sunglasses Pouch Market
Eyewear
Luxury Sunglass Market
Eyewear
Polarized Sunglasses Market
Eyewear
Goggles Market
Eyewear
Luxury Eyewear Market
Eyewear
North America Eyewear Market
Eyewear
Europe Eyewear Market
Eyewear
Latin America Eyewear Market
Eyewear
Sunglasses Market
Eyewear
Smart Eyewear Market
Eyewear
Anti-Fog Lens Market
Eyewear
Reading Glasses Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Blue Light Glasses Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market