
 Sunglasses Market | 2026-2036
Sunglasses Market Size, Share, and Industry Trends Forecast 2026-2036
Sunglasses Market Intelligence
Subscription-based lens replacement and software-enabled tint calibration is consolidating recurring revenue into what was historically a one-time hardware purchase. EssilorLuxottica leverages its vertically integrated optical supply chain to anchor premium positioning across prescription and plano sunwear. Maui Jim specializes in polarized lens technology to differentiate on glare reduction performance in marine and high-altitude environments. De Rigo Vision competes through exclusive licensing arrangements that control distribution access across European specialty retail channels.
Sunglasses are tinted or light-attenuating eyewear assemblies combining UV-absorbing substrates—polycarbonate, Trivex, or mineral glass—with anti-reflective coatings and frame structures to reduce ocular exposure to solar radiation and improve visual comfort under bright conditions. Polarized lenses dominate functional sales among drivers and water sports participants due to glare cancellation properties, while photochromic segments capture commuter crossover demand through light-adaptive convenience. Acetate and titanium material tiers concentrate margin pools in fashion and sports professional channels respectively, where durability and weight specifications command price premiums.
The US FDA classifies sunglasses as Class I medical devices with 21 CFR 886.5850 lens transmission standards, while the EU enforces CE marking under the Personal Protective Equipment Regulation for claims exceeding baseline UV filtration. Australia's TGA mandates category-based labeling that shapes consumer comprehension of protection levels. Stakeholders must monitor evolving harmonization between ISO 12312-1 and national deviations as regulatory divergence creates compliance complexity for multi-territory product lines.
Market Dynamics
Subscription-based lens replacement and software-enabled tint calibration is consolidating recurring revenue into what was historically a one-time hardware purchase. This structural shift transforms manufacturer-customer relationships from transactional to continuous engagement models.
Growth Catalysts
- Outdoor recreation participation:Recreational sports participation climbs across North America and Western Europe, expanding the functional sunglasses buyer base beyond fashion consumers.
- UV protection mandates:Australia's TGA and the EU's CE marking framework are tightening product compliance requirements, elevating baseline quality standards and filtering substandard imports.
- Photochromic lens technology:Light-adaptive convenience captures commuter crossover demand, merging prescription eyewear and sun protection into single-assembly solutions.
Market Restraints
- Acetate and titanium input volatility:Premium frame material costs fluctuate with petrochemical and rare earth supply chains, compressing margin pools in fashion and sports professional channels.
- Manufacturing concentration:Domestic production scale in China reshapes regional volume distribution, creating dependency on single-source supply for mid-tier assembly.
- Polarized lens technical ceiling:Glare cancellation performance in marine and high-altitude environments approaches theoretical limits, constraining differentiation through optical engineering alone.
Strategic Opportunities
- Underpenetrated Indian market:Rising consumer discretionary spending and limited organized retail penetration create whitespace for branded entry at mass-premium price points.
- Smart eyewear convergence:Integration of audio, health monitoring, and AR display technologies with UV protection opens adjacent revenue streams beyond traditional optics.
- Direct-to-consumer channel innovation:Virtual try-on and prescription upload workflows bypass specialty retail gatekeepers, capturing margin previously allocated to wholesale distribution.
Industry Challenges
- ISO 12312-1 harmonization delays:Regulatory divergence between international standards and national deviations creates compliance complexity for multi-territory product lines.
- Optical engineering talent scarcity:Specialized lens design and coating chemistry expertise concentrates within legacy manufacturing clusters, constraining new entrant R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sunglasses Market |
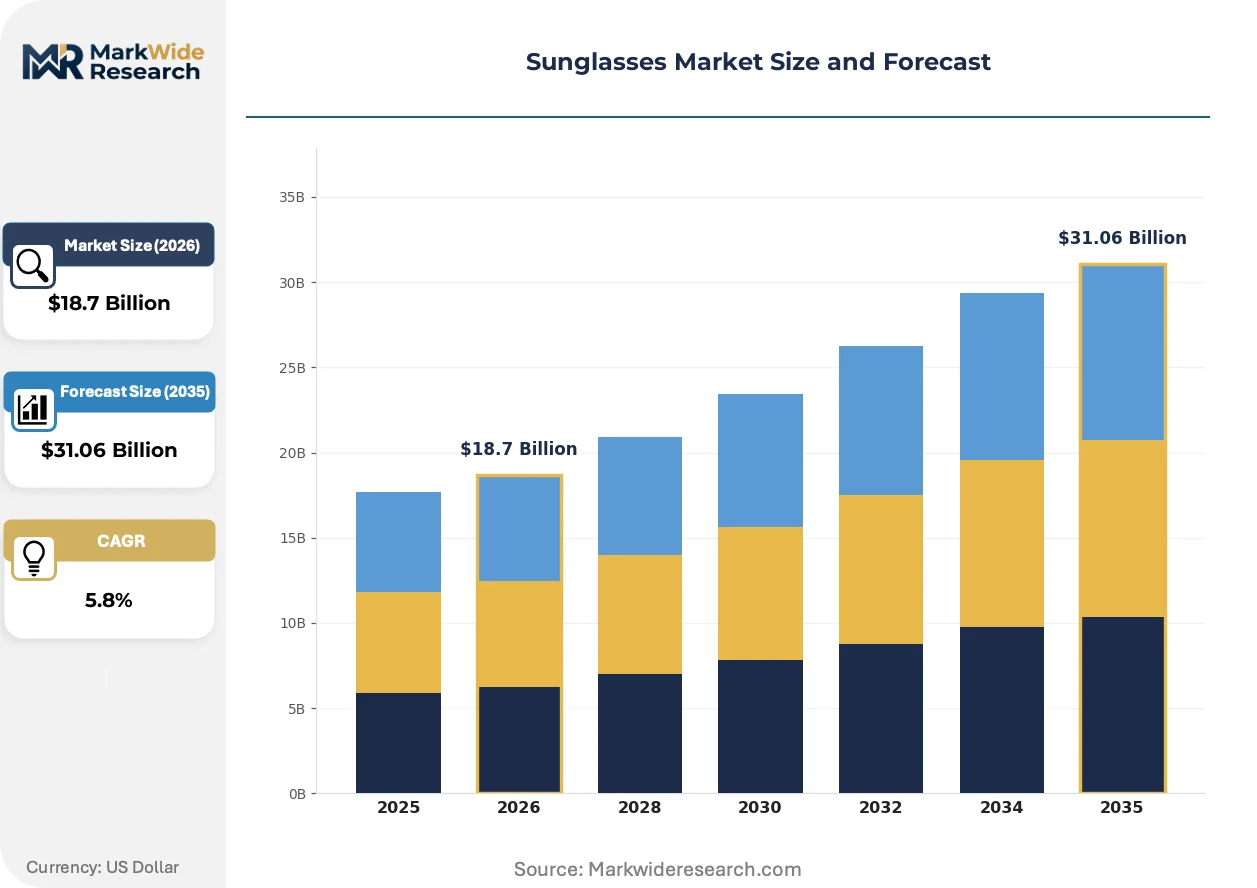
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polarized, Gradient, Mirrored, Photochromic, Rimless, Clip-on Material: Plastic, Metal, Acetate, Titanium, Wood, Nylon End User: Outdoor Enthusiasts, Fashion Consumers, Sports Professionals, Commuters, Drivers, Students Distribution Channel: Optical Stores, Online Retailers, Department Stores, Specialty Boutiques, Sports Shops, Duty-Free Shops |
| Companies Covered | Kering, Ray-Ban, EssilorLuxottica, Maui Jim, Oakley, Safilo Group, De Rigo Vision, MYKITA, Marcolin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sunglasses Market Strategic Shifts & Innovations
Active reshaping of the sunglasses market centers on three vectors: material science advancement, regulatory harmonization pressure, and consumption model disruption. Each trend alters competitive positioning and investment allocation across the value chain.
Electrochromic lens technology is absorbing incremental R&D investment from established optical manufacturers. These assemblies enable user-controlled tint adjustment via embedded power systems, appealing to drivers and pilots requiring rapid adaptation across variable lighting conditions. The technology is absorbing market share from static polarized alternatives in premium functional segments by eliminating the need for multiple specialized pairs.
EU enforcement of CE marking under the Personal Protective Equipment Regulation is intensifying for claims exceeding baseline UV filtration. Manufacturers must now substantiate performance assertions through notified body certification, raising documentation burdens and testing costs. Sports professional and industrial safety segments face the steepest compliance ramps as they migrate from voluntary to mandatory third-party validation.
Buyers increasingly unbundle after-sales service from initial hardware acquisition, treating frame and lens replacement as independent procurement events. Specialty retail channels lose attachment revenue as consumers source replacement lenses through manufacturer-direct portals or third-party optical labs. This pattern concentrates in North America and Western Europe where digital commerce infrastructure supports component-level purchasing.
Sunglasses Market Segmentation
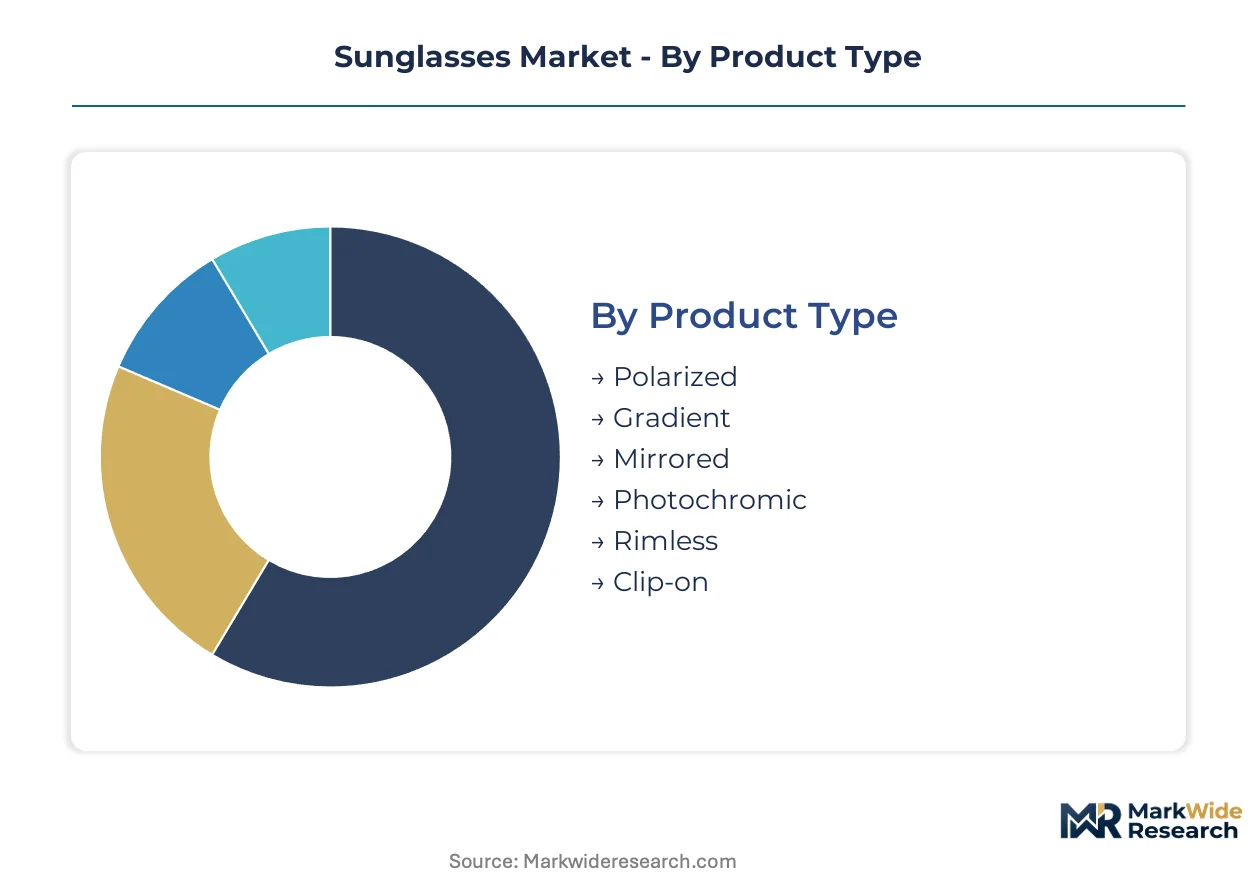
Lens technology and frame material specifications dictate performance boundaries and price positioning across the sunglasses value chain. Segmentation clarity enables manufacturers to align R&D investment with functional requirements rather than demographic assumptions.
Product Type:
Lens engineering specifications separate functional performance tiers from aesthetic positioning in optical design.
- Polarized:Multi-layer polarizing film sandwiches between optical-grade substrates to cancel horizontal glare reflection. Demand concentrates among marine operators and high-altitude pilots where glare-induced visual fatigue creates safety hazards.
- Photochromic:Silver halide or naphthopyran molecules embedded in lens matrix enable reversible darkening under UV exposure. Commuters in Germany and Japan drive adoption where rapid indoor-outdoor transitions occur throughout workdays.
- Gradient:Variable tint density from top to bottom optimizes dashboard visibility for drivers. Popular in urban mobility contexts where overhead sun exposure differs from forward sightlines.
- Mirrored:Thin metallic oxide deposition on lens surface reflects additional visible light beyond substrate absorption. Favored by snow sports participants and military applications requiring maximum light attenuation.
- Rimless:Drill-mounted lenses eliminate frame obstruction for expanded peripheral vision. Lightweight construction appeals to endurance athletes and prescription wearers seeking minimal facial contact.
- Clip-on:Auxiliary tinted lenses attach over prescription eyewear via magnetic or mechanical fixtures. Cost-sensitive consumers and occasional sun exposure users dominate procurement.
Mature deployment sits with polarized configurations. Newer deployment is concentrated in photochromic assemblies with prescription integration.
Material:
Frame substrate selection trades weight, durability, and manufacturing complexity against target price positioning.
- Acetate:Cellulose acetate polymer enables deep color saturation and hand-polished finishing through CNC milling and tumbling processes. Fashion consumers in Italy and France drive volume where heritage craftsmanship commands premium pricing.
- Titanium:Beta-titanium alloys deliver strength-to-weight ratios exceeding stainless steel by 40% with full corrosion resistance. Sports professionals and military contractors specify these frames for equipment compatibility under helmet or goggle systems.
- Plastic:Injection-molded polycarbonate or TR-90 nylon achieves unit economics for mass-market distribution. Volume concentration in China's domestic market where price elasticity shapes purchasing decisions.
- Metal:Stainless steel and Monel alloys provide structural rigidity with moderate weight penalties. Optical stores favor these frames for prescription mounting stability and adjustment durability.
- Wood:Laminated hardwood veneers or bamboo composites target sustainability-positioned consumers. Limited production scale constrains availability to specialty boutiques and direct-to-consumer channels.
- Nylon:Grilamid and similar polyamides deliver flexibility and impact resistance for active use cases. Cycling and running segments specify these materials for sweat resistance and shape memory.
Acetate and titanium concentrate margin capture. Plastic substrates dominate unit volume throughput.
End User:
Activity-specific visual demands create distinct performance requirements that transcend age or income demographics.
- Outdoor Enthusiasts:Hikers, climbers, and anglers require wraparound coverage with side shield integration. Australia's TGA category labeling shapes purchasing criteria for UV protection verification in this segment.
- Sports Professionals:Elite athletes specify frame-lens systems certified to ISO 12312-1 impact standards. Sponsorship-dependent procurement concentrates volume with contracted eyewear partners.
- Drivers:Polarized or gradient configurations reduce road surface glare and dashboard reflection. Automotive fleet procurement in Germany and Japan creates B2B volume concentration.
- Fashion Consumers:Brand signaling and facial aesthetics dominate specification over optical performance. Seasonal collection cycles drive replacement frequency above functional degradation timelines.
- Commuters:Photochromic convenience merges sun protection with indoor clarity for mixed-environment travel. Urban density in Singapore and South Korea accelerates adoption.
- Students:Price sensitivity and trend responsiveness concentrate demand in fast-fashion retail channels. Campus proximity stores capture impulse purchasing patterns.
Outdoor enthusiasts and sports professionals are expanding most quickly. Fashion consumers retain the largest absolute revenue base.
Distribution Channel:
Channel selection determines margin retention, customer education depth, and inventory risk allocation between manufacturer and retailer.
- Optical Stores:Licensed opticians provide prescription verification, pupillary distance measurement, and frame adjustment services. Professional consultation justifies price premiums for progressive lens and bifocal configurations.
- Online Retailers:Virtual try-on algorithms and home trial programs reduce fit uncertainty for standardized frame geometries. Direct-to-consumer brands bypass wholesale margin extraction through proprietary digital platforms.
- Department Stores:Seasonal merchandising and promotional calendar alignment drive volume for fashion-positioned collections. Loss of specialty optical expertise shifts purchasing toward plano sunwear over prescription integration.
- Specialty Boutiques:Curated independent retail provides discovery environment for emerging designers and limited editions. High service intensity sustains price positioning above mass-market alternatives.
- Sports Shops:Technical staff deliver activity-specific fitting for retention systems and lens tint recommendations. Mountain and marine specialty retailers concentrate in Colorado, California, and Florida coastal markets.
- Duty-Free Shops:Travel retail captures impulse purchasing with price advantages from tax exemption. Airport concession placement targets affluent international travelers with compressed decision windows.
Optical stores retain prescription-complexity transactions. Online retailers are gaining share fastest in plano and replacement-lens categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors optical manufacturing scale for the sunglasses industry, with export corridors feeding distribution networks across North America and Europe. Domestic consumption clusters in coastal Chinese cities reshape volume allocation as discretionary spending rises.
China
Outdoor recreation participation climbs in Zhejiang and Jiangsu provinces, expanding functional eyewear procurement beyond fashion buyers. The country's national standardization administration enforces GB 10810.3 for lens transmittance, tightening import substitution for mid-tier assembly. Wenzhou's eyewear industrial cluster concentrates acetate frame finishing for European luxury houses.
United States
Recreational sports participation drives wraparound and polarized lens demand across Colorado and California mountain markets. FDA 21 CFR 886.5850 Class I medical device classification mandates lens transmission documentation for UV-blocking claims. Miami-Dade retail corridors concentrate Latin American export staging and duty-free distribution to Caribbean travelers.
Germany
Photochromic lens adoption accelerates among commuters in Bavaria and Baden-Württemberg automotive manufacturing belts. CE marking under the Personal Protective Equipment Regulation requires notified body certification for performance claims exceeding baseline UV filtration. Munich optical engineering clusters supply coating chemistry expertise to prescription-integrated sunwear programs.
Australia
TGA category-based labeling mandates reshape consumer comprehension of protection levels across Queensland and New South Wales coastal populations. Surf lifesaving clubs and marine operators drive polarized lens specification for glare-critical environments. Sydney specialty retail channels anchor Asia-Pacific product testing for UV attenuation performance.
India
Rising consumer discretionary spending in Maharashtra and Karnataka creates whitespace for branded entry at mass-premium price points. BIS certification requirements for imported eyewear elevate compliance thresholds for organized retail penetration. Mumbai's optical wholesale markets concentrate grey-channel distribution from Chinese manufacturing sources.
Sunglasses Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the sunglasses value chain. EssilorLuxottica's captive lens foundries and frame finishing assets contrast with independent designers outsourcing to Wenzhou and Shenzhen contract manufacturers. Three archetypes dominate: vertically integrated optical conglomerates controlling prescription-to-plano pipelines; independent specialists in polarized or photochromic engineering; and licensed fashion houses monetizing brand equity through distribution partnerships. Consolidation through frame brand acquisition and exclusive retail licensing agreements concentrates shelf access in European and North American markets.
Among vertically integrated players, EssilorLuxottica anchors premium positioning through optical supply chain control. Maui Jim exemplifies the polarized specialist archetype with glare reduction performance differentiation. De Rigo Vision occupies a position within licensed distribution, securing exclusive access across European specialty retail channels through brand partnership structures.
| Leading Market Players |
|---|
| Kering |
| Ray-Ban |
| EssilorLuxottica |
| Maui Jim |
| Oakley |
| Safilo Group |
| De Rigo Vision |
| MYKITA |
| Marcolin |
| Others |
Cost & Logistics Intelligence
Fashion consumers in Italy and France anchor premium pricing through acetate frame procurement, where heritage craftsmanship certification commands substantial markups over injection-molded alternatives. This buyer concentration enables manufacturers to sustain value-based pricing tiers despite polycarbonate commoditization in mass-market channels.
Pricing Analysis
UV protection performance certification anchors value-based pricing across the sunglasses market. Three-tier pricing structure across premium, standard, and economy levels separates FDA-documented Class I medical devices from baseline CE-marked alternatives. Cost compression in plastic-framed segments is intensifying because China's domestic manufacturing scale reshapes regional volume distribution. Students and price-sensitive commuters exhibit highest elasticity, while sports professionals and outdoor enthusiasts demonstrate lowest sensitivity due to safety-critical procurement criteria.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Wenzhou feed hub-and-spoke patterns into European luxury houses and North American specialty retail. Manufacturing concentrates in China, with acetate finishing clusters in Italy and titanium processing in Japan. Raw material dependencies include cellulose acetate polymers, beta-titanium alloys, and silver halide photochromic substrates. Single-source vulnerability concentrates in polycarbonate substrate supply from petrochemical corridors. Distribution runs through optical stores for prescription-complexity transactions and direct-to-consumer portals for plano and replacement-lens categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sunglasses market is becoming a vertical-integration race as players pursue captive lens foundry control to defend margin pools against contract manufacturing commoditization.
For Market Incumbents: Extend optical supply chain control through prescription-to-plano pipeline integration and exclusive retail licensing arrangements. Counter direct-to-consumer entrants by embedding software-enabled tint calibration and subscription-based lens replacement into core offerings. Certification investment in ISO 12312-1 harmonization creates defensive moats against regulatory divergence complexity. For New Entrants and Emerging Players: Capture whitespace in India's underpenetrated organized retail sector through mass-premium price positioning and BIS certification compliance. Target commuter segments in dense urban environments with photochromic convenience propositions. Deploy virtual try-on and prescription upload workflows to bypass established wholesale distribution gatekeepers. For Investors and Strategic Acquirers: The window for entry favors polarized technology specialists with marine and high-altitude performance differentiation. Long-term viability hinges on R&D velocity in electrochromic and smart eyewear convergence categories. Watch for ISO 12312-1 harmonization completion as inflection indicator for multi-territory compliance scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lens Foundries | Captive polycarbonate and Trivex substrate production insulates margin pools from petrochemical volatility. |
| Direct-to-Consumer Channel Launch | Virtual try-on algorithms bypass optical store gatekeepers and capture wholesale margin extraction. |
| Smart Eyewear Technology Licensing | Audio and health monitoring integration opens adjacent revenue streams beyond traditional UV protection. |
| Exclusive Retail Licensing Agreements | European specialty boutique access concentrates shelf positioning against mass-market alternatives. |
| Photochromic Prescription Integration | Light-adaptive convenience merges sun protection with indoor clarity for commuter crossover demand. |
Research Approach
Trade databases, regulatory filings, and optical industry association reports formed the secondary backbone for this analysis. Primary interviews with lens coating chemists, optical store proprietors, frame manufacturing plant managers, and sports specialty retail buyers validated demand assumptions. SEC 10-K disclosures from vertically integrated conglomerates and FDA 21 CFR 886.5850 registration data supplemented customs records from Chinese export corridors. Bottom-up and top-down triangulation reconciled unit volume estimates with value aggregation across material tiers.
Bottom-up modeling built forecasts from product-level pricing and volume assumptions across lens technology, frame material, and end-user segments. Top-down validation cross-checked aggregate market expansion against macroeconomic indicators including recreational sports participation rates and consumer discretionary spending indices. CAGRs were derived from regression analysis of historical shipment data against projected adoption curves for photochromic and electrochromic technologies. The framework incorporated ISO 12312-1 compliance timelines and TGA category labeling enforcement as regulatory boundary conditions.
The model holds under steady regulatory harmonization progress; deviation in ISO 12312-1 national adoption timelines or acute acetate input cost spikes would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Luxury Eyewear Market
Eyewear
North America Eyewear Market
Eyewear
Polarized Sunglasses Market
Eyewear
Spectacles Market
Eyewear
Reading Glasses Market
Eyewear
Anti-Fog Lens Market
Eyewear
Ultralight Eyeglass Frames Market
Eyewear
Asia-Pacific Eyewear Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
United States Eyewear Market
Eyewear
Middle East Eyewear Market
Eyewear
Wooden Eyewear Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Glasses Frame Market
Eyewear
Luxury Sunglass Market