
 Smart Sunglasses Market | 2026-2036
Smart Sunglasses Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sunglasses Market Analytics
Direct-to-consumer online channels are reshaping how smart sunglasses reach buyers, bypassing traditional eyewear retail gatekeepers. Meta leverages its social media ecosystem to drive discovery and conversion for camera-enabled frames. EssilorLuxottica anchors global manufacturing scale through its integrated lens and frame production network. Vuzix specializes in enterprise-grade waveguide optics, differentiating from lifestyle-oriented competitors.
Smart sunglasses integrate microdisplays, sensors, and wireless connectivity into eyewear form factors, typically weighing under 50 grams while delivering heads-up notification overlays and camera capture. Their primary purpose spans hands-free information access, activity monitoring, and immersive media consumption without dedicated handheld devices. Bluetooth-enabled models currently occupy the largest volume tier due to lower cost barriers and smartphone pairing ubiquity. AR-capable headsets represent the fastest-expanding technology segment as waveguide and micro-LED advancements shrink optical engines. Prescription-integrated frames command premium positioning by addressing the myopic demographic that conventional smart glasses exclude.
FCC certification governs radio frequency emissions for US-bound devices, while the EU AI Act imposes risk-classification obligations on facial recognition and biometric processing features. CE marking under the MDR and RED frameworks controls market access for health-adjacent sensing functions and wireless transmission modules. Stakeholders must monitor evolving ophthalmic device classifications that could reclassify prescription smart sunglasses as regulated medical equipment in key jurisdictions.
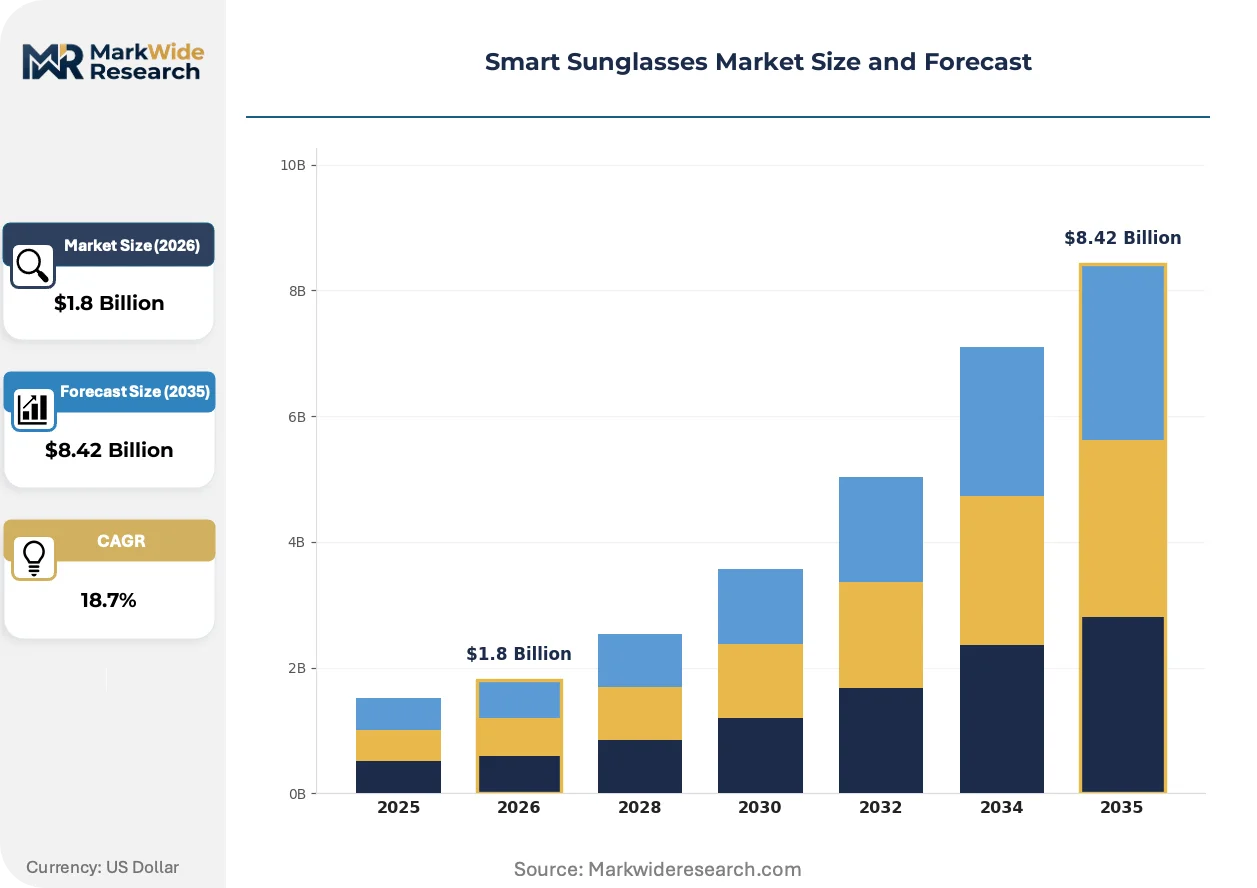
Market Dynamics
The migration of fitness tracking from wrist-worn devices to face-worn form factors is compressing development cycles and forcing sensor miniaturization at unprecedented scales. This hardware convergence is reshaping competitive positioning across consumer electronics and traditional eyewear supply chains simultaneously.
Growth Catalysts
- EU AI Act compliance pathways:Clear risk-classification frameworks for biometric processing are accelerating certification investments among European manufacturers, reducing time-to-market uncertainty for camera-enabled frames.
- Athlete and outdoor enthusiast adoption:Hands-free activity monitoring without wrist occlusion is driving replacement demand from Garmin and Apple Watch users seeking alternative form factors.
- Waveguide optics maturation:Micro-LED and diffractive waveguide advances are shrinking optical engines below 10cc volumes, enabling sub-50-gram AR-capable designs.
Market Restraints
- Lithium-polymer cell volatility:Energy density limitations in sub-2-gram batteries constrain all-day operation for compute-intensive features, forcing thermal throttling or reduced functionality.
- Optical engine supply concentration:Waveguide manufacturing capacity clusters in Taiwan and South Korea, creating single-source vulnerability for AR-capable models.
- FCC Part 15 certification friction:Radio frequency emission testing for multi-band wireless modules adds 4-6 month pre-market delays and six-figure compliance costs per SKU.
Strategic Opportunities
- Prescription-integrated white space:Myopic demographics excluded by conventional smart glasses represent an underserved cohort willing to pay premium positioning for corrective lens compatibility.
- Enterprise safety applications:OSHA-compliant heads-up displays for logistics and manufacturing workers offer volume contracts absent consumer seasonality.
- Direct-to-consumer channel maturation:Social commerce discovery and virtual try-on tools are collapsing traditional eyewear retail gatekeeper margins.
Industry Challenges
- Optomechanical engineering talent scarcity:The intersection of ophthalmic lens design and semiconductor packaging expertise remains concentrated among a handful of specialists in Rochester, New York and Jena, Germany.
- CE marking timeline under MDR:Health-adjacent sensing functions trigger medical device classification reviews, extending conformity assessment periods unpredictably.
- IP fragmentation across display patents:Waveguide, micro-LED, and laser scanning intellectual property is distributed across defense contractors, consumer electronics firms, and university licensing offices, complicating freedom-to-operate analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sunglasses Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable, Clip-on, Prescription, Headset Technology: Bluetooth, Optical, Voice-Controlled, AR End User: Consumers, Athletes, Professionals, Kids Application: Fitness Tracking, Navigation, Communication, Entertainment |
| Companies Covered | Meta, EssilorLuxottica, Vuzix, Amazon.com, Inc., RayNeo, Xreal, Snap Inc., Seiko Epson Corporation, Lumix Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sunglasses Market Evolving Landscape
Optical stack miniaturization and biometric sensor fusion are collapsing the boundary between corrective eyewear and wearable computing platforms. These convergences are forcing simultaneous innovation across materials science, wireless engineering, and regulatory strategy.
Micro-LED display technology is hybridizing illumination and imaging functions into single-chip architectures. Athletes and outdoor enthusiasts are adopting these systems for real-time performance overlays during training sessions. This convergence is compressing the traditional separation between notification displays and immersive AR experiences into unified optical engines.
The EU AI Act's risk-based classification system is imposing documentation obligations on facial recognition and biometric processing features. Manufacturers must maintain technical files and conformity assessments for high-risk AI functions embedded in camera-enabled frames. Prescription-integrated smart sunglasses face the most complex compliance pathways as they straddle consumer electronics and potential medical device classifications.
Social commerce discovery is displacing traditional optical retail as the primary conversion channel for smart sunglasses. Meta's platform-integrated shopping tools and virtual try-on capabilities are collapsing the consideration-to-purchase funnel. This behavioral shift is most visible in the United States, where Silicon Valley and Austin tech corridors concentrate early adopter density and developer ecosystem access.
Smart Sunglasses Market Segmentation
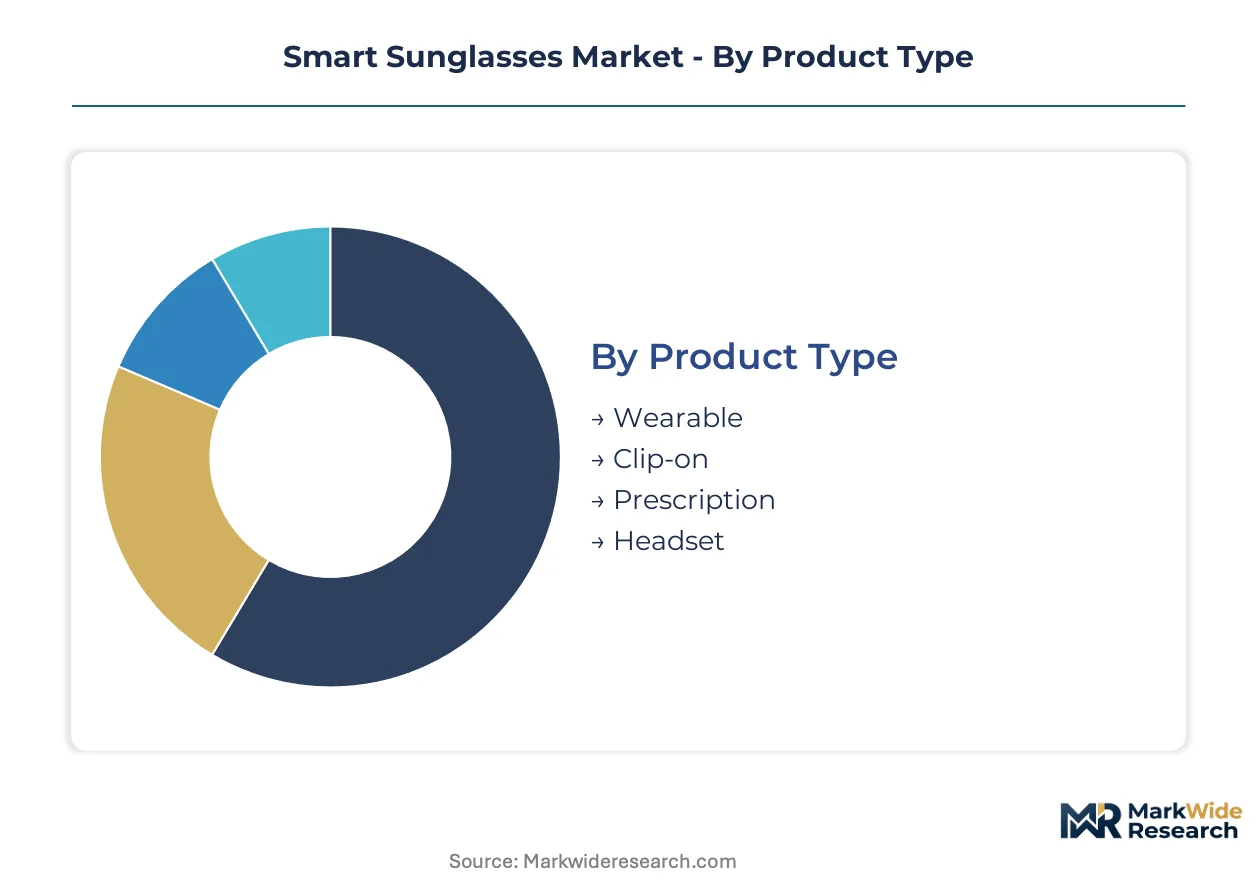
Smart sunglasses segmentation reveals divergent hardware refresh cycles across form factors and use cases. Product type and technology choices determine replacement frequency, while end-user demographics and application intensity shape feature bundling strategies.
Product Type:
Wearable frames turn over fastest at 18-24 month cycles, while prescription-integrated models extend to 36-48 months due to lens durability and fitting friction.
- Wearable:Integrated electronics within standard sunglass frames deliver hands-free notifications and audio. Demand clusters among Austin and Silicon Valley tech workers seeking smartphone companions without wrist occlusion. FCC Part 15 certification requirements add friction to US launches.
- Prescription:Corrective lens compatibility opens access to myopic demographics excluded by conventional smart glasses. European manufacturers face CE marking complexity under MDR frameworks that may trigger medical device classification. These units command premium positioning and slower replacement cycles.
- Clip-on:Modular attachments retrofit intelligence onto existing eyewear. Appeals to cost-conscious users and fashion-cyclical buyers unwilling to commit to dedicated frames.
- Headset:Over-ear or halo-mount designs prioritize compute capacity and battery volume over aesthetics. Enterprise logistics and manufacturing safety applications drive procurement.
Wearable frames dominate installed base. Prescription-integrated models are where expansion concentrates.
Technology:
Cost tier stratification separates connectivity-only units from compute-intensive optical systems, with price multiples spanning 10x between entry Bluetooth and full AR configurations.
- Bluetooth:Radio-only connectivity pairs with smartphones for audio streaming and basic notifications. Lowest cost tier enables mass-market penetration. CE marking under RED frameworks governs European market access.
- AR:Waveguide and micro-LED optical engines overlay contextual information in field-of-view. Athletes and outdoor enthusiasts in US tech corridors adopt these for real-time performance metrics. Supply concentrates in Taiwan and South Korea.
- Optical:Camera-enabled capture without display overlay. EU AI Act compliance obligations apply to facial recognition and biometric processing features.
- Voice-Controlled:Natural language interfaces reduce touch dependency. Privacy-conscious users favor local processing over cloud-dependent alternatives.
Bluetooth-enabled units dominate installed base. AR-capable systems are where expansion concentrates.
End User:
Application intensity varies sharply—athletes generate 3-4x daily usage hours versus casual consumers, driving divergent durability and battery specifications.
- Athletes:Hands-free activity monitoring without wrist occlusion drives replacement demand from Garmin and Apple Watch users. Fitness tracking functionality migration from wrist to face is compressing development cycles.
- Professionals:OSHA-compliant heads-up displays for logistics and manufacturing workers offer volume contracts absent consumer seasonality. Enterprise safety applications anchor this segment.
- Consumers:Lifestyle-oriented buyers prioritize aesthetics and social commerce discovery through platform-integrated shopping tools.
- Kids:Parental control features and durable construction address youth-specific use cases. Regulatory scrutiny on biometric data collection applies.
Consumer units dominate installed base. Athletes are where expansion concentrates.
Application:
Volume concentration favors single-function devices, while margin capture requires multi-application convergence that strains thermal and battery engineering.
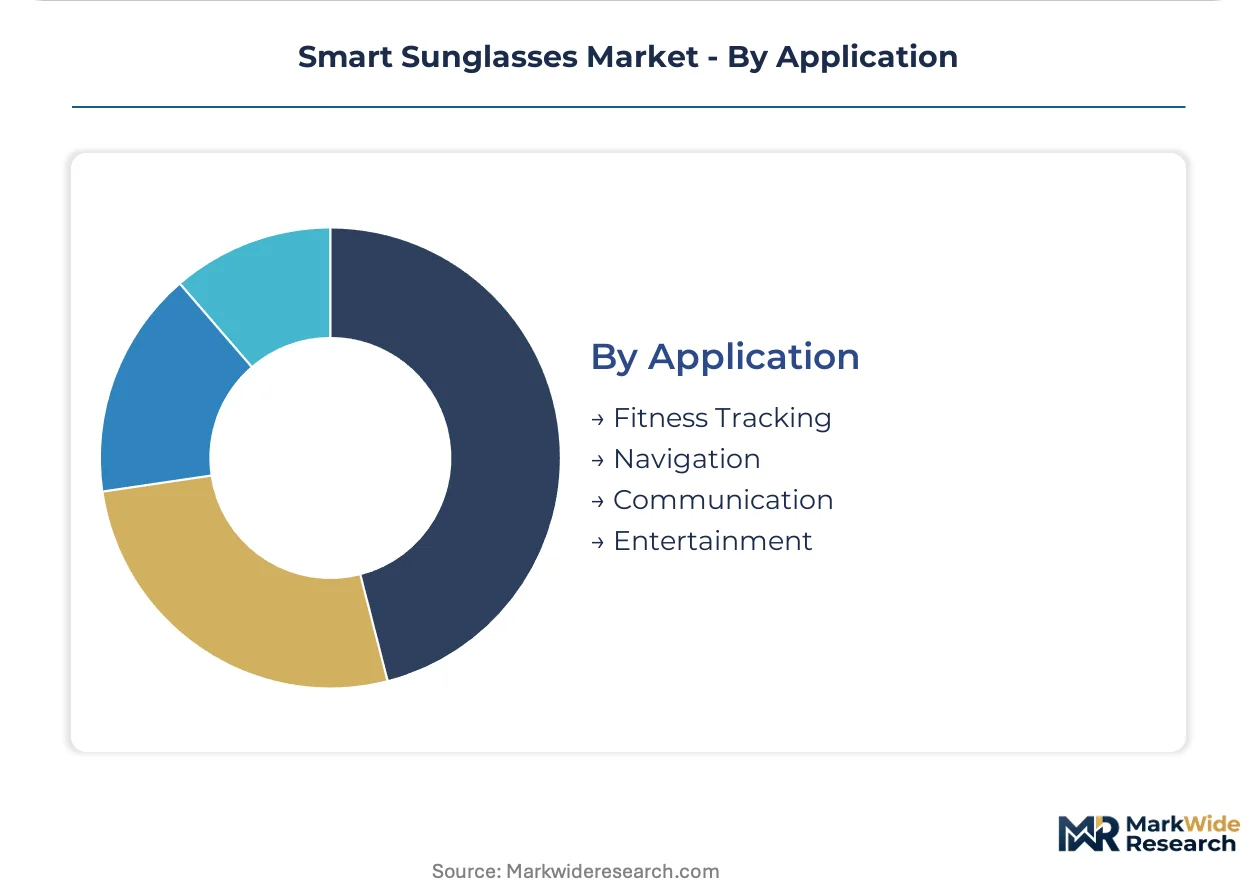
- Fitness Tracking:Real-time biometric monitoring and performance overlays. Athletes and outdoor enthusiasts represent the fastest-growing cohort as sensor miniaturization enables face-worn form factors.
- Communication:Audio streaming, voice calls, and notification triage. Bluetooth-enabled models serve this use case at lowest cost.
- Navigation:Heads-up directional cues and location-based information. AR-capable designs enable visual overlay without smartphone consultation.
- Entertainment:Immersive media consumption and gaming applications. Compute intensity forces thermal throttling in sub-50-gram designs.
Communication applications dominate installed base. Fitness tracking is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors trans-Pacific electronics throughput for North American smart sunglasses distribution. Rotterdam's Maasvlakte terminals handle EU-bound optical component flows from Asian waveguide foundries. Singapore's Tuas megaport mediates South-South trade in micro-LED substrates and sensor modules.
United States
Silicon Valley and Austin tech corridors concentrate developer ecosystems and early adopter density for camera-enabled frames. FCC Part 15 certification governs radio frequency emissions for multi-band wireless modules, adding 4-6 month pre-market delays. Meta leverages its Menlo Park platform infrastructure to drive social commerce discovery for lifestyle-oriented models.
Germany
Precision optics demand from Jena and Munich industrial clusters shapes component sourcing patterns for AR-capable designs. CE marking under MDR and RED frameworks controls market access for health-adjacent sensing functions. Baden-Württemberg's automotive supplier network is repurposing heads-up display expertise for consumer waveguide applications.
China
Shenzhen's electronics manufacturing ecosystem compresses Bluetooth-enabled frame production cycles to 12-16 weeks. MIIT radio type approval and GB standards compliance govern domestic market entry for wireless transmission modules. The Yangtze River Delta's micro-LED foundry capacity is scaling diffractive optical engine volumes for export-tier AR headsets.
South Korea
Seoul Capital Area conglomerates anchor waveguide manufacturing capacity for optical engine supply to global brands. MFDS medical device classification reviews apply to prescription-integrated frames with biometric sensors. Busan-Ulsan's display materials cluster is shipping micro-LED substrates to Taiwan-based optical system integrators.
Japan
Tokyo's consumer electronics retail density supports premium positioning for sub-50-gram AR designs. METI standards coordination and JIS certification frameworks structure domestic product safety requirements. Nagoya's precision machining suppliers are miniaturizing optomechanical assemblies for athlete-facing fitness tracking applications.
Smart Sunglasses Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with waveguide and sensor supply. The vendor base separates into three strata: social media-anchored ecosystem players, integrated eyewear-lens conglomerates, and narrow-focus optical technology developers. Consolidation pressure runs highest where prescription integration and AR capability converge. Competitive moves center on direct-to-consumer channel buildout and optical engine supply security through foundry partnerships.
Within the platform-integrated tier, Meta and Snap exemplify social commerce-driven discovery models. EssilorLuxottica anchors manufacturing scale through captive lens-frame production networks. Vuzix occupies a position representing enterprise-grade waveguide specialization distinct from lifestyle-oriented competitors.
| Leading Market Players |
|---|
| Meta |
| EssilorLuxottica |
| Vuzix |
| Amazon.com, Inc. |
| RayNeo |
| Xreal |
| Snap Inc. |
| Seiko Epson Corporation |
| Lumix Ltd. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Shenzhen's Bluetooth-enabled frame assembly plants is compressing contract manufacturer margins and forcing tiered pricing concessions to brands holding volume commitments. This utilization dynamic rewards buyers with scale while squeezing mid-tier producers lacking prescription integration or AR optical engine differentiation.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement contracts from direct-to-consumer retail, with three-tier pricing across premium AR-capable, standard Bluetooth-enabled, and economy clip-on attachment levels. Price differentiation hinges on CE marking grade under MDR frameworks and waveguide optical engine certification. Pricing pressure stems from lithium-polymer cell cost volatility constraining sub-2-gram battery sourcing. Enterprise safety buyers exhibit lowest price sensitivity; fashion-cyclical consumers demonstrate highest elasticity.
Supply Chain Analysis
Upstream feedstock for diffractive waveguides draws from Taiwan's optical foundries and South Korea's micro-LED substrate growers, with Shenzhen electronics manufacturers anchoring final assembly. Critical inputs span lithium-polymer cells, gallium nitride micro-LED wafers, and titanium alloy frame stock. Single-source vulnerability concentrates in Taiwan's waveguide etching capacity. Distribution runs through direct-to-consumer platform channels and enterprise safety equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward platform-integrated ecosystem players as social commerce discovery consolidates demand aggregation. This concentration fragments traditional eyewear retail gatekeeper influence.
For Market Incumbents: Build prescription-integration moats through captive lens laboratory networks and optometrist channel control. EssilorLuxottica's integrated manufacturing scale demonstrates defensive positioning against pure-play electronics entrants. CE marking investment under MDR frameworks creates compliance barriers for camera-enabled biometric frames. Capacity addition in Jena and Rochester optomechanical clusters secures scarce engineering talent pipelines. For New Entrants and Emerging Players: Pursue white-space capture in OSHA-compliant enterprise safety applications where volume contracts lack consumer seasonality. Athlete-facing fitness tracking with real-time biometric overlays offers the most penetrable segment given wrist-to-face migration momentum. Direct-to-consumer virtual try-on tools collapse traditional fitting friction and enable platform-native discovery. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AR-capable optical engine development as micro-LED and waveguide R&D cycles lengthen. Long-term viability favors enterprises with foundry partnerships securing Taiwan and South Korea waveguide supply. Acquisition targets should demonstrate vertical integration into prescription lens fabrication or captive optomechanical engineering talent. The signal to monitor is FCC Part 15 certification backlog duration as a demand-fulfillment constraint indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership for Waveguide Supply | Taiwan and South Korea optical engine concentration creates single-source vulnerability for AR-capable designs. |
| CE Marking Pathway Investment | MDR framework compliance for health-adjacent sensing functions extends market access timelines unpredictably. |
| Prescription Lens Laboratory Integration | Captive corrective lens production addresses myopic demographics excluded by conventional smart glasses. |
| Direct-to-Consumer Platform Launch | Meta's social commerce discovery tools collapse traditional eyewear retail gatekeeper margins. |
| Enterprise Safety Application Development | OSHA-compliant heads-up displays for logistics workers offer volume contracts absent consumer seasonality. |
Research Methodology
A standing panel of optical engineering directors, eyewear procurement leads at enterprise safety distributors, CE marking consultants, and platform commerce strategists provided ongoing calibration throughout the study. Primary interviews with waveguide foundry operations managers and lithium-polymer cell sourcing specialists combined with secondary validation against FCC equipment authorization databases, EU MDR notified body filings, and MIIT radio type approval records. Bottom-up unit economics modeling triangulated against top-down category spending estimates from social commerce platform disclosures.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include product type, technology tier, end-user application intensity, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to technology adoption S-cycles and replacement frequency assumptions. Forecast inputs incorporated waveguide manufacturing capacity expansion announcements and prescription lens laboratory throughput constraints.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices or semiconductor capital equipment cycles would shift the trajectory. Forecasts reflect documented assumptions regarding biometric sensor fusion adoption rates and EU AI Act enforcement intensity. Cross-checking against FCC equipment authorization filing velocity and CE marking timeline disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market
Eyewear
Polarized Sunglasses Market
Eyewear
Europe Eyewear Market
Eyewear
Asia-Pacific Eyewear Market
Eyewear
Sunglasses Pouch Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Eyeglass Market
Eyewear
Latin America Eyewear Market
Eyewear
Glasses Frame Market
Eyewear
Wooden Eyewear Market
Eyewear
Sunglasses Market
Eyewear
Goggles Market
Eyewear
Eyewear Market
Eyewear
Middle East Eyewear Market
Eyewear
North America Eyewear Market