
 China Anti-Blue Ray Myopia Lenses Market | 2026-2036
China Anti-Blue Ray Myopia Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
China Anti-Blue Ray Myopia Lenses Market Insights
Aftermarket lens coating and replacement services is reshaping margin distribution across the value chain. Mingyue Glasses Co., Ltd. leverages its domestic manufacturing footprint to control cost structures in polycarbonate substrates. Essilor anchors premium positioning through progressive lens designs with integrated blue-light filtration. Zeiss dominates high-index material segments where optical precision commands sustained price premiums.
Anti-blue ray myopia lenses combine dioptric correction with selective wavelength filtration, typically blocking 15-40% of high-energy visible light in the 380-500 nanometer range through vacuum-deposited multi-layer interference coatings or absorptive dye integration. Their primary commercial purpose centers on mitigating digital eye strain while slowing axial elongation in myopic progression. Single vision configurations occupy the volume base as school-age myopia rates climb, while progressive designs capture expanding margin pools among working professionals seeking multifocal convenience with screen protection. Polycarbonate leads material adoption due to impact resistance and inherent UV blocking, though Trivex gains traction where lighter weight and superior optical clarity justify higher unit costs.
SAMR enforces labeling standards for blue-light blocking claims, while NMPA's ophthalmic device registration requirements shape product approval timelines and clinical validation burdens. GB standards for optical lenses establish minimum transmission specifications that manufacturers must meet for domestic market access. Stakeholders should monitor regulatory tightening around unsubstantiated health claims, as enforcement actions could reshape competitive positioning between certified incumbents and uncertified low-cost entrants.
Market Dynamics
NMPA's tightened ophthalmic device registration requirements are compressing product approval timelines and forcing manufacturers to front-load clinical validation costs before market entry.
Growth Catalysts
- Screen-time intensification in educational settings:Chinese students now average 4+ hours of daily digital device exposure, creating sustained replacement demand for prescription lenses with integrated blue-light filtration.
- SAMR labeling enforcement:Mandatory disclosure standards for blue-light blocking claims are filtering out uncertified competitors and consolidating purchasing toward verified products.
- Polycarbonate substrate advances:Vacuum-deposited multi-layer interference coatings now achieve 35-40% HEV blocking without the yellow tint that previously deterred adult adopters.
Market Restraints
- High-index monomer supply concentration:60% of thiourethane raw material originates from three Japanese chemical conglomerates, exposing margin compression risks during feedstock volatility.
- Clinical validation burden:NMPA's updated standards require 12-18 month axial elongation studies for myopia progression claims, extending payback periods for R&D investments.
- Contact lens substitution:Daily disposable silicone hydrogel lenses with surface blue-light inhibitors are capturing 15-20 year-old myopes seeking frame-free alternatives.
Strategic Opportunities
- Tier-2 and tier-3 city expansion:Parental spending on myopia control in Chengdu, Xi'an, and Changsha is rising 3x faster than tier-1 saturation rates.
- Progressive lens convergence:Integrated free-form surfacing with variable blue-light filtration zones addresses working professionals aged 35-50 seeking multifocal convenience.
- Aftermarket coating services:Independent optical retailers are unbundling prescription fulfillment from lens treatment, creating service revenue pools separate from frame-and-lens bundles.
Industry Challenges
- Coating technician scarcity:Vacuum deposition specialists command 40% wage premiums in Dongguan and Suzhou manufacturing clusters, constraining capacity scaling.
- Legacy ERP integration:Mid-size labs struggle to connect free-form design software with NMPA-mandated traceability systems, delaying batch release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Anti-Blue Ray Myopia Lenses Market |
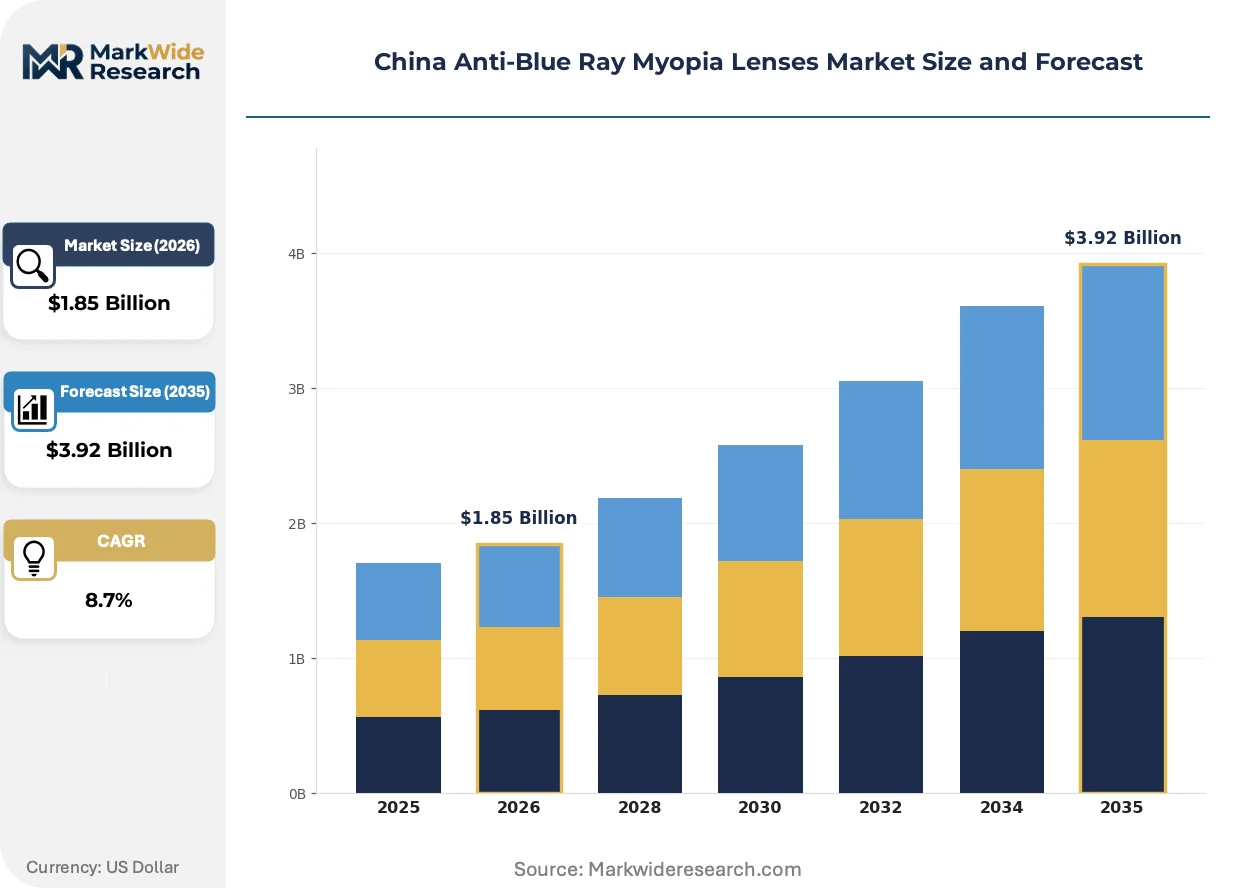
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Bifocal, Progressive, Photochromic End User: Children, Students, Working Professionals, Senior Citizens Material: Polycarbonate, Trivex, CR-39, Glass Distribution Channel: Optical Stores, Online Retail, Hospital Pharmacies, Supermarkets |
| Companies Covered | Mingyue Glasses Co., Ltd., Shanghai Conant Optics Co., Ltd., Jiangsu Hongchen Optical Co., Ltd., Jiangsu Green Stone Optical Co., Ltd., Hoya Group, Essilor, Zeiss, Rodenstock GmbH, Nikon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Anti-Blue Ray Myopia Lenses Market Trends and Innovations
Multi-layer optical engineering and regulatory disclosure mandates are compressing the gap between premium performance claims and verifiable product specifications.
Nanoparticle-embedded absorptive dyes are rendering obsolete traditional vacuum-deposited interference stacks for mid-index prescriptions. Tier-2 optical labs in Wenzhou and Danyang are adopting these materials to bypass coating equipment capital requirements. The shift is compressing price differentiation between coating-intensive and substrate-integrated blue-light blocking architectures.
GB standards for optical lens transmission specifications now mandate third-party verification of HEV-blocking claims above 20% filtration. SAMR enforcement actions against unsubstantiated myopia control marketing are accelerating manufacturer migration toward NMPA-registered medical device classifications. Domestic brands with pre-existing registration portfolios are capturing shelf space from import-dependent competitors facing extended approval queues.
Parental purchasing for school-age children is rotating from hospital-affiliated optical centers toward chain retail with transparent certification displays. Aier Eye Hospital's retail spinoffs and local JINS outlets are displacing traditional white-coat dispensing models in Shanghai and Shenzhen. The behavioral shift rewards brands with visible GB compliance markings over clinical endorsement dependency.
China Anti-Blue Ray Myopia Lenses Market Segmentation
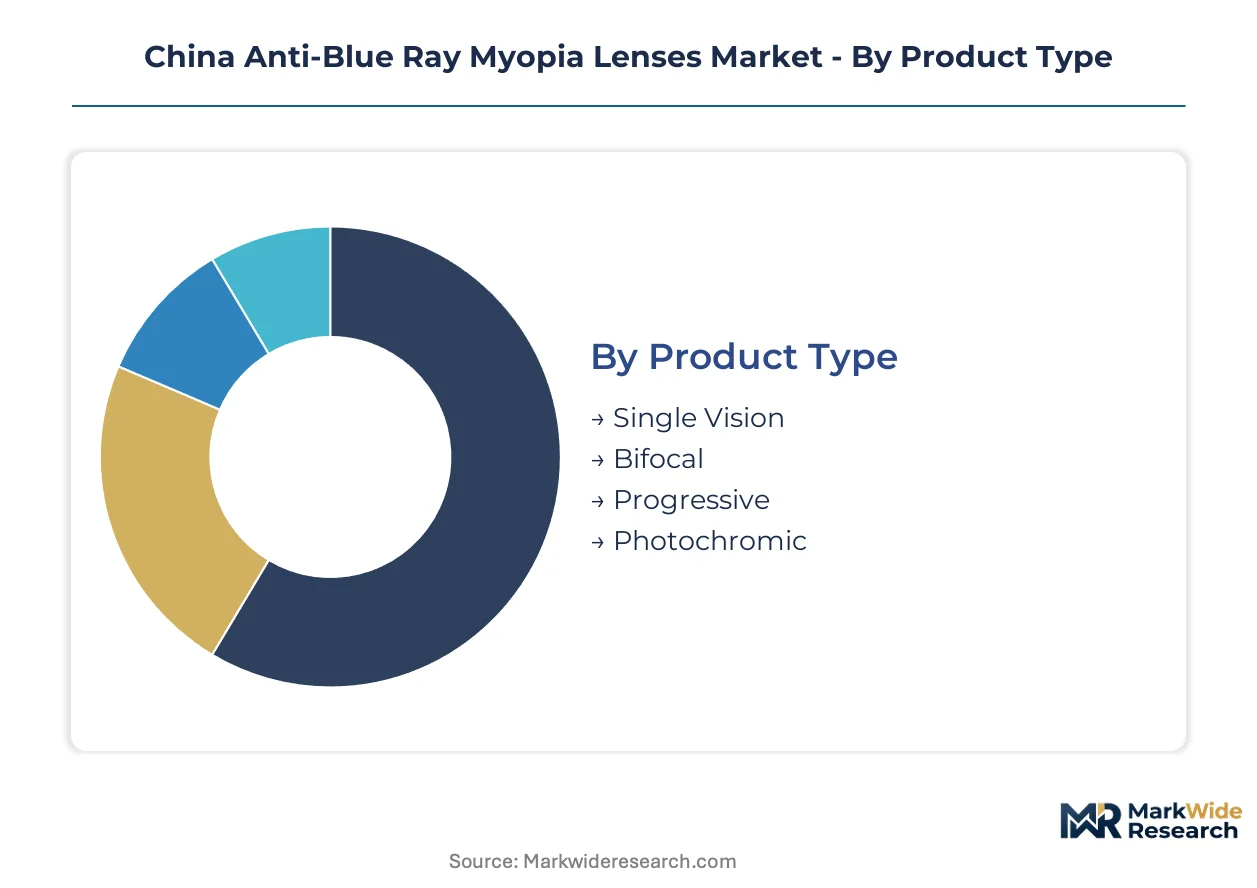
Segmentation in China's anti-blue ray myopia lens market reveals distinct procurement patterns across age cohorts and channel preferences. Product configuration, substrate selection, and distribution access collectively determine margin capture and brand positioning for domestic and import manufacturers.
Product Type:
Use-case spectrum spans simple dioptric correction through adaptive visual performance for variable lighting environments.
- Single Vision:Uniform optical power across the entire lens surface addresses school-age myopia with straightforward distance or near correction. Chinese students in Shanghai and Beijing drive replacement cycles as screen-time exposure intensifies and NMPA registration requirements filter uncertified competitors from hospital-affiliated dispensing.
- Progressive:Gradient power distribution eliminates visible segment lines while integrating variable blue-light filtration zones for multifocal convenience. Working professionals aged 35-50 in Shenzhen and Guangzhou seek frame-mounted alternatives to contact lens substitution, paying premiums for free-form surfacing precision.
- Bifocal:Two distinct optical zones separated by a visible segment line serve cost-conscious presbyopic myopes in tier-3 cities where progressive fitting expertise remains scarce.
- Photochromic:Light-responsive silver halide or naphthopyran molecules embedded in substrate darken under UV exposure, appealing to outdoor workers in high-altitude western provinces with intense solar irradiance.
Established volume favors Single Vision; emerging adoption favors Progressive.
End User:
Customer type segmentation aligns with life-stage visual demands and parental spending authorization patterns.
- Students:The cohort averaging 4+ hours daily digital device exposure generates sustained replacement demand for prescription lenses with integrated HEV filtration. School-mandated vision screening programs in Jiangsu and Zhejiang accelerate detection and parental procurement urgency.
- Children:Pre-teen myopes require impact-resistant substrates and frequent prescription updates as axial elongation progresses. Aier Eye Hospital retail spinoffs capture this segment through visible GB compliance markings that displace traditional white-coat dispensing trust.
- Working Professionals:Multifocal needs converge with occupational screen exposure, driving progressive lens convergence and premium coating acceptance in Chengdu and Xi'an where tier-2 purchasing power expands.
- Senior Citizens:Fixed-income constraints and established wearing habits sustain demand for conventional bifocal configurations in price-sensitive interior provinces.
Students command the steepest expansion trajectory; Children show the strongest parental spending multiplier.
Material:
Substrate economics balance optical precision, impact resistance, and weight against manufacturing scale and raw material supply security.
- Polycarbonate:Thermoplastic polymer with inherent UV blocking and shatter resistance dominates volume production. Vacuum-deposited multi-layer interference coatings achieve 35-40% HEV blocking without yellow tint, supporting Mingyue Glasses Co. cost control in Dongguan manufacturing clusters.
- Trivex:Urethane-based pre-polymer offers superior optical clarity and lighter weight for rimless frame mounting. Premium positioning justifies higher unit costs in Zeiss-dominated high-index segments where optical precision commands sustained price premiums.
- CR-39:Allyl diglycol carbonate thermoset resin retains base-curve flexibility for traditional surfacing equipment in legacy Wenzhou optical labs.
- Glass:Mineral substrate persists in specialty high-power prescriptions requiring exceptional scratch resistance and thermal stability.
Polycarbonate anchors current volume; Trivex gains share fastest among premium repositioning strategies.
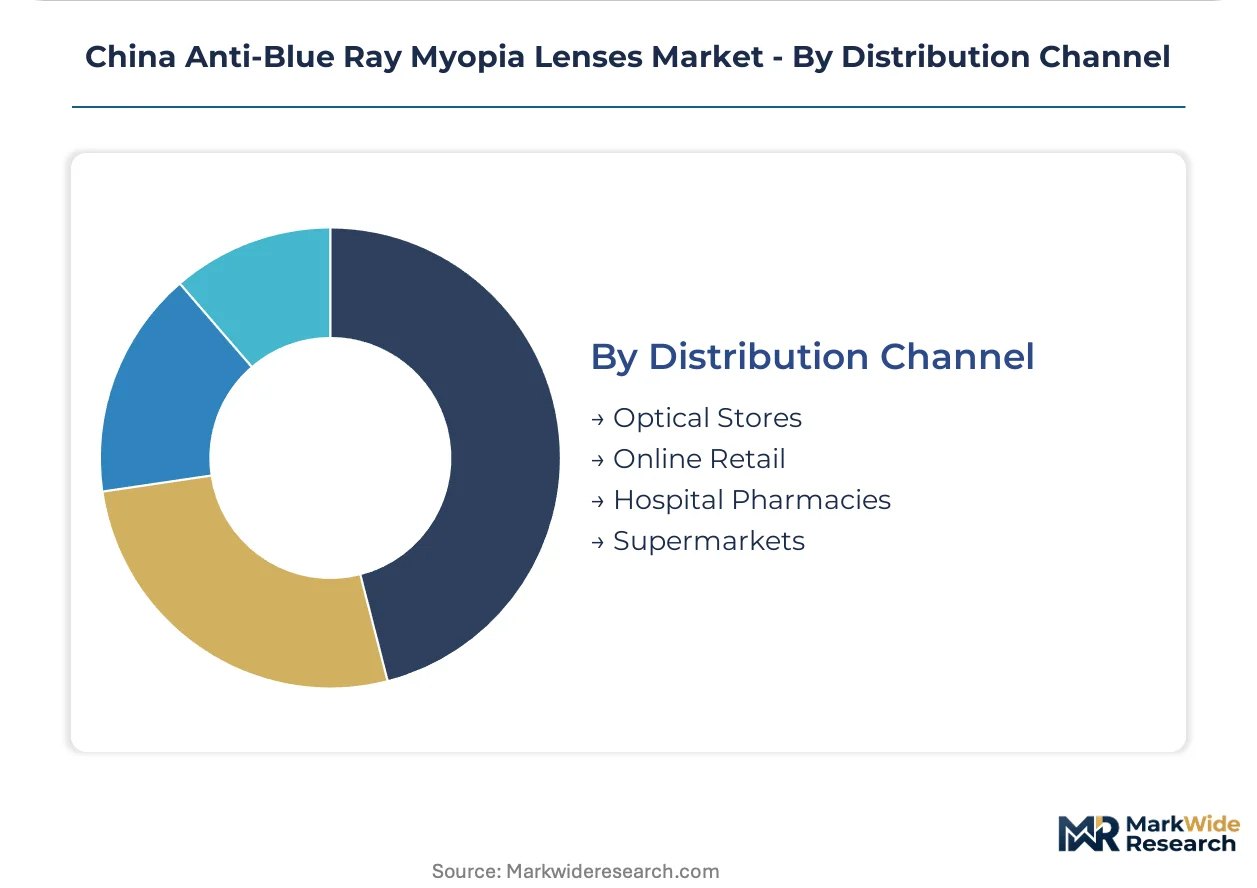
Distribution Channel:
Channel configuration determines certification visibility, fitting service bundling, and margin distribution between manufacturers and retail intermediaries.
- Optical Stores:Independent and chain retailers unbundle prescription fulfillment from lens treatment, creating aftermarket coating service revenue. JINS outlets and local chains displace hospital-affiliated models through transparent GB compliance displays in tier-1 urban cores.
- Online Retail:Direct-to-consumer platforms capture price-sensitive replacements with standardized single-vision prescriptions, though progressive fitting complexity limits category penetration.
- Hospital Pharmacies:Clinical endorsement dependency erodes as parental purchasing rotates toward certification-transparent retail, though high-myopia pediatric cases retain institutional referral pathways.
- Supermarkets:Mass merchandisers stock reading-glass equivalents with basic blue-light tinting for impulse purchase in hypermarket optical kiosks.
Optical Stores defend established volume; Online Retail captures the fastest-growing transaction frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating equipment and substrate manufacturing concentrate in eastern coastal provinces where optical industrial clusters have matured over three decades. Provincial governments in Jiangsu and Zhejiang channel subsidies toward vacuum deposition technology upgrades. This supply-side geography shapes how NMPA registration requirements propagate through domestic value chains.
Shanghai
Hospital-affiliated optical centers in Shanghai command premium positioning through clinical endorsement networks. SAMR enforcement teams maintain headquarters-level inspection capacity here, accelerating compliance verification for brands seeking nationwide distribution. Pudong and Minhang districts host Essilor and Zeiss regional operations serving the Yangtze River Delta.
Guangdong
Dongguan and Shenzhen manufacturing clusters produce polycarbonate substrates for volume single-vision prescriptions. Provincial MIIT offices coordinate with NMPA on ophthalmic device registration pilot programs. Local optical retailers in Guangzhou displace traditional hospital dispensing through transparent GB compliance displays.
Jiangsu
Danyang anchors domestic lens fabrication with legacy surfacing equipment and emerging nanoparticle dye integration. Municipal authorities in Zhenjiang administer technology transformation subsidies for coating line automation. Mingyue Glasses Co., Ltd. leverages this infrastructure for cost-controlled polycarbonate production.
Sichuan
Chengdu's tier-2 purchasing power for myopia control rises three times faster than tier-1 saturation rates. Provincial education bureaus mandate school vision screening programs accelerating detection and parental procurement urgency. Local chain retailers capture displacement from hospital-affiliated models through certification-transparent positioning.
Zhejiang
Wenzhou optical labs adopt nanoparticle-embedded absorptive dyes to bypass coating equipment capital requirements. Taizhou and Ningbo municipal governments fund free-form surfacing technology transfers from German equipment suppliers. Jiangsu Hongchen Optical Co., Ltd. and Jiangsu Green Stone Optical Co., Ltd. source substrate materials from this supplier network.
China Anti-Blue Ray Myopia Lenses Market Competitive Landscape
Domestic volume manufacturers and multinational precision specialists split the market along certification-tier lines. NMPA registration portfolios separate verified incumbents from uncertified low-cost entrants facing SAMR enforcement exposure. Three archetypes dominate: state-supported domestic champions, import-dependent premium brands, and independent coating service providers. Competitive moves concentrate on M&A for registration portfolio accumulation and geographic expansion into tier-2 cities where parental spending accelerates.
Among domestic fabricators, Mingyue Glasses Co., Ltd. exemplifies the state-supported volume archetype through its Dongguan manufacturing footprint. Shanghai Conant Optics Co., Ltd. occupies a position within the precision coating tier serving hospital-affiliated dispensing networks. These Chinese Co., Ltd. structures anchor the mid-market against multinational AG and GmbH entities whose extended NMPA approval queues create shelf space vulnerability.
| Leading Market Players |
|---|
| Mingyue Glasses Co., Ltd. |
| Shanghai Conant Optics Co., Ltd. |
| Jiangsu Hongchen Optical Co., Ltd. |
| Jiangsu Green Stone Optical Co., Ltd. |
| Hoya Group |
| Essilor |
| Zeiss |
| Rodenstock GmbH |
| Nikon |
| Others |
Pricing and Supply Chain Analysis
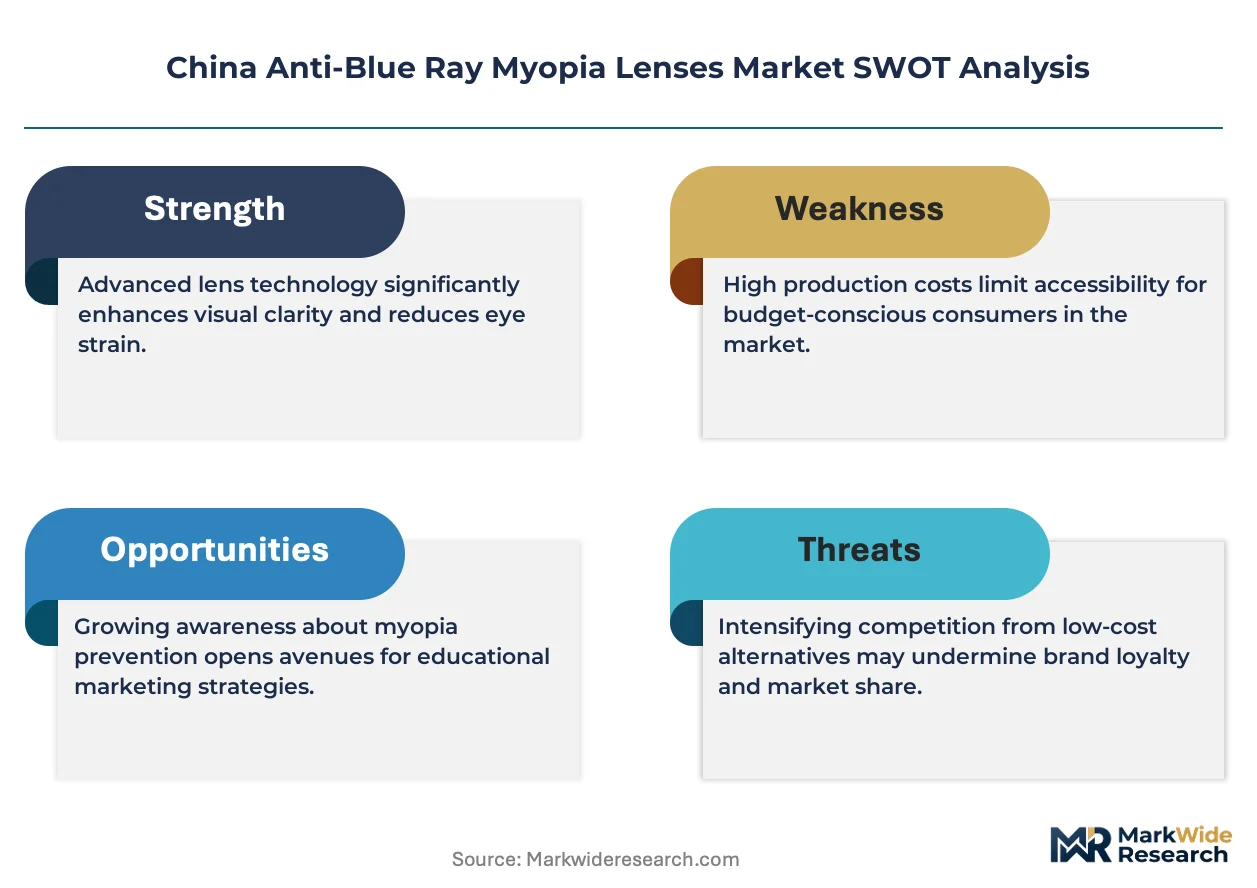
Thiourethane monomer concentration among three Japanese chemical conglomerates determines both the premium-to-economy pricing spread and the geographic shape of upstream sourcing. This single-source dependency forces polycarbonate substrate manufacturers to absorb feedstock volatility while tier-1 optical retailers capture margin through certification-transparent positioning.
Pricing Analysis
NMPA ophthalmic device registration dictates the pricing tier structure across the China market. Premium-mid-economy pricing differentiation separates NMPA-registered medical device classifications from uncertified low-cost entrants facing SAMR enforcement exposure. Brand premium and certification level command 20-35% unit price elevation in hospital-affiliated dispensing networks. Cost compression in economy tiers intensifies as Wenzhou optical labs adopt nanoparticle-embedded dyes to bypass coating equipment capital requirements. Parental buyers for school-age children show lowest price sensitivity, while senior citizens in interior provinces exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between Japan and China dominates raw material procurement risk for high-index substrate production. Thiourethane monomer, polycarbonate resin, and vacuum deposition equipment concentrate supply origins across Japan, South Korea, and domestic Jiangsu manufacturing clusters. Single-source vulnerability in thiourethane feedstock exposes margin compression during petrochemical volatility. Distribution runs through Dongguan and Shenzhen manufacturing nodes before radiating via optical store chains and hospital-affiliated retail networks to tier-1 and tier-2 urban endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China anti-blue ray myopia lens market sits in early-cycle expansion as school vision screening programs accelerate detection rates and parental procurement urgency. NMPA registration requirements filter uncertified competitors, consolidating shelf space toward verified incumbents.
For Market Incumbents: Build certification moats through NMPA medical device portfolio accumulation and GB standards compliance marking visibility. Deepen backward integration into polycarbonate substrate production to control cost structures against Japanese thiourethane feedstock volatility. Expand capacity in Chengdu and Xi'an to capture tier-2 parental spending growth running three times faster than tier-1 saturation rates. For New Entrants and Emerging Players: Pursue aftermarket coating service unbundling as independent optical retailers separate prescription fulfillment from lens treatment. Target tier-3 city bifocal segments where progressive fitting expertise remains scarce and price sensitivity sustains demand for visible-line configurations. Leverage nanoparticle-embedded absorptive dye adoption to bypass vacuum deposition equipment capital barriers in Wenzhou and Danyang lab networks. For Investors and Strategic Acquirers: NMPA registration queue backlogs reshape the acquisition landscape toward domestic brands with pre-existing medical device portfolios. Long-term viability centers on 5-10 year regulatory compliance durability rather than short-term price competition. Watch SAMR enforcement action frequency as the signal indicating competitive consolidation velocity between certified incumbents and uncertified entrants.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Medical Device Registration Accumulation | Pre-existing registration portfolios capture shelf space from import-dependent competitors facing extended approval queues. |
| Backward Integration into Polycarbonate Substrates | Dongguan manufacturing footprint control insulates Mingyue Glasses Co. from Japanese thiourethane feedstock volatility. |
| Tier-2 City Distribution Expansion | Chengdu and Xi'an parental spending on myopia control rises three times faster than tier-1 saturation rates. |
| Aftermarket Coating Service Unbundling | Independent optical retailers create service revenue pools separate from frame-and-lens bundles through lens treatment separation. |
| Nanoparticle Dye Technology Adoption | Wenzhou labs bypass vacuum deposition capital requirements while compressing price differentiation between coating architectures. |
Research Methodology
The analysis maps single vision, progressive, bifocal, and photochromic lens configurations, each validated through optical lab technicians, hospital dispensing network managers, and independent retail chain procurement heads. Primary interviews with coating equipment specialists, NMPA regulatory consultants, and parental buyer panels combined with secondary validation from SAMR enforcement disclosures, GB standards documentation, and provincial MIIT subsidy records. Bottom-up prescription volume modeling and top-down parental spending elasticity triangulation anchored market sizing.
Assumptions held NMPA registration requirement tightening and school vision screening program expansion as fixed conditions while varying thiourethane feedstock cost trajectories and contact lens substitution rates. Segmentation dimensions modeled include product configuration, substrate material tier, end-user age cohort, and distribution channel type across the projection horizon. CAGRs derived from prescription replacement cycle frequency, screen-time exposure trend extrapolation, and tier-2 city purchasing power elasticity coefficients.
Sensitivities concentrate around thiourethane supply disruption, SAMR enforcement intensity variation, and contact lens blue-light inhibitor technology advancement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Luxury Sunglass Market
Eyewear
Ultralight Eyeglass Frames Market
Eyewear
Plano Sunglasses Market
Eyewear
Middle East Eyewear Market
Eyewear
Smart Eyewear Market
Eyewear
Sunglasses Market
Eyewear
Asia-Pacific Eyewear Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Wooden Eyewear Market
Eyewear
Glasses Frame Market
Eyewear
Anti-Fog Lens Market
Eyewear
North America Eyewear Market
Eyewear
Luxury Eyewear Market
Eyewear
Smart Sunglasses Market
Eyewear
Eyewear Market
Eyewear
Reading Glasses Market