
 Polarized Sunglasses Market | 2026-2036
Polarized Sunglasses Market Size, Share, and Industry Trends Forecast 2026-2036
Polarized Sunglasses Market Analysis
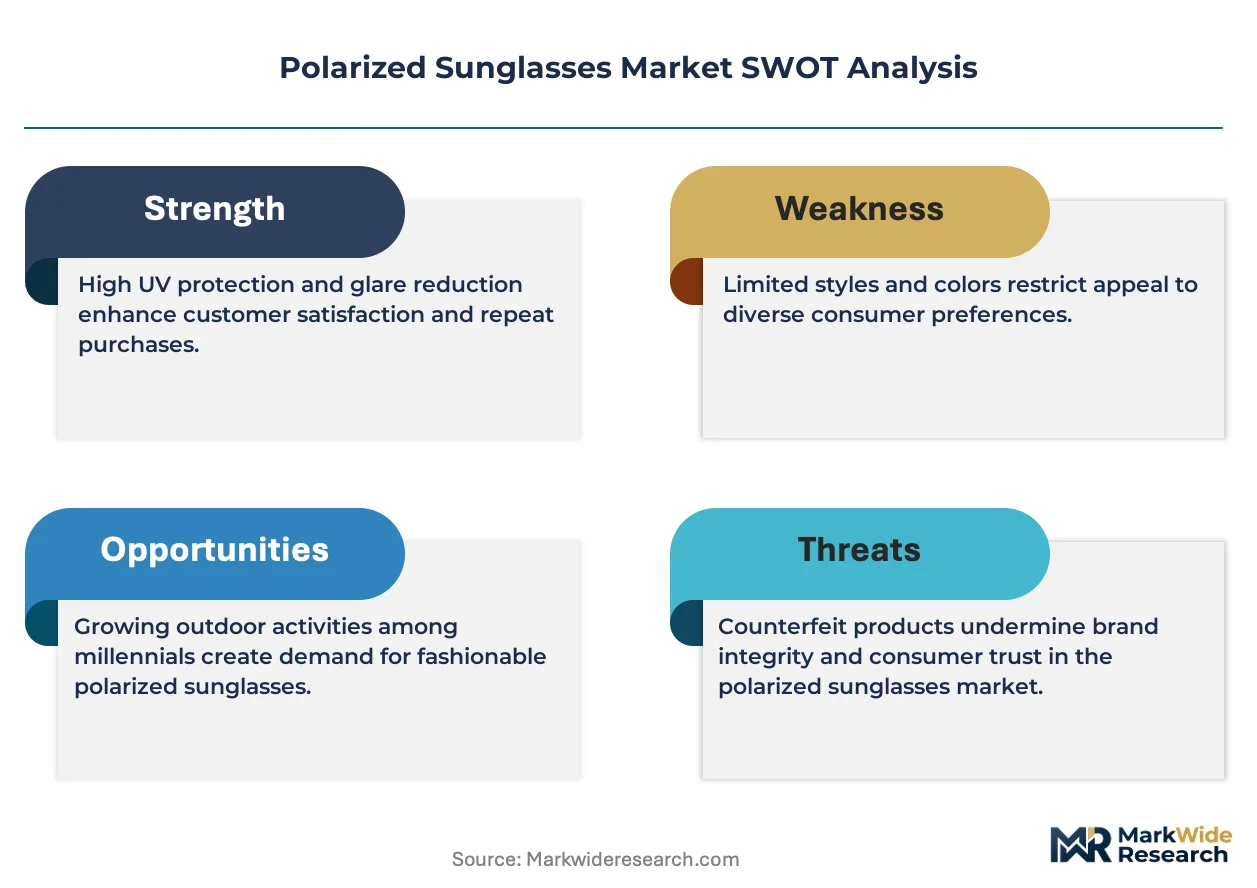
Multi-source lens coating procurement is hardening as brands reduce dependence on single Asian chemical suppliers. EssilorLuxottica S.A. leverages vertical integration across design, lens casting, and retail channels to control cost structures. Maui Jim, Inc. differentiates through proprietary polarization film technology and premium positioning in fishing and boating segments. Safilo Group S.p.A. sustains European manufacturing scale while navigating licensing partnerships with luxury fashion houses.
Polarized sunglasses incorporate vertically oriented polarizing filters, typically laminated between lens substrates or applied as surface coatings, that block horizontally polarized glare from reflective surfaces such as water, asphalt, and snow while transmitting vertically oriented light. The polarization efficiency, measured by glare reduction percentage and optical clarity standards, determines performance in high-luminance environments including marine navigation, alpine sports, and professional driving. Sports-oriented configurations command premium positioning due to ANSI Z87.1 impact requirements and hydrophobic coating durability. Polycarbonate lens material dominates volume production given its shatter resistance and injection molding compatibility, though glass substrates retain share in premium optical clarity segments. Everyday Wear designs anchor mass-market distribution through pharmacy chains and fast-fashion retail, while Wraparound styles capture growth in cycling and running applications where peripheral glare protection matters.
The U.S. Food and Drug Administration classifies non-prescription sunglasses as Class I medical devices, requiring impact resistance testing and UV labeling accuracy that shapes product liability exposure and import documentation. The European Union's REACH regulation and RoHS directive restrict heavy metals and certain phthalates in frame materials and lens coatings, forcing reformulation of traditional production chemistries. California's Proposition 65 adds state-level disclosure requirements for bisphenol-A and other substances in polycarbonate frames sold into the U.S. West Coast. Stakeholders must monitor evolving chemical restriction lists across multiple jurisdictions while building compliance documentation into supplier qualification processes.
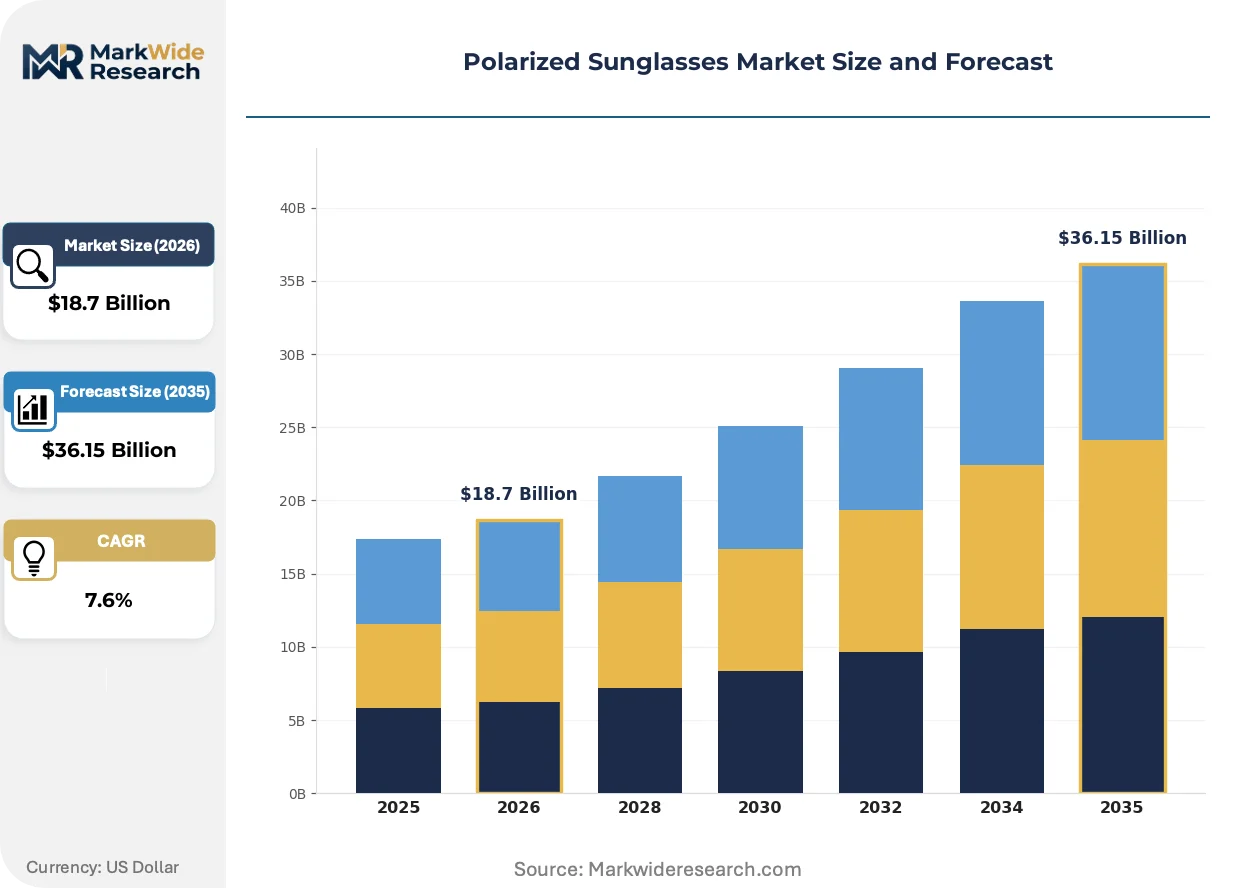
Market Dynamics
Adventure travel spending is concentrating demand for high-performance eyewear, forcing manufacturers to reconcile polarizing film supply constraints with rapid SKU proliferation across fishing, alpine, and motorsport verticals.
Growth Catalysts
- EU F-Gas Regulation:The regulation's phase-down of hydrofluorocarbons is accelerating reformulation of anti-reflective lens coatings toward fluorine-free chemistries, opening procurement relationships with European specialty chemical firms.
- Marine navigation segment:Professional charter operators and competitive sailing teams are mandating ANSI Z87.1-rated polarized eyewear as standard safety equipment, institutionalizing replacement cycles.
- Belluno manufacturing cluster:Italy's concentrated eyewear production infrastructure enables rapid prototype-to-production scaling for brands launching limited-edition collaborations.
Market Restraints
- TAC film supply concentration:Triacetate cellulose polarizing film production concentrates among Japanese and Korean chemical specialists, creating single-source vulnerability for mid-tier brands.
- Polycarbonate resin volatility:Bisphenol-A feedstock costs fluctuate with crude oil derivatives, compressing margin buffers on volume-priced Everyday Wear SKUs.
- California Proposition 65:The state's disclosure requirements for BPA in polycarbonate frames add compliance overhead for West Coast distribution without corresponding price recovery mechanisms.
Strategic Opportunities
- India outdoor retail expansion:Organized sporting goods chains in Mumbai and Bangalore are building dedicated eyewear sections, creating first-mover positioning for polarized lens specialists.
- Photochromic-polarized convergence:Hybrid lenses combining light-adaptive technology with glare reduction are capturing cycling commuters who transition between shaded urban corridors and exposed roadways.
- Eco-design incentives:The EU Green Deal's product environmental footprint requirements favor bio-based frame materials and recyclable lens substrates, rewarding early certification investments.
Industry Challenges
- Optical metrology talent scarcity:Polarization efficiency testing and wavefront aberration analysis require specialized technicians that competing semiconductor and medical device sectors also target.
- REACH compliance documentation:The European Chemicals Agency's substance of very high concern list updates force continuous reformulation tracking across multi-tier supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polarized Sunglasses Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports, Fashion, Everyday Wear, Safety Lens Material: Polycarbonate, Glass, Trivex, CR-39 Design Style: Classic, Aviator, Wraparound, Cat Eye Customer Type: Outdoor Enthusiasts, Casual Users, Athletes, Professionals |
| Companies Covered | EssilorLuxottica S.A., Safilo Group S.p.A., Maui Jim, Inc., Oakley, Inc., Kering S.A., Marcolin Group S.p.A., De Rigo Vision S.p.A., Costa Del Mar, Inc., Warby Parker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polarized Sunglasses Market Emerging Trajectories
Active shutter and electrochromic technologies are compressing the functional gap between fixed-tint polarized lenses and adaptive eyewear, reshaping R&D allocation across the sector.
Gradient-index polarized lenses are unifying distance correction with glare suppression in single substrates. Prescription sunwear providers are adopting these at 18-month refresh cycles. The technology is unifying previously separate optical lab workflows, reducing lens finishing steps by 40 percent.
REACH authorization requirements for chromium trioxide in mirror coatings are eliminating hexavalent chrome processes from EU-serving production lines. Italian frame manufacturers are migrating to physical vapor deposition alternatives. Premium mirror-finish SKUs bear 12-15 percent cost premiums as supply chains absorb qualification delays.
Direct-to-consumer prescription polarized platforms are displacing traditional optical retail intermediaries. Millennial buyers in Germany and France are completing full prescription sunwear transactions online, using smartphone pupillary distance tools. This channel rotation is most visible in cycling and running segments where fit familiarity reduces in-store trial dependency.
Polarized Sunglasses Market Segmentation
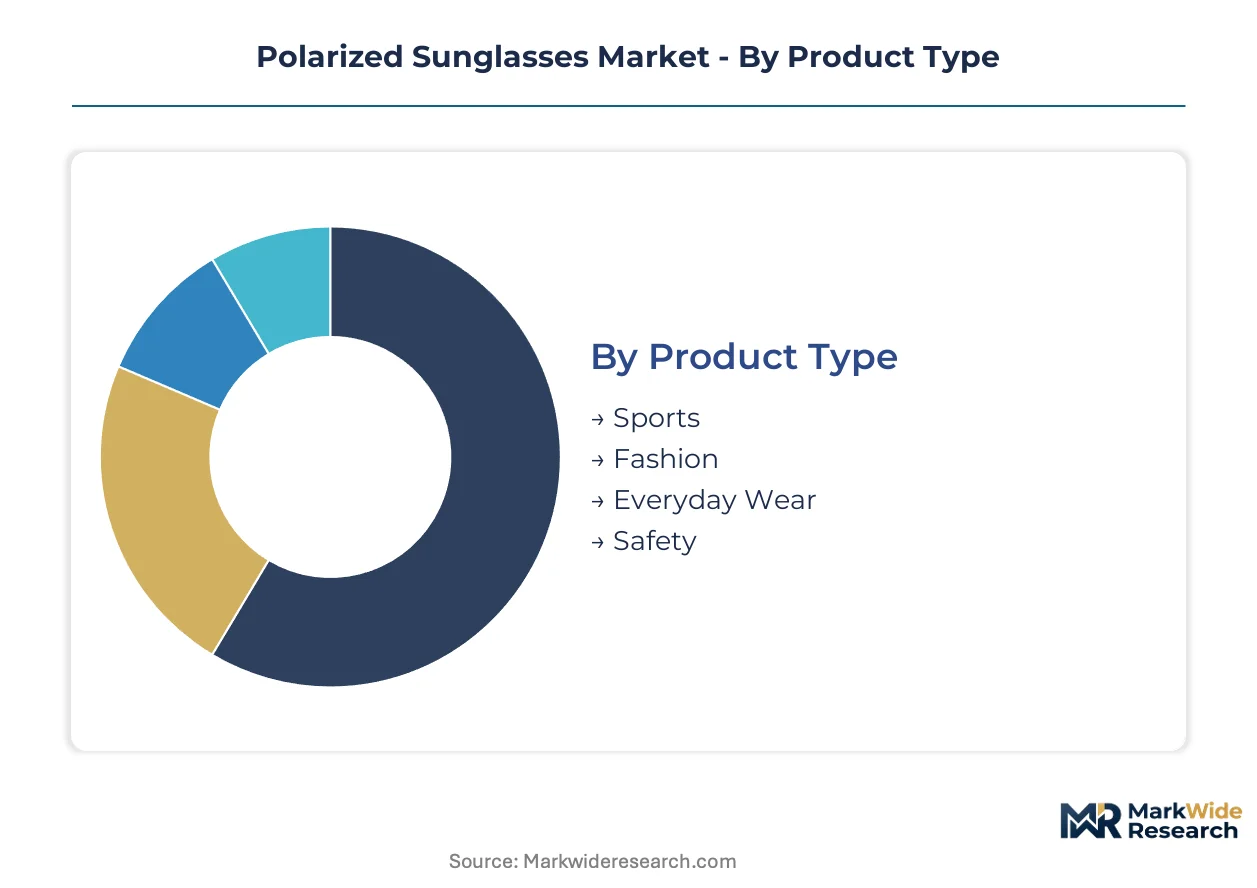
Polarized sunglasses manufacturers configure production lines around performance specifications that diverge sharply between ANSI-rated safety applications and fashion-forward SKUs. Segmentation discipline determines coating chemistry selection, polarization film lamination processes, and distribution channel alignment across divergent margin profiles.
Product Type:
Customization intensity spans from mass-market Everyday Wear with standardized polarizing film specifications to Sports configurations demanding impact certification and hydrophobic durability testing.
- Sports:ANSI Z87.1 impact resistance and hydrophobic coating durability are mandatory specifications. Demand concentrates among competitive sailing teams and alpine guides in Italy's Belluno cluster where rapid prototyping supports limited-edition athlete collaborations.
- Fashion:Mirror coating aesthetics and frame design flexibility dominate technical requirements. Italian manufacturers leverage the Belluno infrastructure to execute luxury house licensing partnerships with shortened development cycles.
- Everyday Wear:Volume production targets pharmacy chains and fast-fashion retail with polycarbonate lens standardization.
- Safety:Professional marine navigation and industrial applications mandate documented polarization efficiency and UV labeling accuracy per FDA Class I medical device requirements.
Most installed capacity flows through Everyday Wear. Expansion is steepest in Sports.
Lens Material:
Cost tier stratification separates injection-molded volume substrates from cast-glass premium positioning with distinct capital equipment and technician skill requirements.
- Polycarbonate:Shatter resistance and injection molding compatibility enable high-volume production. Demand concentrates in mass-market distribution through US pharmacy chains where Bisphenol-A feedstock cost volatility compresses margin buffers on price-sensitive SKUs.
- Glass:Optical clarity superiority retains premium positioning despite weight penalties. German and Italian optical labs specify cast-glass substrates for prescription sunwear with gradient-index polarization convergence.
- Trivex:Lightweight impact resistance targets cycling and running applications where peripheral vision protection matters.
- CR-39:Scratch resistance and optical precision sustain share in fashion-oriented prescription configurations.
Polycarbonate commands the largest production footprint. Glass maintains the highest unit economics.
Design Style:
Application-driven geometry requirements range from Classic frames accommodating prescription inserts to Wraparound configurations sealing against peripheral glare intrusion.
- Wraparound:Curved lens geometry and temple coverage address cycling commuters and running enthusiasts transitioning between shaded urban corridors and exposed roadways. Photochromic-polarized hybrid integration is gaining share fastest in this configuration.
- Aviator:Teardrop lens shape and metal frame construction retain institutional demand among professional pilots and motorsport teams.
- Classic:Universal fit geometry supports prescription lens retrofitting and mass-market distribution scale.
- Cat Eye:Upswept frame geometry targets fashion-forward positioning with limited prescription compatibility.
Classic designs anchor the broadest distribution footprint. Wraparound configurations are climbing the fastest.
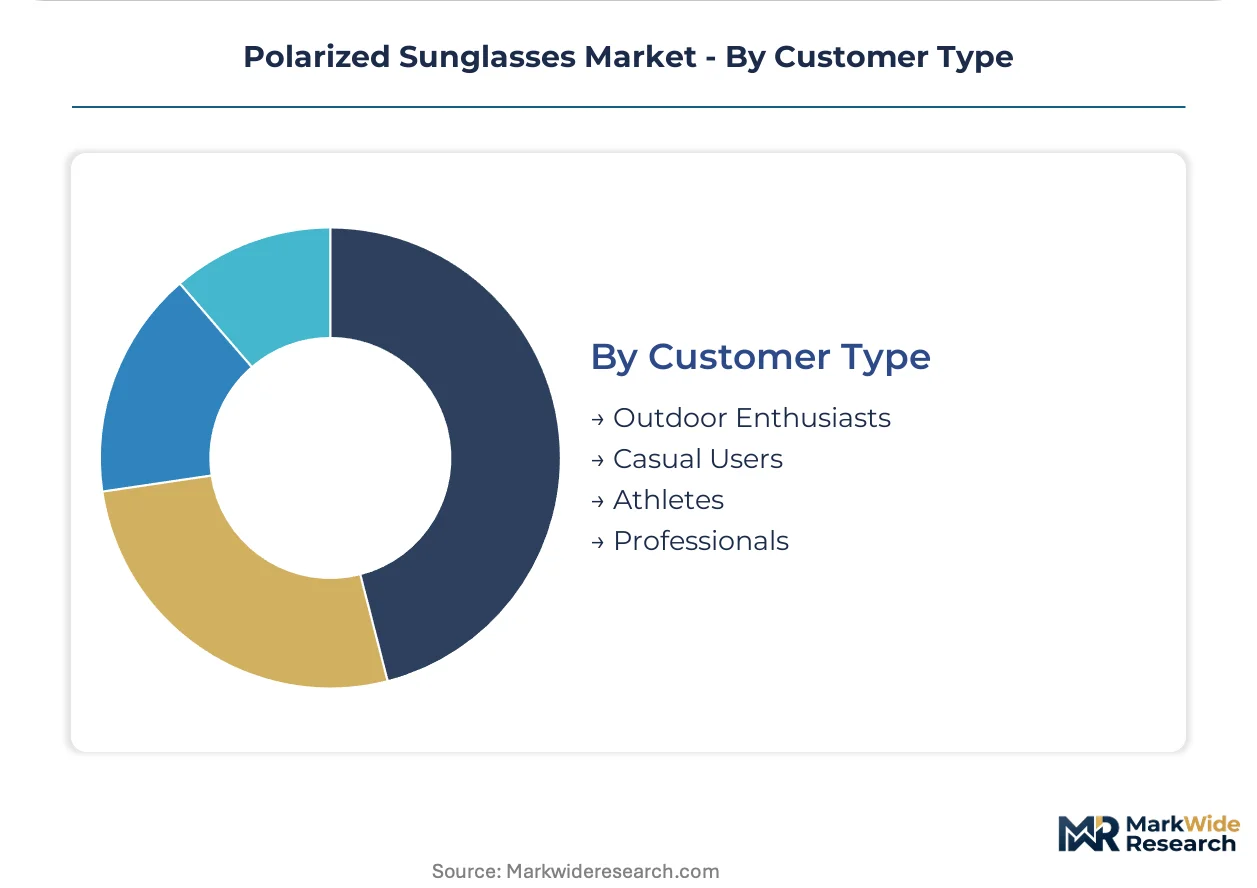
Customer Type:
Volume concentration sits with Casual Users purchasing through seasonal retail cycles, while Athletes and Professionals institutionalize replacement cadences through safety mandates and competitive equipment standards.
- Outdoor Enthusiasts:Fishing and boating specialists demand proprietary polarization film technology with glare reduction optimization for water surface reflection angles. Maui Jim's premium positioning targets this segment with dedicated marine navigation SKUs.
- Athletes:Competitive cycling and running applications require Wraparound geometry combined with hydrophobic coating durability. German and French millennial buyers are completing transactions through direct-to-consumer prescription platforms using smartphone pupillary distance tools.
- Casual Users:Seasonal purchasing patterns through pharmacy and fast-fashion channels drive volume production planning.
- Professionals:Charter operators and commercial drivers face institutional mandates for ANSI-rated eyewear with documented UV protection labeling.
Casual Users generate the highest transaction volume. Athletes are expanding most quickly through digital channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belluno's eyewear manufacturing cluster anchors global polarized sunglasses production, concentrating specialized lens casting, polarization film lamination, and luxury frame finishing within a 50-kilometer radius in Italy's Veneto region.
United States
Adventure travel spending and marine recreation drive demand for ANSI Z87.1-rated eyewear. FDA Class I medical device regulations govern UV labeling accuracy and impact resistance testing for non-prescription imports. California's Proposition 65 mandates bisphenol-A disclosure for polycarbonate frames sold through West Coast retail channels.
Italy
Luxury fashion licensing partnerships and rapid prototyping capabilities sustain premium positioning. EU REACH restrictions on chromium trioxide in mirror coatings force migration to physical vapor deposition alternatives. The Belluno cluster enables limited-edition athlete collaborations with shortened development cycles.
Germany
Direct-to-consumer prescription platforms capture millennial buyers completing full transactions online. ECHA substance of very high concern list updates drive continuous reformulation tracking across supplier networks. Bavarian optical labs specify cast-glass substrates for gradient-index polarization convergence.
Japan
Triacetate cellulose polarizing film production concentrates among chemical specialists serving mid-tier brands. METI standards influence optical clarity benchmarks for high-luminance environments. Osaka-based suppliers maintain single-source relationships with European frame manufacturers.
India
Organized sporting goods chains in Mumbai and Bangalore build dedicated eyewear sections for outdoor enthusiasts. BIS certification requirements shape import documentation for polycarbonate lens assemblies. Maharashtra retailers target first-mover positioning for polarized lens specialists.
Polarized Sunglasses Market Vendor Landscape
Global majors compete with regional champions across distribution channel control, with vertically integrated conglomerates commanding retail networks while specialized independents capture premium performance segments. Market structure tilts toward consolidation at the top and fragmentation among mid-tier suppliers. Three archetypes dominate: conglomerates with captive retail, performance specialists with proprietary technology, and contract manufacturers serving licensed fashion brands. Competitive moves center on backward integration into lens casting and strategic partnerships with European specialty chemical firms.
Within the conglomerate tier, EssilorLuxottica S.A. and Safilo Group S.p.A. exemplify divergent approaches to vertical scope. EssilorLuxottica occupies a position spanning design, lens production, and retail channel ownership. Safilo anchors European manufacturing scale while navigating luxury house licensing relationships. Maui Jim, Inc. represents the performance specialist archetype, sitting within premium positioning through proprietary polarization film technology.
| Leading Market Players |
|---|
| EssilorLuxottica S.A. |
| Safilo Group S.p.A. |
| Maui Jim, Inc. |
| Oakley, Inc. |
| Kering S.A. |
| Marcolin Group S.p.A. |
| De Rigo Vision S.p.A. |
| Costa Del Mar, Inc. |
| Warby Parker |
| Others |
Supply Flow & Price Mechanics
Fluorine-free anti-reflective coating reformulation under the EU F-Gas Regulation is simultaneously elevating European specialty chemical procurement costs and fragmenting supplier concentration away from Asian coating houses. This dual shift compresses margin buffers on mid-tier Everyday Wear SKUs while rewarding brands with established multi-source qualification protocols.
Pricing Analysis
Bisphenol-A feedstock pass-through from crude oil derivatives determines polycarbonate lens pricing volatility, with volume-priced Everyday Wear absorbing the sharpest cost compression. Three-tier pricing structure across premium, standard, and economy levels separates ANSI Z87.1-certified Sports configurations from fashion-forward mirror-coated SKUs and mass-market pharmacy retail. Pricing pressure stems from TAC film supply concentration among Japanese and Korean chemical specialists. Casual Users purchasing through seasonal fast-fashion channels exhibit highest price sensitivity, while professional marine charter operators institutionalize replacement cycles regardless of cost fluctuations.
Supply Chain Analysis
Dual-sourcing mandates from leading eyewear brands now require qualification of at least two TAC polarizing film suppliers, disrupting historic single-source relationships with Osaka-based chemical specialists. Production gravity centers on Italy's Belluno cluster, Japan's Kansai chemical corridor, and China's injection molding hubs for polycarbonate substrates. Raw material dependencies include triacetate cellulose film, bisphenol-A resin feedstock, and chromium trioxide alternatives for mirror coatings. Single-source vulnerability in TAC film supply creates structural risk for mid-tier manufacturers lacking backward integration. Distribution runs through captive retail networks owned by vertically integrated conglomerates, independent optical labs for prescription sunwear, and direct-to-consumer platforms displacing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU REACH compliance costs elevating European production economics and India's emerging outdoor retail infrastructure offering first-mover positioning at lower regulatory overhead.
For Market Incumbents: Anticipate electrochromic and active shutter technologies compressing the functional gap with fixed-tint polarized lenses by accelerating R&D allocation toward hybrid photochromic-polarized convergence. Defensive consolidation through backward integration into lens casting capabilities secures supply continuity against TAC film supply concentration. Channel control investments in direct-to-consumer prescription platforms capture millennial buyers migrating from optical retail intermediaries.
For New Entrants and Emerging Players: Sporting goods chains in Mumbai and Bangalore represent the most penetrable channel partner type for establishing dedicated eyewear sections targeting India's outdoor enthusiasts. White-space targets include photochromic-polarized hybrid SKUs for cycling commuters and eco-certified frame materials qualifying for EU Green Deal incentives. Go-to-market execution should leverage smartphone pupillary distance tools enabling full prescription transactions without physical retail presence.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier contract manufacturers serving licensed fashion brands without captive lens production or retail channel ownership. Long-term viability over a multi-year horizon favors targets with demonstrated REACH compliance documentation and established European specialty chemical procurement relationships. The signal to watch is ECHA substance of very high concern list updates forcing reformulation cycles that strain undercapitalized competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Coating Qualification | EU F-Gas Regulation compliance opens procurement relationships with European specialty chemical firms. |
| Direct-to-Consumer Platform Launch | Millennial buyers in Germany and France complete full prescription transactions via smartphone pupillary distance tools. |
| Gradient-Index Polarized Lens Adoption | Prescription sunwear providers unify distance correction with glare suppression at 18-month refresh cycles. |
| Physical Vapor Deposition Migration | REACH chromium trioxide elimination forces Italian manufacturers to absorb 12-15 percent mirror-finish cost premiums. |
| India Outdoor Retail Partnership | Organized sporting goods chains in Mumbai and Bangalore build dedicated eyewear sections for polarized lens specialists. |
Methodological Framework
Direct dialogue with lens casting technicians, polarization film procurement managers, luxury brand licensing directors, and optical retail category buyers grounded qualitative findings in operational reality. Secondary validation drew from EU REACH substance registration databases, FDA Class I medical device guidance documents, ECHA authorization lists, and customs trade data tracking polycarbonate resin and TAC film movements. Bottom-up and top-down triangulation reconciled production capacity estimates with point-of-sale transaction data across pharmacy, fast-fashion, and direct-to-consumer channels.
Bottom-up modeling built from SKU-level production cost structures, polarization film lamination throughput rates, and distribution channel margin stacks across the projection horizon. Segmentation dimensions included product type (Sports, Fashion, Everyday Wear, Safety), lens material (polycarbonate, glass, Trivex, CR-39), design style (Wraparound, Aviator, Classic, Cat Eye), and customer archetype (Outdoor Enthusiasts, Athletes, Casual Users, Professionals). CAGRs derived from weighted average of historical volume trajectories and forward-looking demand elasticity estimates for adventure travel spending and marine recreation participation. Industry-specific inputs incorporated ANSI Z87.1 certification penetration rates and EU Green Deal eco-design incentive qualification thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance of very high concern list expansions, bisphenol-A feedstock cost volatility, and electrochromic technology cost curves. Deviation in TAC film supply disruption severity or REACH authorization timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Asia-Pacific Eyewear Market
Eyewear
Ultralight Eyeglass Frames Market
Eyewear
Smart Eyewear Market
Eyewear
Face and Ear Bow Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Eyeglass Market
Eyewear
Anti-Fog Lens Market
Eyewear
Europe Eyewear Market
Eyewear
Wooden Eyewear Market
Eyewear
Eyewear Market
Eyewear
United States Eyewear Market
Eyewear
Smart Sunglasses Market
Eyewear
Goggles Market
Eyewear
Middle East Eyewear Market
Eyewear
Blue Light Glasses Market