
 Glasses Frame Market | 2026-2036
Glasses Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Glasses Frame Market Foresight
ISO 12870 ophthalmic frame endurance testing is redrawing competitive boundaries for manufacturers seeking European market access. EssilorLuxottica leverages captive retail networks across multiple continents to sustain margin capture. Safilo Group anchors its position through licensed luxury brand portfolios and Italian manufacturing heritage. Marcolin competes via specialized design partnerships with fashion houses.
Glasses frames are mechanical structures engineered to position corrective or protective lenses before the eyes, typically constructed from cellulose acetate, beta-titanium alloys, or injection-molded TR90 polymer with specified bridge widths and temple lengths. Acetate and titanium dominate material segmentation due to established color stability and hypoallergenic properties respectively. Full rim and semi rimless product types command the largest volume positions, though rimless configurations attract premium positioning through minimal aesthetic engineering. E-commerce distribution channels are expanding fastest as virtual try-on algorithms reduce fit uncertainty.
FDA 21 CFR 801.410 impact resistance requirements govern frame-lens retention in the United States, while REACH substance restrictions in Europe limit certain plasticizers and heavy metals in acetate formulations. China's SAMR enforces GB/T 14214 national standards for frame dimensional tolerances and nickel release limits. Stakeholders must monitor evolving biocompatibility testing protocols as regulatory convergence between medical device and consumer product classifications intensifies.
Market Dynamics
Virtual try-on algorithms and 3D facial scanning are compressing the traditional retail channel's role in frame selection, forcing manufacturers to rebuild distribution economics around digital-first fit assurance rather than physical inventory depth.
Growth Catalysts
- EU Medical Device Regulation:Biocompatibility testing mandates for nickel release and skin contact materials are accelerating R&D investment in hypoallergenic alloys, elevating technical barriers that favor established laboratories with ISO 17025 accreditation.
- Acetate color stability:Advances in cellulose acetate polymerization yield broader pigment permanence ranges, enabling fashion-forward seasonal collections that drive replacement cycles among style-conscious consumers.
- China:Domestic optical chains including Aier Eye Hospital and Baodao Glasses are scaling proprietary frame lines, creating captive demand that insulates local manufacturers from import competition.
Market Restraints
- Titanium sponge volatility:Beta-titanium alloy feedstock costs fluctuate with aerospace sector demand cycles, squeezing margin predictability for mid-tier frame producers lacking long-term supply contracts.
- Wenzhou manufacturing cluster:Over 60 percent of global acetate frame production concentrates in this single Chinese industrial zone, creating geographic vulnerability to regional logistics disruptions or environmental compliance enforcement.
- Contact lens substitution:Daily disposable silicone hydrogel lenses and orthokeratology solutions capture myopia correction demand among younger demographics, permanently removing some addressable frame volume.
Strategic Opportunities
- India:Organized optical retail penetration remains below 15 percent in tier-two and tier-three cities, creating whitespace for frame brands partnering with regional chains to establish localized distribution.
- Smart glasses convergence:Audio-integrated frames and heads-up display modules merge eyewear with consumer electronics, opening premium price tiers through technology licensing partnerships with semiconductor vendors.
- Direct-to-consumer virtual fitting:Smartphone-based pupillary distance measurement and frame size recommendation engines enable bypass of traditional optometric intermediaries, capturing margin previously allocated to wholesale distribution.
Industry Challenges
- ISO 12870 certification timelines:Endurance testing protocols for bridge deformation and temple hinge fatigue require 12-18 month validation cycles, delaying product launches and tying up working capital in pre-approved inventory.
- Acetate craftsperson scarcity:Hand-finishing techniques for frame polishing and hinge insertion depend on skilled labor pools concentrated in Northern Italy and Shenzhen, with limited apprenticeship pipeline replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glasses Frame Market |
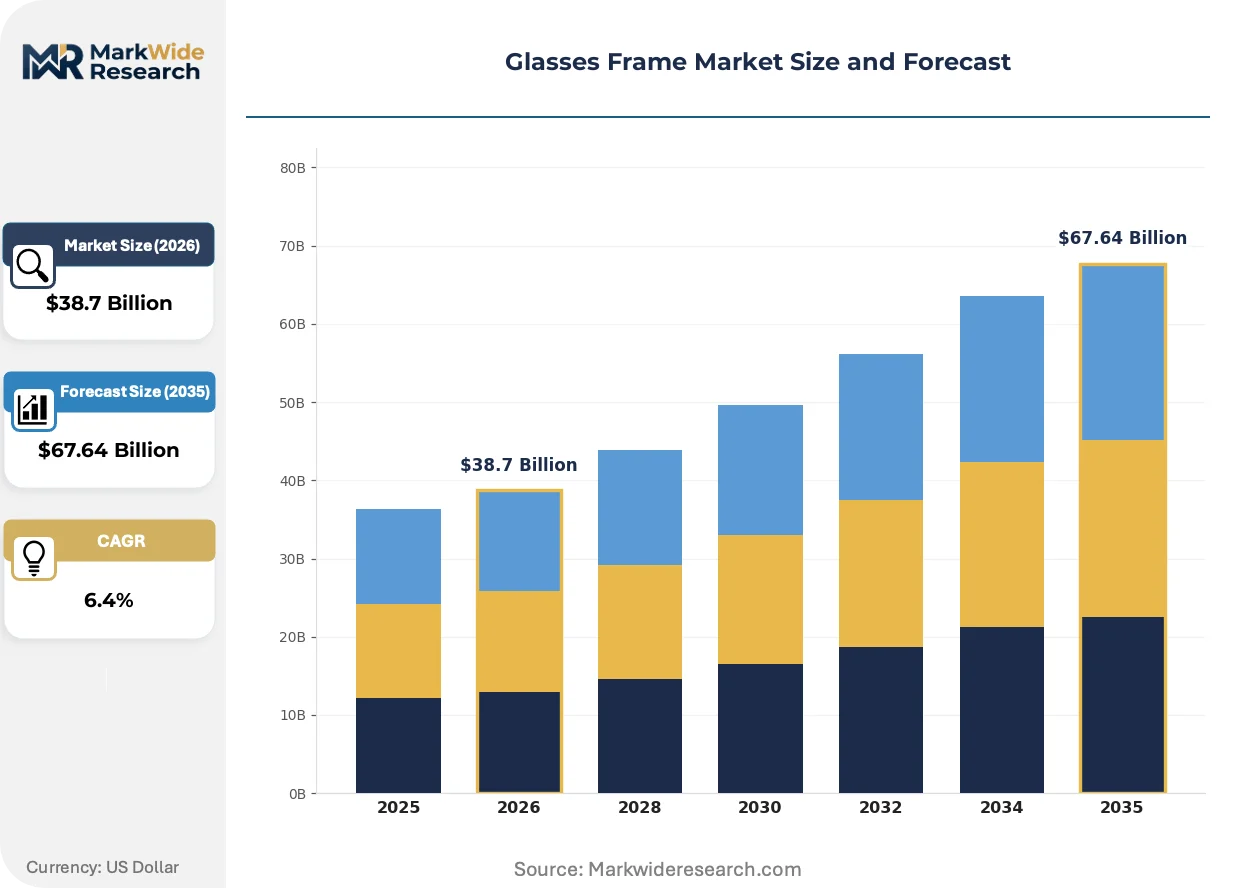
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Acetate, Titanium, Stainless Steel, TR90, Aluminum, Nylon Product Type: Full Rim, Semi Rimless, Rimless, Clip-On, Foldable End User: Optical Retailers, Eye Care Professionals, Fashion Boutiques, Online Retailers Distribution Channel: Specialty Stores, Department Stores, E-Commerce, Optical Shops, Direct Sales |
| Companies Covered | EssilorLuxottica, Safilo Group, Marcolin, Alcon, Bausch & Lomb, Johnson & Johnson Vision Care, CooperVision, Fielmann AG, Innovative Eyewear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glasses Frame Market Shifts & Advancements
Digital fit technologies and sustainable material chemistry are recasting how frames are designed, certified, and sold, collapsing the traditional separation between medical device compliance and fashion accessory marketing.
3D-printed titanium lattice structures are displacing solid-frame construction in premium segments. Optical labs serving high-net-worth clients in Germany and Switzerland now specify topology-optimized temple arms that reduce material weight by 40 percent while maintaining torsional rigidity. This additive manufacturing approach is displacing conventional CNC milling workflows and compressing minimum viable production runs from thousands to single units.
REACH substance restrictions on phthalate plasticizers and heavy metal stabilizers are forcing acetate compounders to reformulate legacy recipes. European frame manufacturers must now document full material substance declarations through SCIP database entries, adding compliance overhead that smaller Italian workshops struggle to absorb. The regulatory pressure falls most heavily on colored acetate variants, where pigment chemistry historically relied on now-restricted cadmium and lead compounds.
Subscription-based frame replacement programs are emerging as an alternative to outright purchase. Younger consumers in urban South Korea and coastal China increasingly prefer quarterly style rotations through membership models rather than multi-year frame ownership. This behavioral shift concentrates inventory risk with manufacturers and demands predictive analytics capabilities that legacy ERP systems lack.
Glasses Frame Market Segmentation
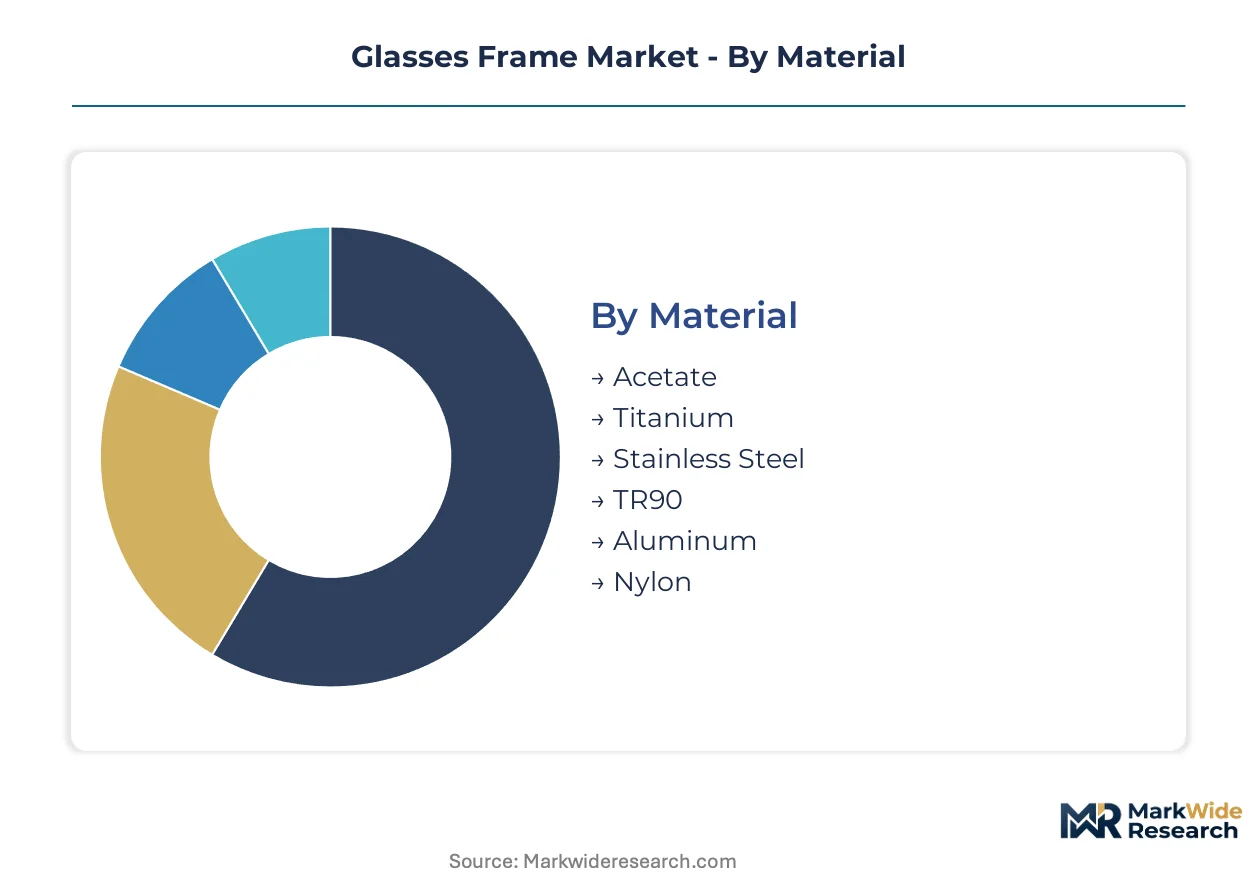
Frame segmentation reveals how material chemistry, product architecture, and channel economics create divergent margin profiles. Each category carries distinct substitution risks from contact lenses, smart eyewear, or surgical correction that reshape investment prioritization.
Material:
Contact lens substitution pressure falls heaviest on commodity metals and basic polymers where fashion differentiation is weakest.
- Acetate:Cellulose acetate polymer enables deep color saturation and hand-polished surface finishes. Optical chains in coastal China rotate seasonal acetate collections to drive replacement cycles among style-conscious consumers.
- Titanium:Beta-titanium alloys deliver superior strength-to-weight ratios and hypoallergenic skin contact properties. German and Swiss optical labs specify topology-optimized titanium temples for high-net-worth clients seeking minimal frame mass.
- Stainless Steel:Cost-efficient stamping and welding processes serve mass-market price tiers with limited corrosion resistance.
- TR90:Injection-molded thermoplastic polyamide offers flexibility and impact resistance for active lifestyle positioning.
- Aluminum:Lightweight extrusion compatibility suits rimless and semi-rimless architectural designs.
- Nylon:Memory polymer characteristics enable extreme frame flex without permanent deformation.
Acetate retains volume leadership; titanium holds the steepest expansion curve.
Product Type:
Cost tier stratification separates medical necessity purchases from discretionary fashion acquisitions.
- Full Rim:Complete lens encapsulation provides maximum structural protection and design surface area. Chinese domestic optical chains scale proprietary full-rim lines to capture replacement demand insulated from import competition.
- Semi Rimless:Nylon cord or metal rim suspension reduces frame mass while preserving lens security. European frame manufacturers favor semi-rimless configurations for REACH-compliant material efficiency.
- Rimless:Drill-mounted lens construction commands premium positioning through minimal aesthetic engineering and precision machining requirements.
- Clip-On:Auxiliary sun protection attachments extend frame utility without dedicated sunglass purchases.
- Foldable:Hinge-intensive engineering targets travel and compact storage use cases.
Full Rim dominates unit economics; Rimless captures the highest margin per frame.
End User:
Procurement authority fragmentation across medical, fashion, and digital channels complicates manufacturer go-to-market design.
- Optical Retailers:Volume aggregators with private label development capabilities. Aier Eye Hospital and Baodao Glasses in China are scaling captive frame lines that displace third-party supplier relationships.
- Eye Care Professionals:Prescription-anchored dispensing with clinical credibility transfer to frame recommendations.
- Fashion Boutiques:Curated assortments emphasizing seasonal design partnerships and limited-edition collaborations.
- Online Retailers:Virtual try-on algorithm deployment reducing fit uncertainty and return rates.
Optical Retailers concentrate volume procurement; Online Retailers are climbing the fastest.
Distribution Channel:
Channel selection dictates working capital intensity and biocompatibility documentation requirements.
- Specialty Stores:High-touch fitting services with trained opticians and adjustable inventory depth. Italian frame workshops depend on specialty store relationships to justify hand-finishing cost premiums.
- Department Stores:Licensed brand presence with fashion accessory positioning adjacent to jewelry and leather goods.
- E-Commerce:Smartphone-based pupillary distance measurement and frame size recommendation engines enable direct-to-consumer margin capture previously allocated to wholesale distribution.
- Optical Shops:Prescription-integrated dispensing with lens edging and fitting services co-located.
- Direct Sales:Manufacturer-owned retail or subscription-based frame replacement programs.
Specialty Stores anchor premium positioning; E-Commerce gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for domestic manufacturing and tightening biocompatibility standards are redrawing regional competitive boundaries. National regulators enforce divergent testing protocols that fragment certification requirements. Local optical retail consolidation creates captive demand channels that insulate domestic producers from import competition.
China
SAMR enforces GB/T 14214 standards for frame dimensional tolerances and nickel release limits. Aier Eye Hospital and Baodao Glasses scale proprietary frame lines that displace third-party suppliers. The Wenzhou manufacturing cluster concentrates over sixty percent of global acetate frame production, creating geographic vulnerability to regional logistics disruptions.
United States
FDA 21 CFR 801.410 impact resistance requirements govern frame-lens retention for corrective eyewear. Virtual try-on algorithm deployment compresses traditional retail channel economics around digital-first fit assurance. California and New York Metro optical chains rebuild distribution models around smartphone-based pupillary distance measurement tools.
Germany
REACH substance restrictions limit phthalate plasticizers and heavy metal stabilizers in acetate formulations. Optical labs in Munich and Stuttgart specify topology-optimized titanium temples for high-net-worth clients seeking minimal frame mass. German frame manufacturers document full material substance declarations through SCIP database entries.
Italy
EU Medical Device Regulation tightens biocompatibility testing mandates for nickel release and skin contact materials. Northern Italian workshops depend on specialty store relationships to justify hand-finishing cost premiums. The Veneto and Lombardy regions concentrate skilled labor pools for acetate polishing and hinge insertion techniques.
South Korea
MFDS enforces medical device classification standards for corrective eyewear frames sold through optical channels. Subscription-based frame replacement programs concentrate inventory risk with manufacturers in Seoul and Busan. Younger consumers in urban districts prefer quarterly style rotations through membership models rather than multi-year frame ownership.
Glasses Frame Market Competitive Landscape
Player mix skews toward vertically integrated luxury houses and specialized design licensors. The vendor base concentrates around three structural tiers: global eyewear conglomerates with captive retail networks, licensed brand specialists leveraging fashion house partnerships, and regional optical chains scaling proprietary frame lines. Strategic moves center on direct-to-consumer virtual fitting technology and additive manufacturing capacity for topology-optimized titanium construction.
Among Italy-based specialists, Marcolin occupies a position exemplifying the licensed luxury archetype through fashion house design partnerships. EssilorLuxottica and Safilo Group anchor the consolidated tier, representing divergent approaches to margin capture—captive retail network control versus heritage manufacturing positioning. These three entities collectively illustrate how European frame economics split between retail integration and brand licensing vectors.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Safilo Group |
| Marcolin |
| Alcon |
| Bausch & Lomb |
| Johnson & Johnson Vision Care |
| CooperVision |
| Fielmann AG |
| Innovative Eyewear |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Wenzhou acetate compounders and European frame manufacturers lock in both raw material access and eighteen-month price visibility against titanium sponge volatility. These arrangements insulate mid-tier producers from aerospace demand cycles while embedding REACH compliance costs into baseline pricing.
Pricing Analysis
Certification level (ISO 12870/CE/FDA-grade) creates the primary spread between commodity stamped-steel frames and premium topology-optimized titanium constructions. Three-tier pricing structure across premium, standard, and economy levels reflects divergent biocompatibility testing burdens and hand-finishing labor intensity. Cost compression in standard-tier acetate frames is intensifying because Chinese domestic optical chains are scaling captive proprietary lines that bypass traditional wholesale markups. Price-sensitive procurement concentrates among online retailers optimizing for virtual try-on conversion rates, while least-sensitive buyers occupy German and Swiss optical labs specifying custom titanium lattice geometries.
Supply Chain Analysis
China and Italy anchor global frame manufacturing, with Wenzhou supplying over sixty percent of acetate output and Northern Italian workshops commanding hand-finishing expertise for luxury positioning. Beta-titanium alloy feedstock draws from Japanese and Chinese aerospace-grade sponge producers, while cellulose acetate polymer feeds from cotton linter processors in East Asia. Single-source vulnerability concentrates in the Wenzhou cluster, where environmental compliance enforcement or regional logistics disruptions would cascade through global acetate availability. Distribution runs through captive retail networks for conglomerates, licensed brand wholesalers for fashion partnerships, and direct-to-consumer virtual fitting platforms for digital-native entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virtual try-on algorithm penetration remains below thirty percent in tier-two optical markets, creating an early-cycle expansion window for digital-first fit assurance technologies.
For Market Incumbents: Consolidate control over ISO 17025-accredited testing laboratories to defend against EU Medical Device Regulation compliance cost escalation. Acquire additive manufacturing capacity in Germany or Switzerland to secure topology-optimized titanium production before mid-tier competitors can replicate lattice structures. Lock in long-term beta-titanium offtake agreements with Japanese sponge producers to neutralize aerospace demand cycle volatility. For New Entrants and Emerging Players: Lead with smartphone-based pupillary distance measurement tools to bypass traditional optometric intermediaries in India's underpenetrated tier-two and tier-three cities. Target subscription-based frame replacement programs in South Korean urban districts where younger consumers prefer quarterly style rotations. Partner with semiconductor vendors for audio-integrated smart glasses modules to capture premium technology licensing tiers. For Investors and Strategic Acquirers: The market sits at a technology-adoption phase that favors digital fit infrastructure and additive manufacturing capability over legacy acetate craftsperson networks. Five-to-ten year viability hinges on regulatory convergence between medical device and consumer product classifications. Watch for inflection when REACH substance restrictions force material reformulation costs that smaller Italian workshops cannot absorb, triggering consolidation toward SCIP-database-compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Virtual Fitting Platform | Smartphone-based pupillary distance tools capture margin previously allocated to wholesale distribution intermediaries. |
| Additive Manufacturing Capacity Expansion | Topology-optimized titanium temples reduce material weight forty percent for German high-net-worth optical lab clients. |
| ISO 12870 Certification Investment | Endurance testing accreditation accelerates European market access under tightened EU Medical Device Regulation mandates. |
| Smart Glasses Technology Licensing | Audio-integrated frame modules merge eyewear with consumer electronics through semiconductor vendor partnerships. |
| Subscription-Based Frame Replacement Program | Quarterly style rotation models concentrate inventory risk with manufacturers in Seoul and coastal China. |
Research Methodology
Cross-validation between primary interviews with frame manufacturing executives, optical chain procurement directors, and regulatory affairs specialists anchors the qualitative findings against secondary validation from SAMR GB/T 14214 filings, FDA 21 CFR 801.410 impact resistance records, and ECHA SCIP database substance declarations. Bottom-up triangulation across acetate compounders in Wenzhou, titanium alloy processors in Japan, and Italian hand-finishing workshops reconciles with top-down optical retail audit data from coastal Chinese provinces and German metropolitan regions.
Sensitivity analysis across material segmentation (acetate, titanium, TR90), product architecture (full rim, semi rimless, rimless), and distribution channel (specialty stores, e-commerce, direct sales) shapes the analytical framework throughout the forecast period. CAGRs derive from installed base replacement cycles, regulatory compliance cost trajectories, and virtual try-on algorithm adoption curves. Industry-specific inputs include nickel release testing protocol evolution under EU MDR and topology-optimized titanium production yield rates from German optical lab specifications.
The analysis sits within stated boundaries; outcomes outside continued biocompatibility regulatory convergence or sustained titanium sponge price volatility would require recalibration. Forecasts reflect assumptions about REACH substance restriction enforcement intensity and Chinese domestic optical chain captive sourcing expansion. Recalibration cycles align with material shifts in EU Medical Device Regulation implementation timelines and additive manufacturing cost parity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Eyewear Market
Eyewear
Ultralight Eyeglass Frames Market
Eyewear
Smart Eyewear Market
Eyewear
United States Eyewear Market
Eyewear
Eyeglass Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Wooden Eyewear Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market
Eyewear
Latin America Eyewear Market
Eyewear
Reading Glasses Market
Eyewear
Anti-Fog Lens Market
Eyewear
Blue Light Glasses Market
Eyewear
Sunglasses Pouch Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Luxury Eyewear Market
Eyewear
Plano Sunglasses Market