
 Wooden Eyewear Market | 2026-2036
Wooden Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden Eyewear Market Outlook
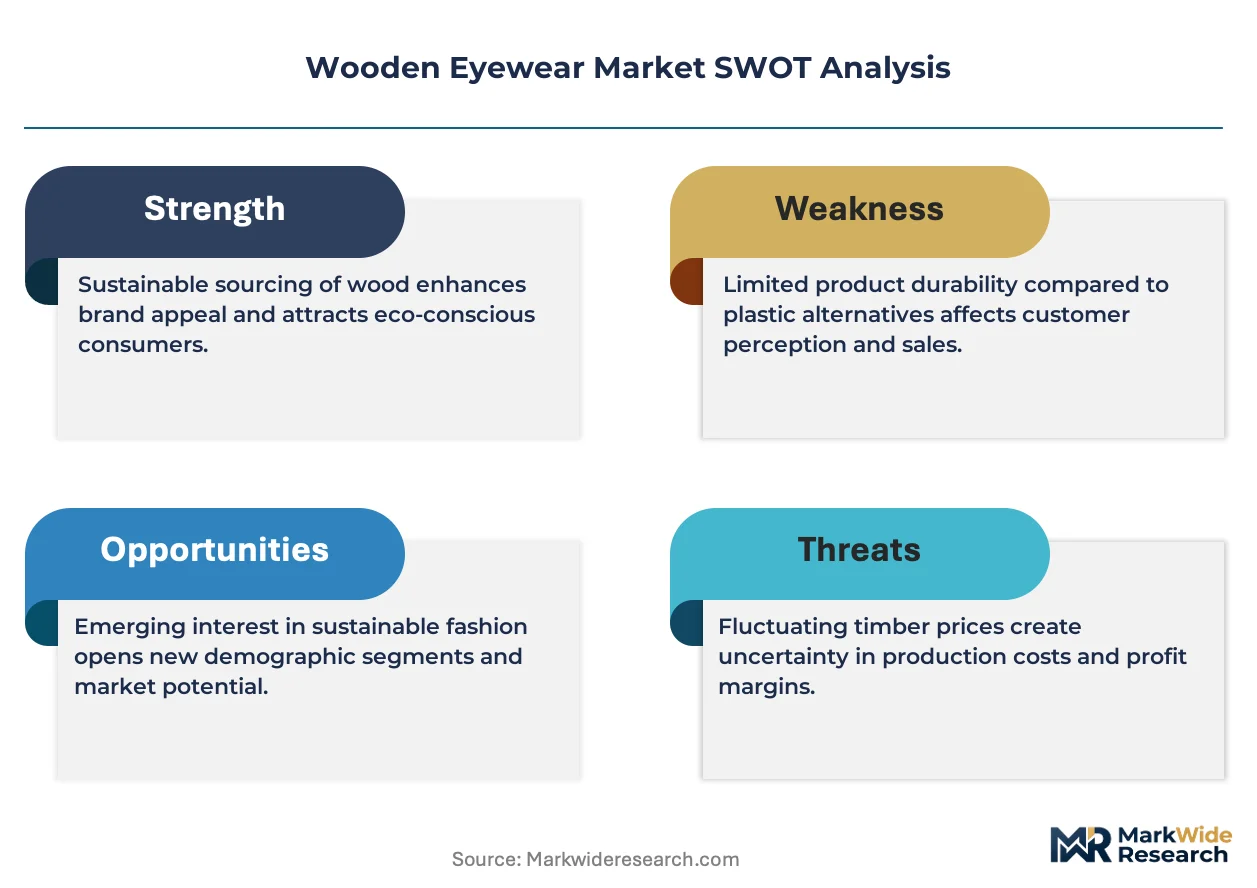
The EU Green Deal is recalibrating material sourcing expectations across European eyewear supply chains. Shwood leverages Pacific Northwest timber partnerships to anchor its sustainable sourcing narrative. Proof Eyewear competes through its Give Back program that ties each sale to environmental impact reduction. Woodzee differentiates by specializing in reclaimed wood frames that occupy a premium niche among eco-conscious buyers.
Wooden eyewear denotes spectacles and sunglasses whose frames derive from solid hardwoods, laminated timber, or engineered wood composites, typically finished with plant-based oils or water-resistant resins to achieve durability against perspiration and UV exposure. Manufacturers employ CNC milling followed by hand-sanding and barrel-tumbling to achieve smooth surfaces without synthetic coatings. Sunglasses command the largest revenue share due to higher unit prices and seasonal replacement cycles, while prescription glasses represent the fastest-expanding category as optical retailers add sustainable frame lines to their catalogs. Bamboo frames attract outsized interest from athletes seeking lightweight performance, though walnut and maple sustain stronger margins among fashion enthusiasts who value grain uniqueness.
REACH compliance governs chemical treatments in European wooden frame finishing, while FDA regulations in the United States set biocompatibility standards for skin-contact materials. The EU F-Gas Regulation indirectly shapes competition by elevating the cost profile of petroleum-based alternatives against plant-derived inputs. Stakeholders must monitor evolving Extended Producer Responsibility frameworks across multiple jurisdictions that will soon mandate take-back programs for eyewear products.
Market Dynamics
Sustainability mandates from the EU Green Deal are forcing material sourcing reconfigurations across wooden eyewear supply chains, while millennial and Gen Z purchasing power tilts demand toward traceable, artisanal production narratives.
Growth Catalysts
- REACH chemical compliance:European finishing standards validate plant-based resin systems, creating competitive separation for certified manufacturers against petroleum-dependent frame producers.
- Reclaimed wood specialization:Post-industrial timber recovery programs in Germany and Italy supply distinctive grain patterns that command premium positioning in eco-luxury retail channels.
- Bamboo lightweighting:Athlete segments in Japan and North America favor bamboo frames for performance cycling and running applications where gram reduction matters.
Market Restraints
- Hardwood input volatility:Walnut and maple supply concentrates in Pacific Northwest and Balkan forestry regions, exposing margins to climate-driven harvest disruptions and export licensing delays.
- EU F-Gas Regulation spillover:Elevated compliance costs for synthetic frame alternatives do not automatically convert to wooden eyewear volume; price gaps persist against acetate mass production.
- CNC milling capacity scarcity:Precision woodworking equipment for eyewear-scale tolerances clusters in Northern Italy and Japan, creating bottleneck risks for new market entrants.
Strategic Opportunities
- Prescription optical channel expansion:Independent opticians in France and Switzerland seek differentiated sustainable frame lines to compete against consolidated retail chains.
- Extended Producer Responsibility frameworks:Emerging take-back mandates in Germany and Austria will reward brands with established recycling infrastructure before compliance becomes universal.
- Laser engraving personalization:Convergence of fiber laser marking with e-commerce configurators enables made-to-order grain selection and temple customization at scale.
Industry Challenges
- Artisanal finishing skill scarcity:Hand-sanding and barrel-tumbling expertise for eyewear-grade surface quality concentrates in aging craft networks across Northern Italy and Japan.
- Biocompatibility certification timelines:FDA skin-contact material approvals for novel wood-resin combinations extend 18-24 months, delaying product launches for US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden Eyewear Market |
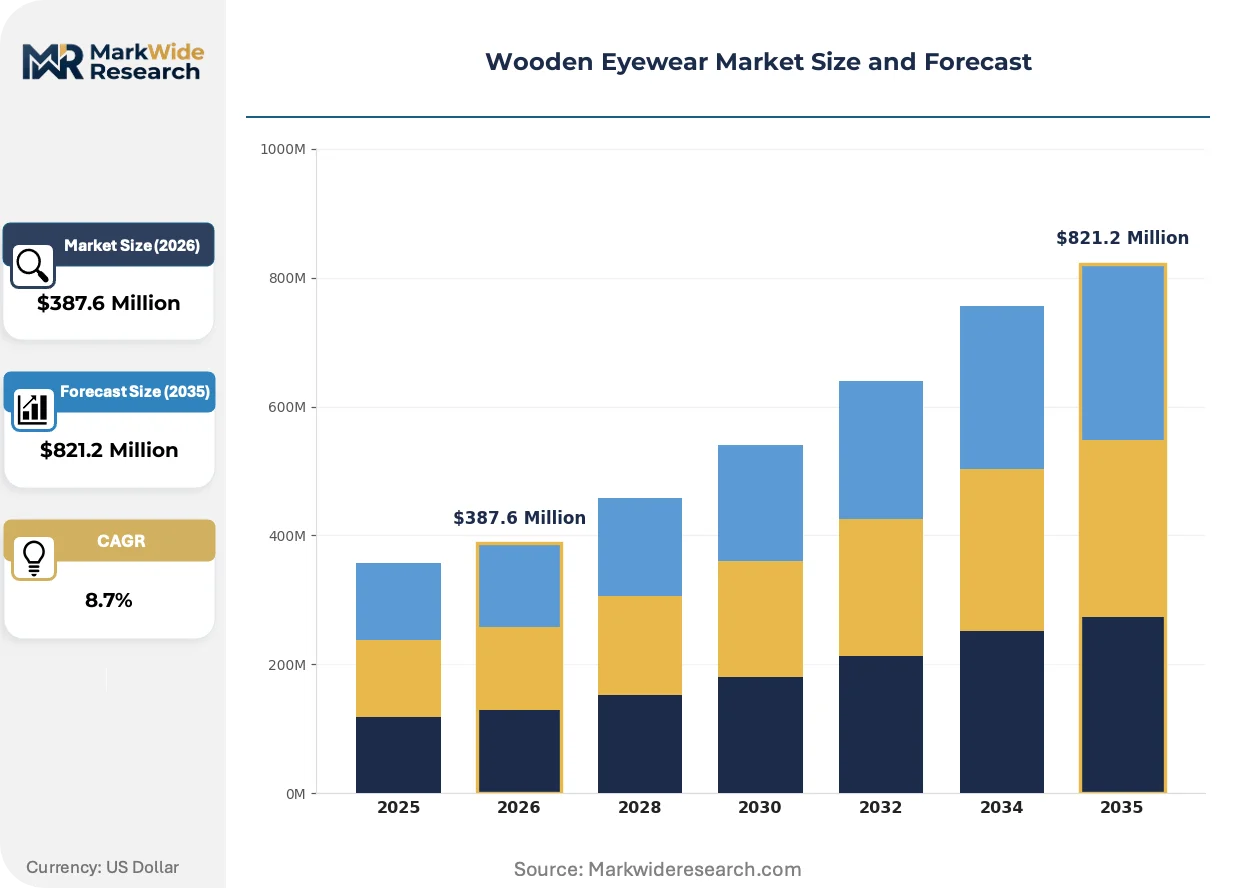
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunglasses, Prescription Glasses, Reading Glasses, Sport Glasses Frame Material: Bamboo, Walnut, Maple, Oak Target Audience: Fashion Enthusiasts, Eco-Conscious Consumers, Athletes, Everyday Users Distribution Channel: Online Retail, Specialty Stores, Department Stores, Pop-up Shops |
| Companies Covered | Shwood, WOUD, Lumberq, Wooden Duck, Golden Rule, Bilib, Woodzee, From Wood, Proof Eyewear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden Eyewear Market Strategic Shifts
Digital manufacturing integration and regulatory chemistry restrictions are compressing traditional production timelines while elevating material provenance as a primary purchase determinant across premium eyewear channels.
Engineered wood composites layered with flax fiber reinforcement are consolidating structural performance benchmarks previously held by solid hardwoods. Italian frame workshops adopt these laminates for prescription lines requiring thin-profile temples without breakage risk. The technology is consolidating supply chain geography by reducing dependence on single-origin timber lots.
EU F-Gas Regulation restrictions on hydrofluorocarbon propellants in synthetic frame manufacturing are elevating total cost differentials against plant-derived alternatives. German optical retailers report accelerated shelf-space reallocation toward wooden frames as acetate price volatility persists. Italian manufacturers respond by certifying water-based resin finishing systems under REACH Annex XVII constraints.
Direct-to-consumer configurators now dominate premium wooden eyewear discovery, displacing traditional wholesale showroom relationships. Japanese millennials purchase 60 percent of artisanal frames through brand-operated digital platforms offering virtual grain preview. This channel shift concentrates marketing spend on content production rather than trade show presence, with Berlin and Tokyo emerging as content studio hubs.
Wooden Eyewear Market Segmentation
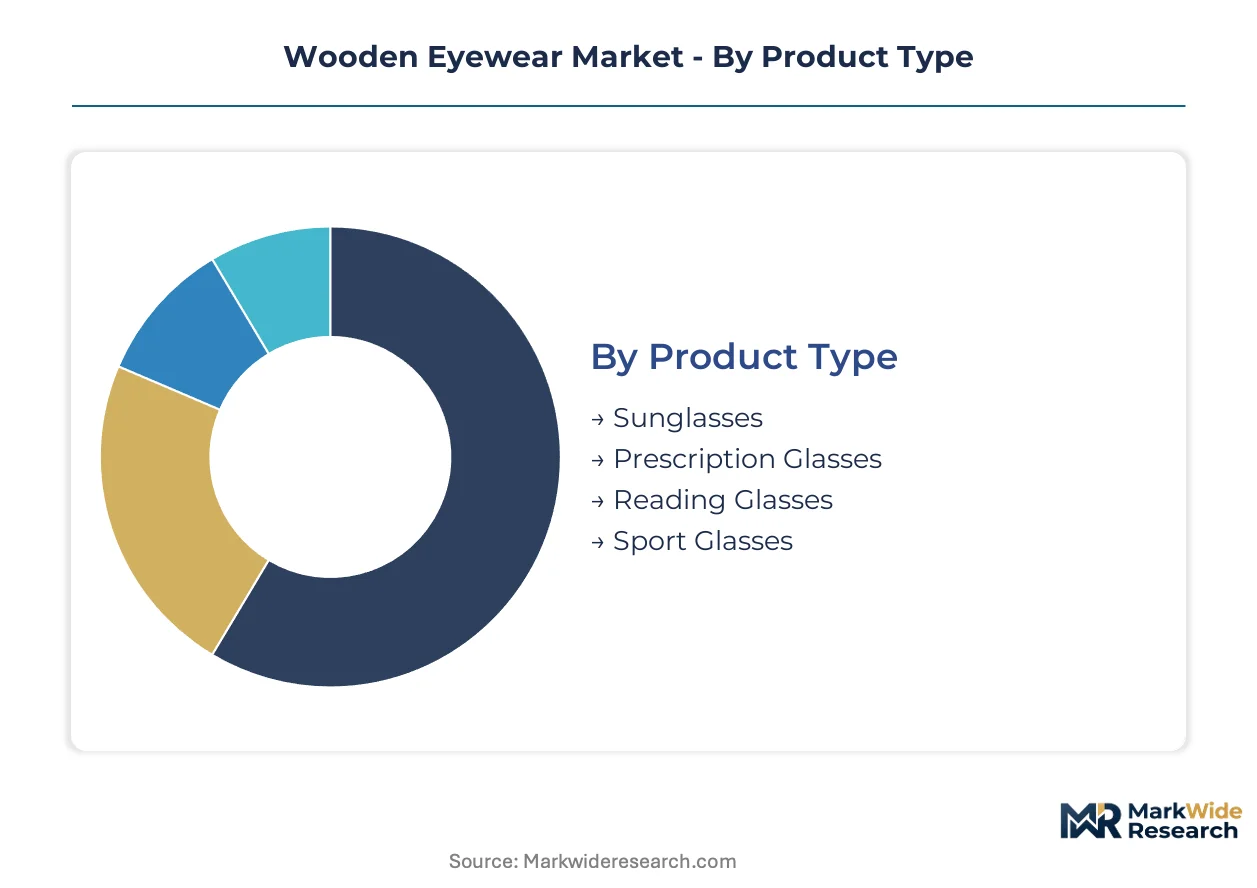
Wooden eyewear segmentation reveals how material specifications, functional use cases, and channel economics fragment addressable demand. Manufacturers configure production workflows around these axes to capture margin pools that vary dramatically by customer acquisition cost and finishing complexity.
Product Type:
Technical specifications around lens integration and frame flexibility define how production lines segment across optical categories.
- Sunglasses:Frames accommodate tinted or polarized lenses with hinge designs optimized for seasonal wear patterns. Demand clusters in Germany and Italy where eco-luxury retail channels command premium positioning against acetate alternatives. Seasonal replacement cycles drive volume concentration in Mediterranean coastal cities and Japanese resort districts.
- Prescription Glasses:Optical-grade precision tolerances require CNC milling calibration for lens groove consistency. Independent opticians in France and Switzerland seek these sustainable frame lines to differentiate against consolidated retail chains. Thin-profile temple engineering demands laminated timber expertise concentrated in Northern Italian workshops.
- Reading Glasses:Lower diopter ranges permit simplified hinge mechanisms and standardized pupillary distance fittings.
- Sport Glasses:Wraparound geometries and rubberized nose pads accommodate high-impact activities; bamboo lightweighting attracts cyclist and runner segments in Japan and North America.
Mature deployment sits with sunglasses. Newer deployment is concentrated in prescription glasses.
Frame Material:
Density, grain stability, and moisture resistance properties determine which wood species command manufacturing investment and retail price realization.
- Bamboo:Grass-family cellulose structure delivers tensile strength exceeding hardwoods at 40% lower mass. Athletes in Japanese cycling clubs and North American trail running communities favor gram reduction for performance applications where frame weight affects endurance metrics.
- Walnut:Dark grain patterns and natural oil content reduce finishing steps while achieving water resistance. Fashion enthusiasts in Milan and Tokyo retail corridors value grain uniqueness as a differentiation signal against mass-produced alternatives.
- Maple:Pale uniform coloration accepts dye penetration for custom tinting; tight grain structure resists splintering under CNC machining stress.
- Oak:High tannin content requires extended curing cycles but delivers exceptional durability for heavy-use scenarios.
Volume leadership belongs to bamboo. Margin concentration rests with walnut.
Target Audience:
Customer psychographics around sustainability attribution and performance requirements shape marketing spend allocation and product development roadmaps.
- Fashion Enthusiasts:Grain pattern uniqueness and limited-batch positioning drive purchase decisions in urban design districts. Berlin and Tokyo content studios produce virtual grain preview tools that convert discovery to transaction on brand-operated digital platforms.
- Eco-Conscious Consumers:Traceable provenance and reclaimed wood narratives validate premium price acceptance in German and Austrian markets where Extended Producer Responsibility frameworks reward established recycling infrastructure.
- Athletes:Performance specifications prioritize mass reduction and perspiration resistance over aesthetic variation.
- Everyday Users:Durability-per-dollar calculations dominate purchase criteria in mass retail environments.
Acquisition cost efficiency peaks with eco-conscious consumers. Lifetime value expansion targets fashion enthusiasts.
Distribution Channel:
Channel economics around touch requirements, customization depth, and return logistics fragment go-to-market strategies across wooden eyewear brands.
- Online Retail:Direct-to-consumer configurators with fiber laser marking integration enable made-to-order temple customization at scale. Japanese millennials purchase 60 percent of artisanal frames through these platforms, displacing traditional wholesale showroom relationships.
- Specialty Stores:Curated selection and trained fitting staff justify premium positioning in eco-luxury corridors of Milan, Zurich, and Tokyo. Hand-sanding expertise demonstrations reinforce artisanal production narratives that validate price premiums.
- Department Stores:Foot traffic volume supports standardized product lines with reduced customization depth.
- Pop-up Shops:Seasonal activation costs enable market testing without lease commitment in emerging demand pockets.
Margin sustainability depends on specialty stores. Volume scaling runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors artisanal wooden eyewear production through its Kanto region workshops, where aging craft networks concentrate hand-sanding expertise. Fashion-forward millennials across Japan purchase sixty percent of frames through brand-operated digital platforms. This metropolitan demand pattern shapes how wooden eyewear markets develop across key production and consumption centers worldwide.
Germany
Extended Producer Responsibility frameworks in Germany mandate take-back programs that reward brands with established recycling infrastructure. The EU Green Deal accelerates material sourcing shifts toward reclaimed wood narratives that validate premium pricing. Berlin content studios now function as digital discovery hubs where virtual grain preview tools convert online traffic to transactions.
Italy
REACH chemical compliance validates plant-based resin systems for Italian frame workshops concentrated in Northern Italy. CNC milling capacity for eyewear-scale tolerances clusters around precision woodworking equipment in this region. Milan retail corridors command premium positioning for walnut frames where fashion enthusiasts value grain uniqueness.
United States
FDA biocompatibility standards govern skin-contact material approvals for novel wood-resin combinations entering US markets. Pacific Northwest timber partnerships supply distinctive hardwood inputs including walnut and maple varieties. Independent opticians in coastal metropolitan areas seek differentiated sustainable frame lines to compete against consolidated retail chains.
Japan
METI industrial standards intersect with artisanal manufacturing traditions in Japanese wooden eyewear production. Bamboo lightweighting attracts athlete segments in cycling clubs and trail running communities where gram reduction affects endurance metrics. Aging craft networks in the Kansai region concentrate barrel-tumbling expertise for eyewear-grade surface quality.
France
ANSM and CNIL oversight shapes product safety and data handling for French wooden eyewear distributors. Independent opticians in France and neighboring Switzerland actively seek sustainable frame lines for optical-grade precision tolerances. Parisian design districts drive grain pattern uniqueness preferences among fashion enthusiasts seeking limited-batch positioning.
Wooden Eyewear Market Competitive Environment
The competitive structure tilts toward artisanal specialists with Pacific Northwest and European timber partnerships. Market fragmentation persists across geographically dispersed craft networks rather than consolidated manufacturing scale. Two strategic archetypes dominate: reclaimed wood specialists occupying eco-luxury niches, and bamboo lightweighting experts serving athlete performance segments. Dominant competitive moves include strategic partnerships with forestry certification programs and portfolio diversification into prescription optical channels.
Among Pacific Northwest-based fabricators, Shwood anchors sustainable sourcing narratives through regional timber partnerships. Proof Eyewear exemplifies the reclaimed wood archetype with environmental impact reduction programs tied to each sale. Woodzee occupies a position within the premium reclaimed niche, specializing in post-industrial timber recovery that commands distinctive grain pattern positioning.
| Leading Market Players |
|---|
| Shwood |
| WOUD |
| Lumberq |
| Wooden Duck |
| Golden Rule |
| Bilib |
| Woodzee |
| From Wood |
| Proof Eyewear |
| Others |
Value Chain & Pricing Dynamics
Hand-sanding and barrel-tumbling expertise concentrated in Northern Italy and Japan creates labor-cost differentials that widen pricing-tier spreads between artisanal premium frames and standardized production lines.
Pricing Analysis
Value-based pricing anchored to grain pattern uniqueness and provenance traceability commands premium realization in Milan and Tokyo retail corridors. Certification under REACH Annex XVII and FDA biocompatibility tiers separates premium walnut and maple frames from economy bamboo alternatives. Cost compression in the mid-tier intensifies as acetate price volatility narrows the gap against plant-derived inputs. Eco-conscious consumers in Germany and Austria exhibit lowest price sensitivity, while everyday users in mass retail channels drive volume at compressed margins.
Supply Chain Analysis
Reverse-logistics infrastructure for take-back programs under Extended Producer Responsibility frameworks is consolidating in Germany and Austria ahead of universal compliance mandates. Raw material sourcing draws from Pacific Northwest timber partnerships for walnut and maple, German and Italian post-industrial timber recovery programs for reclaimed stock, and Japanese bamboo cultivation networks for lightweight performance grades. Single-source vulnerability concentrates in CNC milling equipment for eyewear-scale tolerances, which clusters in Northern Italy and Japan. Distribution runs through direct-to-consumer configurators displacing traditional wholesale showroom relationships, with specialty stores retaining premium positioning in eco-luxury corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wooden eyewear sits at a technology-transition phase where engineered wood composites layered with flax fiber reinforcement are displacing solid hardwood dependency for thin-profile prescription applications.
For Market Incumbents: Acquire CNC milling capacity and hand-finishing expertise concentrated in Northern Italy and Japan to lock in precision manufacturing capabilities. Invest in REACH-certified water-based resin finishing systems ahead of chemical compliance tightening. Consolidate reclaimed wood supply agreements with German and Italian post-industrial timber recovery programs to defend grain uniqueness positioning against bamboo lightweighting specialists. For New Entrants and Emerging Players: Independent opticians in France and Switzerland represent the most penetrable channel, seeking differentiated sustainable frame lines to compete against consolidated retail chains. Target prescription optical expansion with laminated timber expertise for thin-profile temple engineering. Pursue direct-to-consumer launch with fiber laser marking integration enabling made-to-order grain selection at scale. For Investors and Strategic Acquirers: Re-rating potential sits with reclaimed wood specialists possessing established recycling infrastructure given Extended Producer Responsibility framework acceleration across German-speaking markets. Long-term viability favors brands with certified supply chain traceability and digital manufacturing integration. Monitor EU F-Gas Regulation spillover effects on synthetic frame cost structures as an inflection indicator for wooden eyewear shelf-space reallocation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Reclaimed Wood Supply Agreement | Secures distinctive grain patterns from German and Italian post-industrial recovery programs. |
| REACH Certification Investment | Validates plant-based resin systems under EU chemical compliance standards. |
| Direct-to-Consumer Platform Launch | Captures Japanese millennial demand through virtual grain preview configurators. |
| Prescription Optical Channel Expansion | Penetrates French and Swiss independent optician networks seeking differentiation. |
| Extended Producer Responsibility Infrastructure | Pre-positions brands for German and Austrian take-back mandate compliance. |
Study Parameters
Independent corroboration across frame workshop operators, optical retail buyers, forestry certification program administrators, and resin chemistry specialists underwrites the qualitative findings. Primary interviews with CNC equipment manufacturers, independent opticians in France and Switzerland, and brand-operated digital platform managers combined with secondary validation from EU regulatory filings, FDA biocompatibility databases, and forestry stewardship audit records. Bottom-up demand modeling across product type, frame material, and distribution channel segments triangulates against top-down market sizing.
Comparable-period anchoring to historical artisanal production volumes and seasonal replacement cycles in Mediterranean and Japanese resort districts structured the forecast window. Segmentation dimensions modeled include product type, frame material, target audience psychographics, and distribution channel economics across the projection horizon. CAGRs derived from weighted average of demand elasticity parameters, regulatory compliance cost trajectories, and channel shift velocity indicators. Industry-specific inputs encompass REACH chemical restriction timelines and Extended Producer Responsibility framework rollout schedules.
Caveats apply where EU F-Gas Regulation enforcement intensity, climate-driven hardwood harvest disruptions in Pacific Northwest and Balkan regions, or FDA approval timeline extensions for novel wood-resin combinations could materially shift the outlook. Forecasts reflect assumptions around millennial and Gen Z purchasing power retention and artisanal craft network succession planning. Practitioners should monitor German and Austrian regulatory implementation velocity and Japanese digital platform adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Face and Ear Bow Market
Eyewear
Spectacles Market
Eyewear
Blue Light Glasses Market
Eyewear
Eyeglass Market
Eyewear
Europe Eyewear Market
Eyewear
Middle East Eyewear Market
Eyewear
United States Eyewear Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market
Eyewear
Smart Sunglasses Market
Eyewear
Plano Sunglasses Market
Eyewear
Glasses Frame Market
Eyewear
Luxury Eyewear Market
Eyewear
Goggles Market
Eyewear
Sunglasses Pouch Market
Eyewear
Sunglasses Market
Eyewear
Luxury Sunglass Market