
 Mobile Phone Protective Cover Market | 2026-2036
Mobile Phone Protective Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Phone Protective Cover Market Analysis
Chinese injection-molding capacity for thermoplastic polyurethane is hardening as the dominant supply base for mid-range protective covers. OtterBox leverages extensive drop-test certification infrastructure to sustain premium positioning in North American retail channels. Spigen Inc. competes through rapid SKU turnover tied to flagship smartphone release cycles, while Tech21 differentiates via proprietary impact-absorption polymer formulations developed in-house.
Mobile phone protective covers are precision-molded accessories engineered from polymers such as TPU, silicone, polycarbonate, or leather laminates, designed to absorb mechanical shock and prevent cosmetic damage to handheld computing devices. Manufacturing employs dual-shot injection molding or vacuum forming to achieve wall thicknesses between one and three millimeters while maintaining port and button accessibility. Silicone and TPU variants lead volume production due to material elasticity and cost-efficient processing, though leather commands margin concentration in gift and corporate channels. Slim-fit and shockproof feature sets now dominate consumer preference hierarchies, while waterproof configurations remain niche due to sealing complexity and device IP-rating redundancy. Distribution runs through online retail for maximum SKU breadth, though brick-and-mortar still anchors impulse purchases at point-of-sale.
The US Consumer Product Safety Commission and California Proposition 65 framework govern chemical disclosure for phthalate-containing TPU formulations, while the EU REACH regulation restricts SVHC substances in imported accessories. China's SAMR enforces GB standards for electronic product accessory labeling and flame-resistance testing, creating multi-jurisdictional compliance burdens for cross-border sellers. Stakeholders must monitor evolving right-to-repair legislation across US states and European member countries, as device repairability mandates could reduce replacement-driven cover demand or shift design requirements toward tool-free removal compatibility.
Market Dynamics
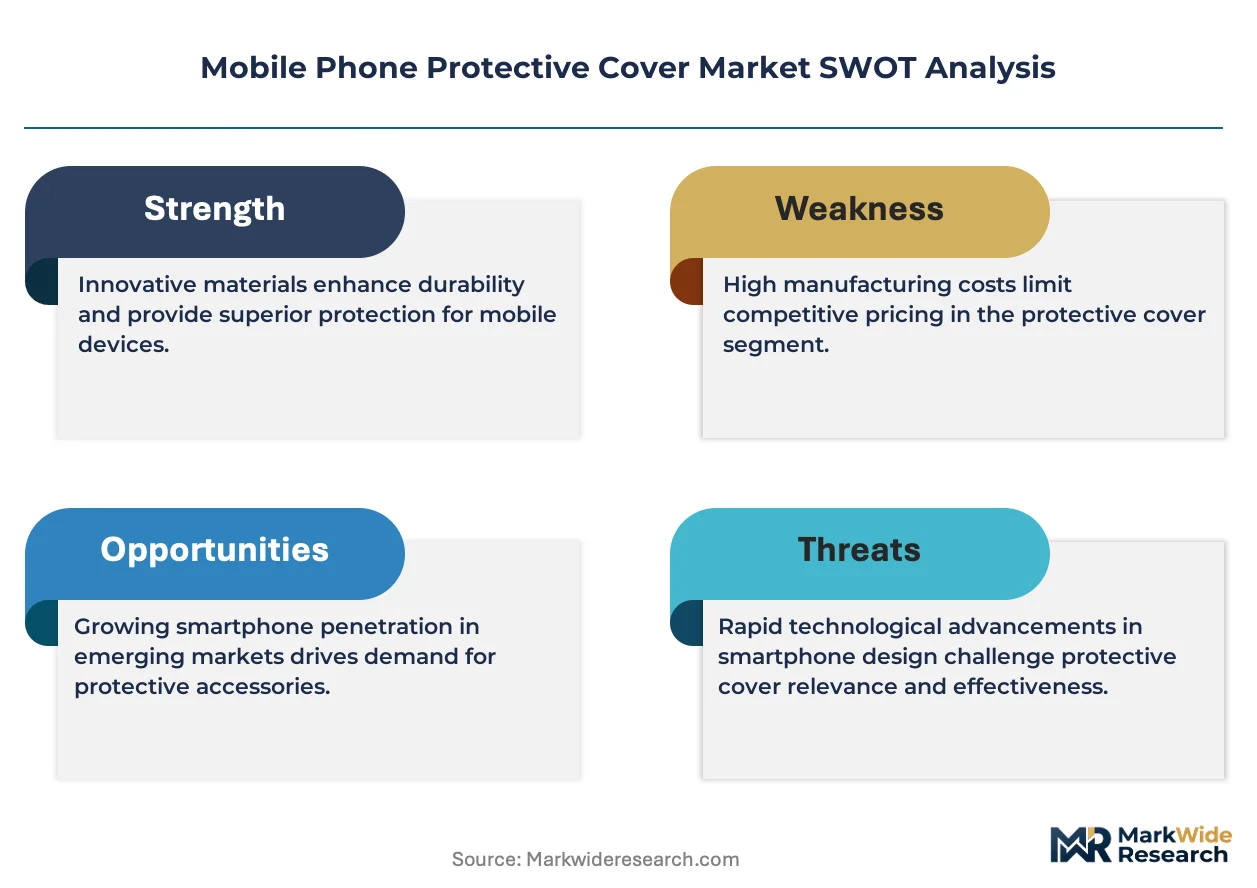
Chinese thermoplastic polyurethane injection-molding capacity has concentrated supply authority for mid-range protective covers, compressing margin structures for Western molders while enabling rapid SKU proliferation tied to flagship smartphone release cycles.
Growth Catalysts
- EU REACH chemical compliance:Stricter SVHC substance restrictions in imported TPU and silicone formulations are accelerating material innovation among compliant suppliers, creating preference pull from safety-conscious European retailers.
- India's urban smartphone penetration:First-time smartphone buyers in Mumbai, Delhi, and Bangalore generate sustained accessory demand through device protection anxiety and social signaling via cover aesthetics.
- Gen Z replacement cycles:Frequent device turnover among younger demographics normalizes cover purchases as standard onboarding behavior, expanding addressable volume beyond warranty-period attachment rates.
Market Restraints
- Crude oil derivative volatility:TPU and polycarbonate feedstock costs fluctuate with petrochemical indices, compressing gross margins for molders without long-term supply contracts or backward integration into resin production.
- Guangdong supply concentration:Overreliance on Shenzhen and Dongguan injection-molding clusters exposes buyers to regional logistics disruptions, power rationing events, and concentrated quality control failures.
- Device IP-rating redundancy:Factory-sealed waterproofing in flagship smartphones eliminates functional differentiation for waterproof cover variants, relegating them to niche outdoor and industrial applications.
Strategic Opportunities
- Right-to-repair mandates:Emerging EU and US state-level device repairability legislation could shift cover design requirements toward tool-free removal compatibility, opening premium positioning for quick-release mechanisms.
- Corporate gift channels:Leather laminate covers command margin concentration in B2B procurement for executive gifting and brand merchandise, with customization services creating switching costs against commodity suppliers.
- Biopolymer convergence:PLA and algae-derived TPU formulations are penetrating sustainability-focused retail channels in Germany and Scandinavia, enabling price premiums through carbon footprint differentiation.
Industry Challenges
- Drop-test certification timelines:Military-standard MIL-STD-810G validation requires 6-12 month laboratory cycles, delaying product launches behind flagship smartphone release windows and compressing sales windows.
- Dual-shot molding skill scarcity:Precision control over TPU-polycarbonate bonding in multi-material covers demands experienced technicians, with training pipelines failing to match Southeast Asian capacity expansion rates.
- Multi-jurisdictional labeling burden:Simultaneous compliance with US CPSC phthalate disclosure, EU REACH SVHC documentation, and China SAMR flame-resistance marking fragments packaging design resources and extends time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Phone Protective Cover Market |
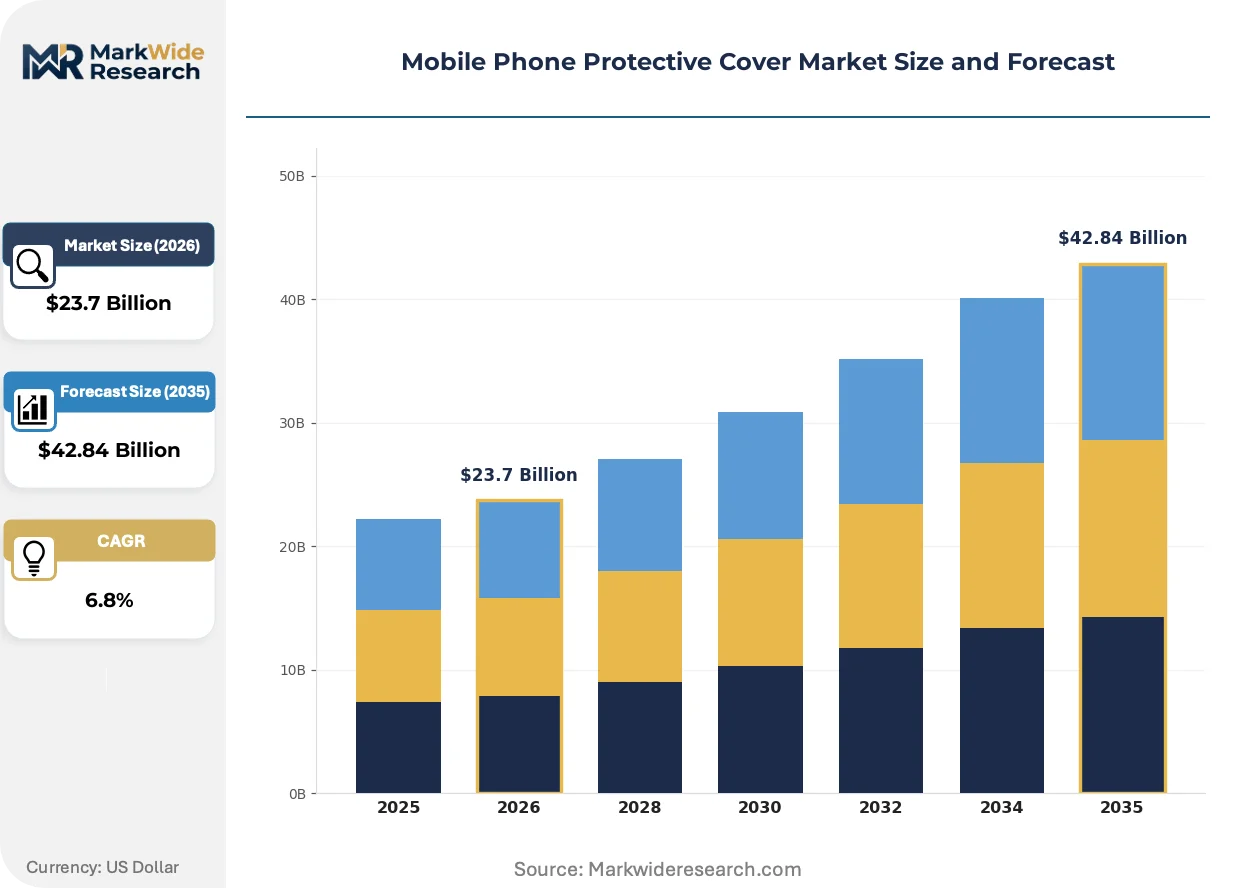
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, TPU, Leather, Hard Shell Feature: Waterproof, Shockproof, Slim Fit, Kickstand Customer Type: Consumers, Businesses, OEMs, Retailers Distribution Channel: Online Retail, Brick-and-Mortar, Wholesale, Direct Sales |
| Companies Covered | OtterBox, Spigen Inc., Incipio LLC, Belkin International, Inc., ZAGG Inc., Griffin Technology, Case-Mate, Inc., Tech21, Urban Armor Gear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Phone Protective Cover Market Emerging Trajectories
Material science advances and regulatory chemical restrictions are compressing traditional silicone dominance while opening premium positioning for engineered polymers with verifiable sustainability credentials.
MagSafe-compatible magnetic arrays embedded in TPU substrates are absorbing accessory ecosystem attachment demand from Apple's supplier-certified program. Third-party molders in Dongguan and Taoyuan are adopting licensed magnet module integration at scale, enabling wireless charging compatibility without case removal. This magnetic integration is absorbing the functional role previously served by adhesive wallet attachments and car mounts, consolidating accessory spend into the cover itself.
California Proposition 65 enforcement against phthalate-containing TPU formulations is forcing reformulation across suppliers serving North American retail channels. The state's chemical disclosure framework now requires warning labels on accessories with DEHP or DBP content above safe harbor levels, triggering supply chain audits by Target, Best Buy, and Amazon. Children's electronics accessory segments face the strictest scrutiny, with several major retailers demanding third-party lab certification prior to purchase order issuance.
Direct-to-consumer subscription models for seasonal cover replacement are disrupting traditional retail attachment economics. Younger buyers in Seoul, Tokyo, and Los Angeles now expect curated colorway drops tied to fashion cycles rather than device releases, with Instagram and TikTok discovery replacing point-of-sale impulse. This behavioral shift is most visible among female consumers aged 18-34, where cover purchasing frequency has decoupled from smartphone replacement intervals entirely.
Mobile Phone Protective Cover Market Segmentation
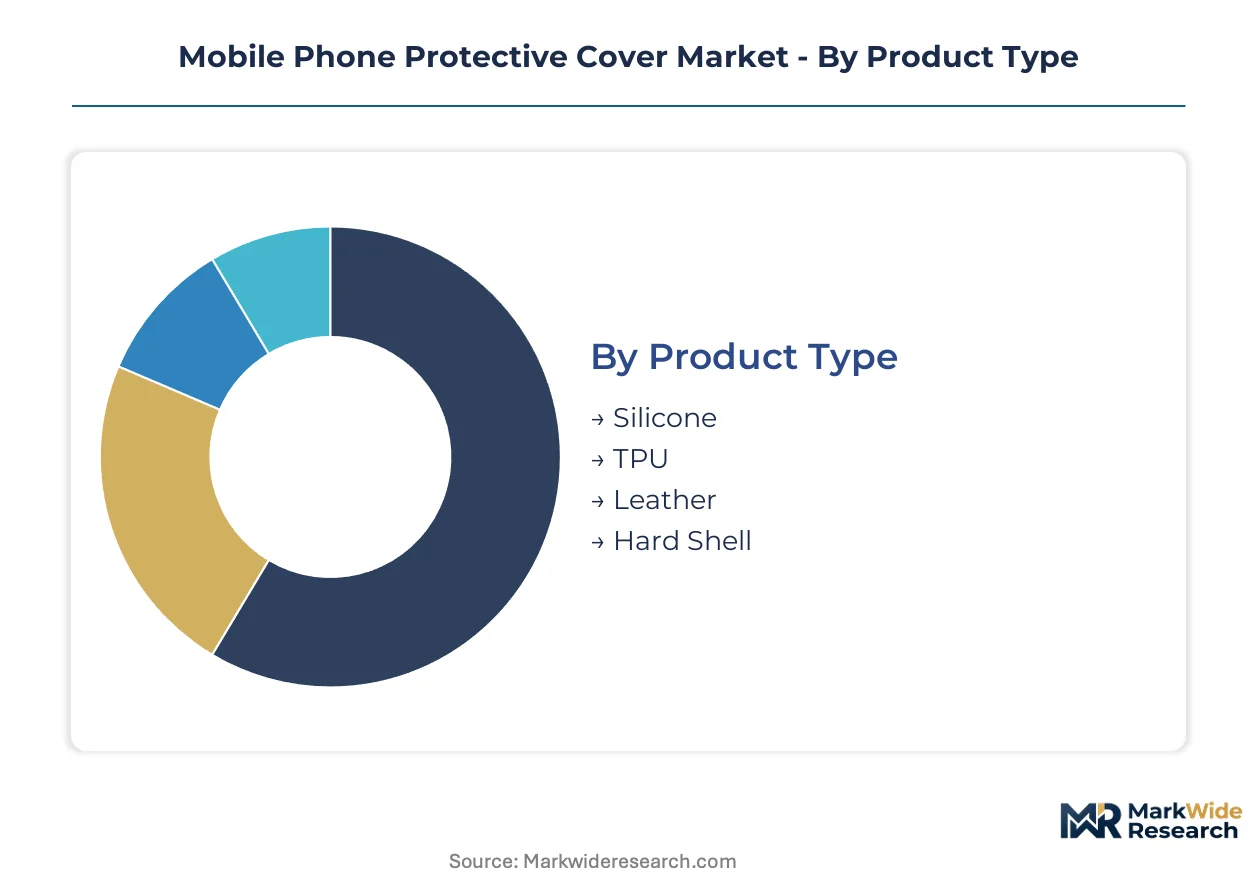
Protective cover purchasing patterns diverge sharply across material preferences, functional requirements, and procurement channels. Upgrade cycles for flagship smartphones create distinct replacement windows that reshape demand concentration within each segment category.
Product Type:
Frequent device turnover among Gen Z and millennial buyers generates repeat purchases tied to each handset upgrade, with material selection increasingly influenced by sustainability credentials and tactile preference rather than pure price minimization.
- Silicone:Injection-molded elastomer formulations deliver grippy surface textures and cost-efficient production at sub-millimeter wall thicknesses. Demand clusters in India's urban centers among first-time smartphone buyers prioritizing basic drop protection at entry price points.
- TPU:Thermoplastic polyurethane enables dual-shot molding with polycarbonate for hybrid rigidity-flexibility combinations. Chinese injection-molding capacity in Shenzhen and Dongguan dominates supply, with EU REACH compliance requirements accelerating reformulation away from phthalate-containing variants.
- Leather:Laminated hide or synthetic alternatives command margin concentration in corporate gift channels and premium retail positioning.
- Hard Shell:Polycarbonate or acrylic single-material constructions serve slim-fit preference hierarchies where bulk minimization outweighs shock absorption.
Silicone sits at the top of the volume ranking, with TPU climbing the fastest as MagSafe-compatible magnetic array integration absorbs accessory ecosystem spend.
Feature:
Functional differentiation now concentrates in physical protection and form-factor optimization rather than environmental sealing, as factory IP ratings in flagship devices reduce cover waterproofing relevance.
- Waterproof:Multi-layer sealing with gasket interfaces and port covers addresses niche outdoor and industrial applications where device submersion exceeds factory ratings.
- Shockproof:Engineered impact-absorption polymers and air-cushion corner geometries target OtterBox-certified drop-test validation for premium North American retail placement.
- Slim Fit:Sub-two-millimeter wall thicknesses with precision port cutouts dominate Seoul, Tokyo, and Los Angeles fashion-cycle purchasing decoupled from device replacement intervals.
- Kickstand:Integrated hinge mechanisms or magnetic fold-out supports consolidate media consumption and video calling utility.
Shockproof configurations hold the volume lead, while slim-fit variants gain share fastest among subscription-model seasonal replacement behavior.
Customer Type:
Procurement authority fragments across individual preference-driven purchasing, bulk B2B customization requirements, and supply-chain integration demands from handset manufacturers.
- Consumers:Individual buyers in Mumbai, Delhi, and Bangalore drive accessory pull through device protection anxiety and social signaling via aesthetic selection.
- Businesses:Corporate procurement of leather laminate covers for executive gifting generates switching costs against commodity suppliers through logo embossing and custom color matching.
- OEMs:Handset manufacturers bundle covers with device sales or certify third-party suppliers for co-branded accessory programs.
- Retailers:Target, Best Buy, and Amazon impose third-party lab certification requirements for California Proposition 65 compliance prior to purchase order issuance.
Consumer purchasing anchors volume, with business procurement expanding most quickly as employer-provided device programs standardize protection accessories.
Distribution Channel:
Channel selection determines SKU breadth exposure, impulse conversion mechanics, and compliance documentation burdens across multi-jurisdictional labeling requirements.
- Online Retail:Maximum SKU breadth enables rapid turnover tied to flagship smartphone release cycles, with Instagram and TikTok discovery replacing point-of-sale impulse among female buyers aged 18-34.
- Brick-and-Mortar:Physical retail anchors impulse purchases at point-of-sale, particularly for emergency replacement following device damage.
- Wholesale:Bulk distribution to regional electronics markets and independent mobile phone shops concentrates in Guangdong supply clusters.
- Direct Sales:Manufacturer-owned channels bypass retailer margin extraction for subscription-model seasonal cover replacement programs.
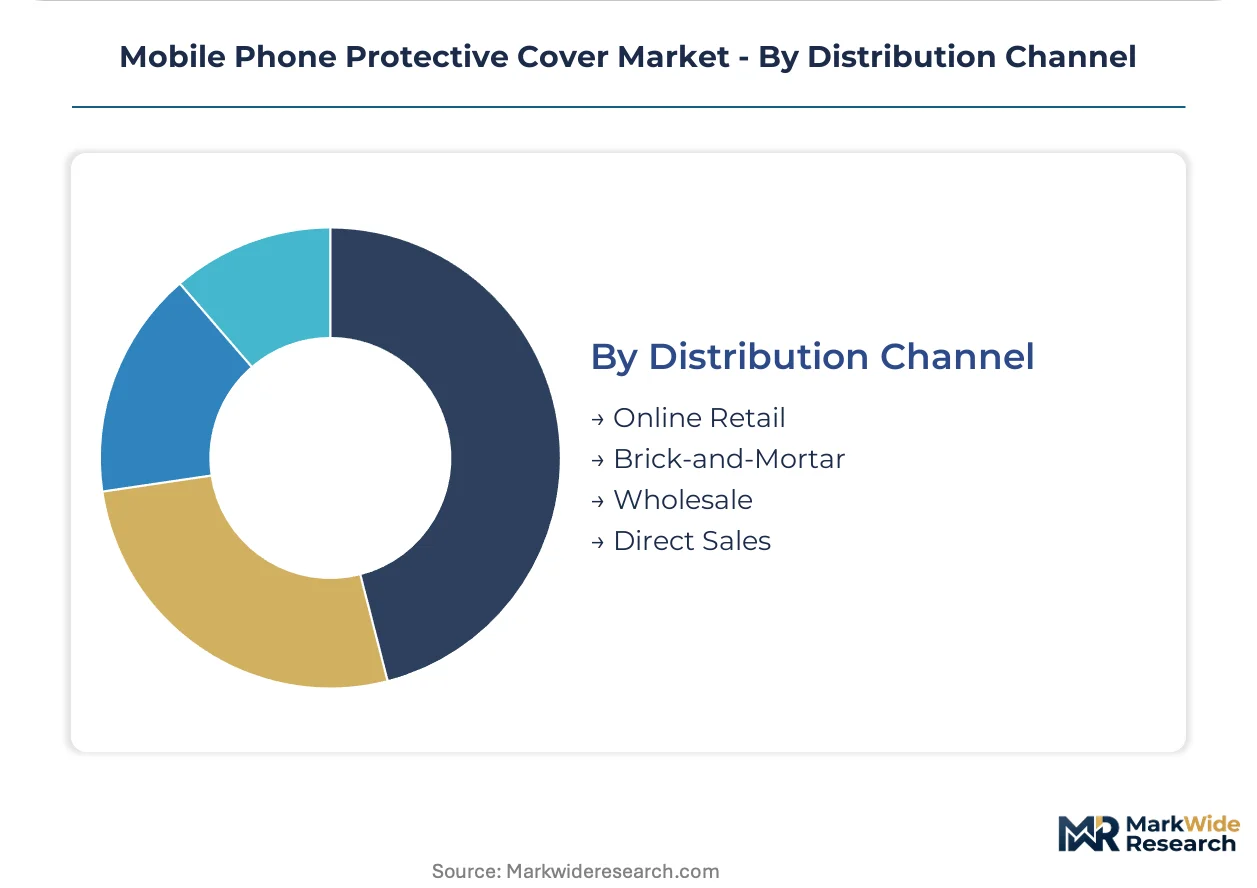
Online retail commands the volume position, with direct sales channels showing the steepest expansion trajectory as curated colorway drops displace traditional retail economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's injection-molding clusters supply mid-range protective covers at compressed margins, while the United States sustains premium-tier certification infrastructure. India's urban smartphone penetration generates sustained accessory pull through first-time buyer protection anxiety. Germany's sustainability-focused retail channels open biopolymer positioning, and Japan's fashion-cycle purchasing decouples cover replacement from device turnover.
United States
California Proposition 65 enforcement drives phthalate-free TPU reformulation across suppliers serving Target and Best Buy procurement channels. The US Consumer Product Safety Commission governs chemical disclosure requirements for children's electronics accessories. Drop-test certification laboratories in California and Texas anchor OtterBox's premium positioning through MIL-STD-810G validation infrastructure.
China
Shenzhen and Dongguan injection-molding capacity concentrates supply authority for thermoplastic polyurethane mid-range covers. The State Administration for Market Regulation enforces GB standards for electronic product accessory labeling and flame-resistance testing. Pearl River Delta clusters absorb MagSafe-compatible magnetic array integration at scale, enabling wireless charging compatibility without case removal.
Germany
PLA and algae-derived TPU formulations penetrate sustainability-focused retail channels in Berlin and Hamburg, enabling carbon footprint price premiums. EU REACH regulation restricts SVHC substances in imported accessories, accelerating compliant material innovation. Bavarian specialty chemical suppliers develop proprietary impact-absorption polymer formulations for premium European positioning.
India
First-time smartphone buyers in Mumbai, Delhi, and Bangalore generate sustained accessory demand through device protection anxiety and social signaling via cover aesthetics. The Bureau of Indian Standards oversees quality certification for electronic accessories entering organized retail. Maharashtra and Karnataka urban centers concentrate silicone cover distribution through regional electronics markets and independent mobile phone shops.
Japan
Fashion-cycle purchasing among female consumers aged 18-34 in Tokyo and Osaka decouples cover replacement from smartphone upgrade intervals entirely. The Ministry of Economy, Trade and Industry monitors chemical safety in consumer electronics accessories through JIS standards alignment. Kanto region direct-to-consumer subscription models pioneer curated colorway drops tied to seasonal fashion cycles rather than device releases.
Mobile Phone Protective Cover Market Vendor Landscape
Chinese producers anchor the high-volume, rapid-SKU tier; North American specialists hold the certification-intensive premium segment. The vendor base splits between consolidated injection-molding capacity in Guangdong and fragmented brand marketers competing on drop-test validation and design differentiation. Three archetypes dominate: scale-driven OEM suppliers, certification-heavy premium brands, and direct-to-consumer fashion-cycle curators. Competitive moves concentrate on backward integration into magnet module sourcing and strategic partnerships with flagship smartphone launch timelines.
Among North American premium-tier specialists, OtterBox and Tech21 exemplify certification-driven positioning archetypes. Spigen Inc. occupies a position within the rapid-SKU, release-cycle-aligned tier. These three named entities represent distinct competitive vectors: extensive drop-test laboratory infrastructure, proprietary polymer formulation development, and agile supply chain responsiveness tied to flagship device launches.
| Leading Market Players |
|---|
| OtterBox |
| Spigen Inc. |
| Incipio LLC |
| Belkin International, Inc. |
| ZAGG Inc. |
| Griffin Technology |
| Case-Mate, Inc. |
| Tech21 |
| Urban Armor Gear |
| Others |
Supply Flow & Price Mechanics
Injection-molding technician scarcity in the Pearl River Delta widens labor-cost differentials between Shenzhen and Dongguan clusters versus emerging Southeast Asian capacity, compressing margin structures at the economy tier while premium certification-grade covers sustain price spreads through OtterBox's California laboratory infrastructure.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for commodity silicone covers, forcing Chinese molders into faster SKU turnover to defend throughput. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-810G validated products from dual-shot TPU-polycarbonate hybrids and single-material injection-molded entry covers. Cost compression in the economy tier intensifies because of petrochemical feedstock volatility and concentrated buyer power at Amazon and Target. First-time smartphone buyers in Indian urban centers exhibit highest price sensitivity, while corporate gift procurement in North America shows least elasticity due to customization switching costs.
Supply Chain Analysis
Single-source vulnerability sits with Shenzhen and Dongguan injection-molding clusters for thermoplastic polyurethane mid-range covers, exposing buyers to regional power rationing and logistics disruption. Raw material dependencies center on petrochemical-derived TPU resin, polycarbonate feedstock, and licensed MagSafe magnet modules sourced through Apple's supplier-certified program. Tariff exposure on Chinese-origin accessories entering US retail channels constitutes the dominant structural risk. Distribution runs through direct-to-consumer subscription platforms for curated seasonal drops, though brick-and-mortar anchors emergency replacement demand at point-of-sale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in protective covers hinges on biopolymer premiumization in EU sustainability channels and backward integration into magnet module sourcing that captures accessory ecosystem spend.
For Market Incumbents: Extend drop-test certification infrastructure into quick-release mechanisms compatible with emerging right-to-repair mandates, defending against unbranded Dongguan competitors exploiting rapid flagship-device launch windows. Deepen backward integration into algae-derived TPU formulation to secure carbon footprint differentiation in German and Scandinavian retail channels. For New Entrants and Emerging Players: Capture corporate gift channel white space through leather laminate customization services with logo embossing and color-matching capabilities that create switching costs against commodity suppliers. Target India's organized retail penetration in Maharashtra and Karnataka through BIS-certified silicone cover distribution partnerships with regional electronics market aggregators. For Investors and Strategic Acquirers: Specialty chemical suppliers with proprietary impact-absorption polymer IP are the most active acquirer in this space, consolidating formulation capabilities ahead of EU REACH SVHC restriction tightening. Long-term viability favors targets with dual competence in certified premium positioning and agile release-cycle responsiveness. Monitor California Proposition 65 enforcement patterns as inflection indicator for phthalate-free reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Formulation Development | PLA and algae-derived TPU penetration in German sustainability-focused retail enables carbon footprint price premiums. |
| MagSafe Module Integration | Licensed magnet array adoption in Dongguan clusters consolidates wireless charging accessory spend into cover purchases. |
| Quick-Release Mechanism R&D | Tool-free removal compatibility aligns cover design with EU and US state-level right-to-repair legislative trajectories. |
| Corporate Gift Channel Expansion | Leather laminate customization with logo embossing creates switching costs against commodity suppliers in B2B procurement. |
| Direct-to-Consumer Subscription Launch | Curated seasonal colorway drops in Seoul and Los Angeles decouple purchasing frequency from device replacement intervals. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with injection-molding plant managers, procurement leads at Target and Best Buy, TPU resin technical R&D directors, and aftermarket distribution channel partners. Secondary validation draws from US CPSC filings, EU ECHA SVHC candidate list updates, China SAMR GB standard publications, and SEC 10-K disclosures from listed accessory vendors. Bottom-up volume modeling triangulates against top-down addressable smartphone installed base estimates.
Granularity-level framing applies country-specific pricing tiers, material formulation categories, feature sets, and distribution channel splits across the projection horizon. CAGRs derive from segment-level volume build-ups applied to price trajectory assumptions. Forecast inputs include flagship smartphone release cycle timing, petrochemical index correlation models, and regulatory compliance cost pass-through elasticity.
Crude oil derivative volatility, Guangdong cluster disruption events, and right-to-repair legislative acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on replacement cycle decoupling and biopolymer adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Personal Flotation Devices Market
Protective Gear
Work Shoes Market
Protective Gear
Helmet Lining Market
Protective Gear
Global Mobile Phone Protective Cases Market
Protective Gear
Food Processing Uniforms Market
Protective Gear
Combat Boots Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Diving Suits Market
Protective Gear
Waterproof Boots Market
Protective Gear
UK Mobility Devices Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Flavored Condoms Market
Protective Gear
Military Boots Market
Protective Gear
Goalkeeper Gloves Market
Protective Gear
Antistatic Protection Shoes Market
Protective Gear
Cooking Gloves Market