
 Goggles Market | 2026-2036
Goggles Market Size, Share, and Industry Trends Forecast 2026-2036
Goggles Market Insights
A shift from single-source optical supply toward multi-source procurement is rebalancing how goggle manufacturers secure lens substrates and frame polymers. EssilorLuxottica leverages captive resin production to control cost volatility across its eyewear portfolio. Hoya Corporation anchors its position through deep R&D intensity in optical coatings. Carl Zeiss AG competes on precision surfacing capabilities that extend into tactical and industrial segments.
Goggles are tight-sealing eyewear devices engineered with impact-resistant polycarbonate or Trivex lenses, elastomeric frames, and indirect ventilation systems to protect against particulates, chemicals, UV radiation, and ballistic threats. Primary purposes span occupational hazard mitigation, underwater visibility enhancement, and low-light tactical operations. Safety goggles dominate value pools where ANSI Z87.1 and EN 166 compliance commands premium positioning, while ski and swim variants occupy thinner margin tiers despite higher unit volumes. Photochromic lens technology leads growth trajectories as athletes and industrial workers demand adaptive visible-light transmission without dual-lens swapping.
OSHA mandates in the United States, EN 166 standards enforced across Europe, and GB 14866 requirements in China shape product certification pathways and factory audit obligations for exporters. The EU PPE Regulation and forthcoming CSRD disclosure rules add compliance layers that favor scaled manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor convergence between occupational safety standards and consumer sports certifications, as dual-use positioning opens channel access but risks specification over-engineering.
Market Dynamics
Photochromic lens chemistry is converging with anti-fog nanocoatings to create adaptive eyewear that eliminates dual-lens inventory for industrial and athletic users alike.
Growth Catalysts
- OSHA Impact Mandates:Tightened lens impact standards under 29 CFR 1910.133 are forcing manufacturing facilities to upgrade from basic safety glasses to sealed-frame goggles, expanding the addressable base for ANSI Z87.1-certified products.
- Winter Sports Infrastructure:China is deploying ski resorts at scale in Hebei and Jilin provinces, creating concentrated demand for UV-blocking snow goggles with interchangeable magnetic lenses.
- Polycarbonate Resin Advances:Optical-grade polycarbonate with Abbe number improvements above 30 is reducing chromatic aberration, enabling thinner lens profiles without sacrificing ballistic resistance.
Market Restraints
- Crude-Derived Feedstock Volatility:Bisphenol A and phosgene prices track naphtha spreads, compressing margin predictability for injection-molded frame producers locked into annual supply agreements.
- East Asian Mold Concentration:Precision optical mold fabrication clusters in Dongguan and Taichung, creating single-source vulnerability for European and North American goggle assemblers.
- Photochromic Kinetics Limitation:Current organic photochromic dyes require 60-90 seconds for full darkening at 23°C, failing to meet military specifications for rapid light-adaptation in tactical environments.
Strategic Opportunities
- India Industrial PPE Gap:Factory Safety Act enforcement remains patchy outside Maharashtra and Gujarat, leaving 40 million unprotected metalworking and chemical processing workers as a greenfield conversion target.
- EU CSRD Disclosure Alignment:Large goggle manufacturers can capture sustainability procurement preference by certifying recycled polymer content and Scope 3 emissions transparency ahead of 2027 reporting deadlines.
- Augmented Reality Convergence:Waveguide optics integration with industrial safety frames is enabling hands-free assembly guidance, opening premium pricing tiers beyond passive eye protection.
Industry Challenges
- Optical Coating Technician Scarcity:Vacuum deposition and plasma-enhanced chemical vapor deposition expertise concentrates in Japan and Germany, constraining capacity expansion for anti-reflective and hardcoat stack production.
- Dual-Certification Timeline Compression:Achieving concurrent EN 166 and ANSI Z87.1 approval requires 14-18 months of sequential testing, delaying product launches for multi-region distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Goggles Market |
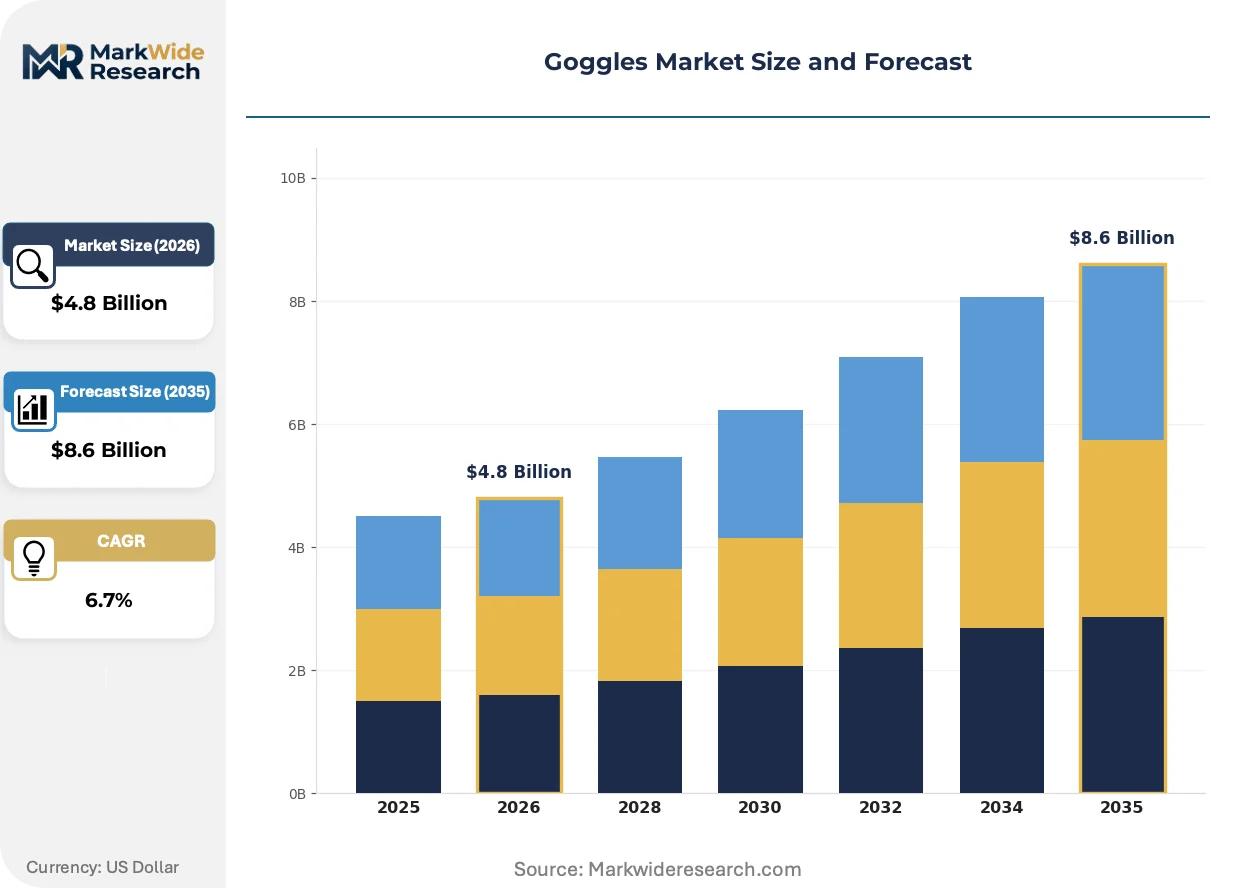
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Goggles, Swim Goggles, Ski Goggles, Night Vision Goggles End User: Industrial Workers, Athletes, Military Personnel, Recreational Users Lens Technology: Polarized, Anti-Fog, Photochromic, UV Protection Application: Sports, Occupational Safety, Tactical Use, Recreational Activities |
| Companies Covered | EssilorLuxottica, Hoya Corporation, The Cooper Companies, Bausch + Lomb, Carl Zeiss AG, Safilo Group, Fielmann AG, Johnson & Johnson Vision Care, Alcon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Goggles Market Trends and Innovations
Materials science breakthroughs in surface engineering and adaptive optics are compressing product refresh cycles while regulatory disclosure requirements are reshaping procurement criteria for institutional buyers.
Electrochromic thin-film technology is converging with liquid crystal shutter systems to enable millisecond-scale visible-light transmission adjustment in tactical and motorsport applications. Special forces units in Germany and competitive cycling teams in Italy are piloting these systems for variable-light environments. This convergence is collapsing the distinction between fixed-tint and photochromic product lines, forcing manufacturers to consolidate R&D roadmaps.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating long-chain fluorinated coatings historically used for oleophobic lens treatments. EU-based goggle producers are reformulating with short-chain fluorinated alternatives and ceramic nanoparticle overlays, adding 8-12 months to product recertification timelines. Industrial safety distributors in France and the Netherlands are prioritizing inventory positions with compliant coating stacks ahead of 2025 enforcement windows.
Institutional procurement through integrated suppliers is displacing direct manufacturer relationships for mid-sized manufacturing plants. Safety distributors like W.W. Grainger and RS Components are bundling goggles with respiratory and hearing protection under consolidated vendor-managed inventory programs. This channel consolidation is most pronounced in the United States Midwest automotive supply chain, where tier-two stamping plants now specify single-source PPE contracts spanning 50+ SKUs.
Goggles Market Segmentation
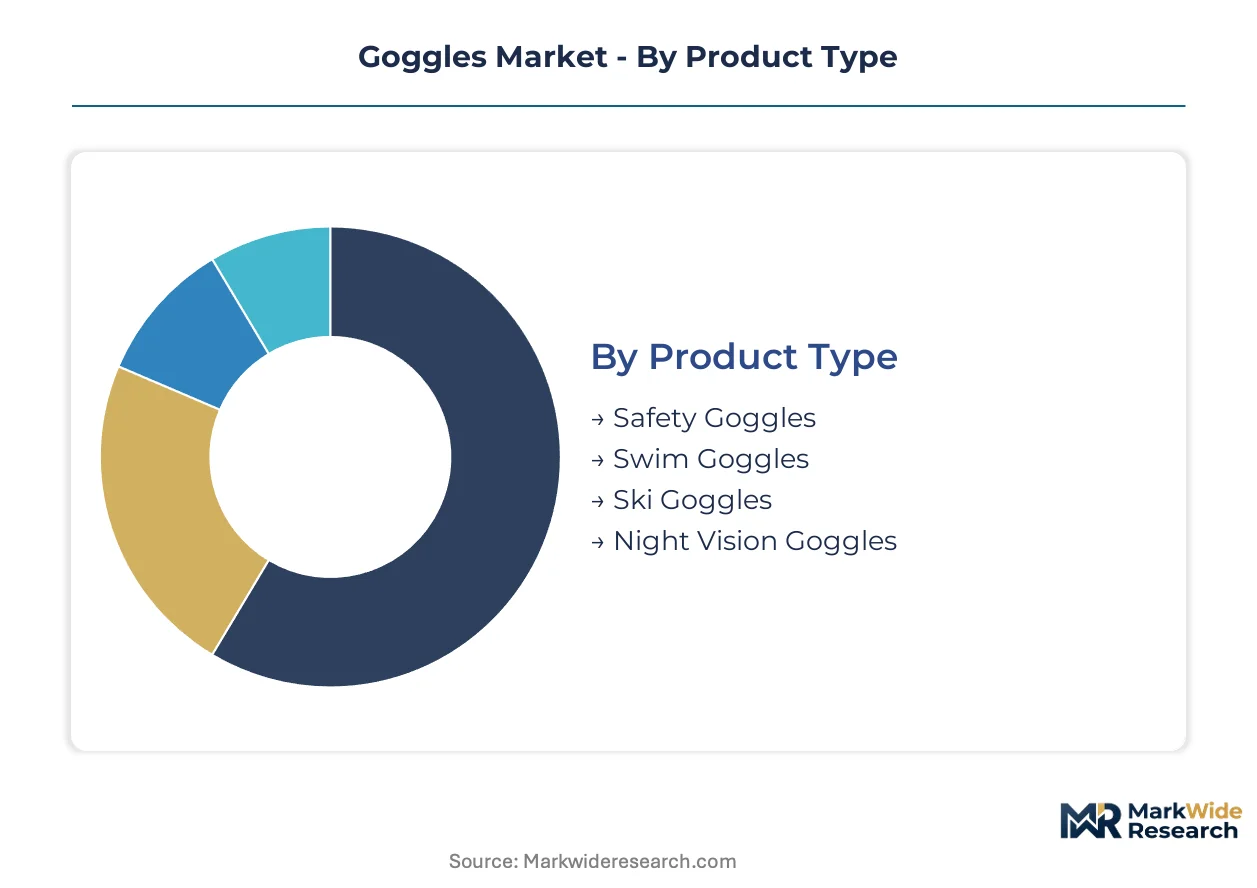
Certification requirements fragment the goggles market into distinct compliance tiers, with industrial safety mandates creating the highest barrier to entry while recreational segments compete on feature differentiation. Understanding how lens technologies and end-use specifications map to regulatory pathways enables manufacturers to prioritize R&D investment and channel strategy.
Product Type:
ANSI Z87.1 and EN 166 certifications dominate industrial safety procurement, while ski and swim variants navigate voluntary standards frameworks that emphasize optical clarity and hydrodynamics over impact resistance.
- Safety Goggles:Sealed-frame designs with indirect ventilation systems and polycarbonate lenses meeting ballistic impact specifications. Demand concentrates in United States manufacturing facilities upgrading from basic safety glasses under OSHA 29 CFR 1910.133 mandates, with premium pricing tied to dual-certification achievement.
- Ski Goggles:Cylindrical or spherical dual-lens constructions with anti-fog coatings and magnetic interchange systems. China’s Hebei and Jilin province resort developments are absorbing volume for UV-blocking snow variants with visible light transmission ratings spanning 9% to 43%.
- Swim Goggles:Hydrodynamic silicone gaskets with polycarbonate lenses and anti-fog surfactant treatments. Competitive swimming federations and recreational aquatic centers drive replacement cycles.
- Night Vision Goggles:Image intensifier tube or thermal sensor integration with ballistic-rated housings. Military procurement through Germany and United States defense channels sustains specialized manufacturing capacity.
Leading the category by volume: Safety Goggles. Growing fastest: Ski Goggles.
End User:
Procurement authority and specification complexity vary sharply across user types, from centralized industrial safety departments to individual athlete purchasing decisions.
- Industrial Workers:Mandatory PPE programs in chemical processing, metal fabrication, and construction drive bulk purchasing through integrated distributors. United States OSHA enforcement and China GB 14866 implementation are expanding protected worker populations.
- Military Personnel:Ballistic fragmentation and laser threat specifications from United States Army PEO Soldier and German BAAINBw govern development roadmaps. Extended product lifecycles contrast with commercial segments.
- Athletes:Performance optimization demands from competitive cycling, swimming, and skiing federations prioritize optical precision and weight reduction over durability metrics.
- Recreational Users:Price-sensitive purchasing through mass retail and direct-to-consumer channels, with brand marketing and aesthetic differentiation driving selection.
Dominating procurement value: Industrial Workers. Expanding most quickly: Athletes.
Lens Technology:
Coating stack complexity and materials science intensity determine manufacturing yield and pricing power across optical performance tiers.
- Photochromic:Organic dye-embedded or inorganic halide glass formulations enabling adaptive visible light transmission. Current 60-90 second transition kinetics limit military adoption despite strong athletic and industrial demand for dual-environment utility.
- Anti-Fog:Hydrophilic surfactant coatings or forced-air ventilation systems preventing moisture condensation. REACH Annex XVII fluorinated compound restrictions are forcing coating reformulation cycles in EU production.
- Polarized:Polyvinyl alcohol film lamination blocking polarized glare from reflective surfaces. Maritime and snow applications anchor volume.
- UV Protection:Ultraviolet-absorbing monomer integration in polycarbonate substrates blocking 99-100% of UVA/UVB radiation. Baseline requirement across all premium product tiers.
Commanding premium pricing: Photochromic. Gaining share fastest: Anti-Fog.
Application:
Use-case specificity dictates frame geometry, ventilation architecture, and the regulatory compliance burden manufacturers must absorb.
- Occupational Safety:Chemical splash, dust, and impact hazards drive sealed-frame designs with ANSI Z87.1+ and EN 166 certification requirements. Institutional procurement consolidation through W.W. Grainger and RS Components is compressing distributor margins.
- Tactical Use:Ballistic fragmentation, laser eye protection, and night vision compatibility specifications from United States and German defense procurement channels. Low-volume, high-margin production with extended qualification timelines.
- Sports:Aerodynamic profiling, interchangeable lens systems, and helmet integration features for cycling, skiing, and swimming disciplines.
- Recreational Activities:General-purpose eye protection for hiking, water sports, and motorcycling with fashion-forward frame designs.
Generating highest revenue per unit: Tactical Use. Steepest expansion trajectory: Sports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bisphenol A and polycarbonate resin production clusters in the United States Gulf Coast and China's Yangtze River Delta anchor raw-material supply for goggle manufacturers serving industrial and consumer segments.
United States
OSHA enforcement of 29 CFR 1910.133 mandates is accelerating facility upgrades from safety glasses to sealed-frame goggles across Midwest automotive stamping plants and Gulf Coast chemical processing complexes. The Department of Labor's inspection prioritization in Ohio and Michigan metalworking corridors is expanding protected worker populations. Houston and Baton Rouge petrochemical clusters supply optical-grade polycarbonate resin to frame injection molders serving ANSI Z87.1-certified product lines.
China
Hebei and Jilin province ski resort developments are absorbing UV-blocking snow goggles with magnetic interchange systems for domestic winter sports infrastructure. GB 14866 implementation by SAMR is tightening industrial PPE compliance in Guangdong and Jiangsu manufacturing belts. Dongguan's precision optical mold fabrication cluster remains the dominant source for frame tooling serving both domestic brands and export-oriented assemblers.
Germany
BAAINBw tactical procurement specifications for ballistic fragmentation and laser eye protection sustain specialized manufacturing in Bavaria and Baden-Württemberg. EN 166 certification requirements enforced by national market surveillance authorities shape product development roadmaps for industrial safety exporters. The Stuttgart precision optics corridor hosts vacuum deposition expertise for anti-reflective coating stacks.
India
Maharashtra and Gujarat metalworking facilities represent conversion opportunities as Factory Safety Act enforcement gradually extends beyond current strongholds. BIS certification pathways for protective eyewear remain underdeveloped relative to industrial accident rates in chemical processing zones. Pune and Ahmedabad industrial clusters currently rely on imported safety goggles due to limited domestic optical coating capacity.
Japan
METI-supported R&D programs in optical coatings advance photochromic kinetics and anti-fog nanotechnology for athletic and industrial applications. JIS standards for protective eyewear create parallel certification requirements for exporters serving domestic institutional procurement. The Chubu region around Nagoya concentrates plasma-enhanced chemical vapor deposition expertise constraining regional capacity expansion.
Goggles Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to secure lens substrate supply and coating technology access without captive production investment. The vendor base separates into three tiers: integrated optical conglomerates with resin-to-retail control, specialized coating houses licensing surface engineering IP, and regional assemblers dependent on outsourced component supply. Two strategic archetypes have emerged: upstream-integrated players controlling polycarbonate resin production, and downstream-focused brands leveraging distributor consolidation for channel access. M&A activity and technology licensing agreements represent the primary competitive vectors as firms address coating technician scarcity and dual-certification timeline pressures.
Among integrated optical conglomerates, EssilorLuxottica, Hoya Corporation, and Carl Zeiss AG occupy positions spanning lens substrate production through finished eyewear distribution. EssilorLuxottica exemplifies the captive resin production archetype, leveraging backward integration into polymer supply to manage cost volatility across eyewear portfolios. Hoya Corporation sits within the deep R&D intensity tier, anchoring competitive positioning through optical coating expertise concentrated in Japanese manufacturing corridors. Carl Zeiss AG represents precision surfacing capabilities extending from consumer optics into tactical and industrial segments requiring ballistic-rated specifications. These three firms collectively illustrate how control over distinct value chain segments—resin, coatings, or precision finishing—shapes strategic options in a market fragmented by certification requirements and end-use specialization.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Hoya Corporation |
| The Cooper Companies |
| Bausch + Lomb |
| Carl Zeiss AG |
| Safilo Group |
| Fielmann AG |
| Johnson & Johnson Vision Care |
| Alcon |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ANSI Z87.1-plus industrial safety goggles and basic impact-rated eyewear manifests in divergent pricing power and supply chain depth. Premium-tier manufacturers command captive resin production and dedicated coating capacity, while commodity assemblers remain exposed to spot-market polycarbonate volatility and outsourced optical stack procurement.
Pricing Analysis
Warranty and service bundling separate premium industrial safety distributors from unbundled mass retail channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity, with dual-certified ANSI Z87.1 and EN 166 products commanding sustained premiums over single-standard alternatives. Price differentiation rests on coating stack durability guarantees and vendor-managed inventory programs. Cost compression in economy-tier swim and recreational variants is intensifying because of raw material pass-through clauses in annual supply agreements. Small manufacturing plants in the United States Midwest exhibit highest price sensitivity, while military procurement through German BAAINBw and United States Army PEO Soldier demonstrates lowest sensitivity due to specification rigidity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from integrated safety distributors, while specialty optical retailers serve fragmented athletic and recreational segments. Geographic supply concentration centers on China's Dongguan precision mold cluster, Germany's Stuttgart optical corridor, and Japan's Chubu coating equipment belt. Raw material dependencies draw from United States Gulf Coast bisphenol A production, Chinese Yangtze River Delta polycarbonate resin, and Japanese plasma-enhanced chemical vapor deposition chambers. Single-source vulnerability in precision optical mold fabrication constrains European and North American frame assemblers. Distribution runs through consolidated PPE distributors bundling goggles with respiratory and hearing protection under multi-year vendor-managed inventory contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as dual-certification timeline compression and coating technician scarcity force sub-scale manufacturers toward exit or acquisition. Regulatory disclosure requirements ahead of EU CSRD enforcement favor scaled players with dedicated compliance infrastructure.
For Market Incumbents: Acquire vacuum deposition and plasma-enhanced chemical vapor deposition expertise to internalize anti-reflective and hardcoat stack production. EssilorLuxottica's captive resin model and Hoya Corporation's coating R&D intensity illustrate how upstream control defends margin position against feedstock volatility. Secure dedicated regulatory affairs capacity to compress EN 166 and ANSI Z87.1 approval timelines from 18 months toward 12 months.
For New Entrants and Emerging Players: Unprotected metalworking and chemical processing workers in Maharashtra and Gujarat represent the most penetrable buyer archetype as Factory Safety Act enforcement gradually extends beyond current strongholds. Target this greenfield conversion opportunity with GB 14866-compliant product lines priced below imported alternatives. Pursue direct relationships with state-level industrial safety inspectors to accelerate specification adoption ahead of distributor consolidation.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated optical conglomerates seeking coating technology access or regional assemblers requiring certification expertise. Long-term viability over the analysis window favors targets with established dual-certification achievement and dedicated regulatory affairs teams. Watch for inflection when REACH Annex XVII fluorinated compound enforcement accelerates coating reformulation cycles, favoring acquirers with compliant stack production already scaled.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Coatings | Captures margin from Japanese and German coating houses while securing capacity against technician scarcity. |
| Dual-Certification Fast-Track Investment | Compresses 18-month EN 166 and ANSI Z87.1 timelines to accelerate product launches for multi-region distributors. |
| India Industrial PPE Market Entry | Targets 40 million unprotected workers in Maharashtra and Gujarat as Factory Safety Act enforcement expands. |
| EU CSRD Disclosure Alignment | Captures sustainability procurement preference by certifying recycled polymer content ahead of reporting deadlines. |
| Augmented Reality Safety Frame Development | Opens premium pricing tiers through waveguide optics integration enabling hands-free assembly guidance. |
Research Methodology
Multi-period observation of certification achievement timelines, coating technology adoption curves, and procurement consolidation patterns anchored the trend analysis, supplemented by interviews with plant safety managers at Midwest automotive stamping facilities, procurement leads at integrated PPE distributors, optical coating R&D directors in Japan and Germany, regulatory affairs specialists navigating EN 166 and ANSI Z87.1 pathways, and SAMR enforcement officers in Guangdong manufacturing belts. Secondary validation drew from OSHA enforcement action databases, EU PPE Regulation implementation reports, customs records tracking polycarbonate resin trade flows, SEC filings of listed eyewear manufacturers, and GB 14866 compliance audit disclosures. Bottom-up demand modeling across industrial, military, athletic, and recreational user segments was triangulated against top-down market sizing from raw material consumption patterns.
Segment-weighting across product type, end user, lens technology, and application dimensions shaped volume and value allocation throughout the forecast period. Modeled dimensions included certification tier, procurement channel structure, coating stack complexity, and regional regulatory enforcement intensity. CAGRs were derived from regression analysis of historical certification-driven replacement cycles and projected enforcement expansion. Industry-specific forecast inputs incorporated OSHA inspection prioritization patterns in Ohio and Michigan, Hebei and Jilin ski resort development timelines, and BAAINBw tactical procurement specifications.
Revisions become necessary when photochromic kinetics breakthroughs eliminate military adoption barriers, when REACH Annex XVII enforcement accelerates coating reformulation failures, or when integrated distributor consolidation crosses threshold concentration levels. Forecasts reflect assumptions regarding regulatory enforcement continuity, raw material supply stability, and certification standard harmonization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Smart Eyewear Market
Eyewear
Plano Sunglasses Market
Eyewear
United States Eyewear Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Sunglasses Pouch Market
Eyewear
Europe Eyewear Market
Eyewear
Luxury Eyewear Market
Eyewear
Asia-Pacific Eyewear Market
Eyewear
Eyeglass Market
Eyewear
Middle East Eyewear Market
Eyewear
Polarized Sunglasses Market
Eyewear
Sunglasses Market
Eyewear
Wooden Eyewear Market
Eyewear
Smart Sunglasses Market
Eyewear
Blue Light Glasses Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market