
 Plano Sunglasses Market | 2026-2036
Plano Sunglasses Market Size, Share, and Industry Trends Forecast 2026-2036
Plano Sunglasses Market Analysis
Subscription-based lens replacement and software-enabled virtual try-on services is shifting how retailers monetize plano sunglasses beyond the initial transaction. EssilorLuxottica leverages its vertically integrated optical labs to bundle plano frames with blue-light filtering upgrades. Warby Parker sustains direct-to-consumer channel control through home try-on logistics and tele-optometry integration. Marchon Eyewear anchors wholesale relationships with department stores and independent opticians across multiple continents.
Plano sunglasses are non-prescription eyewear constructed from injection-molded acetate, stamped metal alloys, or machined titanium, featuring tinted or coated lenses that block ultraviolet radiation and reduce visible glare for cosmetic and protective outdoor use. Polarized lenses command premium positioning in coastal and alpine markets where glare reduction delivers functional differentiation, while photochromic variants bridge indoor-outdoor use cases for urban commuters. Metal frames, particularly titanium, occupy the highest margin tier due to material cost and precision machining requirements, whereas plastic dominates unit volume through fashion-forward colorways and lower price accessibility.
The US Food and Drug Administration classifies plano sunglasses as Class I medical devices requiring impact resistance testing under 21 CFR 801.410, while the EU's REACH regulation restricts phthalates and heavy metals in frame materials, compelling reformulation of traditional cellulose acetate. China's State Administration for Market Regulation enforces GB 10810.3 lens standards for transmittance and optical power deviation, shaping export compliance costs for overseas brands. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and California that will soon mandate recycling infrastructure for eyewear components.
Market Dynamics
REACH compliance costs are restructuring acetate supply chains, forcing frame manufacturers to abandon traditional cellulose acetate formulations and absorb premium pricing for bio-based alternatives certified under ECHA's Substance of Very High Concern protocols.
Growth Catalysts
- UV protection mandates:Australia's Therapeutic Goods Administration requires Category 2 or higher UV400 labeling for all sunglasses, expanding baseline demand for certified lenses across Oceania export markets.
- Photochromic lens chemistry:Advances in silver halide microcrystalline embedding enable faster darkening speeds, attracting urban commuters seeking single-pair indoor-outdoor solutions.
- Middle-class consumption clusters:Tier-2 Chinese cities including Chengdu and Hangzhou are outpacing coastal metros in per-capita plano eyewear spending through live-stream commerce channels.
Market Restraints
- Titanium feedstock volatility:Sponge titanium prices fluctuate with aerospace allocation priorities, compressing margins for precision-machined frame tiers dependent on Japanese Kobe Steel supply.
- Acetate reformulation timelines:ECHA's authorization requirements for plasticizers extend new material qualification cycles to 18-24 months, freezing product pipelines.
- Polarized film concentration:Nitto Denko and Sumitomo Chemical control 70%+ of PVA polarizing film supply, creating single-source vulnerability for lens assemblers.
Strategic Opportunities
- Extended producer responsibility frameworks:California's SB 54 implementation will mandate eyewear take-back infrastructure by 2032, creating first-mover advantage for closed-loop recycling operators.
- AR-enabled virtual fitting:Convergence of LiDAR facial scanning and real-time ray-traced lens simulation enables zero-inventory retail models.
- Alpine sports specialization:Glacier-certified Category 4 lenses remain underpenetrated in North American ski resort retail relative to European alpine markets.
Industry Challenges
- Optical metrology talent scarcity:ISO 12312-1 certification testing requires wavefront aberration analysis capabilities concentrated in German and Japanese metrology labs.
- Multi-jurisdiction labeling complexity:Simultaneous FDA 21 CFR, CE marking, and GB 10810.3 compliance demands parallel documentation streams with conflicting symbol protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plano Sunglasses Market |
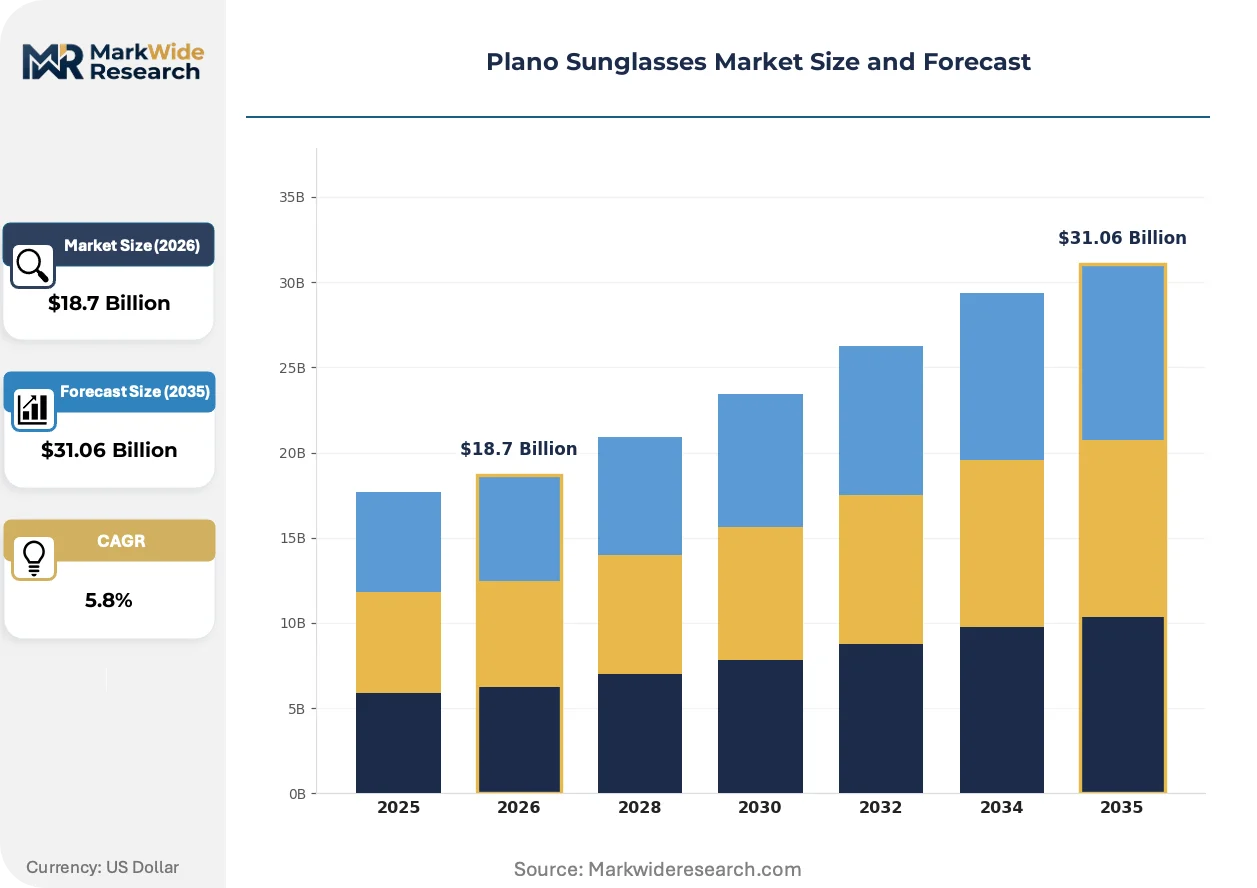
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Frame Material: Plastic, Metal, Wood, Titanium Lens Type: Polarized, Photochromic, Mirrored, Gradient Style: Aviator, Wayfarer, Cat Eye, Round Target Audience: Men, Women, Children, Athletes |
| Companies Covered | Marchon Eyewear, DE RIGO REM, EssilorLuxottica, Ray-Ban, Silhouette International, Safilo Group, Marcolin, Warby Parker, Luxottica Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plano Sunglasses Market Emerging Trajectories
Bio-based material substitution and software-enabled retail experiences are compressing traditional manufacturing and distribution hierarchies simultaneously. These shifts favor capital-light brands capable of rapid formulation iteration and direct consumer data capture.
Cellulose diacetate derived from sustainably harvested wood pulp is consolidating position as the primary alternative to petroleum-based frame substrates. Italian compounders including Mazzucchelli 1849 have scaled production of this material to commercial volumes. Premium fashion houses are absorbing 15-20% material cost premiums to secure ECHA-compliant supply chains.
REACH Annex XVII restrictions on phthalate plasticizers are compelling frame molders to validate citrate-based alternatives through migration testing protocols. The regulation's 2025 enforcement deadline is accelerating reformulation investments ahead of compliance windows. Small-batch acetate producers in Jura Valley manufacturing clusters face disproportionate qualification burdens relative to integrated chemical compounders.
Subscription lens replacement programs are capturing recurring revenue from fashion-forward consumers who treat frames as durable accessories. Direct-to-consumer platforms displace seasonal wholesale pre-orders with data-driven inventory positioning. This pattern concentrates in US coastal metros where tele-optometry laws permit remote prescription verification for blue-light upgrade attachments.
Plano Sunglasses Market Segmentation
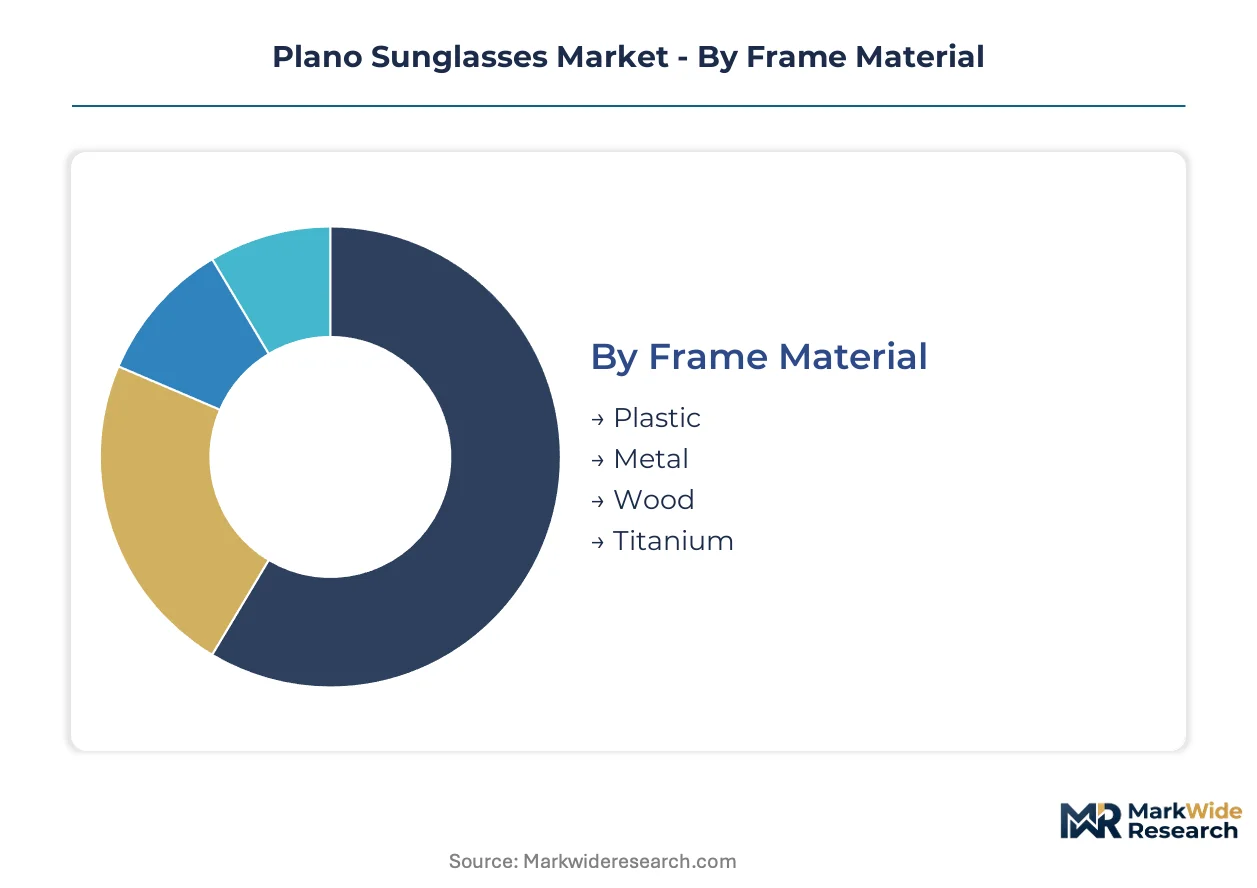
Frame material chemistry and lens functionality differentiate margin structures and compliance burdens across the plano sunglasses value chain. Style preferences cluster by demographic cohort, while target audience selection determines channel strategy and pricing architecture.
Frame Material:
Cost tier separates mass-market accessibility from precision-machined premium positioning.
- Plastic:Injection-molded cellulose acetate and propionate dominate unit volumes through fashion-forward colorways and sub-$50 retail accessibility. China's injection molding clusters in Wenzhou and Shenzhen supply private-label programs for fast-fashion retailers. REACH Annex XVII phthalate restrictions are forcing reformulation timelines of 18-24 months for European-bound shipments.
- Metal:Stamped stainless steel and nickel silver alloys occupy the mid-tier through scalable die-casting and electroplating finishes. Italian and German frame houses source these substrates from specialized metalworking districts around Solingen and Valenza. Alloy price volatility compresses margins when nickel futures spike.
- Wood:Laminated bamboo and hardwood veneers serve sustainability-positioned niche brands with limited production scalability. Thin-veneer lamination over acetate cores solves structural durability limitations. Supply concentrates in craft workshops across Guangdong and Oregon.
- Titanium:Precision-machined beta-titanium and memory alloys command the highest margin tier through aerospace-grade material specifications and CNC finishing requirements. Japanese Kobe Steel sponge titanium allocations determine production feasibility for premium Japanese and Swiss frame manufacturers. Aerospace demand spikes create intermittent feedstock scarcity.
Plastic leads volumes today; titanium is gaining share fastest.
Lens Type:
Functional performance tier determines outdoor use-case penetration and replacement frequency.
- Polarized:PVA film laminates block horizontally polarized glare through iodine-doped polyvinyl alcohol alignment. Coastal and alpine markets in Australia, Florida, and Colorado absorb premium positioning for fishing and skiing applications. Nitto Denko and Sumitomo Chemical control 70%+ of polarizing film substrate, creating single-source procurement risk.
- Photochromic:Silver halide microcrystals embedded in polycarbonate enable reversible darkening under UV exposure. Urban commuter demand concentrates in Tokyo, London, and New York for single-pair indoor-outdoor convenience. Faster transition speeds below 30 seconds differentiate newer chemistry generations.
- Mirrored:Thin-film metallic oxide deposition creates reflective cosmetic finishes with modest functional heat reduction. Snow sports and high-altitude applications in the Swiss Alps and Colorado Rockies drive seasonal demand spikes. Vacuum deposition equipment requirements limit supplier base to specialized optical coaters.
- Gradient:Variable tint density from top to bottom serves automotive and fashion applications requiring unobstructed downward vision. Driving-optimized gradients with darker upper zones concentrate demand in German and California automotive culture markets. Tint uniformity tolerances challenge coating process control.
Polarized lenses anchor revenue concentration; photochromic variants are expanding most quickly.
Style:
Customer archetype and occasion-based usage separate timeless classics from trend-driven fashion cycles.
- Aviator:Teardrop lens geometry with double or triple bridge construction originated in military aviation specifications. Masculine positioning persists in North American and Middle Eastern markets. Metal construction dominates this silhouette.
- Wayfarer:Trapezoidal acetate frames with rivet detailing define the most replicated silhouette in eyewear history. Unisex appeal spans age demographics from Gen Z vintage revivalists to boomer loyalty. Injection molding scalability supports mass-market penetration.
- Cat Eye:Upswept outer edges with pointed corners serve feminine fashion positioning and retro aesthetic cycles. Premium Italian acetate houses including Mazzucchelli 1849 supply distinctive color laminations for this silhouette. Social media influencer cycles accelerate obsolescence risk.
- Round:Circular lens shapes reference 1960s counterculture and intellectual archetypes. Asian facial geometry compatibility drives concentration in Japanese and South Korean markets. Thin metal wire construction or thick acetate rims define price tier differentiation.
Wayfarer silhouettes maintain volume leadership; cat eye shapes are climbing the fastest on social commerce platforms.
Target Audience:
Purchase occasion and channel behavior separate gift buyers from self-purchase decision-makers.
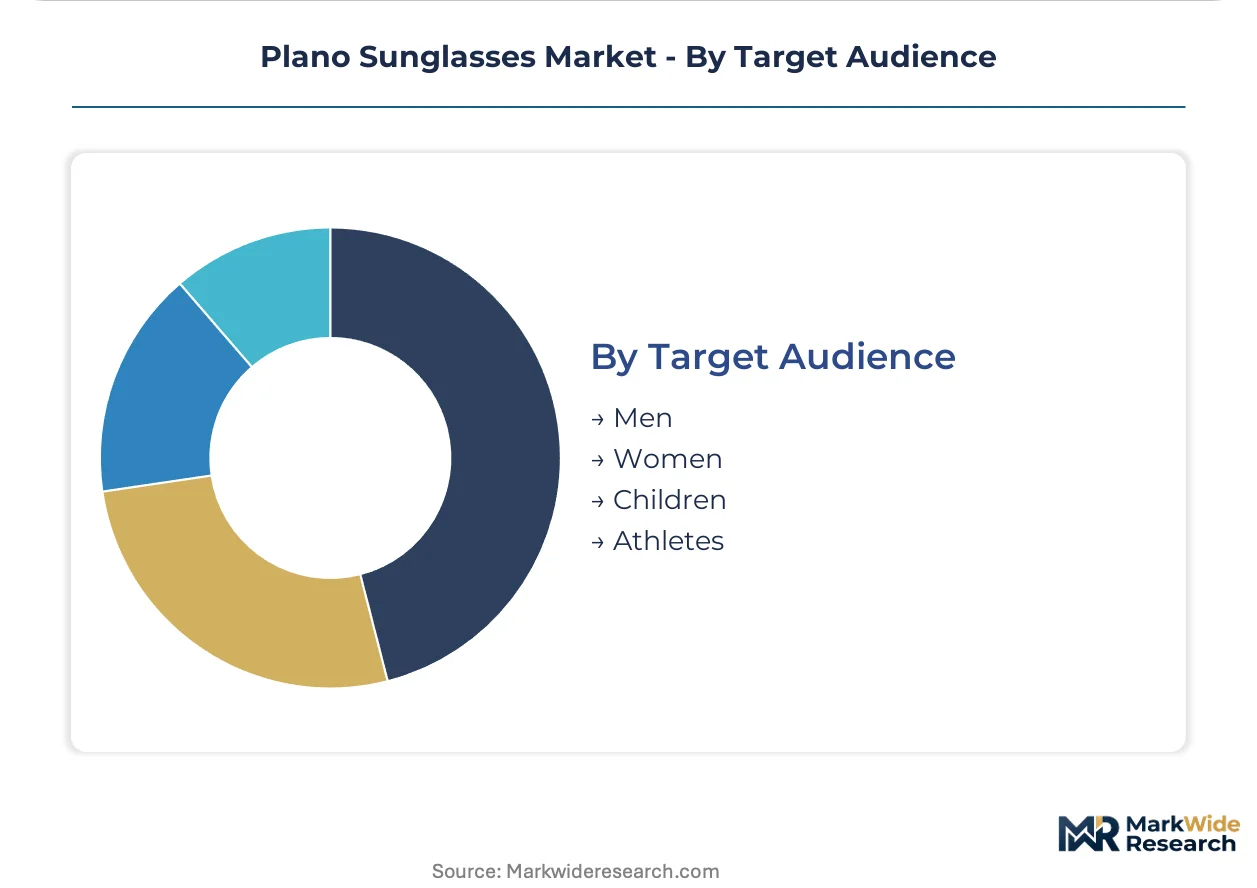
- Men:Functional durability and brand heritage drive purchase criteria with lower replacement frequency than female segments. Sports performance and driving optimization concentrate demand in polarized and photochromic lens attachments. E-commerce penetration lags women's segments due to lower virtual try-on engagement.
- Women:Accessory coordination with apparel cycles and social media visibility elevates fashion-forward frame importance. Higher SKU velocity and seasonal refresh rates support subscription lens replacement program economics. Instagram and TikTok discovery channels dominate awareness generation.
- Children:Impact resistance mandates under FDA 21 CFR 801.410 and parental safety concerns prioritize polycarbonate lenses and flexible frame materials. School sports programs and pediatric optometrist recommendations drive prescription-adjacent plano sales. Character licensing from entertainment properties sustains retail placement.
- Athletes:Sport-specific optical requirements including wraparound retention, vented anti-fog designs, and prescription insert compatibility define technical specifications. Cycling, running, and water sports each demand distinct lens curvature and grip architecture. Specialty retail through running stores and bike shops displaces general optical channels.
Women's segments generate highest revenue per capita; children's athletic positioning is expanding most quickly through pediatric channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing frame manufacturing from EU-bound producers facing REACH Annex XVII compliance costs toward Asian injection-molding clusters serving domestic and export markets with less stringent chemical restrictions. This migration pattern concentrates bio-based acetate innovation in Italian Jura Valley compounders while Wenzhou and Shenzhen absorb volume production for price-sensitive segments.
United States
Fashion-conscious millennials in coastal metros drive premium non-prescription eyewear adoption through subscription lens replacement programs. FDA 21 CFR 801.410 impact resistance mandates shape children's and sports-specific product development. Los Angeles and New York anchor direct-to-consumer brand headquarters and influencer marketing operations.
China
Domestic brands and live-stream commerce channels capture rising middle-class spending on lifestyle accessories in tier-2 cities including Chengdu and Hangzhou. SAMR enforces GB 10810.3 lens standards for transmittance and optical power deviation. Wenzhou and Shenzhen injection-molding clusters supply private-label programs for fast-fashion retailers.
Italy
Premium fashion houses absorb 15-20% material cost premiums for ECHA-compliant bio-based acetate from Mazzucchelli 1849 and comparable compounders. REACH Annex XVII phthalate restrictions accelerate reformulation investments ahead of 2025 enforcement deadlines. Jura Valley manufacturing clusters face disproportionate qualification burdens relative to integrated chemical compounders.
Japan
Precision-machined beta-titanium frames command highest margin tiers through aerospace-grade material specifications. Kobe Steel sponge titanium allocations determine production feasibility for premium domestic and Swiss frame manufacturers. Tokyo concentrates urban commuter demand for photochromic single-pair indoor-outdoor solutions.
Australia
TGA Category 2 or higher UV400 labeling mandates expand baseline demand for certified lenses across Oceania export markets. Coastal markets absorb premium positioning for polarized lenses in fishing applications. Sydney and Melbourne retail channels emphasize sun protection compliance in product positioning.
Plano Sunglasses Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated optical houses controlling premium distribution while OEM suppliers serve private-label programs. The vendor base concentrates around three strategic archetypes: fashion-luxury houses with licensed eyewear portfolios, direct-to-consumer platforms with tele-optometry integration, and precision-metal specialists serving alpine and performance segments. Competitive moves center on backward integration into lens coating capabilities and geographic expansion through department store wholesale relationships.
Among vertically integrated specialists, EssilorLuxottica and Marchon Eyewear exemplify contrasting channel strategies. EssilorLuxottica occupies a position anchoring luxury licensed portfolios with captive optical lab networks. Marchon Eyewear represents wholesale relationship specialists sustaining department store and independent optician placement across multiple continents. Warby Parker sits within the direct-to-consumer archetype, though the report makes no specific claims about its operational scale or strategic priorities.
| Leading Market Players |
|---|
| Marchon Eyewear |
| DE RIGO REM |
| EssilorLuxottica |
| Ray-Ban |
| Silhouette International |
| Safilo Group |
| Marcolin |
| Warby Parker |
| Luxottica Group |
| Others |
Supply Flow & Price Mechanics
Captive acetate compounding in Italian Jura Valley clusters anchors premium pricing power for REACH-compliant bio-based frames, while outsourced injection molding in Wenzhou and Shenzhen locks mass-market tiers into volatile commodity cost cycles. This integration divergence separates margin-defensible fashion houses from price-taking private-label suppliers serving fast-fashion retailers.
Pricing Analysis
Distributor margins absorb 40-50% of ex-factory value for department store wholesale channels, whereas direct-to-consumer platforms capture full retail markup through home try-on logistics. Three-tier pricing structure across premium titanium, standard metal-acetate hybrids, and economy injection-molded plastic reflects certification grade and material cost differentiation. Cost compression in mid-tier metal frames is intensifying because nickel futures volatility feeds through electroplating supply chains. Fast-fashion retailers exhibit highest price sensitivity, while alpine sports specialists accept premium positioning for glacier-certified Category 4 lenses.
Supply Chain Analysis
Ocean freight rate volatility from Asia-Europe lanes compresses margin buffers for European-bound acetate shipments dependent on Jura Valley compounders. Manufacturing gravity centers on Italy for bio-based formulation, Japan for beta-titanium machining, and China for injection-molded volume production. Frame assemblers rest on Kobe Steel sponge titanium allocations, Mazzucchelli 1849 cellulose diacetate supply, and Nitto Denko PVA polarizing film substrates. Single-source vulnerability in polarizing film creates procurement risk concentration for lens manufacturers. Distribution runs through department store wholesale for licensed fashion houses, direct-to-consumer platforms for digitally native brands, and specialty retail for performance alpine segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on bio-based material substitution enabling 15-20% cost pass-through to REACH-compliant buyers, alongside software-enabled virtual fitting displacing inventory-heavy wholesale models.
For Market Incumbents: Cement category ownership in photochromic lens chemistry through silver halide microcrystalline embedding patents, while securing captive titanium allocations from Kobe Steel ahead of aerospace demand spikes. Threat from direct-to-consumer platforms with tele-optometry integration demands channel control reinforcement through subscription lens replacement programs. For New Entrants and Emerging Players: AR-enabled virtual fitting technology offers white-space entry against inventory-constrained incumbents, targeting underpenetrated North American ski resort retail for glacier-certified Category 4 lenses. Live-stream commerce channels in tier-2 Chinese cities present the most penetrable geography, with data-driven inventory positioning as the go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs disproportionately burden small-batch Jura Valley acetate producers relative to integrated chemical compounders. Long-term viability favors vertically integrated optical houses with captive lens coating capabilities and licensed luxury portfolios. Watch extended producer responsibility framework implementation in California and the European Union as inflection indicators for recycling infrastructure valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Acetate Scale-Up | Mazzucchelli 1849 expansion secures ECHA-compliant supply chains for premium fashion houses. |
| Direct-to-Consumer Platform Launch | Home try-on logistics with tele-optometry integration displaces seasonal wholesale pre-orders. |
| Polarized Lens Backward Integration | In-house PVA film coating reduces dependence on Nitto Denko and Sumitomo Chemical allocations. |
| Extended Producer Responsibility Infrastructure | Closed-loop recycling operators gain first-mover advantage under California SB 54 mandates. |
| Alpine Sports Specialization | Glacier-certified Category 4 lens penetration in North American ski resorts mirrors European adoption curves. |
Methodological Framework
Multiple input streams — frame manufacturer interviews, lens chemistry specialist consultations, retail channel partner discussions, and regulatory affairs dialogues — were reconciled against customs trade records, ECHA substance registration databases, FDA 21 CFR guidance documents, and optical industry association publications. Bottom-up unit economics from injection molding clusters in Wenzhou and Shenzhen were triangulated with top-down market sizing from licensed fashion house revenue disclosures.
Historical volume trajectories were cross-referenced against panel input from acetate compounders and titanium distributors to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated frame material chemistry, lens functionality tier, style silhouette, and target audience archetype dimensions. CAGRs were derived from demand elasticity analysis against UV protection mandate rollouts and middle-class consumption cluster expansion in tier-2 Chinese cities.
The model holds under stable REACH enforcement timelines and continued aerospace titanium allocation patterns; deviation in ECHA authorization acceleration or Kobe Steel supply disruption would shift volume and value outputs. Forecasts reflect documented assumptions about live-stream commerce penetration rates and tele-optometry regulatory expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Polarized Sunglasses Market
Eyewear
Luxury Eyewear Market
Eyewear
Spectacles Market
Eyewear
Sunglasses Market
Eyewear
Saudi Arabia E-Commerce Eyewear Market
Eyewear
Eyeglass Market
Eyewear
Eyewear Market
Eyewear
Glasses Frame Market
Eyewear
Smart Eyewear Market
Eyewear
Reading Glasses Market
Eyewear
Europe Eyewear Market
Eyewear
Smart Sunglasses Market
Eyewear
Ultralight Eyeglass Frames Market
Eyewear
Blue Light Glasses Market
Eyewear
3D Printing in Eyewear Market
Eyewear
Latin America Eyewear Market