
 United States Avocado Oil Market | 2026-2036
United States Avocado Oil Market Size, Share, and Industry Trends Forecast 2026-2036
United States Avocado Oil Market Intelligence
Subscription-based replenishment programs for specialty cooking oils is consolidating how households purchase avocado oil, shifting volume from episodic retail trips to recurring direct-to-consumer shipments. Chosen Foods LLC leverages its retail placement in club stores to sustain volume leadership. La Tourangelle anchors its position through artisanal positioning in premium grocery channels. Spectrum Organics differentiates via USDA Organic certification across its entire avocado oil portfolio.
United States avocado oil is a lipid extracted from the fleshy mesocarp of Persea americana fruit, typically cold-pressed at temperatures below 50°C to preserve oleic acid concentrations exceeding 70% and chlorophyll content, serving primarily as a high-smoke-point culinary medium and cosmeceutical emollient. Extra virgin grades command the strongest margin pools due to minimal processing and premium positioning, while refined avocado oil competes on scale in food processing applications where neutral flavor and extended shelf stability matter most. Online retail channels represent the fastest-growing distribution vector as direct-to-consumer platforms reduce intermediary costs and enable traceability storytelling.
The FDA governs edible avocado oil labeling under the Federal Food, Drug, and Cosmetic Act, while USDA Organic certification shapes premium tier access and California's state-level Proposition 65 compliance requirements influence contaminant testing protocols for both food and cosmetic applications. Stakeholders must monitor how evolving clean-label standards and state-specific agricultural regulations reshape sourcing requirements and product claims.
Market Dynamics
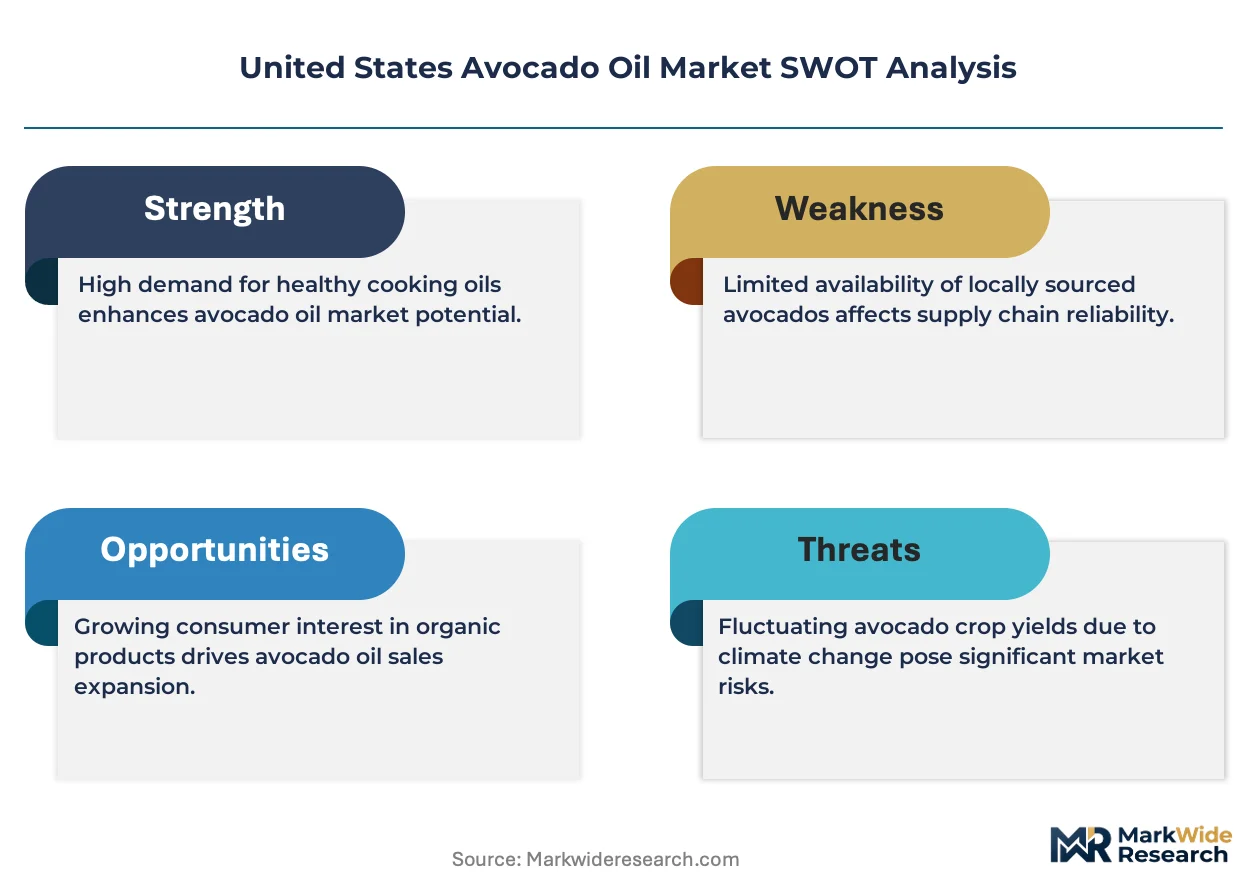
California's dominance in domestic avocado cultivation and processing infrastructure concentrates supply-side leverage among a narrow corridor of growers and cold-press operators, amplifying price volatility during seasonal harvest gaps and forcing downstream brands into long-term offtake negotiations.
Growth Catalysts
- Clean-label mandates:FDA's updated edible oil labeling requirements under the Federal Food, Drug, and Cosmetic Act compel reformulation toward single-ingredient, minimally processed oils that favor extra virgin avocado oil positioning.
- Cosmeceutical grade demand:Personal care brands embed cold-pressed avocado oil into premium skincare formulations targeting oleic acid concentrations exceeding 70% for barrier repair and emollient applications.
- Smoke point superiority:Refined avocado oil's 270°C smoke point displaces seed oils in commercial food manufacturing across California's restaurant supply and packaged goods sectors.
Market Restraints
- Input cost volatility:Water scarcity in California's Central Valley intensifies irrigation expenses and compresses grower margins during drought cycles.
- Supply concentration risk:Over 80% of domestic avocado oil processing capacity clusters within 150 miles of San Diego, creating single-point vulnerability to wildfire disruption and logistics bottlenecks.
- Substitution pressure:High-oleic sunflower oil and refined olive oil compete on price in foodservice applications where neutral flavor and extended fry life matter most.
Strategic Opportunities
- Direct-to-consumer channel expansion:Subscription-based replenishment programs for specialty cooking oils capture recurring household volume and reduce retail intermediary costs.
- USDA Organic tier premiumization:Certification unlocks shelf placement in premium grocery channels and justifies 40-60% price premiums over conventional grades.
- Traceability technology convergence:Blockchain-enabled lot tracking paired with QR-code storytelling differentiates origin-verified oils from commodity blends in online retail.
Industry Challenges
- Proposition 65 compliance complexity:California's contaminant testing protocols for heavy metals and pesticide residues extend certification timelines and raise analytical costs for both food and cosmetic applications.
- Skill scarcity in cold-press operations:Specialized technicians for temperature-controlled extraction below 50°C command premium wages and limit capacity expansion speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Avocado Oil Market |
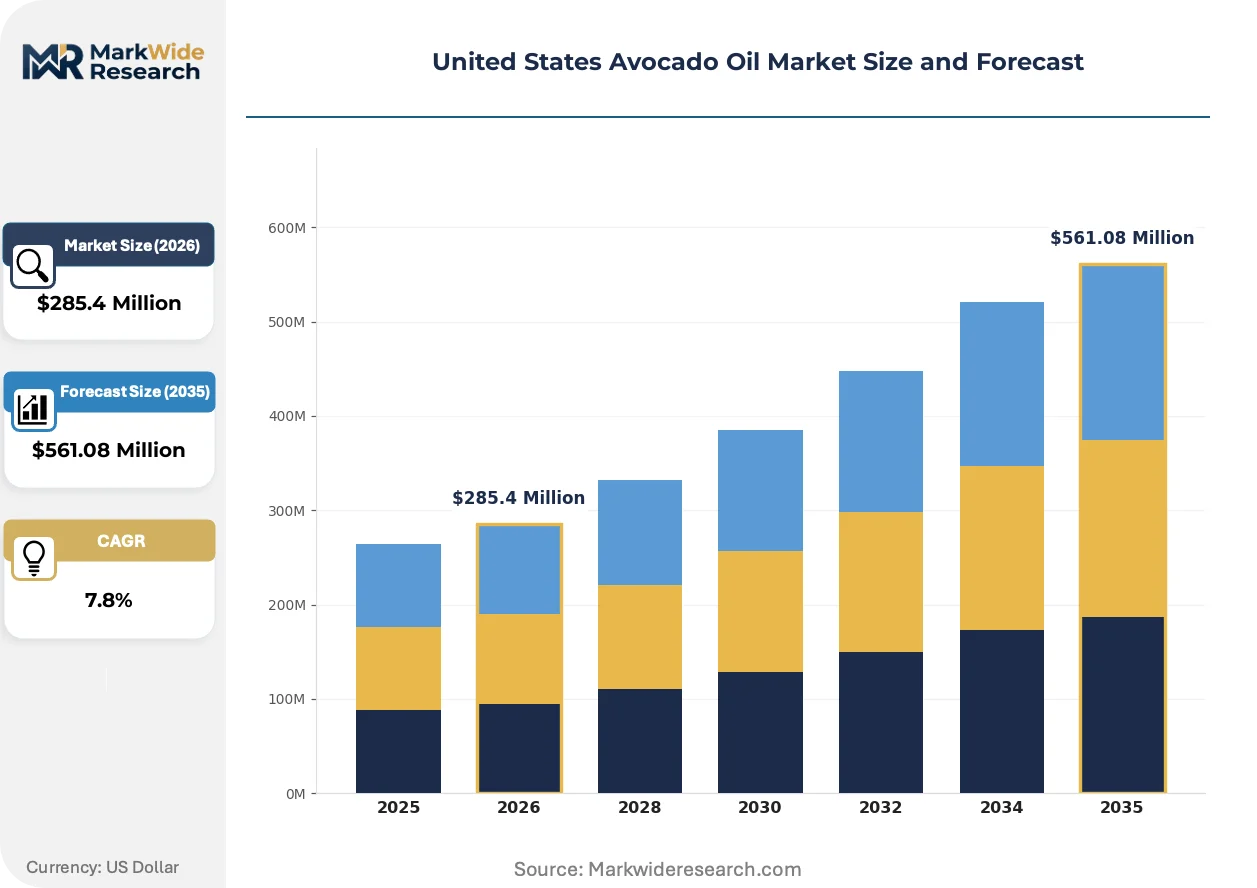
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined, Unrefined, Extra Virgin, Avocado Oil Blends Application: Cooking, Cosmetics, Salad Dressings, Food Processing Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores End User: Households, Restaurants, Food Manufacturers, Personal Care Brands |
| Companies Covered | La Tourangelle, The Village Press, Bella Vado Avocado Oil, Grove Avocado Oil, Cibaria International, Chosen Foods LLC, Kevala, Olivado USA, Spectrum Organics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Avocado Oil Market Strategic Shifts & Innovations
Technological, regulatory, and behavioral forces are compressing traditional value chains and redistributing margin capture toward traceability-enabled brands and direct distribution platforms.
Blockchain-based provenance tracking is decentralizing quality verification away from centralized laboratory testing and toward distributed ledger systems accessible via consumer-facing interfaces. Mid-sized avocado oil processors in California and Texas adopt this infrastructure to differentiate against commodity importers. The technology is decentralizing trust mechanisms and enabling price premiums previously captured only by vertically integrated heritage brands.
FDA's updated labeling requirements for edible oils under the Federal Food, Drug, and Cosmetic Act mandate disclosure of refining processes and origin claims. This regulatory pressure compresses market share for blended or ambiguously sourced products while rewarding single-origin, cold-pressed certifications. Extra virgin grade producers in California's San Diego County are responding with enhanced lot-level documentation and third-party audit investments.
Club store and online retail channels now capture volume previously flowing through conventional grocery intermediaries. Costco's Kirkland Signature and direct-to-consumer platforms like Thrive Market displace traditional distributor networks for premium cooking oils. This channel rotation is most visible in California and Texas metropolitan markets where household penetration of subscription replenishment models exceeds national averages by significant margins.
United States Avocado Oil Market Segmentation
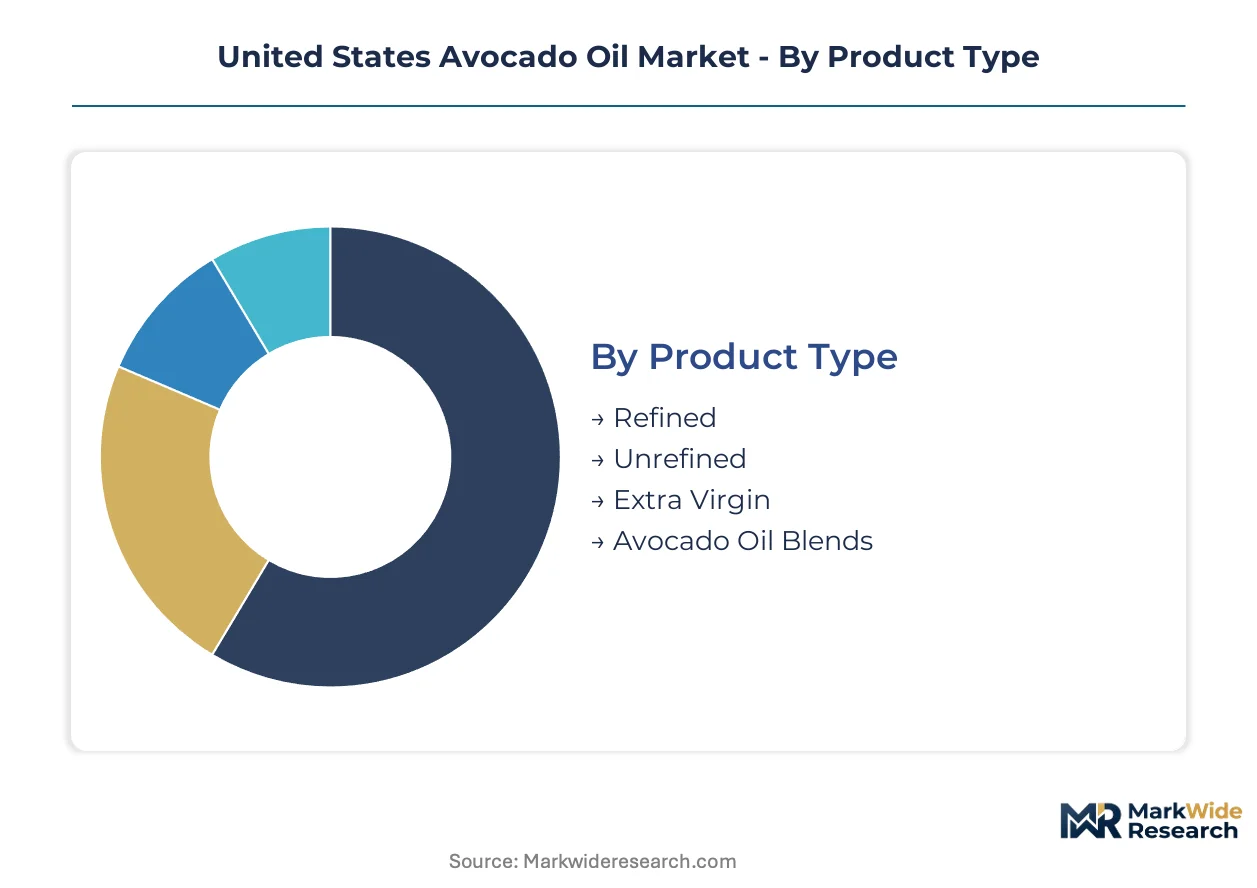
Segmentation reveals how avocado oil value pools fragment across processing grades, use cases, and procurement channels. Each dimension exposes distinct margin structures and vulnerability to substitution.
Product Type:
Upgrade cycles from refined to cold-pressed grades accelerate as households replace commodity seed oils with premium culinary alternatives.
- Refined:Bleached and deodorized at high temperatures to neutralize flavor and extend shelf stability. Food manufacturers across California's Central Valley favor this grade for high-heat frying applications where smoke point trumps flavor retention.
- Unrefined:Mechanical extraction preserves chlorophyll and carotenoid content. Natural products retailers in Austin and Denver metropolitan areas stock this grade for consumers prioritizing minimal processing over extended storage.
- Extra Virgin:Cold-pressed below 50°C with oleic acid exceeding 70%. USDA Organic-certified extra virgin commands placement in Whole Foods Market and Sprouts Farmers Market premium sets.
- Avocado Oil Blends:Formulations combining avocado oil with olive or grapeseed oils. Price-sensitive foodservice operators in Texas specify blends for bulk procurement.
Refined avocado oil sits at the top of the volume ranking, with extra virgin climbing the fastest.
Application:
Application mix tracks divergence between culinary consumption and cosmeceutical ingredient demand.
- Cooking:Sautéing, roasting, and pan-frying applications leverage avocado oil's 270°C smoke point. Restaurant chains in Los Angeles and San Francisco specify refined grades for back-of-house operations.
- Cosmetics:Cold-pressed grades supply emollient formulations for barrier repair serums. Personal care brands in California embed traceability claims into premium skincare packaging.
- Salad Dressings:Extra virgin grades dominate refrigerated dressing aisles. Clean-label mandates from FDA's updated labeling requirements favor single-ingredient oil positioning.
- Food Processing:Refined oil integrates into packaged snacks and frozen prepared meals. National CPG manufacturers source through long-term offtake contracts with San Diego County processors.
Food processing captures the largest volume share, while cosmetics expands most quickly.
Distribution Channel:
Channel structure reflects consolidation toward high-volume intermediaries and direct relationships.
- Online Retail:Subscription replenishment programs reduce customer acquisition costs for specialty brands. Thrive Market and direct-to-consumer platforms bypass traditional distributor markups.
- Supermarkets:Conventional grocery placement requires slotting fee investments. Kroger and Albertsons chains in California allocate shelf space based on velocity thresholds.
- Health Food Stores:Regional cooperatives and natural products retailers prioritize USDA Organic certification. Staff education programs drive recommendation-based purchase decisions.
- Specialty Stores:Gourmet food shops and culinary supply retailers stock estate-bottled single-origin oils. Sommelier-led tasting events support premium price realization.
Supermarkets maintain volume leadership, with online retail gaining share fastest.
End User:
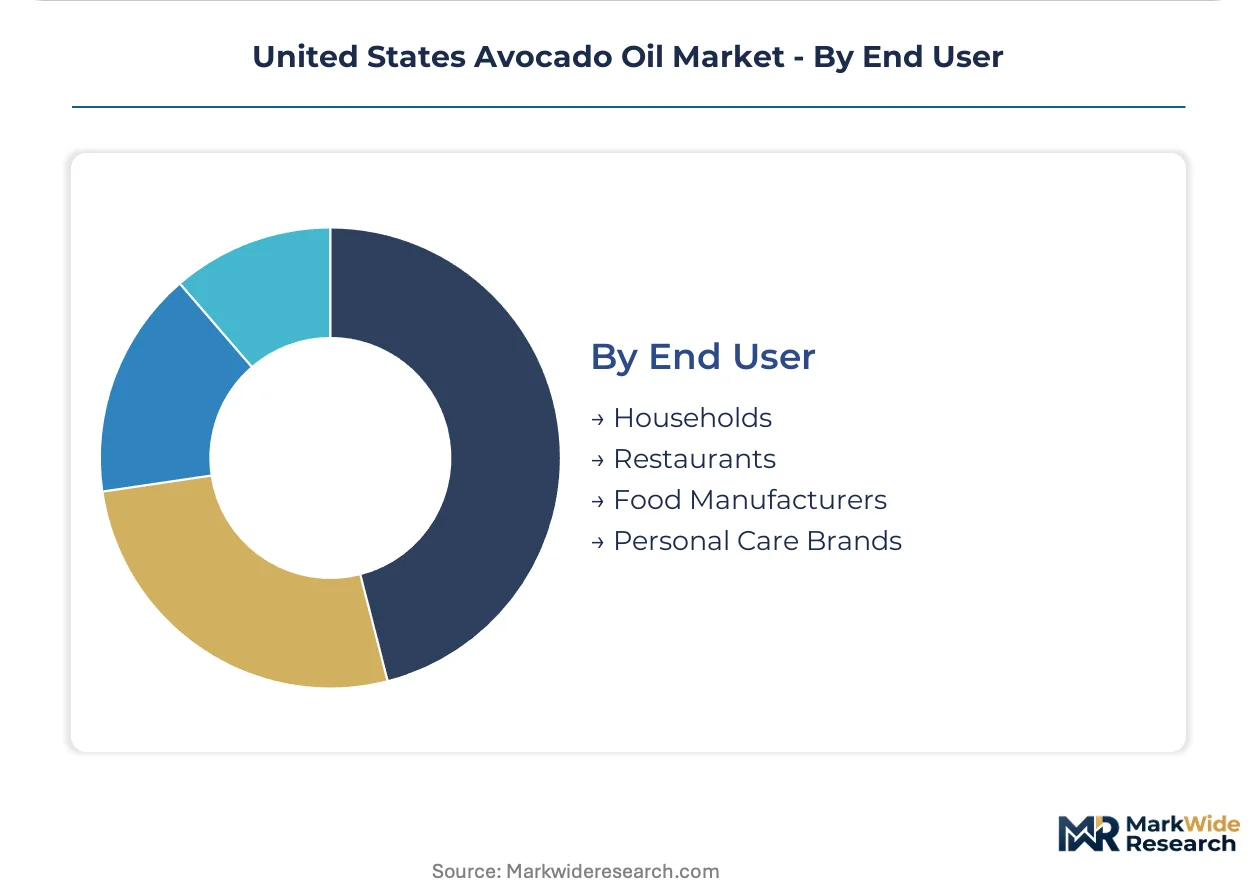
End-user segmentation exposes divergent procurement sophistication and price elasticity.
- Households:Direct-to-consumer subscriptions capture recurring pantry replenishment. California and Texas metropolitan households over-index on premium grade adoption.
- Restaurants:Foodservice distributors supply refined grades in bulk packaging. Independent operators in San Diego County source through regional produce distributors.
- Food Manufacturers:Refined oil purchases tie to fry life specifications and neutral flavor requirements. National brands negotiate annual contracts with processing cooperatives.
- Personal Care Brands:Cosmetic-grade specifications demand lot-level documentation and contaminant testing. Proposition 65 compliance extends certification timelines for California-based formulators.
Food manufacturers represent the largest procurement volume, with personal care brands expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's processing infrastructure dwarfs all other states, yet Texas and Florida are cultivating distinct demand profiles that diverge from the West Coast model.
California
San Diego County hosts over 80% of domestic cold-press capacity, with Fallbrook and Temecula growers supplying Persea americana fruit to vertically integrated processors. FDA labeling requirements under the Federal Food, Drug, and Cosmetic Act drive reformulation toward single-origin certifications. Los Angeles and San Francisco restaurant chains specify refined grades for high-heat applications, consolidating procurement through regional produce distributors.
Texas
Metropolitan Austin and Dallas-Fort Worth households over-index on premium grade adoption through subscription replenishment programs. State agriculture department initiatives support experimental avocado cultivation in the Rio Grande Valley. Cold-press operators in Houston serve personal care brands seeking Proposition 65-compliant cosmetic-grade oils for barrier repair formulations.
Florida
Miami-Dade and Palm Beach counties import Mexican avocado fruit for secondary processing, bypassing California's seasonal harvest gaps. State environmental regulations govern wastewater discharge from oil extraction facilities. Orlando and Tampa food manufacturers source refined grades for packaged snack applications, negotiating annual contracts with Gulf Coast processors.
New York
The metropolitan area's specialty food retailers anchor East Coast distribution for estate-bottled single-origin oils. State Department of Agriculture and Markets enforces organic certification compliance for premium shelf placement. Brooklyn-based direct-to-consumer platforms bypass traditional distributor markups, capturing recurring pantry replenishment from affluent households.
Arizona
Phoenix and Tucson processors leverage proximity to California supply chains while operating under lower water-cost structures. State groundwater management regulations constrain expansion of cultivation acreage. Yuma County cold-press facilities serve Southwestern foodservice operators seeking traceability-verified oils for clean-label menu positioning.
United States Avocado Oil Market Key Industry Players
Top-tier vendors anchor club store and premium grocery placement, while mid-tier processors compete on USDA Organic certification and direct-to-consumer channel access. The vendor base stratifies across three archetypes: vertically integrated heritage brands with captive California groves, contract-dependent processors sourcing through long-term offtake agreements, and specialty importers blending Mexican and domestic supply. Dominant competitive moves include subscription platform development and blockchain-enabled traceability investments.
Within the heritage-brand tier, La Tourangelle and Chosen Foods LLC occupy positions defined by retail density and volume scale. Spectrum Organics exemplifies the certification-driven archetype, anchoring its portfolio differentiation through USDA Organic compliance across all grades. Bella Vado Avocado Oil represents the estate-processor model, with geography embedded in its naming convention suggesting San Diego County origin and single-origin positioning.
| Leading Market Players |
|---|
| La Tourangelle |
| The Village Press |
| Bella Vado Avocado Oil |
| Grove Avocado Oil |
| Cibaria International |
| Chosen Foods LLC |
| Kevala |
| Olivado USA |
| Spectrum Organics |
| Others |
Cost & Logistics Intelligence
Extra virgin-to-refined grade bifurcation drives divergent margin architectures across the United States avocado oil market, with cold-pressed certifications commanding shelf placement premiums in premium grocery channels while deodorized grades compete on volume scale in food manufacturing procurement. This tier divergence manifests in supply chain configurations: heritage brands with captive California groves capture upstream margin pools, whereas contract-dependent processors absorb input cost volatility through long-term offtake negotiations with San Diego County growers.
Pricing Analysis
Capacity additions in Texas and Arizona are reshaping price floors for refined grades as new cold-press operators enter the market with lower water-cost structures than California incumbents. Three-tier pricing structure across extra virgin, unrefined, and refined levels anchors the dominant model, with USDA Organic certification and smoke point performance serving as primary price differentiation drivers. Cost compression in refined tiers is intensifying because high-oleic sunflower oil substitutes compete aggressively in foodservice applications. Food manufacturers represent the most price-sensitive buyer segment, while personal care brands demonstrate lowest sensitivity due to formulation lock-in requirements.
Supply Chain Analysis
Dual-sourcing requirements from national CPG manufacturers mandate multi-supplier qualification across California, Mexico, and Texas processing facilities to mitigate harvest gap vulnerabilities. Raw material dependencies center on Persea americana fruit supply, cold-press equipment with temperature control capabilities, and USDA Organic certification infrastructure. Single-source vulnerability concentrates risk where over 80% of domestic cold-press capacity clusters within 150 miles of San Diego. Distribution runs through club store networks, direct-to-consumer platforms, and regional produce distributors serving restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States avocado oil market functions as a stable compounder, with clean-label regulatory tailwinds from FDA labeling mandates driving steady household penetration and premium grade adoption across California and Texas metropolitan corridors.
For Market Incumbents: Extend traceability technology investments to defend margin position against commodity importers leveraging blockchain-enabled lot tracking and QR-code origin storytelling. Fortify long-term offtake agreements with Fallbrook and Temecula growers to secure captive supply of high-oleic acid fruit ahead of seasonal harvest gaps. Channel control through club store exclusivity represents a critical lever against emerging direct-to-consumer entrants. For New Entrants and Emerging Players: Metropolitan Austin and Dallas-Fort Worth households present an underserved buyer archetype with subscription replenishment adoption rates exceeding national benchmarks. Personal care brands seeking Proposition 65-compliant cosmetic-grade oils offer the most penetrable application segment given extended certification timelines burdening incumbent processors. A go-to-market angle anchored in USDA Organic certification with direct-to-consumer platform bypass of retail slotting fees unlocks initial traction. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier processors lack backward integration into California cultivation assets and remain exposed to drought-driven input cost volatility. Acquisition targets with estate-bottled single-origin positioning and vertically integrated San Diego County groves offer strongest long-term viability through the projection horizon. The signal to watch is FDA enforcement intensity around refined process disclosure mandates, which would accelerate share capture by cold-pressed specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Subscription replenishment programs bypass Kroger and Albertsons slotting fee structures while capturing recurring California household volume. |
| USDA Organic Certification Investment | Organic compliance unlocks Whole Foods Market and Sprouts Farmers Market premium shelf placement with justified price premiums. |
| Backward Integration into Cultivation | Captive groves in Fallbrook and Temecula insulate processors from water scarcity-driven input cost volatility in California's Central Valley. |
| Blockchain Traceability Deployment | Distributed ledger systems with consumer-facing QR interfaces differentiate origin-verified oils from Mexican commodity blends on Thrive Market. |
| Cosmetic-Grade Capacity Expansion | Proposition 65-compliant cold-press facilities serve personal care brands in Houston and Brooklyn with barrier repair formulation demand. |
Research Approach
Bottom-up household and food manufacturer procurement modeling reconciled against top-down California and Texas cold-press capacity tracking forms the analytical core of this study. Primary interviews with brand managers at heritage oil processors, category buyers at club store chains, supply planners at national CPG manufacturers, and procurement leads at personal care formulators combined with secondary validation from FDA Federal Food, Drug, and Cosmetic Act filings, USDA Organic certification databases, Nielsen retail audit data, and California agricultural trade statistics. Triangulation between demand-side adoption patterns and supply-side infrastructure investments ensures measurement coherence.
Historical trendline analysis of extra virgin grade penetration rates and refined oil foodservice displacement patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include processing grade tier, application use case, distribution channel structure, and end-user procurement sophistication. CAGRs derive from regression-adjusted trend extrapolation incorporating smoke point performance premiums, clean-label regulatory momentum, and cosmeceutical ingredient demand growth as industry-specific forecast inputs.
Underlying measurement precision varies by segment; extra virgin grade volume and direct-to-consumer channel flows carry tighter precision than refined oil foodservice procurement and blend formulations. Forecasts reflect assumptions around FDA labeling enforcement continuity, California water allocation stability, and Mexican avocado import tariff structures. Deviation in drought severity or wildfire disruption frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fonio Flour Market
Ingredients
Fluid Lecithin Market
Ingredients
Bouillon Market
Ingredients
Xylooligosaccharide Market
Ingredients
Coconut Cream Powder Market
Ingredients
Food Ingredients Market
Ingredients
Beverage Ingredients Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Yeast Flakes Market
Ingredients
Beetroot Powder Market
Ingredients
Peanut Flour Market
Ingredients
Europe Agar Market
Ingredients
Alcohol Ingredients Market
Ingredients
Compressed Yeast Market
Ingredients
South America Vegetable Oil Market
Ingredients
North America Dairy Protein Market