
 Sunflower Oil Market | 2026-2036
Sunflower Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Sunflower Oil Market Analysis
Crude oil trading margins is reconfiguring how processors capture value across the sunflower oil chain. Bunge Global SA leverages its Black Sea origination network to control upstream supply. Cargill Incorporated anchors its position through integrated crushing assets in Eastern Europe. Kernel Holding S.A. competes on seed procurement scale and port logistics.
Sunflower oil is a triglyceride vegetable oil extracted from Helianthus annuus seeds, typically refined to less than 0.1% free fatty acid content for food applications, with high oleic variants exceeding 80% monounsaturated fat for frying stability. Refined grades dominate volume throughput due to neutral flavor and extended shelf life, while cold pressed variants command premium positioning in specialty stores. The food industry end-use segment absorbs the majority of output, though biofuels applications are gaining policy support in select jurisdictions. Bulk packaging channels serve industrial buyers, whereas bottles and pouches target retail consumers through supermarkets.
EU REACH compliance and F-Gas Regulation frameworks govern processing emissions and solvent recovery in European crushing facilities. FDA oversight in the United States sets residue limits and labeling standards for imported oil shipments. India's FSSAI mandates nutritional fortification for edible oils sold through domestic distribution channels. Stakeholders must monitor how sustainability certification requirements and origin traceability rules reshape procurement criteria and supplier qualification processes.
Market Dynamics
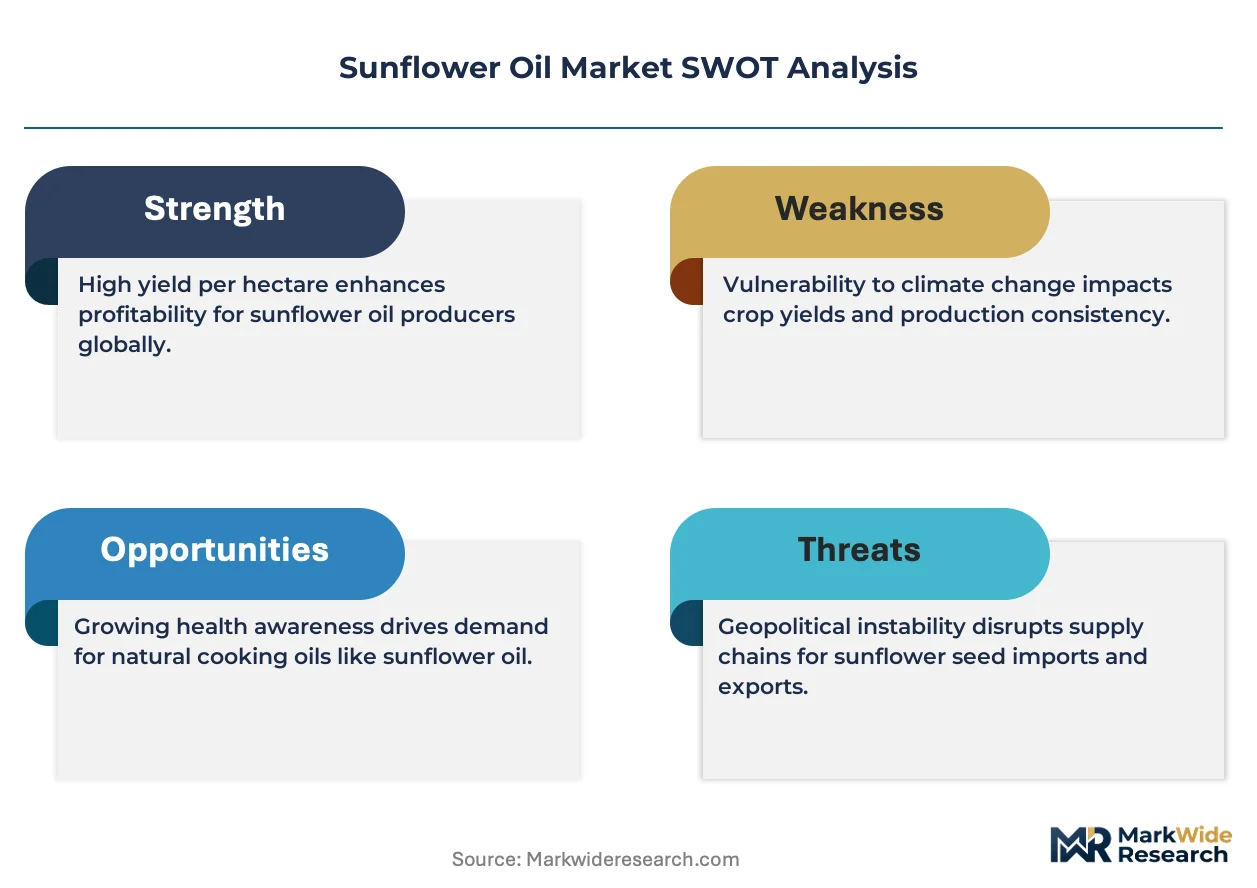
Black Sea supply concentration is forcing processors to rebuild origination networks around alternative seed sources and inland crushing assets. Trade flow disruptions since 2022 have permanently altered how refiners manage geographic risk in sunflower oil procurement.
Growth Catalysts
- FSSAI fortification mandates:India's edible oil fortification rules require Vitamin A and D enrichment in all packaged oils sold through domestic retail channels. Packaged food manufacturers are scaling refined sunflower oil procurement to meet compliance deadlines.
- High-oleic seed breeding:New Helianthus annuus cultivars exceeding 80% monounsaturated fat content deliver extended fry life for foodservice operators. Seed companies are accelerating variety registration in Argentina and Turkey.
- Biofuel policy support:The EU Green Deal and national blending mandates in select member states are creating offtake agreements for sunflower oil methyl ester. Refiners with flexible processing trains are reconfiguring output splits.
Market Restraints
- Seed supply geographic concentration:Ukraine and Russia collectively account for the majority of global sunflower seed exports. Any disruption to Black Sea port access immediately constrains crush margins in importing regions.
- Palm oil price arbitrage:Indonesian and Malaysian palm oil production cycles create periodic price undercuts that displace sunflower oil in bulk frying applications across price-sensitive food manufacturing segments.
- EU F-Gas Regulation compliance costs:Solvent recovery and hexane emission controls at European crushing facilities require capital upgrades that smaller processors cannot absorb, consolidating capacity toward integrated multinationals.
Strategic Opportunities
- Underpenetrated African markets:Nigeria, Ethiopia, and Kenya exhibit rising per capita edible oil consumption with limited local crush capacity. Regional traders are establishing bottling and distribution partnerships to capture import demand.
- Carbon intensity scoring integration:The EU Carbon Border Adjustment Mechanism and corporate Scope 3 reporting requirements are creating premium price tiers for deforestation-free, origin-certified sunflower oil with verified greenhouse gas footprints.
- Cold-pressed specialty channels:Health-conscious consumers in Germany, the United Kingdom, and Australia are paying substantial premiums for unrefined, high-linoleic variants sold through organic retailers and direct-to-subscription platforms.
Industry Challenges
- Seed oil analytics talent scarcity:Crushing facilities require specialists in near-infrared spectroscopy and fatty acid profiling to optimize output splits between food and fuel applications. Recruitment pipelines from agricultural universities remain insufficient.
- REACH registration timelines:New processing aids and refining catalysts face 12-18 month ECHA evaluation windows that delay technology adoption. Formulators must maintain dual supply chains during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sunflower Oil Market |
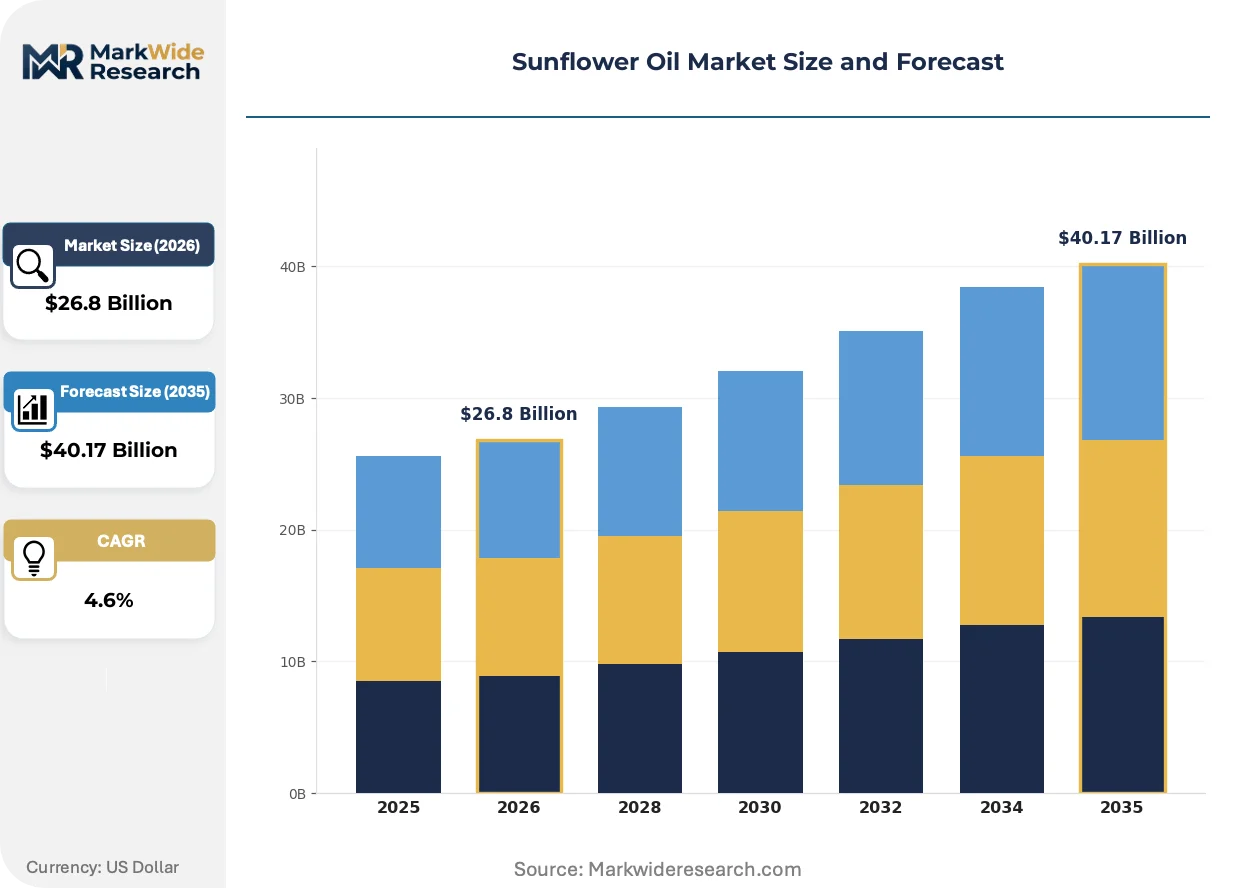
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $40.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined, Unrefined, Cold Pressed, Organic End Use: Food Industry, Personal Care, Biofuels, Pharmaceuticals Packaging Type: Bottles, Cans, Pouches, Bulk Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Bunge Global SA, Kernel Holding S.A., Cargill Incorporated, Avril Group, Adani Wilmar Ltd., Archer Daniels Midland Company, Louis Dreyfus Company, COFCO Corporation, Wilmar International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sunflower Oil Market Emerging Trajectories
Processing technology advances and traceability requirements are compressing the traditional boundaries between origination, crushing, and refined product distribution. These shifts are redrawing competitive advantage around data integration rather than scale alone.
Supercritical CO2 extraction is collapsing the cost differential between conventional hexane solvent extraction and mechanical pressing for mid-scale processors. European specialty oil producers in France and Italy are adopting these systems to serve organic certification requirements. The technology is collapsing the minimum efficient scale for premium-grade output, enabling regional crushers to compete against Black Sea bulk supply.
EU Deforestation Regulation due diligence obligations require geolocation verification for all sunflower seed entering European supply chains after December 2025. Crushing facilities must implement satellite-based farm polygon mapping and risk classification protocols. Ukrainian and Russian exporters are investing in third-party audit infrastructure to maintain EU market access, while Argentine and Turkish origin suppliers are capturing new customer relationships from compliance-ready positions.
Food manufacturers are consolidating supplier relationships around integrated crush-to-refine operators with documented sustainability credentials. Long-term offtake agreements with fixed volume-flexible pricing terms are displacing spot market purchasing for industrial accounts. This concentration is most visible in German and Dutch packaged food sectors, where procurement teams prioritize supply security and emissions transparency over lowest-unit-cost sourcing.
Sunflower Oil Market Segmentation
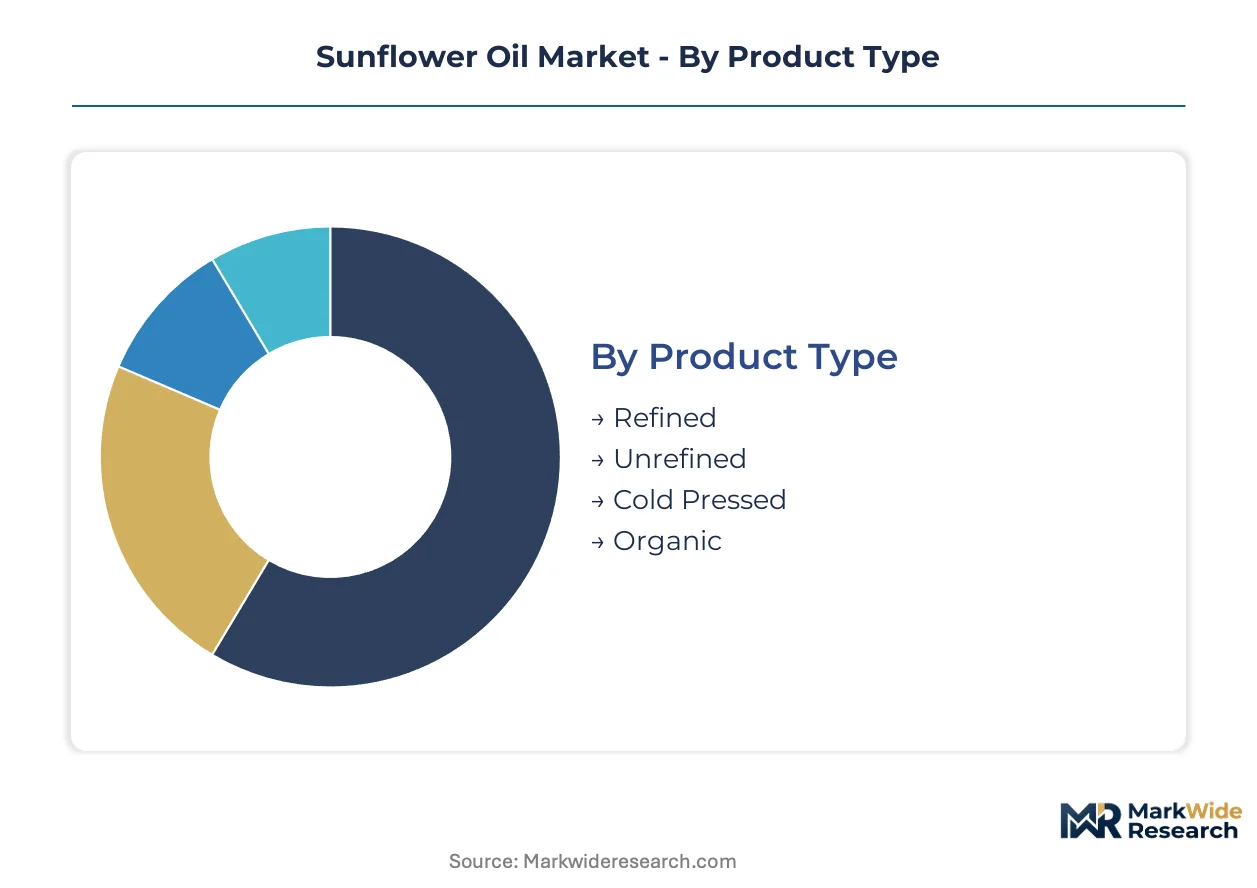
Sunflower oil segmentation reflects divergent processing intensities and buyer sophistication levels. Refined grades serve mass-market food manufacturers while cold-pressed variants target premium wellness channels. Each dimension carries distinct margin structures and regulatory exposure.
Product Type:
Mature refining technologies dominate volume flows, though emerging extraction methods are capturing premium positioning.
- Refined:Neutral-flavor oil processed to under 0.1% free fatty acid content through degumming, bleaching, and deodorization. Packaged food manufacturers in India scale procurement under FSSAI fortification mandates requiring Vitamin A and D enrichment.
- Unrefined:Retains natural color and phospholipid content with minimal post-press treatment. Eastern European consumers favor this grade for traditional salad preparations, though limited shelf stability constrains export scalability.
- Cold Pressed:Mechanical extraction below 40°C preserves tocopherols and phenolic compounds. German and Australian organic retailers command substantial premiums for high-linoleic variants through subscription platforms.
- Organic:Certified cultivation excluding synthetic pesticides and hexane solvent recovery. EU Deforestation Regulation geolocation requirements after December 2025 favor Argentine and Turkish origin suppliers with audit-ready farm polygon mapping.
Refined handles the majority of throughput; cold pressed is expanding most quickly on share.
End Use:
Application diversity spans edible consumption, industrial chemistry, and energy substitution with sharply divergent specification requirements.
- Food Industry:Frying, baking, and salad dressing applications absorb the largest volume share. High-oleic cultivars exceeding 80% monounsaturated fat content deliver extended fry life for foodservice operators in Argentina and Turkey.
- Personal Care:Emollient properties in lotions and hair formulations leverage linoleic acid content. French and Italian cosmetic formulators specify organic-certified grades with supercritical CO2 extraction to meet REACH registration timelines.
- Biofuels:Sunflower oil methyl ester production gains offtake momentum from EU Green Deal blending mandates. Refiners with flexible processing trains reconfigure output splits between food and fuel applications.
- Pharmaceuticals:Excipient and active ingredient applications require GMP-compliant refining with documented fatty acid profiling. EMA oversight sets impurity thresholds that constrain supplier qualification to integrated crush-to-refine operators.
Food industry channels command the dominant volume position; biofuels demonstrate the steepest expansion trajectory.
Packaging Type:
Container selection tracks buyer scale and shelf-life requirements from industrial tanker shipments to single-serve retail formats.
- Bottles:PET and glass containers target household consumers through supermarket retail. German and Dutch procurement teams prioritize supply security and emissions transparency over lowest-unit-cost sourcing in long-term offtake agreements.
- Cans:Metal packaging extends oxidative stability for export shipments to underpenetrated African markets. Regional traders establish bottling partnerships in Nigeria and Ethiopia to capture import demand.
- Pouches:Flexible film reduces material cost and shipping weight for price-sensitive emerging markets. Indian domestic distribution channels favor this format for rural penetration.
- Bulk:Tanker and flexitank shipments serve industrial fryer operations and biodiesel refineries. Black Sea port disruptions since 2022 force processors to rebuild origination networks around inland crushing assets.
Bulk packaging moves the largest tonnage; pouches are gaining share fastest in emerging consumption markets.
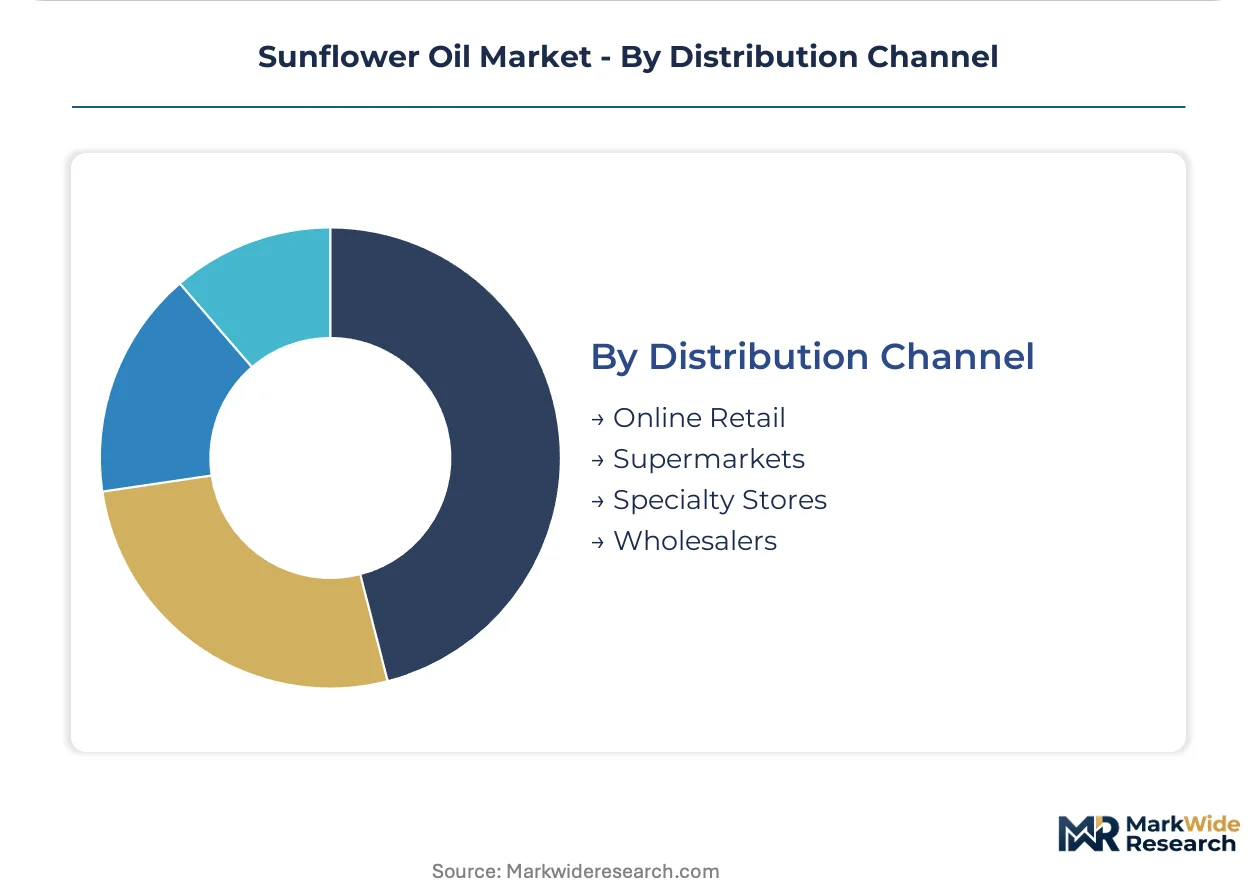
Distribution Channel:
Channel structure reflects buyer digital sophistication and the consolidation of supplier relationships around integrated operators with sustainability credentials.
- Online Retail:Direct-to-consumer platforms and subscription services capture health-conscious segments. Australian wellness consumers pay premiums for origin-certified sunflower oil with verified greenhouse gas footprints.
- Supermarkets:Mass retail dominates household penetration in mature consumption markets. Carbon intensity scoring integration under EU Carbon Border Adjustment Mechanism creates premium price tiers for deforestation-free grades.
- Specialty Stores:Organic and gourmet retailers curate cold-pressed and high-oleic variants. United Kingdom health food chains emphasize unrefined options with transparent supply chain documentation.
- Wholesalers:Foodservice distributors and industrial ingredient suppliers aggregate volume for manufacturing accounts. Kenya exhibits rising per capita edible oil consumption with limited local crush capacity, creating import dependency.
Supermarkets and wholesalers together anchor volume throughput; online retail climbs the fastest on penetration rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. India absorbs refined grades for fortified packaged foods; Germany prioritizes cold-pressed organic variants; Argentina scales high-oleic seed breeding for foodservice fry life.
India
FSSAI fortification mandates drive packaged food manufacturers to scale refined sunflower oil procurement with mandatory Vitamin A and D enrichment. The regulator's compliance deadlines are reshaping domestic distribution channels. Maharashtra and Gujarat host the largest bottling and refining clusters, with Adani Wilmar anchoring volume throughput in these states.
Germany
Health-conscious consumers pay substantial premiums for cold-pressed, high-linoleic variants through organic retailers and subscription platforms. ECHA REACH registration timelines govern new processing aids and refining catalysts. The Hamburg-Rotterdam corridor concentrates specialty oil import and supercritical CO2 extraction capacity for French and Italian cosmetic formulators.
Argentina
High-oleic Helianthus annuus cultivars exceeding 80% monounsaturated fat content deliver extended fry life for foodservice operators. Seed companies accelerate variety registration under national agricultural biotechnology frameworks. The Pampas region dominates seed production scale, with crushing assets clustered around Rosario port logistics.
Ukraine
Black Sea port access disruptions since 2022 have permanently altered how refiners manage geographic risk in sunflower oil procurement. Exporters invest in third-party audit infrastructure to maintain EU Deforestation Regulation compliance after December 2025. Odessa and Mykolaiv anchor the origination network, though inland crushing assets are rebuilding around alternative logistics corridors.
Turkey
Rising per capita edible oil consumption combines with limited local crush capacity to create import dependency and regional trading opportunities. The country's national food safety regulator aligns fortification requirements with export market access protocols. Istanbul and Izmir host bottling partnerships capturing demand from underpenetrated African markets including Nigeria and Ethiopia.
Sunflower Oil Market Vendor Landscape
Capability concentration sits with integrated crush-to-refine operators; scale advantage sits with multinational trading houses with origination networks. The vendor base stratifies across three tiers: Black Sea-anchored seed procurement specialists, European sustainability-certified refiners, and Asian packaged food distributors. Dominant competitive moves include backward integration into seed breeding programs and long-term offtake agreements with fixed volume-flexible pricing terms.
Among Black Sea-originated operators, Kernel Holding S.A. and Bunge Global SA exemplify the procurement-scale archetype, while Cargill Incorporated represents the integrated crushing asset model. These three companies anchor the competitive structure around which smaller regional processors and specialty organic producers position for defensible niches.
| Leading Market Players |
|---|
| Bunge Global SA |
| Kernel Holding S.A. |
| Cargill Incorporated |
| Avril Group |
| Adani Wilmar Ltd. |
| Archer Daniels Midland Company |
| Louis Dreyfus Company |
| COFCO Corporation |
| Wilmar International Limited |
| Others |
Supply Flow & Price Mechanics
Odessa and Mykolaiv crushing clusters anchor upstream capacity dynamics that translate directly into downstream pricing power for Black Sea-originated supply. Refiners with captive port access command premium contract terms against inland processors forced into higher logistics costs.
Pricing Analysis
Long-term offtake agreements with fixed volume-flexible pricing terms dominate industrial procurement, displacing spot market purchasing for packaged food manufacturers. Price differentiation rests on sustainability certification tier and geographic origin traceability under EU Deforestation Regulation compliance deadlines. Cost compression in standard refined grades is intensifying because Indonesian and Malaysian palm oil production cycles create periodic price undercuts. Bulk frying applications across price-sensitive food manufacturing segments exhibit highest price sensitivity, while German organic retailers show least sensitivity for cold-pressed variants.
Supply Chain Analysis
Sunflower seed feedstock draws from Ukraine, Russia, and Argentina as primary origination points, with crushing assets clustered around Black Sea and Rosario port logistics. Hexane solvent, high-oleic seed cultivars, and flexitank shipping containers constitute critical input dependencies. Single-source vulnerability concentrates in Black Sea port access, where disruptions since 2022 have permanently altered geographic risk management. Distribution runs through integrated crush-to-refine operators with documented sustainability credentials serving German and Dutch packaged food sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated packaged food manufacturers in India and Germany, as procurement teams prioritize supply security and emissions transparency over lowest-unit-cost sourcing in long-term agreements.
For Market Incumbents: Pre-empt margin erosion from palm oil price arbitrage by accelerating backward integration into high-oleic seed breeding programs in Argentina and Turkey. Invest in EU Deforestation Regulation audit-ready infrastructure before December 2025 compliance deadlines to defend premium positioning against compliance-ready Argentine and Turkish origin suppliers. For New Entrants and Emerging Players: Underpenetrated African markets in Nigeria, Ethiopia, and Kenya offer white-space capture through regional bottling and distribution partnerships. Target cold-pressed specialty channels in Australian wellness segments via direct-to-subscription platforms with verified greenhouse gas footprint documentation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated crush-to-refine operators with long-term offtake agreements and sustainability certification infrastructure. Over a multi-year horizon, acquisition focus should center on European specialty oil producers with supercritical CO2 extraction capacity serving French and Italian cosmetic formulators. Watch for EU Carbon Border Adjustment Mechanism implementation signals as inflection indicator for premium price tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Breeding | Kernel Holding S.A. and Bunge Global SA control upstream supply through high-oleic cultivar development in Argentina. |
| EU Deforestation Regulation Compliance Infrastructure | Third-party audit investments by Ukrainian exporters maintain market access against Argentine and Turkish competition. |
| Supercritical CO2 Extraction Adoption | French and Italian specialty oil producers collapse minimum efficient scale for premium-grade organic output. |
| Long-term Offtake Agreement Expansion | German and Dutch procurement teams consolidate supplier relationships around integrated operators with documented credentials. |
| African Distribution Partnership Establishment | Regional traders in Istanbul and Izmir capture import demand from Nigeria and Ethiopia bottling operations. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with crushing facility managers, procurement leads at packaged food manufacturers, seed company breeding directors, and Black Sea port logistics operators; and secondary validation through customs and trade flow databases, FSSAI regulatory filings, ECHA REACH registration documentation, and SEC disclosures from integrated multinationals. Bottom-up volume triangulation across seed crush capacity, refining throughput, and end-use consumption patterns was cross-checked against top-down value estimates derived from trade value flows and pricing benchmarks.
Forecast inputs considered product type segmentation across refined, unrefined, cold-pressed, and organic grades; end-use splits between food industry, personal care, biofuels, and pharmaceuticals; and packaging format differentiation across bottles, cans, pouches, and bulk shipments. CAGRs were derived from elasticity modeling against per capita edible oil consumption trends, policy mandate implementation timelines, and substitution dynamics with palm and soybean oils. Industry-specific inputs included FSSAI fortification compliance deadlines and EU Green Deal blending mandate progression.
Practitioners should monitor Black Sea port access stability, palm oil production cycle timing, and EU Deforestation Regulation enforcement intensity for early signals requiring forecast revision. Cross-checking against USDA Foreign Agricultural Service trade statistics and Oil World seed oil balance reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Casein Hydrolysate Market
Ingredients
South America Protein Market
Ingredients
Fermented Ingredients Market
Ingredients
Cocoa Maker Market
Ingredients
North America Corn Starch Market
Ingredients
Asia-Pacific Soy Protein Concentrate Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market
Ingredients
Mirepoix Market
Ingredients
Hen Egg White Protein Market
Ingredients
Karaya Gum Market
Ingredients
Olive Oil Market
Ingredients
Interesterified Fats Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Millet Protein Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Avocado Powder Market