
 Algae-Based Ingredients Market | 2026-2036
Algae-Based Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Algae-Based Ingredients Market Analysis
Modular formulation kits for algae-based ingredients are pivoting how dietary supplement producers configure finished products, letting buyers blend spirulina, chlorella, and carrageenan extracts in variable ratios rather than purchasing fixed premixes. Cargill Inc. leverages its global supply chain infrastructure to secure raw algae biomass across multiple continents. DSM-Firmenich sustains technology leadership in fermentation-derived omega-3 and astaxanthin platforms. Corbion N.V. specializes in microalgae cultivation systems with controlled-environment photobioreactors.
Algae-based ingredients comprise proteins, lipids, polysaccharides, and pigments extracted from microalgae and macroalgae through cell disruption, solvent extraction, or supercritical CO2 processing, serving as functional inputs for nutrition, texture modification, and coloration in formulated goods. Powder formulations dominate commercial volumes due to extended shelf stability and ease of incorporation into dry food matrices, while liquid extracts command premium positioning in cosmetics and beverage applications where solubility and sensory profile determine formulation success. Nutraceutical applications lead value generation as dietary supplement producers prioritize clinically substantiated algae-derived bioactives.
EFSA novel food regulations, EU Green Deal bioeconomy frameworks, and REACH chemical safety standards collectively shape market access, ingredient purity benchmarks, and sustainability claims verification for algae-based inputs sold across European markets. FDA GRAS self-affirmation pathways and USDA organic certification requirements add compliance layers for suppliers targeting North American nutraceutical and food channels. Stakeholders must monitor evolving carbon accounting methodologies and biotechnology disclosure rules that will determine which cultivation and extraction processes qualify for preferred procurement status.
Market Dynamics
Fermentation biotechnology infrastructure is consolidating production economics for algae-derived bioactives, compressing cost structures and enabling modular supply configurations that bypass traditional open-pond cultivation limitations.
Growth Catalysts
- EU Green Deal bioeconomy targets:Binding sustainability quotas for food manufacturers in Germany and France are mandating algae protein incorporation into clean-label formulations, creating guaranteed offtake channels for chlorella and spirulina suppliers.
- Photobioreactor automation:Controlled-environment cultivation systems are eliminating batch-to-batch variability in astaxanthin and omega-3 yields, improving contract reliability for nutraceutical buyers.
- Denmark cultivation clusters:Concentrated biotechnology infrastructure around Copenhagen and Kalundborg is attracting ingredient suppliers seeking shared fermentation capacity and technical talent pools.
Market Restraints
- EFSA novel food authorization timelines:Protracted safety assessment procedures for new algae species are extending time-to-market by 18-36 months and freezing R&D pipelines for emerging producers.
- Biomass input concentration:Premium spirulina supply concentrates in sub-Saharan African and South Asian open-pond operations, exposing buyers to climate volatility and geopolitical disruption.
- Solvent extraction cost structure:Supercritical CO2 processing equipment requires substantial capital deployment, limiting mid-scale entrants to lower-margin spray-dried powder segments.
Strategic Opportunities
- Cosmetics formulation white space:Liquid algae extracts command premium positioning in South Korean and French skincare markets where solubility and sensory profile determine procurement decisions.
- USDA organic certification pathway:USDA organic algae ingredients access price premiums in North American natural products channels, with certification creating defensible supplier differentiation.
- Modular formulation kits:Variable-ratio blending systems for spirulina, chlorella, and carrageenan extracts are displacing fixed premix purchases among dietary supplement contract manufacturers.
Industry Challenges
- Phycocyanin stabilization expertise:Technical talent scarcity in pigment extraction and encapsulation is constraining expansion into high-value natural colorant applications for beverage manufacturers.
- REACH chemical safety documentation:Comprehensive substance dossier requirements for novel algae-derived compounds are consuming regulatory affairs bandwidth and delaying EU market entry.
- Batch consistency certification:Lot-to-lot variation in algae bioactive content complicates USP or FCC monograph compliance for pharmaceutical-grade ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algae-Based Ingredients Market |
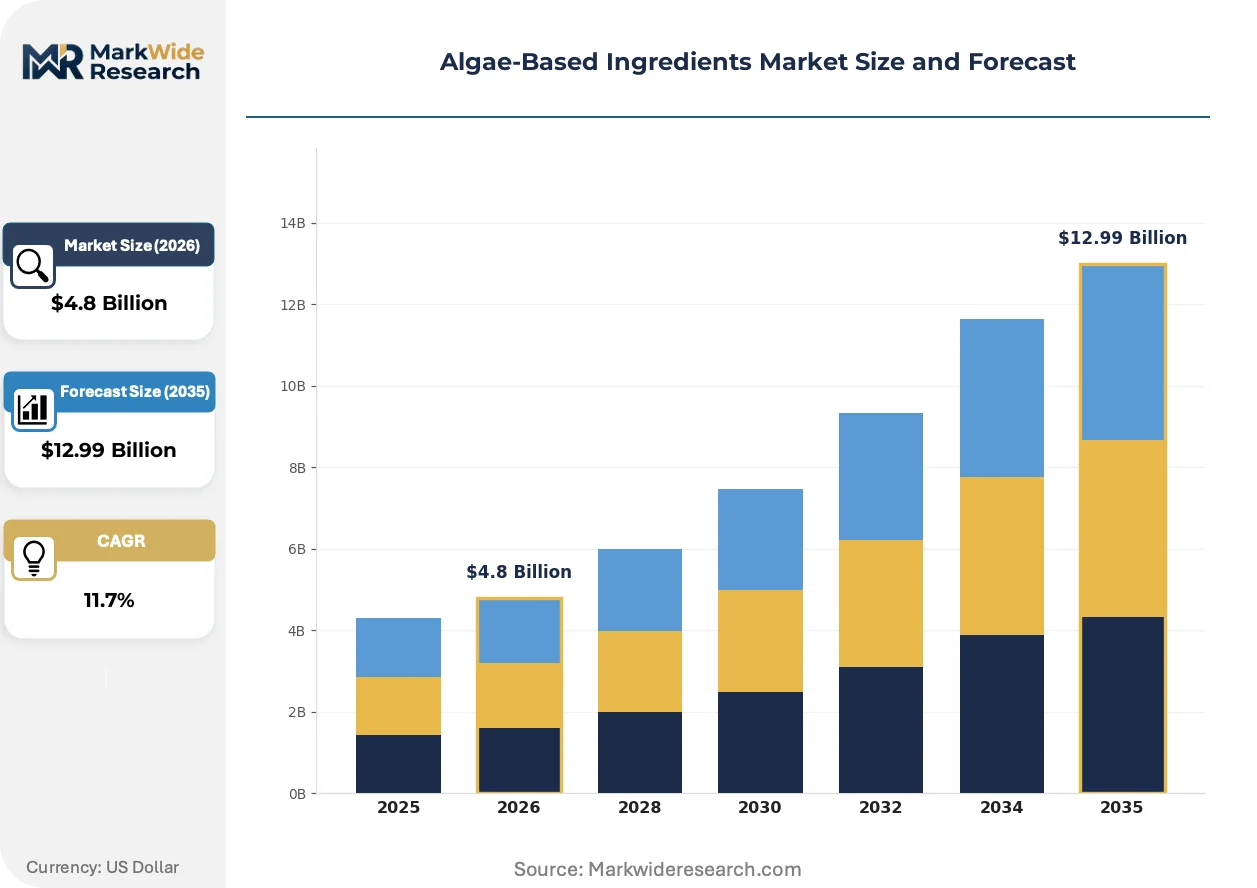
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirulina, Chlorella, Carrageenan, Agar Application: Nutraceuticals, Food & Beverages, Cosmetics, Animal Feed End User: Food Manufacturers, Dietary Supplement Producers, Cosmetic Companies, Farmers Form: Powder, Liquid, Extract, Capsules |
| Companies Covered | Cargill Inc., Corbion N.V., DSM-Firmenich, BASF SE, Archer Daniels Midland Company, Marine Hydrocolloids, Taiwan Chlorella Manufacturing Company, Cyanotech Corporation, Aliga Microalgae, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algae-Based Ingredients Market Emerging Trajectories
Bioprocess engineering advances and regulatory pathway maturation are compressing production timelines while reshaping how buyers configure supply relationships across nutrition, cosmetics, and pharmaceutical end-uses.
Continuous harvesting systems integrated with real-time biomass monitoring sensors are automating cell density optimization in photobioreactor operations. Nutraceutical contract manufacturers in Denmark and the Netherlands are adopting these platforms at accelerating rates to secure supply commitments for clinically substantiated omega-3 and astaxanthin ingredients. This automation is compressing unit economics and enabling smaller-batch production runs that match supplement brand SKU proliferation.
REACH chemical safety standards and the EU Green Deal's carbon accounting methodologies are mandating lifecycle disclosure for algae cultivation inputs. Industrial consequence includes mandatory documentation of water, energy, and nutrient consumption across supply chains, with EFSA novel food applications now requiring embedded carbon footprints. Nutraceutical and food ingredient segments are responding by investing in closed-loop photobioreactor systems that qualify for preferred procurement status under emerging sustainability scoring frameworks.
Clean-label formulation mandates from European retailers are rotating procurement specifications toward single-ingredient algae powders with transparent provenance claims. Fixed premix purchases are giving way to buyer-controlled blending configurations where supplement producers specify exact spirulina-to-chlorella ratios and carrageenan viscosity grades. This specification control is most visible in German and French markets where private-label dietary supplement brands compete on ingredient transparency credentials.
Algae-Based Ingredients Market Segmentation
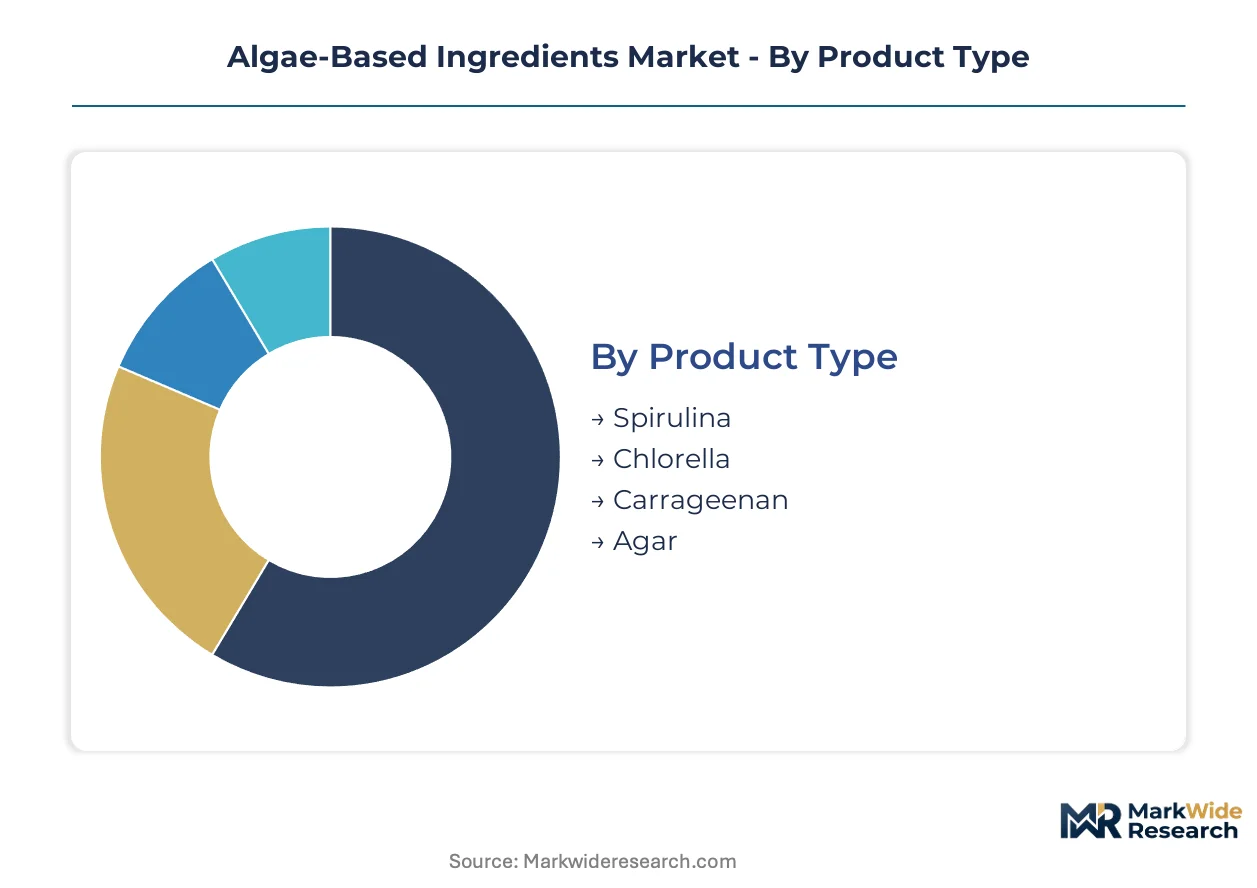
Ingredient form and application destination determine margin capture across algae supply chains. Powder formats dominate volume throughput while liquid extracts secure premium positioning in cosmetics. Procurement patterns diverge sharply between food manufacturers seeking cost-efficient bulk inputs and cosmetic companies prioritizing sensory performance.
Product Type:
Volume concentrates in commodity powders while premium concentrates in specialized extracts with defined bioactive specifications.
- Spirulina:Cyanobacterial biomass with protein content exceeding 60% dry weight serves as the foundational input for mass-market dietary supplements. German and French food manufacturers are scaling purchases for clean-label protein fortification under EU Green Deal bioeconomy procurement mandates. EFSA novel food pathways have streamlined authorization for established suppliers, locking in incumbent advantages.
- Chlorella:Chlorophyte microalgae with superior chlorophyll concentration and cell wall complexity requiring mechanical disruption for bioavailability. Demand is concentrating in Denmark's cultivation clusters where photobioreactor automation eliminates batch-to-batch variability for nutraceutical contract manufacturers. Cell wall processing expertise separates premium suppliers from commodity traders.
- Carrageenan:Sulfated polysaccharide from red macroalgae functioning as gelling and stabilizing agent in processed foods.
- Agar:Gelose polysaccharide extracted from Rhodophyta species with superior gel strength for microbiological media and confectionery applications.
Today's leader: Spirulina. Tomorrow's challenger: Chlorella.
Application:
End-use destinations range from clinical substantiation requirements in nutraceuticals to sensory-driven formulation in cosmetics.
- Nutraceuticals:Dietary supplement producers prioritize clinically substantiated algae-derived bioactives with USP or FCC monograph compliance. DSM-Firmenich's fermentation-derived omega-3 and astaxanthin platforms command technology leadership here. Batch consistency certification remains the binding constraint for pharmaceutical-grade suppliers.
- Food & Beverages:Clean-label mandates from European retailers are rotating procurement toward single-ingredient algae powders with transparent provenance claims. Cargill Inc. leverages global supply chain infrastructure to secure raw biomass across multiple continents for this segment. Texture modification and protein fortification drive specification sheets.
- Cosmetics:Liquid algae extracts with defined solubility and sensory profiles command premium positioning in South Korean and French skincare markets.
- Animal Feed:Aquaculture and livestock producers utilize algae meal for pigment deposition and omega-3 enrichment in finished animal products.
Nutraceuticals anchor current value generation. Cosmetics represent the steepest expansion trajectory as formulation science advances.
End User:
Customer type determines specification control, with contract manufacturers accepting standardized inputs while brand owners demand configurable ratios.
- Food Manufacturers:Industrial-scale buyers in Germany and France are incorporating chlorella and spirulina into clean-label formulations under binding sustainability quotas. REACH chemical safety documentation and EU Green Deal carbon accounting methodologies shape supplier qualification. Volume commitments favor established players with multi-continent biomass sourcing.
- Dietary Supplement Producers:Contract manufacturers are displacing fixed premix purchases with modular formulation kits enabling variable-ratio blending of spirulina, chlorella, and carrageenan extracts. This specification control is most visible in German and French private-label markets competing on transparency credentials. Corbion N.V.'s controlled-environment photobioreactor systems target this customer tier.
- Cosmetic Companies:Formulation houses prioritize liquid extract solubility and sensory performance over cost minimization.
- Farmers:Direct procurement of algae meal for aquaculture and livestock operations concentrates in coastal regions with established seaweed harvesting infrastructure.
Food manufacturers dominate current volume. Dietary supplement producers are gaining procurement sophistication fastest.
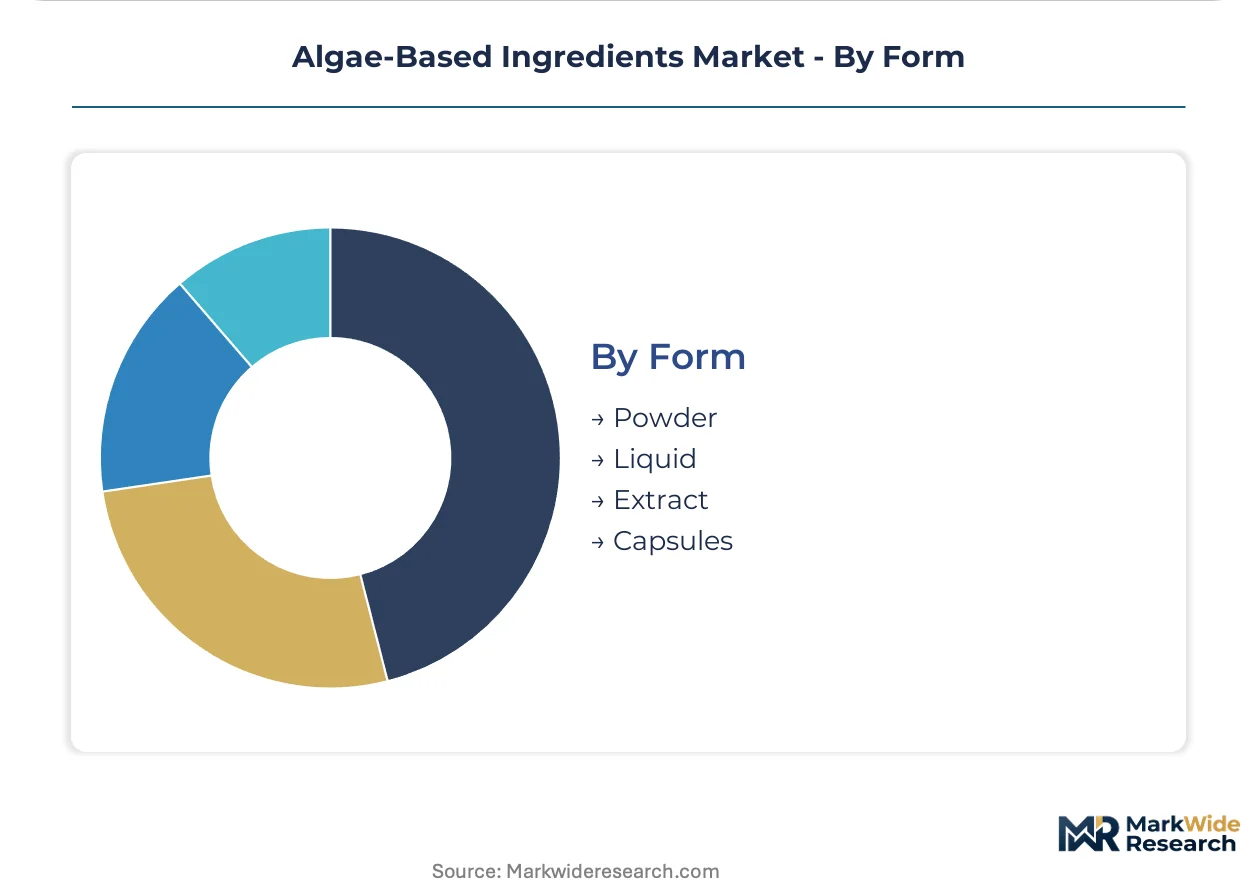
Form:
Physical presentation dictates shelf stability, incorporation ease, and margin structure across supply tiers.
- Powder:Spray-dried and freeze-dried formulations dominate commercial volumes due to extended shelf stability and ease of incorporation into dry food matrices. Supercritical CO2 processing equipment requirements limit mid-scale entrants, concentrating supply among capital-deployed players. Powder specifications vary by particle size, moisture content, and bioactive retention rates.
- Liquid:Aqueous and oil-based extracts command premium positioning in cosmetics and beverage applications where solubility and sensory profile determine formulation success. Phycocyanin stabilization expertise scarcity constrains expansion into high-value natural colorant applications. Liquid form requires cold chain logistics for bioactive preservation.
- Extract:Concentrated bioactive fractions including omega-3 fatty acids, astaxanthin, and phycocyanin obtained through solvent or supercritical processing.
- Capsules:Pre-dosed unit formats for direct-to-consumer supplement channels with defined potency claims and encapsulation technology requirements.
Powder leads on volume throughput. Liquid extracts are climbing the fastest on value per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algae cultivation originated in Japan's post-war food security programs before migrating to Taiwan's commercial spirulina farms in the 1960s. European biotechnology infrastructure now hosts the most sophisticated controlled-environment production systems.
Germany
Food manufacturers in Bavaria and North Rhine-Westphalia are scaling chlorella purchases for clean-label protein fortification under binding EU Green Deal bioeconomy quotas. EFSA novel food authorization pathways have streamlined regulatory clearance for established suppliers. The Hamburg biotechnology corridor concentrates fermentation infrastructure serving nutraceutical contract manufacturers.
France
Cosmetic formulators in Île-de-France command premium liquid algae extracts for skincare applications where sensory profile determines procurement. REACH chemical safety documentation requirements shape supplier qualification protocols. The Brittany coastal region maintains traditional macroalgae harvesting operations supplying carrageenan processors.
Denmark
Cultivation clusters around Copenhagen and Kalundborg attract ingredient suppliers seeking shared photobioreactor capacity and technical talent pools. The Danish Energy Agency's biorefinery funding programs accelerate industrial biotechnology deployment. Kalundborg's industrial symbiosis network enables nutrient recycling between algae cultivation and adjacent pharmaceutical operations.
United States
Dietary supplement producers in California and Utah prioritize USDA organic certification pathways for algae ingredients accessing natural products price premiums. FDA GRAS self-affirmation procedures add compliance layers for novel bioactive introductions. The Pacific Northwest hosts astaxanthin extraction specialists serving cosmetic and nutraceutical channels.
China
Open-pond spirulina operations in Yunnan and Inner Mongolia supply global commodity biomass volumes despite climate volatility exposure. The Ministry of Agriculture's rural development programs subsidize algae cultivation as alternative protein sources. Qingdao's marine biotechnology zone concentrates macroalgae processing infrastructure for Asian hydrocolloid markets.
Algae-Based Ingredients Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and bioactive specification depth. The vendor base stratifies between capital-deployed multinationals with multi-continent biomass sourcing and regional specialists with cultivation technology advantages. Three archetypes dominate: integrated agribusiness conglomerates with global supply chain infrastructure, fermentation biotechnology specialists with controlled-environment platforms, and coastal harvesting cooperatives with macroalgae extraction expertise. Competitive moves concentrate on capacity expansion in Denmark and strategic partnerships for EFSA novel food authorization acceleration.
Among Netherlands-based biotechnology specialists, Corbion N.V. exemplifies controlled-environment photobioreactor expertise. DSM-Firmenich represents fermentation-derived bioactive leadership through its omega-3 and astaxanthin platforms. Cargill Inc. anchors the integrated agribusiness tier with global raw biomass sourcing infrastructure spanning multiple continents. These three occupy distinct competitive positions without direct segment overlap.
| Leading Market Players |
|---|
| Cargill Inc. |
| Corbion N.V. |
| DSM-Firmenich |
| BASF SE |
| Archer Daniels Midland Company |
| Marine Hydrocolloids |
| Taiwan Chlorella Manufacturing Company |
| Cyanotech Corporation |
| Aliga Microalgae |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 processing equipment costs cascade through algae ingredient supply chains, concentrating premium extraction capacity among capital-deployed multinationals while mid-scale entrants remain tethered to lower-margin spray-dried powder segments. This upstream capital intensity stratifies downstream pricing power between fermentation biotechnology specialists and open-pond commodity biomass traders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade astaxanthin with USP monograph compliance from food-grade spirulina powders and commodity algae meal. Price differentiation rests on certification tier — EFSA novel food authorization and USDA organic pathways command substantial premiums over uncertified biomass. Pricing pressure stems from solvent extraction cost compression as photobioreactor automation spreads through Denmark cultivation clusters. Dietary supplement contract manufacturers exhibit highest price sensitivity, while South Korean and French cosmetic formulators prioritize sensory performance over cost minimization.
Supply Chain Analysis
Freight costs for cold-chain liquid extract logistics constrain geographic reach for premium algae bioactives, favoring regional production hubs over centralized manufacturing. Raw biomass supply concentrates in China's Yunnan and Inner Mongolia open-pond operations, Denmark's Copenhagen-Kalundborg photobioreactor clusters, and sub-Saharan African spirulina farms. Input dependencies span nitrogen nutrient feeds, specialized LED lighting systems, and pharmaceutical-grade encapsulation materials. Single-source vulnerability runs through premium spirulina supply exposed to climate volatility in sub-Saharan Africa. Distribution runs through Cargill's global supply chain infrastructure for commodity powders and direct technical partnerships for customized nutraceutical formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement specifications rotate toward clinically substantiated bioactives with transparent provenance documentation. The demand-shift toward premium specifications with embedded carbon footprints and EFSA novel food authorization locks in advantages for capital-deployed incumbents.
For Market Incumbents: Cement technology leadership in fermentation-derived omega-3 and astaxanthin platforms through continued photobioreactor automation investment in Denmark cultivation clusters. Defend against emerging open-pond commodity traders by deepening backward integration into controlled-environment biomass production, eliminating climate volatility exposure that threatens batch consistency certification.
For New Entrants and Emerging Players: The gap between premium liquid extract pricing and economy powder margins offers white-space entry through modular formulation kits serving dietary supplement contract manufacturers in Germany and France. Target private-label brands competing on ingredient transparency credentials with variable-ratio blending configurations. Pursue USDA organic certification pathway for North American natural products channel access.
For Investors and Strategic Acquirers: Consolidation pressure builds where batch consistency certification capabilities concentrate among a limited pool of fermentation biotechnology specialists with controlled-environment platforms. Long-term viability favors acquisition targets with embedded photobioreactor automation and EFSA novel food authorization track records. Watch for inflection signals in carbon accounting methodology adoption that would disqualify open-pond cultivation from preferred procurement status.
| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Capacity Expansion | Denmark cultivation clusters attract shared fermentation infrastructure investment from multiple ingredient suppliers. |
| EFSA Novel Food Authorization Acceleration | Streamlined regulatory pathways compress time-to-market for chlorella and spirulina suppliers in EU markets. |
| Backward Integration into Controlled-Environment Cultivation | Fermentation biotechnology specialists secure captive biomass supply insulated from climate volatility exposure. |
| Modular Formulation Kit Development | Variable-ratio blending systems displace fixed premix purchases among German and French contract manufacturers. |
| USDA Organic Certification Investment | Certification creates defensible supplier differentiation in North American natural products channels. |
Methodological Framework
Direct dialogue with photobioreactor operations managers, regulatory affairs specialists at EFSA-authorized suppliers, dietary supplement contract manufacturing procurement leads, and cosmetic formulation houses grounded qualitative insights. Secondary validation drew from EU novel food application databases, REACH chemical safety dossiers, USDA organic certification records, and customs trade data for algae biomass imports. Bottom-up modeling of cultivation capacity and extraction throughput triangulated against top-down demand segmentation across nutraceutical, food, and cosmetic end-uses.
Segment-level projections across ingredient form, application destination, and geographic production hub informed value and volume outputs across the analysis window. Modeled dimensions encompassed powder versus liquid extract format, pharmaceutical-grade versus food-grade certification tier, and controlled-environment versus open-pond cultivation origin. CAGRs derived from trend extrapolation of photobioreactor automation adoption rates and clean-label procurement mandate expansion through EU Green Deal implementation. Forecast inputs incorporated EFSA authorization pipeline velocity and carbon accounting methodology adoption curves.
The model assumes a particular technology adoption path; alternative pathways for open-pond cultivation cost reduction through climate-resilient strain engineering would alter the outlook for commodity biomass pricing. Forecasts embed assumptions regarding EFSA regulatory capacity and EU Green Deal bioeconomy quota enforcement that material regulatory delays or political reversal would revise. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Chewing Gum Base Market
Ingredients
Cooking Oil Market
Ingredients
Egg Yolk Powder Market
Ingredients
Global Pregelatinized Starch Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Drum to Hopper Blends Market
Ingredients
United States Soy Protein Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Peanut Flour Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Wheat Malt Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
Fluid Lecithin Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Buckwheat–Mediterranean Grain Blend Ingredients Market