
 All Purpose Flour Market | 2026-2036
All Purpose Flour Market Size, Share, and Industry Trends Forecast 2026-2036
All Purpose Flour Market Outlook
North American milling capacity expansion is reshaping trade flows in wheat-derived commodities. Ardent Mills leverages its integrated grain elevator network to secure cost advantages across the Great Plains. General Mills sustains brand loyalty through proprietary flour blends tailored to commercial bakery specifications. King Arthur Baking Company differentiates via specialty milling expertise and direct-to-consumer channel control.
All purpose flour denotes a refined wheat flour with protein content typically ranging from 9% to 12%, milled from hard red winter or soft red winter wheat blends and designed for versatile baking and cooking applications without requiring additional leavening agents. The organic and gluten-free product type categories command premium positioning as health-conscious consumers shift away from conventional refined options. Food manufacturers among end users represent the most concentrated margin pool due to long-term supply contracts and volume-based procurement structures.
The USDA enforces grading standards that define protein content and ash specifications, directly influencing product classification and interstate commerce eligibility. The FDA oversees allergen labeling requirements under FALCPA, compelling manufacturers to declare wheat content and cross-contamination risks. Stakeholders must monitor evolving FDA guidance on bioengineered food disclosure as gene-edited wheat varieties approach commercialization thresholds.
Market Dynamics
Urbanization across India and Southeast Asia is compressing the traditional loose flour distribution model, forcing millers to build branded packaged supply chains capable of reaching fragmented retail endpoints.
Growth Catalysts
- EU Green Deal compliance mandates:Sustainability requirements for grain sourcing are accelerating certified supply chain investments across European milling operations.
- Commercial bakery procurement consolidation:Food manufacturers are locking multi-year flour supply contracts to secure volume stability and hedge input volatility.
- India:Urban consumer preference for hygienic packaged formats is displacing loose commodity purchases in tier-1 and tier-2 cities.
Market Restraints
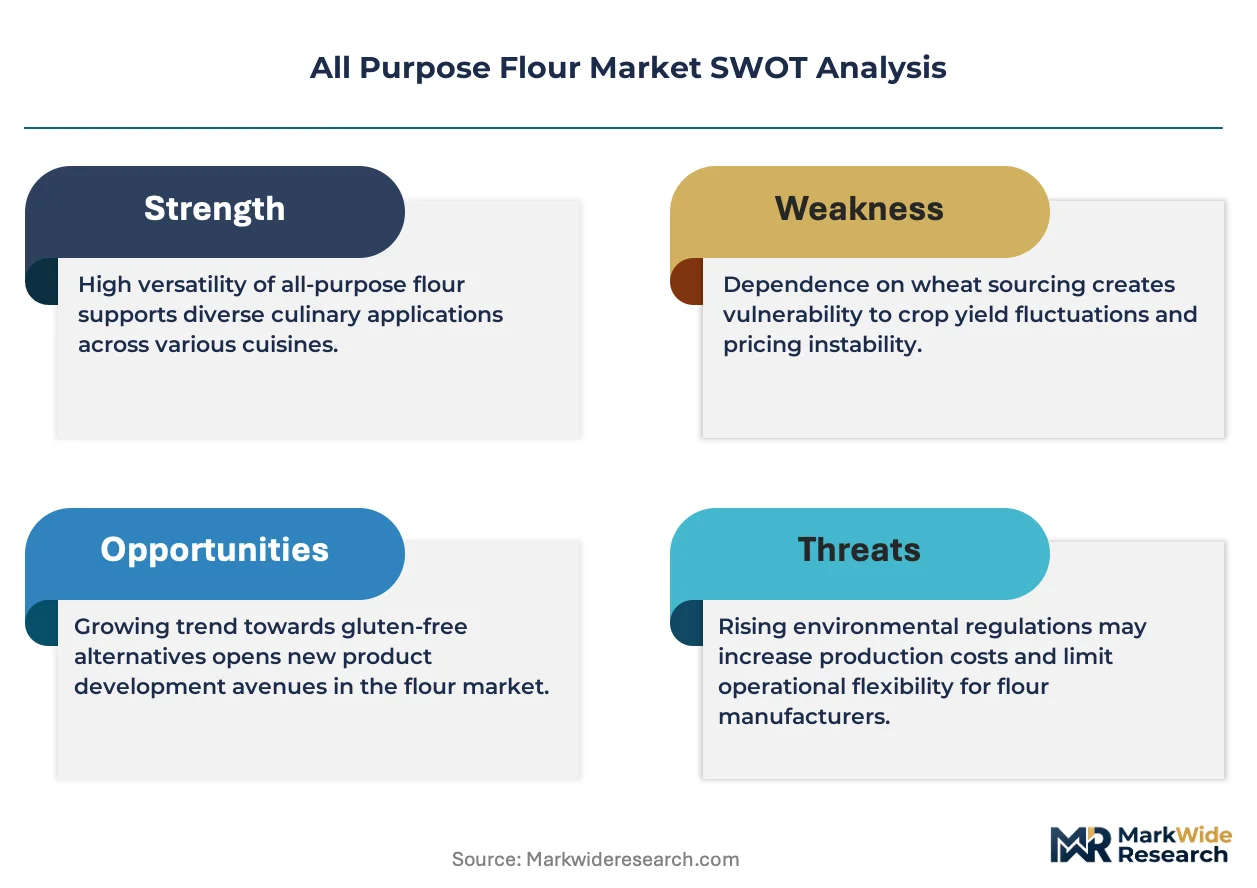
- Hard red winter wheat price volatility:Weather-driven yield fluctuations in the US Great Plains transmit directly to miller cost structures.
- Great Plains elevator concentration:Regional grain handling infrastructure creates single-point vulnerabilities for national supply security.
- Gluten-free substitution:Rice flour, almond flour, and cassava-based alternatives are capturing health-conscious household spending.
Strategic Opportunities
- Indonesia:Underpenetrated modern trade channels present first-mover advantages for branded flour entrants.
- Gene-edited wheat varieties:CRISPR-derived low-gluten and high-protein strains approaching commercial thresholds offer product differentiation pathways.
- E-commerce direct-to-consumer:Specialty millers are bypassing traditional distributor networks to capture margin and consumer data.
Industry Challenges
- USDA grading certification timelines:Protein content and ash specification testing creates batch-release bottlenecks for export-bound production.
- Legacy mill equipment retrofit costs:Converting stone and roller mills for organic handling requires capital outlays that strain mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All Purpose Flour Market |
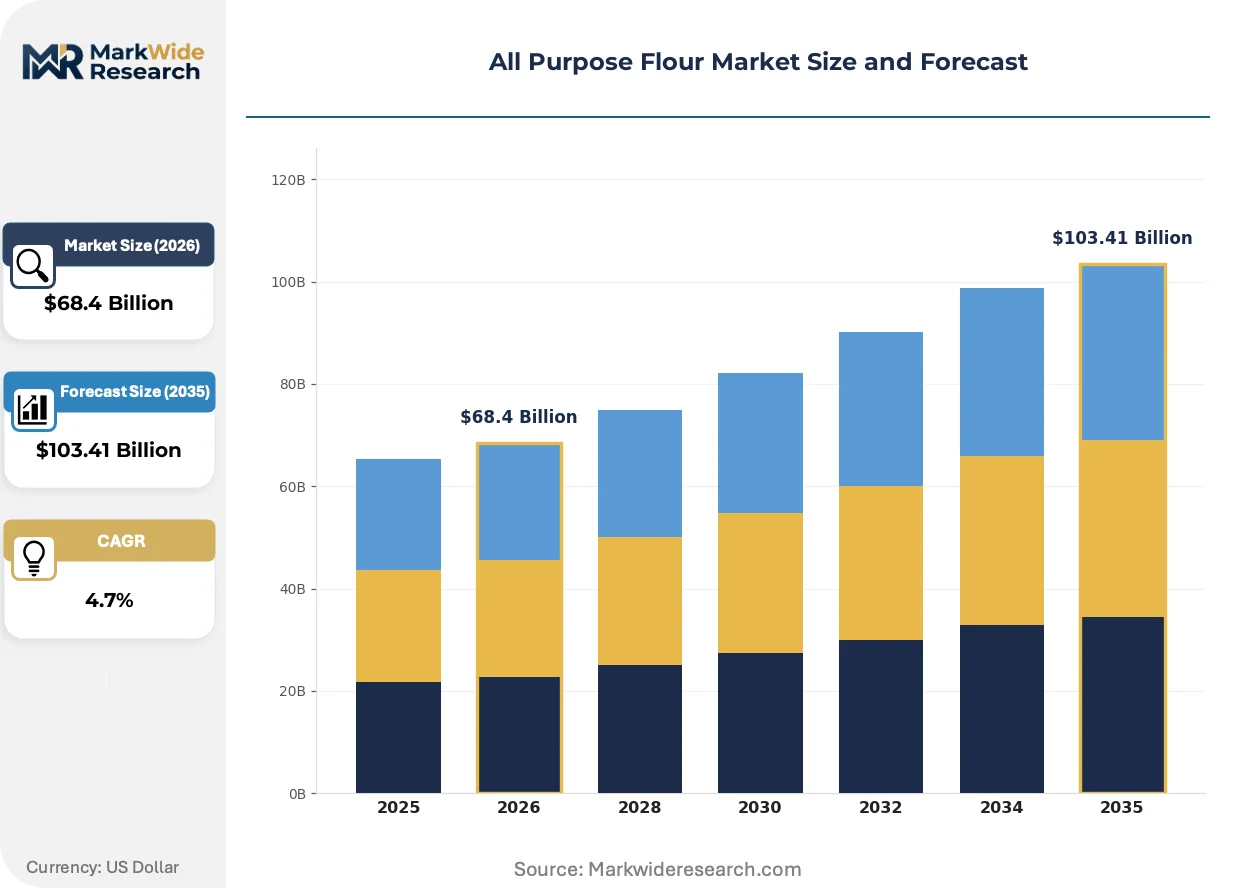
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Gluten-Free, Whole Wheat, Conventional End User: Bakeries, Restaurants, Home Cooks, Food Manufacturers Packaging Type: Bags, Bulk Containers, Boxes, Pouches Distribution Channel: Online Retailers, Supermarkets, Local Stores, Wholesale |
| Companies Covered | Archer Daniels Midland Company, General Mills, Ardent Mills, King Arthur Baking Company, Interflour Group, Goodmills Group, Acarsan Holding, Manildra Group, Bob's Red Mill Natural Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All Purpose Flour Market Strategic Shifts
Digital traceability and precision milling technologies are compressing quality variance and enabling segment-specific flour customization at industrial scale.
Near-infrared spectroscopy integrated into mill flow systems is collapsing the gap between laboratory analysis and real-time production adjustment. Large commercial bakeries in Germany and the Netherlands are adopting these inline monitoring arrays to maintain dough consistency across multiple production sites. The technology is collapsing traditional batch-to-batch quality drift that previously required manual intervention and reblending.
The FDA's evolving guidance on bioengineered food disclosure is forcing millers to segregate gene-edited wheat streams ahead of anticipated commercialization. US-based grain handlers are investing in identity-preserved supply chains to maintain regulatory optionality. Organic and non-GMO certified product lines face the most complex compliance mapping as disclosure thresholds remain under regulatory review.
Food service distributors are consolidating flour SKUs and demanding performance-specified blends rather than commodity grades. Restaurant chains in the United Arab Emirates and Saudi Arabia are shifting procurement toward custom-milled blends with guaranteed protein ranges and absorption specifications. This specification-driven buying is most visible in the Gulf Cooperation Council where centralized kitchen models require ingredient consistency across dispersed outlets.
All Purpose Flour Market Segmentation
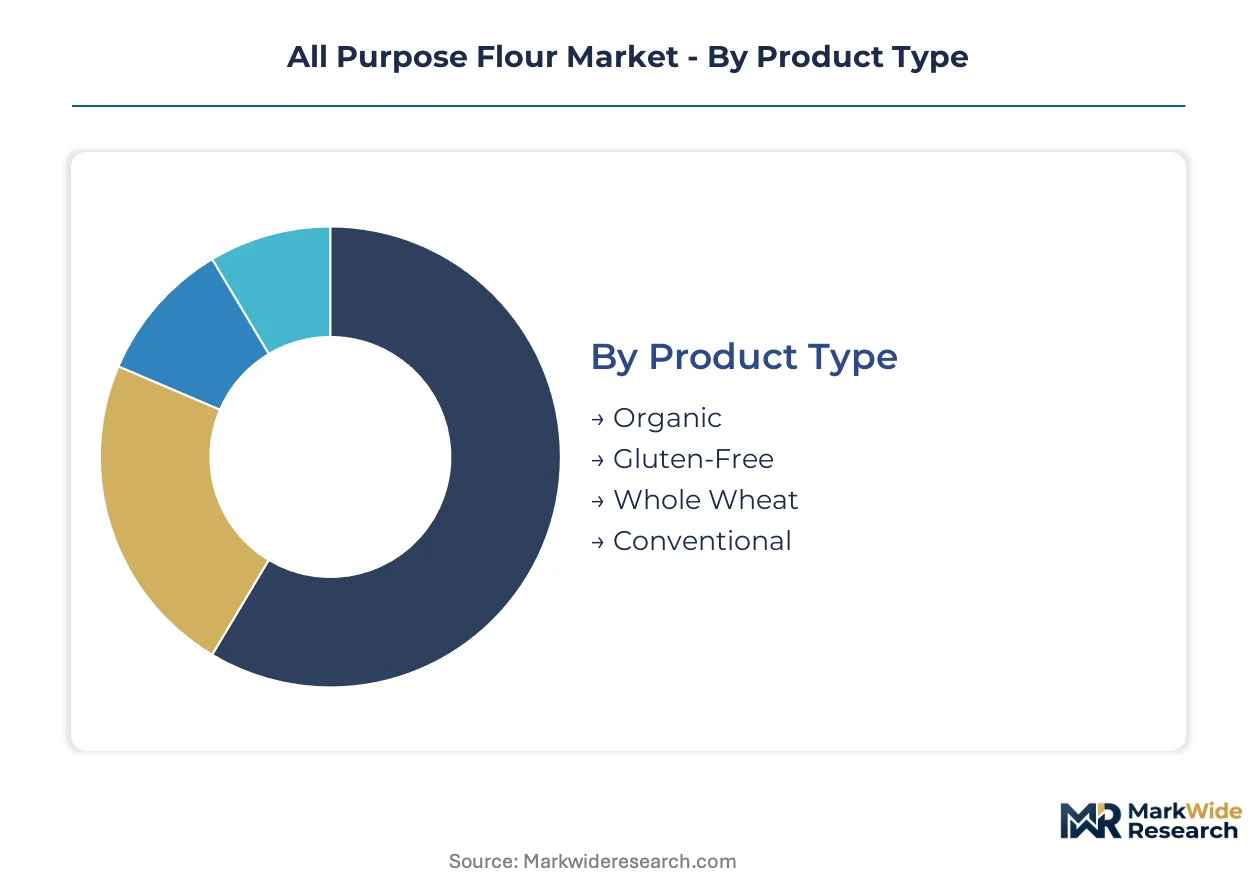
Segmentation in all purpose flour markets separates commodity-grade volume plays from premium positioning strategies. Protein specifications, certification tiers, and packaging formats create distinct margin pools that reward specialized supply chain investments. Understanding these divides reveals where capital deployment captures pricing power versus where scale efficiency dominates.
Product Type:
Mature conventional grades anchor volume throughput while emerging certified categories command premium extraction.
- Conventional:Refined wheat flour with 9-12% protein content milled from hard red winter or soft red winter blends serves as the baseline specification for industrial baking and household cooking. Food manufacturers in India and Southeast Asia lock multi-year procurement contracts around this grade to secure input cost stability for high-volume production lines.
- Organic:Certified grain sourcing with prohibited synthetic pesticide and fertilizer inputs requires segregated handling infrastructure from field to mill. EU Green Deal compliance mandates are accelerating certified supply chain investments across European milling operations, tightening available organic grain flows.
- Gluten-Free:Rice flour, almond flour, and cassava-based alternatives formulated to replace wheat protein functionality in baking applications. Health-conscious household spending is shifting toward these substitutes in tier-1 US and European cities.
- Whole Wheat:Stone-ground or roller-milled flour retaining bran and germ fractions for elevated fiber and nutrient content. Indian urban consumers in tier-2 cities are displacing loose commodity purchases with branded packaged whole wheat options.
Conventional handles the majority of throughput; organic is gaining share fastest on certification premiums.
End User:
Customer type stratification separates specification-driven commercial buyers from price-sensitive household purchasers.
- Food Manufacturers:Industrial bakeries and processed food producers requiring guaranteed protein ranges, absorption specifications, and batch consistency for automated production lines. Restaurant chains in the United Arab Emirates and Saudi Arabia are shifting procurement toward custom-milled blends with centralized kitchen models demanding ingredient uniformity across dispersed outlets.
- Bakeries:Artisan and commercial bread producers sourcing flour with specific fermentation performance and dough handling characteristics. Bakery chains across Southeast Asia are expanding procurement volumes for premium flour blends as modern trade penetration deepens.
- Restaurants:Food service operators purchasing smaller-format packaging with flexible delivery schedules matched to menu cycles. Indonesian underpenetrated modern trade channels present first-mover advantages for branded flour entrants targeting this segment.
- Home Cooks:Household consumers selecting retail-packaged flour based on brand recognition, price positioning, and recipe versatility. Urbanization across India is compressing the traditional loose flour distribution model, forcing millers to build branded packaged supply chains capable of reaching fragmented retail endpoints.
Food manufacturers concentrate margin capture through contract structures; bakeries are expanding most quickly on out-of-home consumption growth.
Packaging Type:
Format selection traces the tension between distribution economics and consumption occasion fragmentation.
- Bags:Multi-layer paper or plastic sacks ranging from 1kg household sizes to 25kg commercial formats, dominating retail and small-trade channels. German and Dutch commercial bakeries adopting inline near-infrared spectroscopy systems maintain dough consistency specifications that bagged flour must meet across multiple production sites.
- Bulk Containers:Tote bins, silo trucks, and railcar shipments serving industrial users with dedicated handling infrastructure and high-volume offtake commitments. Great Plains elevator concentration creates single-point vulnerabilities for national bulk supply security.
- Boxes:Corrugated cases with inner liners protecting flour from moisture and contamination during longer distribution cycles. US-based grain handlers investing in identity-preserved supply chains for gene-edited wheat segregation utilize box formats for regulatory optionality in specialty shipments.
- Pouches:Flexible laminated films with reseal features targeting premium positioning and single-use convenience in urban retail environments. Specialty millers bypassing traditional distributor networks through e-commerce direct-to-consumer channels favor pouch formats for shipping economics and brand presentation.
Bags carry the volume base; pouches are climbing the fastest on channel diversification.
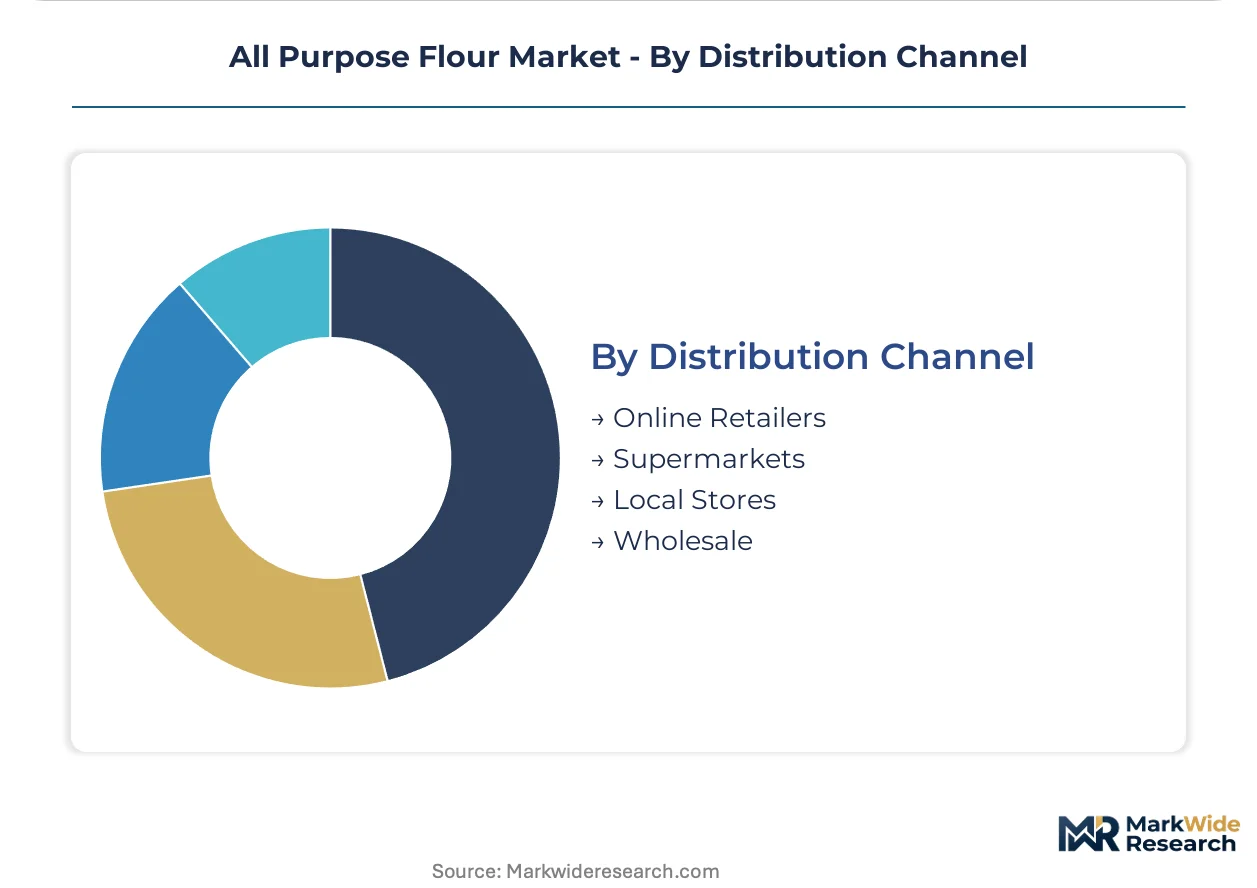
Distribution Channel:
Channel configuration determines margin retention and consumer data access versus scale reach.
- Supermarkets:Modern trade outlets with centralized distribution, category management, and private label competition dominating branded packaged flour sales in developed markets. Urban Indian consumers shifting toward hygienic packaged formats drive supermarket channel expansion in tier-1 and tier-2 cities.
- Wholesale:Distributor networks serving independent bakeries, restaurants, and institutional food service with volume pricing and credit terms. Food service distributors in the Gulf Cooperation Council are consolidating flour SKUs and demanding performance-specified blends rather than commodity grades.
- Online Retailers:E-commerce platforms and direct-to-consumer websites enabling specialty millers to capture margin and consumer data outside traditional distributor networks. King Arthur Baking Company leverages direct-to-consumer channel control to sustain specialty milling expertise positioning.
- Local Stores:Traditional kirana shops, corner stores, and independent grocers maintaining loose flour distribution in rural and semi-urban India. Legacy mill equipment retrofit costs for organic handling strain mid-tier operators serving this channel.
Supermarkets anchor mass-market throughput; online retailers show the steepest expansion trajectory on data-capture economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes all purpose flour predominantly through loose commodity channels, while the United States and Germany favor branded packaged formats with protein specifications. This consumption-mix differential shapes miller investment priorities across geographies.
United States
Commercial bakeries in the Great Plains lock multi-year procurement contracts around hard red winter wheat specifications. The USDA enforces grading standards that define protein content and ash specifications, directly influencing interstate commerce eligibility. Ardent Mills leverages its integrated grain elevator network across the Great Plains to secure cost advantages in bulk supply security.
Germany
Industrial bakeries adopt near-infrared spectroscopy systems to maintain dough consistency across multiple production sites. The EU Green Deal compliance mandates are accelerating certified supply chain investments across European milling operations. Commercial baking clusters in the Netherlands and northern Germany drive specification-driven buying for custom-milled blends with guaranteed protein ranges.
India
Urban consumers in tier-1 and tier-2 cities displace loose commodity purchases with branded packaged flour for hygienic formats. The FSSAI oversees food safety standards that packaged flour must meet to access organized retail channels. Maharashtra and Gujarat host expanding milling capacity as millers build supply chains capable of reaching fragmented retail endpoints.
Indonesia
Bakery chains expand procurement volumes for premium flour blends as modern trade penetration deepens. The country's national food regulator enforces fortification requirements that imported and domestic flour must satisfy. Jakarta and Surabaya present first-mover advantages for branded flour entrants targeting underpenetrated modern trade channels.
Saudi Arabia
Restaurant chains shift procurement toward custom-milled blends with guaranteed absorption specifications for centralized kitchen models. The SFDA oversees food safety and labeling requirements for wheat-derived products. Riyadh and Jeddah concentrate food service distributor consolidation as procurement moves toward performance-specified blends rather than commodity grades.
All Purpose Flour Market Competitive Environment
Capability concentration sits with specialty millers commanding premium positioning through certification tiers; scale advantage sits with integrated grain handlers leveraging elevator networks for cost efficiency. The market structures around three tiers: multinational processors with continental milling footprints, regional specialists with identity-preserved supply chains, and commodity millers competing on volume throughput. Dominant competitive moves include backward integration into grain origination and portfolio diversification into organic and gluten-free certified lines.
Among North American integrated processors, Ardent Mills and General Mills exemplify the scale-driven archetype, while King Arthur Baking Company occupies a position within the specialty-tier focused on direct-to-consumer channel control. These three anchors illustrate how milling economics split between commodity volume plays and premium extraction strategies.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| General Mills |
| Ardent Mills |
| King Arthur Baking Company |
| Interflour Group |
| Goodmills Group |
| Acarsan Holding |
| Manildra Group |
| Bob's Red Mill Natural Foods |
| Others |
Value Chain & Pricing Dynamics
Great Plains elevator concentration anchors cost structures for downstream millers, concentrating margin capture with integrated grain handlers while fragmenting pricing power among independent processors dependent on spot wheat markets.
Pricing Analysis
Long-term offtake contracts dominate procurement between industrial bakeries and integrated millers, insulating volume buyers from hard red winter wheat spot volatility while spot-market exposure squeezes mid-tier operators lacking origination assets. Three-tier pricing structure across organic certified, conventional branded, and commodity loose formats captures certification premiums and volume discounts. Cost compression in conventional grades intensifies as Indian urban consumers trade up to packaged formats. Food manufacturers with multi-year supply agreements exhibit lowest price sensitivity; home cooks in traditional trade channels remain most exposed to spot fluctuations.
Supply Chain Analysis
Hard red winter wheat from the United States, Canada, and Australia feeds global milling capacity, with protein specifications varying by harvest region and varietal selection. Roller mill equipment, grain elevator infrastructure, and segregated organic handling systems constitute critical fixed assets. Single-source vulnerability concentrates in Great Plains elevator networks serving national bulk distribution. Distribution runs through integrated processor direct-ship programs, food service distributor networks, and modern trade retail channels with diverging margin retention profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty milling expertise for organic and gluten-free certified production remains scarce relative to commodity capacity, creating asymmetric returns for operators who bridge this capability gap.
For Market Incumbents: Harden supply security through backward integration into grain origination assets across the Great Plains and Maharashtra milling clusters. Accelerate organic certification investments ahead of EU Green Deal enforcement timelines. Defend against gluten-free substitution threats by acquiring specialty milling capabilities rather than building in-house. For New Entrants and Emerging Players: Underpenetrated modern trade channels in Indonesian tier-2 cities represent the most penetrable entry point for branded flour entrants. E-commerce direct-to-consumer distribution in US and European specialty segments offers margin capture outside traditional distributor networks. Lead with pouch-format premium positioning and identity-preserved supply chain transparency as differentiated go-to-market architecture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional millers lacking organic handling infrastructure but commanding strong local brand equity. Five-to-ten-year viability hinges on capital deployment into certified supply chain segregation and precision milling technology. Watch for FDA bioengineered disclosure guidance finalization as inflection signal for gene-edited wheat commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Captures elevator margin and insures against hard red winter wheat spot volatility for integrated processors. |
| Organic Certification Investment | Positions millers for EU Green Deal compliance mandates and premium extraction in European export markets. |
| Precision Milling Technology Deployment | Enables near-infrared spectroscopy integration for real-time protein specification control across multi-site production. |
| Direct-to-Consumer Channel Launch | Bypasses distributor margin stacking while capturing consumer data for specialty flour customization. |
| Identity-Preserved Supply Chain Buildout | Maintains regulatory optionality for gene-edited wheat segregation ahead of anticipated FDA disclosure thresholds. |
Study Parameters
A standing panel of grain elevator operators, commercial bakery procurement directors, food service distributor category managers, and FSSAI regulatory affairs specialists provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against USDA grading standards documentation, EU Green Deal compliance frameworks, FDA FALCPA guidance updates, and customs trade flow data. Bottom-up volume modeling triangulated against top-down value estimates from milling capacity utilization assessments.
Scenario-bracketing around hard red winter wheat yield volatility, EU sustainability mandate enforcement timing, and Indian urbanization pace shaped projection ranges across the modeling period. Segmentation dimensions included product type tier, end-user procurement structure, packaging format economics, and distribution channel margin retention. CAGRs derived from iterative convergence of demand-side consumption trajectory and supply-side capacity expansion schedules, with protein specification trends and certification adoption curves as flour-specific forecast inputs.
Practitioners should monitor FDA bioengineered disclosure rulemaking, EU organic grain availability constraints, and Indian modern trade penetration rates for early signals requiring forecast revision. Cross-checking against USDA wheat production estimates and FAO grain price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Brazil Starch Derivatives Market
Ingredients
Bouillon Market
Ingredients
Drum to Hopper Blends Market
Ingredients
Fermented Rennet Market
Ingredients
Dairy Ingredients Market
Ingredients
Pet Food Premix Market
Ingredients
Citrus Pectin Market
Ingredients
South America Spirulina Extract Market
Ingredients
Hydrolyzed Egg Market
Ingredients
Coconut Cream Powder Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Cocoa Derivatives Market
Ingredients
Fish Peptones Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Waxy Maize Starch Market
Ingredients
Brewer's Yeast Market