
 Fluid Lecithin Market | 2026-2036
Fluid Lecithin Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Lecithin Market Analytics
A shift from single-source soy lecithin procurement to multi-source botanical supply is recalibrating raw material strategy across the industry. Cargill leverages its oilseed processing network to secure upstream control over fluid lecithin streams. Lipoid GmbH anchors European pharmaceutical-grade supply through specialized solvent-free extraction capabilities. Wilmar International dominates Asia-Pacific origination with integrated crushing and refining assets.
Fluid lecithin comprises a mixture of phospholipids—primarily phosphatidylcholine, phosphatidylethanolamine, and phosphatidylinositol—typically extracted via degumming of crude vegetable oils at 70-90°C, serving as a natural emulsifier, wetting agent, and dispersant across food, pharmaceutical, and cosmetic formulations. Soy lecithin occupies the largest volume share given established crushing infrastructure, though sunflower lecithin captures premium positioning in allergen-free and non-GMO formulations. The food industry application segment sustains the deepest margin pools, while nutrition supplements represent the fastest-growing demand vector as encapsulation technologies advance.
FDA food additive regulations under 21 CFR 184.1400 govern lecithin use in US food applications, while EFSA maintains purity specifications for lecithin employed in infant nutrition and dietary supplements under EU regulatory frameworks. REACH registration requirements for imported phospholipid concentrates shape market access conditions for non-European suppliers. Stakeholders must monitor evolving EU F-Gas Regulation impacts on solvent-based extraction processes and assess backward integration opportunities into regional oilseed crushing to secure supply chain resilience.
Market Dynamics
EU Green Deal mandates on solvent-free extraction are compressing margins for conventional processors while rewarding backward-integrated oilseed crush operators with captive phospholipid streams. Food manufacturers now specify multi-source botanical lecithin to de-risk soy dependency, rewiring procurement patterns across emulsifier supply chains.
Growth Catalysts
- Clean-label emulsification:Food processors in Germany and France are reformulating with fluid lecithin to replace synthetic emulsifiers in bakery and confectionery applications, driven by retailer clean-label mandates.
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases in solvent-based extraction is accelerating capital deployment into enzymatic and membrane degumming technologies for pharmaceutical-grade output.
- Encapsulation demand:Nutrition supplement manufacturers are expanding fluid lecithin use in liposomal delivery systems for bioactive compounds, creating new volume pull from functional food brands.
Market Restraints
- Input cost volatility:Sunflower seed prices fluctuate with Black Sea supply disruptions, compressing margins for non-GMO lecithin producers dependent on Ukrainian and Russian origination.
- Supply concentration risk:Over half of pharmaceutical-grade fluid lecithin capacity clusters in Germany's Hamburg-Frankfurt corridor, creating single-point vulnerability for EU drug formulators.
- Substitution threat:Synthetic emulsifiers like polysorbates and sucrose esters retain cost advantage in mass-market food applications where label claims carry less pricing power.
Strategic Opportunities
- India nutrition supplements:FSSAI regulatory harmonization with Codex standards is opening import pathways for pharmaceutical-grade lecithin into India's expanding nutraceutical contract manufacturing sector.
- EU Green Deal tailwind:Solvent-free extraction mandates are creating first-mover advantage for processors with enzymatic degumming capabilities, locking in long-term supply agreements with infant formula brands.
- Cosmeceutical convergence:Fluid lecithin is penetrating skin-care formulations as phosphatidylcholine carriers for active ingredients, bridging food-grade and cosmetic-grade specification gaps.
Industry Challenges
- Phospholipid assay standardization:Variability in phosphatidylcholine content measurement methods across ISO, USP, and EP frameworks creates batch rejection risk at customer QC gates.
- Legacy oilseed infrastructure retrofit:Conventional hexane-based crush plants face stranded asset risk as EU F-Gas Regulation tightens solvent emission thresholds, requiring multimillion-euro enzymatic conversion capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Lecithin Market |
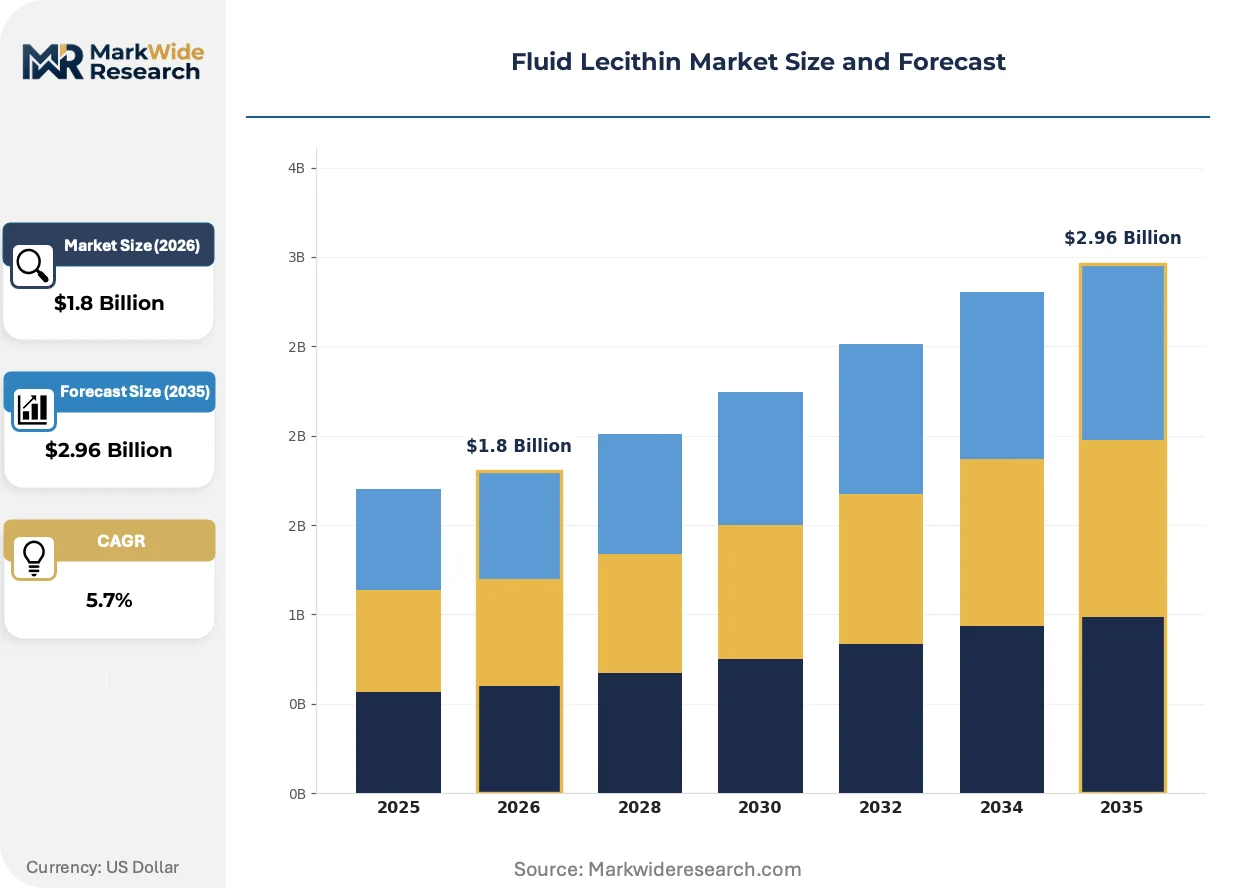
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunflower Lecithin, Soy Lecithin, Egg Lecithin, Other Lecithins Application: Food Industry, Nutrition Supplements, Pharmaceuticals, Personal Care Format: Liquid, Powder, Granules, Emulsifier Market Channel: Direct Sales, Distributor Sales, Online Retail, Specialty Stores |
| Companies Covered | American Lecithin Company, Lipoid GmbH, Cargill, Lasenor Emul, Lecico, Archer Daniels Midland Company, Wilmar International, Sonic Biochem Extractions, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Lecithin Market Evolving Landscape
Membrane filtration and enzymatic degumming are displacing hexane extraction as the dominant phospholipid recovery pathway, compressing capital intensity while raising purity floors. Processor R&D budgets are pivoting toward solvent-free process validation to secure pharmaceutical and infant nutrition certifications.
Enzymatic phospholipase treatment is absorbing market share from conventional water-degumming in European oilseed processing. Specialty oil refiners in the Netherlands and Belgium are retrofitting existing lines with immobilized enzyme reactors, cutting solvent handling costs while hitting EFSA purity specifications for infant formula applications. This technology is absorbing margin pressure from rising hexane disposal fees under EU industrial emissions rules.
REACH registration requirements for imported phospholipid concentrates are tightening market access for non-European suppliers. ECHA's updated dossier demands on reproductive toxicity endpoints are extending registration timelines by 12-18 months for Asian-origin material. Pharmaceutical formulators are responding by dual-sourcing from EU-registered suppliers to avoid API submission delays.
Long-term supply agreements are displacing spot procurement in food manufacturer lecithin buying. Major bakery and chocolate brands in Germany and Switzerland are locking in three-to-five-year contracts with crush-integrated processors to secure non-GMO sunflower lecithin streams. This shift is most visible in premium confectionery segments where allergen-free claims command shelf price premiums.
Fluid Lecithin Market Segmentation
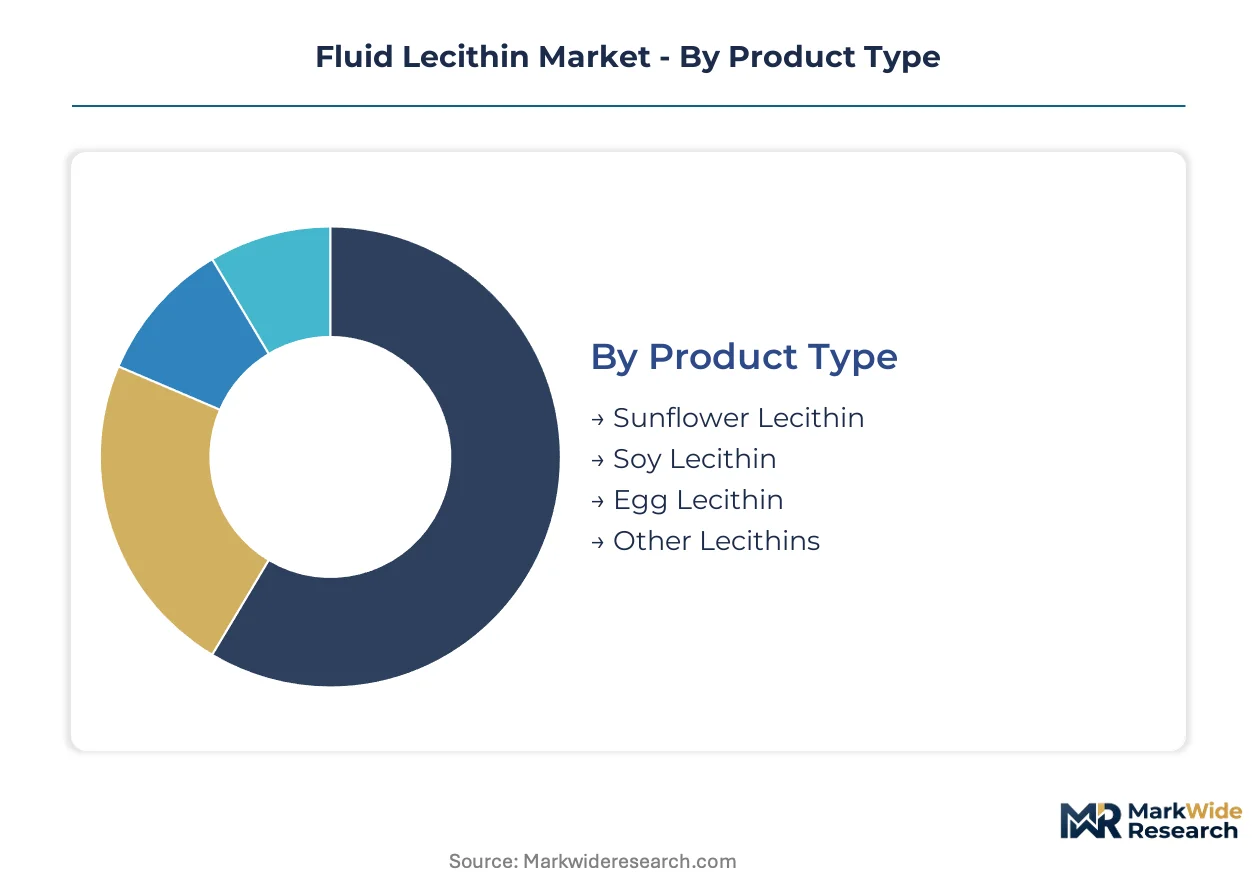
Fluid lecithin procurement patterns diverge sharply across product origins and application specifications. Food manufacturers prioritize allergen-free certifications, while pharmaceutical formulators enforce phospholipid purity thresholds that reshape supplier qualification criteria.
Product Type:
Phospholipid composition and allergen profile define competitive positioning across botanical sources.
- Soy Lecithin:Derived from crude soybean oil degumming, this segment delivers standardized phosphatidylcholine content at scale. Crushing infrastructure concentration in the US Midwest and Argentina's Pampas region underwrites volume availability, though non-GMO premiums are widening price spreads.
- Sunflower Lecithin:Black Sea origination dominates, with Ukrainian and Russian seed supplies commanding allergen-free positioning in European infant nutrition. EFSA purity specifications for phospholipid content are tightening procurement specifications for pharmaceutical-grade streams.
- Egg Lecithin:High phosphatidylcholine concentration supports liposomal encapsulation demand from Swiss and German nutraceutical formulators.
- Other Lecithins:Rapeseed and cottonseed variants serve regional oilseed processing byproduct streams with limited specification standardization.
Mature deployment sits with Soy Lecithin. Newer deployment is concentrated in Sunflower Lecithin.
Application:
End-use specifications cascade backward into raw material qualification requirements and extraction method selection.
- Food Industry:Clean-label emulsification in German and French bakery and confectionery applications is displacing synthetic alternatives. Retailer mandates on ingredient transparency are compressing acceptance of modified lecithin grades.
- Nutrition Supplements:Liposomal delivery system expansion for bioactive compounds is climbing the fastest across all application segments. FSSAI regulatory harmonization in India is opening import pathways for pharmaceutical-grade material.
- Pharmaceuticals:EMA and FDA drug master file requirements enforce solvent-free extraction validation for parenteral and oral dosage forms.
- Personal Care:Phosphatidylcholine carriers for active ingredient delivery are bridging food-grade and cosmetic-grade specification gaps in skin-care formulations.
Volume concentration rests with Food Industry. Specification intensity peaks in Pharmaceuticals.
Format:
Physical state determines handling infrastructure requirements and end-use integration pathways.
- Liquid:Standard fluid lecithin maintains dominant volume position in industrial food processing for ease of metering and dispersion. Tank farm infrastructure at crush-integrated processors locks in supply security for major bakery chains.
- Powder:Spray-dried and oil-free variants address dry blend compatibility in nutritional premixes and instant beverage applications.
- Granules:Low-dust handling properties suit pharmaceutical tableting operations and precise dosing requirements.
- Emulsifier:Pre-hydrated and compounded grades reduce customer-side processing steps in specialized cosmetic and pharmaceutical formulations.
Processing efficiency favors Liquid. Precision dosing demand clusters in Granules.
Market Channel:
Procurement modality reflects customer scale, specification complexity, and supply security requirements.
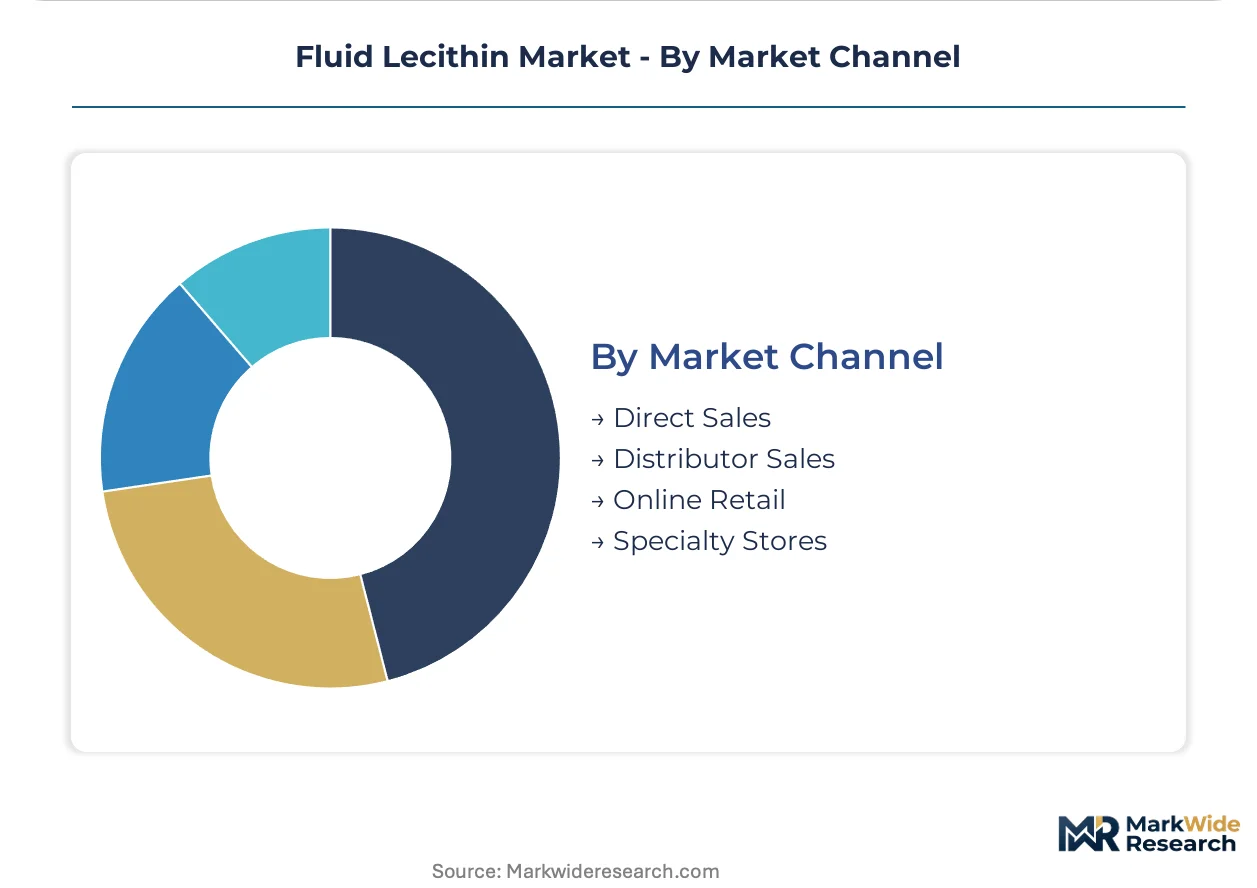
- Direct Sales:Crush-integrated processors contract directly with multinational food and pharmaceutical manufacturers for three-to-five-year supply agreements. REACH registration and solvent-free extraction certification are non-negotiable qualification gates.
- Distributor Sales:Regional ingredient distributors aggregate smaller volume requirements from mid-tier food processors and contract manufacturers.
- Online Retail:E-commerce platforms serve nutraceutical startups and research institutions requiring small-batch, specification-flexible procurement.
- Specialty Stores:Health food retail channels move consumer-packaged lecithin supplements with organic and non-GMO positioning.
Contract security concentrates in Direct Sales. Flexibility requirements drive Online Retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean crushing corridors in the US Midwest and sunflower seed belts across Ukraine and Russia anchor fluid lecithin origination. Processing capacity clusters near Rotterdam, Hamburg, and Singapore mediate trade flows between raw material zones and formulation demand centers.
United States
Midwest soybean crush plants supply standardized fluid lecithin to North American bakery and confectionery chains. FDA regulations under 21 CFR 184.1400 govern food additive specifications, while EPA emissions rules shape solvent handling economics. Chicago-area processors concentrate volume supply for industrial emulsifier procurement.
Germany
Specialty ingredient demand from infant formula and pharmaceutical formulators drives Hamburg-Frankfurt corridor capacity concentration. EFSA purity specifications and EU F-Gas Regulation mandates enforce solvent-free extraction validation. Enzymatic degumming retrofit projects absorb capital deployment across Lower Saxony oilseed facilities.
India
Nutraceutical contract manufacturing expansion in Maharashtra and Gujarat creates import pull for pharmaceutical-grade fluid lecithin. FSSAI regulatory harmonization with Codex standards accelerates market access pathways. Mumbai-Pune industrial zones concentrate liposomal encapsulation demand from functional food startups.
China
Integrated crushing and refining assets along the Yangtze River Delta dominate Asia-Pacific origination volume. SAMR food additive registration requirements and evolving GB standards shape import substitution dynamics. Shanghai-area processors balance domestic soy lecithin supply with sunflower lecithin re-export processing.
Brazil
Pampas region soybean crush infrastructure underwrites South American fluid lecithin export capacity. ANVISA pharmaceutical ingredient regulations govern import pathways for high-purity grades. São Paulo-state formulators serve Mercosur confectionery and bakery demand with regional supply security.
Fluid Lecithin Market Competitive Landscape
Backward integration into oilseed crushing dominates the current landscape as processors secure captive phospholipid streams. The vendor base concentrates around crush-integrated multinationals, specialized European extraction technology firms, and Asia-Pacific origination specialists. Three archetypes define positioning: upstream-integrated agricultural processors, pharmaceutical-grade purity specialists, and regional origination aggregators. Competitive intensity centers on enzymatic extraction technology licensing and long-term supply contract capture.
Among crush-integrated agricultural processors, Cargill and Bunge Limited exemplify upstream control strategies through Midwest and South American oilseed networks. Lipoid GmbH occupies a position within the pharmaceutical-grade purity specialist tier, anchoring European solvent-free extraction capabilities for infant nutrition and drug formulation applications. Wilmar International represents the Asia-Pacific origination archetype, leveraging integrated crushing and refining assets across Southeast Asian supply zones.
| Leading Market Players |
|---|
| American Lecithin Company |
| Lipoid GmbH |
| Cargill |
| Lasenor Emul |
| Lecico |
| Archer Daniels Midland Company |
| Wilmar International |
| Sonic Biochem Extractions |
| Bunge Limited |
| Others |
Value Network & Pricing Analysis
Crush-integrated multinationals anchored by Cargill and Bunge exercise pricing discipline through captive phospholipid streams, while independent processors face margin compression from hexane disposal fees and enzymatic retrofit capex. Family-owned mid-caps in Germany's Hamburg-Frankfurt corridor command pharmaceutical-grade premiums through solvent-free extraction certifications, creating a bifurcated ownership landscape where financing structure dictates supply security and pricing power.
Pricing Analysis
Service-bundling separates pharmaceutical-grade fluid lecithin from food-grade commodity streams, with infant nutrition contracts including EFSA compliance validation and batch-level phospholipid assay documentation. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with non-GMO sunflower lecithin from Black Sea origination commanding allergen-free premiums over conventional soy grades. Cost compression in standard-tier soy lecithin is intensifying because Midwest crush capacity expansion outpaces bakery demand growth. Mass-market food processors show highest price sensitivity, while Swiss and German nutraceutical formulators absorb premiums for liposomal-grade egg lecithin.
Supply Chain Analysis
Single-source vulnerability sits with Ukraine and Russia for non-GMO sunflower seed origination, creating concentration risk for European allergen-free lecithin supply. Manufacturing draws from Argentine Pampas soybean crush, US Midwest oilseed processing, and Black Sea sunflower belts as primary input zones. Raw material dependencies center on crude vegetable oil degumming streams, immobilized enzyme reactor inputs for solvent-free extraction, and phospholipase enzyme supplies for pharmaceutical-grade validation. Tariff exposure on Black Sea seed imports threatens margin stability for European processors. Distribution runs through Rotterdam and Hamburg port clusters for EU pharmaceutical formulators, with Singapore mediating Asia-Pacific trade flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fluid lecithin market functions as a cost-of-compliance arena where EU F-Gas Regulation mandates on solvent-free extraction erect barrier-to-entry moats for enzymatic-capable processors while stranding conventional hexane-based capacity.
For Market Incumbents: Cement defensive positioning by locking three-to-five-year supply agreements with infant formula brands before REACH registration timelines extend for Asian-origin competitors. Prioritize enzymatic degumming capacity additions in Lower Saxony to capture EU Green Deal tailwinds. Synthetic emulsifier substitution in mass-market food applications threatens volume retention; counter with clean-label certification investments that command shelf price premiums from German and Swiss retailers. For New Entrants and Emerging Players: E-commerce platforms serving nutraceutical startups offer the most penetrable white-space entry, bypassing crush-integrated processor gatekeeping through small-batch, specification-flexible procurement. Target India's Maharashtra and Gujarat contract manufacturing zones where FSSAI regulatory harmonization opens import pathways for pharmaceutical-grade material. Pursue liposomal encapsulation application focus to differentiate from commodity emulsifier competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor enzymatic retrofit specialists in the Netherlands and Belgium where stranded hexane-based assets trade below replacement cost. Long-term viability over the projection horizon hinges on solvent-free extraction validation capabilities that secure pharmaceutical and infant nutrition certifications. Watch ECHA dossier completion rates on reproductive toxicity endpoints as inflection signal for EU-registered supplier scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Degumming Retrofit | EU F-Gas Regulation compliance locks in infant formula supply agreements with EFSA-validated processors. |
| Backward Integration into Oilseed Crushing | Cargill's Midwest network demonstrates captive phospholipid stream security against Black Sea supply disruptions. |
| Long-term Supply Agreement Capture | German bakery chains secure non-GMO sunflower lecithin through three-to-five-year crush-integrated contracts. |
| Pharmaceutical-grade Certification Investment | Lipoid GmbH anchors European drug formulation supply through solvent-free extraction validation. |
| Regional Distributor Partnership | Mid-tier food processors in France access fluid lecithin through aggregated distributor procurement channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across oilseed crush plant managers, pharmaceutical procurement leads at infant formula manufacturers, enzymatic extraction technology providers, and FSSAI regulatory affairs specialists. ECHA REACH registration databases, FDA 21 CFR 184.1400 food additive specifications, EU F-Gas Regulation implementation reports, and Black Sea sunflower seed trade statistics supplied validation benchmarks. Bottom-up volume modeling triangulated against top-down value estimates from processor capacity disclosures.
Segmentation granularity extended to phospholipid composition tier, botanical origin, extraction method, and end-use application specification across the modeling period. CAGRs derived from historical crush capacity expansion rates, infant nutrition formulation trends, and encapsulation technology adoption curves. Forecast inputs incorporated EU Green Deal implementation pace, enzymatic reactor deployment timelines, and India nutraceutical contract manufacturing growth trajectories.
The model holds under stable EU regulatory enforcement and intact Black Sea seed supply corridors; deviation in F-Gas Regulation acceleration or Ukrainian origination disruption would shift pharmaceutical-grade availability assumptions. Forecasts reflect documented base-case conditions with acknowledged sensitivity to phospholipid assay standardization outcomes and hexane disposal fee trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
White Wheat Malt Market
Ingredients
Cheese Powder Market
Ingredients
Wheat Starch Market
Ingredients
Mung Bean Starch Market
Ingredients
Bovine Gelatin Market
Ingredients
Pet Food Premix Market
Ingredients
Mung Bean Protein Market
Ingredients
Smoke Ingredients for Food Market
Ingredients
Quark Powder Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Vegan Ingredients Market
Ingredients
Modified Soya Flour Market