
 Malted Barley Flour Market | 2026-2036
Malted Barley Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Malted Barley Flour Market Analysis
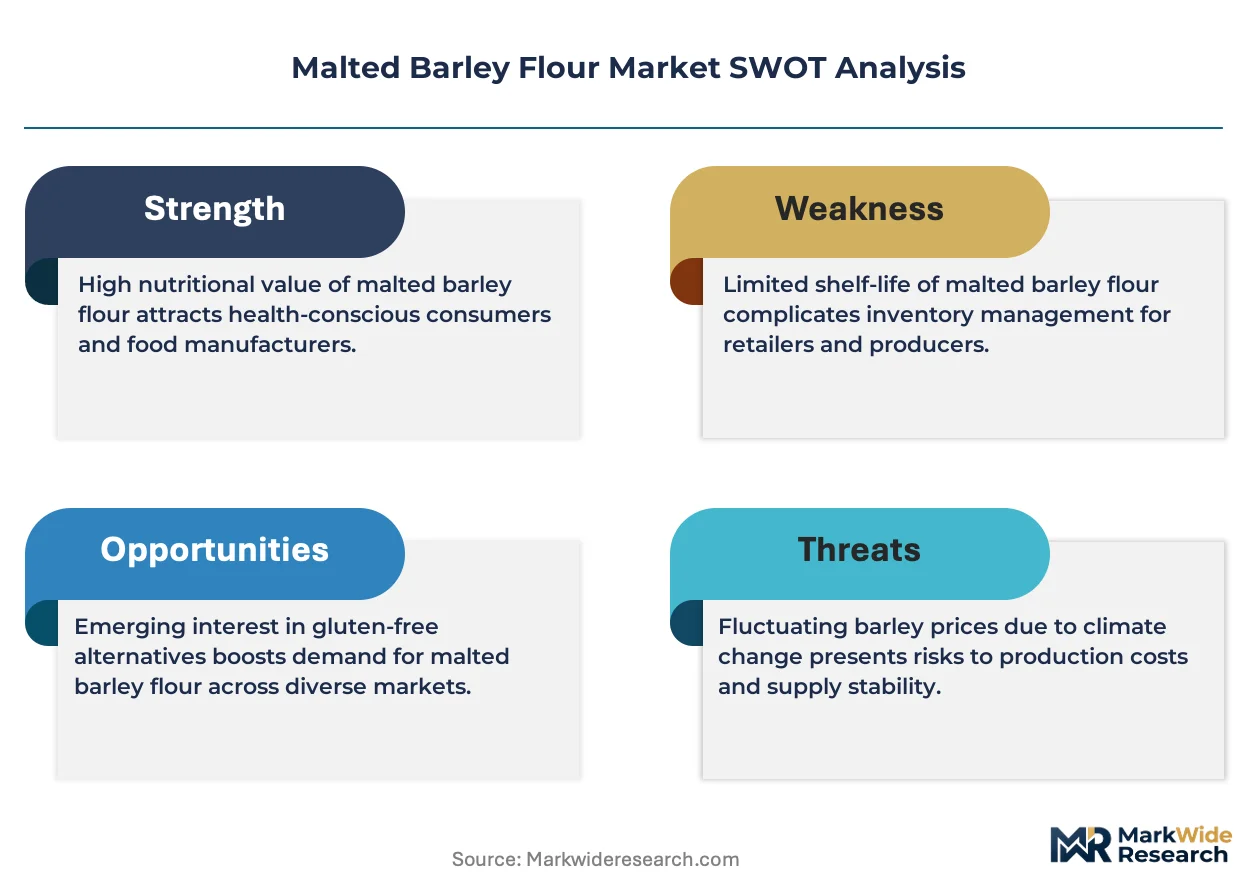
Ingredient-as-a-service contracting is repositioning how malted barley flour reaches industrial buyers, with long-term supply agreements now bundling technical support and quality certification. Muntons Plc anchors British brewing supply through vertically integrated malting operations. Cargill Incorporated leverages global grain origination networks to secure premium barley varietals. Briess Malt & Ingredients Co specializes in custom diastatic specifications for North American craft bakeries.
Malted barley flour consists of dried, ground malted barley kernels containing active enzymes, primarily alpha-amylase and diastase, typically standardized to specific degrees Lintner for enzymatic activity; manufacturers kiln green malt to halt germination at precise moisture thresholds before roller milling. The ingredient functions as a natural dough conditioner, browning agent, and fermentable sugar source across commercial baking and brewing. Organic product type commands premium positioning as clean-label bakery chains enforce zero-synthetic-input sourcing. Breweries represent the fastest-growing end user segment as craft producers seek flavor-differentiated base malts. Direct sales distribution channel captures the highest margin pool through technical-service-embedded contracts with large food processors.
FDA GRAS status and EPA pesticide tolerance limits govern malted barley flour entering US food channels, while EU REACH and EFSA mycotoxin thresholds shape import acceptance at European ports. BIS food safety standards and FSSAI cereal grain regulations apply to malt flour circulating in Indian commercial baking. Stakeholders must monitor evolving enzyme activity labeling requirements and carbon intensity disclosures across multiple jurisdictions to maintain formulation compliance and procurement flexibility.
Market Dynamics
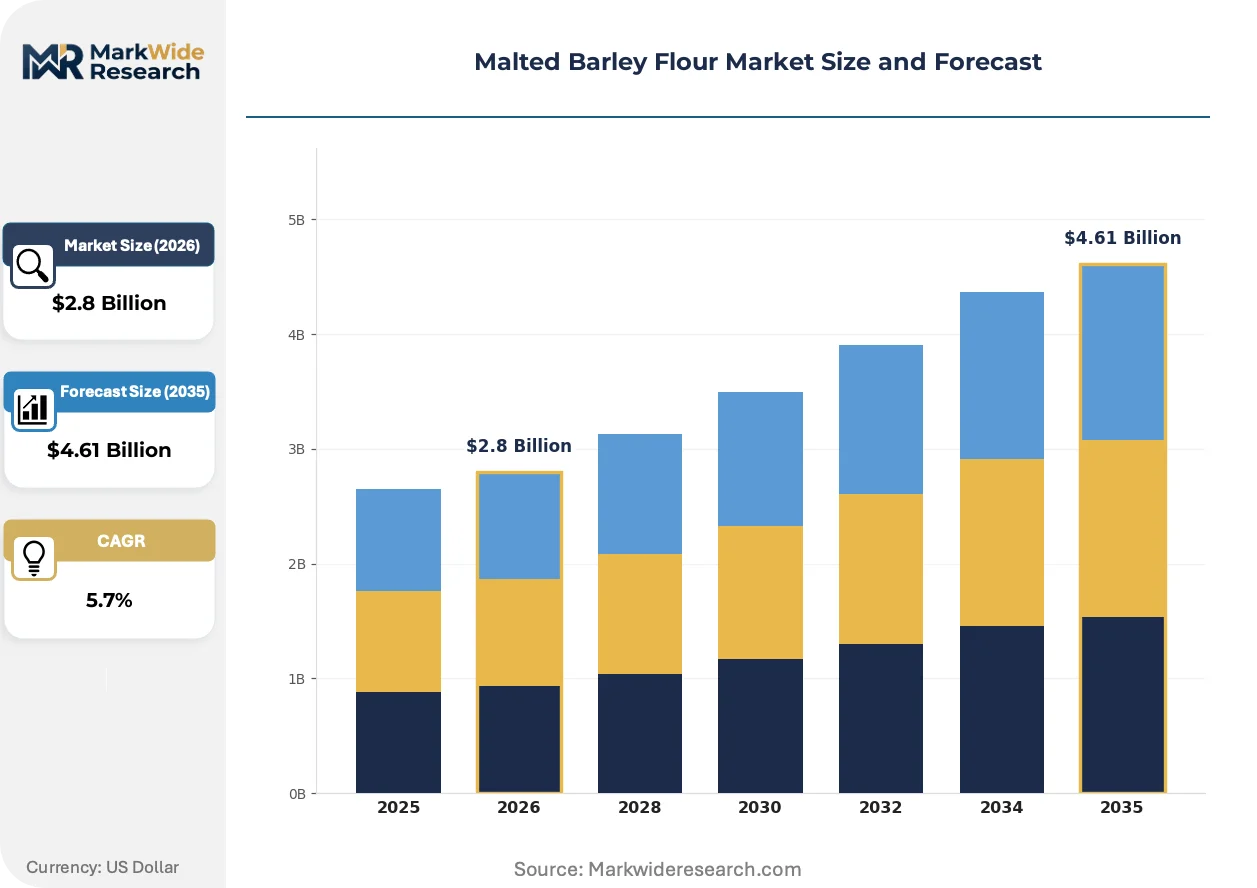
Ingredient-as-a-service contracting is compressing traditional spot-market procurement for malted barley flour, embedding technical support and quality certification into multi-year supply agreements that lock in enzymatic specifications and carbon traceability.
Growth Catalysts
- EU Green Deal Farm-to-Fork strategy:Tightening pesticide residue limits on cereal grains is accelerating demand for certified organic malt flour across European artisan bakeries and industrial processors seeking compliance-ready inputs.
- Alpha-amylase standardization:Precise degrees Lintner measurement is enabling craft breweries to replicate flavor profiles batch-to-batch, pulling specialty malt flour into brewing applications previously dominated by commodity inputs.
- North American craft bakery expansion:Diastatic malt powder adoption for crust browning and fermentation control is spreading from artisan clusters in Portland and Brooklyn into regional wholesale baking operations.
Market Restraints
- Barley varietal concentration:Premium two-row malting barley production concentrates in specific climatic zones across Canada and northern France, creating weather-dependent supply vulnerability.
- EPA pesticide tolerance enforcement:Stricter residue testing at US ports is rejecting shipments that cleared origin inspections, generating demurrage costs and formulation delays for importers.
- Enzyme activity degradation:Diastatic potency declines measurably during ocean transit and warehouse storage, forcing buyers to over-specify activity levels or absorb yield variance.
Strategic Opportunities
- Carbon intensity disclosure mandates:EU CSRD reporting requirements for Scope 3 emissions are creating first-mover advantage for malt suppliers with verified farm-level carbon accounting.
- Clean-label bakery chains:Zero-synthetic-input sourcing policies at fast-casual restaurant groups are opening premium positioning for organic malt flour in burger bun and sandwich bread applications.
- Precision kilning technology:IoT-enabled moisture and temperature control during germination halt is enabling custom enzyme spectra for specific dough systems, differentiating technical service offerings.
Industry Challenges
- Mycotoxin certification timelines:EFSA threshold compliance for deoxynivalenol and zearalenone requires batch-specific testing that extends lead times by two to three weeks for EU-bound shipments.
- Legacy ERP integration:Food processors running SAP or Oracle systems built for commodity grain procurement struggle to track enzymatic activity lots through formulation and costing modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malted Barley Flour Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, Gluten-Free, Instant End User: Bakers, Breweries, Snack Manufacturers, Food Processors Application: Baking, Brewing, Thickening Agent, Food Fortification Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Ardent Mills LLC, Archer Daniels Midland Company, Cargill Incorporated, Muntons Plc, Briess Malt & Ingredients Co, IREKS GmbH, Soufflet Group, GrainCorp, Malteurop Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malted Barley Flour Market Emerging Trajectories
Active enzyme preservation and supply chain digitization are converging to transform how malted barley flour is specified, procured, and traced from kiln to final dough system.
Precision kilning control systems using IoT sensors and automated airflow modulation are unifying moisture removal and enzyme fixation into single-process optimization. North American craft maltsters deploy these systems to produce customer-specific diastatic profiles within 48-hour turnaround. This capability is compressing minimum order quantities and enabling just-in-time procurement previously impossible at small scale.
EU REACH chemical registration requirements and EFSA mycotoxin thresholds are tightening documentary burdens on malt flour entering European food channels. Importers now face mandatory third-party testing for pesticide residues and heavy metals at designated border control posts. German and British industrial bakers are responding by qualifying domestic malting sources and demanding supplier-held inventory buffers.
Long-term technical-service contracts are displacing spot purchasing among large food processors seeking guaranteed enzyme activity and embedded quality certification. Direct sales channels now bundle formulation support, lot traceability, and carbon accounting into multi-year agreements. This pattern is most visible in France and the United Kingdom where industrial bakery consolidation has concentrated procurement decision-making.
Malted Barley Flour Market Segmentation
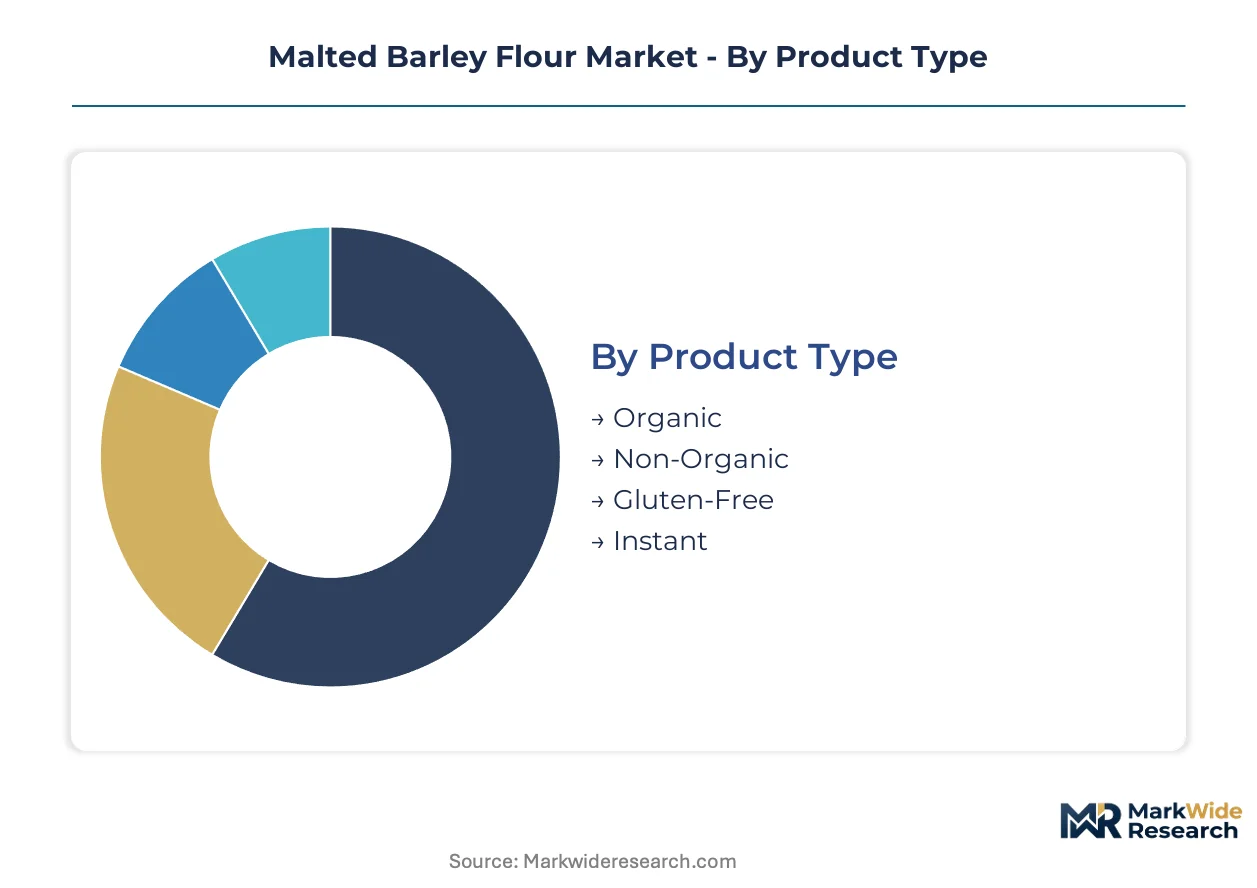
Malted barley flour segments diverge sharply between standalone ingredient sales and embedded technical-service contracts. Procurement patterns across product grades and distribution channels reveal distinct margin pools and compliance burdens.
Product Type:
Integration depth varies from commodity bulk inputs to certified organic streams requiring farm-level traceability and third-party audit documentation.
- Organic:Zero-synthetic-input sourcing mandates from EU Green Deal Farm-to-Fork strategy and clean-label bakery chains drive premium positioning. German artisan bakeries and French industrial processors absorb the bulk of certified organic volume, paying significant premiums for pesticide residue documentation.
- Non-Organic:Conventional malting barley processed without organic certification serves price-sensitive industrial baking and mainstream brewing applications across North America and Europe.
- Gluten-Free:Barley-derived ingredients face inherent gluten content challenges; specialty enzymatic treatments and alternative grain bases serve celiac-safe product formulations in regulated markets.
- Instant:Pre-gelatinized malt flour dissolves rapidly in cold water systems, supporting beverage fortification and quick-mix bakery applications where traditional diastatic activation is impractical.
Non-Organic leads volumes today; Organic is gaining share fastest.
End User:
Customer sophistication tiers separate commodity buyers from those requiring embedded technical support and enzymatic specification guarantees.
- Breweries:Craft producers across Portland, Brooklyn, and London specify precise degrees Lintner measurements for flavor replication, pulling specialty malt flour into brewing applications previously dominated by commodity inputs. Alpha-amylase standardization enables batch-to-batch consistency.
- Bakers:Artisan clusters specify diastatic malt powder for crust browning and fermentation control, with demand spreading from Portland and Brooklyn into regional wholesale baking operations.
- Snack Manufacturers:Malt flour functions as natural coloring and flavoring agent in extruded and baked snack matrices, with clean-label positioning driving substitution for artificial caramel colorants.
- Food Processors:Large-scale manufacturers integrate malt flour as natural dough conditioner across burger bun, sandwich bread, and frozen dough applications, often under long-term technical-service contracts.
Breweries show the steepest expansion trajectory; Bakers retain the largest installed base.
Application:
Functional role determines whether malt flour operates as primary ingredient or processing aid, shaping regulatory classification and labeling requirements.
- Baking:Natural dough conditioning, crust browning, and fermentable sugar generation dominate commercial bakery applications, with diastatic specifications varying by flour type and desired fermentation speed.
- Brewing:Base malt and specialty malt applications require precise enzyme spectra for starch conversion during mashing, with craft producers demanding custom kilning profiles.
- Thickening Agent:Pre-gelatinized instant malt flour provides viscosity modification in sauces, gravies, and beverage systems without synthetic hydrocolloids.
- Food Fortification:Malt extract and malt flour contribute B-vitamins, minerals, and fermentable carbohydrates to nutritional enhancement applications.
Baking commands current volume leadership; Brewing is climbing the fastest.
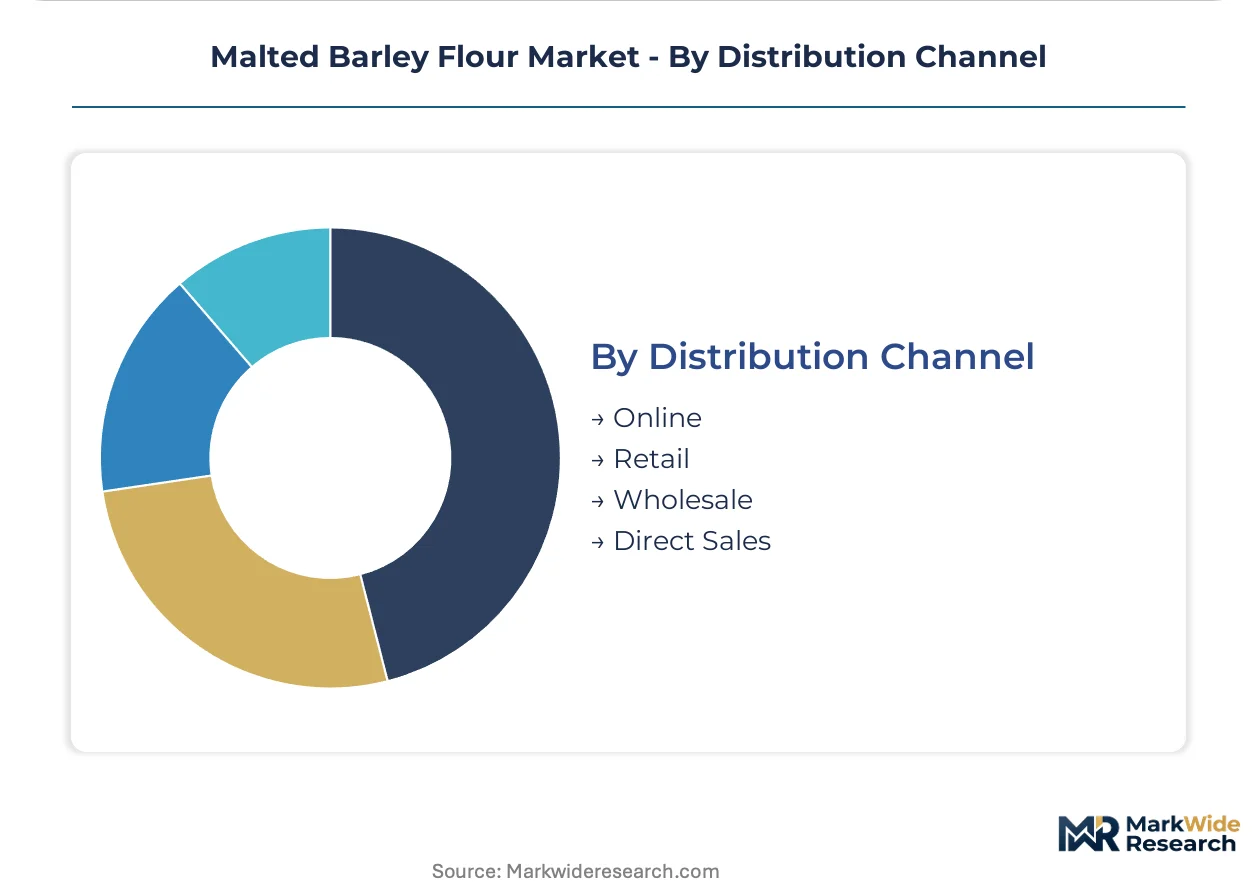
Distribution Channel:
Channel selection locks in margin structure and determines access to technical support, quality certification, and carbon traceability documentation.
- Direct Sales:Technical-service-embedded contracts with large food processors capture the highest margin pool, bundling formulation support, lot traceability, and carbon accounting into multi-year agreements. This pattern concentrates in France and the United Kingdom where industrial bakery consolidation has centralized procurement decision-making.
- Wholesale:Regional distributors serve mid-tier bakeries and smaller breweries with standardized enzymatic specifications and inventory buffering against supply volatility.
- Online:E-commerce platforms enable craft producers and artisan bakers to access specialty diastatic specifications with compressed minimum order quantities and rapid turnaround.
- Retail:Consumer-packaged malt flour for home baking and small-scale brewing represents a niche channel with limited volume but premium pricing.
Direct Sales dominates value capture; Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between jurisdictions are redirecting malted barley flour production toward markets with streamlined pesticide residue protocols and integrated carbon accounting infrastructure. Premium malting barley cultivation concentrates in temperate zones with established varietal breeding programs.
Germany
Industrial bakery consolidation across Bavaria and North Rhine-Westphalia drives demand for certified organic malt flour with embedded carbon traceability. EU Green Deal Farm-to-Fork pesticide limits enforced by EFSA accelerate domestic sourcing over imports. The Munich-Stuttgart corridor hosts precision kilning facilities supplying craft breweries with custom diastatic specifications.
United States
Portland and Brooklyn artisan clusters specify diastatic malt powder for crust browning, with demand spreading into regional wholesale baking across the Midwest. EPA pesticide tolerance enforcement at major ports generates demurrage costs for shipments clearing origin inspections. Wisconsin and North Dakota malting operations serve craft breweries seeking alpha-amylase standardization.
France
Parisian industrial bakers and Lyon-area snack manufacturers absorb bulk specialty malt flour volumes under long-term technical-service contracts. ANSM border controls enforce REACH documentation and mycotoxin thresholds at Calais and Marseille entry points. The Hauts-de-France cereal belt anchors premium two-row malting barley production for domestic kilning.
United Kingdom
London-based craft breweries and Manchester industrial baking operations specify precise degrees Lintner measurements for batch consistency. FSA alignment with EU pesticide residue standards post-Brexit creates documentation friction for continental suppliers. Suffolk and Norfolk malting facilities supply diastatic specifications to artisan bakeries across the Southeast.
Canada
Prairie provinces concentrate two-row malting barley production vulnerable to weather-dependent yield variance. Health Canada pesticide residue limits and PMRA enforcement shape import acceptance at Vancouver and Montreal ports. Alberta malting operations serve North American craft breweries seeking flavor-differentiated base malts with verified farm-level provenance.
Malted Barley Flour Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium organic streams concentrating around vertically integrated malting operations while commodity volumes flow through grain trading houses. The vendor base organizes into three tiers: integrated malting-to-flour processors, specialty ingredient formulators, and global grain origination platforms. Strategic moves center on backward integration into premium barley varietal sourcing and precision kilning technology licensing for custom enzyme spectra.
Within the integrated malting tier, Muntons Plc and Malteurop Group exemplify captive supply structures spanning germination control through final milling. Cargill Incorporated anchors the grain origination archetype with global premium barley procurement networks. Briess Malt & Ingredients Co occupies a position bridging specialty diastatic formulation and North American craft bakery technical service.
| Leading Market Players |
|---|
| Ardent Mills LLC |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Muntons Plc |
| Briess Malt & Ingredients Co |
| IREKS GmbH |
| Soufflet Group |
| GrainCorp |
| Malteurop Group |
| Others |
Supply Flow & Price Mechanics
Industrial bakery consolidation across France and the United Kingdom concentrates procurement decision-making among a shrinking pool of large food processors, embedding long-term technical-service contracts as the dominant pricing mechanism for malted barley flour. This buyer concentration shifts pricing power toward suppliers capable of bundling enzymatic specification guarantees with carbon traceability documentation.
Pricing Analysis
Capacity additions in Germany and Canada are reshaping price floors for specialty diastatic specifications. Three-tier pricing structure across premium organic, certified standard, and commodity bulk levels reflects divergence in farm-level traceability and third-party audit documentation. Cost compression in the commodity tier is intensifying because spot-market buyers face enzyme activity degradation during extended storage. Regional wholesale bakeries exhibit highest price sensitivity; craft breweries seeking precise degrees Lintner measurements absorb premium positioning with limited negotiation leverage.
Supply Chain Analysis
EU REACH chemical registration and EFSA mycotoxin thresholds now gate entry for malted barley flour shipments at European ports. Supply concentrates in Canada, France, and Germany where premium two-row malting barley cultivation rests on established varietal breeding programs. Germination kilns, roller milling equipment, and enzyme activity testing laboratories constitute critical input dependencies. Single-source vulnerability concentrates in the Hauts-de-France cereal belt where weather-dependent yield variance disrupts premium barley flows. Distribution runs through direct sales channels for large processors and regional wholesale distributors for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in malted barley flour hinges on carbon intensity disclosure mandates creating first-mover advantage for suppliers with verified farm-level accounting, while precision kilning technology unlocks premium pricing for custom enzyme spectra.
For Market Incumbents: Deepen backward integration into premium barley varietal sourcing across Canadian prairie provinces and northern France to secure weather-hedged supply positions. Invest in IoT-enabled kilning systems capable of 48-hour custom diastatic turnaround to defend against emerging craft maltsters. Lock in multi-year technical-service contracts with consolidated industrial bakers before carbon accounting requirements harden procurement criteria. For New Entrants and Emerging Players: Launch via e-commerce platforms serving North American craft breweries and artisan bakeries with compressed minimum order quantities and rapid specialty specifications. Target underpenetrated organic certification streams in snack manufacturing applications where clean-label caramel colorant substitution creates pull-through demand. Anchor initial positioning around pre-gelatinized instant malt flour for beverage fortification systems requiring cold-water solubility. For Investors and Strategic Acquirers: Grain trading houses with global origination networks are the most active acquirer in this space, seeking captive malting capacity to secure premium barley flows. Over the medium-term horizon, vertically integrated malting-to-flour processors with precision kilning capabilities represent the most defensible acquisition profile. Monitor EU CSRD Scope 3 reporting compliance timelines as the inflection indicator for carbon-accounting-enabled supplier premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premium Barley Origination | Cargill and Muntons anchor supply security through captive Canadian and British varietal sourcing. |
| Precision Kilning Technology Licensing | IoT-enabled moisture control enables Briess to deliver custom enzyme spectra within 48-hour windows. |
| Carbon Accounting Certification Program | Farm-level Scope 3 tracking creates compliance-ready positioning for EU Green Deal procurement mandates. |
| Long-term Technical-Service Contracting | Direct sales bundling formulation support and lot traceability captures highest margin pools in France and the United Kingdom. |
| Organic Certification Stream Expansion | Zero-synthetic-input documentation opens premium positioning at fast-casual restaurant chains enforcing clean-label policies. |
Methodological Framework
Bottom-up bakery and brewery demand modeling reconciled against top-down malting capacity and barley harvest tracking forms the analytical core of this study. Primary interviews with procurement directors at industrial baking operations, technical service managers at malt suppliers, quality certification auditors, and craft brewery founders combined with secondary validation from FDA GRAS filings, EPA pesticide tolerance databases, EU REACH registration records, and EFSA mycotoxin threshold documentation. Trade flow analysis from customs records and malting industry association reports provided supply-side triangulation against end-use consumption estimates.
Input-output matrices mapped barley varietal availability through germination kilning, enzyme fixation, and final milling stages across the projection horizon. Segmentation modeling spanned product type tiers, end-user sophistication levels, application functional roles, and distribution channel margin structures. CAGRs derived from trend extrapolation of enzymatic specification adoption rates and carbon disclosure compliance timelines, cross-referenced against craft brewery formation patterns and industrial bakery consolidation trajectories. Alpha-amylase standardization penetration and organic certification share evolution served as industry-specific forecast anchors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme weather events affecting premium two-row barley cultivation zones or abrupt pesticide residue limit tightening at major import ports. Model outputs reflect assumptions regarding EU Green Deal implementation pacing and craft brewery sector stability. A model refresh is warranted upon material change in EFSA mycotoxin threshold enforcement or carbon intensity disclosure mandate rollout schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Plant Protein Ingredients Market
Ingredients
Plant Based Premix Market
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Shortening Fats Market
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
Homecare Ingredients Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Cholesterol API Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Omega 6 Market
Ingredients
Millet Protein Market