
 Home Baking Ingredients Market | 2026-2036
Home Baking Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Home Baking Ingredients Market Outlook
E-commerce distribution is rewriting how home baking ingredients reach consumers. Kerry Group leverages its integrated ingredient platforms to sustain direct-to-baker supply relationships across North America. Cargill anchors bulk commodity flows into retail and foodservice channels with extensive grain origination networks. Lesaffre specializes in yeast and fermentation solutions that dominate professional and home baking segments in Europe and Asia.
Home baking ingredients comprise formulated and commodity inputs including flour milled to specific protein contents, refined and specialty sugars, chemical leavening agents such as sodium bicarbonate, and active dry or instant yeast cultures, all manufactured to precise moisture, ash, and activity specifications for consistent performance in residential and small-scale commercial ovens. Flour and yeast together capture the largest margin pools due to technical differentiation in protein quality and strain viability. Cookies and pastries represent the fastest-growing application segments as consumers experiment with complex recipes previously confined to professional settings.
FDA food labeling standards, EFSA additive safety evaluations, and USDA organic certification requirements collectively shape permissible ingredient compositions and marketing claims across major supply jurisdictions. The EU Green Deal's sustainable agriculture targets are beginning to influence sourcing specifications for wheat and sugar supply chains entering European retail. Stakeholders must monitor evolving clean-label thresholds and regional carbon-accounting rules to maintain formulation compliance and consumer trust.
Market Dynamics
Social media-driven baking culture is compressing product development cycles as home bakers demand professional-grade ingredients with consumer-friendly accessibility, forcing suppliers to bridge technical performance and household convenience simultaneously.
Growth Catalysts
- Clean-label mandates:FDA and EFSA reformulation requirements are accelerating ingredient transparency investments across flour and leavening categories.
- Protein quality differentiation:Specialty wheat varieties with defined gluten specifications command premium positioning in residential baking segments.
- Yeast strain innovation:Instant dry yeast cultures with enhanced temperature tolerance are expanding home baker success rates in challenging climates.
Market Restraints
- Wheat price volatility:Climate-driven harvest variability in major grain belts compresses margin predictability for flour millers.
- Supply concentration risk:Bulk active dry yeast production clusters in limited fermentation facility networks, creating single-point vulnerability.
- Regulatory friction:USDA organic certification timelines delay new product introductions by 12-18 months for reformulated ingredient lines.
Strategic Opportunities
- Underpenetrated e-commerce channels:Direct-to-baker subscription models bypass traditional retail markup structures in secondary US markets.
- Emerging application expansion:Sourdough starter cultures and heritage grain blends capture experimentation-driven demand in coastal metropolitan areas.
- EU Green Deal alignment:Carbon-accounted wheat sourcing specifications create first-mover positioning for suppliers with verified supply chain data.
Industry Challenges
- Fermentation science talent scarcity:Industrial microbiology expertise required for yeast strain development competes with pharmaceutical sector recruitment.
- Legacy equipment integration:Small-scale commercial bakeries struggle to reconcile artisan process controls with automated ingredient dosing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Baking Ingredients Market |
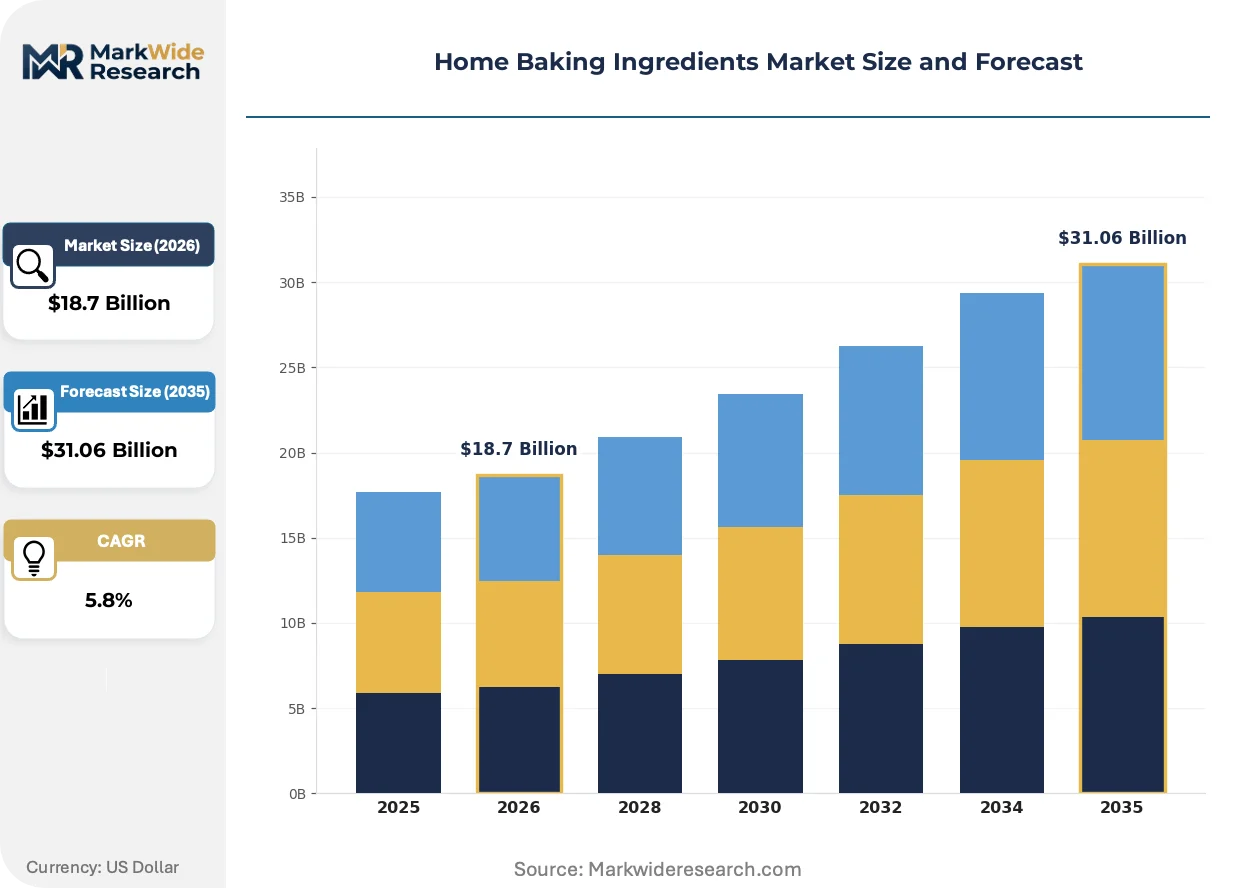
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour, Sugar, Baking Soda, Yeast Application: Breads, Cakes, Pastries, Cookies Packaging Type: Bags, Jars, Boxes, Pouches End User: Home Bakers, Professional Bakers, Bakeries, Cooking Schools |
| Companies Covered | Kerry Group, Dawn Food Products, Cargill, Corbion, Lesaffre, Archer Daniels Midland Company, DSM-Firmenich, Ingredion, Associated British Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Baking Ingredients Market Strategic Shifts
Precision fermentation and digital recipe platforms are converging to transform how home bakers source, measure, and execute complex formulations previously confined to professional environments.
Precision-milled flour with batch-specific protein and ash content labeling is rendering obsolete the generic all-purpose category that dominated residential pantries for decades. Serious home bakers in Germany and Japan now specify exact gluten percentages when ordering online. This granularity is compressing price tolerance for undifferentiated commodity flour.
EFSA additive safety evaluations are tightening permissible preservative thresholds in leavening agents and shelf-stable mixes. Manufacturers reformulate around natural acidulants and cultured wheat derivatives. The EU Green Deal's sustainable agriculture targets are accelerating sourcing documentation requirements for organic certification claims.
Recipe-driven ingredient bundling is replacing single-item purchasing as the dominant e-commerce behavior. Subscription services curate flour, yeast, and specialty sugar combinations matched to viral social media tutorials. This pattern concentrates most visibly in UK and Australian metropolitan markets where baking content consumption correlates directly with purchase bundling frequency.
Home Baking Ingredients Market Segmentation
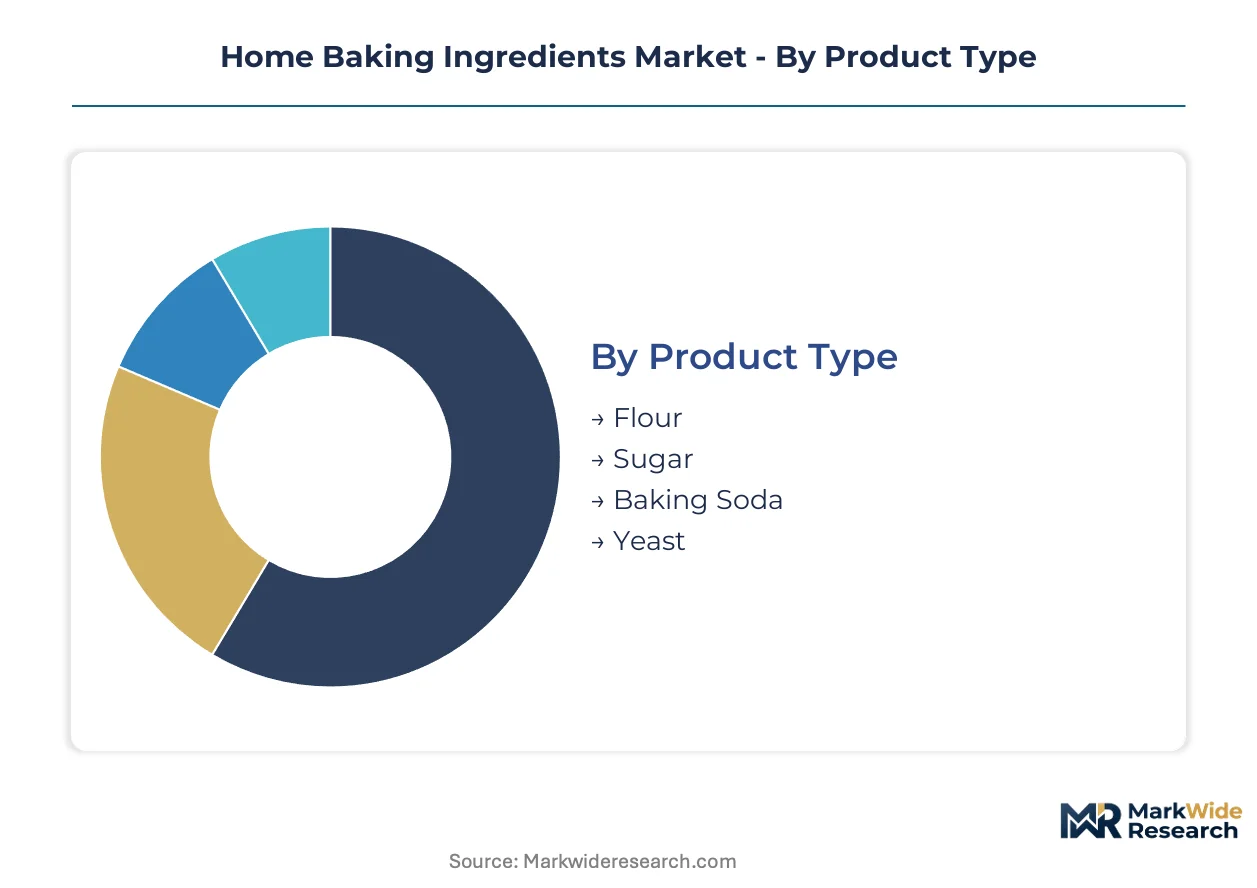
Ingredient specification granularity determines supplier profitability in home baking. Technical differentiation across protein content, fermentation activity, and moisture specifications creates tiered margin structures that reward precision manufacturing.
Product Type:
After-sales service intensity varies sharply across ingredient categories, with yeast requiring technical support for storage conditions and viability troubleshooting while flour demands minimal post-purchase engagement.
- Flour:Milled wheat products specify protein content, ash percentage, and gluten strength for precise baking performance. Demand concentrates in the United States where premium heritage wheat varieties command shelf space in specialty retail. Protein quality differentiation now drives replacement of generic all-purpose categories with batch-specific labeled alternatives.
- Yeast:Active dry and instant cultures deliver defined fermentation activity measured in billions of cells per gram. Coastal metropolitan areas in Germany and Japan exhibit strongest demand for temperature-tolerant strains that accommodate residential kitchen variability. Strain innovation cycles compress as home bakers demand professional-grade viability in consumer packaging formats.
- Sugar:Rined sucrose and specialty varieties including demerara and muscovado serve distinct recipe requirements across cookie and pastry applications.
- Baking Soda:Sodium bicarbonate and sodium aluminum phosphate provide chemical leavening with precise reaction timing for quick breads and cakes.
By volume, flour leads. By growth pace, yeast is ahead.
Application:
Recipe complexity tiers separate commodity ingredient demand from premium specialty purchases, with laminated dough applications requiring multiple precision inputs versus single-ingredient bread formulations.
- Breads:Yeast-leavened loaves and quick breads represent the foundational home baking entry point with established repeat purchase patterns. Sourdough experimentation in UK and Australian metropolitan markets drives heritage flour and starter culture bundling.
- Cookies:Drop, rolled, and molded varieties exhibit highest social media tutorial correlation with ingredient purchase spikes. Viral recipe cycles compress development timelines for limited-release flavor inclusions and specialty sugar blends.
- Cakes:Layered and sheet cake formulations demand precise leavening agent measurement and protein-specific flour selection.
- Pastries:Laminated dough applications including croissants and puff pastry require butter integration and temperature-controlled processing that challenges residential equipment limitations.
By volume, breads dominate. By margin expansion, pastries lead.
Packaging Type:
Format selection reflects usage frequency and storage constraints, with high-rotation ingredients in resealable pouches versus occasional-use specialties in protective jars.
- Bags:Multi-wall paper and plastic constructions dominate flour and sugar distribution with moisture barrier specifications. Bulk bag formats penetrate professional-adjacent home baker segments in the United States.
- Pouches:Resealable flexible packaging gains share for yeast and specialty ingredients requiring oxygen and moisture exclusion. UK subscription services favor pouch formats for recipe-matched ingredient curation.
- Jars:Glass and rigid plastic containers protect hygroscopic ingredients and support premium positioning in specialty retail.
- Boxes:Folding carton structures accommodate baking mixes and kit configurations with printed recipe integration.
By volume, bags lead. By value per unit, jars command premium positioning.
End User:
Technical sophistication gradients separate price-sensitive casual bakers from specification-driven enthusiasts who demand batch-certified ingredient documentation.
- Home Bakers:Residential consumers span casual occasional users to dedicated enthusiasts with professional-grade equipment. Social media tutorial engagement directly correlates with ingredient experimentation frequency in UK and Australian markets.
- Professional Bakers:Small-scale commercial operators with residential-compatible equipment specifications bridge home and artisan bakery categories. This segment demands consistent supply reliability that strains traditional retail distribution.
- Bakeries:Micro-bakeries and cottage food operations purchase ingredients in intermediate volumes between retail and foodservice tiers.
- Cooking Schools:Instructional facilities require standardized ingredient specifications for curriculum consistency across student cohorts.
By volume, home bakers dominate. By specification intensity, professional bakers lead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's grain handling infrastructure underwrites Europe's role as the primary entry point for wheat and specialty milling inputs serving home baking supply chains across the continent.
United States
Premium heritage wheat varieties and sourdough starter cultures drive demand concentration in coastal metropolitan markets. FDA food labeling standards mandate ingredient transparency disclosures that reshape formulation strategies. Chicago's milling corridor anchors bulk flour distribution networks reaching residential bakers through direct-to-consumer e-commerce channels.
Germany
Precision-milled flour with batch-specific protein labeling displaces generic all-purpose categories in serious home baker segments. EFSA additive safety evaluations tighten permissible preservative thresholds in leavening agents. Munich and Berlin metropolitan clusters exhibit strongest demand for temperature-tolerant yeast strains accommodating residential kitchen variability.
United Kingdom
Recipe-driven ingredient bundling through subscription services replaces single-item purchasing as dominant e-commerce behavior. EU Green Deal sustainable agriculture targets influence sourcing documentation requirements for organic certification claims. London and Manchester baking content consumption correlates directly with purchase bundling frequency across flour and specialty sugar combinations.
Japan
Technical sophistication in residential baking equipment drives specification intensity for protein-specific flour selection and fermentation activity standards. METI industrial standards shape quality benchmarks for imported wheat processing. Tokyo and Osaka urban clusters lead adoption of instant dry yeast cultures with enhanced viability in challenging climates.
Australia
Social media tutorial engagement directly correlates with ingredient experimentation frequency in metropolitan baking communities. The country's national food standards regulator enforces labeling requirements for gluten content and additive disclosures. Sydney and Melbourne coastal markets capture experimentation-driven demand for sourdough starter cultures and heritage grain blends.
Home Baking Ingredients Market Competitive Environment
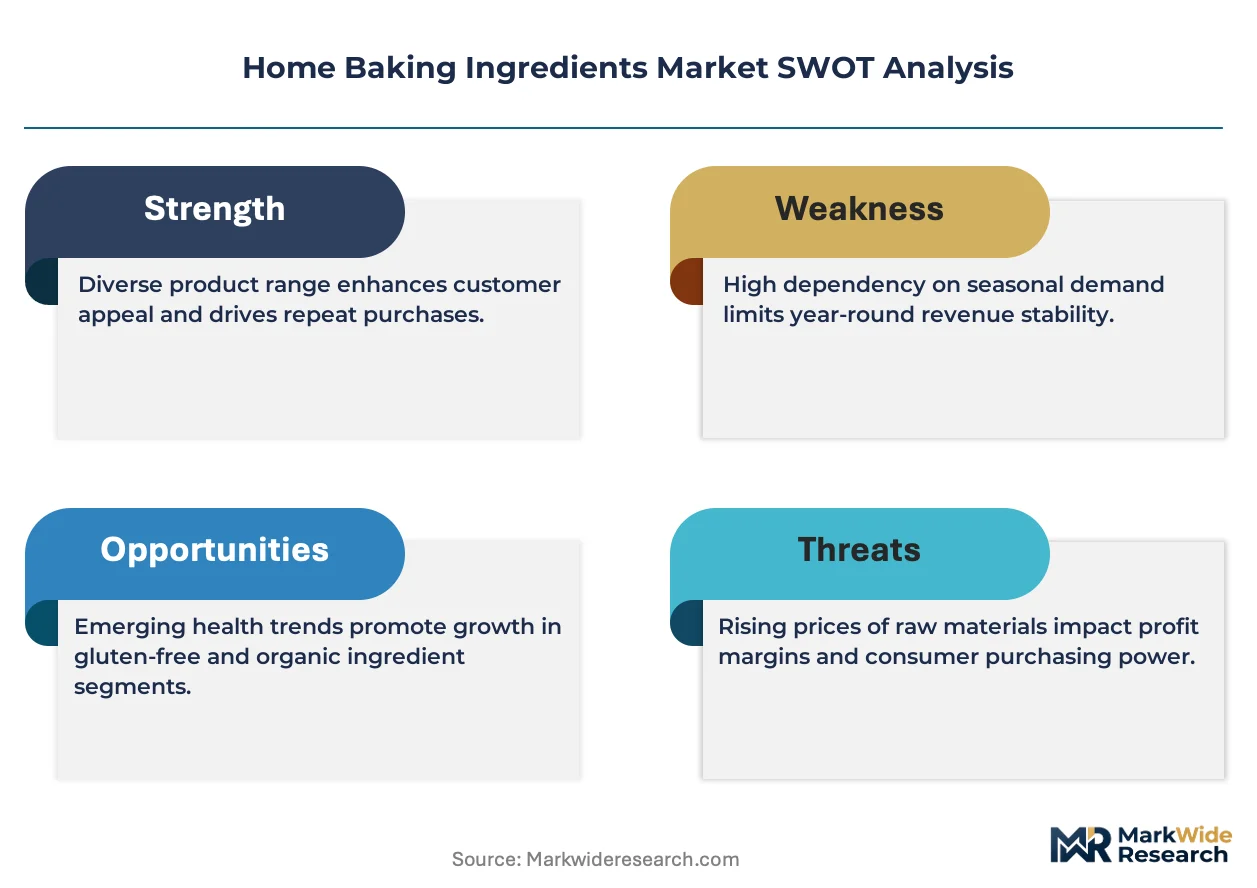
On the supply side, the industry is consolidating around integrated ingredient platforms with grain origination networks and fermentation science capabilities. Tiered competitive positioning separates bulk commodity suppliers from precision-manufactured specialty producers. Strategic archetypes include integrated agricultural processors, dedicated fermentation specialists, and diversified food ingredient conglomerates. Dominant competitive moves encompass vertical integration into upstream grain sourcing and geographic expansion through e-commerce distribution partnerships.
Within the integrated processing tier, Cargill and Archer Daniels Midland Company exemplify scale-driven agricultural commodity flows into retail and foodservice channels. Kerry Group occupies a position bridging technical ingredient platforms with direct-to-baker relationship management across North America. Lesaffre represents the fermentation specialist archetype, anchoring yeast and fermentation solutions that serve professional and home baking segments. Associated British Foods sits within the diversified conglomerate category, leveraging portfolio breadth across multiple ingredient categories and geographic markets.
| Leading Market Players |
|---|
| Kerry Group |
| Dawn Food Products |
| Cargill |
| Corbion |
| Lesaffre |
| Archer Daniels Midland Company |
| DSM-Firmenich |
| Ingredion |
| Associated British Foods |
| Others |
Value Chain & Pricing Dynamics
Active dry yeast production clusters in limited European and North American fermentation facility networks concentrate margin capture upstream, forcing downstream flour millers and specialty sugar refiners to compete on specification granularity rather than scale economies. This upstream bottleneck redistributes profitability toward strain innovation leaders while compressing commodity ingredient returns.
Pricing Analysis
Volume-discount tiering structures separate casual home bakers purchasing retail-format pouches from professional-adjacent operators sourcing bulk bags through direct channels. Price differentiation hinges on protein certification grades and fermentation viability guarantees, with USDA organic tiers commanding substantial premiums over conventional equivalents. Cost compression in standard-grade flour intensifies as generic all-purpose categories face displacement by batch-labeled alternatives. Casual occasional users exhibit highest price sensitivity, while specification-driven enthusiasts in Germany and Japan tolerate significant premiums for heritage wheat varieties and temperature-tolerant yeast strains.
Supply Chain Analysis
Supplier-financing facilities including extended payment terms and supply-chain finance programs have proliferated among integrated grain processors seeking to lock in bakery and cooking school procurement commitments. Geographic supply concentration centers on the United States for premium wheat varieties, France and Germany for fermentation science capabilities, and Brazil for bulk sugar origination. Raw material dependencies include specific gluten-strength wheat cultivars, active dry yeast cultures with defined cell counts, and refined sucrose meeting moisture specifications. Single-source vulnerability in specialized yeast strain production creates structural risk exposure. Distribution runs through e-commerce subscription platforms and traditional retail channels serving distinct end-user sophistication tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-mixed baking kits and meal-delivery subscription services pose acute substitution risk to standalone ingredient suppliers, requiring incumbents to demonstrate irreplaceable technical performance in fermentation and protein specification categories.
For Market Incumbents: Insulate core margin pools by deepening backward integration into heritage wheat seed programs and captive yeast strain development laboratories. Secure exclusive distribution partnerships with viral social media baking content creators to maintain channel control against private-label entrants. Certification investment in USDA organic and EU Green Deal carbon-accounted sourcing specifications provides defensive moats against commodity substitution. For New Entrants and Emerging Players: Coastal metropolitan markets in Australia and the United Kingdom represent the most penetrable entry points, where experimentation-driven demand for sourdough starter cultures and heritage grain blends outpaces established supplier responsiveness. Direct-to-baker subscription models bypass entrenched retail markup structures in secondary US markets. Recipe-curated bundling platforms offer the strongest go-to-market angle, leveraging social media tutorial correlation to drive initial purchase conversion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation facilities and batch-specific flour milling infrastructure, favoring scaled platforms over artisan operations. Acquisition targets should emphasize suppliers with verified supply chain data capabilities aligned to EU Green Deal documentation requirements. The signal to watch is regulatory acceleration in clean-label threshold tightening across FDA and EFSA jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heritage Wheat Seed Programs | Captive supply of premium cultivars secures protein specification differentiation against commodity millers. |
| Direct-to-Baker Subscription Platform Launch | Recipe-curated bundling captures social media-driven purchase behavior in UK and Australian metropolitan markets. |
| EU Green Deal Carbon-Accounting Certification | Verified supply chain data creates first-mover positioning for European retail and export qualification. |
| Temperature-Tolerant Yeast Strain R&D Investment | Enhanced fermentation viability addresses residential kitchen variability in challenging climates. |
| Social Media Content Creator Partnership Network | Viral tutorial correlation drives ingredient experimentation frequency and subscription conversion rates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA food labeling standards, EFSA additive safety evaluations, USDA organic certification databases, and grain trade flow documentation. Primary interviews engaged flour milling operations directors, yeast fermentation scientists, specialty retail category buyers, e-commerce subscription platform operators, and professional baking school curriculum coordinators. Secondary validation drew from SEC filings of integrated agricultural processors, customs and trade data for wheat and sugar flows, and EU Green Deal sustainable agriculture target disclosures. Bottom-up segment sizing triangulates against top-down market value reconstructions.
Forecast inputs incorporate protein quality tier adoption curves, yeast strain innovation cycle compression, social media content engagement correlation with purchase bundling frequency, and regulatory threshold evolution across clean-label mandates. Segmentation dimensions span ingredient type, application complexity, packaging format, and end-user sophistication gradient. CAGRs derive from modeled volume trajectories adjusted for substitution elasticity and channel shift dynamics. Wheat price volatility indices and fermentation facility capacity utilization rates inform scenario boundaries.
Macroeconomic conditions sit as an overlay; deviation in grain commodity price indices, consumer discretionary spending patterns, or cross-border regulatory harmonization timelines would shift the trajectory. Forecasts embed assumptions regarding social media platform algorithm stability and clean-label threshold enforcement consistency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Fats and Oils Market
Ingredients
Native Starch Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
Starch Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
North America Soybean Oil Market
Ingredients
Citrus Fiber Market
Ingredients
Protein Hydrolysate Market
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Pine Needle Oil Market
Ingredients
Dry Blended Products Market
Ingredients
Smoke Ingredients for Food Market
Ingredients
Baking Ingredients Market
Ingredients
France Protein Market