
 Europe Fat Replacers Market | 2026-2036
Europe Fat Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fat Replacers Market Foresight
Market Context
Reformulation-as-a-service is hardening as the dominant commercial layer, with ingredient suppliers bundling technical support, application testing, and regulatory documentation into long-term contracts. Cargill Incorporated leverages its European starch and lecithin network to anchor large-scale bakery reformulation programs. Roquette Frères competes through pea-protein specialization, sustaining premium positioning in plant-based fat mimetic systems.
Technical Definition and Segment Structure
Europe fat replacers are functional ingredients engineered to replicate the mouthfeel, lubricity, and structural integrity of conventional fats while delivering reduced caloric density, typically comprising carbohydrate-based polymers, protein matrices, or lipid analogs with defined particle size distributions below 50 microns. Their primary commercial purpose centers on enabling food manufacturers to achieve front-of-pack nutritional claims without sacrificing sensory performance in finished goods. Protein-based systems lead in margin contribution due to clean-label premiums, while emulsifiers dominate volume throughput across industrial sauce and dressing applications. Starches occupy the most mature position with compressed pricing, whereas texture improvement functionality captures the fastest-growing demand segment as processors target indulgence parity in reduced-fat formulations.
Regulatory Framework and Outlook
EFSA evaluates novel fat replacer submissions under consolidated health claim procedures, while REACH governs chemical safety profiles for synthetic lipid analogs and the EU Green Deal's Farm to Fork strategy imposes origin traceability requirements on imported raw materials. These overlapping frameworks elevate compliance costs for non-EU suppliers and privilege established European compounders with in-house regulatory affairs capabilities. Stakeholders must monitor ECHA's expanding substance restriction candidate list and anticipate stricter carbon footprint disclosure rules for ingredient procurement decisions.
Market Dynamics
EFSA's evolving nutrition claims framework is compressing approval timelines for novel fat replacers while simultaneously elevating documentation burdens, forcing ingredient suppliers to embed regulatory affairs capabilities directly into technical service contracts or exit reformulation partnerships.
Growth Catalysts
- EU Green Deal's Farm to Fork strategy:Mandatory sustainable ingredient sourcing is accelerating reformulation mandates across German and French dairy processors seeking carbon footprint reductions.
- Clean-label protein systems:Pea-protein fat mimetics are capturing premium positioning in plant-based bakery applications as consumer scrutiny intensifies around ingredient provenance.
- Calorie-reduction functionality in dairy:Western European production clusters are concentrating demand for texture-matched reduced-fat formulations in yogurt and cheese analogs.
Market Restraints
- EFSA consolidated health claim procedures:Novel fat replacer submissions face 18-24 month evaluation windows that freeze commercialization timelines and tie up R&D capital.
- Imported raw material traceability:REACH compliance costs for non-EU suppliers of synthetic lipid analogs privilege established European compounders with captive regulatory infrastructure.
- Starch-based system commoditization:Mature carbohydrate polymer pricing compresses margins for suppliers lacking differentiated texture-engineering capabilities.
Strategic Opportunities
- United Kingdom post-Brexit regulatory autonomy:Divergence from EFSA procedures creates parallel approval pathways for reformulated products targeting British retail channels.
- ECHA substance restriction candidate list expansion:Anticipated carbon footprint disclosure rules will reward early adopters of origin-verified supply chains with preferred supplier status.
- Emulsifier-indulgence convergence:Industrial sauce and dressing manufacturers are integrating fat replacers with flavor-carrying lipid systems to achieve sensory parity in reduced-calorie condiments.
Industry Challenges
- Particle size distribution engineering:Sub-50 micron consistency requirements demand capital-intensive micronization equipment that mid-scale suppliers struggle to finance.
- Cross-functional talent scarcity:Food scientists capable of bridging sensory evaluation, regulatory documentation, and application testing command premium compensation that strains fixed-cost structures.
Report Scope
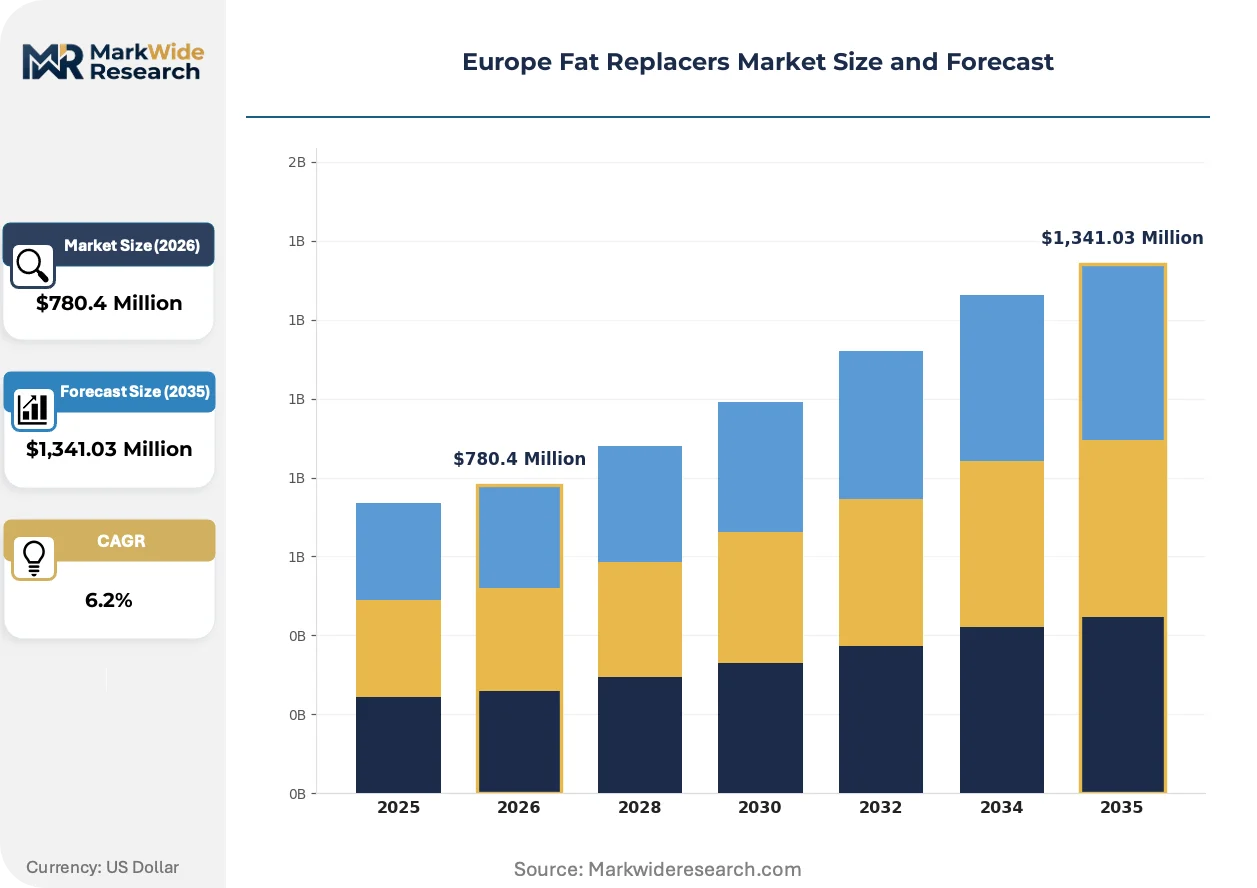
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fat Replacers Market |
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,341.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Starches, Gums, Proteins Application: Dairy Products, Baked Goods, Sauces, Snacks End User: Food Manufacturers, Retailers, Foodservice, Consumers Functionality: Texture Improvement, Flavor Enhancement, Calorie Reduction, Moisture Retention |
| Companies Covered | Corbion N.V., Fuji Oil Europe, Cargill Incorporated, Ajinomoto Foods Europe Sas, Tate & Lyle, Ingredion Inc., BDF Natural Ingredients, Roquette Frères, Kerry Group plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fat Replacers Market Shifts & Advancements
Reformulation-as-a-service is hardening from consultative add-on to contractual core, with technical support, application testing, and regulatory documentation bundling into multi-year supply agreements that lock out unbundled competitors.
Pea-protein fat mimetic technology is unifying mouthfeel replication with clean-label positioning in plant-based systems. German and French bakery manufacturers are adopting these matrices at accelerated pace for croissant and puff-pastry reformulations. The convergence is compressing demand for traditional carbohydrate-based polymers in premium positioning tiers.
EFSA's novel food catalog updates are tightening safety assessment protocols for enzymatically modified starches and lipid analogs. Industrial consequence includes elevated toxicology study requirements that favor suppliers with in-house clinical validation capabilities. Dairy alternative manufacturers in the Netherlands and Belgium are most affected, accelerating partnerships with established European compounders possessing documented substance histories.
Buyer concentration among multinational processed food manufacturers is consolidating procurement decisions into centralized technical sourcing functions. Regional ingredient distributors are losing direct access to formulation teams as direct supplier-manufacturer relationships deepen. This disintermediation is most visible in United Kingdom and German reformulation programs where technical service integration determines contract awards.
Europe Fat Replacers Market Segmentation
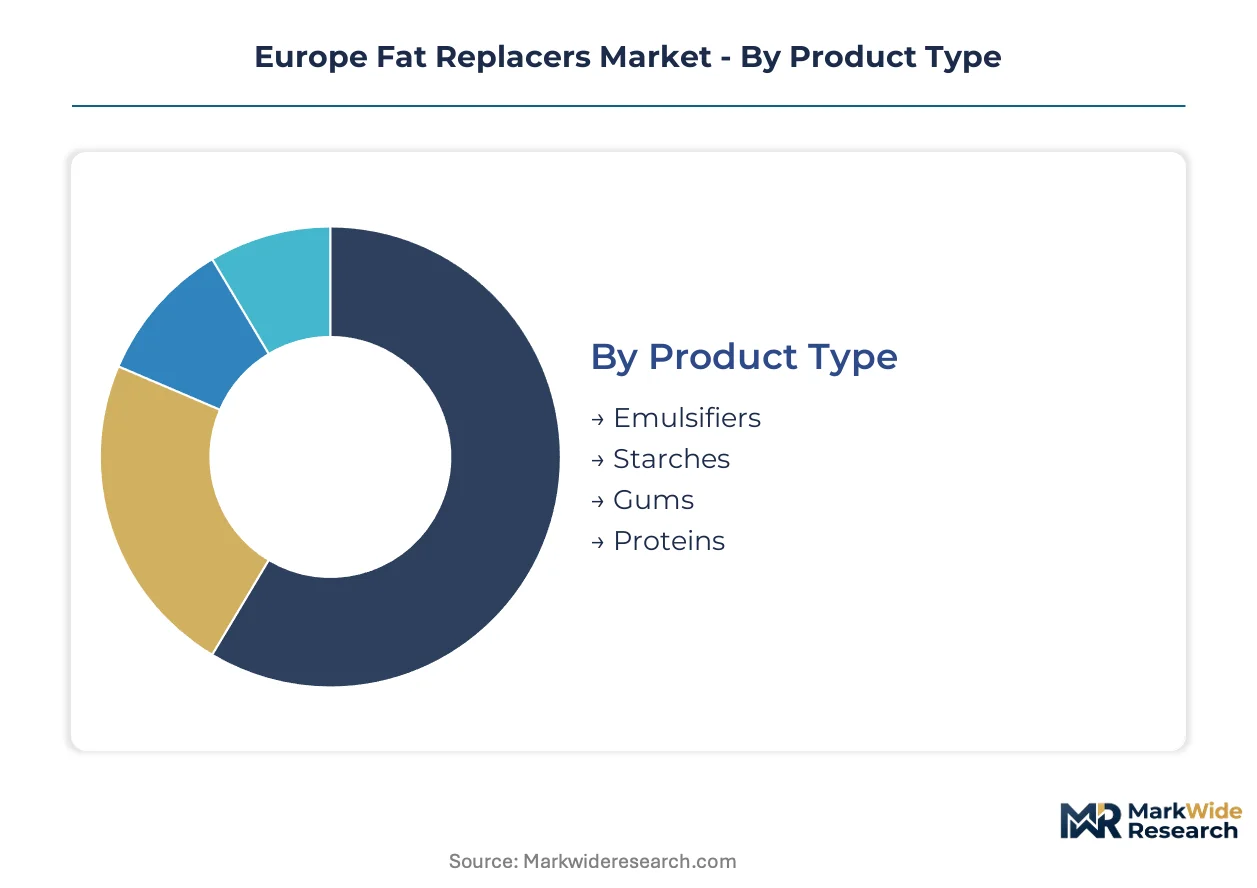
Fat replacer procurement in Europe follows distinct technical and commercial logics across product categories and application contexts. Understanding where each segment sits on the standalone-to-embedded spectrum clarifies supplier positioning and margin capture opportunities.
Product Type:
Integration depth varies sharply—emulsifiers and starches operate as commodity inputs in high-volume formulations, while proteins and gums command premium positioning through specialized technical service requirements.
- Emulsifiers:Lipid-compatible surfactant systems stabilize water-in-oil and oil-in-water interfaces at industrial scale. German and French dairy processors concentrate procurement for reduced-fat cheese and spread applications where EFSA nutrition claim compliance drives specification rigor.
- Starches:Modified carbohydrate polymers from maize, potato, and tapioca sources provide viscosity and mouthfeel replication through controlled gelatinization profiles. Pricing compression across Western European supply chains limits margin expansion for suppliers lacking differentiated texture-engineering capabilities.
- Gums:Hydrocolloid matrices from locust bean, guar, and xanthan fermentation build thixotropic structures in low-fat sauces. REACH documentation burdens favor established European compounders with captive regulatory infrastructure.
- Proteins:Pea and whey protein concentrates replicate fat globule functionality through controlled denaturation and particle size engineering. Clean-label positioning in UK and Dutch plant-based bakery applications supports premium pricing tiers.
Emulsifiers lead volumes today; proteins are gaining share fastest.
Application:
Cost tier segmentation separates indulgence-parity formulations from basic calorie-reduction mandates, with technical complexity and claim substantiation requirements determining procurement budgets.
- Dairy Products:Yogurt, cheese, and spread reformulations demand precise fat globule size distribution matching to maintain creaminess perception. Netherlands and Belgian production clusters drive specification intensity for texture-matched reduced-fat analogs.
- Baked Goods:Croissant, puff-pastry, and cake applications require lamination integrity and moisture retention under thermal stress. German manufacturers prioritize clean-label protein systems for premium positioning tiers.
- Sauces:Industrial dressing and condiment producers integrate fat replacers with flavor-carrying lipid systems. Volume throughput concentrates among multinational processors with centralized technical sourcing functions.
- Snacks:Extruded and fried product categories utilize carbohydrate-based systems for reduced-fat claims. French savory snack manufacturers anchor demand for EFSA-compliant reformulation documentation.
Dairy applications command the highest technical service intensity; baked goods show the steepest expansion trajectory.
End User:
Customer type determines contract structure—food manufacturers lock in multi-year technical service agreements while foodservice and retail channels prioritize cost flexibility and minimum order efficiency.
- Food Manufacturers:Multinational processed food producers centralize procurement decisions into technical sourcing functions that bundle application testing, regulatory documentation, and supply security. Direct supplier relationships disintermediate regional distributors.
- Retailers:Private-label program managers specify fat replacer systems for co-manufactured reduced-fat product lines. UK supermarket chains drive clean-label formulation requirements through own-brand reformulation mandates.
- Foodservice:Industrial kitchens and chain restaurant operators prioritize shelf-stable pre-mix solutions with minimal preparation complexity. Cost sensitivity limits adoption to standard emulsifier and starch systems.
- Consumers:Direct-to-home ingredient sales remain marginal, concentrated in specialty baking supply channels targeting home reformulation enthusiasts.
Food manufacturers dominate contract value; retailers are expanding specification influence fastest.
Functionality:
Margin concentration aligns with performance differentiation—texture improvement and calorie reduction capture premium positioning, while moisture retention operates as a baseline hygiene factor.
- Texture Improvement:Particle size engineering below 50 microns replicates lubricity and mouthfeel in reduced-fat matrices. Capital-intensive micronization equipment requirements privilege large-scale European compounders.
- Flavor Enhancement:Lipid analog systems carry and release volatile flavor compounds in low-fat formulations. French sauce manufacturers prioritize this functionality for indulgence parity in reduced-calorie condiments.
- Calorie Reduction:Caloric density reduction while maintaining sensory performance enables front-of-pack nutritional claims. EFSA evaluation timelines for novel systems freeze commercialization schedules for 18-24 months.
- Moisture Retention:Water-binding capacity prevents staling and syneresis in extended shelf-life applications. Mature starch and gum technologies compress pricing in this functional tier.
Texture improvement commands premium margins; calorie reduction faces the steepest regulatory documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production capacity toward jurisdictions with streamlined novel food approval pathways. The EU Green Deal's carbon accounting requirements privilege domestic compounders over importers facing traceability documentation burdens.
Germany
Bavarian and North Rhine-Westphalian dairy processors drive demand for texture-matched reduced-fat cheese analogs. EFSA consolidated health claim procedures govern reformulation documentation for export-bound products. The Cologne-Düsseldorf industrial corridor concentrates technical service contracts for emulsifier-based fat replacement systems.
France
Auvergne-Rhône-Alpes and Île-de-France host reformulation programs targeting indulgence parity in sauce and bakery applications. REACH compliance for enzymatically modified starches elevates toxicology study requirements. Parisian food manufacturers are consolidating procurement into centralized technical sourcing functions.
United Kingdom
Post-Brexit regulatory autonomy creates parallel approval pathways diverging from EFSA timelines. UK supermarket chains mandate clean-label protein systems for private-label reduced-fat product lines. The Midlands production cluster anchors pea-protein fat mimetic adoption in croissant and puff-pastry reformulations.
Netherlands
Belgian-Dutch dairy alternative manufacturers face tightened EFSA novel food catalog protocols for lipid analogs. The Wageningen food innovation ecosystem accelerates partnerships with established European compounders possessing documented substance histories. Rotterdam-Antwerp logistics corridors facilitate carbon footprint disclosure for origin-verified supply chains.
Italy
Emilia-Romagna and Lombardy processors concentrate demand for EFSA-compliant reformulation documentation in savory snack categories. The EU Green Deal's Farm to Fork strategy mandates sustainable ingredient sourcing for export-oriented manufacturers. Milan-based food manufacturers are integrating fat replacers with flavor-carrying lipid systems in reduced-calorie condiments.
Europe Fat Replacers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational ingredient compounders anchoring long-term technical service contracts while regional distributors lose direct formulation access. The vendor base organizes around three archetypes: integrated agribusinesses with captive starch and protein networks, hydrocolloid specialists with REACH-compliant regulatory infrastructure, and dairy-derived ingredient processors leveraging enzymatic modification capabilities. Consolidation pressures favor players bundling application testing, regulatory documentation, and supply security into multi-year agreements.
Among Dutch and French compounders, Corbion N.V. and Roquette Frères exemplify the integrated specialist archetype through pea-protein specialization and European manufacturing footprints. Cargill Incorporated anchors the agribusiness tier with starch and lecithin network coverage across German and UK reformulation programs. These three represent divergent strategic positions on the clean-label functionality spectrum.
| Leading Market Players |
|---|
| Corbion N.V. |
| Fuji Oil Europe |
| Cargill Incorporated |
| Ajinomoto Foods Europe Sas |
| Tate & Lyle |
| Ingredion Inc. |
| BDF Natural Ingredients |
| Roquette Frères |
| Kerry Group plc |
| Others |
Supply & Pricing Matrix
Pea-protein concentrate costs cascade through three distinct pricing tiers as raw material traceability requirements harden under EU Green Deal mandates. German dairy processors absorb premium positioning for clean-label systems while French sauce manufacturers negotiate volume discounts on modified starch commodities.
Pricing Analysis
Distributor margins compress as multinational food manufacturers consolidate procurement into direct supplier relationships. Three-tier pricing structure across premium, standard, and economy levels separates protein-based fat mimetics from emulsifier commodities and starch generics. Price differentiation hinges on EFSA documentation completeness and particle size engineering precision. Margins are tightening due to REACH compliance cost absorption for non-EU synthetic lipid analog suppliers.
Supply Chain Analysis
Dual-sourcing requirements from Dutch and Belgian dairy alternative manufacturers mandate multi-supplier qualification for enzymatically modified starches. Supply concentrates in Germany, France, and the Netherlands for pea-protein extraction and carbohydrate polymer processing. Raw material dependencies center on Ukrainian sunflower lecithin, French wheat starch, and Canadian yellow pea protein. Single-source vulnerability persists for micronization equipment servicing sub-50 micron particle size consistency. Distribution runs through Rotterdam-Antwerp logistics corridors with carbon footprint disclosure documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Fat Replacers Market compounds steadily as reformulation-as-a-service contracts lock in multi-year technical service relationships. EFSA's evolving nutrition claims framework sustains incumbent advantage through documentation barriers.
For Market Incumbents: Hedge against pea-protein commoditization by anchoring proprietary particle size engineering capabilities in long-term dairy reformulation partnerships. Defensive moves center on backward integration into Ukrainian lecithin sourcing and capacity expansion in the Cologne-Düsseldorf corridor. Certification investment in REACH-compliant toxicology study archives privileges established European compounders over import-dependent challengers.
For New Entrants and Emerging Players: Capture white-space in UK post-Brexit regulatory divergence where parallel approval pathways shorten commercialization timelines. The Midlands production cluster offers penetrable entry for croissant and puff-pastry reformulation programs. Go-to-market positioning should emphasize clean-label protein systems for supermarket private-label mandates.
For Investors and Strategic Acquirers: Roll-up economics work for hydrocolloid specialists with captive regulatory infrastructure because EFSA evaluation timelines freeze out capital-constrained mid-scale competitors. Five-to-ten year viability rests on consolidation of application testing and documentation capabilities. Watch ECHA substance restriction candidate list expansion as inflection signal for preferred supplier status reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Sourcing | Captive supply of Canadian yellow pea isolates secures clean-label positioning for Dutch dairy alternatives. |
| REACH-Compliant Toxicology Archive Investment | Documented substance histories accelerate EFSA novel food approvals for Belgian lipid analog manufacturers. |
| Micronization Equipment Partnership | Sub-50 micron consistency capabilities unlock premium texture-engineering contracts with German bakery processors. |
| UK Regulatory Divergence Exploitation | Parallel approval pathways capture British retail channel reformulation mandates ahead of continental competitors. |
| Carbon Footprint Disclosure System Deployment | Origin-verified supply chains secure preferred supplier status under EU Green Deal procurement rules. |
Research Methodology
Bottom-up food manufacturer procurement modeling reconciled against top-down ingredient supplier capacity tracking forms the analytical core of this study. Primary interviews with dairy reformulation directors, bakery application technologists, regulatory affairs managers at compounders, and supermarket private-label buyers combined with secondary validation from EFSA novel food catalog updates, REACH substance restriction lists, and EU Green Deal Farm to Fork strategy documentation. Customs data on pea-protein and modified starch trade flows, alongside SEC filings of listed ingredient suppliers, provided supply-side triangulation.
Input-output matrices mapped fat replacer demand across dairy, bakery, sauce, and snack applications against emulsifier, starch, gum, and protein supply capacity. Segmentation dimensions modeled include product type integration depth, application technical intensity, end-user contract structure, and functionality margin tier. CAGRs were derived from volume trajectory analysis across the projection horizon, incorporating EFSA approval timeline assumptions and carbon disclosure rule implementation schedules.
EFSA evaluation timeline extensions, REACH substance restriction accelerations, and EU Green Deal sourcing mandate enforcement are the dominant revision risks. Deviation in EFSA approval velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Asia-Pacific Food Hydrocolloids Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Polydextrose Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Food Coating Market
Food Components and Additives
Spain Food Hydrocolloids Market