
 Specialty Shortenings Market | 2026-2036
Specialty Shortenings Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Shortenings Market Analytics
Modular fat blending is restructuring how food manufacturers configure shortening procurement, shifting volume commitments away from single-specification bulk contracts toward portfolio-based supply agreements. Bunge North America leverages its oilseed crush network to sustain integrated supply security across North American bakery accounts. Cargill competes through formulation services that extend technical support deeper into customer R&D pipelines. Ventura Foods anchors foodservice distribution through regional shortening blends tailored to frying stability requirements.
Specialty shortenings are refined lipid formulations engineered with controlled solid fat content, melting profiles, and oxidative stability to deliver specific functional performance in food matrices; manufacturers achieve these properties through interesterification, fractionation, or blending of oils with distinct fatty acid compositions. Non-hydrogenated shortenings dominate reformulation activity as food manufacturers eliminate partially hydrogenated oils from legacy recipes. Palm oil occupies the largest volume position due to its cost structure and functional versatility, though sustainability certification pressures are reshaping sourcing requirements. Margarine segments lead margin pools where premium bakery and confectionery applications command price premiums for precise plasticity and mouthfeel control.
The FDA's PHO removal mandate and subsequent GRAS revocation reshaped domestic formulation standards, while EFSA's continued evaluation of 3-MCPD esters in refined vegetable oils drives European purity specifications tighter. BIS quality benchmarks and FSSAI packaging regulations in India create layered compliance requirements for imported specialty fat products. Stakeholders must monitor emerging limits on palm oil sustainability claims and accelerating interest in enzymatic interesterification as cleaner-process alternatives.
Market Dynamics
Modular fat blending protocols are fragmenting procurement patterns across bakery and foodservice accounts, forcing suppliers to abandon single-specification bulk contracts in favor of portfolio-based supply agreements that accommodate rapid formulation pivots.
Growth Catalysts
- PHO Elimination Mandates:The FDA's GRAS revocation for partially hydrogenated oils compels reformulation across North American packaged food and bakery sectors, accelerating demand for enzymatically interesterified alternatives.
- Clean-Label Bakery Applications:Consumer packaged goods manufacturers are pulling reformulated shortenings into wider foodservice channels as operators seek simplified ingredient declarations for menu transparency.
- Southeast Asian Processing Clusters:Integrated refining capacity concentrated in Indonesia and Malaysia feeds global specialty fat supply chains with cost-competitive, functionally versatile palm-based inputs.
Market Restraints
- Crude Palm Oil Price Volatility:Input cost swings tied to Malaysian ringgit fluctuations and El Niño weather patterns compress margin predictability for refined specialty fat producers.
- 3-MCPD Ester Regulatory Friction:EFSA's tightening purity specifications for refined vegetable oils impose additional refining steps and analytical compliance burdens on European-bound shipments.
- Sustainability Certification Concentration:RSPO and MSPO compliance requirements concentrate sourcing leverage among integrated plantation-refiner operations, limiting qualified supplier pools for mid-scale buyers.
Strategic Opportunities
- Enzymatic Interesterification Expansion:Cleaner-process enzymatic methods are displacing chemical interesterification in premium bakery and confectionery applications where label simplicity commands price premiums.
- Indian Foodservice Penetration:FSSAI packaging regulations and BIS quality benchmarks create structured entry pathways for imported specialty fats targeting organized bakery chains and quick-service restaurant fryer operations.
- Plant-Based Meat Analogues:Fat structuring technologies originally developed for bakery plasticity are migrating into alternative protein formulations requiring controlled solid fat content for mouthfeel simulation.
Industry Challenges
- Fractionation Technology Talent Scarcity:Specialized process engineers capable of optimizing dry fractionation and detergent fractionation sequences remain concentrated within Malaysian and Indonesian refiner operations.
- Legacy System Integration Complexity:Bakery manufacturers running continuous mixing lines face production disruption risks when retrofitting equipment for non-hydrogenated shortening rheology profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Shortenings Market |
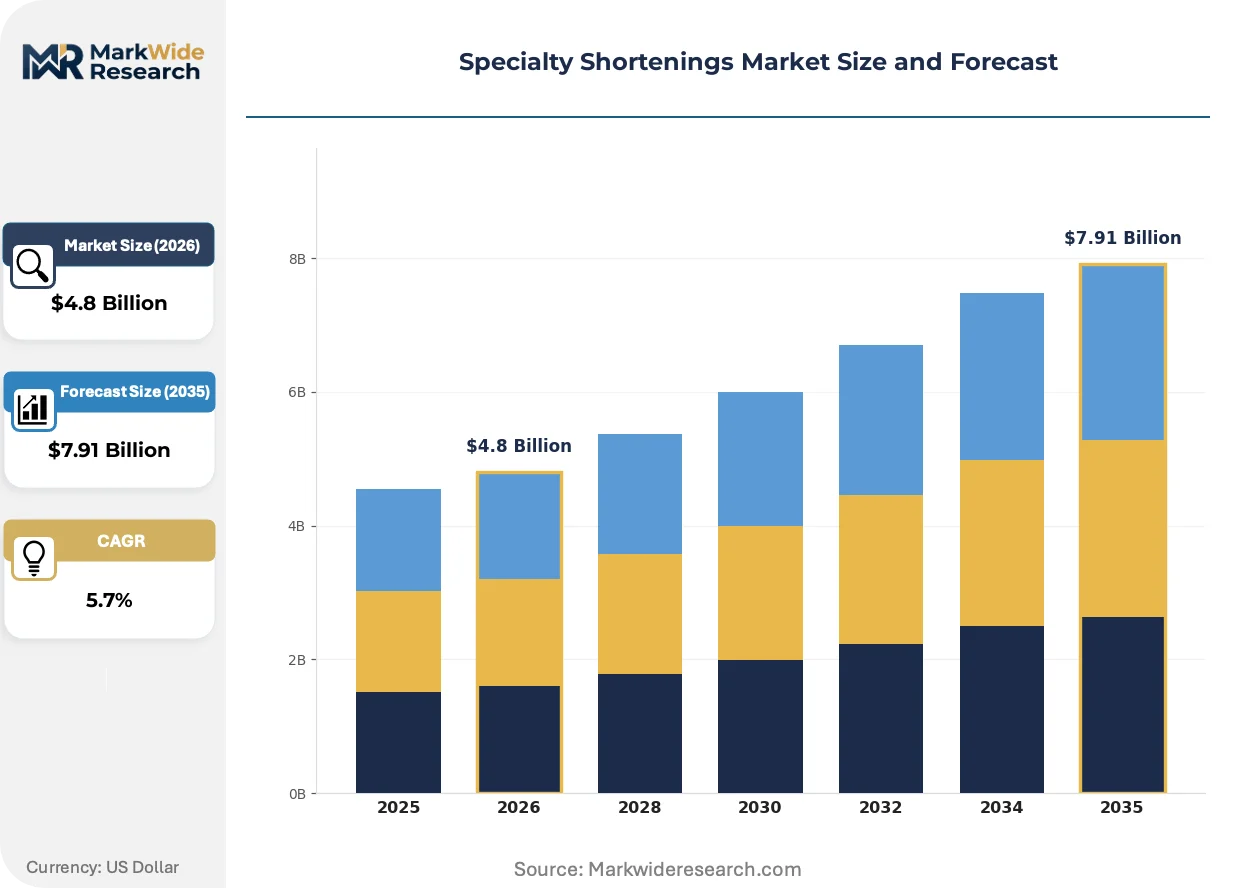
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Hydrogenated, Palm Oil, Margarine, Lard Application: Baking, Frying, Spreading, Confectionery End User: Food Manufacturers, Bakeries, Restaurants, Cafés Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Bunge North America, Inc., Cargill, Inc., Archer Daniels Midland Company, Ventura Foods, Musim Mas Holdings Pte. Ltd., Sime Darby Kempas Sdn. Bhd., Tate & Lyle Plc., AAK AB, Wilmar International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Shortenings Market Evolving Landscape
Reformulation chemistry and process engineering are converging to eliminate trans-fat functionality gaps while preserving the oxidative stability and plasticity ranges that industrial bakers require for consistent product quality.
Enzymatic interesterification is decentralizing production geography by enabling smaller-scale, lower-temperature processing that reduces capital intensity for regional specialty fat manufacturers. Mid-scale North American and European oil processors are adopting immobilized lipase systems to produce bakery-tailored fat blends without the infrastructure scale historically required for chemical interesterification. This technology compression is enabling contract manufacturing networks to serve regional bakery clusters with shortened lead times.
EFSA's evolving 3-MCPD ester guidelines are forcing European refiners to deploy modified deodorization protocols and alternative refining aids. The regulatory pressure tightens purity specifications for refined palm oil and palm olein fractions destined for infant formula and premium confectionery applications. German and Dutch refiners are responding with dual-refining train investments that segregate high-purity output streams from standard food-grade production.
Bakery procurement teams are consolidating supplier relationships around technical service capabilities rather than commodity price alone. Large North American packaged bread manufacturers now require embedded formulation support for shortening substitution in legacy recipes, displacing traditional spot-market purchasing patterns. This service bundling is most pronounced in artisan and frozen dough segments where precise melting profile control determines product consistency.
Specialty Shortenings Market Segmentation
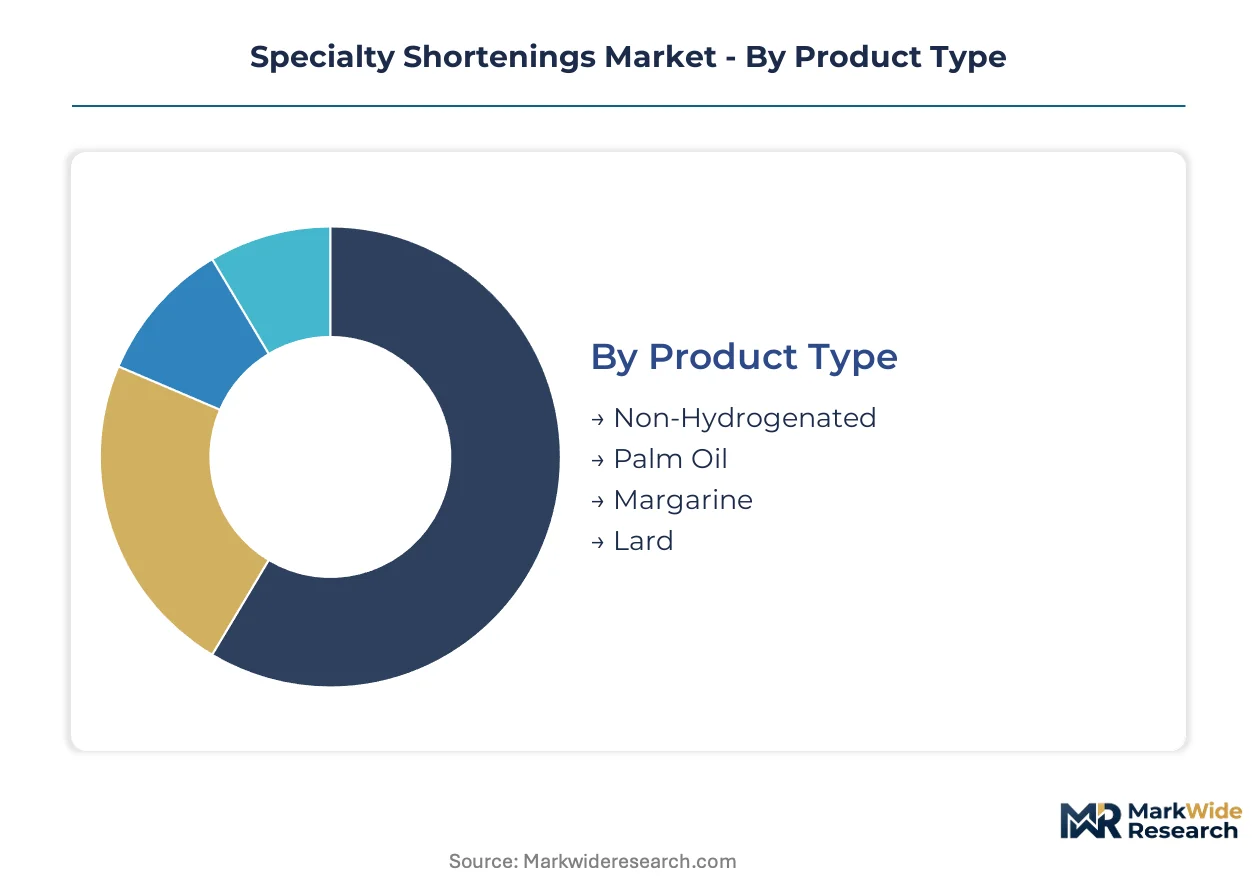
Specialty shortenings require precise functional matching between lipid chemistry and processing conditions. Segmentation reveals where formulation complexity drives premium pricing versus where commodity substitution suffices.
Product Type:
Customization intensity spans from drop-in commodity replacements to engineered fat systems requiring technical collaboration between supplier and buyer R&D teams.
- Non-Hydrogenated:These interesterified or fractionated formulations eliminate trans-fat content while mimicking PHO functionality through controlled solid fat content manipulation. North American bakery manufacturers have concentrated procurement here following FDA's GRAS revocation for partially hydrogenated oils. Enzymatic processing methods command price premiums where clean-label declarations matter.
- Palm Oil:Fractionated palm stearin and olein fractions provide cost-competitive structuring capability through natural solid fat content without hydrogenation. Indonesian and Malaysian integrated refiners dominate supply, though RSPO certification requirements now filter qualified supplier pools for European and North American accounts.
- Margarine:Water-in-fat emulsions with precise plasticity ranges for laminating and creaming applications.
- Lard:Rendered pork fat retaining niche demand in traditional baking and specific ethnic cuisine formulations.
Most installed capacity flows through Palm Oil. Expansion is steepest in Non-Hydrogenated.
Application:
Performance requirements diverge sharply between thermal stress environments and gentle processing conditions.
- Baking:Lamination, creaming, and shortening applications demand precise melting profiles and plasticity windows. Frozen dough manufacturers and artisan bakeries concentrate demand for specialty fats with narrow solid fat content curves that maintain performance across temperature fluctuations.
- Frying:Oxidative stability and polymerization resistance determine oil life in continuous fryer operations. Quick-service restaurant chains and snack food manufacturers prioritize polar compound formation rates and foam suppression over initial purchase price.
- Spreading:Table-use margarines and specialty spreads require mouthfeel optimization and flavor stability.
- Confectionery:Cocoa butter equivalents and tempering fats need exact polymorphic stability for gloss and snap retention.
Volume concentrates in Baking. Margins peak in Confectionery.
End User:
Procurement sophistication separates large-scale formulation partnerships from transactional commodity purchasing.
- Food Manufacturers:Industrial bakeries and packaged food producers negotiate technical service bundles including recipe reformulation support. These accounts drive enzymatic interesterification adoption and sustainability certification requirements through supply chain leverage.
- Bakeries:Independent and chain operations span from commodity shortening buyers to artisan producers specifying exact solid fat content curves for laminated dough performance.
- Restaurants:Foodservice fryer operations prioritize oil stability and filtration compatibility over ingredient declaration simplicity.
- Cafés:Small-batch pastry production with intermittent demand patterns favors distributor-delivered packaged formats.
Contract value concentrates with Food Manufacturers. Growth velocity is highest among Bakeries.
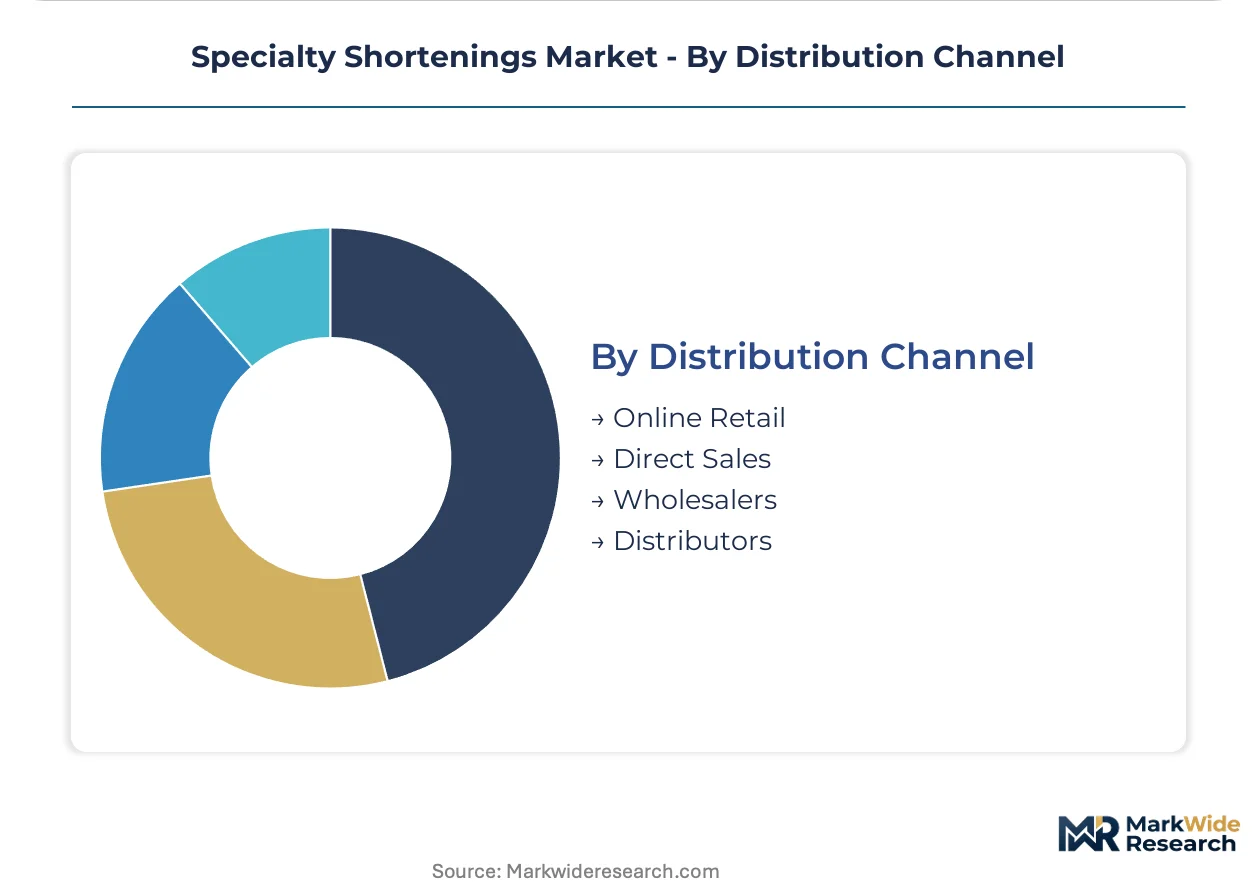
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic proximity to processing infrastructure.
- Direct Sales:National bakery chains and multinational food manufacturers maintain direct relationships with Bunge, Cargill, and integrated palm refiners for volume commitments and embedded formulation services. These agreements now incorporate sustainability certification documentation and technical R&D collaboration.
- Distributors:Regional foodservice distributors aggregate demand from mid-scale bakeries and restaurant accounts, warehousing shortening blends tailored to local frying stability and climate conditions.
- Wholesalers:Cash-and-carry and broadline foodservice suppliers serve small independent bakeries with standard packaged formats.
- Online Retail:E-commerce penetration remains limited to specialty and organic shortening variants targeting home bakers and small commercial accounts.
Volume flows through Distributors. Digital channel development lags other food ingredient categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The specialty shortenings industry traces its modern scale to integrated palm oil refining complexes established in Southeast Asia during the 1980s. These processing clusters subsequently expanded into global supply networks serving reformulated bakery and confectionery markets. Today, regional demand patterns reflect divergent regulatory pressures and end-use manufacturing concentrations.
United States
FDA's GRAS revocation for partially hydrogenated oils forced systematic reformulation across packaged bread and frozen dough sectors. Large bakery manufacturers now require embedded technical support for shortening substitution in legacy equipment. Regional blending facilities in the Midwest and Southeast supply enzymatically interesterified alternatives to industrial accounts.
Germany
EFSA's tightening 3-MCPD ester specifications drive investments in modified deodorization protocols at refineries serving confectionery and infant formula applications. Dual-refining train configurations segregate high-purity output streams from standard food-grade production. The Port of Rotterdam corridor anchors European import and redistribution capacity for certified sustainable palm fractions.
Indonesia
Integrated plantation-refiner operations in Sumatra and Kalimantan feed global supply chains with cost-competitive palm stearin and olein fractions. RSPO and MSPO certification requirements concentrate sourcing leverage among vertically integrated producers. Government biodiesel blending mandates periodically divert crude palm oil volumes from food-grade refining channels.
India
FSSAI packaging regulations and BIS quality benchmarks create structured entry pathways for imported specialty fats targeting organized bakery chains and quick-service restaurant fryer operations. Maharashtra and Karnataka host expanding domestic shortening formulation capacity serving regional foodservice distributors. Mid-scale processors face compliance complexity when sourcing fractionated palm components from multiple origins.
Malaysia
Johor and Port Klang refining clusters maintain global leadership in dry fractionation technology for bakery and confectionery applications. El Niño weather patterns and ringgit volatility introduce margin unpredictability for exporters serving European and North American accounts. Specialized process engineering talent remains concentrated within established refiner operations, constraining new entrant expansion.
Specialty Shortenings Market Competitive Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with captive oilseed crush and fractionation infrastructure. Market concentration is pronounced at the upstream refining tier, where plantation-to-port operations in Southeast Asia supply global formulators. Three archetypes dominate: integrated palm refiners controlling raw material access, North American oilseed processors with technical service bundling capabilities, and regional foodservice blenders optimizing fryer stability for local climate conditions. Capacity expansion and sustainability certification acquisition represent the dominant competitive vectors as buyers consolidate supplier relationships around compliance documentation and embedded R&D support.
Within the integrated agribusiness tier, Bunge North America and Cargill anchor North American supply security through oilseed crush networks and formulation service extensions. Ventura Foods occupies a position among regional foodservice specialists tailoring shortening blends to frying stability requirements across climate-diverse distribution territories. Musim Mas Holdings Pte. Ltd. exemplifies the Southeast Asian plantation-refiner archetype with integrated capacity feeding global specialty fat supply chains. These three entities represent distinct strategic positions without overlapping functional emphasis.
| Leading Market Players |
|---|
| Bunge North America, Inc. |
| Cargill, Inc. |
| Archer Daniels Midland Company |
| Ventura Foods |
| Musim Mas Holdings Pte. Ltd. |
| Sime Darby Kempas Sdn. Bhd. |
| Tate & Lyle Plc. |
| AAK AB |
| Wilmar International |
| Others |
Value Network & Pricing Analysis
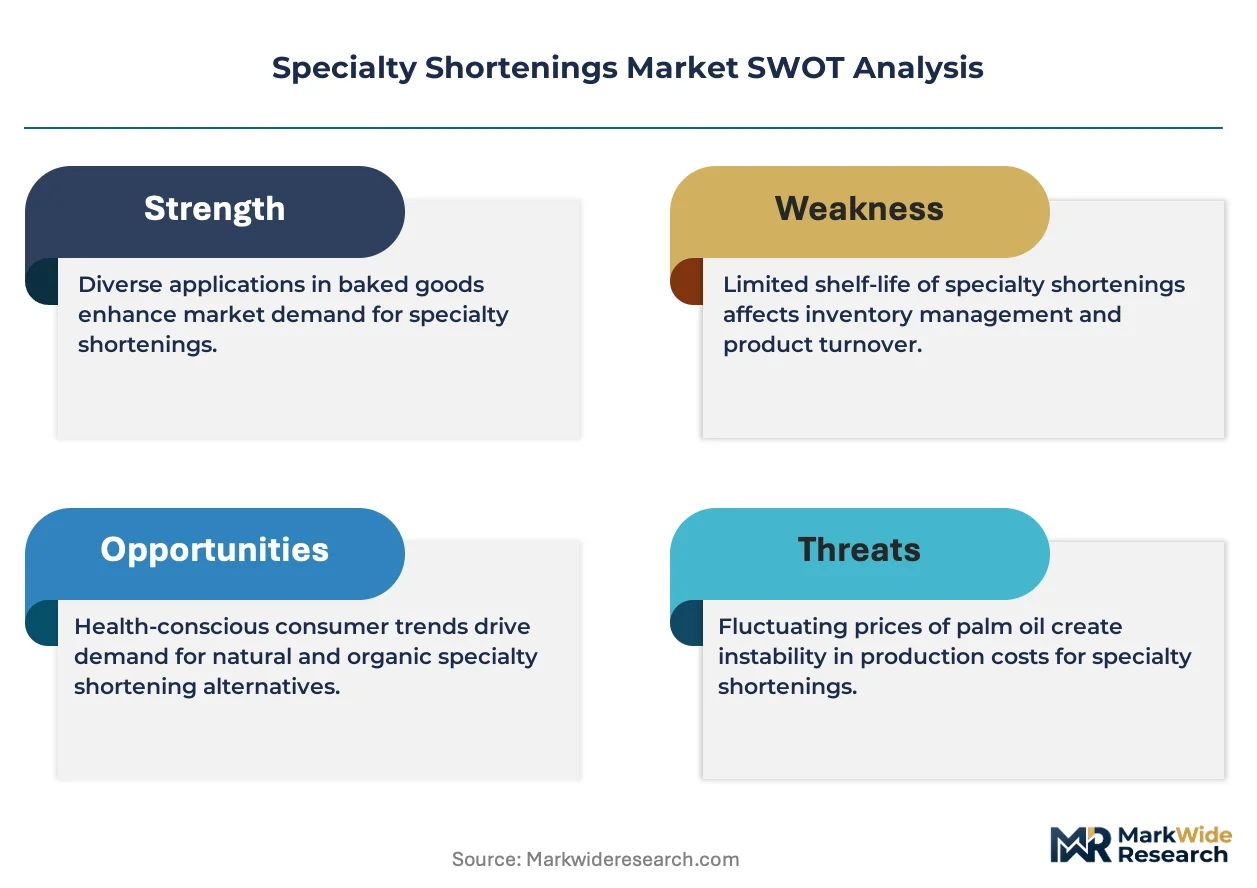
Industrial bakery manufacturers purchasing enzymatically interesterified shortenings negotiate contract structures that bundle technical formulation support with volume commitments, compressing spot-market participation to commodity palm oil fractions alone. FDA's PHO removal mandate forced these buyers to abandon price-first procurement in favor of performance-guaranteed supply agreements that internalize R&D collaboration costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and embedded technical service intensity. Premium tiers attach to RSPO-certified enzymatic products with supplier-embedded formulation teams, while economy tiers cover unmodified palm olein fractions traded on Malaysian ringgit-linked benchmarks. Pricing pressure stems from El Niño-driven crude palm oil volatility that compresses margin predictability for refiners serving European confectionery accounts. Food manufacturers with dedicated R&D staff exhibit lowest price sensitivity; independent bakeries and cash-and-carry foodservice buyers concentrate price elasticity.
Supply Chain Analysis
Ocean freight rates from Port Klang and Tanjung Priok to Rotterdam and Houston anchor landed cost calculations for North American and European buyers sourcing fractionated palm components. Supply concentrates in Indonesia, Malaysia, and increasingly India where integrated plantation-refiner operations control upstream crude palm oil access. Raw material flows draw from Sumatran and Kalimantan estates, with dependency on Malaysian dry fractionation technology for high-value bakery stearin outputs. Single-source vulnerability concentrates in Johor-based specialty fractionation capacity serving global confectionery demand. Distribution runs through regional foodservice distributors that warehouse climate-formulated shortening blends for quick-service restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA's GRAS revocation for partially hydrogenated oils permanently restructured formulation demand toward enzymatic alternatives. Compliance-driven substitution created durable volume anchors for suppliers with clean-process capabilities.
For Market Incumbents: Extend technical service bundling deeper into customer R&D pipelines to lock out commodity competitors from bakery reformulation accounts. Defend against enzymatic technology diffusion by acquiring immobilized lipase system capabilities or exclusive licensing arrangements with European enzyme suppliers. Prioritize RSPO and MSPO certification acquisition to filter qualified supplier pools for sustainability-screened multinational accounts.
For New Entrants and Emerging Players: Capture white space in Indian organized bakery chains where FSSAI packaging regulations and BIS quality benchmarks create structured entry pathways for imported specialty fats. Target quick-service restaurant fryer operations in Maharashtra and Karnataka through regional distributor partnerships that warehouse climate-stabilized shortening blends. Lead with oxidative stability guarantees and filtration compatibility rather than price competition against established palm refiners.
For Investors and Strategic Acquirers: Integrated agribusiness conglomerates with captive plantation-to-port infrastructure are the most active acquirers in this space, seeking to consolidate upstream control over fractionation capacity. Long-term viability hinges on exposure to enzymatic processing technology and sustainability certification depth rather than commodity refining scale alone. Watch for 3-MCPD ester regulatory tightening in Europe as the signal indicating accelerated capital deployment toward modified deodorization protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Scale-Up | Immobilized lipase systems displace chemical processing for clean-label bakery applications in North America. |
| Dual-Refining Train Investment | German and Dutch refiners segregate high-purity output streams to meet EFSA's tightening 3-MCPD specifications. |
| RSPO Certification Acquisition | Sustainability documentation becomes table stakes for European and North American multinational food manufacturer accounts. |
| Regional Blending Facility Expansion | Midwest and Southeast U.S. locations shorten lead times for enzymatically processed bakery shortenings. |
| Plant-Based Meat Analogue Partnership | Fat structuring technologies migrate from bakery plasticity into alternative protein mouthfeel applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with oil refinery process engineers, bakery procurement directors, foodservice distributor category managers, and enzymatic technology suppliers with secondary validation. Primary fieldwork centered on Southeast Asian integrated refiner operations, North American bakery manufacturing facilities, and European confectionery formulation labs. Secondary sources included FDA GRAS determination filings, EFSA scientific opinions on 3-MCPD esters, FSSAI packaging regulation updates, Malaysian Palm Oil Board production statistics, and customs trade data for fractionated palm oil movements. Bottom-up volume modeling triangulated against top-down market sizing from refining capacity utilization rates.
Historical reference periods anchored the forecast window to pre- and post-PHO removal mandate demand shifts, with projection horizons extending through regulatory compliance cycle completion. The analytical framework modeled segmentation dimensions spanning processing method, application performance tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume trajectories incorporating substitution rates from hydrogenated to non-hydrogenated formulations. Industry-specific inputs included Malaysian ringgit volatility patterns, El Niño Southern Oscillation indices affecting crude palm oil yields, and enzymatic processing capacity buildout announcements.
Crude palm oil price volatility, regulatory purity specification evolution, and sustainability certification scheme fragmentation are the dominant revision risks to modeled outputs. Forecasts embed assumptions regarding fractionation technology diffusion rates and bakery equipment retrofit timelines that material variance could invalidate. A model refresh is warranted upon material change in FDA enforcement posture or EFSA 3-MCPD limit finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Aromatherapy Oils Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Madecassoside Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Specialty Meat Ingredients Market
Specialty Ingredients
Global Fruit and Vegetable Powder Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Specialty Ingredients Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Aromatherapy Carrier Oil Market