
 Roasted Grain Ingredients Market | 2026-2036
Roasted Grain Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Roasted Grain Ingredients Market Analysis
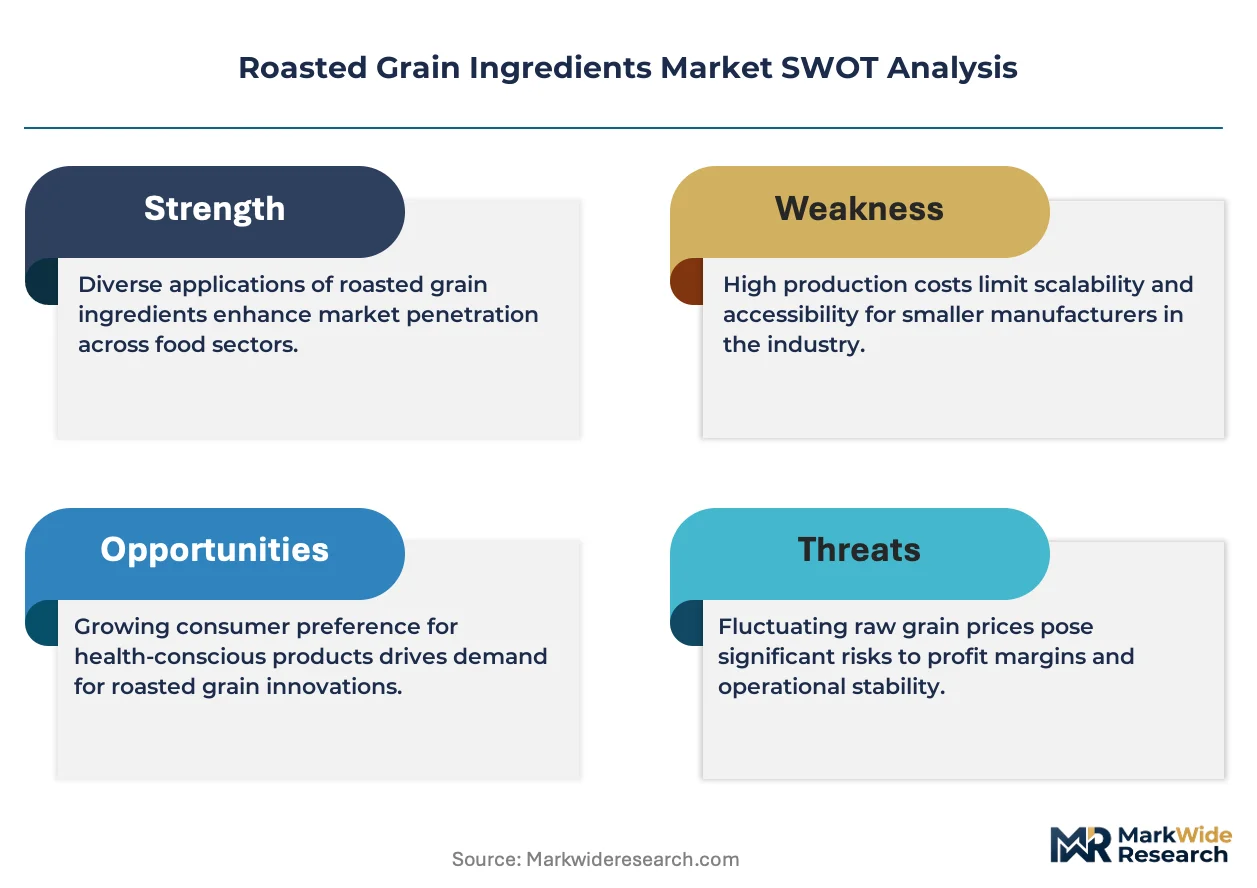
Ingredient customization revenue is tilting toward specialty roasted profiles as brewers and bakers seek differentiated flavor signatures. Cargill leverages its global grain sourcing infrastructure to secure consistent supply of premium roasted varieties across multiple continents. Briess Malt & Ingredients Co. anchors its position through deep specialization in small-batch roasted formulations for craft beverage clients. Muntons Malted Ingredients Inc. competes on technical service intensity, embedding application scientists directly into customer R&D workflows.
Roasted grain ingredients are cereal grains subjected to controlled thermal treatment, typically at temperatures between 120°C and 230°C, to develop Maillard-reaction color, aroma, and enzymatic modification for food and beverage applications. The process reduces moisture content to below 5% while generating melanoidins that contribute bitterness, sweetness, or toasted notes depending on time-temperature profiles. Roasted barley maintains dominant volume share in beverage applications due to entrenched brewing protocols, though roasted oats are gaining fastest in bakery products where fiber positioning and texture modification command premium placement. Powdered forms capture the deepest margin pools through integration into dry-mix manufacturing and instant beverage formulations, while whole grain formats remain constrained by shorter shelf stability and higher logistics costs.
FDA food safety modernization requirements and EU REACH chemical compliance frameworks shape ingredient specifications for cross-border trade in roasted grain derivatives. BIS standards in India and GB standards in China add layer complexity for suppliers seeking multi-territory certification. Stakeholders must monitor evolving mycotoxin thresholds and carbon-footprint disclosure mandates that will increasingly determine supplier qualification and contract renewal terms.
Market Dynamics
Clean-label mandates from EFSA and FDA are compressing formulation cycles as manufacturers reformulate around minimally processed roasted grain derivatives with full supply chain traceability.
Growth Catalysts
- EU Green Deal carbon-footprint mandates:Roasted grain processors investing in renewable thermal energy systems gain preferential supplier status with multinational food manufacturers seeking Scope 3 reductions.
- Craft brewing expansion:Specialty malt houses in Germany and the Czech Republic are scaling small-batch roasting capacity to serve independent breweries demanding terroir-specific flavor profiles.
- Maillard-reaction optimization:Advanced process control systems now enable precise melanoidin targeting, allowing bakers to replace artificial colorants with naturally roasted wheat and oat derivatives.
Market Restraints
- Barley supply concentration:Premium malting barley production clusters in France, Germany, and Australia, exposing processors to weather-driven harvest volatility and freight cost spikes.
- REACH chemical compliance:ECHA's evolving substance restrictions force reformulation of certain roasted grain extracts used in flavoring applications, extending R&D timelines by 12-18 months.
- Enzymatic activity degradation:High-temperature roasting above 200°C permanently denatures diastatic enzymes, limiting functional applications in certain fermentation-dependent food systems.
Strategic Opportunities
- India FSSAI clean-label acceleration:Urban packaged food brands in Mumbai and Bangalore are importing roasted quinoa and amaranth ingredients to differentiate premium snack lines.
- Precision fermentation convergence:Roasted grain hydrolysates are emerging as preferred carbon sources for cell-cultured protein production, opening industrial biotechnology channels.
- Direct-to-brewery distribution:Regional roasting facilities are bypassing traditional malt distribution networks to establish captive supply relationships with craft beverage clusters.
Industry Challenges
- Roastmaster skill scarcity:Experienced operators capable of executing complex time-temperature profiles for specialty applications command premium wages and limited geographic mobility.
- Multi-territory certification stacking:Simultaneous compliance with FDA food safety modernization, EU REACH, and BIS standards requires dedicated regulatory affairs headcount that mid-scale processors struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roasted Grain Ingredients Market |
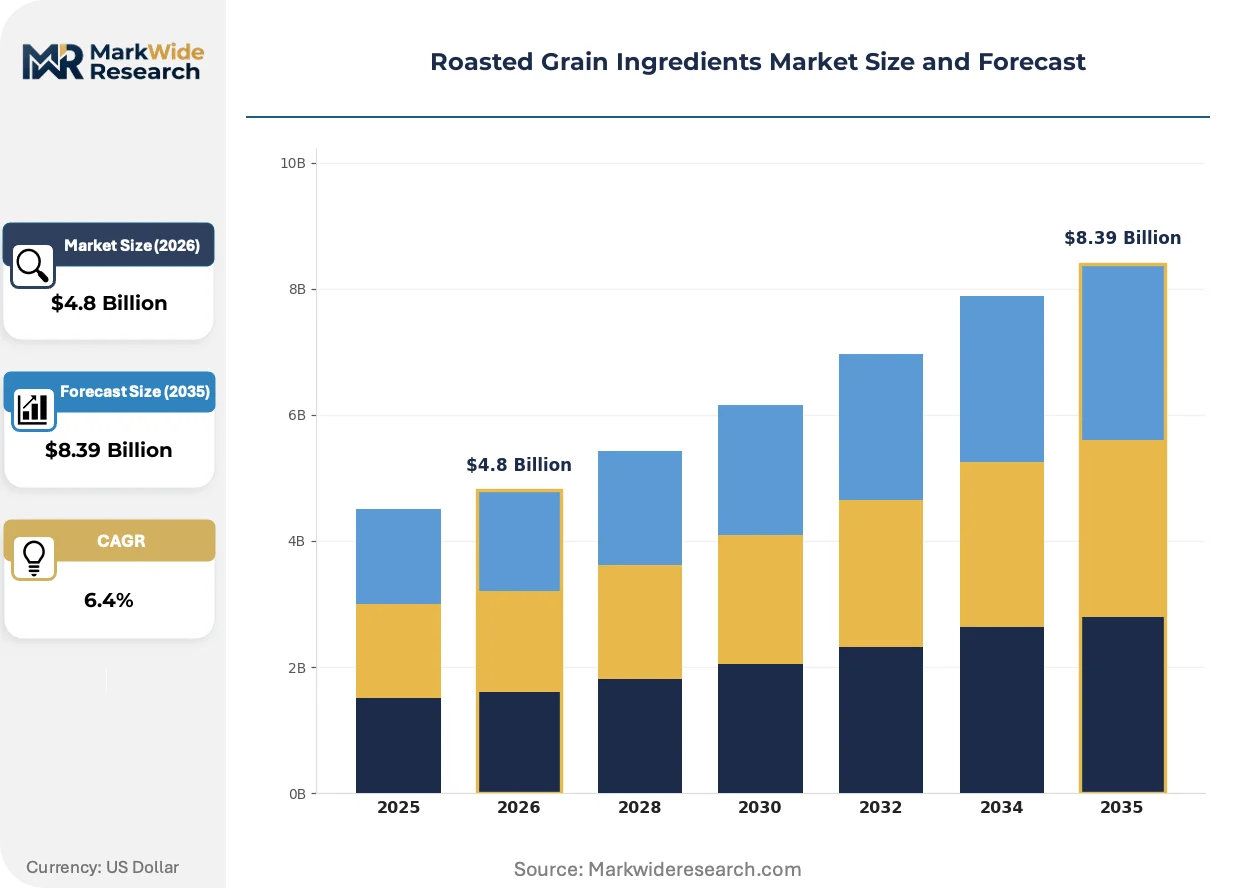
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roasted Barley, Roasted Wheat, Roasted Oats, Roasted Rye Application: Beverages, Bakery Products, Snack Foods, Confectionery End User: Food Manufacturers, Beverage Companies, Retailers, Restaurants Form: Powdered, Flaked, Whole Grain, Extracts |
| Companies Covered | Cargill, Boortmalt, Briess Malt & Ingredients Co., Rahr Malting Company, Malteurop Group, Muntons Malted Ingredients Inc., SunOpta Inc., Castle Malting S.A., Palatia Malz GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roasted Grain Ingredients Market Emerging Trajectories
Thermal processing intelligence and sustainability verification systems are reconfiguring how roasted grain specifications are negotiated between ingredient suppliers and their manufacturing customers.
Electromagnetic roasting technology is migrating from conventional gas-fired drum systems to precision-controlled infrared and microwave platforms that reduce energy intensity by enabling selective volumetric heating. Specialty coffee and craft chocolate producers are piloting these systems for grain applications, attracted by batch-to-batch consistency. This migration from conduction-dominated to radiative heating is compressing the traditional equipment supply base while opening service contracts for thermal process engineering firms.
REACH chemical compliance frameworks in Europe are forcing disclosure of all processing aids and surface treatments used in roasted grain production, with ECHA's SCIP database requiring traceability down to the farm gate. Manufacturers exporting to the EU must now document moisture-reduction agents and anti-caking coatings. The bakery and infant nutrition segments are responding fastest, reformulating around certified additive-free roasted oat and rice ingredients to preempt regulatory rejection.
Buyer concentration among multinational food manufacturers is consolidating procurement decisions into centralized technical sourcing teams that specify roasted grain attributes at the molecular level. Regional roasting cooperatives that previously sold commodity grades are now embedding application scientists to translate R&D requirements into custom thermal profiles. This pattern is most pronounced in Germany, where traditional malting houses compete for technical service contracts with global bakery and beverage conglomerates.
Roasted Grain Ingredients Market Segmentation
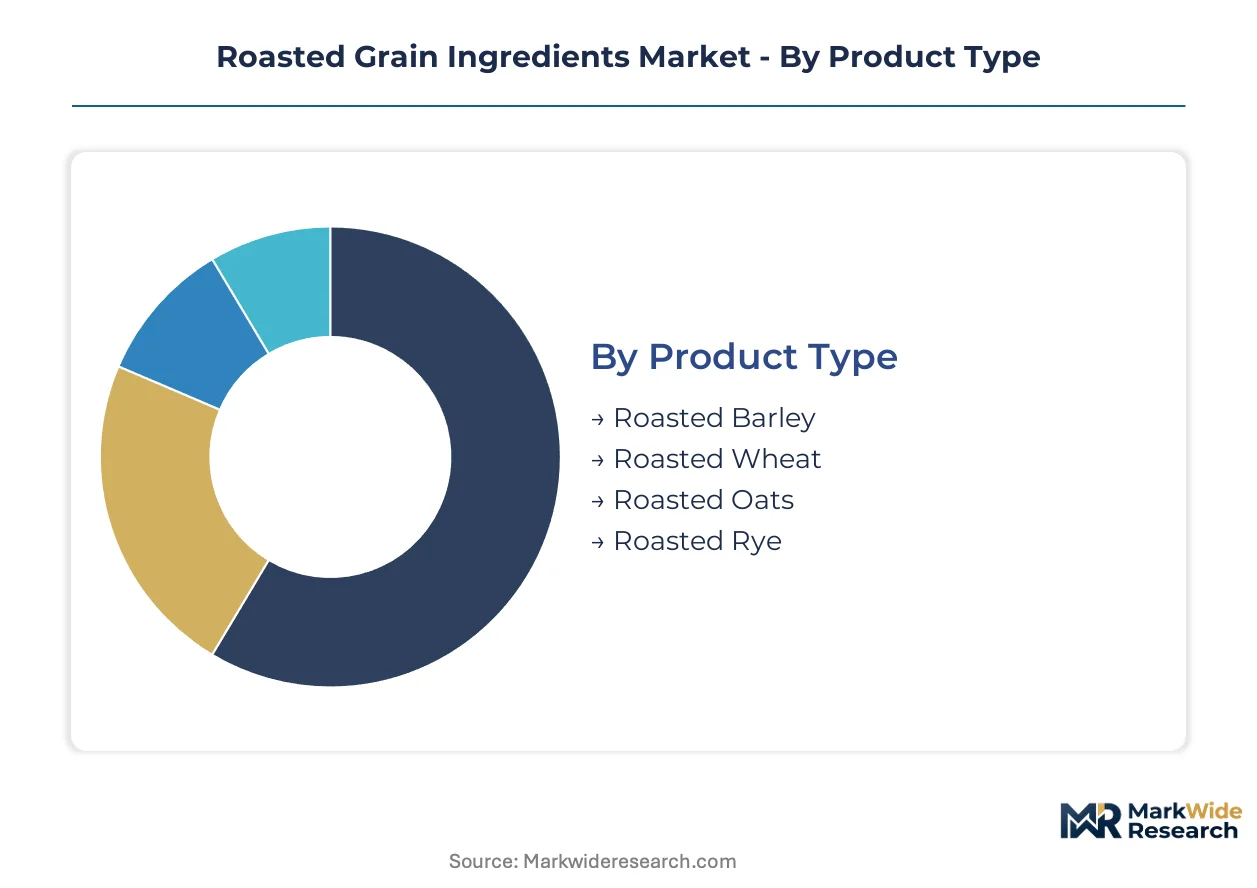
Roasted grain ingredient suppliers configure production lines around distinct thermal profiles and particle specifications demanded by beverage brewers, industrial bakeries, and snack formulators. Segmentation clarity enables processors to align roasting capacity with margin-differentiated applications.
Product Type:
The use-case spectrum spans enzymatically active brewing adjuncts through fiber-forward bakery inputs, each requiring calibrated Maillard intensity and moisture targets.
- Roasted Barley:High-temperature kilning between 180°C and 230°C generates melanoidin-rich colorants and bitter-sweet flavor compounds for stout and porter brewing protocols. Demand concentrates in Germany and the Czech Republic, where craft malt houses supply independent breweries seeking terroir-specific roast signatures.
- Roasted Wheat:Controlled roasting at 140°C to 180°C preserves partial enzymatic activity while developing golden-brown hues for premium bread and pastry applications. French and Belgian industrial bakeries are procuring specialty wheat roasts to replace artificial caramel colorants under EFSA clean-label pressure.
- Roasted Oats:Lower-temperature profiles retain beta-glucan fiber content for functional positioning in granola bars and infant nutrition.
- Roasted Rye:Intense roasting produces characteristic spicy-bitter notes for traditional Eastern European bread styles and specialty distilled spirits.
The dominant share belongs to Roasted Barley, while Roasted Oats is closing the gap fastest.
Application:
Cost tier differentiation separates commodity beverage inputs from premium bakery and confectionery grades commanding technical service premiums.
- Beverages:Brewing applications specify precise Lovibond color ratings and diastatic power measurements for mash efficiency. German craft breweries are contracting directly with regional roasting facilities to bypass traditional malt distribution networks.
- Bakery Products:Industrial bread and pastry manufacturers require consistent granulation and moisture specifications for automated dough handling. ECHA REACH disclosure mandates are accelerating reformulation toward certified additive-free roasted grain derivatives.
- Snack Foods:Extruded and puffed applications leverage roasted grain powders for flavor adhesion and browning control.
- Confectionery:Chocolate and compound coating producers use roasted grain extracts for bitter counter-notes and textural inclusions.
Beverages command the largest volume position, though Bakery Products is expanding most quickly as clean-label mandates compress formulation cycles.
End User:
Customer type fragmentation creates divergent procurement patterns between centralized technical sourcing teams and distributed craft operators.
- Food Manufacturers:Multinational bakery and cereal conglomerates specify roasted grain attributes at molecular levels, embedding application scientists into supplier qualification. Procurement decisions are consolidating into centralized technical sourcing functions.
- Beverage Companies:Craft breweries and specialty distillers demand small-batch consistency with full farm-gate traceability. India FSSAI clean-label acceleration is driving urban packaged food brands to import roasted quinoa and amaranth for premium snack differentiation.
- Retailers:Private-label programs require cost-optimized roasted grain inputs with basic organic or non-GMO certification.
- Restaurants:Chef-driven procurement seeks distinctive roast profiles for menu differentiation in high-traffic urban clusters.
Food Manufacturers retain the deepest volume share, while Beverage Companies are gaining procurement influence fastest through direct-to-roaster contracting.
Form:
Margin concentration favors processed formats with extended shelf stability and logistics efficiency over whole grain alternatives.
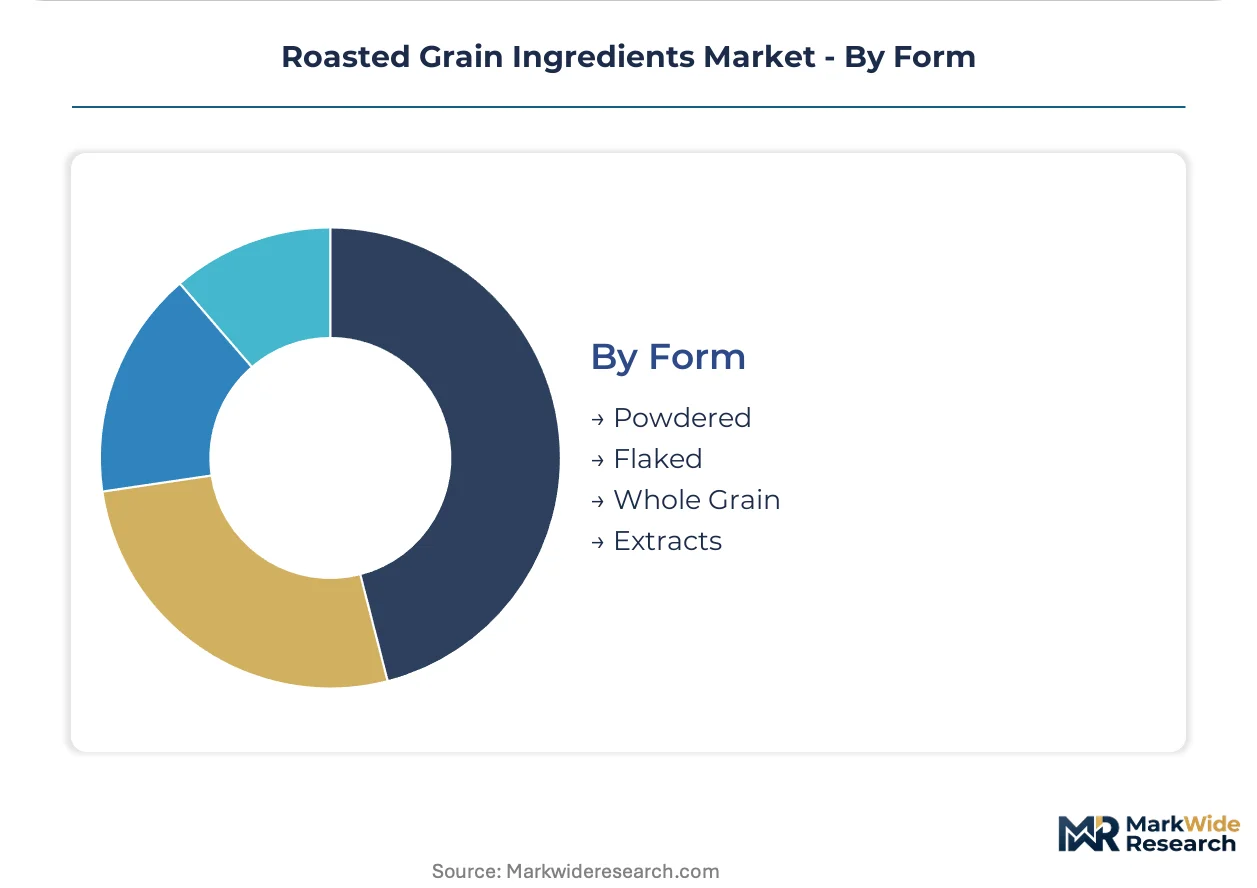
- Powdered:Fine-milled roasted grains integrate into dry-mix manufacturing, instant beverage formulations, and extrusion systems. Powdered formats capture the deepest margin pools through bulk handling efficiency and year-round stability.
- Flaked:Rolled and toasted grain flakes serve hot cereal and granola applications requiring rapid hydration.
- Whole Grain:Intact roasted kernels deliver visual authenticity and texture contrast in artisan bread and specialty brewing. Whole grain formats face constraints from moisture sensitivity and higher freight costs.
- Extracts:Concentrated soluble compounds enable precise flavor dosing in beverage and confectionery systems.
Powdered forms dominate value capture, while Extracts is climbing the fastest as precision formulation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Czech Republic exhibit the lowest price elasticity, paying premiums for terroir-specific roast signatures, while procurement teams in India and Brazil prioritize cost-optimized inputs for mass-market formulations. This demand-elasticity contrast shapes supplier investment patterns across continents.
Germany
Craft breweries in Bavaria and North Rhine-Westphalia contract directly with regional malt houses for small-batch roasted barley with documented provenance. ECHA's REACH chemical compliance frameworks force disclosure of all processing aids used in thermal treatment. The Bamberg-Forchheim brewing corridor anchors specialty roasting capacity expansion as independent breweries bypass traditional distribution networks.
United States
Industrial bakeries in the Midwest reformulate around clean-label roasted wheat derivatives to replace artificial caramel colorants under FDA food safety modernization requirements. The FDA's evolving mycotoxin thresholds determine supplier qualification for cross-border grain ingredient trade. Minneapolis-St. Paul hosts concentrated procurement teams from multinational cereal manufacturers specifying molecular-level roasted grain attributes.
India
Urban packaged food brands in Mumbai and Bangalore import roasted quinoa and amaranth ingredients to differentiate premium snack lines under FSSAI clean-label acceleration. BIS standards add certification complexity for suppliers seeking multi-territory market access. The Maharashtra-Gujarat industrial corridor attracts regional roasting facilities serving domestic bakery and beverage conglomerates.
China
Precision fermentation startups in the Yangtze River Delta procure roasted grain hydrolysates as preferred carbon sources for cell-cultured protein production. GB standards govern food safety specifications for thermal-processed grain derivatives in domestic and export channels. Shanghai's biotechnology cluster drives demand for certified-organic roasted oat inputs in infant nutrition formulations.
Czech Republic
Traditional malting houses in South Moravia scale small-batch roasting capacity to serve independent breweries demanding heritage barley varieties with controlled Maillard intensity. EU Green Deal carbon-footprint mandates favor processors investing in renewable thermal energy systems. The Plzeň brewing region maintains entrenched procurement relationships with regional roastmasters executing complex time-temperature profiles.
Roasted Grain Ingredients Market Vendor Landscape
Multinational grain processors and specialized malt houses split the market between scale-driven commodity supply and technical-service-intensive custom formulations. The vendor base concentrates around three strategic archetypes: global agricultural conglomerates with integrated sourcing infrastructure, regional malting specialists with deep brewing protocol expertise, and application-science-focused ingredient engineers embedding directly into customer R&D workflows. Dominant competitive moves include backward integration into premium barley procurement networks and geographic expansion of small-batch roasting capacity near craft beverage clusters.
Within the specialized malt house tier, Briess Malt & Ingredients Co. and Muntons Malted Ingredients Inc. exemplify technical-service-intensive positioning, while Cargill anchors the scale-driven commodity vector. These three entities represent divergent approaches to customer intimacy: Briess occupies a position defined by small-batch formulation specialization, Muntons sits within the application-scientist-embedded workflow archetype, and Cargill exemplifies global sourcing infrastructure leverage. Regional specialists including Castle Malting S.A. and Palatia Malz GmbH demonstrate how geographic concentration near traditional brewing cultures translates into supplier qualification advantages for terroir-specific procurement.
| Leading Market Players |
|---|
| Cargill |
| Boortmalt |
| Briess Malt & Ingredients Co. |
| Rahr Malting Company |
| Malteurop Group |
| Muntons Malted Ingredients Inc. |
| SunOpta Inc. |
| Castle Malting S.A. |
| Palatia Malz GmbH |
| Others |
Supply Flow & Price Mechanics
The Hamburg-Rotterdam barge corridor anchors grain ingredient logistics costs for European processors, with freight rate volatility amplifying price spreads between premium malting barley from France and standard feed-grade alternatives. This corridor's cost dynamics concentrate procurement power among malt houses with captive riverine storage, while downstream price differentiation separates craft breweries paying terroir premiums from mass-market bakers sourcing commodity roasted wheat derivatives.
Pricing Analysis
Technical service contracts and extended formulation support drive lifetime value for specialty roasted grain suppliers. Three-tier pricing structure across premium, standard, and economy levels separates certified organic heirloom varieties from conventional commodity grades, with EFSA clean-label certification commanding measurable premiums. Cost compression in economy-tier roasted barley intensifies because Australian harvest volatility exposes processors to spot-market spikes. Industrial bakeries in the Midwest exhibit highest price sensitivity, while German craft breweries demonstrate lowest elasticity for documented-provenance inputs.
Supply Chain Analysis
Regional malting specialists in Germany, the Czech Republic, and Belgium hold contracted roasting capacity for premium beverage applications. Premium malting barley supply draws from France, Germany, and Australia, with processors sourcing renewable thermal energy systems and precision moisture-reduction equipment. Single-source vulnerability concentrates in Australian premium barley exports exposed to El Niño-driven harvest shortfalls. Distribution runs through traditional malt distribution networks, though direct-to-brewery contracting is displacing intermediaries in craft beverage clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roasted grain ingredient suppliers face substitution pressure from precision-fermentation-derived flavor compounds and synthetic melanoidin alternatives, requiring incumbents to defend through irreplaceable technical service depth and provenance verification systems.
For Market Incumbents: Insulate specialty roasting expertise through captive roastmaster training programs and documented time-temperature intellectual property. Backward integration into heritage barley procurement networks in Germany and the Czech Republic secures terroir-specific inputs that precision fermentation cannot replicate. ECHA REACH disclosure mandates favor processors with pre-certified additive-free production lines, creating regulatory moats against commodity competitors. For New Entrants and Emerging Players: Mid-scale regional roasting facilities serving underserved craft beverage clusters in India and Brazil represent the most penetrable entry point, bypassing entrenched malt distribution networks. Precision fermentation carbon-source supply contracts with Yangtze River Delta biotechnology startups offer an alternative channel with lower capital intensity than beverage-grade malting. Direct technical embedding with bakery R&D teams in Mumbai and Bangalore accelerates qualification timelines versus traditional distributor-led approaches. For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural conglomerates divesting non-core specialty malt divisions lacking technical service infrastructure. Long-term viability hinges on whether roasted grain hydrolysates maintain preferred carbon-source status against sugar-feedstock alternatives in cell-cultured protein production. Watch EFSA mycotoxin threshold revisions as an inflection signal that could disqualify commodity suppliers and consolidate share toward certified-clean processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heritage Barley Procurement | Cargill's sourcing infrastructure demonstrates how farm-gate control secures terroir-specific inputs for premium roasting contracts. |
| Renewable Thermal Energy System Investment | EU Green Deal carbon-footprint mandates reward processors with Scope 3 reductions, unlocking preferential supplier status with multinational food manufacturers. |
| Application Scientist Embedding Program | Muntons Malted Ingredients Inc. validates that direct R&D workflow integration commands technical service premiums from industrial bakery customers. |
| Direct-to-Brewery Distribution Bypass | The Bamberg-Forchheim brewing corridor shows how regional roasting facilities capture margin pools previously absorbed by traditional malt distributors. |
| Precision Fermentation Carbon-Source Qualification | Roasted grain hydrolysate positioning in Shanghai's biotechnology cluster opens industrial biotechnology channels beyond conventional food and beverage applications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary research phases, with malt house operations directors, craft brewery procurement leads, industrial bakery R&D scientists, and specialty grain traders contributing qualitative inputs. Secondary validation drew from ECHA SCIP database disclosures, FDA food safety modernization guidance documents, EU customs trade statistics for roasted grain derivatives, and FSSAI clean-label regulatory circulars. Bottom-up volume modeling from individual facility capacity and top-down demand segmentation from end-use consumption patterns were triangulated to constrain estimate ranges.
Calibration against historical price realizations for premium malting barley and roasted wheat derivatives anchored projection trajectories across the analysis window. Segmentation dimensions modeled include thermal intensity tier, particle specification, organic certification status, and regional regulatory cluster complexity. CAGRs were derived from slope-constrained growth curves fitted to documented capacity expansion announcements and procurement contract tenors. Industry-specific forecast inputs incorporated craft brewery formation rates in Germany and precision fermentation facility commissioning timelines in China.
Stress conditions across Australian barley harvest yields, EU natural gas pricing for thermal processing energy, and EFSA additive disclosure stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding clean-label mandate enforcement timelines and craft beverage demand elasticity. Quarterly review of ECHA substance restriction proposals and FSSAI import certification changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Sunflower Oil Market
Ingredients
South America Spirulina Extract Market
Ingredients
Mastic Gum Market
Ingredients
Arachidonic Acid Market
Ingredients
Arrowroot Starch Market
Ingredients
South America Malt Ingredient Market
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Corn Gluten Meal Market
Ingredients
Salt Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
Halal Ingredients Market
Ingredients
Fish Gelatin Market
Ingredients
Sodium Reduction Ingredients Market