
 Psyllium Husk Powder Market | 2026-2036
Psyllium Husk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Psyllium Husk Powder Market Insights
The capital-intensity gap between integrated processors and trading-only intermediaries is collapsing as solvent-extraction and milling automation become standard. NOW Foods leverages backward integration into seed sourcing to sustain margin control across volatile harvest cycles. Patanjali Ayurved Limited anchors its dominance through Ayurvedic brand equity and captive distribution through its own retail network. Satnam Psyllium Industries competes on pharmaceutical-grade certification, occupying a niche that commands premium positioning in export markets.
Psyllium husk powder consists of the epidermis and collapsed adjacent layers from Plantago ovata seeds, containing approximately 85% dietary fiber with exceptional water-holding capacity exceeding 10 times its weight. Industrial processing involves mechanical milling, gravity separation, and sieving to achieve pharmacopeial grades for laxative and cholesterol-lowering applications. Powder formulations lead volume consumption due to versatility across beverage and bakery applications, while capsules represent the fastest-growing segment as convenience-seeking consumers shift from bulk mixing. Dietary supplements command the deepest margin pools, whereas food additive applications are maturing with commoditization in mass-market cereals.
The FDA regulates psyllium husk as a dietary supplement under DSHEA and as an authorized health claim ingredient for coronary heart disease risk reduction, while FSSAI mandates microbial and heavy metal limits for Indian export consignments. USDA organic certification and India's APEDA export protocols jointly determine market access for premium-tier suppliers. Stakeholders must monitor evolving fiber-specific labeling requirements in target jurisdictions and assess whether captive farming investments outweigh contract-sourcing flexibility as climate volatility intensifies.
Market Dynamics
India's FSSAI purity mandates and FDA health-claim authorizations are squeezing unqualified processors while concentrating export-grade supply among certified operators who control captive farming networks in Gujarat and Rajasthan.
Growth Catalysts
- Coronary health claim authorization:The FDA's approved health claim for psyllium's cholesterol-lowering properties drives pharmaceutical and functional food formulation demand across US dietary supplement channels.
- Gut microbiome research acceleration:Clinical validation of soluble fiber's prebiotic effects expands psyllium incorporation into synbiotic and digestive wellness products by nutraceutical manufacturers.
- Contract farming densification:Processor-led cultivation agreements in Gujarat's Mehsana and Patan districts secure seed supply quality and traceability for export-grade husk production.
Market Restraints
- Monsoon-dependent raw material volatility:Plantago ovata cultivation requires specific rainfall windows; erratic precipitation patterns in Rajasthan's Barmer and Jalore districts create harvest quantity uncertainty.
- Pharmacopeial compliance cost escalation:USP-NF and EP certification requirements for microbial limits, heavy metals, and pesticide residues impose testing burdens that eliminate small-scale traders from premium segments.
- Synthetic fiber substitution threat:Methylcellulose and polycarbophil alternatives in laxative formulations compete on dosing convenience and taste masking in pharmaceutical applications.
Strategic Opportunities
- Organic certification penetration:USDA organic and India Organic standards unlock price premiums in European natural products channels where clean-label positioning commands shelf placement priority.
- Ready-to-mix beverage formats:Single-serve sachets and flavored instant drink powders address convenience gaps among urban professionals in German and UK functional food markets.
- APEDA export protocol alignment:India's Agricultural and Processed Food Products Export Development Authority quality benchmarks create pathway for integrated processors to bypass intermediary markups in direct-to-manufacturer relationships.
Industry Challenges
- Skilled milling technician scarcity:Precision gravity separation and sieving operations require experienced operators; Gujarat's processing clusters face labor competition from higher-wage manufacturing sectors.
- Integrated facility capex requirements:Solvent-extraction and automated milling lines demand capital deployment that exceeds trading-only intermediary balance sheet capacity, forcing exit or acquisition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Psyllium Husk Powder Market |
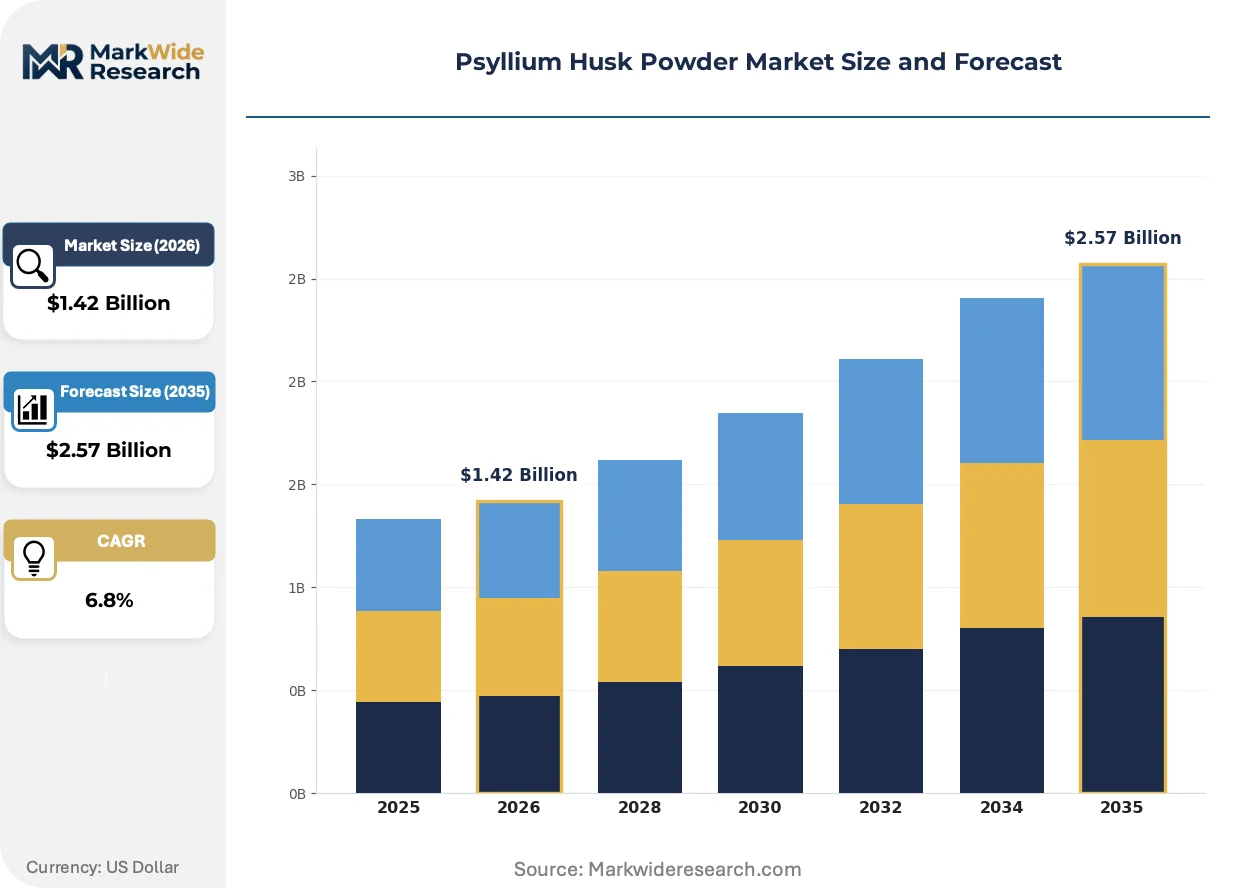
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Capsules, Tablets Application: Dietary Supplements, Food Additives, Pharmaceuticals, Animal Feed End User: Retail, Healthcare Providers, Food Manufacturers, Pet Industry Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | NOW Foods, Patanjali Ayurved Limited, Satnam Psyllium Industries, Altrafine Gums, JYOT Overseas Pvt. Ltd., Organic India, Keyur Industries, Yerba Prima, Konsyl Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Psyllium Husk Powder Market Trends and Innovations
Processing automation and regulatory tightening are compressing the supplier base while convenience-oriented delivery formats reshape downstream demand patterns across pharmaceutical and food additive segments.
Advanced optical sorting and near-infrared seed composition analyzers are miniaturizing quality control from laboratory settings onto processing floors. Integrated operators in Gujarat deploy these systems to segregate seed lots by mucilage content before milling, compressing batch-to-batch variation and reducing pharmacopeial rejection rates. This capability is enabling real-time contract pricing tied to verified fiber potency rather than commodity-grade assumptions.
The EU's evolving Novel Food catalog updates and fiber-specific nutrition labeling requirements under EFSA guidance are reshaping import documentation burdens. Manufacturers targeting European markets must demonstrate compliance with tightened heavy metal thresholds and allergen cross-contamination protocols. Dietary supplement distributors in Germany and the Netherlands are responding by consolidating supplier relationships toward vertically integrated Indian processors with established EU representation.
Buyer concentration among direct-to-consumer wellness brands is compressing traditional distribution hierarchies. E-commerce-first supplement companies in the US and UK are sourcing psyllium directly from certified processors, bypassing ingredient distributors who previously aggregated small orders. This disintermediation is most visible in capsule and gummy format launches where brands prioritize supply chain storytelling and batch traceability over distributor inventory convenience.
Psyllium Husk Powder Market Segmentation
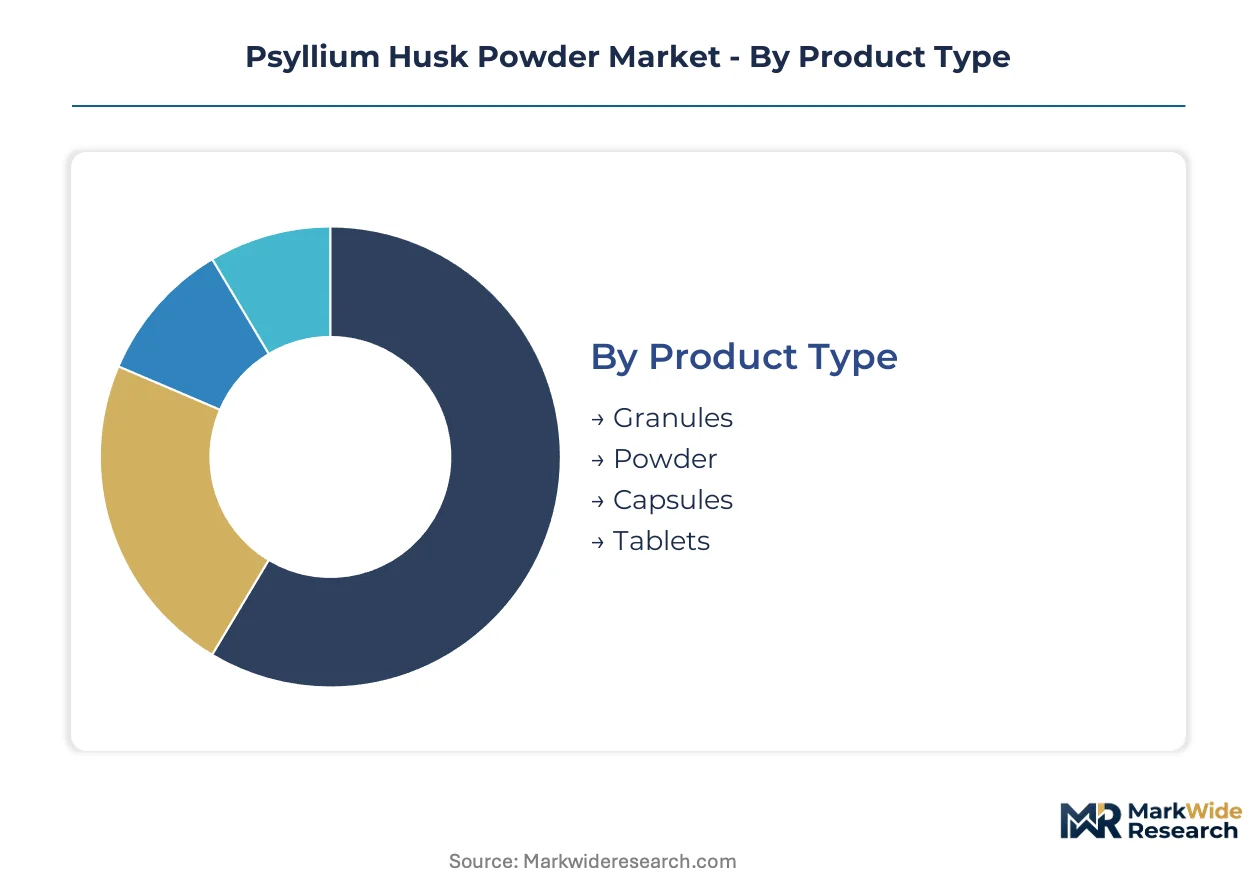
Psyllium husk powder's commercial structure fragments across four distinct dimensions, each mapping to different margin pools and regulatory exposure. Product format determines processing capital intensity, while application verticals dictate certification requirements and customer concentration.
Product Type:
Export-grade production concentrates in powder and granule formats serving pharmaceutical and food additive channels, whereas domestic Indian consumption favors capsules and tablets through Ayurvedic distribution networks.
- Powder:Mechanical milling of Plantago ovata seed epidermis yields approximately 85% dietary fiber content with water-holding capacity exceeding ten times dry weight. Demand concentrates in North American functional food manufacturing, where FDA-authorized coronary health claims drive bulk procurement by beverage and bakery formulators. Gujarat's integrated processors control supply through captive farming networks in Mehsana and Patan districts.
- Capsules:Pre-measured gelatin or vegetable-cellulose shells address convenience gaps among urban professionals seeking portable digestive wellness solutions. German and UK direct-to-consumer wellness brands source directly from APEDA-certified Indian processors, bypassing traditional ingredient distributors to secure batch traceability for e-commerce storytelling.
- Granules:Coarser particle size retains mucilage potency for pharmaceutical-grade laxative formulations requiring controlled dissolution rates.
- Tablets:Compressed formats dominate Indian Ayurvedic retail through Patanjali's captive distribution network and traditional pharmacy channels.
Powder commands the established base. The steepest expansion runs through capsules.
Application:
Margin stratification separates premium-certified pharmaceutical grades from commoditizing food additive volumes, with dietary supplements occupying intermediate positioning.
- Dietary Supplements:DSHEA-regulated positioning in US channels leverages FDA cholesterol-lowering health claims to command price premiums over generic fiber alternatives. NOW Foods anchors this segment through backward integration into seed sourcing.
- Food Additives:Mass-market cereal and bakery applications face commoditization as synthetic fiber alternatives compete on cost and processing convenience.
- Pharmaceuticals:USP-NF and EP certification requirements for microbial limits, heavy metals, and pesticide residues concentrate supply among Satnam Psyllium Industries and comparable certified operators.
- Animal Feed:Equine digestive health applications in US and European markets represent emerging volume with lower regulatory burden than human-grade channels.
Pharmaceuticals capture the deepest margin pools. Dietary supplements are climbing the fastest.
End User:
Procurement patterns diverge between concentrated institutional buyers demanding pharmacopeial documentation and fragmented retail channels prioritizing brand recognition.
- Retail:Direct-to-consumer wellness brands in US and UK e-commerce channels consolidate supplier relationships toward vertically integrated Indian processors with established EU representation and organic certification.
- Healthcare Providers:Clinical recommendation of psyllium for irritable bowel syndrome and hypercholesterolemia management drives prescription-adjacent sales through pharmacy networks.
- Food Manufacturers:German and Dutch functional food companies require EFSA-aligned import documentation demonstrating compliance with tightened heavy metal thresholds.
- Pet Industry:Equine supplement formulators represent specialized demand with distinct microbiological specifications from human-grade standards.
Food manufacturers anchor procurement volume. Retail channels are expanding most quickly.
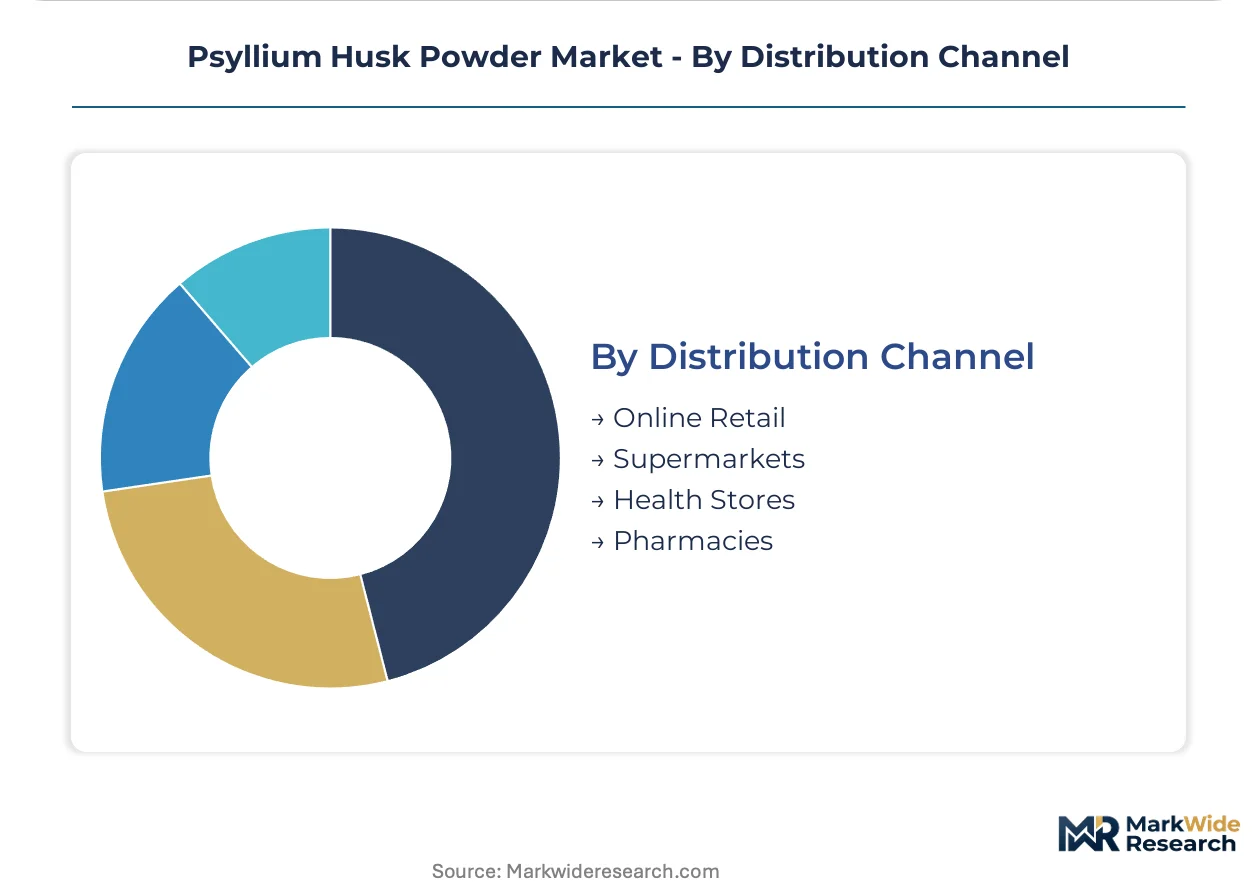
Distribution Channel:
Channel structure reflects buyer concentration trends, with disintermediation compressing traditional distributor hierarchies.
- Online Retail:E-commerce-first supplement companies source psyllium directly from certified processors, prioritizing supply chain storytelling over distributor inventory convenience.
- Supermarkets:Mass-market placement requires price competitiveness that favors commodity-grade powder from trading intermediaries rather than certified operators.
- Health Stores:Natural products channels in Europe prioritize USDA organic and India Organic certification for clean-label positioning.
- Pharmacies:OTC laxative and cholesterol-management positioning depends on USP-NF compliance and FDA health claim authorization visibility.
Pharmacies retain the established prescription-adjacent base. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gujarat's integrated processing clusters while German and US buyers extract traceability premiums through direct procurement relationships that bypass traditional trading hierarchies.
United States
FDA's authorized coronary health claim drives pharmaceutical and supplement channel demand through NOW Foods and Konsyl Pharmaceuticals distribution networks. DSHEA regulatory framework mandates adverse event reporting and good manufacturing practice compliance for domestic formulators. Chicago and New Jersey logistics hubs consolidate import volumes from APEDA-certified Indian processors for redistribution across North American dietary supplement manufacturing.
Germany
EFSA-aligned fiber nutrition labeling and tightened heavy metal thresholds reshape import documentation burdens for functional food manufacturers. BfR (Federal Institute for Risk Assessment) guidance on botanical ingredient safety influences downstream formulation decisions across Düsseldorf and Hamburg natural products channels. Bavarian and Baden-Württemberg wellness brands consolidate supplier relationships toward vertically integrated Indian processors with established EU organic certification.
India
FSSAI purity mandates and microbial limit enforcement concentrate export-grade supply among certified operators controlling captive farming networks. APEDA export protocols determine market access for premium-tier suppliers targeting European and North American pharmaceutical channels. Mehsana and Patan districts in Gujarat anchor seed processing gravity through processor-led contract farming agreements securing traceable supply for USP-NF certification.
United Kingdom
Direct-to-consumer wellness brands in London and Manchester e-commerce channels source psyllium directly from certified processors, prioritizing batch traceability for supply chain storytelling. FSA (Food Standards Agency) novel food consultations and post-Brexit retained EU law create regulatory continuity for EFSA-aligned fiber claims. UK capsule and gummy format launches disintermediate traditional ingredient distributors who previously aggregated small orders.
Netherlands
Rotterdam and Amsterdam natural products distributors consolidate procurement from India Organic and USDA-certified processors for redistribution across Benelux and Nordic markets. NVWA (Netherlands Food and Consumer Product Safety Authority) enforcement of EU food additive regulations shapes import inspection protocols for psyllium husk powder entering European food manufacturing channels. Dutch functional food companies require demonstrated compliance with EFSA heavy metal thresholds and allergen cross-contamination protocols.
Psyllium Husk Powder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated processors with automated milling and optical sorting capabilities command pharmacopeial-grade premiums while trading intermediaries compete on commodity volumes. The supplier base compresses as solvent-extraction and milling automation become standard capital requirements that exceed trading-only balance sheet capacity. Three archetypes dominate: backward-integrated seed-to-powder processors, Ayurvedic brand owners with captive retail distribution, and pharmaceutical-grade certification specialists. Competitive dynamics center on M&A consolidation of processing assets and strategic partnerships securing captive farming networks in climate-volatile growing regions.
Among Indian-origin integrated processors, Satnam Psyllium Industries and Altrafine Gums occupy positions exemplifying the pharmaceutical-grade certification archetype, while Patanjali Ayurved Limited anchors the Ayurvedic brand equity tier through its captive retail network. NOW Foods represents the North American backward-integration model, controlling seed sourcing to sustain margin stability across volatile harvest cycles. These three companies illustrate the strategic divergence between export-grade certification investments and domestic market brand building.
| Leading Market Players |
|---|
| NOW Foods |
| Patanjali Ayurved Limited |
| Satnam Psyllium Industries |
| Altrafine Gums |
| JYOT Overseas Pvt. Ltd. |
| Organic India |
| Keyur Industries |
| Yerba Prima |
| Konsyl Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day seed-to-powder lead times in Gujarat's processing clusters concentrate pricing power among integrated operators with captive farming networks, while spot-market traders absorb harvest volatility without margin buffers. This temporal structure rewards backward-integrated processors who lock in seed supply through monsoon-cycle contracts, forcing commodity-grade intermediaries into price-taking positions during Rajasthan's erratic rainfall windows.
Pricing Analysis
Configured-to-order USP-NF pharmaceutical grades command spreads exceeding standard food-additive powder by certification burden and testing intensity. Three-tier pricing structure across premium, standard, and economy levels stratifies by pharmacopeial compliance, with FDA-authorized health claim positioning anchoring the top tier. Cost compression in mass-market cereal applications intensifies as methylcellulose alternatives compete on dosing convenience. Direct-to-consumer wellness brands exhibit lowest price sensitivity, prioritizing batch traceability and organic certification over per-kilogram procurement economics.
Supply Chain Analysis
Inbound logistics costs from Mundra and Kandla ports to Rotterdam and Hamburg fluctuate with container availability across the Asia-Europe trade lane, compressing processor margins during peak export seasons. Supply concentrates in India's Gujarat and Rajasthan states, with secondary processing nodes in Germany and the United States for final pharmaceutical formulation. Raw material dependencies center on Plantago ovata seed mucilage content, monsoonal precipitation timing, and agricultural labor availability during harvest windows. Single-source vulnerability to Rajasthan's Barmer and Jalore district rainfall patterns creates harvest quantity uncertainty. Distribution runs through APEDA-certified processors to direct manufacturer relationships, bypassing traditional trading hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among direct-to-consumer wellness brands and pharmaceutical formulators who consolidate supplier relationships toward vertically integrated processors, fragmenting traditional distributor intermediaries into margin-squeezed commodity handlers.
For Market Incumbents: Secure captive farming networks in Mehsana and Patan districts through processor-led contract cultivation agreements that guarantee seed quality and traceability for USP-NF certification. Deepen optical sorting and near-infrared analyzer deployment to compress batch-to-batch variation and defend pharmacopeial-grade positioning against synthetic fiber substitution in laxative formulations. Channel control through established EU representation offices protects against disintermediation by e-commerce-first supplement brands. For New Entrants and Emerging Players: Differentiate on USDA organic and India Organic certification penetration in German and Dutch natural products channels where clean-label positioning commands shelf placement priority. Target ready-to-mix beverage formats in UK and German urban professional segments, where single-serve sachets and flavored instant drink powders address convenience gaps with minimal incumbent lock-in. Go-to-market through direct-to-manufacturer relationships leveraging APEDA export protocol alignment to bypass intermediary markups. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because solvent-extraction and automated milling capital requirements exceed trading-only balance sheet capacity, forcing exit or acquisition of sub-scale processors. Acquisition target archetype: integrated seed-to-powder operators with established EU or North American pharmaceutical channel relationships and captive farming networks in climate-resilient Gujarat districts. Signal to watch: FSSAI enforcement intensity tightening microbial and heavy metal limits, accelerating certification cost burdens that eliminate unqualified competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Sourcing | Captive farming networks in Gujarat's Mehsana district stabilize margin control across volatile monsoon harvest cycles. |
| Pharmaceutical-Grade Certification Investment | USP-NF and EP compliance opens premium positioning in FDA-authorized coronary health claim channels. |
| Organic Certification Penetration | USDA organic standards unlock price premiums in German and Dutch clean-label natural products channels. |
| Ready-to-Mix Format Development | Single-serve sachets address convenience gaps among urban professionals in UK and German functional food markets. |
| Direct-to-Manufacturer Distribution | APEDA-certified processors bypass intermediary markups through relationships with e-commerce wellness brands. |
Research Methodology
Desk research of FSSAI regulatory filings, APEDA export statistics, FDA health claim authorizations, and EU Novel Food catalog updates preceded structured interviews with Gujarat-based processing plant managers, pharmaceutical procurement leads at German functional food companies, Ayurvedic brand supply chain directors, and US dietary supplement formulators. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of publicly listed nutraceutical companies, and EFSA guidance documents. Bottom-up seed production estimates from Rajasthan and Gujarat agricultural departments were triangulated against top-down pharmaceutical and food additive consumption patterns.
Variance decomposition across product format, application vertical, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled included powder, capsule, granule, and tablet formats; dietary supplement, food additive, pharmaceutical, and animal feed applications; and retail, healthcare provider, food manufacturer, and pet industry end users. CAGRs were derived from fitted growth curves incorporating monsoon variability indices, pharmacopeial compliance cost trajectories, and synbiotic product launch pipelines. Industry-specific forecast inputs centered on Plantago ovata cultivation area expansion in Gujarat's contract farming networks and FDA adverse event reporting trends for fiber supplements.
Decision-makers should treat outputs as directional under assumptions of continued FSSAI enforcement intensity, stable EU-India trade lane container availability, and sustained FDA health claim authorization for coronary risk reduction; material deviation in monsoon precipitation patterns or synthetic fiber substitution rates would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Rice Bran Oil Market
Ingredients
Mineral Premix Market
Ingredients
North America Sodium Reduction Ingredients Market
Ingredients
Camelina Oil Market
Ingredients
Peanut Ingredients Market
Ingredients
Collagen Casings Market
Ingredients
Plant-Based API Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Oak Extract Market
Ingredients
Olive Oil Market
Ingredients
Salad Oil Market
Ingredients
India Protein Market
Ingredients
Soy Derivatives Market
Ingredients
Lime Seed Oils Market
Ingredients
Global Bioactive Ingredients Market