
 Phytosterols Market | 2026-2036
Phytosterols Market Size, Share, and Industry Trends Forecast 2026-2036
Phytosterols Market Intelligence
The phytosterols market is consolidating around a widening split between pharmaceutical-grade purity tiers and commodity food-grade supply. BASF SE leverages its integrated oleochemical platform to dominate high-purity beta-sitosterol extraction for drug applications. Cargill Inc. anchors the commodity tier through backward integration into vegetable oil refining streams across North American processing corridors. Arboris, LLC competes in the mid-tier by specializing in tall oil-derived sterols for European nutraceutical formulators.
Phytosterols comprise plant-derived steroid alcohols—primarily beta-sitosterol, campesterol, and stigmasterol—typically extracted at 40-90% purity depending on source material and distillation method, functioning chiefly as cholesterol-lowering agents in functional foods and therapeutics. Beta-sitosterol leads product type value pools due to its established efficacy in prostate health and cardiovascular applications, while campesterol commands tighter supply amid limited pine-derived feedstock availability. Dietary supplements represent the fastest-expanding application segment as nutraceutical companies reformulate delivery formats beyond traditional tablets into emulsified beverages and gummies.
FDA qualified health claims and EFSA Article 13.1 approvals shape demand by setting daily intake thresholds that manufacturers must hit for label compliance, while REACH registration requirements in Europe constrain market access for non-EU extractors. India's FSSAI is tightening import purity standards for phytosterol concentrates used in edible oil fortification programs. Stakeholders must monitor evolving pharmacopeial monograph revisions that could redraw the boundary between food additive and active pharmaceutical ingredient classifications.
Market Dynamics
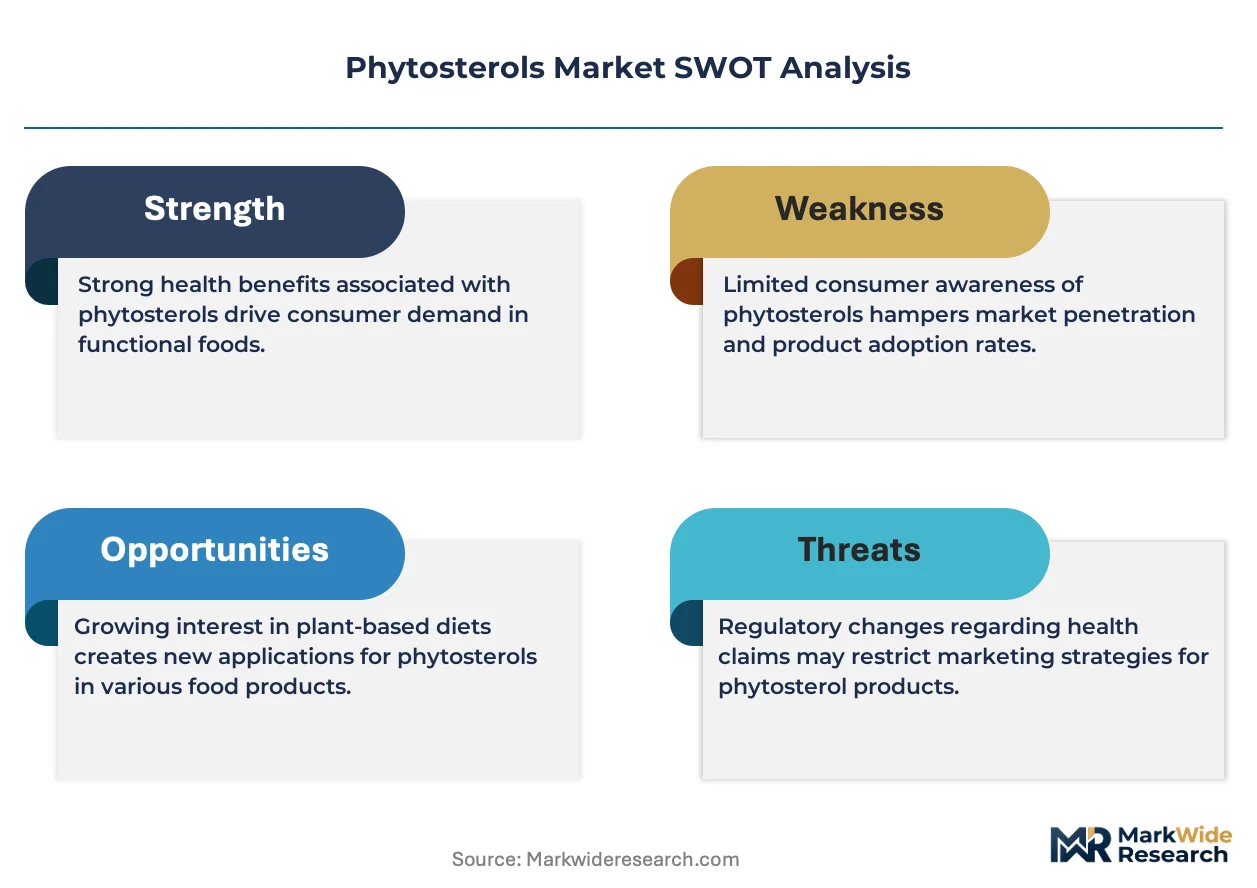
Phytosterol supply chains face acute pressure from diverging purity standards between pharmaceutical and food-grade channels, with EFSA daily intake thresholds and FDA qualified health claims forcing manufacturers into dual-certification investments that fragment production economics.
Growth Catalysts
- FDA Qualified Health Claims:The FDA's plant sterol intake thresholds enable heart-health label positioning that drives reformulation demand across US dairy and spreads categories.
- Emulsified Delivery Formats:Nutraceutical brands are deploying phytosterols in beverages and gummies, expanding addressable populations beyond traditional tablet users.
- German Functional Food Integration:German food manufacturers embed beta-sitosterol into dairy matrices at scale, creating template adoption patterns across neighboring markets.
Market Restraints
- Pine-Derived Feedstock Scarcity:Campesterol supply tightens amid constrained tall oil availability from Nordic pulp operations, compressing margins for mid-purity extractors.
- REACH Registration Barriers:European chemical registration requirements block non-EU extractors from direct market access, entrenching incumbent suppliers.
- Synthetic Statin Substitution:Generic atorvastatin price erosion in cardiovascular therapy displaces phytosterol demand in price-sensitive patient segments.
Strategic Opportunities
- India Edible Oil Fortification:FSSAI tightening of import purity standards creates first-mover advantage for certified suppliers in government-backed fortification programs.
- Prostate Health Therapeutics:Beta-sitosterol's established efficacy profile opens prescription-grade positioning in urology clinics across aging populations.
- Precision Fermentation Convergence:Biosynthesis platforms combining microbial cell factories with traditional extraction could decouple supply from agricultural commodity cycles.
Industry Challenges
- Pharmacopeial Monograph Divergence:USP, EP, and JP sterol assay methods lack harmonization, forcing redundant validation studies for multi-territory filings.
- Fractionation Capex Intensity:Supercritical CO2 and short-path distillation units require capital deployment that strains mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phytosterols Market |
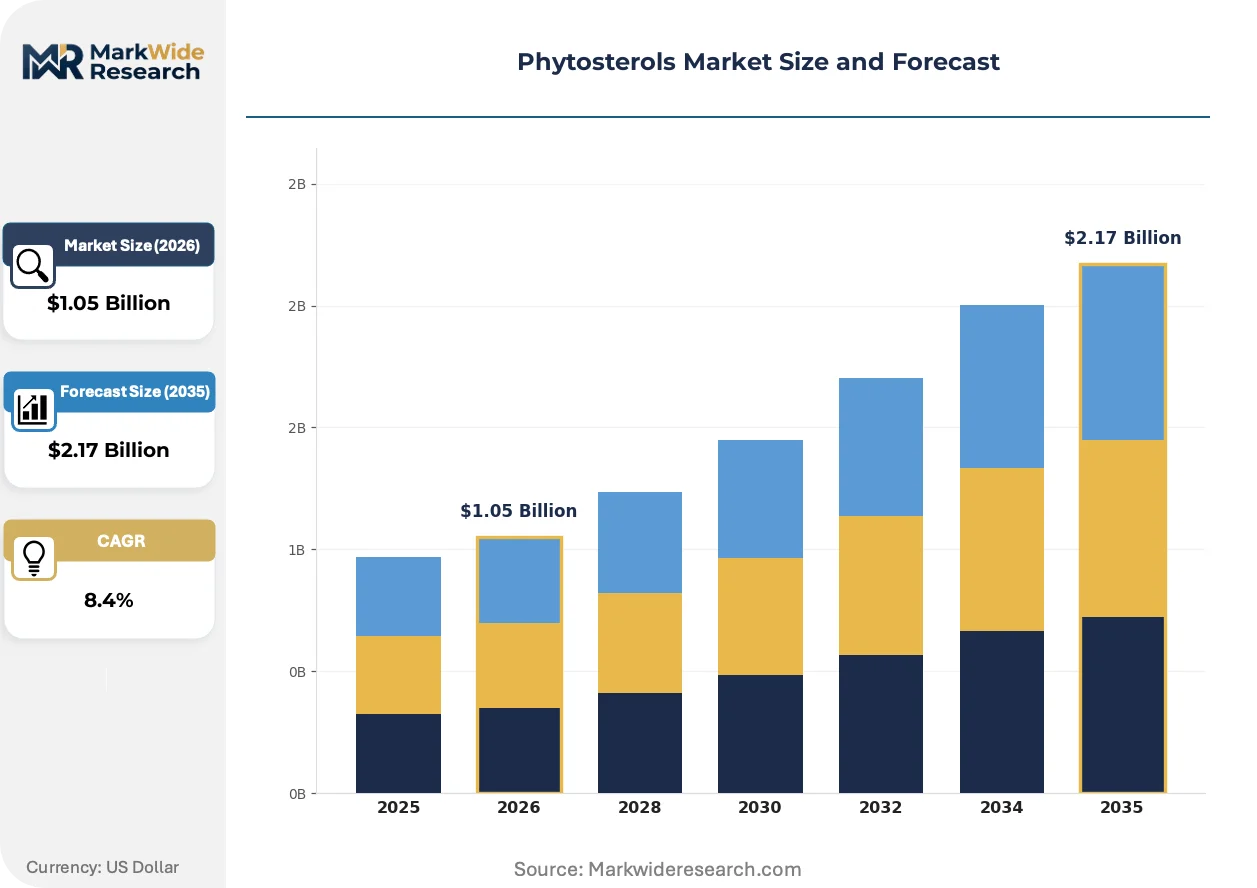
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-Sitosterol, Campesterol, Stigmasterol, Brassicasterol Application: Food & Beverage, Cosmetics, Dietary Supplements, Pharmaceuticals Source: Vegetable Oils, Nuts, Seeds, Grains End User: Food Manufacturers, Nutraceutical Companies, Cosmetic Brands, Healthcare Providers |
| Companies Covered | BASF SE, Cargill Inc., Archer Daniels Midland Company, DuPont de Nemours, Inc, Merck Group, Pharmachem Laboratories, Inc., The Lubrizol Corporation, Arboris, LLC, Gustav Parmentier GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phytosterols Market Strategic Shifts & Innovations
Supercritical fluid extraction and molecular distillation advances are compressing the cost curve for high-purity fractions while regulatory clarity on pharmaceutical-food boundaries reshapes competitive positioning across value tiers.
Supercritical CO2 extraction is rewriting cost structures for beta-sitosterol purification above 95% purity. Pharmaceutical formulators in cardiovascular and urology segments are accelerating adoption as batch-to-batch consistency improves. The technology is compressing the premium commanded by solvent-based crystallization methods in drug applications.
REACH registration deadlines for phytosterol concentrates are forcing supply chain reconfiguration across European nutraceutical channels. Non-EU extractors face exclusion from direct ingredient sales, driving toll-manufacturing partnerships with registered EU entities. German and Dutch toll processors are capturing margin previously held by raw material exporters.
Buyer consolidation among contract manufacturers is shortening qualification timelines and compressing supplier rosters to pre-audited tier-one sources. Mid-sized nutraceutical brands are outsourcing formulation entirely, eliminating in-house phytosterol procurement functions. This pattern concentrates most visibly in North American sports nutrition and women's health verticals.
Phytosterols Market Segmentation
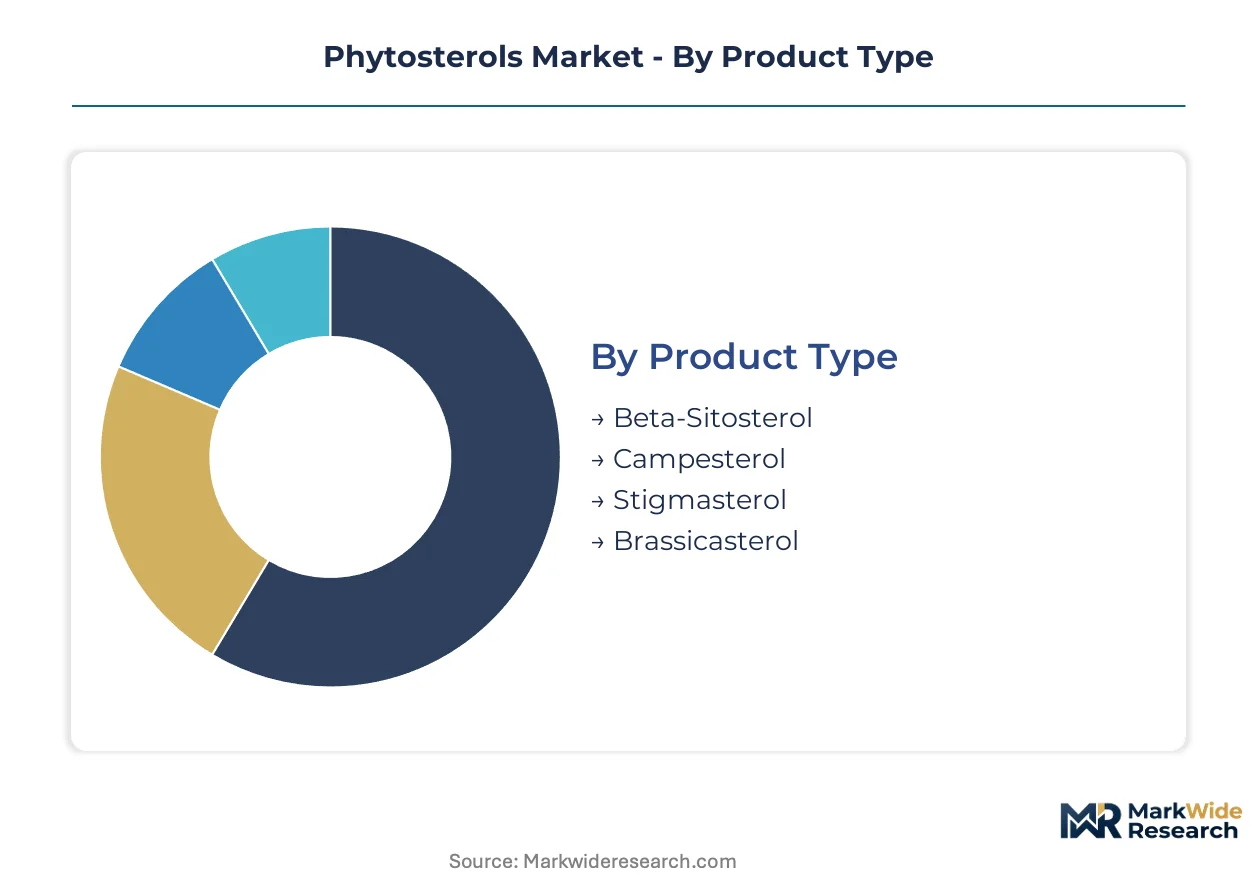
Phytosterol procurement patterns diverge sharply across purity grades and end-use specifications, with pharmaceutical buyers demanding USP-grade beta-sitosterol above 95% purity while food manufacturers optimize around 40-60% mixed sterol concentrates for cost-effective fortification.
Product Type:
Buyers in this category differentiate by therapeutic target specificity versus formulation flexibility, with urology and cardiology segments prioritizing single-sterol purity while functional food brands favor cost-optimized blends.
- Beta-Sitosterol:The most abundant plant sterol constitutes 50-80% of typical vegetable oil-derived mixtures, prized for prostate health and LDL cholesterol reduction applications. German dairy processors embed this sterol into spreadable matrices at scale, while US supplement brands deploy it in heart-health positioning under FDA qualified health claim thresholds. Demand concentrates in pharmaceutical-grade extraction where supercritical CO2 purification above 95% purity commands premium positioning in prescription urology formulations.
- Campesterol:This C-28 sterol typically represents 15-30% of natural phytosterol mixtures but faces acute supply pressure from constrained Nordic tall oil availability. European nutraceutical formulators prize campesterol for its distinct metabolic pathway in cholesterol modulation, though pine-derived feedstock scarcity has compressed margins for mid-purity extractors serving EFSA-regulated markets.
- Stigmasterol:A C-29 sterol common in soybean and rapeseed oil processing streams, valued by steroid hormone precursor manufacturers for its double-bond configuration at C-22.
- Brassicasterol:A C-28 sterol marker compound for marine and brassica-derived sources, tracked by quality control laboratories for adulteration detection in botanical extracts.
Beta-sitosterol leads volumes today; campesterol is gaining share fastest amid tightening pine-derived supply and specialized therapeutic applications.
Application:
Formulation complexity and regulatory pathway costs separate buyers, with pharmaceutical applicants absorbing pharmacopeial validation expenses that food-grade buyers avoid through GRAS self-determination.
- Food & Beverage:Margarine, yogurt, and orange juice fortification dominates tonnage offtake, with daily intake thresholds set by EFSA and FDA dictating minimum effective dosing for label claims. German manufacturers embed phytosterols into dairy spreads as template formulations for neighboring markets, while Indian edible oil fortification programs under FSSAI oversight create government-contract volume anchors.
- Dietary Supplements:Emulsified beverages and gummy formats are expanding addressable populations beyond traditional tablet users, with North American sports nutrition and women's health verticals driving reformulation activity. Contract manufacturer consolidation has shortened supplier qualification timelines, concentrating procurement among pre-audited tier-one sources.
- Cosmetics:Anti-aging topical formulations leverage phytosterol anti-inflammatory properties, though regulatory classification ambiguity between cosmetic and drug claims constrains positioning flexibility.
- Pharmaceuticals:Prescription-grade beta-sitosterol for benign prostatic hyperplasia requires USP/EP monograph compliance, with batch-to-batch consistency specifications that exclude commodity-grade suppliers.
Food and beverage leads volumes today; dietary supplements are expanding most quickly through delivery format innovation.
Source:
Supply security and price volatility exposure differentiate procurement strategies, with integrated processors controlling upstream vegetable oil refining while specialist extractors compete for premium tall oil and botanical fractions.
- Vegetable Oils:Soybean, rapeseed, and sunflower oil deodorizer distillates constitute the dominant commercial feedstock, with North American processing corridors generating economies of scale through backward integration into oilseed crushing.
- Nuts:Almond and walnut sterol concentrates command premium positioning in organic-certified supplement channels, though limited processing scale constrains volume expansion.
- Seeds:Pumpkin and flaxseed sources attract clean-label positioning in European naturals segments, with cold-press extraction methods preserving co-active phytochemicals.
- Grains:Corn fiber oil and wheat germ derivatives offer non-GMO positioning alternatives for label-sensitive North American buyers.
Vegetable oils lead volumes today; nuts are climbing the fastest through premium organic positioning.
End User:
Technical capability depth and regulatory sophistication separate buyers, with healthcare providers demanding pharmacopeial documentation that cosmetic brands bypass through cosmetic-grade specifications.
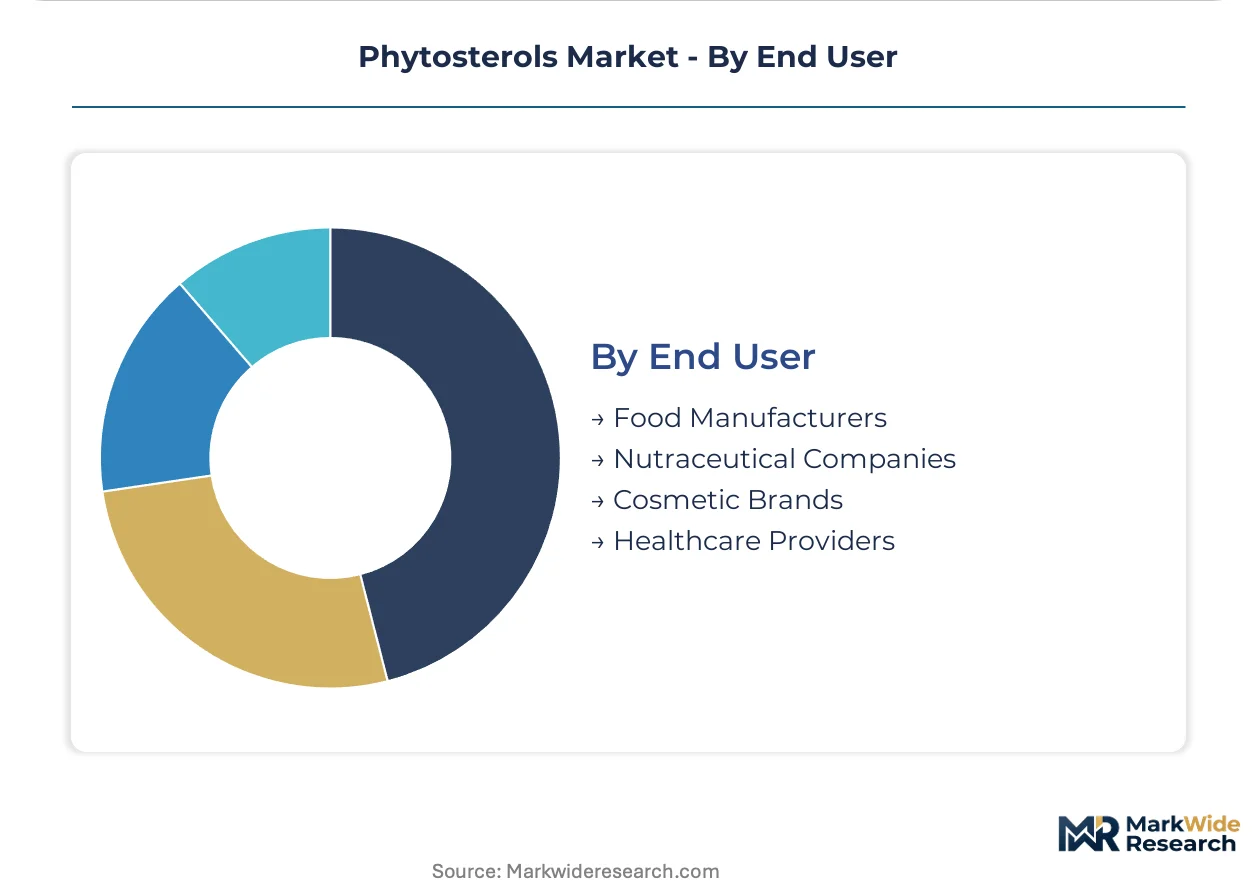
- Food Manufacturers:Multinational dairy and spreads producers drive tonnage demand through EFSA Article 13.1 and FDA qualified health claim compliance, with daily intake threshold adherence dictating formulation minimums.
- Nutraceutical Companies:Mid-sized brands are outsourcing formulation entirely, eliminating in-house phytosterol procurement functions and concentrating supplier rosters among toll-manufacturing partners.
- Cosmetic Brands:Clean-label positioning requirements favor certified organic or non-GMO verified sterol sources, with European naturals channels prioritizing sustainability credentials.
- Healthcare Providers:Urology clinics and cardiovascular specialists prescribe pharmaceutical-grade beta-sitosterol for BPH and hyperlipidemia management, requiring prescription drug documentation that commodity suppliers cannot provide.
Food manufacturers lead volumes today; healthcare providers are gaining share fastest through prescription-grade therapeutic positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized oleochemical engineers and food technology PhDs cluster in Germany's Ruhr industrial corridor, anchoring European phytosterol innovation. North American extraction specialists concentrate around vegetable oil processing hubs in the US Midwest. Asian markets are building technical capabilities through government-backed edible oil fortification programs.
United States
FDA qualified health claims for plant sterol intake drive reformulation across dairy and spreads categories. The agency's daily intake thresholds set minimum effective dosing for heart-health label positioning. Chicago-based food manufacturers embed phytosterols into functional dairy matrices, creating template adoption patterns for domestic brands.
Germany
EFSA Article 13.1 approvals shape demand by setting compliance thresholds for functional food fortification. REACH registration requirements constrain market access for non-EU extractors, entrenching incumbent suppliers. North Rhine-Westphalia's oleochemical cluster hosts backward-integrated processors dominating high-purity beta-sitosterol extraction for pharmaceutical applications.
India
FSSAI tightening of import purity standards creates first-mover advantage for certified suppliers in government-backed edible oil fortification programs. The regulator's evolving sterol concentrate specifications reshape procurement criteria for domestic oil processors. Maharashtra's edible oil refiners integrate phytosterol dosing systems to meet public health program mandates.
China
SAMR oversight of food additive classifications determines phytosterol positioning between functional food and therapeutic categories. National standards for plant sterol purity in fortified edible oils guide domestic manufacturer compliance. Shandong Province's vegetable oil processing corridors generate economies of scale through integrated deodorizer distillate recovery.
Japan
METI coordination of functional food labeling systems enables specific health claim approvals for cholesterol-lowering sterol products. PMDA pharmacopeial standards distinguish pharmaceutical-grade from food-grade sterol specifications. Osaka-Kobe's nutraceutical formulation cluster specializes in emulsified delivery formats expanding beyond traditional tablet applications.
Phytosterols Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a tiered supplier base. Integrated oleochemical platforms with captive vegetable oil refining streams dominate commodity-grade supply, while specialized extractors compete for premium pharmaceutical-grade positioning. Three archetypes anchor competition: backward-integrated agribusiness conglomerates, tall oil-derived sterol specialists, and toll-manufacturing intermediaries serving regulatory-constrained European channels. Competitive intensity centers on dual-certification investments for pharmaceutical-food grade boundaries and supercritical extraction capacity deployment for purity tier differentiation.
Among German-origin chemical conglomerates, BASF SE anchors the high-purity pharmaceutical tier through integrated oleochemical platform control. Cargill Inc. exemplifies the North American agribusiness archetype with backward integration into vegetable oil refining corridors. Arboris, LLC occupies the mid-tier specialist position for tall oil-derived sterols serving European nutraceutical channels.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Inc. |
| Archer Daniels Midland Company |
| DuPont de Nemours, Inc |
| Merck Group |
| Pharmachem Laboratories, Inc. |
| The Lubrizol Corporation |
| Arboris, LLC |
| Gustav Parmentier GmbH |
| Others |
Cost & Logistics Intelligence
Tall oil fatty acid price indices cascade through phytosterol supply chains into three distinct pricing tiers, with Nordic pulp mill output volatility compressing margins for mid-purity extractors while pharmaceutical-grade premiums widen on supercritical CO2 capacity constraints.
Pricing Analysis
Raw material-plus-processing fee unbundling separates commodity-grade from pharmaceutical-grade transactions, with vegetable oil deodorizer distillate spot pricing anchoring the standard tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and volume scale thresholds. Pricing pressure stems from generic statin price erosion in cardiovascular therapy, displacing phytosterol demand in cost-sensitive patient segments. Food manufacturers exhibit highest price sensitivity due to GRAS self-determination pathways, while healthcare providers absorb pharmacopeial validation costs for prescription-grade positioning.
Supply Chain Analysis
Deodorizer distillate recovery and tall oil fractionation byproducts generate circular feedstock flows back into sterol extraction circuits. Supply concentrates in the United States, Germany, and China through integrated vegetable oil refining corridors. Raw material dependencies rest on soybean and rapeseed oil processing streams, Nordic pulp mill tall oil availability, and pine-derived botanical fractions. Single-source vulnerability runs through Nordic campesterol supply amid constrained pulp operations. Distribution runs through pre-audited toll-manufacturing partnerships in European REACH-regulated channels and direct processor relationships in North American commodity tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phytosterols market operates as a regulatory compounder where FDA qualified health claims for plant sterol intake thresholds have structurally expanded addressable demand across functional food reformulation.
For Market Incumbents: Extend supercritical CO2 purification capacity above 95% beta-sitosterol purity to capture prescription urology segment premiums before synthetic statin substitution erodes cardiovascular positioning. Defend against emerging precision fermentation platforms by locking long-term tall oil supply agreements with Nordic pulp operators and accelerating dual USP-EP pharmacopeial certification investments. For New Entrants and Emerging Players: Contract manufacturers serving mid-sized nutraceutical brands represent the most accessible channel partner type for bypassing incumbent toll-processor gatekeeping. Target India's FSSAI-certified edible oil fortification programs as the most penetrable geography, where tightening import purity standards have disqualified uncertified suppliers. Lead with emulsified beverage and gummy format formulation capabilities to differentiate from tablet-commoditized incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration barriers block non-EU extractors from direct European market access, entrenching toll-manufacturing intermediaries as acquisition targets. Long-term viability favors vertically integrated processors with captive vegetable oil refining streams and supercritical extraction assets over asset-light traders. Watch for pharmacopeial monograph harmonization initiatives between USP, EP, and JP as the critical inflection signal that could redraw pharmaceutical-food grade boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Pharmacopeial Certification Investment | USP and EP monograph compliance unlocks prescription-grade beta-sitosterol positioning in urology clinics. |
| Supercritical CO2 Capacity Expansion | High-purity extraction above 95% captures pharmaceutical premiums from cardiovascular and prostate health formulators. |
| Toll-Manufacturing Partnership Formation | REACH-registered EU entities enable non-EU extractors to access European nutraceutical channels. |
| Precision Fermentation Platform Development | Biosynthesis capabilities could decouple sterol supply from agricultural commodity price cycles. |
| Edible Oil Fortification Contract Securement | FSSAI-certified supply agreements anchor volume in India's government-backed public health programs. |
Research Approach
Direct dialogue with extraction plant managers, nutraceutical procurement leads, EFSA regulatory affairs specialists, and urology clinic formulary directors grounded qualitative findings in operational reality. Secondary validation drew from FDA qualified health claim filings, REACH registration databases, FSSAI fortification program specifications, and customs trade data on deodorizer distillate flows. Bottom-up volume modeling across purity tiers and top-down market sizing through end-use consumption patterns were cross-referenced for triangulation.
Segment-level projections across product type, application, source material, and end-user categories were generated through the analytical framework. CAGRs were derived from elasticity-adjusted demand curves incorporating EFSA daily intake threshold compliance rates and FDA label claim adoption velocity. Industry-specific inputs included pharmacopeial monograph revision timelines, supercritical extraction capacity deployment schedules, and Nordic pulp mill tall oil output forecasts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to synthetic statin pricing trajectories and precision fermentation technology maturation. Practitioners should monitor REACH registration deadline extensions, FSSAI purity specification amendments, and USP-EP assay method harmonization proposals for early signals of supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market
Ingredients
Jojoba Oil Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Salad Oil Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Arachidonic Acid Market
Ingredients
North America Malt Ingredients Market
Ingredients
Mustard Oil Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Modified Flour Market
Ingredients
Starch Market
Ingredients
Sugar Beet Pectin Market