
 Special Boiling Point Solvents Market | 2026-2036
Special Boiling Point Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Special Boiling Point Solvents Market Intelligence
Capital-intensity divergence between integrated refiners and standalone blenders is bifurcating competitive returns across the Special Boiling Point Solvents landscape. ExxonMobil Corporation leverages captive naphtha streams and hydrocracking assets to sustain margin capture from feedstock through finished solvent. BASF SE anchors European supply with dedicated hydrogenation capacity, while HCS Group GmbH competes through specialized narrow-cut distillation expertise for pharmaceutical-grade specifications.
Special boiling point solvents constitute petroleum-derived hydrocarbon fractions refined to precise initial and final boiling ranges, typically between 30°C and 160°C, serving as controlled-evaporation carriers in industrial formulations. Their primary purpose centers on dissolving resins, adjusting viscosity, and enabling uniform film formation without residual contamination in coatings and adhesives. Toluene fractions occupy the dominant volume position across coatings applications where rapid flash-off properties command premium pricing, while ethyl acetate segments lead growth in adhesives as water-borne system formulators seek co-solvent compatibility bridges. Methanol categories sustain entrenched positions in cleaning agent formulations despite pressure from halogenated alternatives.
EPA New Source Performance Standards constrain US refinery emissions from solvent recovery operations, while REACH registration requirements in Europe mandate full toxicological dossiers for imported hydrocarbon blends. India's BIS certification for industrial solvents adds compliance layering for exporters targeting pharmaceutical and automotive OEM supply chains. Stakeholders must monitor regulatory divergence between jurisdictions where carbon border adjustments and product carbon footprint disclosures threaten to resegment competitive access.
Market Dynamics
Special boiling point solvents face structural pressure from India's tightening volatile organic compound discharge limits, which are forcing coatings manufacturers to reformulate with lower-aromatic narrow-cut fractions while simultaneously expanding procurement volumes.
Growth Catalysts
- Pharmaceutical-grade specifications:Automotive OEM supply chains in Gujarat's chemical corridor are demanding ultra-low residue SBP grades for precision coating applications, driving specialty blender capacity additions.
- EPA New Source Performance Standards:US refinery emission constraints on solvent recovery operations are accelerating investment in closed-loop recovery systems that extend effective solvent lifecycle economics.
- Hydrogenation capacity expansion:European producers are commissioning dedicated hydrogenation units to convert pyrolysis gasoline into pharmaceutical-grade cyclohexane and heptane fractions.
Market Restraints
- Naphtha feedstock volatility:Standalone blenders without captive cracking assets face margin compression when Asian naphtha spot prices spike against contracted solvent offtake agreements.
- REACH registration dossiers:Full toxicological documentation requirements for imported hydrocarbon blends create compliance layering that disadvantages non-EU exporters to European pharmaceutical formulators.
- Halogenated cleaning alternatives:Perchloroethylene and trichloroethylene formulations retain entrenched positions in metal degreasing despite environmental liabilities, limiting SBP penetration in industrial maintenance.
Strategic Opportunities
- Water-borne adhesive bridges:Ethyl acetate SBP grades are capturing formulation share as co-solvents that enable water-borne adhesive compatibility without sacrificing open-time performance.
- Carbon border adjustment positioning:EU product carbon footprint disclosure requirements create first-mover advantage for producers with verified low-carbon hydrogenation pathways and renewable naphtha integration.
- BIS certification layering:Exporters achieving Bureau of Indian Standards industrial solvent certification gain preferred supplier status to domestic pharmaceutical and automotive OEM procurement committees.
Industry Challenges
- Narrow-cut distillation expertise scarcity:Pharmaceutical-grade SBP production requires precise fractionation control within 5°C boiling ranges, constraining qualified operator availability and extending commissioning timelines for new facilities.
- Legacy coating system reformulation:Established toluene-based automotive refinish protocols resist specification changes despite regulatory pressure, forcing solvent suppliers to maintain dual-grade inventories during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Boiling Point Solvents Market |
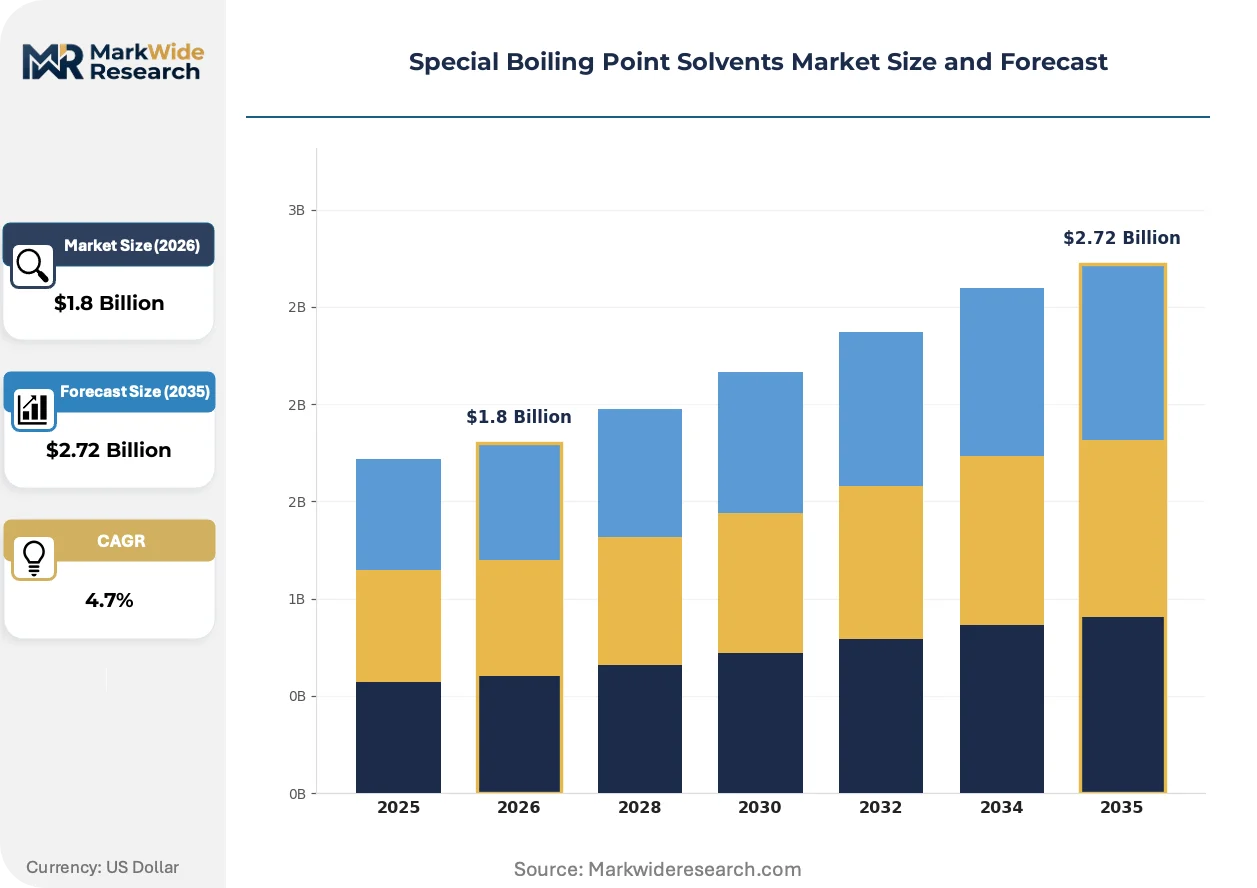
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetone, Ethyl Acetate, Methanol, Toluene Application: Coatings, Adhesives, Paints, Cleaning Agents End Use Industry: Pharmaceutical, Automotive, Chemicals, Cosmetics Packaging Type: Drums, IBC Tanks, Bottles, Flexitanks |
| Companies Covered | ExxonMobil Corporation, Royal Dutch Shell plc, TotalEnergies SE, Bharat Petroleum Corporation Limited, BASF SE, DHC Solvent Chemie GmbH, HCS Group GmbH, Calumet Specialty Products Partners, Banner Chemicals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Boiling Point Solvents Market Strategic Shifts & Innovations
Reformulation chemistry and regulatory disclosure requirements are actively restructuring how SBP solvents are specified, procured, and integrated into industrial coating and adhesive systems across multiple end-use verticals.
Membrane separation technology is decomposing traditional energy-intensive distillation sequences for narrow-cut fraction recovery. Pharmaceutical-grade solvent blenders in Germany and Switzerland are piloting polymeric membrane systems that reduce thermal degradation of heat-sensitive hydrocarbon fractions. This technology is decomposing the historical advantage of integrated refiners with massive fractionation trains, enabling mid-scale specialty producers to achieve comparable purity specifications with lower capital intensity.
REACH registration requirements are mandating full substance identity and toxicological dossiers for every hydrocarbon blend constituent imported into European Union member states. Formulators serving pharmaceutical and cosmetic applications must now document complete supply chain substance identity down to C10 isomer distribution. Coatings manufacturers with legacy multi-source procurement strategies are consolidating supplier bases to reduce registration duplication costs and audit complexity.
Buyers are consolidating solvent procurement through qualified supplier programs that bundle technical service, inventory management, and regulatory documentation into single-source agreements. Tier-one automotive OEMs in India and Germany are disqualifying spot-market suppliers in favor of partners with certified carbon footprint tracking and BIS or REACH-compliant quality systems. This consolidation is most visible in Gujarat's chemical corridor, where specialty solvent blenders are capturing multi-year supply contracts previously fragmented across commodity traders.
Special Boiling Point Solvents Market Segmentation
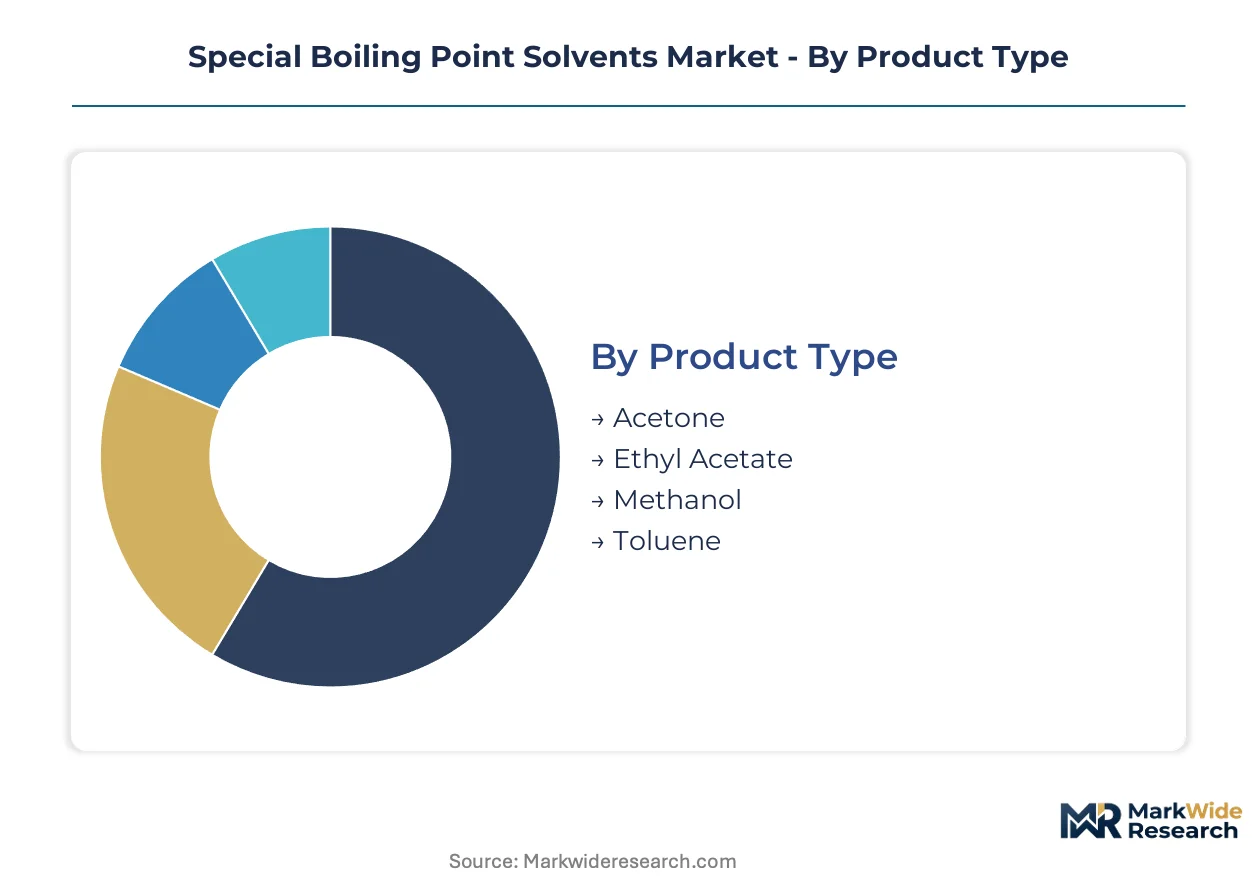
Special boiling point solvents serve distinct functional roles across industrial formulations, with product chemistry and application requirements dictating procurement patterns. Segment boundaries reflect divergent purity standards, evaporation profiles, and regulatory compliance burdens that reshape supplier-customer relationships.
Product Type:
Domestic production concentrates on commodity alcohols and aromatics for mass-market coatings, while export-oriented volumes flow toward pharmaceutical-grade narrow cuts with certified impurity profiles.
- Toluene:Aromatic hydrocarbon fraction refined to 110.6°C boiling point with controlled benzene content below 0.1% for coating applications. Demand concentrates in Gujarat's automotive refinish supply chain where rapid flash-off properties command specification adherence from OEM procurement committees.
- Ethyl Acetate:Ester solvent with 77°C boiling range serving as viscosity reducer in nitrocellulose lacquers and adhesive formulations. Export volumes to European water-borne adhesive formulators are climbing fastest as REACH-compliant grades displace commodity alternatives.
- Acetone:Ketone solvent with 56°C boiling point used in pharmaceutical extraction and cosmetic nail polish removers. Mumbai specialty blenders supply BIS-certified grades to domestic pharmaceutical API manufacturers.
- Methanol:Simplest alcohol solvent with 64.7°C boiling point sustaining entrenched positions in industrial cleaning and fuel additive applications despite toxicity handling requirements.
Toluene holds the largest share; momentum sits with ethyl acetate.
Application:
Volume distribution tracks construction cycle intensity and automotive production schedules, with coating applications dominating value capture through technical service bundling.
- Coatings:Dominant value segment encompassing architectural, industrial, and automotive refinish formulations where solvent selection determines film formation quality and dry-time performance. Gujarat and Maharashtra manufacturing clusters absorb the highest domestic offtake volumes.
- Adhesives:Fastest-expanding application as ethyl acetate grades enable water-borne system compatibility without sacrificing open-time characteristics required in flexible packaging lamination.
- Paints:Decorative and protective coating applications where toluene fractions adjust viscosity in alkyd resin systems for industrial maintenance markets.
- Cleaning Agents:Precision degreasing and electronics cleaning applications where controlled evaporation prevents residue contamination on sensitive substrates.
Coatings command the revenue concentration; adhesives are climbing the fastest.
End Use Industry:
Customer sophistication tiers separate commodity spot buyers from qualified suppliers serving validated pharmaceutical and automotive supply chains with full documentation packages.
- Automotive:OEM and refinish coating systems demanding ultra-low residue SBP grades with batch-specific certificates of analysis and carbon footprint disclosures for EU export eligibility.
- Pharmaceutical:API synthesis and extraction applications requiring USP-grade solvents with complete supply chain substance identity documentation down to isomer distribution.
- Chemicals:Intermediate manufacturing and custom synthesis operations purchasing drum quantities through distributor networks with flexible delivery scheduling.
- Cosmetics:Nail care and personal care formulations where odor profile and skin safety testing constrain acceptable solvent specifications.
Automotive absorbs the highest volume; pharmaceutical offers the steepest margin expansion trajectory.
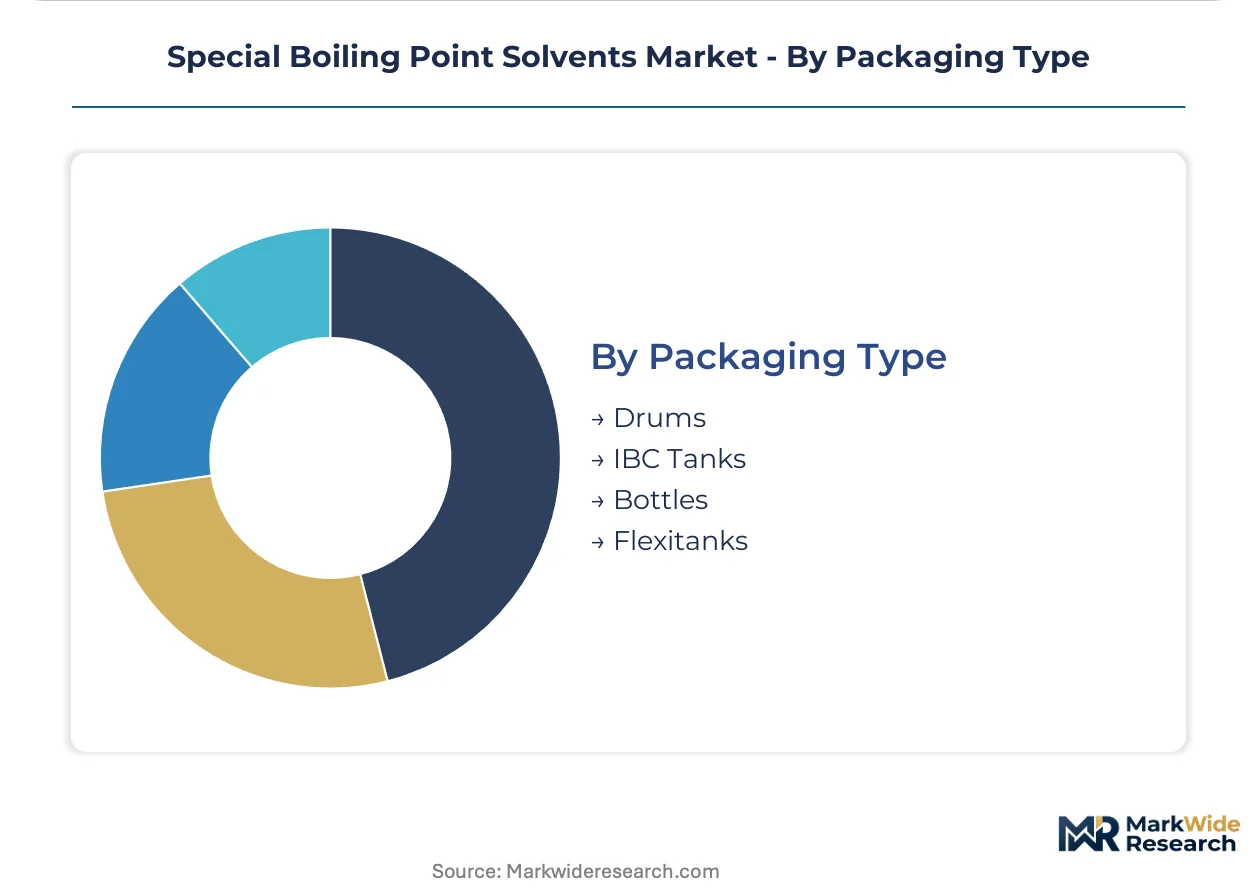
Packaging Type:
Logistics economics and contamination risk determine format selection, with bulk formats dominating integrated chemical park deliveries and small containers serving fragmented maintenance markets.
- Drums:Standard 200-liter steel containers serving mid-scale manufacturing operations with established material handling infrastructure and monthly consumption patterns.
- IBC Tanks:Intermediate bulk containers capturing share in continuous manufacturing environments where tote return programs reduce packaging waste costs.
- Flexitanks:Single-use flexible containers enabling ocean freight of solvent volumes without dedicated tank cleaning between product changeovers.
- Bottles:Laboratory and pilot-scale quantities for R&D sampling and quality control reference standards in pharmaceutical development workflows.
Drums retain the installed base; IBC tanks are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European buyers command premium-grade specifications that Indian exporters struggle to match on margin, while Gulf Coast refiners leverage feedstock proximity to undercut Asian spot pricing during naphtha volatility spikes.
United States
EPA New Source Performance Standards constrain refinery emissions from solvent recovery operations, accelerating capital deployment into closed-loop systems along the Texas-Louisiana chemical corridor. Houston-area integrated producers capture margin advantages from captive naphtha cracking that standalone blenders in the Northeast cannot replicate.
Germany
REACH registration dossiers mandate complete toxicological documentation for every hydrocarbon blend constituent, forcing pharmaceutical formulators to consolidate supplier bases. BASF SE anchors European supply from Ludwigshafen with dedicated hydrogenation capacity serving cosmetic and API synthesis markets.
India
BIS certification requirements for industrial solvents add compliance layering that disadvantages unqualified exporters targeting pharmaceutical procurement committees. Gujarat's chemical corridor concentrates specialty blender capacity additions as automotive OEMs demand ultra-low residue SBP grades with batch-specific certificates of analysis.
China
NMPA oversight of pharmaceutical-grade solvent imports intensifies documentation scrutiny for European exporters seeking API synthesis market access. Yangtze River Delta coating manufacturers are reformulating with lower-aromatic narrow-cut fractions under provincial environmental discharge tightening.
Japan
METI industrial standards for electronics-grade solvents constrain acceptable impurity profiles in precision cleaning applications. Osaka-based formulators source pharmaceutical-specification heptane fractions through long-term supply agreements that prioritize documentation consistency over spot-market pricing.
Special Boiling Point Solvents Market Key Industry Players
Concentration sits with integrated petroleum majors possessing captive naphtha streams and hydrocracking infrastructure. The vendor base stratifies into three tiers: global refiners with backward integration into feedstock production, European specialists with dedicated hydrogenation assets for pharmaceutical grades, and regional blenders competing on narrow-cut distillation expertise. Dominant competitive moves include capacity expansion in low-aromatic fraction production and strategic partnerships with automotive OEMs for qualified supplier program enrollment.
Within the integrated refiner tier, ExxonMobil Corporation and Royal Dutch Shell plc represent archetypes of margin capture from crude intake through finished solvent, leveraging Gulf Coast and Rotterdam infrastructure respectively. BASF SE anchors the European specialist position from Ludwigshafen, while HCS Group GmbH exemplifies the narrow-cut distillation expertise model serving pharmaceutical-grade specifications from German facilities. These three patterns—captive feedstock, hydrogenation specialization, and precision fractionation—define competitive positioning across the landscape.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Royal Dutch Shell plc |
| TotalEnergies SE |
| Bharat Petroleum Corporation Limited |
| BASF SE |
| DHC Solvent Chemie GmbH |
| HCS Group GmbH |
| Calumet Specialty Products Partners |
| Banner Chemicals Limited |
| Others |
Cost & Logistics Intelligence
Water-borne adhesive reformulation replacing solvent-borne systems in Gujarat's automotive corridor simultaneously concentrates procurement power among qualified blenders and compresses commodity toluene margins. This substitution dynamic reconfigures supply geography toward hydrogenation-capable facilities while pricing economics bifurcate between certified pharmaceutical grades and undifferentiated narrow cuts.
Pricing Analysis
The customization-premium spread between configured-to-order pharmaceutical grades and standard coating solvents spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on BIS certification status and REACH-compliant documentation depth, with spot-market toluene experiencing cost compression from naphtha feedstock volatility. Contracted automotive OEM buyers exhibit lowest price sensitivity due to qualified supplier program lock-in, while commodity traders face acute margin pressure from integrated refinery competition.
Supply Chain Analysis
Germany and India anchor pharmaceutical-grade hydrogenation capacity, while the US Gulf Coast concentrates integrated refinery output. Raw material dependencies draw from Asian naphtha spot markets, pyrolysis gasoline streams, and renewable feedstock pilots. Single-source vulnerability concentrates in narrow-cut distillation expertise for sub-5°C boiling range control. Distribution runs through qualified supplier programs bundling technical service, inventory management, and regulatory documentation into multi-year agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defensive story where REACH registration dossiers and BIS certification entrenchment create switching-cost barriers that protect incumbent positions from commodity competition.
For Market Incumbents: Consolidate supplier relationships through backward integration into captive naphtha cracking and dedicated hydrogenation assets. ExxonMobil Corporation's margin-capture model from feedstock through finished solvent exemplifies this path. Defend against membrane separation technology disruption by acquiring narrow-cut distillation expertise scarce in qualified operator markets.
For New Entrants and Emerging Players: Differentiate on carbon footprint verification for EU border adjustment positioning. Target water-borne adhesive bridge formulations in Gujarat's chemical corridor where ethyl acetate grades command specification premiums. Pursue BIS certification layering as the go-to-market angle for pharmaceutical procurement committee access.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European specialty blenders lacking integrated feedstock positions but possessing REACH-registered product portfolios. Long-term viability favors hydrogenation-capable facilities with verified low-carbon pathways over commodity narrow-cut operations. Watch membrane separation technology maturation as the inflection signal for capital-intensity disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogenation Capacity Expansion | BASF SE's Ludwigshafen investments anchor pharmaceutical-grade cyclohexane supply for API synthesis markets. |
| Backward Integration into Naphtha | Gulf Coast refiners capture margin advantages from captive cracking that standalone blenders cannot replicate. |
| Membrane Separation Technology Pilot | German and Swiss blenders reduce thermal degradation while achieving comparable purity with lower capital intensity. |
| BIS Certification Achievement | Exporters gain preferred supplier status to Indian pharmaceutical and automotive OEM procurement committees. |
| Carbon Footprint Verification Program | First-mover advantage emerges for producers with documented low-carbon hydrogenation pathways under EU disclosure rules. |
Research Approach
Desk research of customs trade databases, SEC 10-K filings, and ECHA registration dossiers preceded structured interviews with specialty solvent plant managers, automotive OEM procurement leads, pharmaceutical formulators, and distribution channel partners. Primary fieldwork combined with secondary validation from ACC and Cefic industry reports enabled bottom-up volume triangulation against top-down refinery capacity assessments.
Variance decomposition across product type, application vertical, end-use industry tier, and regional production hub shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling and feedstock cost pass-through coefficients, with naphtha price volatility and regulatory compliance cost inflation as solvent-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained naphtha supply stability or accelerated REACH enforcement timelines would require recalibration. Forecasts reflect documented assumptions on hydrogenation capacity commissioning schedules and carbon border adjustment implementation scope. Recalibration cycles align with material shifts in EPA New Source Performance Standards stringency and Indian BIS certification requirement expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Structure Directing Agents Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Caryophyllene Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Phospholipid Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Pegylated Lipids Market
Specialty Chemicals
Shikimic Acid Market