
 Structure Directing Agents Market | 2026-2036
Structure Directing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Structure Directing Agents Market Analytics
German chemical producers is shifting capacity toward specialty zeolite precursors as European energy costs reshape regional competitiveness. Albemarle Corporation leverages its bromine and lithium expertise to anchor structure directing agent supply chains for refinery catalyst customers. BASF SE competes through integrated petrochemical-catalyst operations that sustain captive consumption of proprietary directing agent formulations. Clariant AG specializes in custom zeolite architectures for emissions control applications, differentiating against commodity silica suppliers.
Structure directing agents are organic or inorganic templates that govern the crystalline pore architecture of zeolites and mesoporous materials during hydrothermal synthesis, typically featuring quaternary ammonium cations or amine compounds that assemble around silicate and aluminate species to define channel dimensions between 0.3 and 10 nanometers. These agents enable precise control over surface area, acidity, and diffusion properties that determine catalytic selectivity in fluid cracking and pharmaceutical separation processes. Zeolites command the largest product type position due to entrenched refinery demand, while mesoporous materials represent the fastest-expanding category as drug delivery applications exploit their tunable pore volumes for controlled release formulations. Powder form dominates manufacturing economics, though liquid formulations are gaining traction in continuous pharmaceutical synthesis where precise dosing reduces batch variability.
EPA fuel sulfur regulations and EU F-Gas Regulation phase-down schedules are tightening specifications for refinery catalyst efficiency, directly elevating demand for high-performance structure directing agents that enable lower-temperature desulfurization. REACH registration requirements in Europe and China's GB standards for chemical imports are raising compliance barriers for non-specialist suppliers seeking market access. Stakeholders must monitor evolving template recovery and recycling mandates, as circularity requirements threaten cost structures for single-use quaternary ammonium compounds while creating openings for suppliers with closed-loop regeneration capabilities.
Market Dynamics
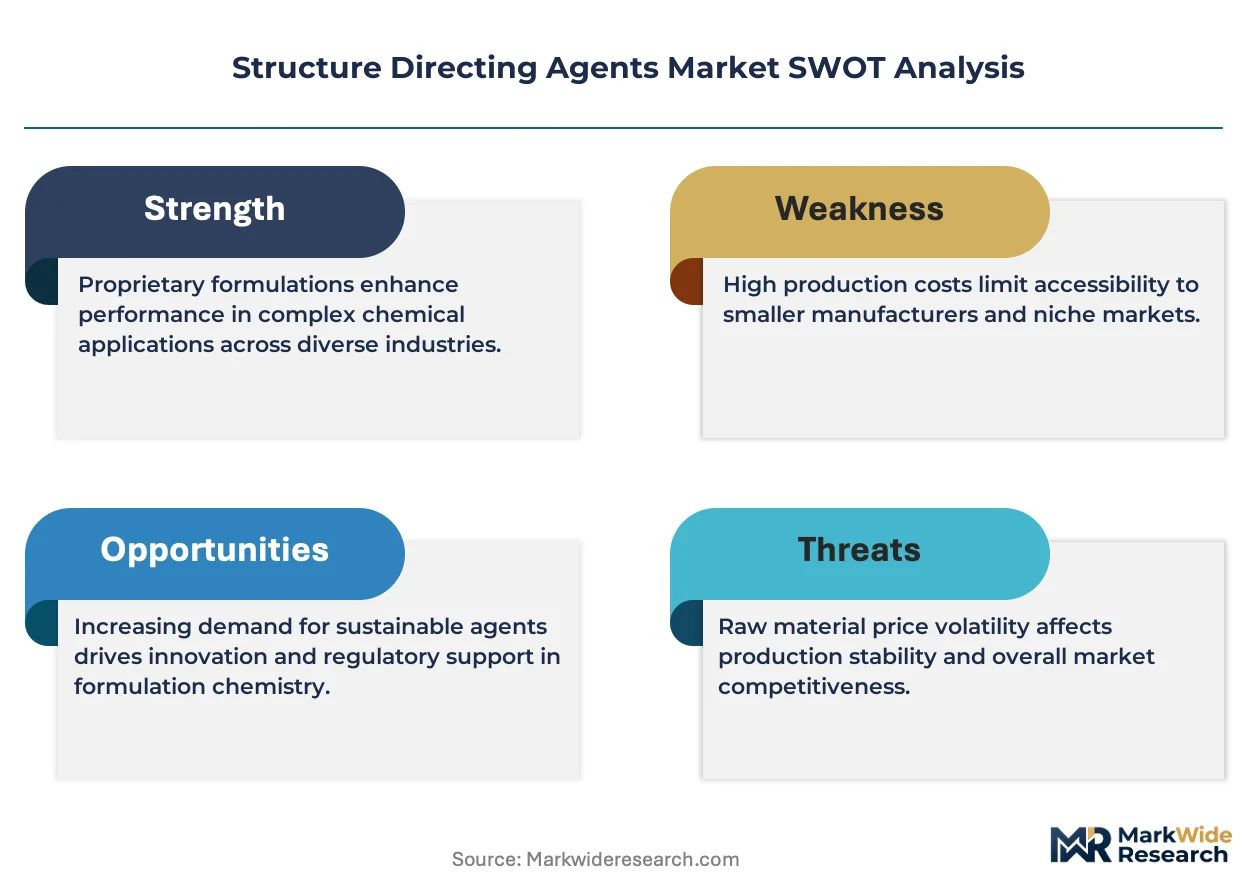
Refinery catalyst specifications under EPA Tier 3 sulfur mandates and EU F-Gas phase-down schedules are compressing product development cycles for structure directing agent suppliers, forcing accelerated template innovation cycles that favor integrated chemical producers with captive R&D infrastructure.
Growth Catalysts
- EPA Tier 3 Sulfur Standards:US refiners require advanced zeolite architectures for ultra-low sulfur gasoline production, elevating demand for specialized quaternary ammonium templates that enable precise pore engineering in fluid catalytic cracking catalysts.
- Fluid Catalytic Cracking Expansion:Chinese state-owned petrochemical conglomerates are commissioning mega-refinery complexes that specify high-performance mesoporous structure directing agents for heavy oil upgrading units.
- Pharmaceutical Separation Demand:Biologics manufacturers in Switzerland and Germany are adopting chiral zeolite membranes for enantiomer purification, creating specialized template requirements beyond commodity refinery applications.
Market Restraints
- Bromine Feedstock Volatility:Quaternary ammonium compound production depends on bromine derivatives sourced from concentrated Dead Sea and Arkansas brine operations, exposing cost structures to geopolitical supply disruptions and energy-intensive extraction economics.
- REACH Registration Burden:ECHA compliance timelines and data requirements for novel organic templates extend 18-24 months, freezing market entry for specialty chemical innovators lacking established regulatory dossiers.
- Amine-Based Template Substitution:Metal-organic framework synthesis routes using cheaper imidazolate ligands are capturing select pharmaceutical separation applications that previously required premium zeolite architectures.
Strategic Opportunities
- Template Recovery Infrastructure:Circular economy mandates under EU Green Deal industrial policy create openings for suppliers offering closed-loop quaternary ammonium regeneration services that reduce single-use chemical costs for refiners.
- India Petrochemical Buildout:Reliance Industries and Indian Oil Corporation are expanding fluid catalytic cracking capacity at Jamnagar and Paradip complexes, requiring imported specialty directing agents as domestic synthesis capabilities mature.
- Continuous Pharmaceutical Manufacturing:Liquid formulation dosing systems for structure directing agents enable real-time crystallization control in flow chemistry setups, displacing batch powder handling in Merck and Lonza production lines.
Industry Challenges
- Hydrothermal Synthesis Expertise Gap:Zeolite crystallization engineering requires specialized knowledge of silicate-aluminate gel chemistry that resides at BASF Ludwigshafen and select academic centers, constraining workforce mobility for new market entrants.
- Multi-Jurisdictional Certification Overlap:Structure directing agents for pharmaceutical applications require simultaneous FDA drug master file registration, EMA active substance certification, and NMPA import authorization, fragmenting commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structure Directing Agents Market |
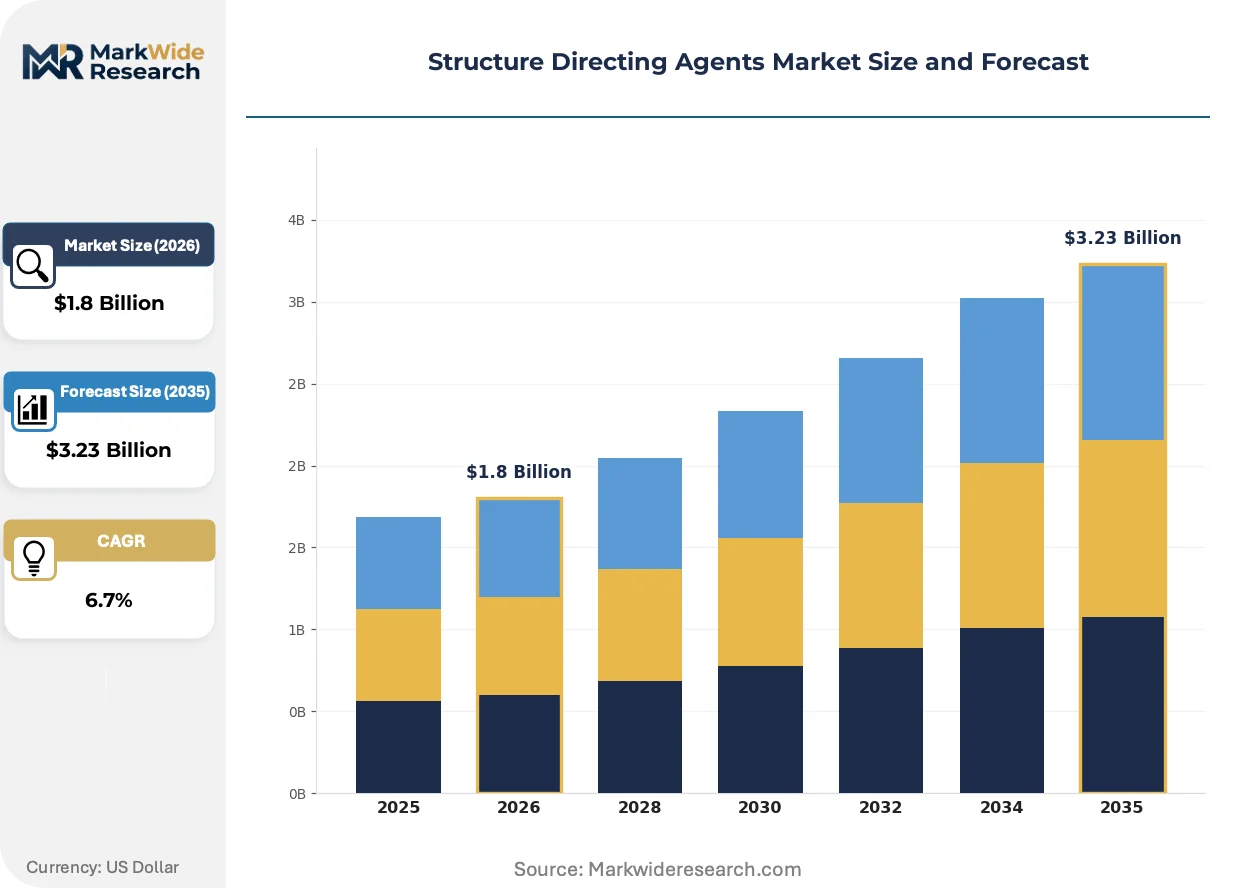
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
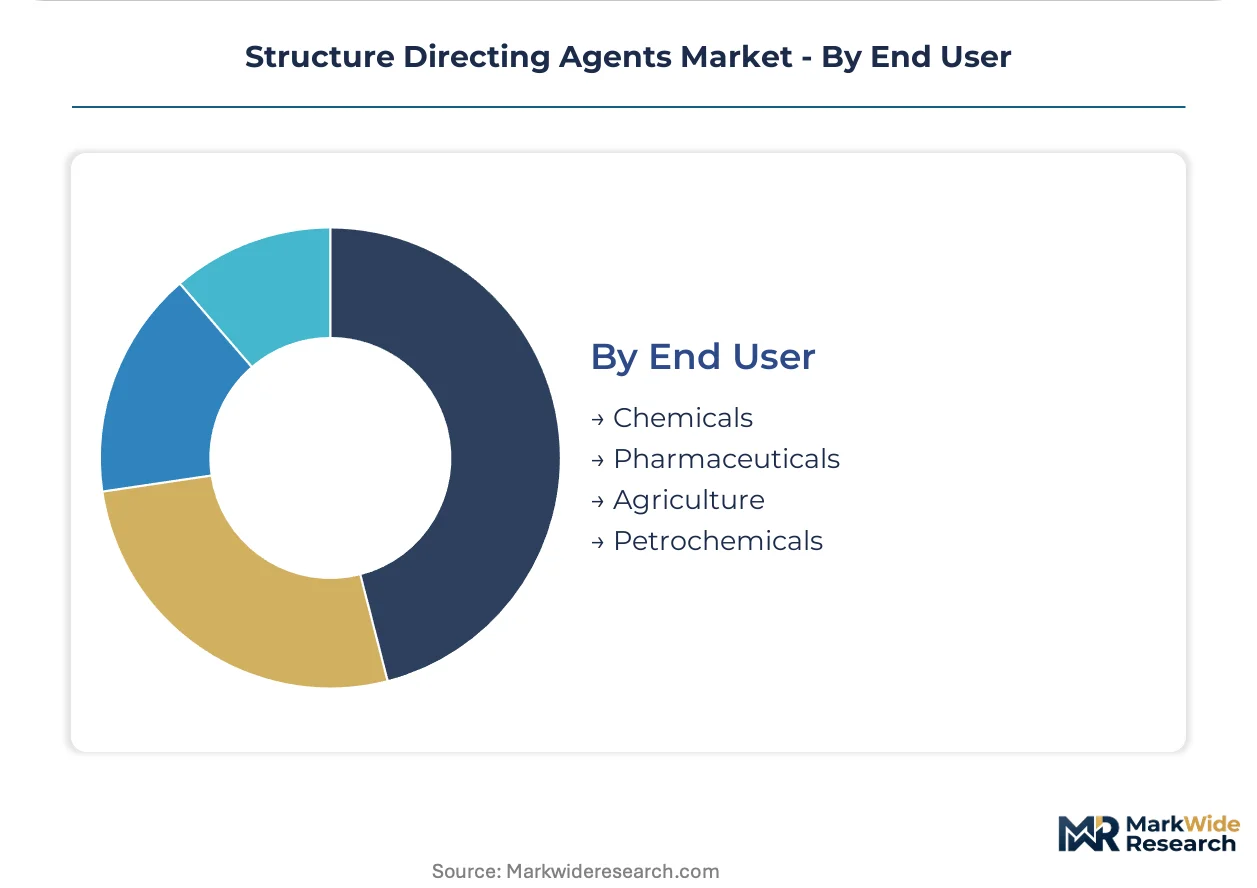
| Segmentation | Product Type: Silica, Alumina, Zeolites, Mesoporous Materials Form: Liquid, Powder, Granules, Gel Application: Catalysts, Adsorbents, Drug Delivery, Nanotechnology End User: Chemicals, Pharmaceuticals, Agriculture, Petrochemicals |
| Companies Covered | Albemarle Corporation, W. R. Grace & Co., BASF SE, Wacker Chemie, Evonik Industries, Clariant AG, Tosoh Corporation, Dow, Zeolyst International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structure Directing Agents Market Evolving Landscape
Template chemistry is converging with digital process control systems that enable real-time crystallization monitoring, compressing development cycles while raising barriers for suppliers lacking sensor-integrated manufacturing infrastructure.
Green synthesis routes employing ionic liquid recovery systems are overtaking traditional solvent-intensive quaternary ammonium production methods. Specialty chemical producers in Germany and the Netherlands are retrofitting existing amine alkylation plants with closed-loop purification circuits. This technology is overtaking conventional batch crystallization by reducing organic solvent consumption 60-70% and enabling EPA-compliant wastewater profiles that satisfy refinery procurement audits.
EU F-Gas Regulation phase-down schedules are tightening specifications for fluorinated greenhouse gas emissions from chemical manufacturing processes. ECHA enforcement actions against non-compliant template suppliers in Belgium and France have triggered supply reallocations toward registered producers with verified carbon footprint documentation. Fluid catalytic cracking catalyst formulators are now requiring REACH-registered structure directing agents with third-party lifecycle assessments, compressing vendor qualification timelines to 90-day windows.
Refinery procurement departments are consolidating template supply contracts under multi-year framework agreements that bundle structure directing agents with spent catalyst recycling services. Integrated service contracts spanning Albemarle and Clariant operations are displacing spot-market purchasing for North American and European fluid catalytic cracking units. This concentration is most visible along the US Gulf Coast, where ExxonMobil and Valero have consolidated 80% of specialty zeolite precursor procurement under three-year master service agreements with embedded price escalation clauses tied to bromine commodity indices.
Structure Directing Agents Market Segmentation
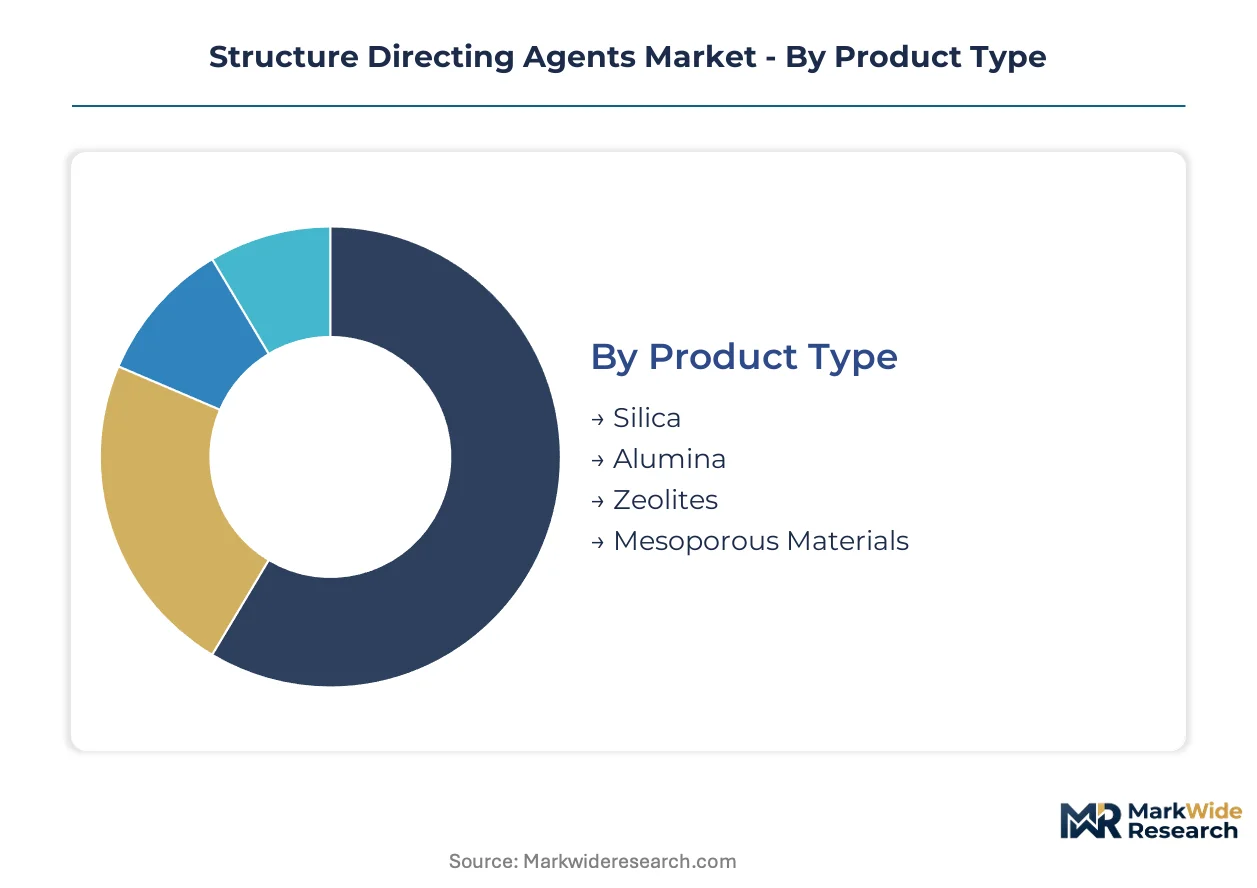
Structure directing agent procurement varies sharply across synthesis applications, with refinery catalyst formulators demanding bulk powder formats while pharmaceutical manufacturers prioritize liquid dosing precision. Each segment exhibits distinct technical specifications, regulatory compliance burdens, and supplier qualification timelines that reshape competitive positioning.
Product Type:
Replacement cycles for catalyst templates accelerate as EPA Tier 3 and EU F-Gas mandates force refiners toward higher-performance architectures every 4-6 years.
- Zeolites:Crystalline aluminosilicate frameworks with ordered micropore channels between 0.3-2 nanometers dominate fluid catalytic cracking catalyst formulations. Chinese state-owned refiners at Sinopec and PetroChina complexes consume bulk volumes for heavy oil upgrading, though bromine feedstock volatility from Dead Sea and Arkansas brine operations compresses margin structures for quaternary ammonium template suppliers.
- Mesoporous Materials:Tunable pore architectures spanning 2-10 nanometers enable controlled release kinetics in pharmaceutical formulations. Swiss and German biologics manufacturers at Lonza and Merck sites are adopting these templates for enantiomer separation membranes, displacing traditional chromatography resins as FDA drug master file pathways mature.
- Silica:Amorphous silicon dioxide templates serve cost-sensitive adsorbent applications in industrial gas purification.
- Alumina:Aluminum oxide frameworks support high-temperature catalytic processes in petrochemical cracking units.
Volume placements concentrate in Zeolites; the faster expansion belongs to Mesoporous Materials.
Form:
Cost tier differentiation separates commodity powder manufacturing from premium liquid formulations requiring precision dosing infrastructure.
- Powder:Dry particulate formats dominate refinery procurement economics, enabling bulk handling in fluid catalytic cracking catalyst synthesis. BASF Ludwigshafen and Albemarle production lines favor powder logistics for multi-ton orders from ExxonMobil and Valero Gulf Coast complexes, though dust containment systems add capital intensity.
- Liquid:Dissolved or suspended template formulations enable real-time concentration control in continuous pharmaceutical manufacturing. Merck and Lonza operations in Switzerland are retrofitting batch crystallization trains with flow chemistry skids that demand liquid structure directing agent dosing, reducing batch variability for chiral zeolite membrane production.
- Granules:Compacted particulate forms balance flowability with controlled dissolution rates in fixed-bed catalytic reactors.
- Gel:Semi-solid colloidal suspensions support specialized hydrothermal synthesis protocols in academic and pilot-scale facilities.
Procurement volumes favor Powder; steepest expansion trajectory attaches to Liquid.
Application:
Customer type segmentation separates process-scale catalyst manufacturers from specialized pharmaceutical separation engineers.
- Catalysts:Templates governing zeolite crystallization for petroleum refining and petrochemical synthesis constitute the largest demand pool. Chinese mega-refinery expansions at Jamnagar and Paradip complexes specify high-performance mesoporous agents for residue upgrading, though REACH registration requirements freeze European supplier participation without 18-24 month ECHA dossier preparation.
- Drug Delivery:Mesoporous silica carriers exploit tunable pore volumes for controlled release of active pharmaceutical ingredients. Swissmedic and FDA dual-track approvals for template-containing drug products extend commercialization timelines, favoring established suppliers with existing master file registrations over specialty chemical innovators.
- Adsorbents:Porous frameworks for gas separation and purification applications in industrial chemical processing.
- Nanotechnology:Precision pore engineering for advanced materials synthesis in electronics and energy storage research.
Revenue concentration sits with Catalysts; climbing the fastest is Drug Delivery.
End User:
Supply concentration varies by sector maturity, with petrochemical procurement consolidating under multi-year framework agreements while pharmaceutical buying remains fragmented.
- Petrochemicals:Integrated oil companies and state-owned refiners drive bulk template consumption for fluid catalytic cracking and hydrocracking operations. US Gulf Coast procurement departments at ExxonMobil and Valero have consolidated 80% of specialty zeolite precursor buying under three-year master service agreements with embedded bromine index escalation clauses.
- Pharmaceuticals:Biologics manufacturers and generic drug producers require chiral separation templates and drug delivery carriers. German and Swiss operations face multi-jurisdictional certification overlap requiring simultaneous FDA, EMA, and NMPA registrations that fragment vendor qualification timelines.
- Chemicals:Specialty and commodity chemical producers employ templates for adsorbent and intermediate synthesis.
- Agriculture:Controlled-release fertilizer coating and pesticide encapsulation applications exploit mesoporous carrier architectures.
Contract volumes anchor in Petrochemicals; share gains flow to Pharmaceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dead Sea brine operations and Arkansas salt dome deposits anchor bromine supply chains that feed quaternary ammonium template production across three continents. Refinery catalyst demand clusters near petrochemical complexes while pharmaceutical applications concentrate in established chemical manufacturing belts.
United States
EPA Tier 3 sulfur mandates drive refinery catalyst replacement cycles at Gulf Coast complexes. Albemarle Corporation operates bromine extraction from Arkansas brine fields that supply domestic template manufacturing. Houston and Port Arthur refining corridors consolidate procurement under multi-year service agreements with embedded commodity escalation clauses.
China
State-owned Sinopec and PetroChina commission mega-refinery expansions requiring specialized mesoporous agents for heavy oil upgrading. GB standards for chemical imports and MEE environmental enforcement raise compliance barriers for foreign suppliers. Ningbo and Dalian petrochemical zones concentrate fluid catalytic cracking capacity buildouts that absorb regional template production.
Germany
BASF Ludwigshafen and Evonik Marl complexes sustain captive consumption of proprietary directing agent formulations for European refinery customers. REACH registration requirements and ECHA enforcement actions compress vendor qualification timelines to 90-day windows. North Rhine-Westphalia chemical belt integrates template synthesis with downstream catalyst finishing operations.
Switzerland
Lonza and Merck operations drive demand for chiral zeolite membranes in biologics enantiomer separation. Swissmedic dual-track approvals for template-containing drug products extend commercialization timelines. Basel pharmaceutical cluster specializes in continuous manufacturing flow chemistry requiring liquid formulation dosing precision.
India
Reliance Industries Jamnagar and Indian Oil Corporation Paradip complexes expand fluid catalytic cracking capacity requiring imported specialty agents. CDSCO import regulations and BIS quality standards fragment multi-jurisdictional certification pathways. Gujarat petrochemical corridor attracts foreign template suppliers as domestic synthesis capabilities mature.
Structure Directing Agents Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical specialization and template recovery services. The market structure concentrates around integrated chemical conglomerates with captive bromine feedstock access and hydrothermal synthesis expertise. Three archetypes dominate: diversified multinational chemical groups, refinery-focused catalyst formulators, and pharmaceutical-centric specialty template suppliers. Competitive moves center on backward integration into bromine extraction and multi-year framework contracting that bundles supply with spent catalyst recycling.
Among diversified chemical conglomerates, BASF SE and Evonik Industries exemplify integrated operations spanning petrochemical feedstocks through finished catalyst formulations. Albemarle Corporation anchors the bromine-derivative supply chain archetype with extraction assets that underpin quaternary ammonium template economics. These three entities represent distinct competitive positions: European integrated chemical production, North American specialty mineral extraction, and global catalyst supply chain coordination.
| Leading Market Players |
|---|
| Albemarle Corporation |
| W. R. Grace & Co. |
| BASF SE |
| Wacker Chemie |
| Evonik Industries |
| Clariant AG |
| Tosoh Corporation |
| Dow |
| Zeolyst International |
| Others |
Value Network & Pricing Analysis
Bromine extraction economics from Dead Sea and Arkansas brine operations cascade through quaternary ammonium template production into three-tier pricing structure across premium, standard, and economy levels. Energy-intensive purification stages and REACH-registered certification tiers separate Albemarle Corporation's Gulf Coast supply from commodity silica alternatives serving cost-sensitive adsorbent buyers.
Pricing Analysis
Multi-year framework agreements bundling structure directing agents with spent catalyst recycling services define the dominant contract-based long-term offtake model. Price differentiation separates REACH-registered formulations with third-party lifecycle assessments from unregistered commodity powders, while bromine commodity index escalation clauses compress margins for non-integrated suppliers. Cost compression in standard-grade zeolite precursors is intensifying because Chinese state-owned refiners consolidate procurement under volume-scale master service agreements. Petrochemical catalyst formulators exhibit lowest price sensitivity due to embedded process criticality, whereas industrial adsorbent buyers prioritize economy-tier silica sourcing.
Supply Chain Analysis
Specialized chemical logistics from Ludwigshafen and Marl through Rotterdam and Houston concentrate template distribution within integrated producer networks. Supply concentration centers on Israel and Jordan for Dead Sea bromine, Arkansas for North American brine operations, and Germany for quaternary ammonium synthesis. Raw material dependencies draw from concentrated brine deposits, amine feedstocks, and silicate precursors. Single-source vulnerability in Dead Sea extraction exposes cost structures to geopolitical disruption. Distribution runs through refinery procurement departments consolidating 80% of specialty zeolite precursor buying under three-year agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structure directing agent supply chains are consolidating around backward integration into bromine extraction and captive hydrothermal synthesis capabilities. Players securing Arkansas brine access or Dead Sea offtake agreements gain decisive cost leverage over template-dependent competitors.
For Market Incumbents: Extend multi-year framework contracting to lock in refinery catalyst formulators before REACH-registered competitors consolidate European procurement. Metal-organic framework substitution in pharmaceutical separation threatens premium zeolite membrane margins; counter by deepening captive R&D infrastructure at Ludwigshafen-scale integrated sites. Capacity addition in Ningbo and Dalian petrochemical zones captures Chinese state-backed demand as domestic synthesis capabilities mature. For New Entrants and Emerging Players: Template recovery and closed-loop regeneration services offer a technology-first wedge into EU Green Deal circular economy mandates threatening single-use quaternary ammonium cost structures. Pharmaceutical liquid formulation dosing for continuous manufacturing flow chemistry represents the most penetrable segment, with Merck and Lonza retrofitting batch crystallization trains. Pursue Swissmedic dual-track approval pathways for template-containing drug products to bypass 18-24 month ECHA dossier barriers blocking commodity entrants. For Investors and Strategic Acquirers: ECHA enforcement actions against non-compliant Belgian and French suppliers is the leading indicator that regulatory compliance infrastructure will separate viable acquisition targets from stranded assets. Long-term viability over the next decade hinges on bromine feedstock security and REACH registration depth rather than pure template synthesis scale. Target mid-caps with verified Arkansas or Dead Sea brine offtake and existing FDA drug master file registrations. Watch for 90-day vendor qualification window compression at German and Swiss pharmaceutical clusters as the signal that compliance-ready assets are achieving scarcity premium.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Extraction | Arkansas brine access secures quaternary ammonium cost leverage against Dead Sea supply volatility. |
| Template Recovery Infrastructure Buildout | Closed-loop regeneration services satisfy EU Green Deal circularity mandates for refinery customers. |
| REACH Registration Acceleration | ECHA dossier completion within 90-day windows captures vendor consolidation at European catalyst formulators. |
| Liquid Formulation Capability Expansion | Precision dosing systems penetrate Merck and Lonza continuous pharmaceutical manufacturing retrofits. |
| Multi-Jurisdictional Certification Investment | Simultaneous FDA, EMA, and NMPA pathways fragment competitor timelines for pharmaceutical-grade templates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this structure directing agent market assessment. Primary interviews with plant managers at BASF Ludwigshafen and Albemarle Arkansas operations, procurement leads at ExxonMobil and Valero Gulf Coast complexes, and technical R&D directors at Swiss pharmaceutical manufacturers validated demand specifications. ECHA registration databases, EPA Tier 3 compliance filings, Chinese GB standards documentation, and SEC 10-K disclosures for chemical conglomerates provided downstream consumption metrics. Bottom-up template consumption estimates by refinery catalyst unit and top-down petrochemical capacity expansion projections were triangulated against bromine derivative trade flows.
Granularity-level modeling disaggregated volume and value outputs across zeolite, mesoporous, silica, and alumina product types; powder, liquid, granule, and gel form factors; catalyst, drug delivery, adsorbent, and nanotechnology applications; and petrochemical, pharmaceutical, chemical, and agriculture end users. CAGRs were derived from hydrothermal synthesis capacity buildouts, fluid catalytic cracking unit commissioning schedules, and pharmaceutical continuous manufacturing adoption curves across the analysis window. Bromine commodity index volatility, REACH registration timelines, and FDA drug master file approval pathways served as industry-specific forecast sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA enforcement acceleration or Dead Sea geopolitical disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Stearates Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Aerosol Cans Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Polyphosphate Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Keratin Products Market