
 North America Sugarcane Wax Market | 2026-2036
North America Sugarcane Wax Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sugarcane Wax Market Insights
The EPA's bio-based procurement preferences under the Farm Bill is broadening commercial interest in sugarcane-derived inputs across North American industrial channels. Cargill leverages its agricultural sourcing infrastructure to secure raw material streams from Brazilian and domestic cane processors. Kraton Corporation competes through polymer-wax hybrid technologies that extend performance parameters in coating applications. Emery Oleochemicals specializes in oleochemical pathways that sustain cost-competitive positions against petroleum-derived paraffin alternatives.
Sugarcane wax comprises long-chain aliphatic esters, alcohols, and hydrocarbons extracted from filter cake residues of sugar refining, typically melting between 76°C and 82°C and serving as a renewable substitute for carnauba and synthetic waxes in surface coatings and mold release. Natural wax grades occupy the largest volume share due to straightforward processing requirements and broad compatibility with food-contact and cosmetic formulations. Desugarized wax variants are gaining traction in premium cosmetics applications where residual sugar content would compromise emulsion stability. The food industry application segment anchors steady baseline demand through fruit coating and confectionery glazing requirements across North American processing facilities.
The USDA BioPreferred program and FDA food-contact substance notifications jointly establish compliance pathways that shape product development timelines and market access conditions for sugarcane wax suppliers. California's Proposition 65 enforcement patterns and Health Canada PMRA residue guidelines add layered testing obligations for cross-border formulations. Stakeholders must monitor evolving state-level packaging mandates and bio-content thresholds that will determine qualification for preferential procurement programs.
Market Dynamics
EPA bio-based procurement preferences under the Farm Bill are redirecting formulation decisions across industrial coatings, personal care, and food-contact applications throughout the United States and Canada. This regulatory pivot is compressing decision cycles for procurement officers who must now qualify renewable wax inputs against petroleum-derived benchmarks.
Growth Catalysts
- USDA BioPreferred program mandates:Federal purchasing requirements create guaranteed offtake channels for certified sugarcane wax suppliers serving institutional coatings and lubricant contracts.
- California personal care cluster expansion:Cosmetic formulators in Los Angeles and San Francisco corridors are accelerating plant-derived wax substitutions to meet clean beauty certification standards.
- Filter cake residue valorization:Sugar refineries in Louisiana and Florida are installing dedicated wax extraction units to capture value from previously discarded processing byproducts.
Market Restraints
- Brazilian raw material concentration:Over seventy percent of filter cake supply originates from São Paulo state cane processors, exposing North American refiners to currency and logistics volatility.
- Carnauba wax price compression:Northeast Brazilian carnauba harvests have recovered from drought, restoring price competitiveness of this established cosmetic and automotive coating input.
- Melting point performance gap:Sugarcane wax's 76-82°C range limits substitution in high-temperature mold release applications where synthetic paraffins tolerate 95°C+ operating conditions.
Strategic Opportunities
- Texas food processing corridor penetration:Fruit coating and confectionery glazing operations in Dallas-Fort Worth and Houston represent underdeveloped demand nodes with proximity to Gulf Coast import infrastructure.
- Health Canada PMRA biopesticide adjuvant pathway:Emerging regulatory recognition of sugarcane wax as inert ingredient in crop protection formulations opens agricultural chemical applications.
- Polymer-wax hybrid R&D convergence:Coating manufacturers are blending sugarcane wax with bio-based polyurethanes to achieve performance parity with petroleum-derived barrier films.
Industry Challenges
- FDA food-contact notification timelines:New intended use approvals require 180-240 day safety reviews, delaying product launches for reformulated confectionery and produce coating applications.
- Desugarized wax processing capex:Premium cosmetic grades require solvent extraction and crystallization equipment that smaller toll processors cannot finance without offtake guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sugarcane Wax Market |
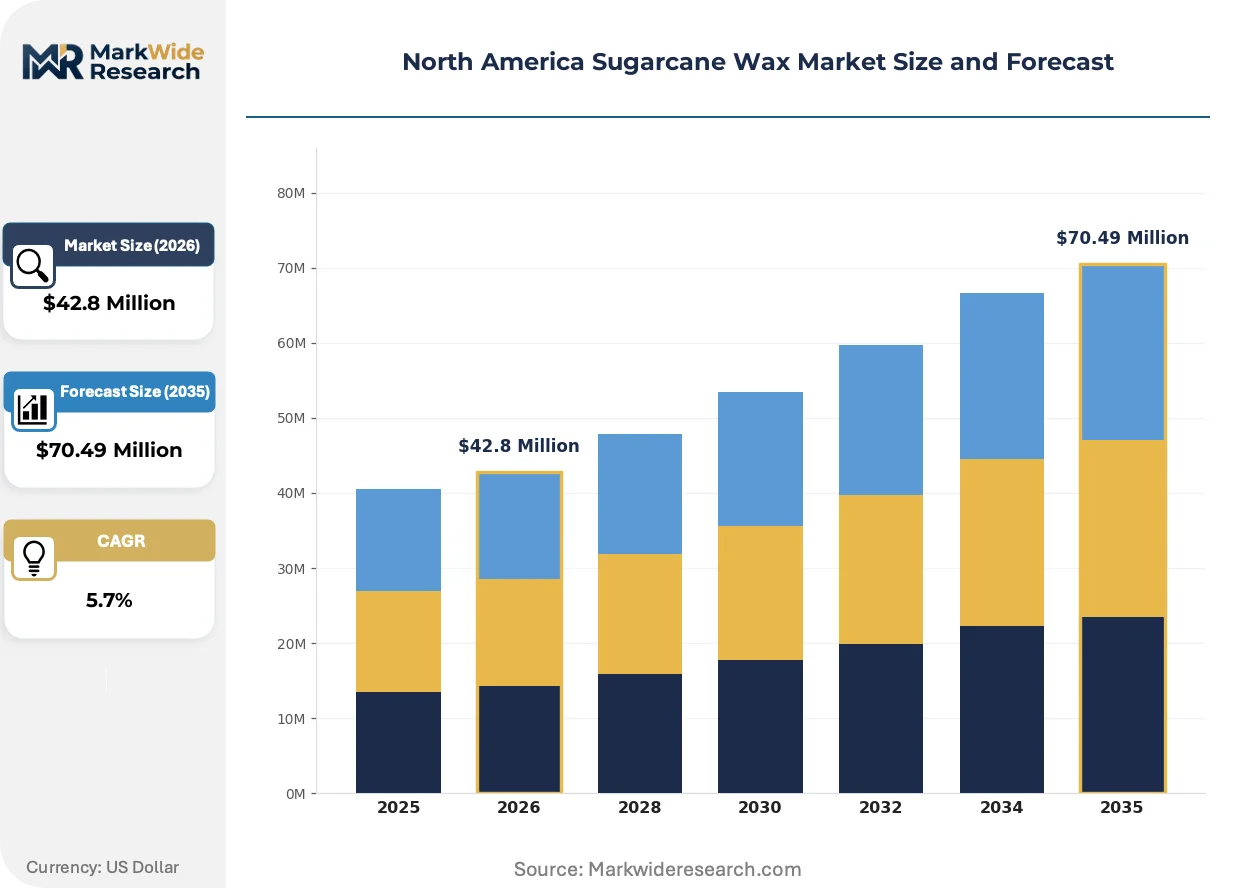
| Market Size in 2026 | $42.8 Million |
| Market Size in 2035 | $70.49 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Wax, Desugarized Wax, Bleached Wax, Emulsified Wax Application: Cosmetics, Packaging, Candles, Food Industry End User: Personal Care, Food Processing, Household, Industrial Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Cargill, Hawkins, Kraton Performance Polymers, NatureWax, BASF SE, Austrian Wax, Kraton Corporation, Emery Oleochemicals, Sasol, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sugarcane Wax Market Trends and Innovations
Formulation science and procurement policy are converging to reposition sugarcane wax from niche substitute to specified input across North American industrial channels. Three developments are compressing adoption timelines and reshaping competitive requirements.
Enzymatic esterification is integrating molecularly tailored sugarcane wax derivatives into high-performance coating systems. Specialty chemical manufacturers in New Jersey and Ohio are adopting these biocatalytic processes to achieve viscosity and adhesion specifications that previously required petroleum-derived modifiers. The technology is integrating renewable waxes into automotive undercoating and marine barrier applications where synthetic dominance had seemed entrenched.
California's Proposition 65 enforcement patterns are forcing disclosure reformulations across personal care and food-contact packaging. Manufacturers now face litigation exposure for residual petroleum distillates in conventional waxes, driving specification changes in Los Angeles and San Francisco formulating clusters. The state's attorney general actions are accelerating clean label transitions faster than federal timelines would predict.
Direct refiner-to-formulator contracting is displacing traditional distributor intermediaries in volume sugarcane wax transactions. Large cosmetics and food processors in Illinois and Pennsylvania are negotiating multi-year supply agreements that guarantee filter cake offtake and lock extraction capacity. This pattern concentrates procurement leverage with buyers who can commit to minimum volume thresholds, marginalizing smaller compounders dependent on spot market flexibility.
North America Sugarcane Wax Market Segmentation
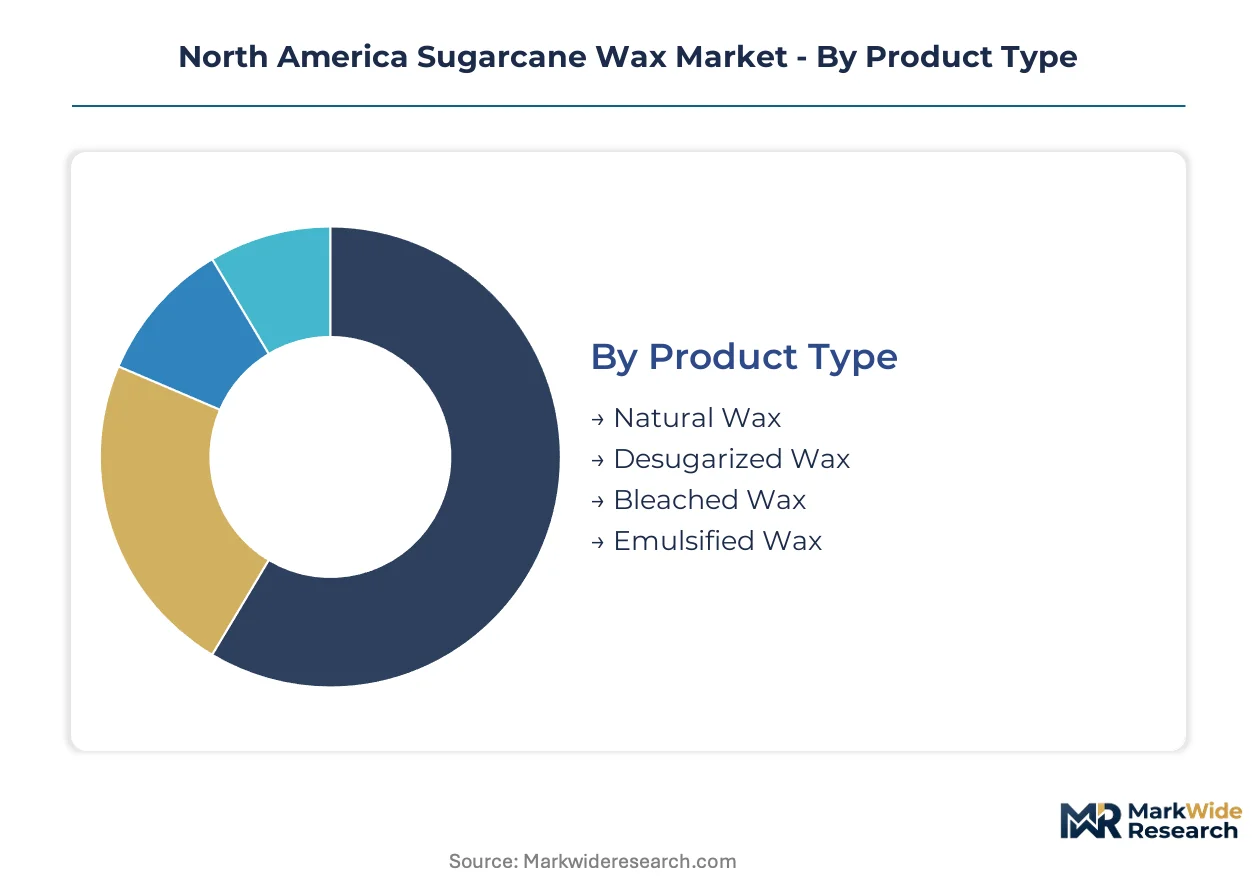
Sugarcane wax specifications diverge sharply between commodity grades serving high-volume food coating and refined variants commanding premium positioning in California's clean beauty formulations. Procurement officers segment purchases by functional purity thresholds rather than nominal product categories, compressing supplier qualification timelines for desugarized and emulsified grades.
Product Type:
Volume applications favor straightforward extraction protocols, while premium tiers demand post-processing investments that reshape margin structures across Louisiana and Florida refining corridors.
- Natural Wax:Long-chain aliphatic esters extracted directly from filter cake residues without secondary refinement, typically melting between 76°C and 82°C. Demand concentrates in Texas fruit coating operations and Midwest confectionery processors where residual sugar content poses no formulation conflict and cost minimization dominates procurement criteria.
- Desugarized Wax:Solvent-extracted and crystallized grades with reduced polar compound content, achieving superior emulsion stability in water-based cosmetic systems. California personal care manufacturers in Los Angeles and San Francisco corridors specify these grades for clean beauty certifications that disqualify standard natural wax alternatives.
- Bleached Wax:Oxidative or adsorptive decolorization yields lighter appearance grades for visible coating applications.
- Emulsified Wax:Pre-dispersed aqueous formulations reducing compounding complexity for mid-tier cosmetics houses.
Today's leader: Natural Wax. Tomorrow's challenger: Desugarized Wax.
Application:
End-use specifications fragment the addressable market between FDA-regulated food contact and EPA-influenced industrial coatings.
- Cosmetics:Lipstick structuring agents and cream emulsion stabilizers require batch-to-batch consistency in melting point and acid value. Los Angeles formulating clusters specify sugarcane wax to avoid Proposition 65 disclosure triggers associated with petroleum-derived alternatives.
- Food Industry:Confectionery glazing and fresh produce coatings constitute the largest volume segment, with Texas and Florida processing facilities driving baseline demand through FDA food-contact substance notifications.
- Packaging:Barrier coatings for paperboard and corrugated substrates.
- Candles:Container and pillar wax blends competing with soy and paraffin alternatives.
Food Industry anchors present volume. Cosmetics commands expansion velocity.
End User:
Procurement sophistication varies dramatically between specification-driven personal care multinationals and price-sensitive household product marketers.
- Personal Care:Multinational cosmetics houses with dedicated clean beauty portfolios negotiate multi-year supply agreements directly with cane refiners, bypassing traditional distributor markups. These buyers impose strict residual solvent limits and carbon footprint documentation exceeding baseline regulatory requirements.
- Food Processing:Fruit packers and confectionery manufacturers in California's Central Valley and Illinois processing corridors purchase through established oleochemical distributors, prioritizing lot-to-lot consistency over origin certification.
- Industrial:Mold release and lubricant compounders serving automotive and marine coating systems.
- Household:Candle manufacturers and DIY craft suppliers purchasing through retail channels.
Personal Care extracts premium pricing. Food Processing sustains throughput scale.
Distribution Channel:
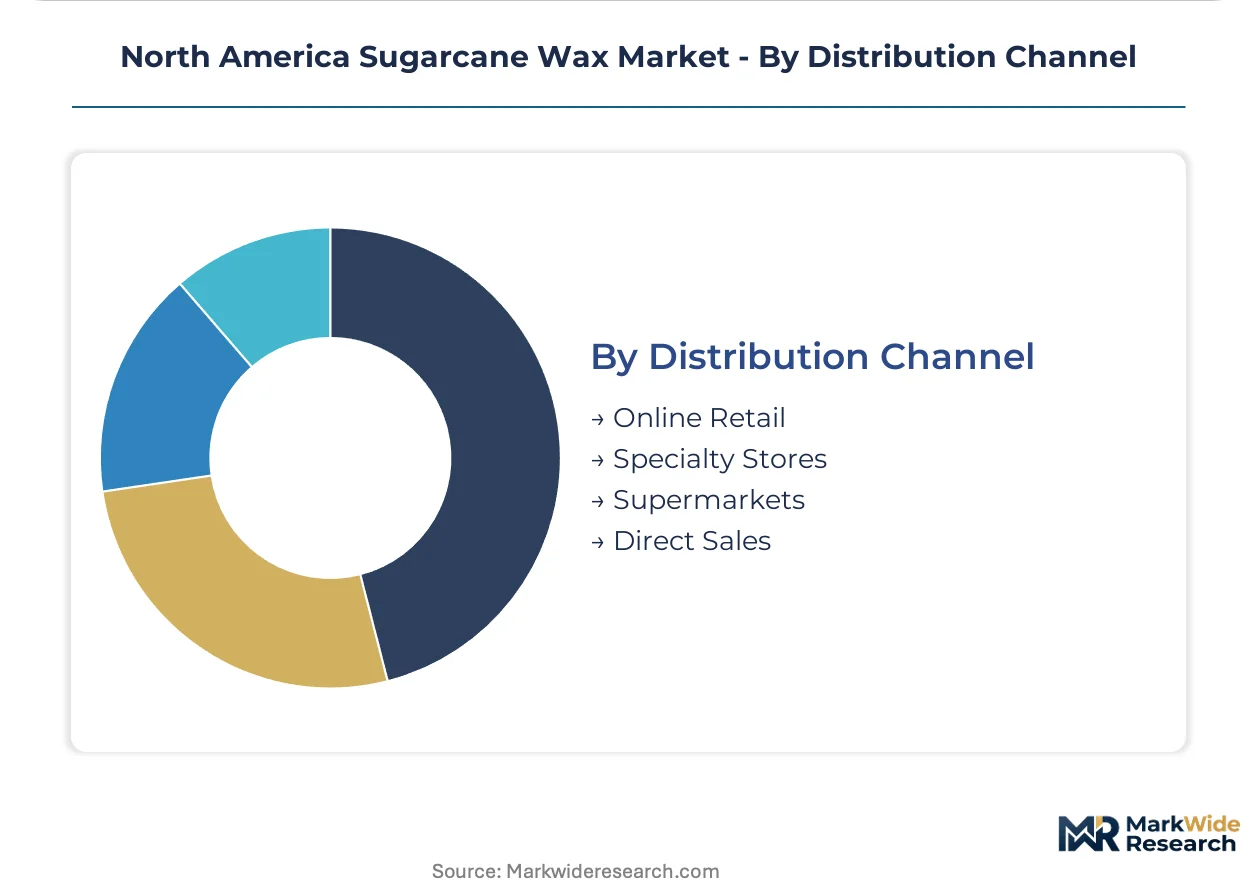
Channel selection reflects buyer scale and formulation complexity, with large processors disintermediating traditional supply tiers.
- Direct Sales:Refiner-to-formulator contracts now dominate volume transactions for cosmetics and food processing accounts above minimum threshold commitments. Cargill and domestic cane processors negotiate these arrangements to secure filter cake offtake and amortize dedicated extraction unit investments.
- Specialty Stores:Regional distributors serving mid-tier personal care compounders in New Jersey and Ohio maintain technical service capabilities for wax blending and custom specification development.
- Online Retail:Small-batch cosmetics entrepreneurs and candle makers purchasing desugarized grades in sub-ton quantities.
- Supermarkets:Consumer-facing wax products for household candle and craft applications.
Direct Sales consolidates volume leadership. Specialty Stores defend service-intensive niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sugarcane wax extraction originated in Brazilian sugar refining operations during the mid-twentieth century before migrating to North American processing facilities seeking value recovery from filter cake residues. Louisiana and Florida cane refineries now anchor domestic supply infrastructure.
United States
USDA BioPreferred program mandates and EPA procurement preferences under the Farm Bill are redirecting federal purchasing toward certified bio-based wax inputs. FDA food-contact substance notifications govern confectionery glazing and produce coating applications. California's Los Angeles and San Francisco personal care clusters specify desugarized grades for clean beauty certifications.
Canada
Health Canada PMRA residue guidelines and biopesticide adjuvant recognition are opening agricultural chemical applications for sugarcane wax inert ingredients. The country's national bioeconomy strategy supports renewable material procurement across federal agencies. Ontario food processors in the Golden Horseshoe corridor represent emerging demand nodes for fruit coating applications.
Mexico
Mexican sugar refineries in Veracruz and Jalisco are installing dedicated wax extraction units to supply North American food processing corridors. The country's national standards body establishes quality specifications for export-grade natural wax. Mexico City metropolitan area cosmetic manufacturers are accelerating plant-derived wax substitutions for US-exported formulations.
North America Sugarcane Wax Market Competitive Landscape
Capital-heavy agricultural processors compete with asset-light specialty chemical formulators across differentiated value chain positions. Market structure concentrates upstream extraction capacity with integrated cane refiners while fragmenting downstream compounding and formulation services. Three archetypes dominate: integrated agricultural processors controlling raw material streams, oleochemical specialists with esterification expertise, and polymer-wax hybrid innovators extending performance specifications. Dominant competitive moves include direct refiner-to-formulator contracting and multi-year supply agreements securing dedicated extraction capacity.
Within the integrated agricultural processor tier, Cargill leverages its Brazilian and domestic cane sourcing infrastructure to anchor filter cake supply security. Kraton Corporation and Kraton Performance Polymers exemplify the polymer-wax hybrid archetype, occupying positions where renewable waxes integrate with performance polymer systems. Emery Oleochemicals represents the oleochemical specialist category, sustaining cost-competitive positions through established esterification pathways.
| Leading Market Players |
|---|
| Cargill |
| Hawkins |
| Kraton Performance Polymers |
| NatureWax |
| BASF SE |
| Austrian Wax |
| Kraton Corporation |
| Emery Oleochemicals |
| Sasol |
| Others |
Pricing and Supply Chain Analysis
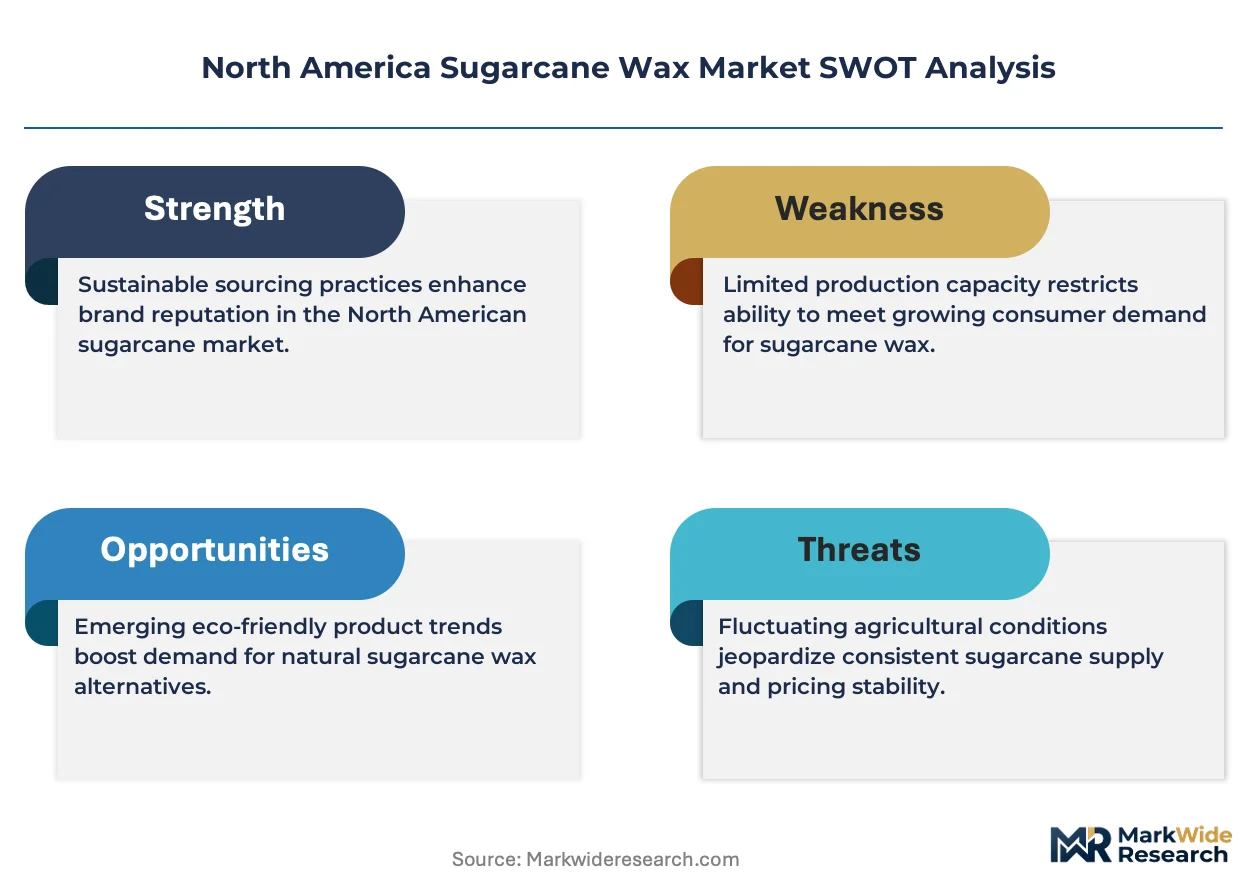
Filter cake residue spot indices in São Paulo state cascade through North American sugarcane wax pricing tiers, compressing margins for toll processors while amplifying bargaining leverage for integrated refiners with captive Brazilian supply. The USDA BioPreferred program's procurement mandates create price floors for certified grades, separating compliant suppliers from spot-market exposed competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transactions, with desugarized cosmetic grades commanding spreads over natural wax based on solvent-extraction certification and residual purity documentation. Price differentiation hinges on FDA food-contact notification status and carbon footprint verification for California clean beauty procurement. Pricing pressure stems from recovering Brazilian carnauba harvests restoring substitute competitiveness. Food processors in Texas and Illinois exhibit highest price sensitivity, while Los Angeles cosmetics houses prioritize specification compliance over unit cost.
Supply Chain Analysis
Gulf Coast freight rates from Brazilian port terminals to Houston and New Orleans determine landed cost competitiveness for filter cake shipments. Supply concentrates in São Paulo state cane processors, Louisiana refineries, and Florida extraction facilities. Raw material flows draw from sugar refining byproducts, solvent extraction chemicals, and crystallization equipment. Single-source vulnerability pervades the Brazilian filter cake dependency. Distribution runs through direct refiner-to-formulator contracts for volume accounts, with specialty distributors serving mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Sugarcane Wax Market functions as a regulatory compounder where EPA bio-based procurement preferences under the Farm Bill generate mandated demand floors that reshape competitive returns.
For Market Incumbents: Deploy backward integration into Brazilian filter cake sourcing to neutralize currency volatility exposure threatening margin stability. Incumbent processors should secure multi-year supply agreements with São Paulo state cane cooperatives before Health Canada PMRA adjuvant recognition triggers demand spikes. Cargill's agricultural infrastructure advantage intensifies competitive pressure on asset-light formulators lacking upstream control. For New Entrants and Emerging Players: Enter via Texas food processing corridor penetration, where fruit coating and confectionery glazing operations remain underdeveloped relative to California and Illinois demand nodes. New entrants should target desugarized wax toll processing for mid-tier cosmetics houses in New Jersey and Ohio lacking volume thresholds for direct refiner contracts. Technical service capabilities for custom emulsion development provide differentiation against commodity distributors. For Investors and Strategic Acquirers: Asymmetric upside sits with oleochemical specialists possessing esterification expertise and existing FDA food-contact notification portfolios. Long-term viability rests on regulatory tailwinds persisting across federal procurement cycles and state-level packaging mandates. Acquisition candidates include Louisiana and Florida refiners with installed extraction capacity and verified BioPreferred certification. Investors should monitor California Proposition 65 enforcement patterns as inflection indicators for clean label substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Cake Supply | Cargill leverages Brazilian agricultural infrastructure to secure raw material streams against currency volatility. |
| Desugarized Wax Capacity Expansion | California clean beauty certification requirements drive solvent extraction and crystallization equipment investments. |
| Direct Refiner-to-Formulator Contracting | Multi-year supply agreements displace distributor intermediaries and lock extraction capacity for volume buyers. |
| Health Canada PMRA Adjuvant Registration | Biopesticide inert ingredient recognition opens agricultural chemical applications beyond food and cosmetics. |
| Polymer-Wax Hybrid R&D Partnership | Kraton Corporation integrates renewable waxes with bio-based polyurethanes for coating performance parity. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each territory's sugar refining and personal care manufacturing corridors. The analysis combines structured interviews with Louisiana and Florida refinery operations managers, California cosmetics formulating executives, and Texas food processing procurement leads with secondary validation from USDA BioPreferred program databases, FDA food-contact substance notification filings, EPA procurement records, and Health Canada PMRA regulatory guidance documents. Bottom-up volume estimates from extraction capacity utilization triangulate against top-down demand projections from end-use industry consumption patterns.
Granularity extends to product type, application, end user, and distribution channel dimensions across the projection horizon. The analytical framework models natural wax, desugarized wax, bleached wax, and emulsified wax grades separately, with cosmetics, food industry, packaging, and candle applications tracked at the state and provincial level. CAGRs derive from regression analysis of historical filter cake valorization trends, regulatory mandate implementation timelines, and substitution elasticity estimates for carnauba and petroleum-derived wax alternatives. Industry-specific inputs include California Proposition 65 litigation frequency and Brazilian real exchange rate volatility assumptions.
The model holds under stable Farm Bill procurement authority and continued EPA bio-based preference enforcement; deviation in federal appropriations cycles or Brazilian harvest disruptions would shift volume trajectories. Forecasts incorporate assumptions about clean beauty certification persistence and Health Canada regulatory recognition timelines. Stakeholders should weight assumptions against their own operating context and risk tolerance for raw material sourcing concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Barium Derivatives Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
Disodium Adenosine Triphosphate Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Catharanthine Market