
 Germany Starch Derivatives Market | 2026-2036
Germany Starch Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Starch Derivatives Market Foresight
The gap between premium modified starches and commodity-grade alternatives is shifting wider as pharmaceutical and clean-label food buyers enforce stricter purity specifications while paper mills prioritize cost. Cargill Inc. leverages its European supply network to secure raw material consistency across German processing sites. Emsland Group anchors its position through backward integration into regional potato starch production. Südzucker AG competes on enzymatic modification expertise for specialized food applications.
Starch derivatives are carbohydrate-based polymers produced through chemical, physical, or enzymatic alteration of native starch, with dextrose equivalence and viscosity profiles tuned to specific industrial functions. These modified starches serve as binders, thickeners, film-formers, and stabilizers across manufacturing sectors. Hydroxypropyl starch commands strong margins in pharmaceutical formulations where USP-grade certification creates entry barriers. Acid modified starch dominates paper mill consumption due to established performance in surface sizing and coating operations. Cationic starch grows fastest among paper producers seeking improved retention and drainage efficiency.
Germany's Federal Institute for Risk Assessment (BfR) and the EU's REACH framework govern chemical modification processes and food-contact safety for starch derivatives. The EU Green Deal and Germany's Packaging Act accelerate biodegradable adhesive demand, directly expanding oxidized starch consumption in corrugated board manufacturing. KBA emissions standards indirectly shape textile processing applications by pushing water-based sizing agents over petrochemical alternatives. Stakeholders must monitor evolving BfR opinions on modified starch migration limits and EU taxonomy alignment for bio-based material investments.
Market Dynamics
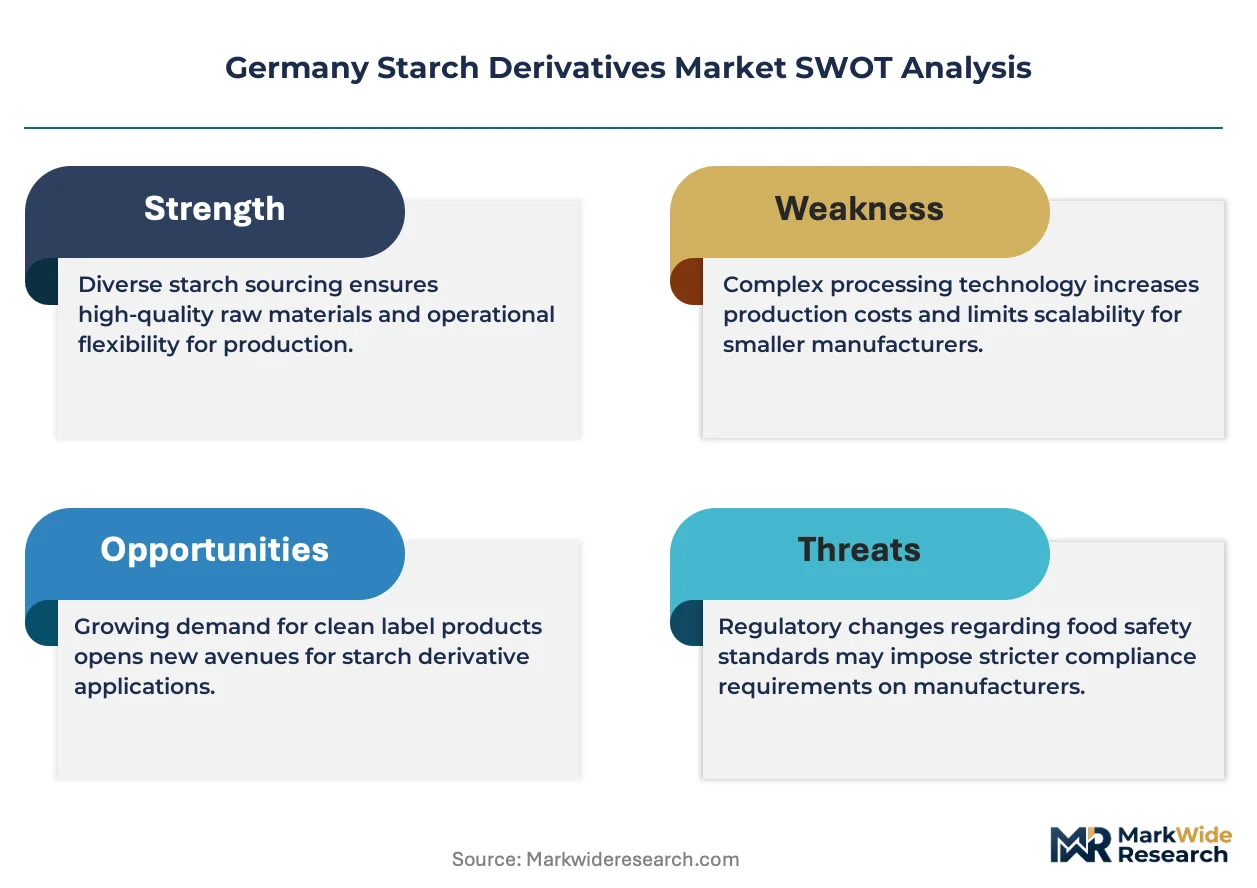
Enzymatic modification technology is splitting the Germany starch derivatives market into purity-tiered supply tiers, with pharmaceutical buyers demanding USP-grade hydroxypropyl starch while paper mills absorb commodity acid-modified grades from regional potato processors.
Growth Catalysts
- EU Green Deal packaging mandates:Biodegradability requirements under Germany's Packaging Act are pulling oxidized starch into corrugated adhesive formulations, displacing synthetic petrochemical binders.
- Clean-label food processing:Bavarian and North Rhine-Westphalian plants are retrofitting lines for enzymatically modified starches that meet EFSA purity thresholds without chemical residue labeling.
- Pharmaceutical formulation demand:USP-grade hydroxypropyl starch for tablet binders and controlled-release matrices is tightening supply allocation toward certified German processors.
Market Restraints
- Potato starch input volatility:Regional harvest fluctuations and energy-intensive extraction costs compress margins for non-integrated processors lacking captive potato supply.
- REACH registration burden:Chemical modification pathways face escalating ECHA compliance costs and extended safety-data timelines that deter mid-cap entrants from novel derivative development.
- Cellulose ether substitution:Paper mills in cost-sensitive segments are trialing CMC and HPMC alternatives for surface sizing where starch performance gaps narrow.
Strategic Opportunities
- Baden-Württemberg pharmaceutical cluster:Underpenetrated enzymatic modification capacity near Stuttgart and Mannheim offers proximity to Merck KGaA and Boehringer Ingelheim formulation demand.
- Dual carbon alignment:Germany's national climate targets channel federal funding toward bio-based adhesive R&D, accelerating oxidized starch validation for industrial packaging.
- Digital twin process control:Integration of inline viscosity monitoring with enzymatic reactors enables real-time DE adjustment for custom pharmaceutical contracts.
Industry Challenges
- Enzyme engineering talent scarcity:German universities produce insufficient biocatalysis PhDs to staff modification R&D labs, forcing processors to recruit from Dutch and Danish enzyme houses.
- USP certification timelines:Pharmaceutical-grade hydroxypropyl starch requires 18-24 month BfR migration studies and EDQM dossier preparation, locking working capital in pre-revenue qualification batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Starch Derivatives Market |
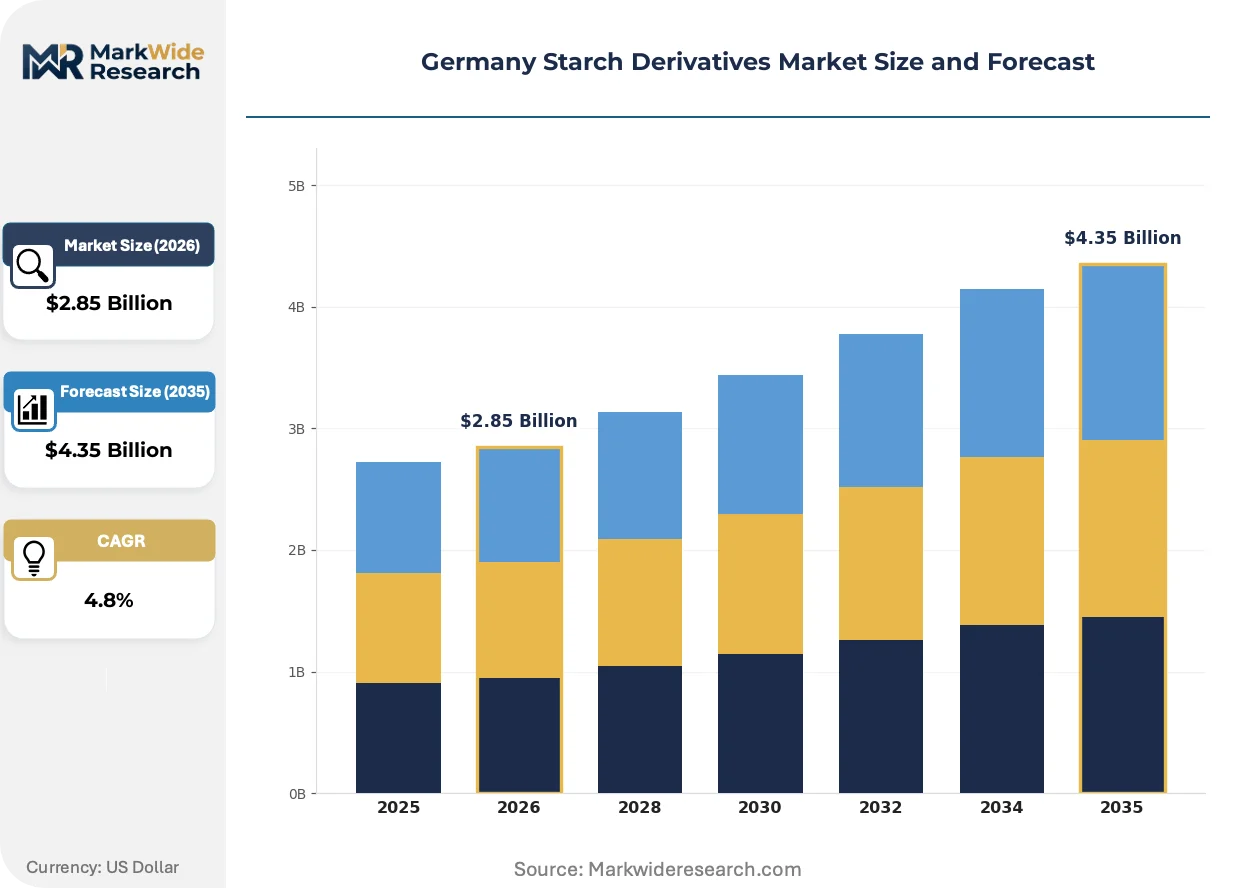
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.35 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acid Modified Starch, Hydroxypropyl Starch, Oxidized Starch, Cationic Starch, Enzymatically Modified Starch Application: Paper & Packaging, Textile Processing, Adhesives Manufacturing, Food Processing, Pharmaceutical Formulations End User Industry: Paper Mills, Textile Manufactories, Adhesive Producers, Food & Beverage Plants, Pharmaceutical Companies Form: Powder, Liquid, Granular, Paste |
| Companies Covered | Cargill Inc., Archer Daniels Midland Company, Ingredion Incorporated, Avebe, AGRANA Group, Roquette Frères, Tate & Lyle PLC, Südzucker AG, Emsland Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Starch Derivatives Market Shifts & Advancements
Process digitization and regulatory tightening are converging to reshape how German starch processors configure enzymatic modification lines and certify outputs for pharmaceutical and food-contact applications.
Inline near-infrared spectroscopy paired with adaptive enzyme dosing is automating dextrose equivalence control across continuous reactor trains. Pharmaceutical contract manufacturers in Hesse and Rhineland-Palatinate are adopting these systems to compress batch-to-batch variability below USP monograph thresholds. The technology is automating quality assurance labor, reducing headcount in QC labs while tightening certificate-of-analysis consistency for export-bound formulations.
Germany's Federal Institute for Risk Assessment is tightening migration limit opinions for modified starches in food-contact materials, directly impacting coating applications for dairy and confectionery packaging. Processors must now submit expanded analytical dossiers demonstrating bound-monomer stability under thermal stress. Acid-modified starch suppliers serving flexible packaging converters face the steepest compliance cost escalation, with some redirecting capacity toward non-food industrial adhesives.
Pharmaceutical procurement departments are consolidating supplier panels and demanding multi-year fixed-price contracts with indexed potato starch pass-throughs. This compresses spot-market participation for smaller enzymatic modifiers and favors processors with backward-integrated raw material security. The shift is most visible among Stuttgart-area generic drug manufacturers, who are awarding sole-source hydroxypropyl starch contracts to Emsland Group and Südzucker AG divisions with verified captive supply chains.
Germany Starch Derivatives Market Segmentation
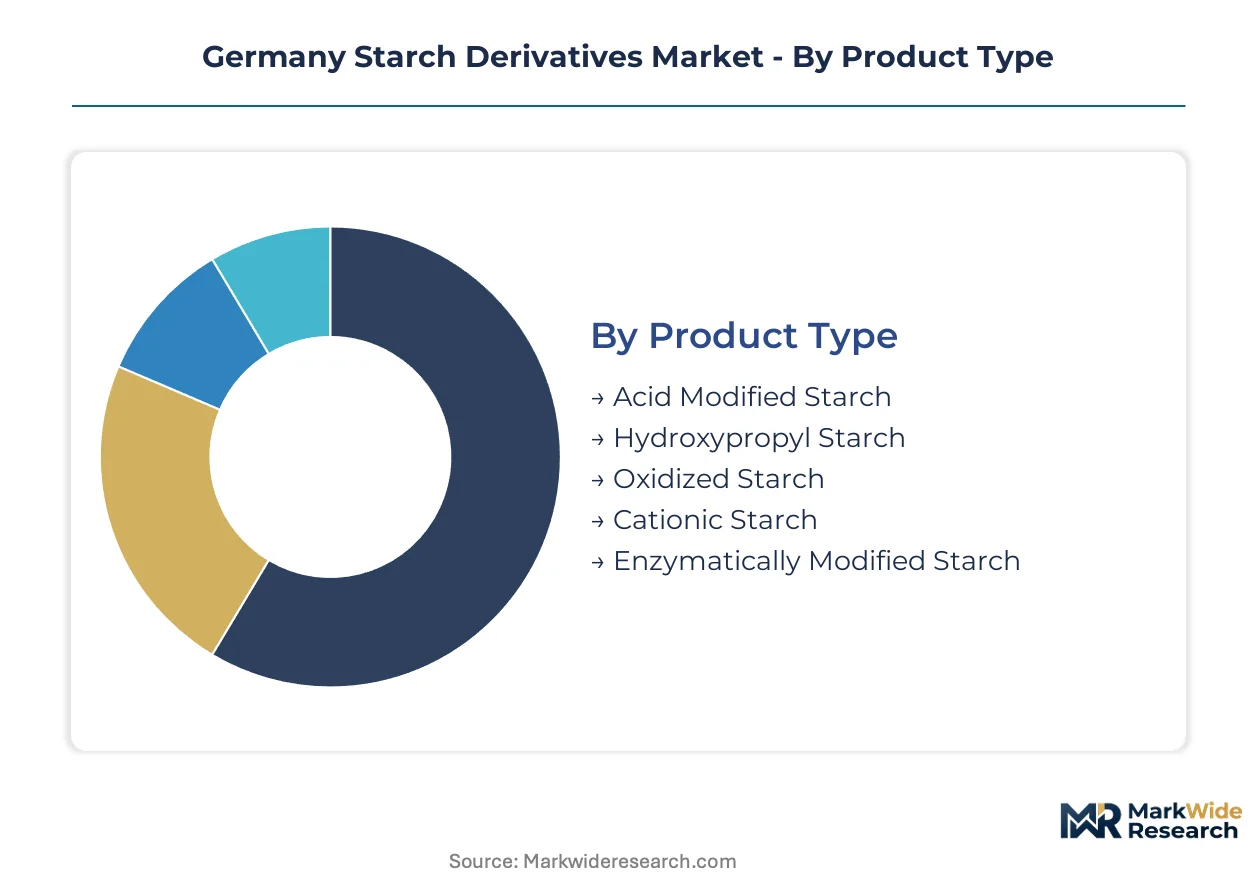
Segmentation in the Germany starch derivatives market exposes divergent capital requirements and margin profiles across modification technologies. Pharmaceutical-grade enzymatic lines demand precision bioreactor investments, while paper-grade acid modification runs on depreciated chemical assets.
Product Type:
Capital intensity peaks in enzymatic modification, where USP-grade certification requires stainless steel reactor trains and inline spectroscopy. Acid modification carries the lowest barrier to entry with established chemical infrastructure.
- Hydroxypropyl Starch:Etherified through propylene oxide treatment under alkaline conditions, achieving targeted molar substitution ratios for film-forming and binding functions. Demand concentrates in Baden-Württemberg pharmaceutical clusters serving Boehringer Ingelheim and Merck KGaA formulation lines, with USP-grade certification creating 18-24 month qualification timelines that lock working capital.
- Enzymatically Modified Starch:Produced via controlled amylase hydrolysis yielding specific dextrose equivalence profiles without chemical residue. Bavarian and North Rhine-Westphalian food processors are retrofitting lines for EFSA-compliant clean-label ingredients, driven by retailer mandates for simplified ingredient declarations.
- Acid Modified Starch:Acid-thinned starches for paper surface sizing and coating.
- Oxidized Starch:Bleached starches for corrugated board adhesives under Germany's Packaging Act biodegradability mandates.
- Cationic Starch:Positively charged derivatives for retention and drainage efficiency in paper mills.
Most installed capacity flows through acid modified starch. Expansion is steepest in enzymatically modified starch.
Application:
Paper and packaging applications absorb the highest tonnage volumes, while pharmaceutical formulations command premium pricing per kilogram. Cost tier separation between commodity adhesives and certified excipients drives divergent customer acquisition strategies.
- Pharmaceutical Formulations:Tablet binders, controlled-release matrices, and disintegrants requiring EDQM dossier submission and BfR migration validation. Stuttgart-area generic drug manufacturers are consolidating supplier panels toward sole-source contracts with verified captive supply chains.
- Food Processing:Clean-label thickeners and stabilizers for dairy, confectionery, and prepared meals. North Rhine-Westphalian plants are prioritizing enzymatic modification to eliminate chemical residue labeling requirements under EFSA thresholds.
- Paper & Packaging:Surface sizing and coating for graphic papers and corrugated board.
- Adhesives Manufacturing:Biodegradable binders for industrial packaging applications.
- Textile Processing:Warp sizing agents displacing petrochemical alternatives under KBA emissions standards.
Volume leadership sits with paper and packaging. Value expansion is climbing the fastest in pharmaceutical formulations.
End User Industry:
Customer concentration varies sharply: paper mills purchase through annual tenders, while pharmaceutical companies negotiate multi-year fixed-price contracts with indexed raw material pass-throughs.
- Pharmaceutical Companies:Formulation houses demanding certificate-of-analysis consistency and batch-to-batch variability below USP monograph thresholds. Procurement departments are compressing spot-market participation through consolidated supplier panels.
- Food & Beverage Plants:Clean-label retrofitting across Bavaria and North Rhine-Westphalia driven by retailer specification sheets. Emsland Group and Südzucker AG divisions compete on enzymatic modification expertise for specialized applications.
- Paper Mills:Cost-sensitive buyers trialing cellulose ether alternatives for surface sizing.
- Adhesive Producers:Corrugated board manufacturers under EU Green Deal packaging mandates.
- Textile Manufactories:Water-based sizing agent adopters responding to KBA emissions standards.
Contract stability is strongest with pharmaceutical companies. Spot market volatility concentrates among paper mills.
Form:
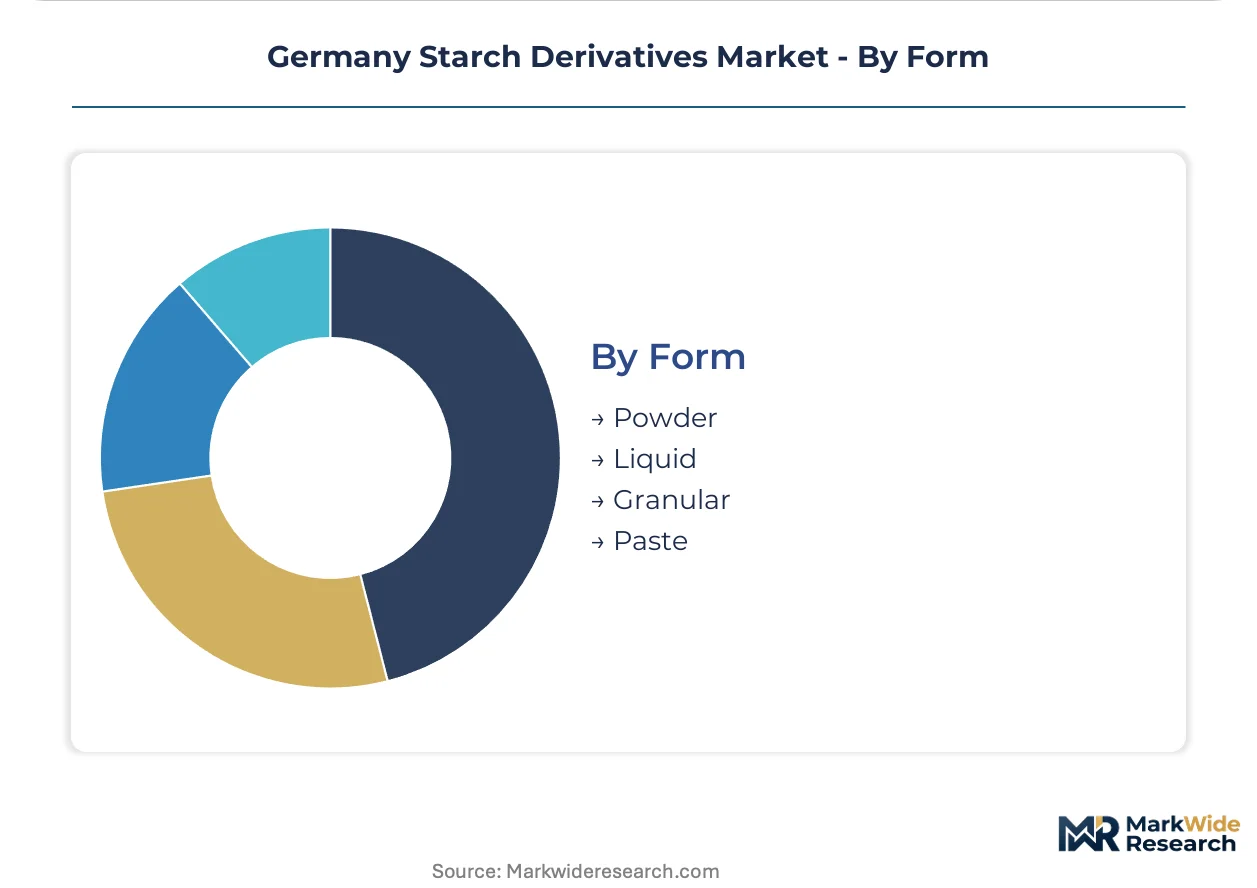
Physical form selection tracks downstream handling infrastructure and dissolution requirements. Powder dominates bulk shipments, while liquid and paste forms command premix premiums.
- Powder:Spray-dried derivatives for bulk handling and extended shelf stability. Paper mills and adhesive producers favor pneumatic conveying compatibility.
- Liquid:Pre-hydrated slurries for continuous process integration. Food processors in Bavaria prefer liquid enzymatic modifications for inline dosing.
- Granular:Agglomerated products for controlled dissolution in pharmaceutical wet granulation.
- Paste:High-viscosity preparations for immediate-use adhesive applications.
Most logistics infrastructure is configured for powder. Premix value capture is expanding most quickly in liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biocatalysis PhDs concentrate in Emsland and Lower Saxony university corridors, anchoring enzymatic modification R&D clusters that feed pharmaceutical and food-grade starch derivative production.
Bavaria
Food processing plants in Munich and Nuremberg retrofit lines for enzymatically modified starches meeting EFSA purity thresholds. Germany's Packaging Act enforces biodegradability mandates that pull oxidized starch into regional adhesive formulations. Clean-label ingredient sourcing accelerates across Bavarian dairy and confectionery packaging converters.
North Rhine-Westphalia
Industrial food manufacturers in Cologne and Düsseldorf prioritize enzymatic modifications eliminating chemical residue labeling requirements. REACH registration burdens escalate ECHA compliance costs for regional chemical modifiers. Paper mills along the Rhine corridor trial cellulose ether alternatives while maintaining acid-modified starch contracts for surface sizing.
Baden-Württemberg
Pharmaceutical formulation demand from Stuttgart-area generic drug manufacturers tightens supply allocation toward USP-grade hydroxypropyl starch. BfR migration studies and EDQM dossier preparation create 18-24 month qualification timelines. Merck KGaA and Boehringer Ingelheim procurement departments consolidate supplier panels toward sole-source contracts with verified captive supply chains.
Lower Saxony
Potato starch extraction infrastructure in Emsland anchors backward-integrated production networks. Regional harvest fluctuations and energy-intensive processing compress margins for non-integrated modifiers. Federal funding for bio-based adhesive R&D under Germany's national climate targets accelerates oxidized starch validation for industrial packaging applications.
Hesse
Pharmaceutical contract manufacturers in Frankfurt and Darmstadt adopt inline near-infrared spectroscopy with adaptive enzyme dosing. KBA emissions standards indirectly shape regional textile processing by pushing water-based sizing agents over petrochemical alternatives. Digital twin process control enables real-time dextrose equivalence adjustment for custom pharmaceutical contracts.
Germany Starch Derivatives Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade enzymatic modification, while regional potato processors and paper-grade chemical modifiers occupy commodity tiers. The vendor base stratifies across three functional archetypes: backward-integrated agricultural processors with captive starch supply, specialized enzymatic modification houses serving pharmaceutical certification requirements, and diversified ingredient conglomerates leveraging European distribution networks. Consolidation pressures intensify as procurement departments demand multi-year fixed-price contracts with indexed raw material pass-throughs, squeezing spot-market participation for smaller modifiers lacking verified supply chain security.
Within the backward-integrated processor archetype, Emsland Group and Südzucker AG exemplify regional players with upstream control over potato starch production. Cargill Inc. occupies a position representing diversified agricultural conglomerates with trans-European supply network leverage. These three anchors illustrate how pharmaceutical-grade certification requirements and clean-label food mandates favor processors with demonstrated captive supply chain verification and enzymatic modification expertise.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Avebe |
| AGRANA Group |
| Roquette Frères |
| Tate & Lyle PLC |
| Südzucker AG |
| Emsland Group |
| Others |
Supply & Pricing Matrix
Pharmaceutical procurement consolidation around multi-year fixed-price contracts with indexed potato starch pass-throughs is forcing supply chain reconfiguration toward backward-integrated processors, compressing spot-market liquidity and amplifying price premiums for certified enzymatic modifiers.
Pricing Analysis
Contract-plus-index pricing separates pharmaceutical-grade hydroxypropyl starch from commodity acid-modified grades for paper mills. USP certification timelines and BfR migration studies create 18-24 month qualification barriers that sustain premium capture for Emsland Group and Südzucker AG divisions. Cost compression in paper-grade segments intensifies as cellulose ether substitution trials narrow performance gaps. Paper mills exhibit highest price sensitivity through annual tender processes, while pharmaceutical companies absorb premium pricing for supply security.
Supply Chain Analysis
Germany's Packaging Act biodegradability mandates and EU Green Deal alignment are reshaping sourcing toward regional potato starch processors. Supply concentrates in Lower Saxony and Emsland extraction infrastructure, with secondary dependence on Dutch and Danish enzyme engineering talent. Raw material flows draw from regional potato harvests, energy-intensive wet-milling operations, and propylene oxide for etherification. Single-source vulnerability sits with enzymatic modification capacity near Baden-Württemberg pharmaceutical clusters. Distribution runs through bulk pneumatic handling for paper mills and specialized cold-chain logistics for pharmaceutical excipients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's starch derivatives market functions as a geographic-arbitrage play where regulatory stringency under REACH and BfR frameworks in Germany contrasts with more permissive chemical modification pathways in Eastern European jurisdictions, creating cost-differential opportunities for cross-border capacity positioning.
For Market Incumbents: Anticipate cellulose ether substitution pressure in paper surface sizing by deepening enzymatic modification expertise for pharmaceutical certification. Prioritize captive potato supply chain verification to defend contract renewals against spot-market undercutting. Invest in inline spectroscopy automation to compress batch-to-batch variability below USP thresholds and sustain sole-source positioning with Stuttgart-area generic manufacturers. For New Entrants and Emerging Players: Capture underpenetrated enzymatic modification capacity gaps near Mannheim and Heidelberg pharmaceutical clusters where Boehringer Ingelheim and Merck KGaA procurement departments seek supplier panel diversification. Target food-grade clean-label retrofit demand across Bavarian dairy packaging converters as the most penetrable entry segment. Lead with EFSA-compliant enzymatic processes eliminating chemical residue labeling requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with backward-integrated regional potato processors possessing verified pharmaceutical-grade certification infrastructure. Long-term viability across the analysis window hinges on bio-based adhesive validation under Germany's national climate targets. Monitor BfR opinion releases on modified starch migration limits as the critical inflection signal for compliance cost escalation and capacity redirection toward non-food industrial applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potato Starch Supply | Emsland Group anchors margin defense through captive regional harvest control against input volatility. |
| Pharmaceutical-Grade Certification Investment | EDQM dossier preparation and BfR migration studies lock 18-24 month barriers against commodity entrants. |
| Enzymatic Modification Capacity Expansion | Baden-Württemberg proximity to Merck KGaA and Boehringer Ingelheim tightens supply allocation toward certified processors. |
| Digital Twin Process Control Implementation | Inline near-infrared spectroscopy with adaptive enzyme dosing automates dextrose equivalence for pharmaceutical contracts. |
| Bio-Based Adhesive R&D Partnership | Federal funding under Germany's climate targets accelerates oxidized starch validation for corrugated board manufacturing. |
Research Methodology
Direct dialogue with starch modification plant managers, pharmaceutical procurement leads at Boehringer Ingelheim and Merck KGaA, paper mill technical directors along the Rhine corridor, and enzyme engineering specialists at Dutch and Danish biocatalysis houses grounded qualitative findings. Secondary validation drew from BfR migration opinion databases, ECHA REACH registration filings, EU Green Deal implementation trackers, and German Packaging Act compliance disclosures. Bottom-up capacity modeling triangulated against top-down demand segmentation across pharmaceutical, food processing, and paper applications.
Bottom-up volume builds aggregated individual facility capacity assessments across enzymatic and chemical modification lines, while top-down demand calibration tracked end-use consumption patterns through the projection horizon. Segmentation dimensions spanned modification technology, application purity tier, physical form, and regional production cluster. CAGRs derived from historical growth trajectory analysis adjusted for regulatory inflection points and pharmaceutical certification pipeline visibility. Forecast inputs incorporated potato harvest yield variability and energy cost pass-through elasticity in wet-milling operations.
Harvest shortfalls, BfR opinion tightening on migration limits, and cellulose ether substitution acceleration in cost-sensitive paper segments are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on certification timeline stability and pharmaceutical procurement contract duration patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market
Specialty Chemicals
Mequinol Market
Specialty Chemicals
GLDA Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Specialty Plasticizer Market
Specialty Chemicals
Sophorolipids Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Metominostrobin Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Global Specialty Fuel Additives Market