
 Marine Adhesives Market | 2026-2036
Marine Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Adhesives Market Intelligence
The European Union's REACH regulation is hardening the chemical formulation and market access requirements for global adhesive manufacturers. Sika AG leverages its extensive R&D in polyurethane and epoxy systems to meet these stringent standards. Henkel AG & Co. KGaA competes on a broad portfolio for both original equipment manufacturing and maintenance applications, while 3M Company differentiates with specialized bonding tapes and high-strength structural adhesives for the marine sector.
Marine adhesives are polymer-based bonding agents engineered for high performance in saline and high-moisture environments. These formulations must exhibit superior hydrolysis resistance and withstand constant vibration, UV exposure, and temperature extremes common in maritime operations. Epoxy and polyurethane adhesive types dominate structural bonding and hull repair applications due to their exceptional load-bearing capabilities. In contrast, flexible silicones and fast-curing cyanoacrylates find significant use among boat manufacturers for sealing and smaller component assembly tasks.
Product certification is governed by standards from organizations like the International Organization for Standardization (ISO) and specific maritime classification societies. In the United States, EPA guidelines on volatile organic compounds (VOCs) influence solvent-based adhesive formulations, driving innovation in water-based and 100% solids systems. Formulators must now balance the demand for faster curing times and greater flexibility with a complex and diverging set of environmental compliance mandates across key markets.
Market Dynamics
The marine adhesives market is shaped by the fundamental tension between stringent environmental regulations and the escalating performance requirements of modern maritime assets. This dynamic forces chemical formulators to innovate within tightening compliance boundaries set by authorities like the EU and EPA.
Growth Catalysts
- Offshore Platform Expansion:The development of deep-water oil, gas, and wind energy installations requires advanced epoxy and polyurethane adhesives capable of withstanding extreme pressures and corrosive saline environments, driving demand for high-performance structural bonding solutions.
- Shipbuilding Concentration:Large-scale vessel construction and repair activities, particularly in shipbuilding nations like South Korea and China, create concentrated demand for a high volume of adhesives for hull assembly, deck-to-hull joints, and interior fitting.
- Low-VOC Mandates:Regulations from bodies like the U.S. EPA limiting volatile organic compounds are spurring R&D and adoption of water-based, solvent-free, and 100% solids adhesive systems, opening new product categories for manufacturers.
Market Restraints
- Petrochemical Price Volatility:The cost of key raw materials for epoxy and polyurethane resins, such as bisphenol A (BPA) and methylene diphenyl diisocyanate (MDI), is tied to volatile petrochemical markets, creating pricing instability for adhesive manufacturers.
- Stringent Regulatory Compliance:The European Union's REACH regulation imposes extensive testing and registration requirements, increasing R&D costs and time-to-market for new adhesive formulations, acting as a barrier for non-compliant products.
- Performance Trade-offs:Formulators face a persistent technical challenge in developing adhesives that offer both faster curing times for operational efficiency and the low-VOC content required by environmental laws, often leading to compromises in one attribute.
Strategic Opportunities
- Leisure Craft and Yacht Segment:The growing market for recreational boating creates opportunities for specialized, aesthetically focused adhesives, including UV-stable sealants and flexible bonding agents for composite and teak components used in yacht manufacturing.
- Composite-to-Metal Bonding:The increasing use of lightweight composite materials alongside steel and aluminum in ship superstructures presents an opportunity for advanced hybrid adhesives designed to join dissimilar materials while managing thermal expansion.
- Bio-Based Formulations:Developing adhesives from renewable feedstocks offers a path to meet corporate sustainability goals and appeal to environmentally conscious customers, particularly in segments like passenger ferries and eco-tourism vessels.
Industry Challenges
- Complex Certification Pathways:Gaining approval for structural adhesives from maritime classification societies like DNV or the American Bureau of Shipping is a lengthy and costly process, delaying the introduction of new technologies to the market.
- Applicator Skill Shortages:The correct application of high-performance structural adhesives requires specialized training in surface preparation and bonding techniques. A lack of certified technicians can lead to application errors and bond failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Adhesives Market |
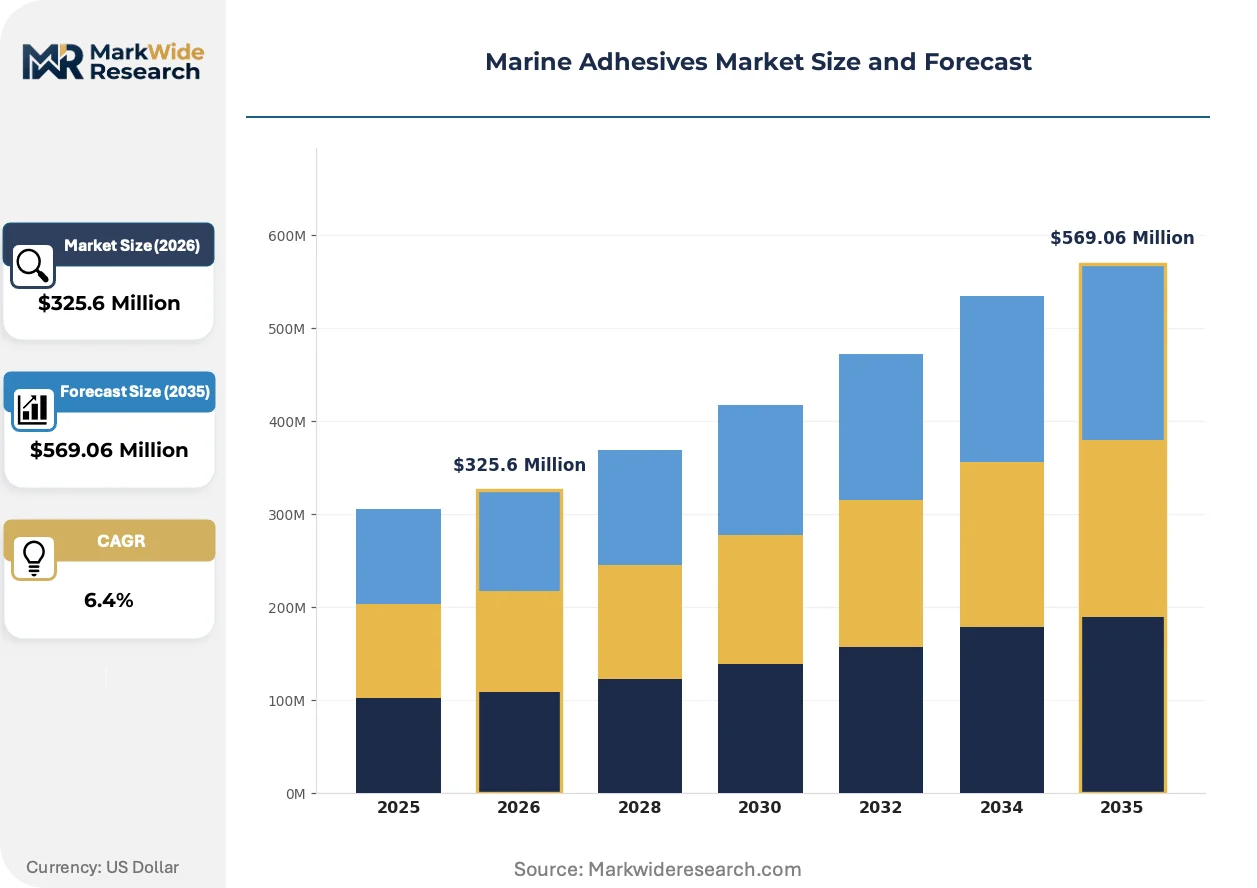
| Market Size in 2026 | $325.6 Million |
| Market Size in 2035 | $569.06 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Adhesive Type: Epoxy, Polyurethane, Silicone, Acrylic, Anaerobic, Cyanoacrylate Application: Hull Repair, Deck Bonding, Engine Assembly, Electrical Insulation, Sealant, Structural Bonding Technology: Waterproof, UV Resistant, Heat Resistant, Fast Curing, Flexible, High Strength End User: Shipyards, Boat Manufacturers, Offshore Platforms, Marine Equipment Providers |
| Companies Covered | Sika AG, Huntsman International, The Dow Chemical Company, Ashland Global Holdings Inc., Arkema Group, Henkel AG & Co. KGaA, H.B. Fuller Company, ITW Performance Polymers, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Adhesives Market Strategic Shifts & Innovations
Product development is increasingly focused on creating formulations that satisfy a dual mandate of enhanced environmental compliance and superior operational durability. This push is creating a new generation of adhesives designed for sustainability and performance throughout the entire vessel lifecycle.
Robotic adhesive dispensing systems provide a method for the precise and consistent application of bonding agents. Large-scale shipyards, especially in South Korea and China, are accelerating their adoption for new vessel construction to improve production speed. This technology is automating the bonding process, which reduces material waste and improves the structural integrity of seams compared to manual methods.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant regulatory development. It compels manufacturers and their maritime customers to disclose detailed data on the environmental impact of their products and supply chains. This primarily affects suppliers to the EU market, who must now invest in life-cycle assessments and develop adhesives with a lower carbon footprint to remain competitive.
A notable demand-side shift is occurring from time-based maintenance schedules to condition-based repair strategies for commercial vessels. This change disrupts traditional MRO procurement, favoring adhesives with documented long-term durability and resistance to environmental degradation. The trend is most pronounced within the commercial shipping and offshore energy sectors, where vessel and platform uptime is a critical financial metric.
Marine Adhesives Market Segmentation
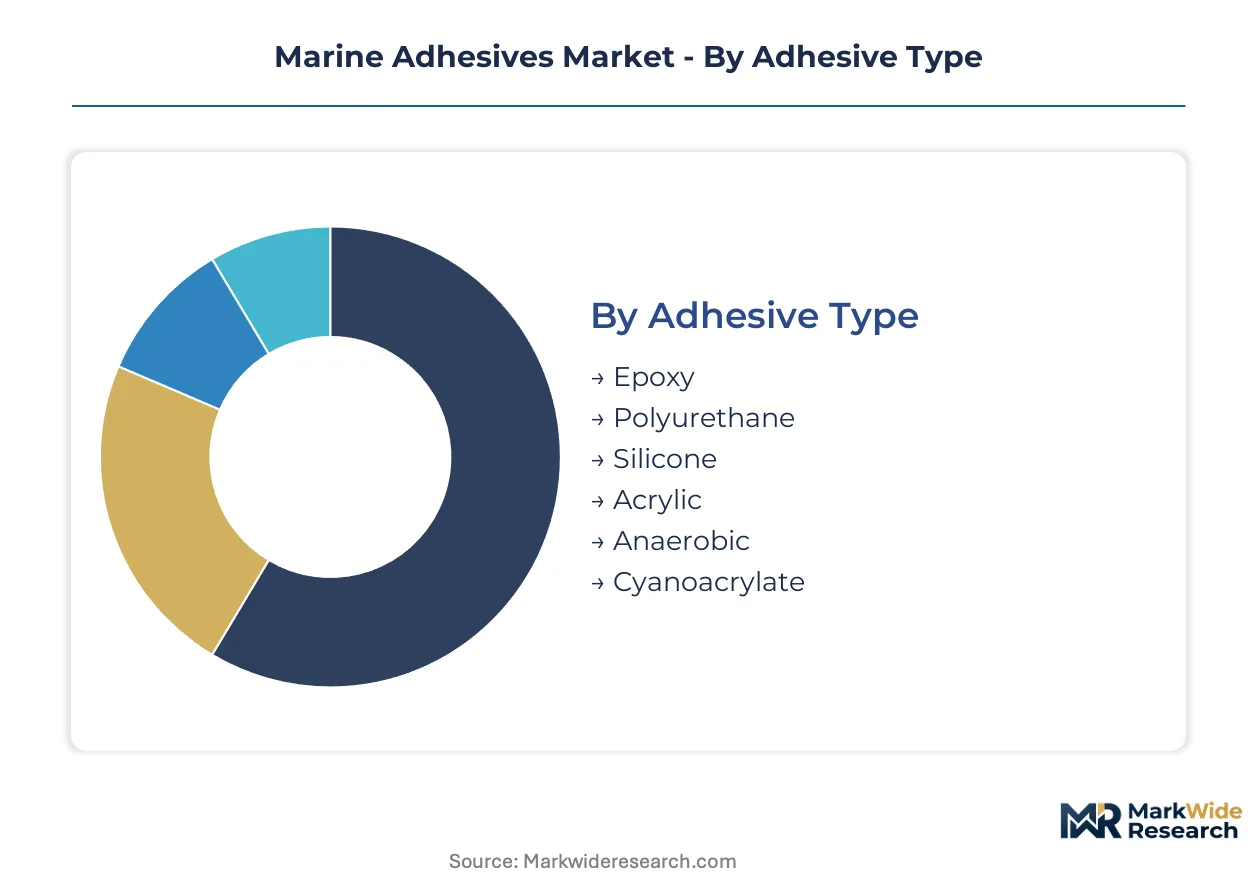
The marine adhesives market comprises diverse product types and applications, each tailored to specific environmental and structural demands within the maritime industry. Understanding these distinct segments is crucial for manufacturers to align product development with evolving performance requirements and regulatory landscapes. This granular analysis illuminates the varied commercial pathways available to participants.
Adhesive Type:
The development and production of specialized adhesive types involve significant capital investment in research and chemical synthesis processes. Formulators focus resources on advanced polymer systems for demanding marine environments. This focus ensures products meet stringent industry standards.
- Epoxy:These thermosetting polymers provide exceptional strength and chemical resistance, ideal for structural bonding in shipbuilding. Demand is high in South Korea for large-scale vessel construction.
- Polyurethane:Known for flexibility and strong adhesion, polyurethanes are critical for deck-to-hull joints. Offshore platforms in the North Sea rely on these systems for durability.
- Silicone:Offering excellent UV stability, silicone adhesives seal windows and hatches in leisure craft applications.
- Acrylic:Acrylic adhesives provide good adhesion, often used for interior panel bonding and trim attachment.
- Anaerobic:Anaerobic adhesives cure without oxygen, primarily for threadlocking metal fasteners in engines.
- Cyanoacrylate:Fast-curing cyanoacrylates are utilized for rapid, small-component assembly and quick repairs on boats.
Most installed capacity flows through Epoxy formulations. Expansion is steepest in Polyurethane systems.
Application:
The complexity and criticality of marine applications dictate performance requirements for adhesives. Structural integrity or harsh environmental exposure demands advanced bonding solutions. This drives specialized product development.
- Structural Bonding:This application demands adhesives with high tensile strength and fatigue resistance for ship construction. Offshore wind turbine foundations in the North Sea extensively utilize these solutions.
- Hull Repair:Adhesives for hull repair must withstand constant immersion and offer rapid curing for efficient dry-docking. Shipyards in Singapore use these products for commercial fleets.
- Deck Bonding:Securing deck materials requires flexible adhesives that accommodate thermal expansion and resist UV degradation.
- Engine Assembly:Adhesives in engine assembly seal critical components, preventing leaks and dampening vibrations.
- Electrical Insulation:Specialized adhesives protect electrical connections from moisture and corrosion, ensuring reliable operation.
- Sealant:Sealants provide watertight barriers around openings, preventing water ingress in all vessel types.
The largest volume segments include Hull Repair and Sealant. Rapid adoption characterizes Structural Bonding applications.
Technology:
Technological advancements in marine adhesives focus on specific performance attributes essential for maritime operations. Differentiation occurs through superior resistance or accelerated application. This enables adhesives to meet diverse operational needs.
- High Strength:Adhesives engineered for high strength provide superior load-bearing capabilities and structural integrity for vessel construction. Naval shipyards in the United States prioritize these materials.
- Waterproof:Waterproof adhesives maintain bond integrity and sealing under continuous immersion and hydrostatic pressure. This is critical for hull and deck sealing across commercial shipping.
- UV Resistant:Formulations resisting degradation from sunlight are vital for exterior applications like deck coatings.
- Heat Resistant:Adhesives with elevated temperature resistance are employed in engine rooms and near exhaust systems.
- Fast Curing:These technologies reduce assembly times and dry-dock periods, improving shipyard operational efficiency.
- Flexible:Flexible adhesives accommodate movement and vibration, preventing stress cracks in composite structures.
Demand for enhanced performance is driving innovation in High Strength and Fast Curing technologies.
End User:
End-user segments are differentiated by operational scale, vessel types, and performance demands. Each segment presents unique procurement patterns and technical requirements. This influences product tailoring and distribution strategies.
- Shipyards:These facilities are significant volume consumers, requiring adhesives for new vessel construction, maintenance, and repair. Large shipyards in China drive substantial demand.
- Offshore Platforms:Operators of offshore energy installations demand highly specialized adhesives enduring extreme pressures and corrosive environments. These are critical for integrity in the Gulf of Mexico.
- Boat Manufacturers:Producers of recreational vessels utilize adhesives for assembly, sealing, and cosmetic finishes, prioritizing ease of application.
- Marine Equipment Providers:Suppliers of marine components integrate adhesives into manufacturing for assembly and sealing processes.
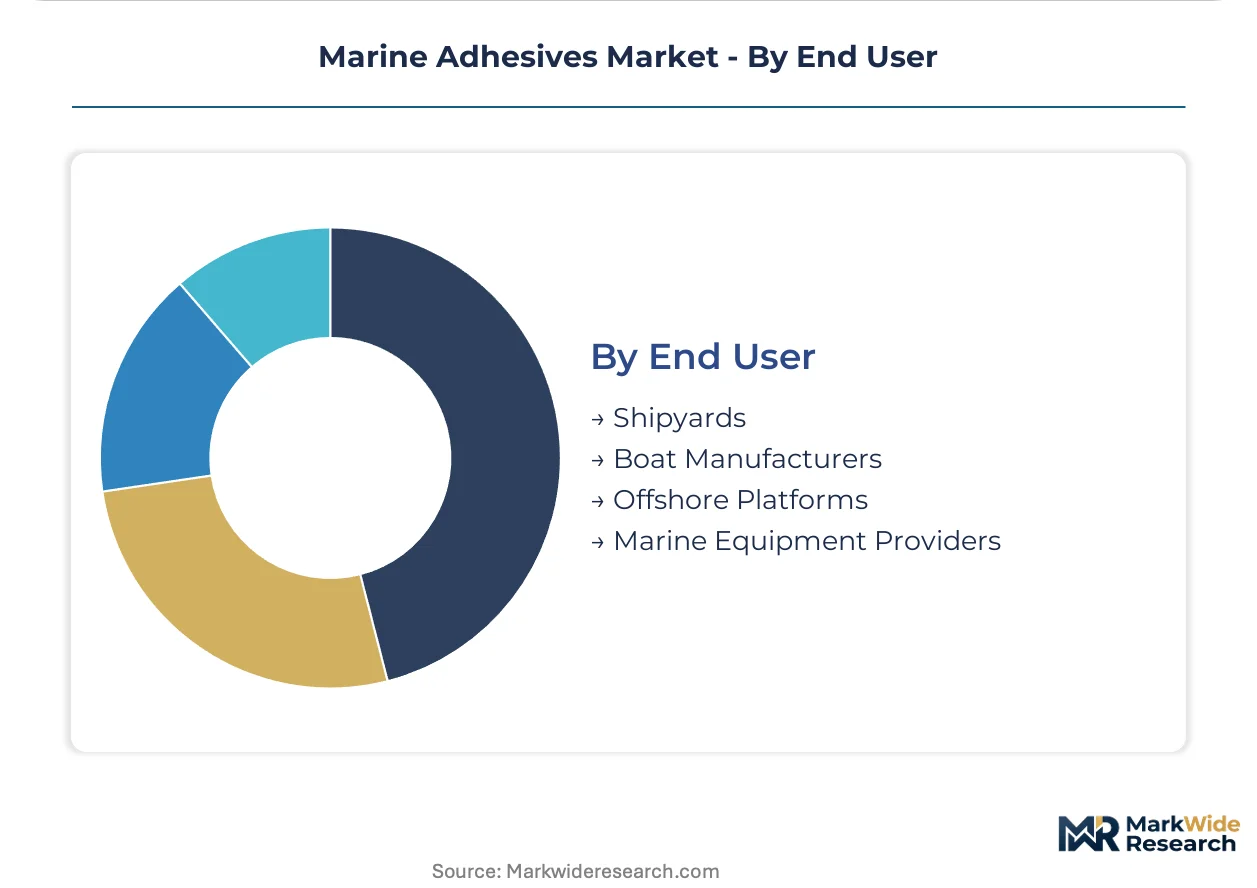
The largest procurement volumes originate from Shipyards. The Offshore Platforms segment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's skilled shipbuilding workforce anchors significant demand for marine adhesives, driven by large-scale vessel construction. This concentration of expertise and manufacturing capacity influences product development and supply chain dynamics across Asia. Other key regions also contribute substantially, each with distinct regulatory environments and industry focuses.
South Korea
Demand for high-performance structural adhesives stems from the nation's robust shipbuilding industry, particularly for LNG carriers and container ships. South Korean shipbuilders comply with ISO standards for material performance and application. Major shipyards in Ulsan and Geoje utilize advanced epoxy systems for hull assembly and critical structural joints.
China
China's vast shipbuilding capacity drives substantial procurement volumes for hull repair and new vessel construction. The Ministry of Ecology and Environment (MEE) mandates influence the formulation of low-VOC adhesive systems. Large state-owned shipyards in Shanghai and Dalian are adopting automated dispensing for increased efficiency in bonding processes.
United States
The United States naval shipyards prioritize high-strength and waterproof adhesives for critical vessel components and maintenance. EPA guidelines on volatile organic compounds significantly shape adhesive formulations for domestic use. Shipyards in Virginia and Mississippi focus on specialized bonding solutions for military and commercial fleets.
Germany
Germany's focus on offshore wind energy installations and specialized vessel construction creates a strong market for advanced polyurethane and epoxy systems. The European Union's REACH regulation dictates chemical formulation and market access for adhesive manufacturers. Hamburg's maritime cluster integrates specialized adhesive technologies into yacht building and ferry construction.
Singapore
Singapore's strategic position as a major shipping hub and MRO center generates consistent demand for fast-curing and durable adhesives for commercial fleet maintenance. The Maritime and Port Authority of Singapore (MPA) oversees compliance with international maritime standards. Ship repair facilities in Tuas and Jurong extensively use advanced sealants and structural bonding agents.
Marine Adhesives Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the marine adhesives market. The industry exhibits a tiered structure, where large chemical companies offer broad portfolios alongside niche players providing specialized solutions. Strategic archetypes include global chemical giants leveraging R&D, and regional manufacturers focusing on specific application segments. Dominant competitive moves involve portfolio diversification to meet varied regulatory demands and strategic partnerships to access new technologies.
Global chemical powerhouses like Henkel AG & Co. KGaA and 3M Company represent the diversified end of the market, offering comprehensive adhesive and sealant solutions for marine applications. These entities leverage extensive R&D capabilities to meet stringent environmental regulations such as the EU's REACH. Sika AG, a Swiss multinational, also occupies a strong position, specializing in high-performance bonding and sealing products for construction and industrial markets, including marine.
| Leading Market Players |
|---|
| Sika AG |
| Huntsman International |
| The Dow Chemical Company |
| Ashland Global Holdings Inc. |
| Arkema Group |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| ITW Performance Polymers |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Automated adhesive dispensing systems, increasingly adopted by large shipyards, simultaneously drive down application costs and concentrate specialized equipment supply within a few key manufacturing hubs.
Pricing Analysis
Bundled service and product offerings define the pricing landscape for high-performance marine adhesives. Project-based pricing is common for large structural bonding applications, while per-unit transactional models apply to sealant and repair products. Certification level from organizations like ISO and DNV, alongside customization for specific vessel types, drives price differentiation. Pricing pressure stems from petrochemical price volatility, particularly for epoxy and polyurethane raw materials. Commercial shipping operators and shipyards are highly price-sensitive for high-volume products, whereas naval shipyards prioritize performance over cost.
Supply Chain Analysis
Local content mandates, particularly in South Korea and China, are reshaping sourcing strategies for marine adhesive manufacturers. The supply chain for marine adhesives concentrates in Germany, the United States, and China. Raw material dependencies include bisphenol A (BPA) for epoxies and methylene diphenyl diisocyanate (MDI) for polyurethanes, alongside various polymer additives. Petrochemical price volatility represents a significant structural risk for manufacturers. Distribution runs through a mix of direct sales to large shipyards and a network of specialized marine distributors for smaller boat manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine adhesives market offers a geographic-arbitrage play, with stringent EU REACH regulations driving up R&D costs in Europe, while less restrictive markets like China enable faster product iteration.
For Market Incumbents: Deploy advanced R&D into bio-based formulations to meet evolving EU CSRD requirements. Consolidate market share through strategic acquisitions of specialized adhesive formulators in high-growth segments like composite-to-metal bonding. The threat of non-compliant products entering the market from regions with laxer regulations necessitates continuous innovation in compliant solutions.
For New Entrants and Emerging Players: Specialized hybrid adhesive technology presents a robust entry wedge for joining dissimilar materials in lightweight vessel construction. Target the leisure craft and yacht segment, where demand for aesthetically focused and UV-stable sealants is growing. A direct-to-manufacturer sales model, emphasizing application support for composite bonding, offers a viable go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional manufacturers lacking the scale for global regulatory compliance. Long-term viability hinges on companies demonstrating a clear path to sustainable, low-VOC formulations and advanced application support for robotic systems. The signal to watch is the increasing adoption rate of composite materials in commercial vessel superstructures.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and aligns with EU Green Deal objectives for marine suppliers. |
| Long-term Supply Agreement | Secures critical raw material inputs like MDI amidst petrochemical price volatility. |
| Capacity Expansion in Asia | Leverages concentrated shipbuilding demand in South Korea and China for high-volume production. |
| Joint Venture for Robotics Integration | Accelerates adoption of automated dispensing systems in global shipyards for efficiency gains. |
| Specialized Product Launch | Addresses the growing demand for composite-to-metal bonding solutions in advanced vessel designs. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and quantitative market data — were reconciled for this analysis. Interviews with R&D directors, shipyard procurement managers, and marine equipment providers informed qualitative insights. Secondary sources included ISO standards, EU ECHA reports, and national shipbuilding association data. A rigorous bottom-up and top-down triangulation process ensured data consistency and validity across all segments.
Historical data, cross-referenced against expert panel input, formed the basis of the analytical framework over the projection horizon. Segmentation dimensions modeled included adhesive type, application, technology, end-user, and regional regulatory compliance. Compound annual growth rates were derived through a proprietary algorithm considering market drivers and restraints. Key forecast inputs included vessel construction order books and petrochemical raw material price projections.
The model holds under current regulatory trajectories and anticipated technological advancements; deviation in global trade policies or unforeseen raw material supply shocks would shift the forecast. Forecasts reflect assumptions documented through extensive primary and secondary research. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
China Sealants Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Anti-Adhesion Products Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Ocular Adhesives and Sealants Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Adhesives and Sealants Market