
 Polyether Modified Silicone Market | 2026-2036
Polyether Modified Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
Polyether Modified Silicone Market Analytics
Specialized organosilicone synthesis expertise is collapsing across European and North American chemical engineering programs, tightening the talent pipeline for molecular design of polyether siloxane copolymers. Dow Inc. leverages captive siloxane feedstock and downstream formulation capabilities to sustain integrated supply positions in personal care and construction additives. Momentive Performance Materials anchors its competitiveness through proprietary hydrosilylation catalyst technology for precise polyether side-chain grafting. Wacker Chemie AG dominates European supply of textile-grade polyether modified silicones, operating dedicated emulsion plants in Germany.
Polyether modified silicone denotes a siloxane backbone with grafted polyoxyalkylene side chains, typically synthesized via hydrosilylation of Si-H functional polydimethylsiloxane with allyl-terminated polyethers to yield amphiphilic surfactants with surface tensions below 25 mN/m. These copolymers function primarily as defoamers, wetting agents, and emulsifiers in aqueous industrial systems where conventional hydrocarbon surfactants fail. Water-based technology leads volume consumption as environmental compliance hardens, while solvent-based formulations retain niche positions in high-performance coatings requiring rapid evaporation. Emulsion-grade products command margin premiums in personal care applications where sensory properties determine formulation value, whereas antifoam concentrates compete primarily on unit economics in pulp and paper processing.
REACH registration requirements in Europe compel full toxicological dossiers for polyether siloxane imports above one tonne annually, elevating compliance costs for Asian exporters. China's MEE enforces GB standards limiting volatile organic compound content in industrial coatings, directly accelerating water-based polyether silicone substitution for solvent-borne alternatives. The EU F-Gas Regulation indirectly supports silicone surfactant demand by restricting fluorinated wetting agents in coating applications. Stakeholders must monitor regulatory divergence between European hazard classification schemes and China's emerging chemical substance inventory requirements, as misaligned compliance timelines threaten cross-border product registration strategies.
Market Dynamics
Water-based emulsion technology is displacing solvent-borne systems as REACH and China's GB standards on volatile organic compounds harden compliance requirements across industrial coatings and personal care formulations.
Growth Catalysts
- MFDS Cosmetic Safety Guidelines:South Korean formulators are expanding procurement of water-based polyether silicone emulsions as the national pharmaceutical regulator tightens ingredient disclosure and safety testing protocols for rinse-off and leave-on products.
- Yangtze River Delta Manufacturing Cluster:Concentrated silicone production infrastructure in eastern China serves integrated textile and construction additive demand, reducing logistics costs and enabling just-in-time emulsion supply to downstream compounders.
- Hydrosilylation Process Refinement:Advances in platinum-catalyzed grafting precision allow tighter control over polyether side-chain distribution, yielding surfactants with sub-25 mN/m surface tension for high-performance wetting applications.
Market Restraints
- Siloxane Feedstock Concentration:Captive production of dimethylsiloxane monomers by integrated chemical conglomerates limits independent emulsion producer access to cost-competitive raw material supply.
- REACH Registration Burden:Full toxicological dossier requirements for polyether siloxane imports above one tonne annually elevate compliance costs and extend market entry timelines for Asian exporters serving European industrial customers.
- Fluorosurfactant Substitution Threat:Perfluorinated wetting agents retain performance advantages in extreme chemical environments despite EU F-Gas Regulation restrictions, preserving niche demand in semiconductor and aerospace coating applications.
Strategic Opportunities
- India Industrial Coatings Expansion:BIS implementation of VOC content limits in architectural and protective coatings creates regulatory tailwind for water-based polyether silicone defoamers and leveling agents in Maharashtra and Gujarat manufacturing corridors.
- Personal Care Sensorial Differentiation:Emulsion-grade polyether modified silicones command formulation premiums in K-beauty and prestige skincare where spreadability, dry-down time, and non-tacky after-feel determine consumer preference and brand positioning.
- Antifoam Concentrate Unit Economics:Pulp and paper processing mills in Brazil and Indonesia present volume expansion potential for high-active-content silicone defoamers competing on dosing efficiency against mineral oil alternatives.
Industry Challenges
- Organosilicone Synthesis Expertise Collapse:European and North American chemical engineering programs have shuttered specialized siloxane copolymer curricula, constricting the talent pipeline for molecular design and process scale-up functions.
- Cross-Border Registration Timeline Misalignment:Divergent compliance schedules between European hazard classification schemes and China's emerging chemical substance inventory requirements threaten product registration strategies for multinational suppliers.
- Emulsion Stability Capital Requirements:High-shear processing equipment and sterile manufacturing environments for personal care-grade emulsions demand significant capital expenditure that mid-scale producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyether Modified Silicone Market |
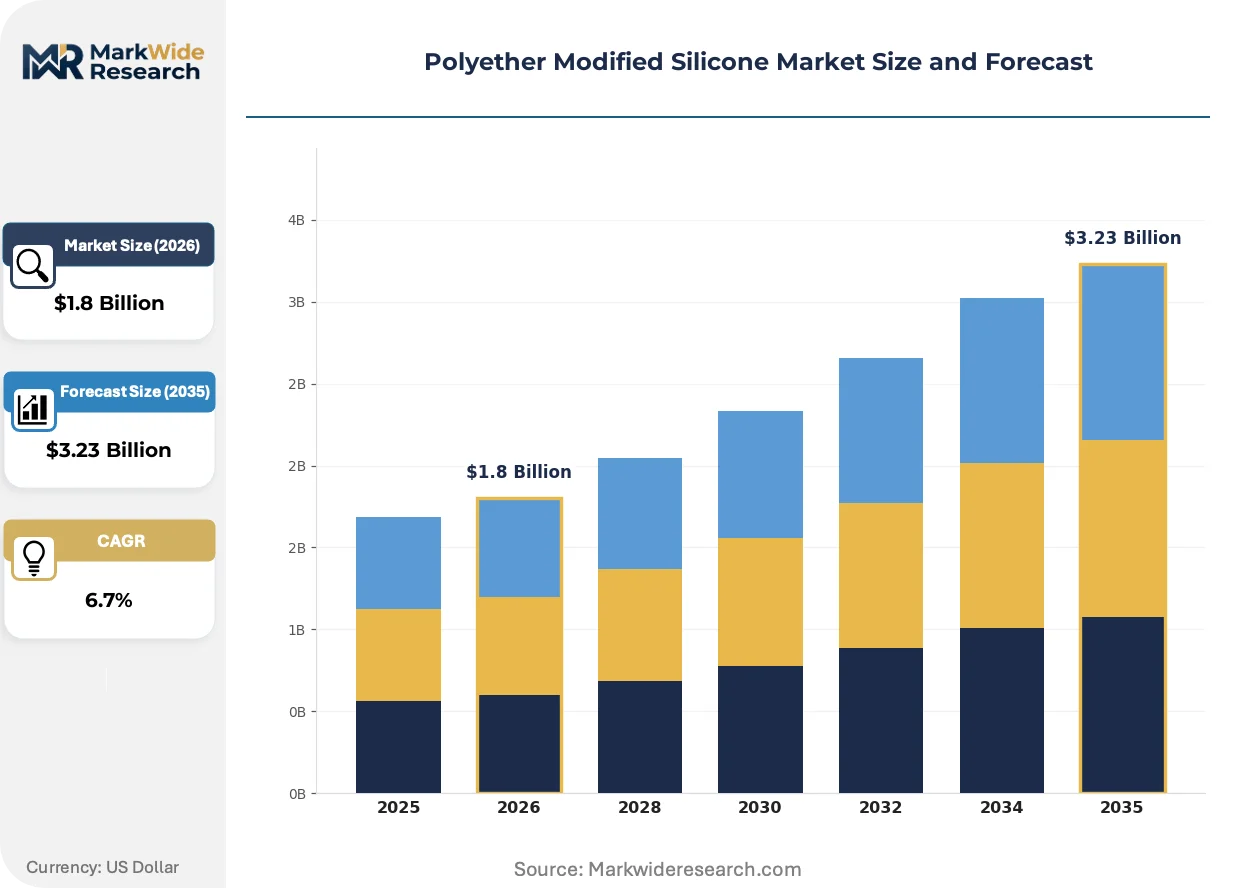
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Antifoams, Coatings, Additives Application: Textiles, Personal Care, Construction, Automotive End User: Manufacturers, Distributors, Retailers, Consumers Technology: Solvent-Based, Water-Based, Dry Film, Liquid |
| Companies Covered | Wacker Chemie AG, Shin-Etsu Chemical, Momentive Performance Materials, Dow Inc., Elkem ASA, Evonik Industries, KCC Corporation, Siltech Corporation, Zhejiang Runhe Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyether Modified Silicone Market Evolving Landscape
Formulation chemistry is pivoting toward aqueous delivery systems as environmental compliance hardens, while precision synthesis methods enable molecular architectures optimized for specific surface-active functions.
Silicone-polyether block copolymers with controlled hydrophilic-lipophilic balance are displacing conventional hydrocarbon surfactants in waterborne industrial coatings. Automotive OEM paint shops in Germany and Japan are adopting these materials for substrate wetting and crater control. The technology is displacing legacy fluorinated additives in applications where moderate chemical resistance suffices, compressing addressable market for perfluorinated chemistry suppliers.
China's MEE enforcement of GB standards limiting volatile organic compound content in industrial coatings is accelerating water-based polyether silicone substitution. Domestic coating manufacturers in the Pearl River Delta are reformulating solvent-borne systems to meet compliance deadlines. Construction and protective coatings segments are most affected, with formulators investing in emulsion compatibility testing and drying time optimization.
Specification-driven procurement is consolidating supplier relationships among personal care multinationals. Large beauty brands in South Korea and France are reducing their emulsion vendor bases from multiple regional suppliers to two or three strategic partners with integrated regulatory support. This concentration is most visible in premium skincare, where formulation stability data and toxicological dossier completeness determine qualification timelines and contract renewal decisions.
Polyether Modified Silicone Market Segmentation
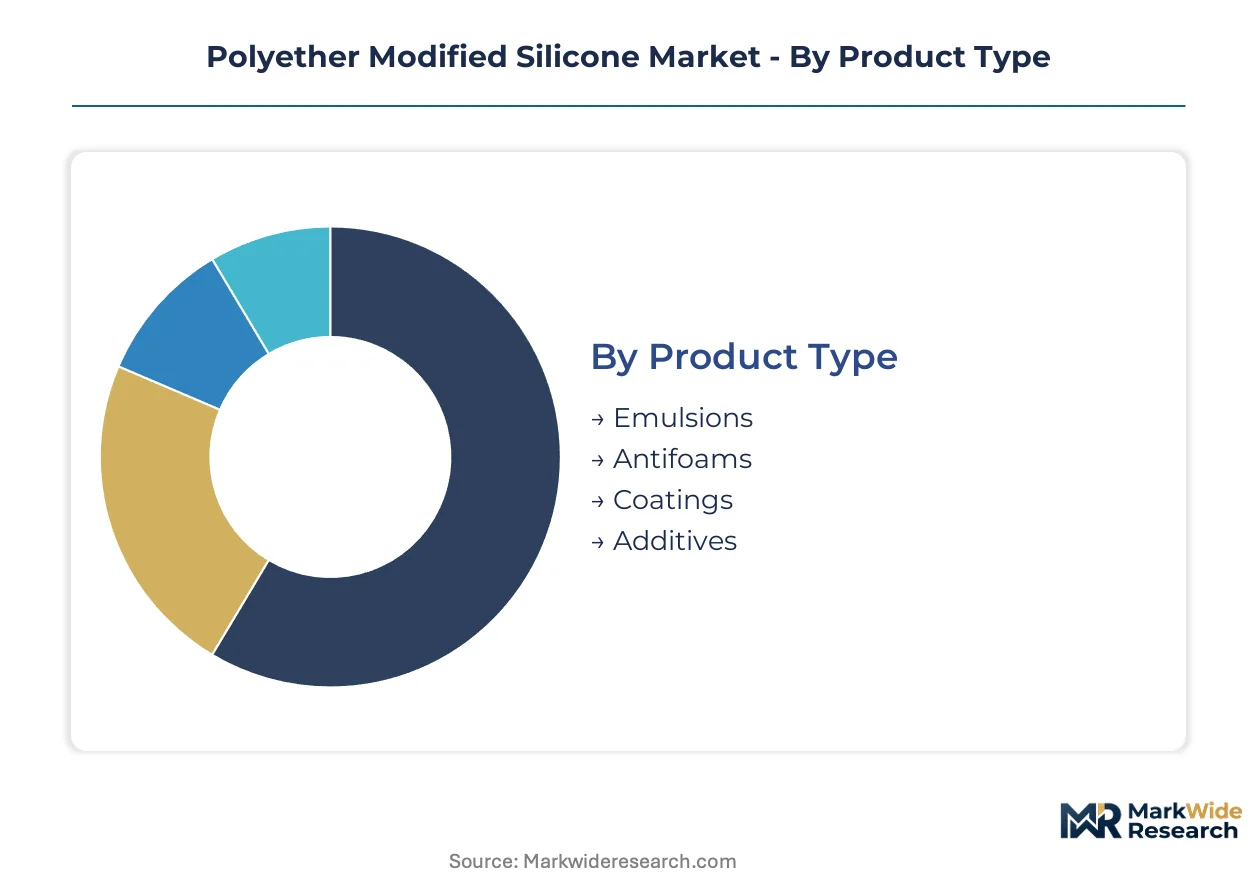
Polyether modified silicone markets fragment across formulation chemistry, application performance requirements, and supply chain position. Understanding these segment boundaries clarifies where substitution pressure concentrates and where technical differentiation sustains margin.
Product Type:
Antifoam concentrates face the strongest substitution threat from mineral oil and polyglycol alternatives in cost-sensitive industrial processing, while emulsion-grade products defend position through sensory performance.
- Emulsions:Aqueous dispersions with particle sizes below 500 nanometers deliver controlled spreadability and dry-down in cosmetic formulations. South Korean personal care manufacturers are expanding procurement as MFDS cosmetic safety guidelines tighten ingredient disclosure requirements. These products command formulation premiums where sensory properties determine brand positioning.
- Antifoams:High-active-content silicone concentrates, typically 10-30% dispersed in carrier fluids, provide foam control in pulp processing and wastewater treatment. Pulp and paper mills in Brazil and Indonesia evaluate dosing efficiency against mineral oil alternatives. Unit economics dominate procurement decisions in this segment.
- Coatings:Surface-active additives for substrate wetting and crater control in waterborne industrial paint systems. Automotive OEM paint shops in Germany and Japan specify these materials for appearance-critical applications.
- Additives:Functional modifiers for construction sealants and textile finishing baths, including leveling agents and flow control aids. Yangtze River Delta manufacturing clusters consume significant volumes for integrated textile and construction supply.
Antifoam concentrates anchor the volume base while emulsions gain share at the steepest rate.
Application:
Personal care applications concentrate margin capture through sensory differentiation, whereas textile processing competes on throughput efficiency and chemical compatibility.
- Textiles:Polyether silicones function as softening agents and sewing lubricants in synthetic fiber finishing. China's Yangtze River Delta manufacturing infrastructure serves integrated demand from domestic textile producers. REACH compliance costs for European imports are redirecting some procurement toward regional suppliers.
- Personal Care:Emulsion-grade products deliver spreadability, dry-down time, and non-tacky after-feel in skincare and haircare formulations. Large beauty brands in South Korea and France are consolidating vendor bases from multiple regional suppliers to strategic partners with complete toxicological dossiers.
- Construction:Additives for sealants, adhesives, and protective coatings where water-based technology is displacing solvent-borne systems. China's MEE enforcement of GB standards on volatile organic compounds is accelerating this transition.
- Automotive:OEM paint specifications for substrate wetting and appearance control in waterborne basecoat and clearcoat systems. German and Japanese automotive coating operations specify silicone-polyether block copolymers for crater resistance.
Textile processing anchors the volume base while personal care gains share at the steepest rate.
End User:
Manufacturer procurement concentrates technical specification power, while distributor relationships determine market access for mid-scale emulsion producers.
- Manufacturers:Integrated chemical companies and formulators with in-house compounding capabilities purchase antifoam concentrates and raw silicone fluids for downstream processing. Dow Inc. and Momentive Performance Materials serve this tier with captive siloxane feedstock positions.
- Distributors:Regional chemical distributors stock standard-grade emulsions and antifoams for just-in-time supply to smaller compounders. Wacker Chemie AG operates dedicated distribution for European textile-grade products.
- Retailers:Limited direct engagement; primarily indirect through contract manufacturers supplying finished personal care and homecare products.
- Consumers:End-product users with no direct procurement relationship to polyether silicone suppliers; demand signals transmit through brand owner formulation specifications.
Manufacturer direct purchasing anchors the volume base while distributor channels gain share at the steepest rate.
Technology:
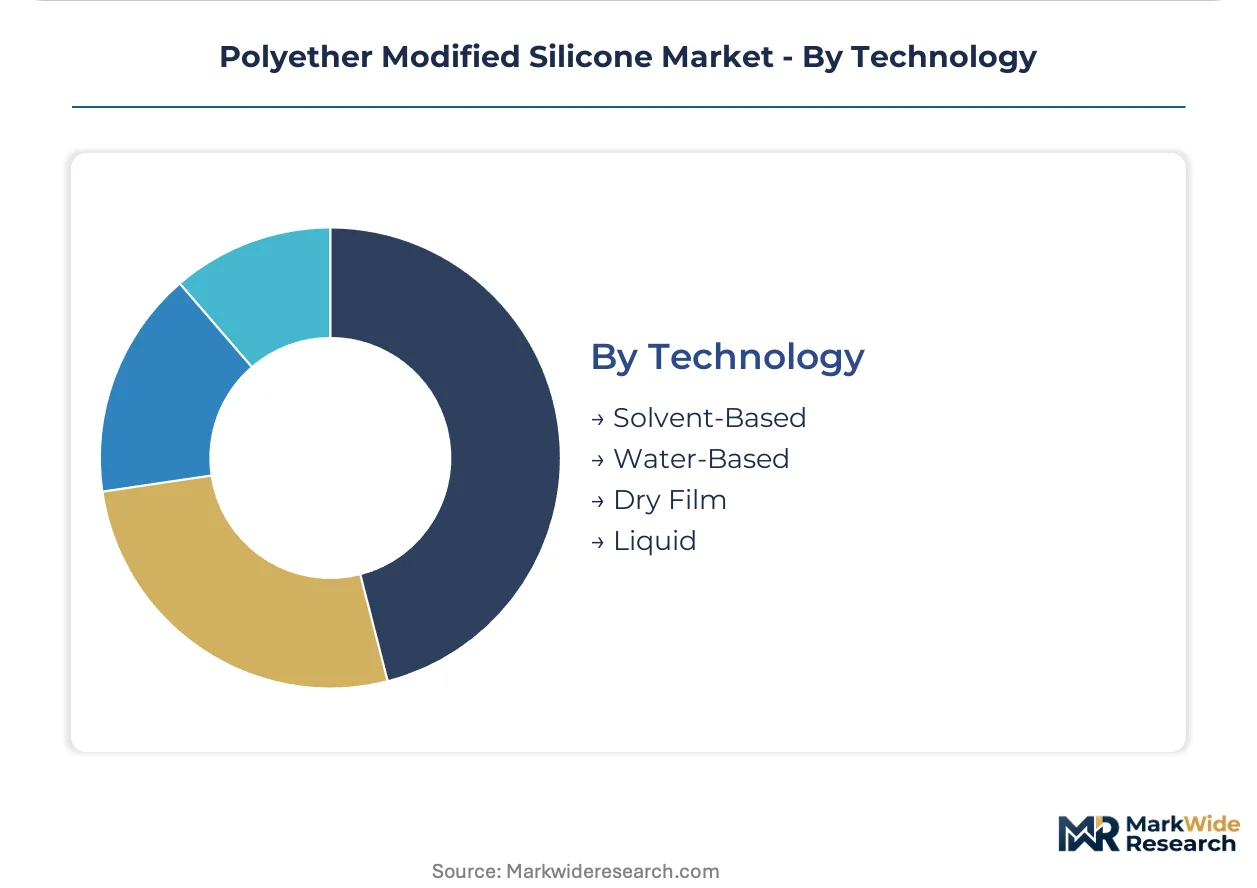
Water-based systems are climbing the fastest as environmental compliance hardens, while solvent-based formulations retain defensive positions in performance coatings.
- Solvent-Based:Solutions in hydrocarbon or oxygenated carriers providing rapid evaporation and film formation. Niche demand persists in high-performance coatings where drying speed determines line productivity.
- Water-Based:Aqueous emulsions and dispersions meeting tightening VOC regulations across industrial coatings and personal care. China's GB standards and REACH requirements in Europe are accelerating substitution for solvent-borne alternatives.
- Dry Film:Solid or powder forms for specific textile and construction applications requiring extended shelf stability or precise dosing.
- Liquid:Neat silicone-polyether copolymers for direct incorporation or further dilution by downstream formulators.
Solvent-based technology anchors the volume base while water-based systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors the dominant geography through GB standards enforcement on volatile organic compounds, redirecting industrial coatings demand toward water-based polyether silicone systems across multiple manufacturing corridors.
China
Yangtze River Delta textile mills and construction additive compounders consume significant polyether silicone volumes for softening agents and sealant modifiers. MEE enforcement of GB standards on VOC content accelerates solvent-to-water formulation transitions. Pearl River Delta coating manufacturers are reformulating architectural and protective systems to meet compliance deadlines.
Germany
Automotive OEM paint shops specify silicone-polyether block copolymers for substrate wetting and crater resistance in waterborne basecoat applications. EU F-Gas Regulation restricts fluorinated wetting agents, opening substitution opportunities for silicone surfactants. Wacker Chemie operates dedicated emulsion plants serving European textile-grade demand from integrated facilities.
South Korea
Personal care formulators expand procurement of water-based polyether silicone emulsions as MFDS cosmetic safety guidelines tighten ingredient disclosure protocols for rinse-off and leave-on products. Large beauty brands consolidate vendor bases from multiple regional suppliers to strategic partners with complete toxicological dossiers. Seoul Capital Area manufacturing clusters serve K-beauty export production.
United States
Construction and coatings compounders face EPA VOC regulations driving water-based system adoption in architectural applications. Dow Inc. leverages captive siloxane feedstock positions to serve personal care and construction additive demand. Gulf Coast chemical manufacturing infrastructure supports integrated silicone fluid production for downstream emulsion processing.
India
BIS implementation of VOC content limits in architectural and protective coatings creates regulatory tailwind for water-based polyether silicone defoamers. Maharashtra and Gujarat manufacturing corridors present volume expansion potential for industrial coating additives. Domestic textile processing in Tamil Nadu consumes emulsion-grade products for synthetic fiber finishing applications.
Polyether Modified Silicone Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated chemical conglomerates compete against specialized emulsion producers. The market consolidates around siloxane feedstock access and downstream formulation capabilities rather than pure scale. Three archetypes dominate: captive siloxane producers with backward integration, specialized hydrosilylation technology licensors, and regional emulsion compounders serving just-in-time distributor channels. Competitive moves concentrate on strategic partnerships for regulatory dossier sharing and capacity expansion in high-compliance jurisdictions.
Within the integrated chemical conglomerate tier, Dow Inc. and Shin-Etsu Chemical occupy positions defined by captive dimethylsiloxane monomer supply and downstream emulsion formulation infrastructure. Wacker Chemie AG exemplifies the European specialist archetype with dedicated textile-grade production assets. Momentive Performance Materials represents technology-led positioning through proprietary catalyst systems for polyether side-chain grafting precision.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Shin-Etsu Chemical |
| Momentive Performance Materials |
| Dow Inc. |
| Elkem ASA |
| Evonik Industries |
| KCC Corporation |
| Siltech Corporation |
| Zhejiang Runhe Chemical |
| Others |
Value Network & Pricing Analysis
Water-based emulsion substitution for solvent-borne systems simultaneously concentrates supply geography in China's Yangtze River Delta manufacturing corridor and compresses margin structures for mid-scale compounders lacking captive siloxane feedstock positions. This input transition elevates pricing power for integrated producers while fragmenting procurement leverage among independent formulators.
Pricing Analysis
Price spreads between European and Asian supply widen as REACH registration costs embed into landed pricing for non-integrated exporters. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification completeness and sensory performance grade. Pricing pressure stems from mineral oil antifoam alternatives in pulp processing applications. Pulp and paper mills exhibit highest price sensitivity, while personal care formulators prioritize sensory attributes over unit cost.
Supply Chain Analysis
Inventory strategy favors just-in-time emulsion delivery for textile and construction compounders in the Yangtze River Delta, whereas personal care manufacturers maintain strategic stockpiles of certified-grade materials to ensure formulation continuity. Supply concentrates in China, Germany, and Japan, drawing from dimethylsiloxane monomers, allyl-terminated polyethers, and platinum catalyst feedstocks. Single-source vulnerability runs through hydrosilylation catalyst supply. Distribution runs through regional chemical distributors serving mid-scale compounders and direct manufacturer relationships for integrated formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large beauty brands and automotive OEMs, with vendor base consolidation from multiple regional suppliers to strategic partners reshaping procurement leverage across personal care and coatings segments.
For Market Incumbents: Secure captive siloxane feedstock positions through backward integration or long-term offtake agreements to defend margin compression from integrated competitors. Invest in MEE-compliant water-based emulsion capacity additions in China's Yangtze River Delta manufacturing corridor. Prioritize toxicological dossier completeness to capture specification-driven procurement consolidation among South Korean and French personal care multinationals. For New Entrants and Emerging Players: Regulatory dossier management services for mid-scale Asian exporters facing REACH registration burdens represent a service-layer gap where incumbents under-serve. Target India's Maharashtra and Gujarat manufacturing corridors for water-based defoamer supply as BIS VOC limits take effect. Pursue distributor partnerships with established regional chemical distributors rather than direct manufacturer competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European specialty chemical producers lacking hydrosilylation catalyst technology. Long-term viability hinges on water-based formulation transition completion and regulatory compliance infrastructure depth. Acquisition candidates with integrated emulsion plants in high-compliance jurisdictions offer defensive positioning. Watch for MFDS cosmetic safety guideline enforcement intensity as inflection indicator for personal care segment margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstock | Dow Inc. and Shin-Etsu Chemical leverage captive monomer supply to compress independent compounder margins. |
| Water-Based Emulsion Capacity Expansion | Wacker Chemie AG's dedicated German plants capture EU F-Gas Regulation-driven fluorosurfactant substitution demand. |
| Regulatory Dossier Sharing Partnerships | Joint toxicological data pools reduce REACH compliance costs for Asian exporters serving European industrial customers. |
| Long-Term Supply Agreements with Textile Mills | Yangtze River Delta compounders lock in volume commitments from domestic synthetic fiber producers. |
| Hydrosilylation Catalyst Technology Licensing | Momentive Performance Materials monetizes proprietary grafting precision for sub-25 mN/m surface tension specifications. |
Research Methodology
The analysis maps antifoam concentrates, emulsion-grade products, coatings additives, and textile softening agents, each validated through technical directors at silicone emulsion compounders, procurement leads at personal care multinationals, plant managers at Yangtze River Delta textile finishing operations, and regulatory affairs specialists navigating REACH and GB standard compliance. Primary interview insights triangulate against customs trade data, ECHA registration dossiers, SEC 10-K filings from integrated chemical conglomerates, and MEE enforcement notices on VOC content limits. Bottom-up segment sizing reconciles with top-down market value estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, application performance tier, technology chemistry, and geographic regulatory cluster dimensions. CAGRs derive from segment-level growth rate synthesis. Key forecast inputs include MEE enforcement trajectory for GB standards, MFDS cosmetic safety guideline implementation pace, and pulp and paper industry capacity expansion in Brazil and Indonesia.
Underlying assumptions cover regulatory compliance timeline adherence, raw material cost stability, and hydrosilylation catalyst supply continuity, with deviation risk concentrated in cross-border registration timeline misalignment between European and Chinese chemical inventory requirements. Forecasts reflect these documented conditions. Revision becomes warranted when BIS VOC limit enforcement intensity or EU F-Gas Regulation scope expansion crosses thresholds that materially alter substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
Middle East and Africa Amino Acids Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Polyphosphate Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Precipitated Barium Sulfate Market
Specialty Chemicals
Distarch Phosphate Market
Specialty Chemicals
Rosin Market
Specialty Chemicals
Global Acrylic Processing Aid Market