
 Niacin and Niacinamide Market | 2026-2036
Niacin and Niacinamide Market Size, Share, and Industry Trends Forecast 2026-2036
Niacin and Niacinamide Market Intelligence
The distribution structure for animal nutrition-grade niacin is fragmenting as regional feed producers seek alternatives to long-term single-supplier contracts. This shift creates openings for specialized producers. Lonza Group leverages its significant manufacturing scale to influence pricing in bulk segments. BASF SE competes on the basis of high-purity formulations for pharmaceutical applications. Vertellus specializes in producing specific niacin derivatives for niche industrial uses, differentiating itself from high-volume competitors.
Niacin and its amide form, niacinamide, are water-soluble B-complex vitamins essential for cellular metabolism. They function as precursors to the coenzymes NAD and NADP, which are vital for redox reactions throughout the body. While the animal nutrition application constitutes a significant volume, the dietary supplements and cosmetics segments provide higher margin opportunities. Powdered forms dominate the market due to their cost-effectiveness and stability, though liquid formulations are gaining traction in specialized cosmetic and pharmaceutical preparations.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate the acceptable daily intake and fortification levels in food and supplements. In parallel, China's State Administration for Market Regulation (SAMR) sets GB standards for feed-grade and food-grade purity. These regulations directly shape product specifications and market access. Future success for manufacturers hinges on managing portfolios that meet the distinct purity and compliance demands of the pharmaceutical, cosmetic, and animal feed sectors.
Market Dynamics
The market's central dynamic is the divergence between high-volume, price-sensitive animal nutrition applications and high-margin, purity-driven segments like cosmetics and pharmaceuticals. This bifurcation forces manufacturers to manage distinct supply chains, regulatory compliance pathways, and pricing strategies for each end-use.
Growth Catalysts
- Food Fortification Mandates:Regulations from the US FDA and Europe's EFSA requiring the fortification of staple foods like flour and cereals with B-vitamins provide a consistent and stable demand base for food-grade niacin.
- Cosmetic Sector Adoption:The expanding use of niacinamide in topical skincare formulations for its anti-inflammatory, barrier-repair, and anti-aging properties drives significant growth in the high-purity personal care segment.
- Animal Nutrition in China:China's massive and industrializing livestock sector, particularly swine and poultry, creates concentrated and large-scale demand for feed-grade niacin to ensure animal health and metabolic function.
Market Restraints
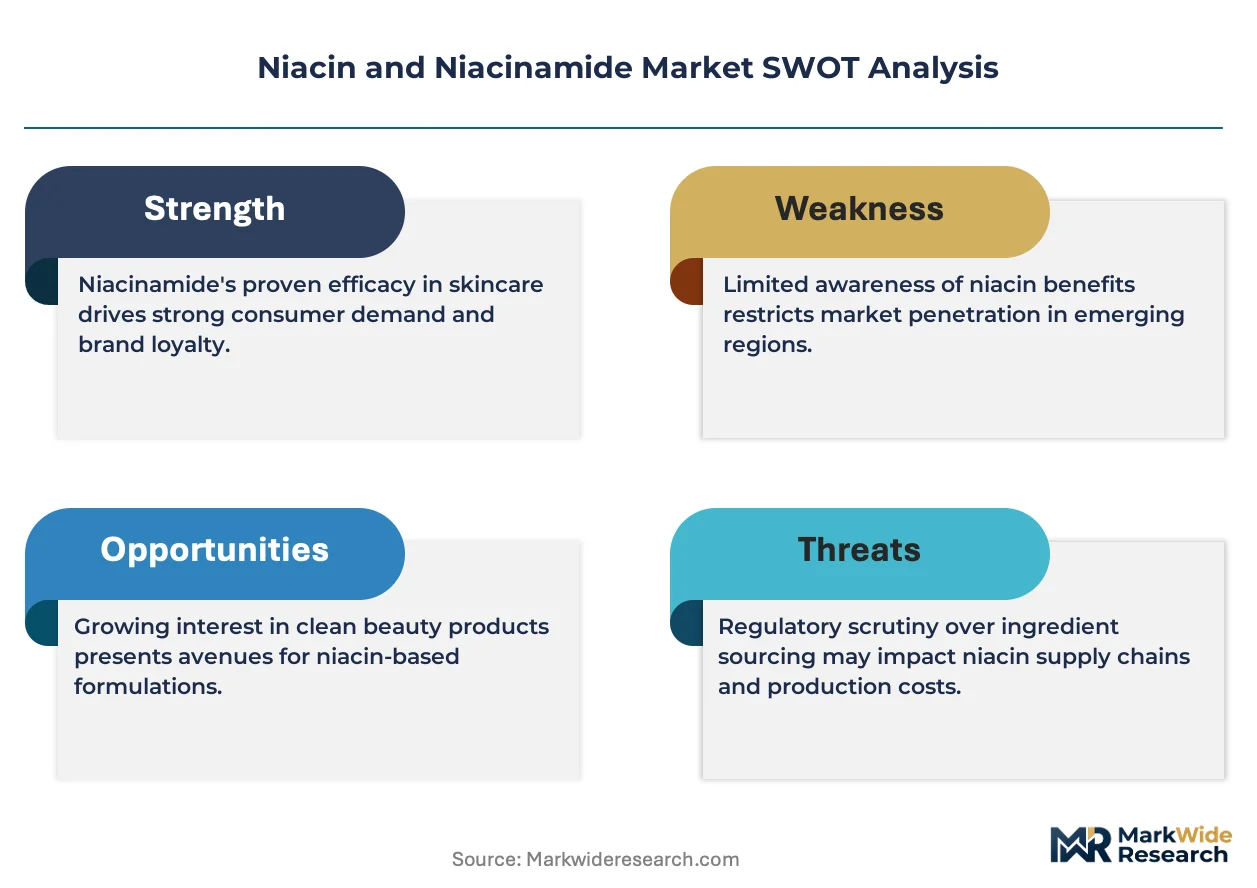
- Raw Material Volatility:The price and availability of key chemical precursors, such as picoline derivatives sourced from the petrochemical industry, introduce significant cost volatility into the niacin production process.
- Bulk Market Price Influence:A few large-scale producers possess the manufacturing capacity to influence pricing in the bulk animal nutrition segment, creating high barriers to entry and margin pressure for smaller competitors.
- Ingredient Substitution:In cosmetics and dietary supplements, alternative active ingredients, including other B vitamins, vitamin C, or botanical extracts, can be substituted for niacinamide, limiting its pricing power in certain formulations.
Strategic Opportunities
- NAD+ Precursor Supplements:The growing consumer interest in longevity and cellular health creates an opportunity for high-purity niacin and niacinamide as precursors for NAD+ boosting dietary supplements, a niche but high-value market.
- Fortification Program Expansion:Food fortification initiatives in developing economies across Latin America and Southeast Asia represent an underpenetrated market for food-grade niacin as public health programs expand.
- Advanced Delivery Systems:Developing liquid and encapsulated niacinamide formulations for enhanced skin penetration in cosmetics or improved bioavailability in pharmaceuticals offers a pathway to differentiate products and capture premium pricing.
Industry Challenges
- Divergent Purity Standards:Manufacturers face the operational complexity of adhering to disparate purity and documentation requirements, from China's GB standards for animal feed to the stringent USP monograph for pharmaceutical applications.
- Supply Chain Fragmentation:Regional feed producers struggle to diversify their niacin sources, facing logistical and contractual hurdles when attempting to move away from long-term agreements with dominant global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Niacin and Niacinamide Market |
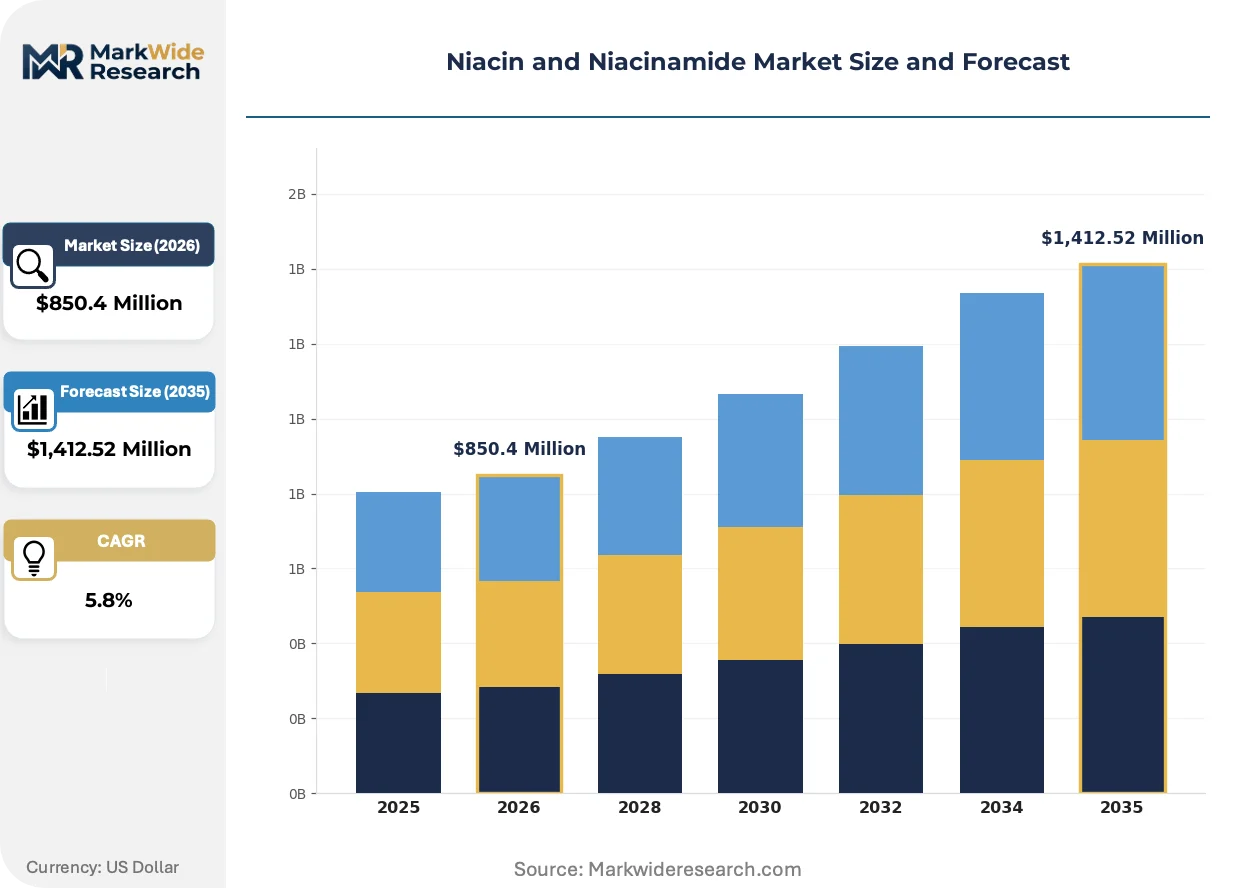
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,412.52 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Niacin, Niacinamide, Niacin Derivatives, Nicotinic Acid, Others Application: Dietary Supplements, Pharmaceuticals, Cosmetics & Personal Care, Food & Beverage, Animal Nutrition End User: Pharmaceutical Manufacturers, Nutraceutical Companies, Cosmetic Brands, Food Producers Form: Powder, Granules, Capsules, Tablets, Liquid |
| Companies Covered | Vertellus, Koninklijke DSM N.V, Brother Enterprises Holding Co., Ltd, Merck KGaA, BASF SE, Evonik Industries AG, Jubilant Life Sciences Limited, Foodchem International Corporation, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Niacin and Niacinamide Market Strategic Shifts & Innovations
Formulation science and application-specific regulatory scrutiny are segmenting the market into distinct value streams. Innovations are focused on improving delivery, bioavailability, and compliance, moving beyond the traditional commodity status of the core vitamin molecule and towards specialized, high-performance ingredients.
Microencapsulation technology provides a protective coating for niacin, enabling its controlled release within an animal's digestive system. Large-scale livestock producers are adopting this for ruminant feed to bypass microbial degradation in the rumen and improve metabolic efficiency. This advanced delivery format is collapsing the value proposition between standard feed-grade niacin and more complex, higher-cost derivatives by offering enhanced performance at a moderate price premium.
The European Union's Cosmetic Products Regulation (CPR) continues to elevate standards for ingredient substantiation and label transparency. This framework compels brands to provide robust efficacy and safety data for active ingredients like niacinamide, particularly for claims related to concentration levels. The high-purity cosmetics segment is most impacted, pushing suppliers to invest in clinical studies to validate specific benefits, such as sebum reduction or skin barrier enhancement.
A behavioral shift among supplement consumers toward ingredient-focused wellness routines is disrupting the market. Buyers are moving from general multivitamins to single-ingredient products, including standalone niacinamide capsules, to address specific health goals like energy metabolism or skin clarity. This trend is most visible in North America, where direct-to-consumer brands and personalized nutrition services are gaining traction over traditional retail channels.
Niacin and Niacinamide Market Segmentation
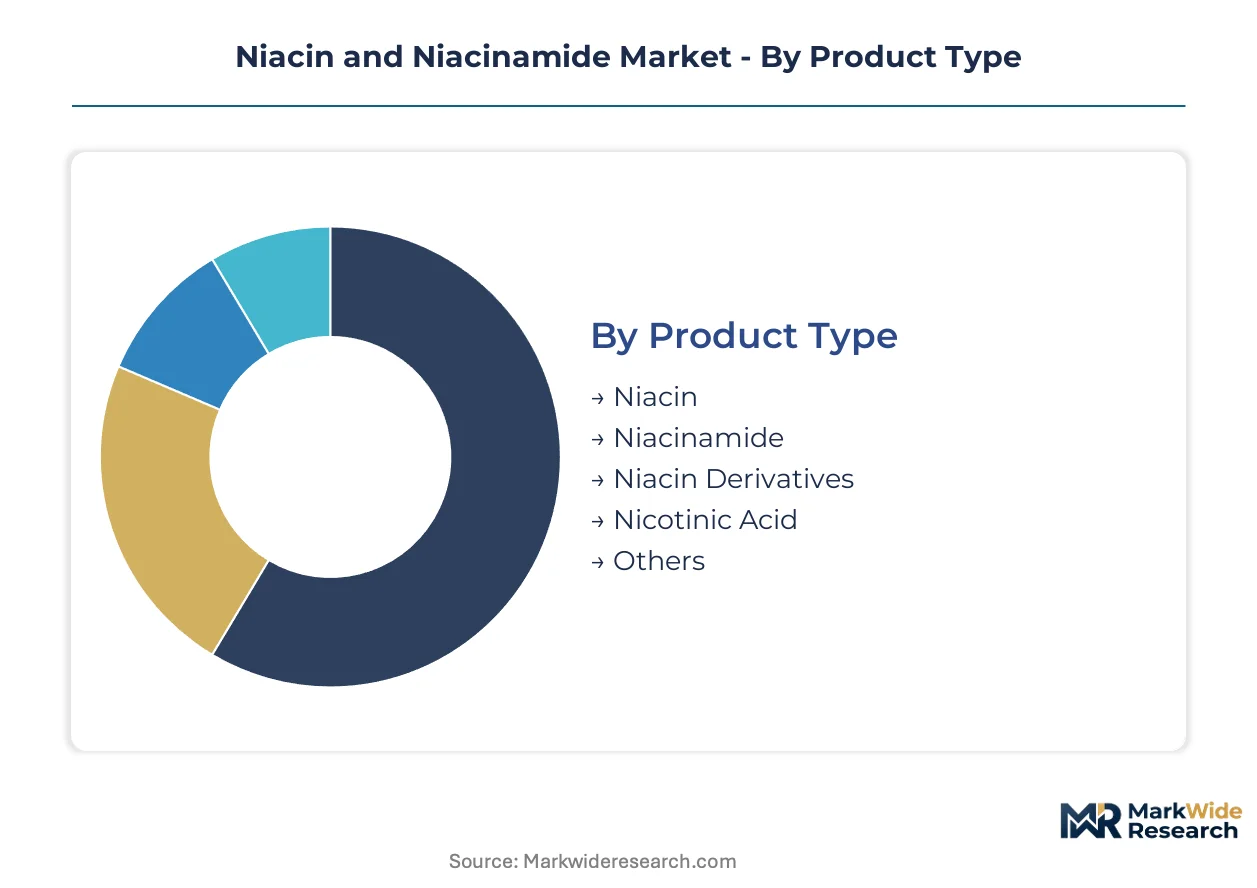
The Niacin and Niacinamide Market exhibits diverse segmentation across product forms, applications, and end-user industries. This stratification reflects varying purity requirements, price sensitivities, and regulatory landscapes for distinct market segments.
Product Type:
The market differentiates product offerings based on their chemical structure and functional properties.
- Niacinamide:This amide form of vitamin B3 is widely utilized in topical skincare for its anti-inflammatory and barrier-repair benefits, driving substantial growth in the cosmetics sector. Demand is concentrating in North America and Europe due to strong consumer interest in advanced skincare formulations.
- Niacin:Also known as nicotinic acid, this form is crucial for cholesterol management and is a primary choice for food fortification initiatives due to its cost-effectiveness and metabolic function. Stable demand stems from mandated fortification programs in the US and Europe.
- Niacin Derivatives:These specialized compounds are engineered for enhanced stability or targeted delivery in specific pharmaceutical or industrial applications, offering niche solutions.
- Nicotinic Acid:As the scientific name for niacin, it serves as a foundational ingredient for various B-vitamin formulations and pharmaceutical-grade products.
- Others:This category encompasses less common or emerging forms and precursors, often explored for novel applications or improved bioavailability.
Niacin commands the established base. The steepest expansion runs through Niacinamide.
Application:
Market demand is segmented by the primary end-use sectors.
- Animal Nutrition:Niacin is a critical feed additive for livestock, particularly swine and poultry, supporting metabolic health and growth efficiency. Significant volume demand is concentrating in China due to its extensive animal agriculture industry.
- Cosmetics & Personal Care:Niacinamide is a highly sought-after active ingredient in skincare products, valued for its skin-brightening, anti-aging, and anti-acne properties. This segment offers higher margins, especially in premium product lines across Europe.
- Dietary Supplements:Niacin and niacinamide are consumed as standalone supplements or within multivitamins to support energy metabolism and overall cellular health. North American consumers increasingly seek single-ingredient formulations for targeted wellness.
- Food & Beverage:Used for fortifying staple foods such as flour, cereals, and baked goods, niacin helps prevent deficiency diseases like pellagra. Regulatory mandates from the US FDA and Europe's EFSA ensure consistent demand.
- Pharmaceuticals:High-purity niacin forms are prescribed for treating dyslipidemia and other conditions, requiring stringent manufacturing standards and regulatory compliance.
The market reflects a bifurcation between high-volume uses and premium, purity-driven applications.
End User:
Customer type plays a critical role in shaping product specifications and service requirements.
- Pharmaceutical Manufacturers:These companies demand ultra-high purity niacin and niacinamide, adhering to pharmacopoeial standards like USP, for use in prescription drugs and over-the-counter medications. Their procurement is driven by stringent quality control and regulatory dossier requirements.
- Cosmetic Brands:Requiring high-purity niacinamide, these brands integrate the ingredient into advanced skincare formulations, focusing on efficacy validation and consumer safety. Demand is particularly strong from premium and dermo-cosmetic brands.
- Nutraceutical Companies:These firms produce dietary supplements containing niacin and niacinamide, catering to health-conscious consumers seeking specific wellness benefits. Their product lines range from general multivitamins to targeted single-ingredient supplements.
- Food Producers:Manufacturers in the food and beverage industry incorporate niacin into staple products for nutritional fortification, guided by public health regulations and consumer health trends.
Distinct regulatory pathways and supply chain needs define the engagement with each end-user group.
Form:
The physical state of niacin and niacinamide products varies to suit diverse manufacturing processes and consumer preferences.
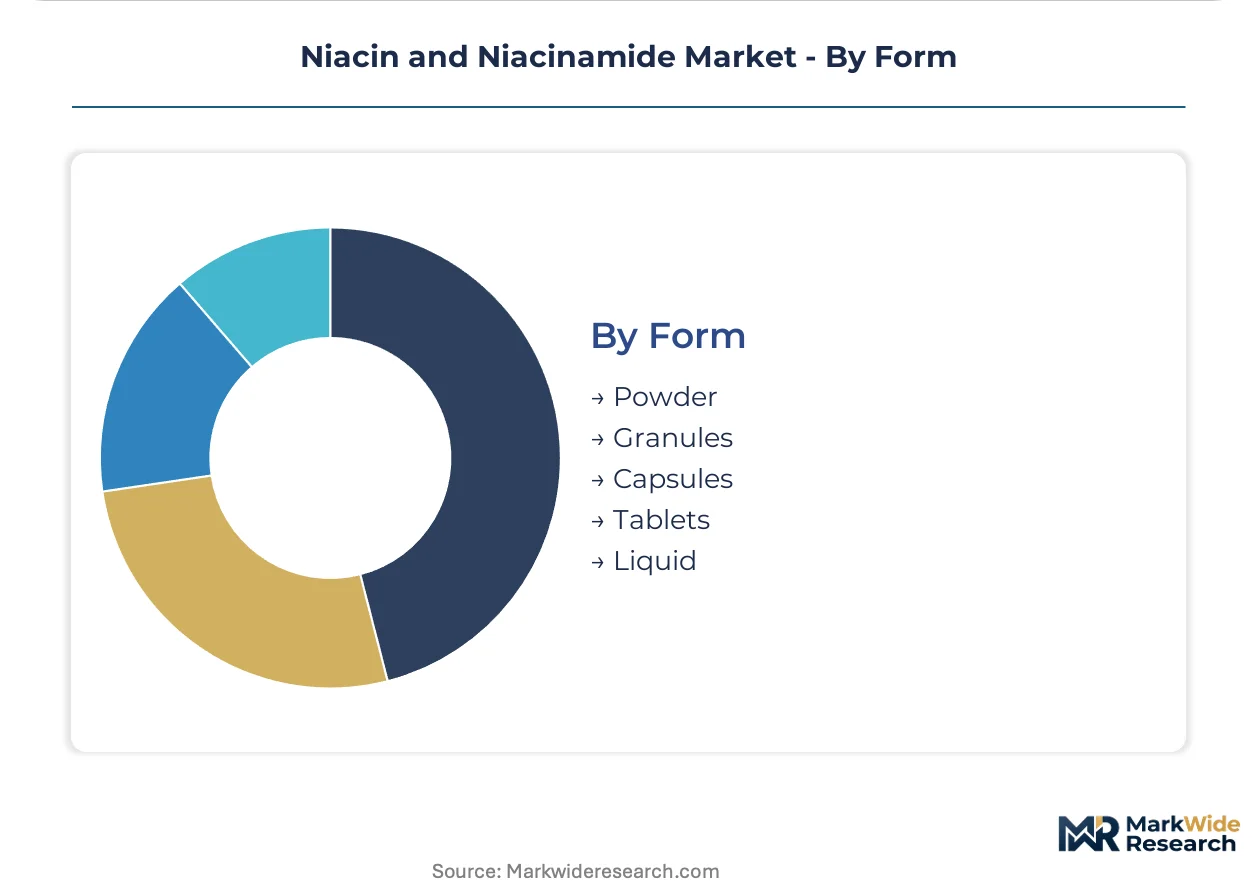
- Powder:This cost-effective and stable form dominates the market, widely used in animal nutrition, food fortification, and bulk pharmaceutical manufacturing.
- Liquid:Gaining traction in specialized cosmetic and pharmaceutical preparations, liquid formulations offer enhanced solubility and ease of incorporation into specific product matrices.
- Granules:Granular forms provide improved flowability and reduced dust, making them suitable for certain blending processes in feed and food applications.
- Capsules:Primarily used in dietary supplements, capsules offer precise dosing and mask the taste of raw ingredients, appealing to individual consumers.
- Tablets:A common dosage form for pharmaceutical and dietary supplement products, tablets provide convenience and controlled release options.
While traditional powdered forms retain market dominance, specialized delivery methods are capturing premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major global shipping lanes underpin the efficient movement of niacin and niacinamide, enabling specialized production hubs to serve diverse international markets. The distinct regulatory frameworks and consumer preferences across continents shape regional demand patterns for this essential vitamin.
China
China's colossal livestock sector drives substantial demand for feed-grade niacin, ensuring animal health and growth efficiency. The State Administration for Market Regulation (SAMR) sets stringent GB standards, influencing product specifications for both feed and food grades. Industrial clusters in Shandong province, a major agricultural and chemical production hub, concentrate significant manufacturing and consumption of niacin for animal nutrition.
United States
The United States exhibits consistent demand for niacin due to mandated food fortification programs and a robust dietary supplements market. The US Food and Drug Administration (FDA) establishes acceptable daily intake levels and fortification requirements for staple foods. The Midwest region, with its extensive food processing and agricultural industries, represents a key area for niacin incorporation into fortified products.
Germany
Germany represents a significant European market for high-purity niacin and niacinamide, especially within pharmaceutical and cosmetics applications. The European Food Safety Authority (EFSA) and the European Cosmetic Products Regulation guide product formulation and safety standards. The Rhine-Main region, a prominent chemical and pharmaceutical industry hub, sees concentrated activity in developing specialized niacin derivatives for these premium segments.
India
India's expanding food fortification initiatives and growing nutraceutical sector are fueling increased demand for niacin and niacinamide. The Food Safety and Standards Authority of India (FSSAI) provides guidelines for food additives and fortification levels. Gujarat, known for its chemical manufacturing and pharmaceutical base, is emerging as a key production and consumption center for these vital B-vitamins.
Niacin and Niacinamide Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the niacin and niacinamide market. The competitive landscape bifurcates between large-scale commodity producers influencing bulk pricing and specialized manufacturers focusing on high-purity, application-specific formulations. Key archetypes include global chemical conglomerates, dedicated vitamin producers, and niche derivative specialists. Manufacturers engage in strategic partnerships to secure raw material supply and pursue portfolio diversification to address varied end-use demands.
Specialists in specific chemical derivatives, such as Vertellus, differentiate their offerings for niche industrial uses. At the scale-driven end, Lonza Group leverages its significant manufacturing capacity to influence pricing dynamics in high-volume segments. BASF SE occupies a position in the high-purity formulations segment, particularly targeting pharmaceutical applications with stringent quality requirements.
| Leading Market Players |
|---|
| Vertellus |
| Koninklijke DSM N.V |
| Brother Enterprises Holding Co., Ltd |
| Merck KGaA |
| BASF SE |
| Evonik Industries AG |
| Jubilant Life Sciences Limited |
| Foodchem International Corporation |
| Lonza Group |
| Others |
Cost & Logistics Intelligence
Shandong province, a major chemical production hub in China, influences global niacin pricing due to its concentrated manufacturing capacity for feed-grade volumes. This capacity dictates the cost structure for high-volume applications worldwide.
Pricing Analysis
Volume-based tiering structures characterize niacin pricing, with significant discounts for large-scale, long-term contracts in animal nutrition. Price differentiation stems from purity grade requirements, such as USP for pharmaceuticals or GB standards for feed, and the volume purchased. Pricing softness in bulk segments reflects the influence of large-scale producers like Lonza Group. Animal nutrition buyers exhibit the highest price sensitivity, contrasting sharply with the premium segments of pharmaceuticals and cosmetics.
Supply Chain Analysis
Export controls on key chemical intermediates, though not currently impacting niacin directly, highlight the potential for future supply restrictions on critical precursors like picoline derivatives. Global niacin supply concentrates in China for feed-grade, with high-purity production in Germany and the United States. Raw material volatility from the petrochemical industry introduces cost instability. The distribution model for bulk animal nutrition is fragmenting, while high-purity segments often utilize direct manufacturer-to-customer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The niacin market requires a robust substitution defense against alternative active ingredients in cosmetics and dietary supplements. Manufacturers must navigate the threat of other B vitamins or botanical extracts limiting pricing power.
For Market Incumbents: Build regulatory and scientific moats by investing in clinical studies to validate niacinamide's specific benefits for cosmetics. Incumbents should secure long-term raw material supply agreements for picoline derivatives to mitigate volatility and counter ingredient substitution threats. Deepening vertical integration into key chemical precursors offers a strategic lever. Expanding R&D into advanced delivery systems, like microencapsulation, can differentiate offerings and protect margins.
For New Entrants and Emerging Players: NAD+ precursor supplements represent a high-value, niche entry point for new players targeting longevity and cellular health. Underpenetrated food fortification programs in developing economies across Latin America and Southeast Asia offer significant volume opportunities. A direct-to-consumer model for standalone niacinamide capsules can capture ingredient-focused wellness consumers in North America. Focus on specialized, high-purity formulations for these specific applications.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized producers with proprietary advanced delivery systems or unique derivative capabilities. The market's long-term viability is secured by niacin's essential biological function and stable demand from regulatory fortification mandates. Acquisition targets include companies proficient in microencapsulation or those holding critical certifications for pharmaceutical-grade niacinamide. The expansion of food fortification programs into new developing economies provides a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Lonza Group's manufacturing scale influences bulk pricing dynamics. |
| Long-term Supply Agreement | Secures raw material access, mitigating volatility from picoline derivatives. |
| Product Launch | Introduces advanced liquid niacinamide formulations for enhanced cosmetic penetration. |
| Regulatory Approval Pathway | Achieves USP compliance for pharmaceutical-grade niacin, expanding market access. |
| Joint Venture | Develops microencapsulation technology for improved ruminant feed efficiency. |
Research Approach
A spread of perspectives from pharmaceutical R&D directors, feed additive procurement managers, cosmetic formulators, and regulatory affairs specialists converged on the working assumptions. This approach combined primary interviews with secondary validation from sources like US FDA filings, EFSA reports, and China GB standards. Bottom-up and top-down triangulation ensured data consistency across market segments. Industry association publications also informed the analysis.
Demand-supply-balance modeling formed the core analytical framework across the analysis window, integrating historical data with projected trends. Segmentation dimensions included product type, application, end-user, form, and purity grade. Compound Annual Growth Rates were derived through regression analysis. Livestock population trends and food fortification mandates served as critical forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in petrochemical prices or trade policies would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability. Raw material price shocks remain key risk factors, and continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Lactic Acid Blend Market
Specialty Chemicals
Superdisintegrants Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Copper Ammonium Carbonate Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
Encapsulated Lactic Acid Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Avobenzone Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Europe Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Chemicals
Nucleotides Market