
 Hydrogenation Catalyst Market | 2026-2036
Hydrogenation Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogenation Catalyst Market Intelligence
Multi-source procurement for precious metal precursors is restructuring supply security across the hydrogenation catalyst value chain. BASF SE leverages its integrated precious metal refining network to secure rhodium and palladium feedstock for pharmaceutical-grade catalysts. Johnson Matthey plc anchors its position through captive recycling facilities that recover platinum group metals from spent refinery catalysts. Albemarle Corporation competes via specialized nickel-cobalt formulations targeting slurry-phase hydrogenation in edible oil processing.
Hydrogenation catalysts are heterogeneous or homogeneous substances that facilitate the addition of hydrogen to unsaturated organic compounds, typically comprising supported metal nanoparticles on alumina, silica, or carbon carriers with active metal loadings between 0.3% and 5% by weight. These materials enable saturation of double bonds, deoxygenation, and hydrodesulfurization in continuous-flow industrial reactors operating at pressures from 10 to 200 bar. Palladium-based systems command premium positioning in pharmaceutical asymmetric hydrogenation where enantioselectivity requirements drive batch-scale deployment. Nickel formulations dominate tonnage demand across petrochemical hydrocracking and food oil hardening, though margin pools concentrate in platinum-ruthenium bimetallic catalysts for fine chemical synthesis.
EPA fuel sulfur specifications, REACH substance authorization requirements, and China's GB 17930 gasoline standards collectively mandate progressive hydrodesulfurization depth that directly dictates catalyst replacement frequency and active metal loading specifications. FDA current good manufacturing practice rules for pharmaceutical catalysts impose residual metal leaching thresholds that reshape validation protocols and supplier qualification timelines. Stakeholders must monitor divergence between EU Green Deal hydrogen integration timelines and refinery utilization rates to calibrate capacity commitments across precious metal recovery and fresh catalyst production.
Market Dynamics
Refinery operators face compressed catalyst replacement cycles as sulfur-content regulations tighten across major jurisdictions, forcing simultaneous upgrades to active metal loadings and carrier formulations.
Growth Catalysts
- GB 17930 gasoline standards:China's sulfur limits mandate deeper hydrodesulfurization in coastal refineries, accelerating consumption of nickel-molybdenum formulations.
- Biofuel blending mandates:Hydrotreated vegetable oil production in European facilities requires specialized sulfided catalysts for deoxygenation.
- Active metal loading specifications:EPA Tier 3 sulfur rules drive demand for platinum-palladium bimetallic systems in North American gasoline hydrotreaters.
Market Restraints
- Palladium supply concentration:Russian and South African mining concentration creates price volatility for automotive and pharmaceutical catalyst precursors.
- Alumina carrier shortages:High-purity gamma-alumina supply bottlenecks from specific calcination facilities limit catalyst production scaling.
- Spent catalyst logistics:Hazardous waste classification of metal-laden refinery residues complicates reverse supply chain economics.
Strategic Opportunities
- India's BIS fuel quality roadmap:Bharat Stage VI-Stage VII transition opens demand for cobalt-promoted molybdenum catalysts in domestic refineries.
- Modular hydrogenation skids:Containerized reactor systems enable distributed pharmaceutical manufacturing away from centralized petrochemical complexes.
- EU Green Deal hydrogen integration:Renewable hydrogen mandates create retrofit demand for sulfur-tolerant catalysts in conventional hydrotreaters.
Industry Challenges
- Spent catalyst metal recovery certification:EPA hazardous waste permits and state-level tracking requirements extend qualification timelines for recycling partners.
- High-throughput screening expertise:Shortage of combinatorial catalyst chemists delays formulation optimization for asymmetric hydrogenation applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogenation Catalyst Market |
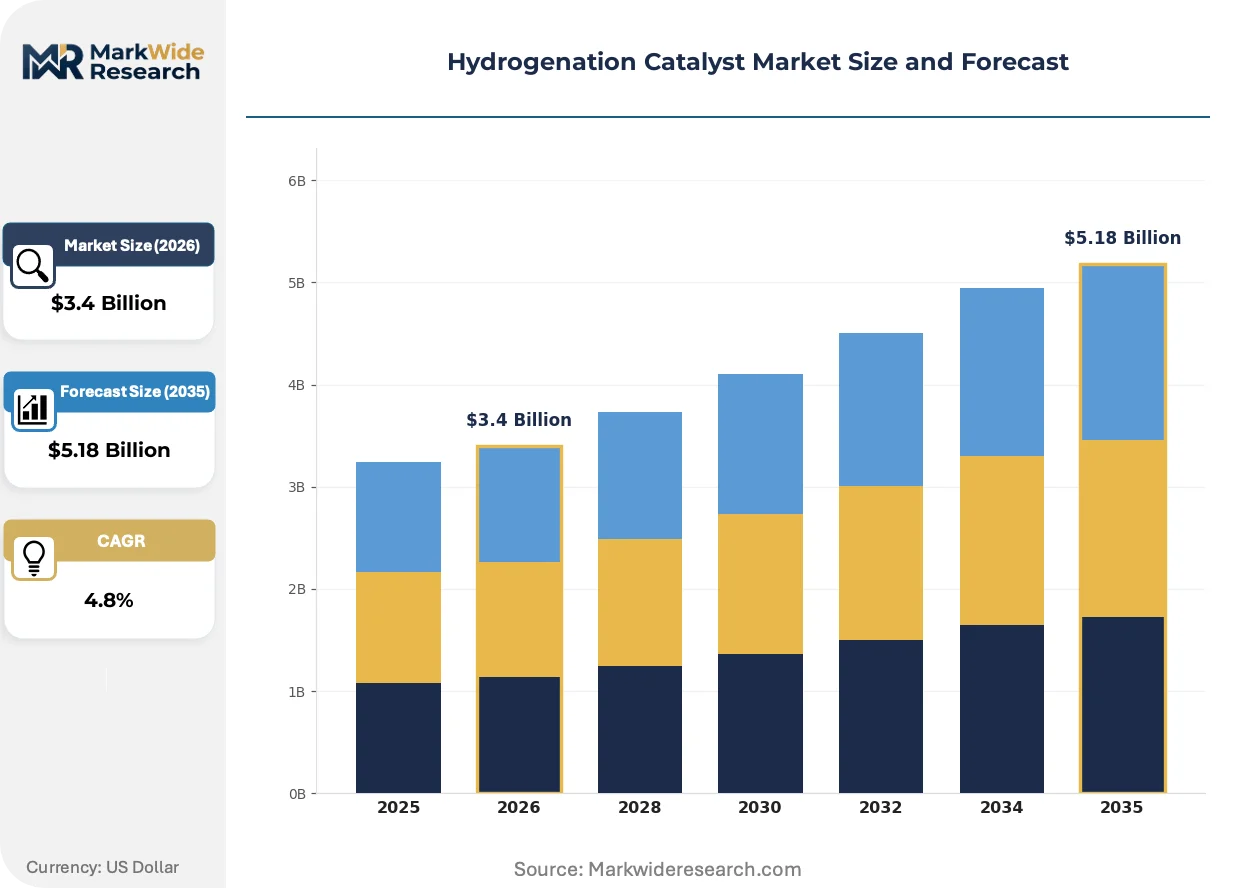
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.18 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nickel, Palladium, Platinum, Ruthenium Application: Petrochemicals, Pharmaceuticals, Agrochemicals, Food Processing End User: Chemical Industry, Oil & Gas, Food Industry, Pharmaceutical Companies Technology: Fixed Bed, Slurry, Batch, Continuous Flow |
| Companies Covered | BASF SE, Evonik Industries AG, Advanced Refining Technologies (ART), Haldor Topsoe A/S, Johnson Matthey plc, Albemarle Corporation, Clariant AG, Honeywell UOP, Criterion Catalysts & Technologies L.P., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogenation Catalyst Market Strategic Shifts & Innovations
Electrification of hydrogen supply and precision manufacturing requirements are restructuring catalyst specification patterns across both commodity and specialty segments.
Single-atom catalyst synthesis is decentralizing active site distribution control. Pharmaceutical manufacturers in Switzerland and Massachusetts adopt these systems for batch-scale asymmetric hydrogenation. The technology is decentralizing quality assurance from centralized analytical labs to point-of-use validation protocols.
REACH substance authorization requirements are tightening residual metal leaching thresholds for pharmaceutical catalysts. Manufacturers must reformulate alumina-supported palladium systems to meet ECHA documentation standards. Fine chemical producers in the Netherlands and Germany are pre-qualifying suppliers eighteen months ahead of commercial campaigns.
Refinery procurement departments now specify performance-guaranteed catalyst supply contracts with embedded metal price hedging. Integrated oil companies in China's Shandong and Zhejiang provinces negotiate tolling arrangements that separate catalyst formulation from precious metal financing. This structure compresses supplier margins while extending contract durations to match turnaround cycles.
Hydrogenation Catalyst Market Segmentation
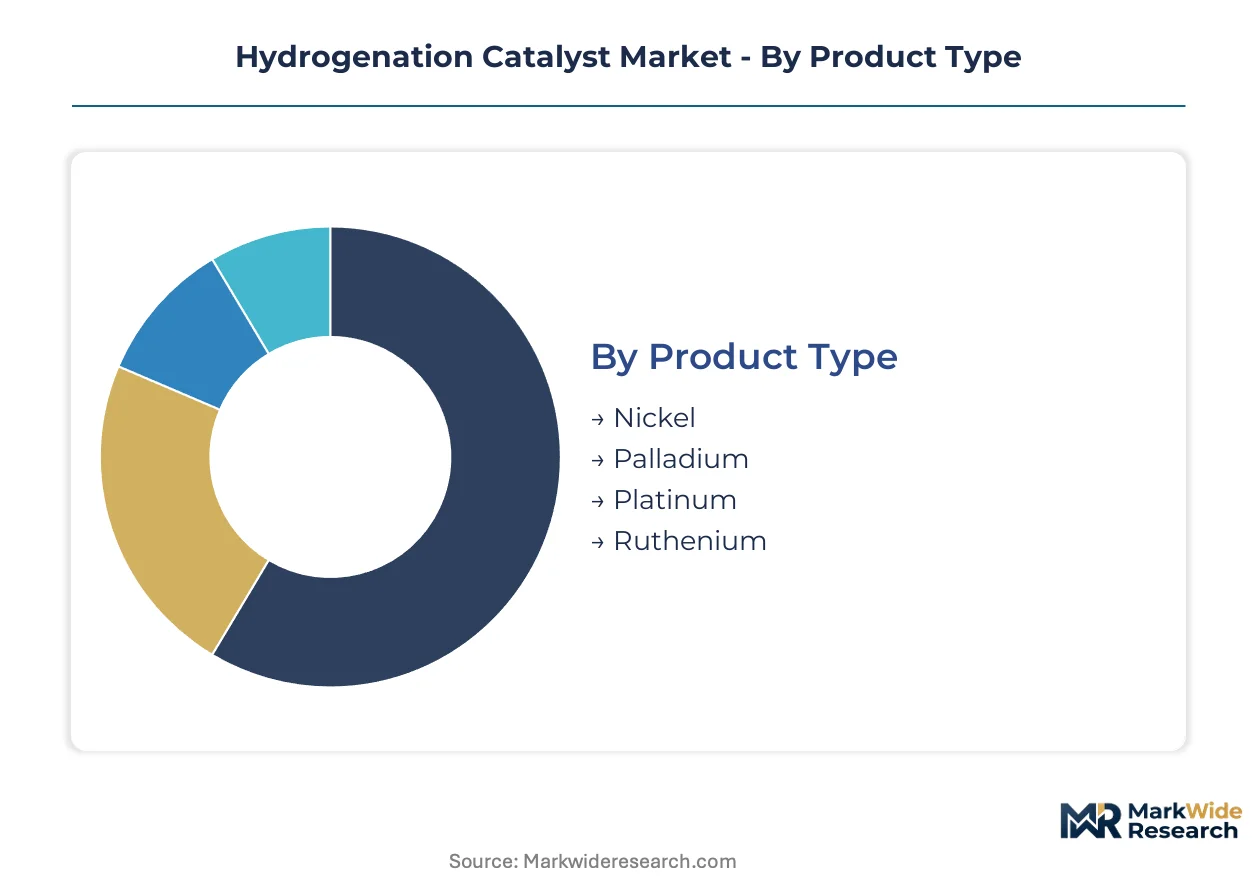
Hydrogenation catalyst specifications diverge sharply between commodity refinery applications and precision pharmaceutical synthesis. Metal loading requirements, carrier purity grades, and batch validation protocols create distinct procurement categories that reshape supplier relationships and margin structures across end-use verticals.
Product Type:
Customization intensity spans from standardized nickel formulations for bulk chemical processing to bespoke platinum-ruthenium systems engineered for enantioselective synthesis.
- Nickel:Sulfided and reduced nickel catalysts on alumina or kieselguhr carriers dominate tonnage demand for edible oil hydrogenation and petrochemical hydrocracking. China's Shandong province refineries consume bulk shipments for diesel hydrotreating under tightening GB sulfur standards.
- Palladium:Carbon-supported palladium systems with 0.5-5% metal loading enable carbon-carbon bond saturation in pharmaceutical intermediate production. Swiss and Massachusetts-based manufacturers specify these for asymmetric hydrogenation of chiral precursors under FDA current good manufacturing practice protocols.
- Platinum:Bimetallic platinum-tin or platinum-rhenium formulations target reforming and dehydrogenation in naphtha processing.
- Ruthenium:Ruthenium dioxide and supported metal systems facilitate selective hydrogenation of aromatic nitro compounds and carbonyl groups in fine chemical synthesis.
Most installed capacity flows through nickel formulations. Expansion is steepest in palladium systems for pharmaceutical asymmetric applications.
Application:
Volume concentration sits with continuous-flow refinery operations, while value concentration clusters in batch-scale pharmaceutical campaigns requiring residual metal certification.
- Petrochemicals:Hydrodesulfurization, hydrocracking, and reforming operations in coastal Chinese and US Gulf Coast refineries drive catalyst consumption. EPA Tier 3 and China's GB 17930 sulfur mandates force accelerated replacement cycles for cobalt-molybdenum and nickel-molybdenum systems.
- Pharmaceuticals:Stereoselective hydrogenation of active pharmaceutical ingredients demands enantiomeric excess above 99% and residual palladium below 10 ppm. ECHA REACH authorization requirements extend supplier qualification timelines to eighteen months for European manufacturers.
- Agrochemicals:Herbicide and pesticide intermediate production utilizes fixed-bed hydrogenation for nitroaromatic reduction.
- Food Processing:Partial hydrogenation of vegetable oils for margarine and shortening applications employs nickel catalysts in slurry-phase reactors.
Petrochemicals absorb the greatest catalyst volume. Pharmaceuticals generate the highest per-kilogram margins and fastest specification escalation.
End User:
Procurement sophistication separates integrated oil companies with captive technical teams from mid-sized food processors relying on toll manufacturers.
- Chemical Industry:Specialty and commodity chemical producers deploy hydrogenation for intermediate synthesis. German and Dutch fine chemical facilities pre-qualify catalyst suppliers against ECHA documentation standards.
- Oil & Gas:Integrated refiners and independent operators specify performance-guaranteed supply contracts with embedded metal price hedging. China's state-owned refiners in Zhejiang province negotiate tolling arrangements separating formulation from precious metal financing.
- Food Industry:Edible oil processors favor nickel catalysts for trans-fat reduction in hydrogenated vegetable oil production.
- Pharmaceutical Companies:Multinational drug manufacturers enforce residual metal leaching thresholds below FDA-mandated limits through dedicated supplier audits.
Oil & gas operators deploy the largest single-site catalyst inventories. Pharmaceutical companies impose the most stringent qualification protocols.
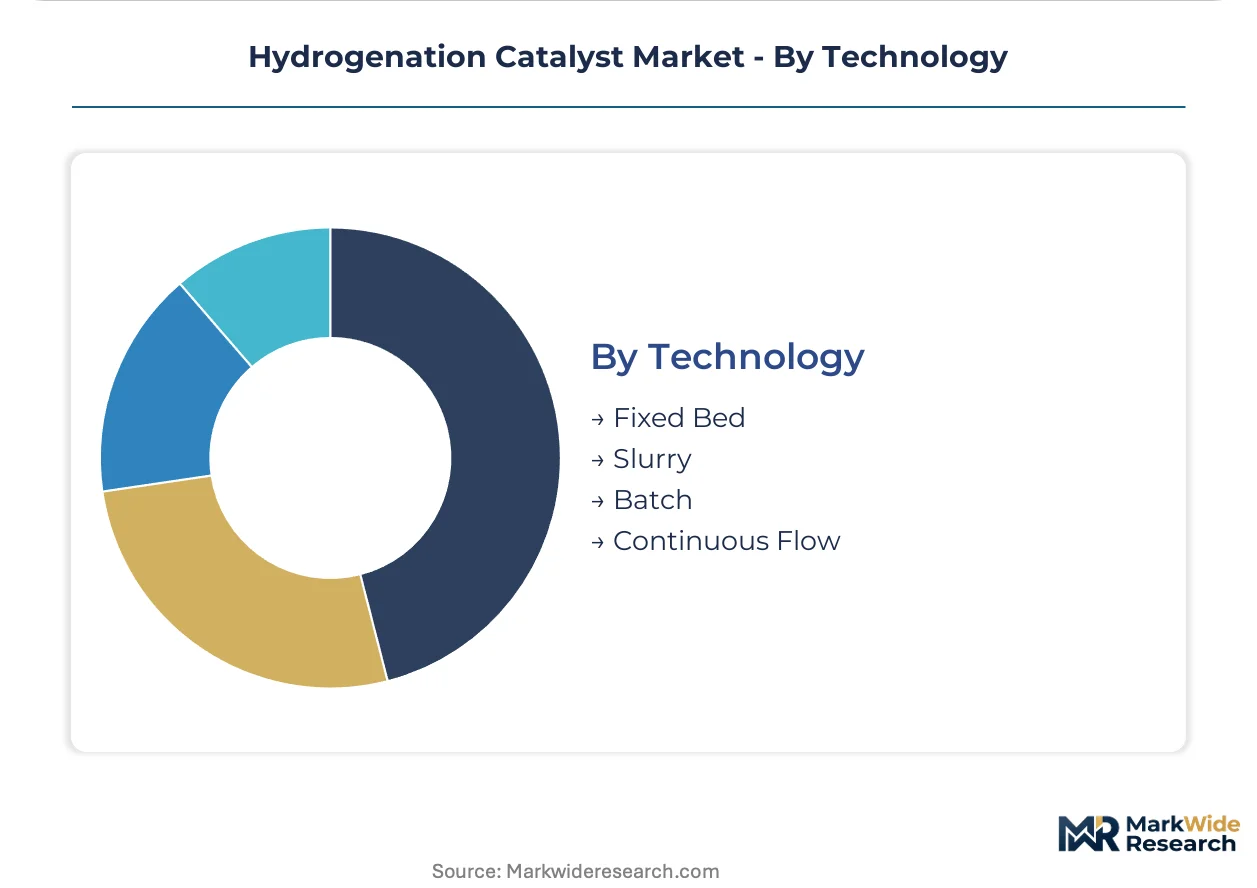
Technology:
Reactor configuration determines catalyst morphology, from extruded pellets for fixed-bed systems to finely dispersed powders for slurry operations.
- Fixed Bed:Pelletized catalysts in tubular reactors enable continuous hydrodesulfurization in refinery hydrotreaters. India's Bharat Stage VI transition drives demand for cobalt-promoted molybdenum formulations in domestic refineries adopting fixed-bed configurations.
- Slurry:Finely divided nickel or palladium powders suspended in liquid phase facilitate edible oil hydrogenation and pharmaceutical batch processing. European hydrotreated vegetable oil facilities require specialized sulfided catalysts for deoxygenation in slurry-phase reactors.
- Batch:Discrete reactor loading allows campaign-based pharmaceutical manufacturing with dedicated catalyst lots for traceability.
- Continuous Flow:Modular skid-mounted systems enable distributed pharmaceutical production away from centralized petrochemical complexes.
Fixed-bed technology commands the greatest installed base. Continuous flow systems are gaining share fastest in pharmaceutical distributed manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing hydrogenation catalyst procurement maps as refiners weigh sulfur-mandate compliance costs against feedstock access. Production investment migrates toward jurisdictions where GB standards and EPA Tier 3 rules create enforceable demand without duplicative certification burdens.
China
Shandong and Zhejiang coastal refineries drive nickel-molybdenum consumption under GB 17930 gasoline sulfur limits. State-owned operators integrate hydrogenation units with downstream aromatics production in Ningbo and Dalian petrochemical clusters. MIIT dual carbon goals accelerate catalyst replacement cycles for hydrotreaters processing high-sulfur crude.
United States
EPA Tier 3 sulfur specifications force platinum-palladium bimetallic upgrades across Gulf Coast refineries. Shale-derived light sweet crude processing in Texas and Louisiana still requires deep hydrodesulfurization for gasoline blendstocks. Houston-area catalyst tolling arrangements separate precious metal financing from formulation services.
Germany
REACH substance authorization requirements reshape pharmaceutical catalyst qualification timelines for fine chemical producers in Ludwigshafen and Leverkusen. ECHA documentation standards extend supplier pre-qualification to eighteen months. EU Green Deal hydrogen integration mandates drive retrofit demand for sulfur-tolerant systems in conventional hydrotreaters.
India
BIS Bharat Stage VI-Stage VII transition opens demand for cobalt-promoted molybdenum catalysts in Reliance Industries' Jamnagar complex and public sector refineries. Gujarat and Maharashtra coastal clusters absorb bulk shipments for diesel hydrotreating. CDSCO pharmaceutical manufacturing rules impose residual metal thresholds that mirror FDA protocols.
Saudi Arabia
SABIC and Aramco downstream integration in Jubail and Yanbu industrial cities concentrates hydrocracking catalyst demand. Hydrotreated vegetable oil export requirements to European markets necessitate specialized sulfided catalysts for deoxygenation. The national hydrocarbon regulator enforces sulfur specifications aligned with EU import standards.
Hydrogenation Catalyst Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue modular reactor packaging and single-atom synthesis niches. The supplier base concentrates around integrated chemical conglomerates with captive precious metal refining and regional specialists with formulation flexibility. Three archetypes dominate: diversified materials giants with upstream metal security, catalyst-focused technology licensors, and recycling-anchored circular economy operators. Capacity expansion and tolling arrangement partnerships constitute the primary competitive vectors as refiners seek to unbundle metal price exposure from technical service fees.
Within the diversified materials tier, BASF SE and Evonik Industries AG exemplify European-headquartered conglomerates with integrated precursor supply chains. Albemarle Corporation occupies a position among North American-based specialty chemical producers with focused nickel-cobalt formulation capabilities. Johnson Matthey plc anchors the recycling-integrated archetype through metal recovery from spent refinery catalysts. These three represent distinct strategic postures: backward integration into precious metal sourcing, specialized base metal formulation, and circular material flows.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Advanced Refining Technologies (ART) |
| Haldor Topsoe A/S |
| Johnson Matthey plc |
| Albemarle Corporation |
| Clariant AG |
| Honeywell UOP |
| Criterion Catalysts & Technologies L.P. |
| Others |
Cost & Logistics Intelligence
GB 17930 sulfur mandates and EPA Tier 3 specifications are compressing procurement timelines for nickel-molybdenum and platinum-palladium systems, forcing suppliers to absorb metal price volatility through tolling arrangements that unbundle formulation from precious metal financing.
Pricing Analysis
Input-cost pass-through from rhodium and palladium spot markets dominates contract structures. Three-tier pricing structure across pharmaceutical-grade, refinery-performance, and industrial-economy levels separates FDA-validated batches from commodity hydrodesulfurization formulations. Cost compression in refinery-grade nickel-molybdenum is intensifying because Chinese state-owned operators negotiate multi-year performance guarantees. Food processors show highest price sensitivity due to thin edible oil margins, while pharmaceutical manufacturers accept premium positioning for residual metal certification below 10 ppm thresholds.
Supply Chain Analysis
Domestic-content mandates in China's petrochemical clusters and India's BIS compliance frameworks are reshaping sourcing patterns for gamma-alumina carriers and active metal precursors. Manufacturing concentrates in China, Germany, and the United States for finished catalyst formulations, while South Africa and Russia supply concentrated platinum group metal feedstock. Raw material dependencies span high-purity alumina from specific calcination facilities, sulfiding agents for activation protocols, and carbon support materials for pharmaceutical applications. Single-source vulnerability runs through Russian palladium supply concentration. Distribution runs through integrated oil company procurement departments with captive technical teams and regional tolling partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand is migrating toward pharmaceutical-grade specifications with eighteen-month supplier qualification timelines and residual metal thresholds below FDA-mandated limits.
For Market Incumbents: Deepen backward integration into precious metal recycling to offset feedstock volatility from South African and Russian mining concentration. Expand captive tolling capacity in China's Shandong and Zhejiang provinces where state-owned refiners unbundle formulation from metal financing. Lock in long-term offtake agreements with European hydrotreated vegetable oil facilities before EU Green Deal retrofit demand peaks. For New Entrants and Emerging Players: Launch via modular hydrogenation skids targeting distributed pharmaceutical manufacturing in Massachusetts and Swiss clusters where batch-scale asymmetric hydrogenation demands point-of-use validation protocols. Penetrate India's Bharat Stage VI-Stage VII transition through cobalt-promoted molybdenum formulations for Reliance Industries' Jamnagar complex and public sector refineries. White space sits with single-atom catalyst synthesis for enantioselective applications. For Investors and Strategic Acquirers: Asymmetric upside sits with recycling-anchored operators possessing EPA hazardous waste permits and state-level tracking certifications that extend qualification timelines for competitors. Five-to-ten year viability favors circular economy archetypes with captive metal recovery from spent refinery catalysts. Watch for divergence between EU Green Deal hydrogen integration timelines and refinery utilization rates as inflection signal for capacity commitment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metal Recycling | Johnson Matthey plc anchors competitive position through captive recovery from spent refinery catalysts. |
| Long-term Tolling Arrangement with State Refiners | China's Zhejiang province operators separate catalyst formulation from precious metal financing. |
| Single-Atom Catalyst Synthesis Scale-Up | Swiss and Massachusetts manufacturers adopt decentralized quality assurance for batch-scale asymmetric hydrogenation. |
| EU Green Deal Hydrogen Retrofit Certification | German and Dutch fine chemical facilities pre-qualify sulfur-tolerant systems eighteen months ahead. |
| Modular Skid Manufacturing for Distributed Pharma | Containerized reactor systems enable campaign-based production away from centralized petrochemical complexes. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged refinery procurement directors, pharmaceutical manufacturing heads, catalyst R&D chemists, and precious metal trading specialists. Secondary validation drew from EPA Tier 3 regulatory filings, ECHA REACH authorization databases, China customs trade data, and SEC 10-K disclosures from listed chemical producers. Bottom-up catalyst consumption estimates triangulated against top-down refinery capacity and utilization assumptions.
Comparable-period anchoring linked forward projections to historical replacement cycle patterns and sulfur-mandate implementation timelines. Segmentation modeling spanned metal type, application vertical, reactor technology, and regional regulatory cluster. CAGRs were derived from fitted growth curves across the projection horizon. Industry-specific inputs included hydrodesulfurization depth requirements under GB 17930 and Bharat Stage VI, plus pharmaceutical enantioselectivity specifications.
Several conditions sit outside the modeled scope, including geopolitical disruption to Russian palladium supply, breakthrough displacement of fixed-bed systems by continuous flow modular reactors, and fundamental reformulation away from platinum group metals. Forecasts reflect documented assumptions about regulatory enforcement consistency and refinery utilization stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Industrial Catalytic Converters Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Catalyst Carrier Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Global Polypropylene Catalyst Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Inorganic Catalyst Market