
 Fluorotelomers Market | 2026-2036
Fluorotelomers Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorotelomers Market Analysis
The EU REACH restriction on perfluorooctanoic acid (PFOA) and related long-chain substances is pivoting fluorotelomer demand toward C6-based and shorter-chain chemistries. The Chemours Company leverages its vertical integration from fluoromonomers to finished polymers to sustain supply security for reformulated product lines. Daikin Industries anchors its position through R&D intensity in fluorotelomer iodide intermediates, while Solvay competes via specialized fluorotelomer surfactants for semiconductor cleaning applications.
Fluorotelomers are telomerization-derived oligomers with terminal perfluoroalkyl groups, typically synthesized through radical polymerization of tetrafluoroethylene with pentafluoroethyl iodide to produce chain lengths of C6 to C12; these compounds deliver oleophobic and hydrophobic surface properties across industrial substrates. Fluorotelomer alcohols dominate volume demand as precursor intermediates for textile and paper treatments, while fluorotelomer surfactants represent the fastest-expanding category due to critical cleaning requirements in advanced electronics manufacturing. Fluorotelomer acids occupy a mature niche with stable margins from firefighting foam formulations despite regulatory phase-out pressures on legacy products.
The US EPA regulates fluorotelomers under the Toxic Substances Control Act with significant new use rules constraining long-chain chemistry introductions, while China's MEE enforces GB standards on perfluorinated compound emissions from fluorochemical manufacturing zones. The EU F-Gas Regulation and ECHA restrictions on per- and polyfluoroalkyl substances (PFAS) collectively tighten product standards and market access conditions across major consumption regions. Stakeholders must monitor evolving PFAS grouping definitions and assess reformulation timelines against polymer exemption debates that will determine competitive positioning in downstream applications.
Market Dynamics
EU REACH restrictions on long-chain perfluorinated substances are forcing immediate reformulation across textile, paper, and electronics supply chains, compressing product development cycles and redirecting capital toward C6-based chemistry platforms.
Growth Catalysts
- Semiconductor fabrication expansion:Advanced node manufacturing in Taiwan and South Korea requires ultra-pure fluorotelomer surfactants for wafer cleaning processes, pulling demand from legacy industrial applications.
- China's domestic fluorochemical integration:Concentrated production capacity in Zhejiang and Jiangsu provinces enables captive supply chains for electronics and coatings manufacturers, reducing import dependency.
- EU F-Gas Regulation phase-down:The mandated reduction in fluorinated greenhouse gas emissions is accelerating adoption of fluorotelomer-based alternatives in fire suppression and thermal management systems.
Market Restraints
- Tetrafluoroethylene feedstock volatility:Price swings in the primary fluoromonomer input compress margins for fluorotelomer alcohol producers during energy cost spikes.
- Substitution by hydrocarbon repellents:Silicone-based and bio-based water repellent technologies are capturing share in mid-tier textile applications where performance requirements allow trade-offs.
- ECHA PFAS grouping uncertainty:The proposed broad definition of per- and polyfluoroalkyl substances threatens to capture shorter-chain fluorotelomers, freezing investment decisions in European manufacturing.
Strategic Opportunities
- India's technical textiles push:The PLI scheme for man-made fibers and protective fabrics is creating first-mover advantages for fluorotelomer finish suppliers establishing local technical service presence.
- Electronics cleaning in Vietnam:Contract manufacturing relocation from China is generating greenfield demand for high-purity fluorotelomer surfactants in semiconductor assembly and testing facilities.
- Japan's carbon neutrality roadmap:METI incentives for low-GWP industrial processes favor fluorotelomer-based thermal management fluids in data center and power electronics cooling applications.
Industry Challenges
- Fluorine chemist scarcity:The specialized knowledge required for telomerization process optimization and impurity control is concentrating among retiring specialists in Germany and Japan.
- Reformulation timeline compression:Brand owners are demanding 12-18 month qualification cycles for replacement chemistries that previously required 36-48 months of performance validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorotelomers Market |
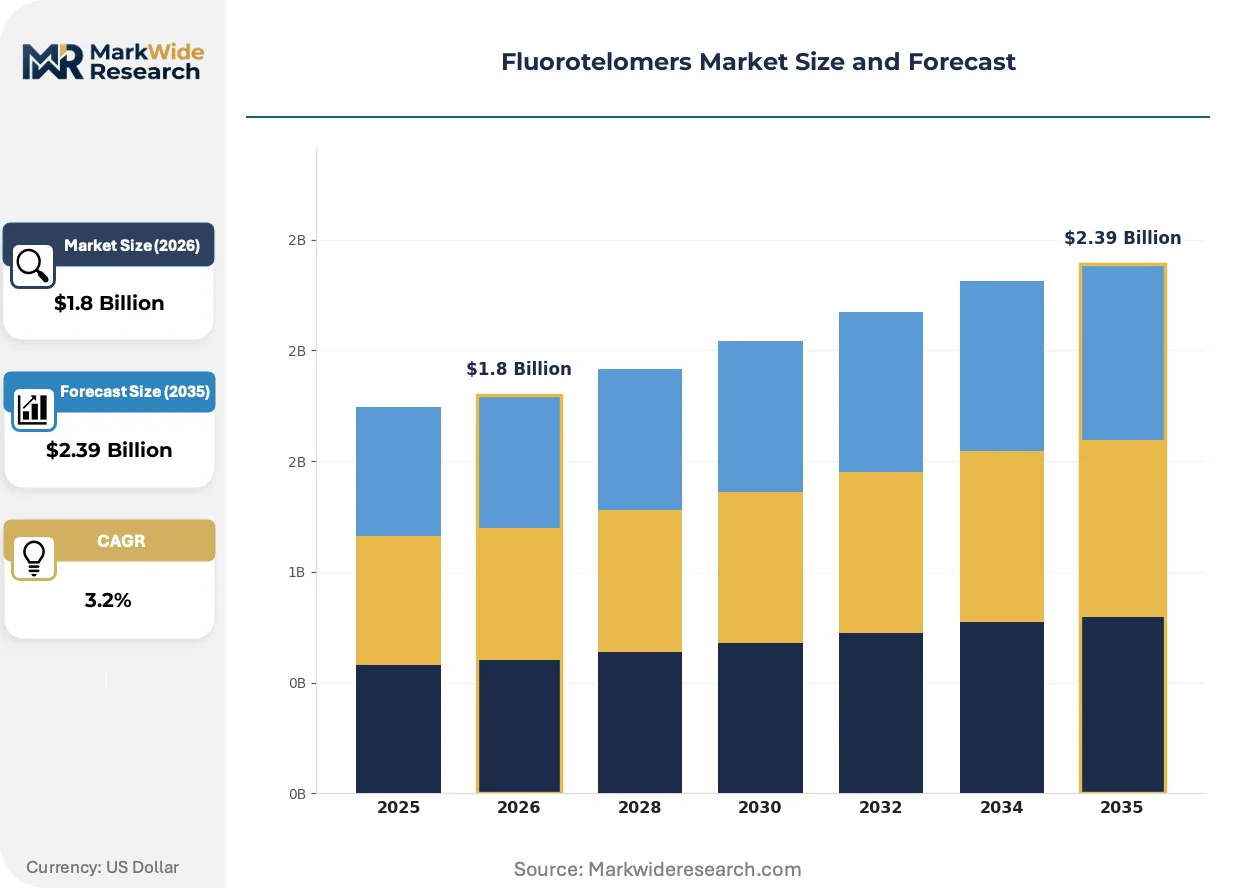
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorotelomer Alcohols, Fluorotelomer Acids, Fluorotelomer Amides, Fluorotelomer Surfactants End Use Industry: Textiles, Electronics, Coatings, Food Packaging Form: Liquid, Solid, Powder, Emulsion Application: Water Repellent, Oil Resistant, Surface Treatment, Flame Retardant |
| Companies Covered | The Chemours Company, Daikin Industries, 3M, Solvay, Arkema, AGC Chemicals, Dongyue Group, Gujarat Fluorochemicals, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorotelomers Market Emerging Trajectories
Reformulation pressure from regulatory phase-outs is accelerating chemistry innovation cycles, with manufacturers racing to match legacy performance using shorter-chain architectures while preserving process compatibility.
Fluorotelomer iodide telomerization with precise chain-length control is overtaking conventional free-radical processes in high-value semiconductor applications. Japanese electronics chemical suppliers are adopting these advanced synthesis routes to meet sub-ppb purity specifications for 3nm node manufacturing. The technology is overtaking established production methods by enabling direct fluorination without intermediate cracking steps, compressing capital intensity for new entrants.
China's MEE enforcement of GB 31572 emissions standards for perfluorinated compounds from fluorochemical manufacturing zones is tightening discharge permits and forcing on-site waste destruction investments. The regulation is redirecting capacity expansion toward integrated industrial parks with centralized effluent treatment infrastructure. Zhejiang-based producers are responding by consolidating dispersed operations into licensed chemical industry zones with membrane filtration and thermal oxidation capabilities.
Textile brand owners are compressing supplier qualification cycles and unbundling chemistry procurement from finishing service contracts. European outdoor apparel manufacturers are directly sourcing fluorotelomer alcohols and blending proprietary formulations in-house, displacing traditional chemical distributor relationships. The shift is most visible in Germany and Switzerland, where Bluesign and OEKO-TEX certification requirements favor transparent chemical supply chain documentation over bundled service offerings.
Fluorotelomers Market Segmentation
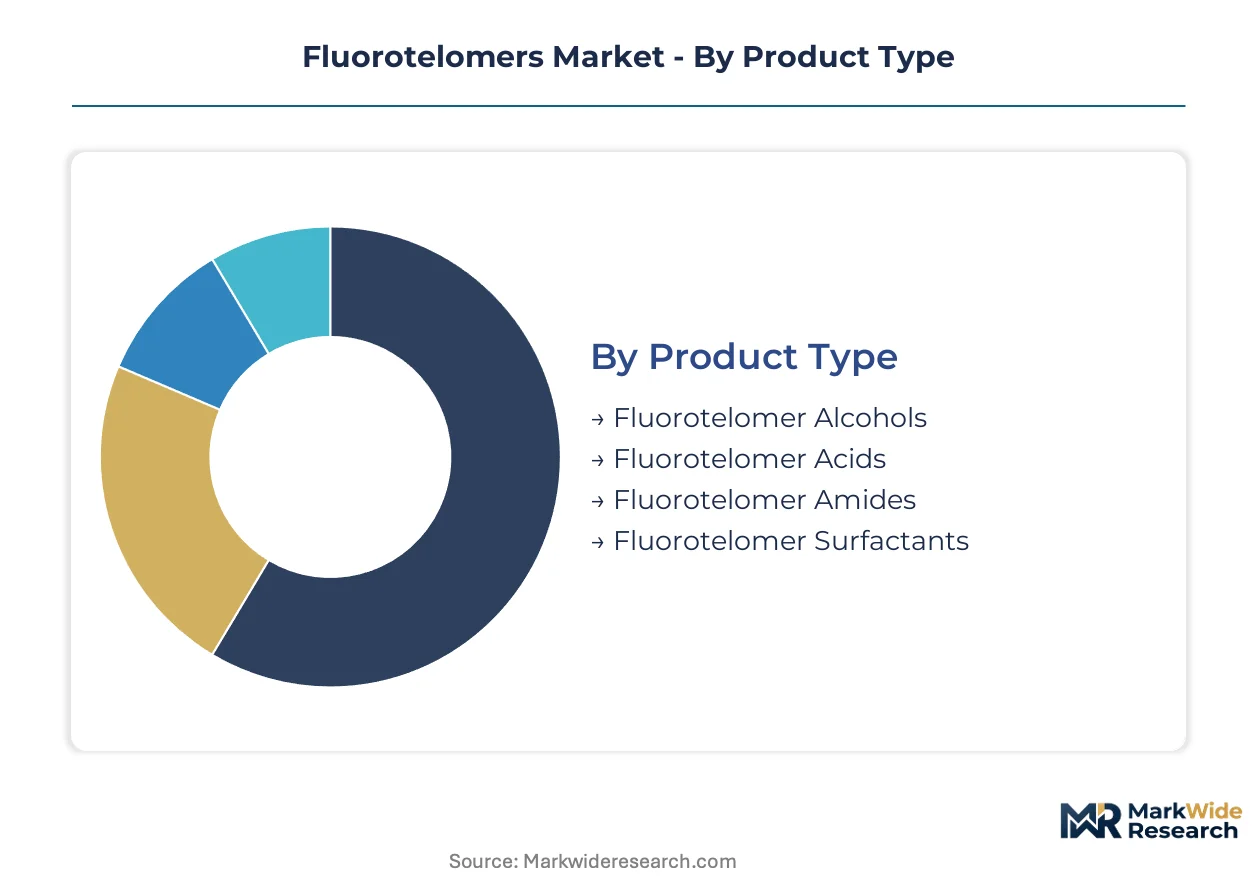
Fluorotelomer chemistry varies sharply in performance characteristics and regulatory exposure across product architectures. Reformulation timelines differ by segment, with shorter-chain alternatives commanding premium positioning in restricted markets.
Product Type:
Replacement cycles accelerate where regulatory pressure intersects with high-volume industrial use, forcing rapid qualification of next-generation chemistries.
- Fluorotelomer Alcohols:These C6-C12 terminal alcohols serve as the dominant precursor intermediates for textile and paper repellent finishes. Demand concentrates in China's Zhejiang textile belt, where integrated finishing houses seek supply security amid REACH-driven reformulation mandates.
- Fluorotelomer Surfactants:Ultra-purity specifications for semiconductor wafer cleaning distinguish this category, with Taiwanese and South Korean fabs pulling volume from legacy industrial applications. METI incentives in Japan favor these chemistries for low-GWP thermal management systems.
- Fluorotelomer Acids:Perfluorinated carboxylic acids occupy stable positions in firefighting foam formulations despite EPA phase-out pressures on legacy long-chain variants.
- Fluorotelomer Amides:These derivatives find niche utility in specialized coating additives where amide functionality enhances substrate adhesion.
Volume placements concentrate in Fluorotelomer Alcohols; the faster expansion belongs to Fluorotelomer Surfactants.
End Use Industry:
Margin structures diverge sharply between specification-driven electronics applications and price-sensitive textile finishing.
- Textiles:Durable water repellent finishes for outdoor apparel and technical fabrics generate the largest absolute demand, with European brand owners compressing supplier qualification cycles to 12-18 months.
- Electronics:Advanced node semiconductor manufacturing in Taiwan and South Korea requires sub-ppb purity specifications, creating captive supply relationships with Japanese and Korean chemical specialists.
- Coatings:Industrial and automotive protective coatings leverage fluorotelomer additives for chemical resistance, with China's domestic production integration reducing import dependency.
- Food Packaging:Grease-resistant paper and board treatments face tightening FDA and EFSA scrutiny, redirecting formulation toward shorter-chain alternatives with clearer toxicological profiles.
Revenue concentrates in Textiles; the steepest expansion trajectory appears in Electronics.
Form:
Physical state selection tracks application equipment compatibility and active ingredient concentration requirements.
- Liquid:Pumpable concentrates dominate textile finishing operations, enabling continuous pad-dry-cure application with precise bath concentration control.
- Emulsion:Aqueous dispersions serve water-based coating systems and environmental compliance in emissions-regulated manufacturing zones.
- Solid:Pelletized forms support extrusion compounding for polymer additive masterbatches.
- Powder:Dry formulations address specialized powder coating and dry-blend polymer applications with minimal solvent exposure.
Volume concentrates in Liquid formulations; Emulsion formats gain share fastest in regulated European markets.
Application:
Performance tier differentiation separates premium specifications from commodity replacements across functional categories.
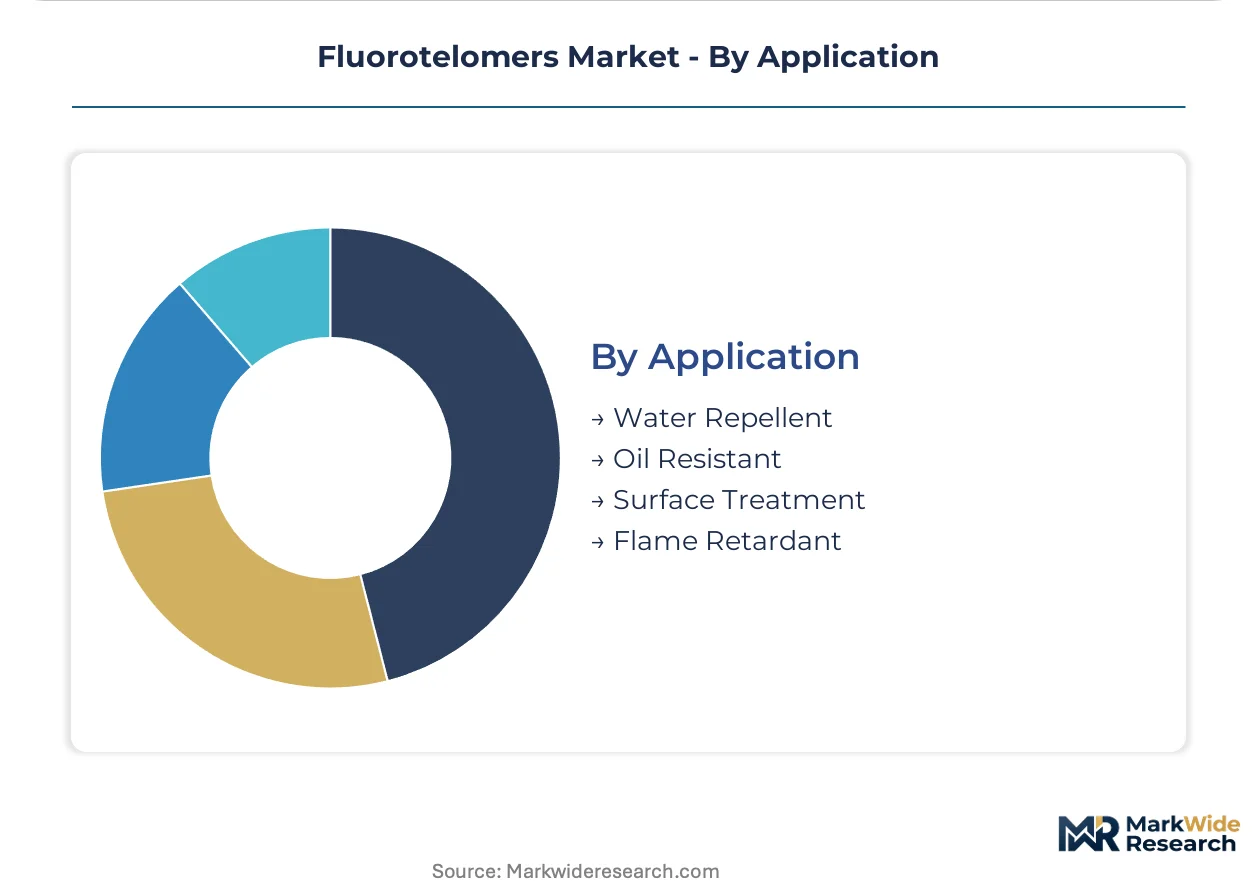
- Water Repellent:Hydrophobic surface treatments for textiles and leather command the largest volume position, with C6-based reformulations displacing legacy C8 chemistry in EU and US markets.
- Oil Resistant:Oleophobic barriers in food service papers and industrial fabrics require precise fluorotelomer chain-length optimization for grease angle performance.
- Surface Treatment:Electronics cleaning and semiconductor processing applications demand the highest purity grades, with Japanese suppliers leading ionic contamination control.
- Flame Retardant:Fire suppression foam formulations utilize fluorotelomer surfactants for film-forming properties, though ECHA restrictions threaten this application's longevity.
Volume placements concentrate in Water Repellent treatments; Surface Treatment applications expand most quickly in East Asian electronics clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates fluorotelomer production capacity while the United States and Germany drive premium consumption for electronics and industrial applications. Regulatory divergence between REACH restrictions in Europe and EPA frameworks in North America is fragmenting formulation strategies across major demand centers.
China
Integrated fluorochemical production in Zhejiang and Jiangsu provinces supplies domestic textile finishers and electronics manufacturers with captive C6-based intermediates. MEE enforcement of GB 31572 emissions standards is consolidating dispersed operations into licensed chemical industry parks with centralized thermal oxidation capabilities. Hangzhou Bay economic zone anchors this consolidation, with membrane filtration investments rising to meet discharge permit requirements.
United States
Semiconductor fabrication in Arizona and Texas pulls ultra-purity fluorotelomer surfactants for advanced node wafer cleaning processes. EPA regulation under the Toxic Substances Control Act constrains long-chain chemistry introductions through significant new use rules. Gulf Coast petrochemical corridors host reformulation R&D for firefighting foam alternatives as legacy PFAS phase-outs accelerate.
Germany
Technical textile finishing in Baden-Württemberg and North Rhine-Westphalia demands Bluesign-certified fluorotelomer alcohols for outdoor apparel supply chains. ECHA restrictions on per- and polyfluoroalkyl substances are freezing investment decisions pending broader PFAS grouping definitions. Bavarian chemical parks concentrate telomerization expertise among specialized process engineers nearing retirement.
Japan
Electronics chemical suppliers in Kansai and Chubu regions lead ionic contamination control for 3nm semiconductor manufacturing. METI incentives for low-GWP industrial processes favor fluorotelomer-based thermal management fluids in data center cooling applications. Osaka-based specialists pioneer precise chain-length telomerization to meet sub-ppb purity specifications.
South Korea
Memory and logic chip production in Gyeonggi Province and around Hsinchu pulls high-purity fluorotelomer surfactants from Japanese and domestic chemical partners. MFDS chemical safety assessments align with EU REACH restrictions, accelerating C6 chemistry adoption in electronics supply chains. Pangyo technovalley clusters semiconductor materials R&D with captive analytical validation capabilities.
Fluorotelomers Market Vendor Landscape
The competitive structure tilts toward vertically integrated fluorochemical conglomerates with captive tetrafluoroethylene supply and telomerization expertise. Three to five multinational chemical groups control premium-grade fluorotelomer surfactants for semiconductor applications, while mid-tier regional producers compete on textile alcohol volumes. Strategic archetypes span integrated fluoromonomer-to-polymer producers, specialized electronics chemical suppliers, and state-affiliated Chinese chemical groups. Capacity consolidation and backward integration into fluoromonomer production represent the dominant competitive moves as feedstock security determines margin stability.
Among North American and European integrated producers, The Chemours Company and Solvay occupy positions exemplifying vertical control from fluoromonomers through finished fluorotelomer derivatives. Daikin Industries represents the specialized electronics chemical archetype with concentrated expertise in fluorotelomer iodide intermediates. These three entities anchor the premium tier where purity specifications and regulatory compliance capabilities separate viable suppliers from commodity competitors.
| Leading Market Players |
|---|
| The Chemours Company |
| Daikin Industries |
| 3M |
| Solvay |
| Arkema |
| AGC Chemicals |
| Dongyue Group |
| Gujarat Fluorochemicals |
| Honeywell International |
| Others |
Supply Flow & Price Mechanics
Tetrafluoroethylene feedstock volatility cascades through fluorotelomer supply chains into three-tier pricing structures across premium, standard, and economy levels. C6-based reformulation premiums in EU REACH-regulated markets diverge sharply from commodity textile alcohol pricing in China's Zhejiang belt.
Pricing Analysis
Yield-based pricing anchors ultra-purity fluorotelomer surfactants for semiconductor wafer cleaning, where sub-ppb contamination control justifies substantial premiums over industrial grades. Certification tier—Bluesign versus standard technical grade—drives price differentiation alongside volume scale. Cost compression in textile alcohols is intensifying because silicone-based repellents capture mid-tier outdoor apparel share. Electronics manufacturers exhibit least price sensitivity; commodity textile finishers face acute margin pressure.
Supply Chain Analysis
Fluorine chemist scarcity in Germany and Japan constrains telomerization process optimization across concentrated manufacturing geographies. China, Japan, and the United States anchor global supply, drawing from captive tetrafluoroethylene, pentafluoroethyl iodide, and hydrofluoric acid feedstocks. Single-source vulnerability concentrates in Japanese electronics chemical specialists holding 3nm node purification expertise. Distribution runs through integrated chemical industry parks with centralized effluent treatment in Zhejiang and direct mill-supply relationships in Baden-Württemberg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorotelomer chemistry is navigating a forced transition from C8-based legacy formulations to C6 and shorter-chain architectures, with precise chain-length telomerization replacing conventional free-radical processes.
For Market Incumbents: To counter ECHA's proposed broad PFAS grouping that threatens to capture shorter-chain fluorotelomers, Chemours and Solvay should accelerate backward integration into fluoromonomer production to secure feedstock cost control. Daikin must deepen R&D intensity in fluorotelomer iodide intermediates to maintain purity leadership for 3nm semiconductor nodes. Certification investment in Bluesign and OEKO-TEX documentation systems preserves premium positioning against commodity regional producers. For New Entrants and Emerging Players: Launch via technical service partnerships with India's PLI scheme beneficiaries in man-made fiber and protective fabric segments. Vietnam's semiconductor assembly relocation from China presents white-space demand for high-purity surfactants. Target captive supply relationships with Taiwanese and South Korean fabs seeking second-source qualification beyond Japanese incumbents. Specialty fluorotelomer amides for coating adhesion modifiers offer penetrable niche entry with lower capital barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier Chinese fluorochemical groups facing MEE emissions compliance costs in Zhejiang consolidation. Long-term viability hinges on reformulation agility across C4-to-C12 chain-length portfolios rather than single-chemistry dependence. Watch ECHA's final PFAS grouping definition as the critical inflection signal determining stranded asset risk in European manufacturing footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoromonomer Production | Chemours' captive tetrafluoroethylene supply insulates margins from energy cost spikes. |
| Green Manufacturing Transition | MEE GB 31572 compliance investments redirect capacity toward licensed chemical industry parks. |
| Long-term Supply Agreement | Taiwanese fabs secure sub-ppb surfactant allocation through multi-year Japanese specialist contracts. |
| Joint Venture | Indian PLI scheme partnerships enable local technical service presence for textile finishers. |
| Capacity Expansion | Zhejiang consolidation into Hangzhou Bay parks centralizes thermal oxidation capabilities. |
Methodological Framework
Independent corroboration across telomerization process engineers, textile finishing house procurement leads, semiconductor fab chemical managers, and fluorochemical distribution channel partners underwrites the qualitative findings. Secondary validation draws from SEC 10-K filings, Cefic fluorochemical trade data, EPA TSCA significant new use rule dockets, and MEE GB standards documentation. Bottom-up capacity assessments across Zhejiang and Jiangsu provinces triangulate with top-down demand modeling from electronics and textiles end-use segments.
Rate-of-change decomposition separates volume growth from mix-shift effects across the analysis window. Segmentation dimensions include product type (alcohols, surfactants, acids, amides), end-use industry (textiles, electronics, coatings, food packaging), form (liquid, emulsion, solid, powder), and application (water repellent, oil resistant, surface treatment, flame retardant). CAGRs derive from regression against semiconductor wafer starts, textile production indices, and regulatory phase-out timelines. Tetrafluoroethylene feedstock cost trajectories and REACH reformulation compliance costs inform price elasticity assumptions.
ECHA PFAS grouping finalization, MEE enforcement intensity in Zhejiang, and silicone repellent technology advancement are the dominant revision risks. Forecasts reflect documented assumptions on chain-length substitution rates and regional regulatory divergence. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Organo-Modified Siloxanes Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
Precipitated Barium Sulfate Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Organo-Modified Bentonite Market
Specialty Chemicals
Bismuth Oxychloride Market
Specialty Chemicals
Panthenol Market