
 Shikimic Acid Market | 2026-2036
Shikimic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Shikimic Acid Market Outlook
Fermentation-derived shikimic acid is decoupling from traditional star anise extraction economics, slashing raw material dependency on cyclical agricultural harvests. JIAHERB leverages its botanical extraction heritage to sustain dual-source supply chains across natural and biotech routes. Wuhan Dahua Weiye anchors regional production capacity through integrated fermentation infrastructure in Hubei province. Sanofi competes on pharmaceutical-grade certification, controlling access to regulated drug precursor markets through stringent quality protocols.
Shikimic acid is a cyclohexene carboxylic acid (C7H10O5) serving as the biosynthetic precursor to aromatic amino acids and a critical chiral building block for neuraminidase inhibitor synthesis, with industrial production requiring stereospecific hydroxylation at the 3,4,5-positions. Pharmaceutical-grade fermentation output commands premium positioning due to FDA and EMA precursor documentation mandates, while natural extraction from Illicium verum fruit remains cost-competitive for nutraceutical applications. Biochemical process development is accelerating as synthetic biology platforms engineer microbial strains with enhanced phosphoenolpyruvate flux toward the shikimate pathway, displacing legacy chemical synthesis routes for industrial-grade material.
China's NMPA enforces Good Manufacturing Practice standards for active pharmaceutical ingredient precursors, while the US FDA maintains import alert protocols on unregistered foreign drug facilities, and the EU REACH framework governs chemical registration for non-pharmaceutical industrial applications. These overlapping compliance architectures elevate barrier costs for uncertified producers and consolidate procurement relationships with validated fermentation houses. Stakeholders must monitor regulatory harmonization between pharmacopeial standards and emerging synthetic biology governance frameworks as next-generation microbial production scales toward commercial volumes.
Market Dynamics
Fermentation-derived production is decoupling shikimic acid supply from Illicium verum harvest volatility, concentrating manufacturing capacity in integrated biotech clusters where phosphoenolpyruvate pathway engineering slashes raw material exposure.
Growth Catalysts
- NMPA precursor documentation mandates:China's tightened GMP standards for active pharmaceutical ingredient precursors redirect procurement toward certified fermentation houses with validated quality protocols.
- Neuraminidase inhibitor synthesis demand:Pharmaceutical manufacturers expand antiviral drug programs, requiring stereospecific hydroxylation capabilities that natural extraction cannot reliably deliver.
- Synthetic biology platform maturation:Engineered microbial strains with enhanced shikimate pathway flux displace legacy chemical synthesis routes, compressing production timelines for industrial-grade material.
Market Restraints
- Star anise harvest cyclicality:Natural extraction feedstock availability fluctuates with agricultural conditions in Guangxi and Yunnan provinces, creating input cost instability for dual-source suppliers.
- FDA import alert protocols:Unregistered foreign drug facilities face exclusion from US pharmaceutical precursor markets, elevating compliance costs for uncertified producers.
- Biochemical process capex intensity:Fermentation infrastructure requires substantial capital deployment for bioreactor capacity, downstream purification, and sterile handling systems.
Strategic Opportunities
- Nutraceutical grade white space:Natural extraction from Illicium verum retains cost competitiveness for dietary supplement applications where pharmaceutical certification is not required.
- EU REACH framework harmonization:Chemical registration governance for non-pharmaceutical industrial applications creates pathway for fermentation-derived material in specialty chemical markets.
- Integrated fermentation-to-extraction facilities:East China pharmaceutical manufacturing clusters offer co-location advantages for producers controlling both biotech and botanical supply routes.
Industry Challenges
- Stereospecific hydroxylation expertise scarcity:Industrial-scale 3,4,5-position chiral chemistry requires specialized biocatalysis talent that outpaces current technical training pipelines.
- Dual certification timeline compression:Simultaneous NMPA and FDA validation for pharmaceutical-grade output extends qualification periods, delaying revenue recognition for new capacity.
- Synthetic biology governance uncertainty:Emerging microbial production oversight frameworks create compliance ambiguity as next-generation strains approach commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shikimic Acid Market |
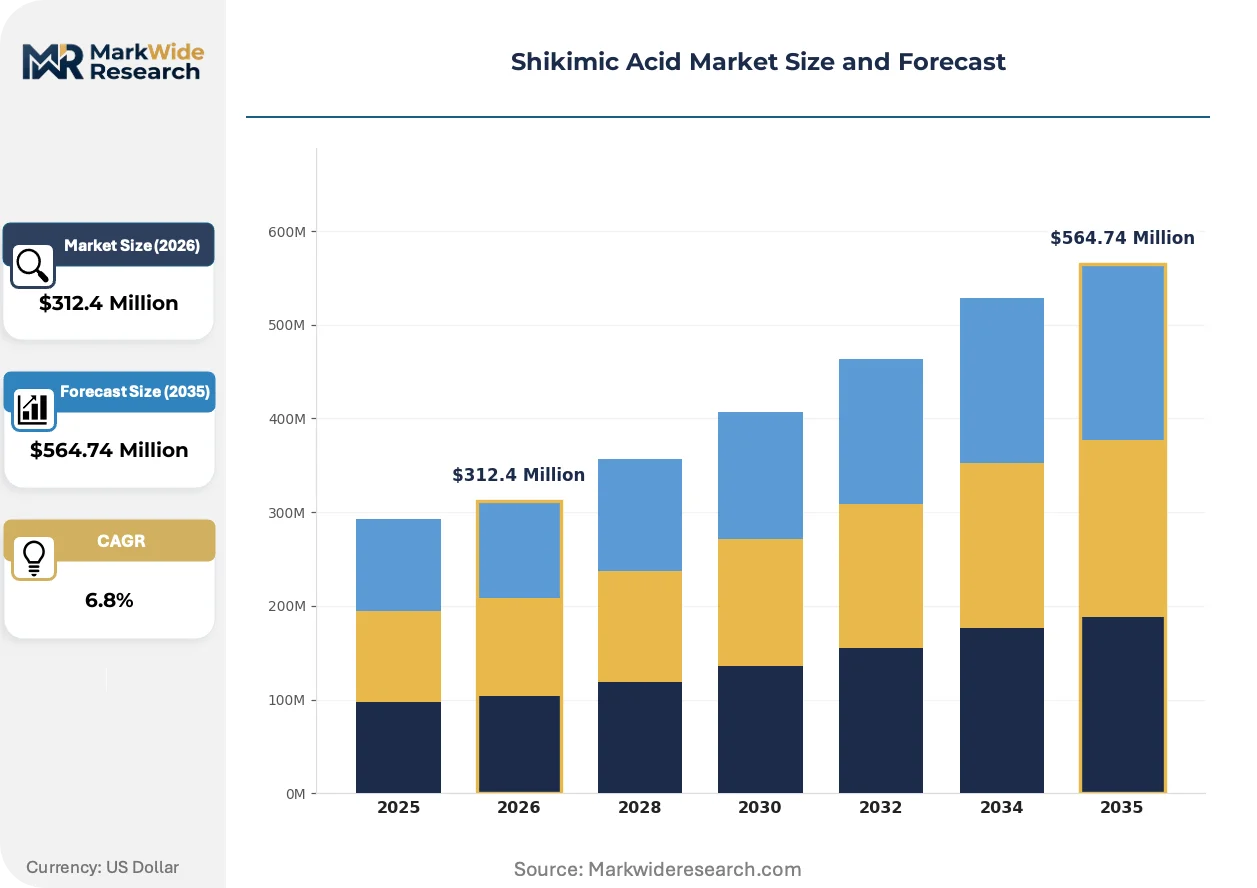
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Synthesis, Natural Extraction, Fermentation-Based, Biochemical Process Application: Pharmaceuticals, Nutraceuticals, Agrochemicals, Cosmetics Purity Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | JIAHERB, Wuhan Dahua Weiye, Sanofi, DSM, Shanghai Pharmaceuticals, Layn, Sichuan Xieli Pharmaceutical, Roche Holding AG, Guangxi Wanshan Spice, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shikimic Acid Market Strategic Shifts
Microbial strain engineering and regulatory documentation convergence are compressing the competitive window for legacy extraction-based supply chains while opening premium positioning for validated biotech producers.
CRISPR-enabled pathway optimization is absorbing phosphoenolpyruvate flux toward shikimate production in engineered Escherichia coli and yeast platforms. Pharmaceutical manufacturers are adopting these biocatalytic routes for neuraminidase inhibitor precursors, locking in multi-year offtake agreements with fermentation houses. The technology is absorbing margin pressure from agricultural feedstock volatility by substituting controlled bioreactor environments for weather-dependent harvests.
REACH chemical registration requirements in Europe are tightening documentation for non-pharmaceutical industrial applications of shikimic acid derivatives. Manufacturers must submit comprehensive safety dossiers to ECHA for downstream chemical intermediates, elevating barrier costs for uncertified suppliers. Specialty chemical buyers in Germany and France are consolidating procurement with REACH-registered fermentation houses to preempt supply disruption.
Certificate-driven supplier qualification is compressing procurement cycles for pharmaceutical-grade material. Large antiviral drug manufacturers in the United States and China are bypassing spot markets, instead embedding validated fermentation producers into long-term precursor agreements. This behavior shift concentrates demand among NMPA- and FDA-certified suppliers, marginalizing natural extraction houses lacking dual-jurisdiction documentation.
Shikimic Acid Market Segmentation
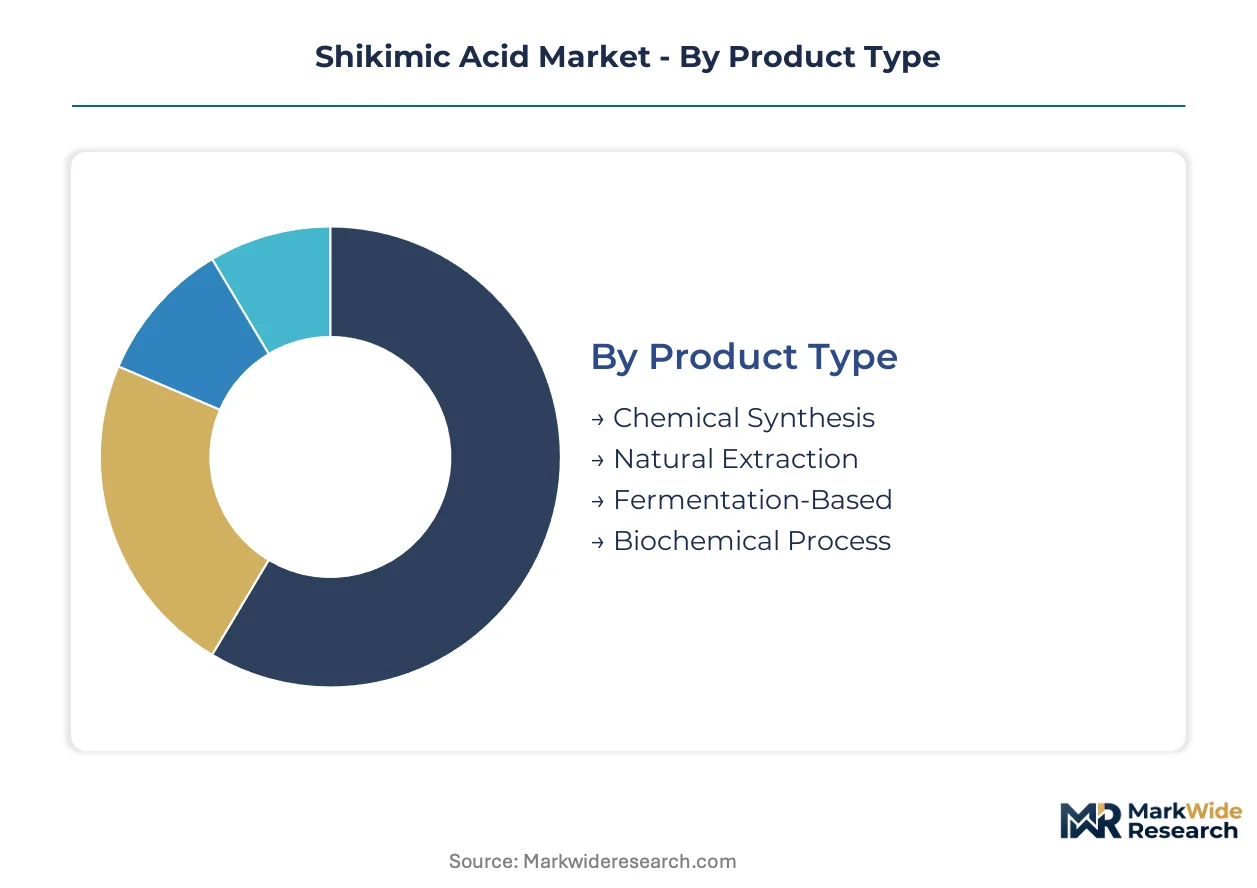
Shikimic acid procurement splits sharply across certification tiers, with pharmaceutical-grade fermentation commanding premium positioning while natural extraction retains cost advantages in less regulated end-uses. Segment boundaries harden around documentation requirements from NMPA, FDA, and EMA, creating divergent competitive arenas.
Product Type:
Fermentation-based and biochemical routes carry heavier regulatory documentation burdens than legacy extraction methods, with pharmaceutical precursors requiring validated GMP protocols.
- Fermentation-Based:Engineered microbial platforms in controlled bioreactor environments deliver stereospecific hydroxylation at the 3,4,5-positions. Demand concentrates in East China pharmaceutical clusters where integrated facilities combine upstream strain engineering with downstream purification. NMPA and FDA precursor mandates redirect procurement toward certified fermentation houses with validated quality systems.
- Natural Extraction:Isolation from Illicium verum fruit in Guangxi and Yunnan provinces retains cost competitiveness where pharmaceutical certification is not required. Harvest cyclicality creates input cost instability, pushing dual-source suppliers toward biotech alternatives for regulated applications.
- Chemical Synthesis:Legacy petrochemical routes face displacement as synthetic biology platforms compress production timelines for industrial-grade material.
- Biochemical Process:CRISPR-enabled pathway optimization in Escherichia coli and yeast absorbs phosphoenolpyruvate flux toward enhanced shikimate yields.
Fermentation-based production sits at the top of the volume ranking, with biochemical process climbing the fastest as next-generation strains approach commercial scale.
Application:
End-use segments diverge by documentation intensity, with antiviral drug synthesis imposing the strictest precursor protocols.
- Pharmaceuticals:Neuraminidase inhibitor programs require stereospecific chiral building blocks that natural extraction cannot reliably deliver. Large antiviral manufacturers in the United States and China embed validated fermentation producers into long-term precursor agreements, bypassing spot markets entirely.
- Nutraceuticals:Dietary supplement applications accept natural extraction from Illicium verum where FDA and EMA pharmaceutical mandates do not apply. Cost-conscious buyers in this segment prioritize agricultural feedstock economics over biotech premium positioning.
- Agrochemicals:Specialty chemical intermediates fall under EU REACH registration requirements, elevating barrier costs for uncertified suppliers.
- Cosmetics:Chiral precursors for active cosmetic ingredients drive modest demand for technical-grade material with intermediate purity thresholds.
Pharmaceuticals captures the dominant revenue share, with nutraceuticals expanding most quickly as wellness product pipelines diversify.
Purity Grade:
Grade stratification locks in three-tier pricing across certification levels, with pharmaceutical-grade material separated by documentation rather than composition alone.
- Pharmaceutical Grade:Active pharmaceutical ingredient precursor standards enforced by NMPA GMP and FDA import alert protocols. Sterile handling systems and downstream purification infrastructure command substantial capital deployment.
- Food Grade:Dietary supplement applications under FSSAI and national food safety frameworks permit natural extraction methods with lower barrier costs.
- Industrial Grade:Chemical intermediate applications governed by REACH and national chemical registration schemes.
- Technical Grade:Research and development consumption with minimal regulatory documentation requirements.
Pharmaceutical grade maintains the steepest price premium, with food grade gaining share fastest as nutraceutical formulators scale procurement.
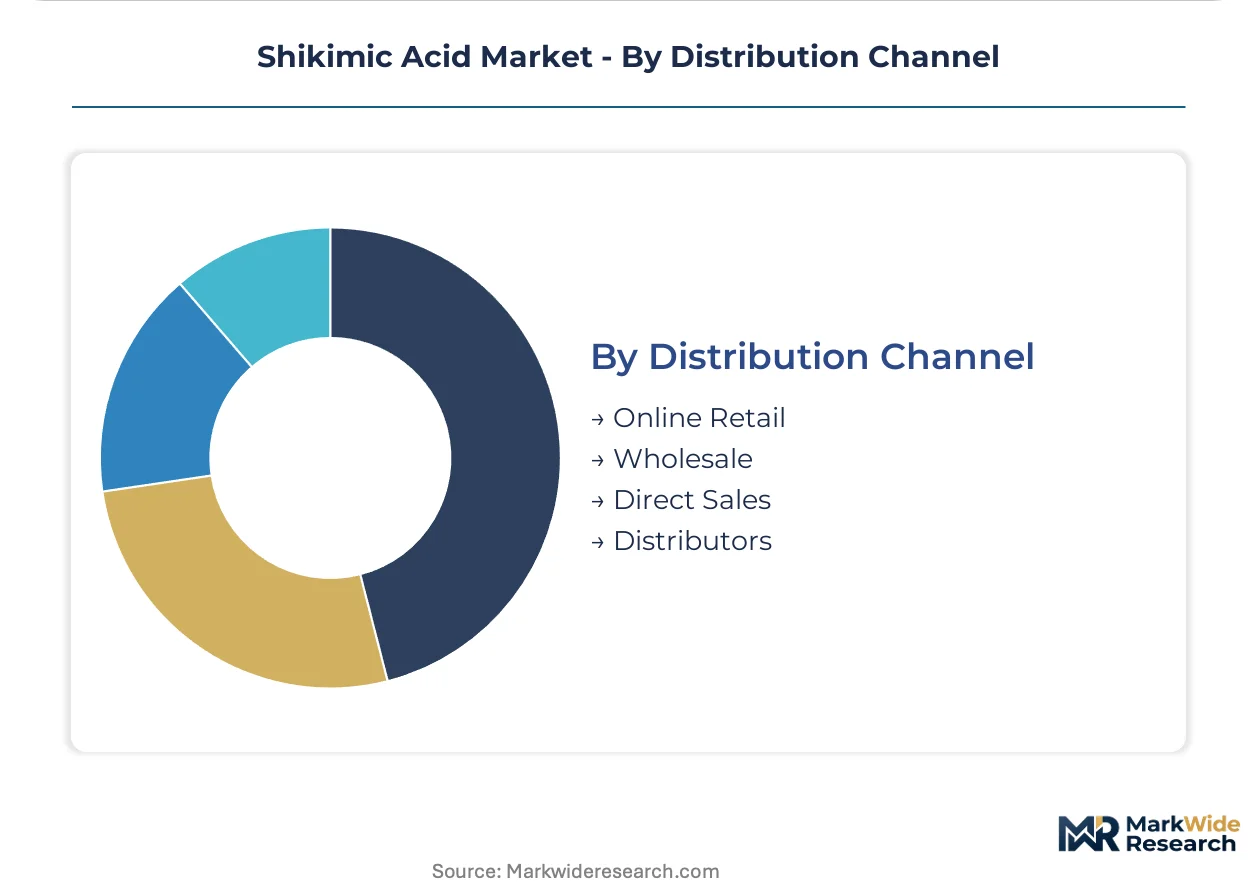
Distribution Channel:
Channel selection tracks customer scale and documentation sensitivity, with large pharmaceutical buyers consolidating direct relationships.
- Direct Sales:Multi-year offtake agreements between antiviral drug manufacturers and validated fermentation houses concentrate procurement among NMPA- and FDA-certified suppliers. Certificate-driven qualification compresses procurement cycles for pharmaceutical-grade material.
- Distributors:Specialty chemical buyers in Germany and France consolidate procurement with REACH-registered fermentation houses to preempt supply disruption.
- Wholesale:Industrial-grade material moves through regional chemical distributors serving agrochemical and cosmetics compounders.
- Online Retail:Technical-grade and small-volume research quantities transact through digital platforms with minimal regulatory friction.
Direct sales dominates pharmaceutical volume, with distributor channels climbing fastest as REACH-registered European buyers consolidate supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East China's pharmaceutical manufacturing clusters anchor global shikimic acid production, with integrated fermentation-to-extraction facilities concentrating capacity in Jiangsu and Zhejiang provinces. Regulatory divergence across major markets is fragmenting procurement patterns and elevating compliance costs for uncertified suppliers.
China
Antiviral drug manufacturers in Shanghai and Suzhou expand fermentation-derived precursor procurement as NMPA enforces stricter GMP documentation for active pharmaceutical ingredients. The national regulator's import alert protocols now require validated quality systems for domestic facilities supplying international markets. Hubei province's Wuhan biotech corridor anchors regional fermentation infrastructure, with phosphoenolpyruvate pathway engineering displacing legacy chemical synthesis routes.
United States
Large pharmaceutical compounders embed certified fermentation houses into multi-year offtake agreements, bypassing spot markets entirely for neuraminidase inhibitor precursors. FDA import alert protocols exclude unregistered foreign drug facilities, consolidating procurement among validated suppliers with dual-jurisdiction documentation. The New Jersey-Pennsylvania pharmaceutical corridor concentrates demand from antiviral program sponsors requiring stereospecific hydroxylation capabilities.
Germany
Specialty chemical buyers consolidate procurement with REACH-registered fermentation houses to preempt supply disruption for non-pharmaceutical industrial applications. ECHA's tightened documentation requirements for shikimic acid derivatives elevate barrier costs for uncertified suppliers seeking chemical intermediate markets. The Rhine-Ruhr industrial basin hosts downstream compounders integrating fermentation-derived material into agrochemical and cosmetic ingredient supply chains.
India
Domestic pharmaceutical formulators expand precursor sourcing as CDSCO aligns active pharmaceutical ingredient standards with international pharmacopeial requirements. The national regulator's tightened purity documentation redirects procurement toward certified fermentation-based suppliers for export-oriented drug programs. Gujarat's Ahmedabad-Vadodara pharmaceutical cluster concentrates contract manufacturing demand, with Maharashtra's Mumbai-Pune corridor hosting import-dependent compounders.
Switzerland
Swissmedic's pharmaceutical-grade certification requirements concentrate demand among fermentation houses with validated sterile handling systems and downstream purification infrastructure. Basel's biopharmaceutical hub anchors European neuraminidase inhibitor precursor demand, with Lake Geneva corridor facilities serving as quality gatekeepers for continental supply. The country's dual-jurisdiction documentation expertise supports FDA-EMA parallel validation for global antiviral drug sponsors.
Shikimic Acid Market Competitive Environment
Global majors compete with regional champions across certification tiers, with pharmaceutical-grade fermentation capacity consolidating among dual-jurisdiction validated suppliers while natural extraction houses retain cost positioning in nutraceutical segments. The vendor base stratifies into three tiers: integrated biotech platforms with synthetic biology capabilities, botanical extraction specialists with agricultural feedstock relationships, and hybrid operators controlling both supply routes. Dominant competitive moves include backward integration into fermentation infrastructure and geographic expansion through distributor partnerships in REACH-regulated European markets.
Within the integrated biotech tier, Sanofi and DSM exemplify pharmaceutical-grade certification strategies, occupying positions as quality gatekeepers for regulated drug precursor markets. Among China-based operators, JIAHERB and Wuhan Dahua Weiye represent dual-source supply models, anchoring regional capacity through combined fermentation and botanical extraction capabilities. These named entities illustrate how certificate-driven supplier qualification compresses procurement cycles and concentrates demand among validated producers.
| Leading Market Players |
|---|
| JIAHERB |
| Wuhan Dahua Weiye |
| Sanofi |
| DSM |
| Shanghai Pharmaceuticals |
| Layn |
| Sichuan Xieli Pharmaceutical |
| Roche Holding AG |
| Guangxi Wanshan Spice |
| Others |
Value Chain & Pricing Dynamics
Star anise spot prices in Guangxi province cascade through fermentation-derived shikimic acid production, compressing margins for dual-source suppliers when agricultural harvests underperform while biotech routes capture pricing power through NMPA-certified premium tiers.
Pricing Analysis
Input-cost pass-through from Illicium verum harvest volatility splits the market into contract-based long-term offtake agreements for pharmaceutical-grade material and commodity spot exposure for nutraceutical buyers. Price differentiation hinges on FDA-NMPA dual certification and sterile handling infrastructure deployment. Cost compression in natural extraction tiers is intensifying because fermentation platforms displace agricultural dependency for regulated applications. Nutraceutical formulators exhibit highest price sensitivity, while antiviral drug manufacturers lock in multi-year premiums with validated fermentation houses.
Supply Chain Analysis
Shikimic acid supply rests on Chinese fermentation infrastructure in Jiangsu and Zhejiang provinces, with secondary concentration in Hubei biotech corridors and Swiss pharmaceutical-grade purification facilities. Raw material feeds draw from phosphoenolpyruvate pathway-engineered Escherichia coli strains, yeast platforms, and residual star anise agricultural harvests from Yunnan. Single-source vulnerability concentrates in East China pharmaceutical clusters where NMPA import alert protocols restrict facility registration. Distribution runs through direct sales channels for certified pharmaceutical precursors and specialty chemical distributors for REACH-registered industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where fermentation capex differentials between East China and European facilities exceed regulatory compliance cost gaps, rewarding capacity placement in integrated Jiangsu-Zhejiang corridors.
For Market Incumbents: Extend sterile handling certification coverage to preempt FDA import alert exposure for unregistered foreign facilities. Consolidate procurement relationships with dual-source suppliers controlling both Hubei fermentation infrastructure and Guangxi botanical extraction networks to hedge agricultural feedstock volatility.
For New Entrants and Emerging Players: REACH registration in Germany opens a window for fermentation-derived material in specialty chemical intermediate markets underserved by pharmaceutical-grade incumbents. Target nutraceutical-grade white space where FSSAI and national food safety frameworks permit natural extraction cost advantages, deploying distributor partnerships with European chemical buyers seeking ECHA-compliant supply.
For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid operators possessing validated microbial strain engineering platforms and existing agricultural feedstock relationships. Long-term viability centers on synthetic biology governance clarity as engineered yeast approaches commercial scale. Watch NMPA-FDA regulatory harmonization progress as the primary inflection signal for capacity valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Captures phosphoenolpyruvate pathway engineering capabilities in Hubei biotech corridors. |
| Dual-Jurisdiction Certification Investment | Unlocks NMPA-FDA validated supply relationships with US antiviral drug manufacturers. |
| REACH Registration for Chemical Intermediates | Opens ECHA-compliant pathways into German and French specialty chemical markets. |
| Long-term Supply Agreement with Antiviral Sponsors | Locks in multi-year offtake commitments bypassing spot market volatility. |
| Synthetic Biology Platform Development | Engineers CRISPR-enabled microbial strains with enhanced shikimate pathway flux. |
Study Parameters
Coverage spans East China pharmaceutical clusters, US antiviral drug manufacturing corridors, and European REACH-regulated chemical markets, with primary inputs from each. Fermentation plant managers, regulatory affairs leads at NMPA-certified facilities, procurement directors at neuraminidase inhibitor sponsors, and specialty chemical buyers in Germany contributed operational data. Secondary validation drew from FDA import alert databases, ECHA registration filings, customs trade records, and SEC 10-K disclosures from listed biotech operators. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Rate-of-change decomposition structured the analytical framework, segmenting by production route, purity grade, and end-use application across the projection horizon. Modeled dimensions included fermentation versus extraction sourcing, pharmaceutical versus nutraceutical certification tiers, and direct sales versus distributor channel structures. CAGRs derived from capacity buildout timelines, regulatory approval trajectories for engineered microbial strains, and substitution elasticity between natural and biotech feedstocks. Strain engineering breakthroughs and NMPA documentation mandate enforcement served as key forecast inputs.
Revisions become necessary when synthetic biology governance frameworks crystallize, star anise harvest failures exceed historical variance bands, or FDA-NMPA regulatory divergence accelerates. Forecasts reflect assumptions about microbial strain commercialization timelines, agricultural yield stability, and certification harmonization progress. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Barium Derivatives Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Glucosinolates Market
Specialty Chemicals
Organometallics Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Iron Phosphate Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Bio Polyol and Green Polyol Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market