
 Perchloroethylene Market | 2026-2036
Perchloroethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Perchloroethylene Market Analytics
A shift from single-source to multi-source chlorinated solvent procurement is pivoting how downstream buyers manage supply risk. Occidental Chemical Corporation leverages captive ethylene integration to sustain cost-advantaged perchloroethylene output across Gulf Coast infrastructure. Dow Chemical Company competes through specialized high-purity grades for electronics degreasing, while INEOS Group anchors European supply via Antwerp-Rotterdam pipeline networks.
Perchloroethylene, a chlorocarbon with the chemical formula C₂Cl₄, functions as a non-flammable solvent with a boiling point of 121 degrees Celsius and high degreasing efficacy for metal and textile applications. Industrial solvent applications dominate volume consumption as dry cleaning demand contracts under environmental pressure, whereas chemical intermediate usage extends fastest into fluoropolymer feedstock production. Cleaning agent formulations for precision electronics manufacturing command premium pricing due to ultra-low moisture specifications.
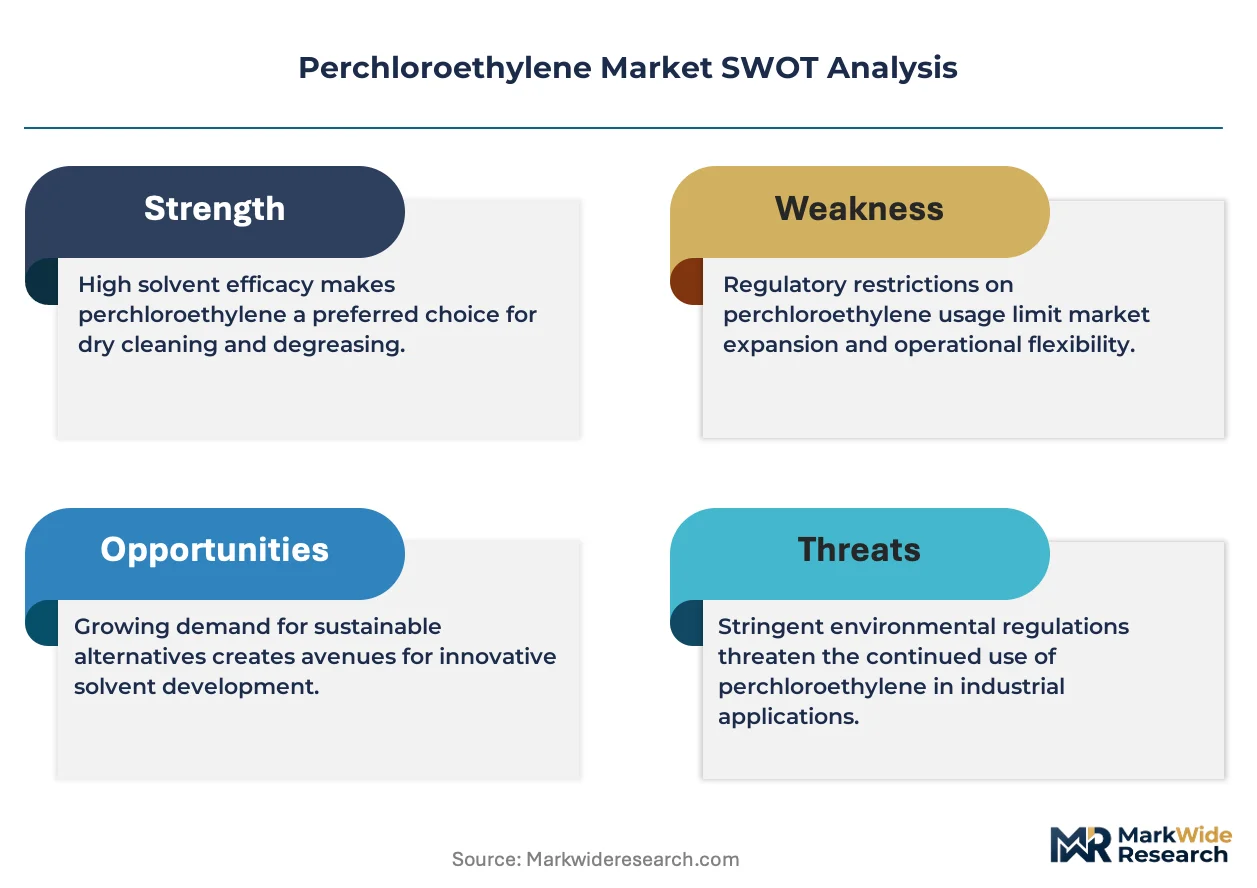
EPA toxicity assessments under the Toxic Substances Control Act restrict emissions thresholds for perchloroethylene facilities, while REACH registration requirements in Europe mandate downstream user communication chains. OSHA permissible exposure limits shape workplace handling protocols and drive investment in closed-loop vapor recovery systems. Stakeholders must monitor regulatory reclassification timelines and evaluate solvent substitution economics against captive recycling infrastructure costs.
Market Dynamics
EPA toxicity reviews under the Toxic Substances Control Act are compressing domestic manufacturing capacity while Chinese textile degreasing operations absorb diverted export volumes, restructuring how solvent suppliers allocate production assets across regulatory jurisdictions.
Growth Catalysts
- Fluoropolymer feedstock demand:Chemical intermediate applications for refrigerant and polymer precursors are expanding production lines at specialty chemical facilities.
- REACH registration compliance:European downstream user communication chains are consolidating procurement through certified distributors with verified supply documentation.
- Precision electronics manufacturing:Ultra-low moisture cleaning agent specifications for semiconductor fabrication are commanding sustained premium volume commitments.
Market Restraints
- Ethylene feedstock volatility:Gulf Coast ethylene supply disruptions transmit directly into perchloroethylene production cost structures.
- EPA emissions thresholds:Toxic Substances Control Act facility restrictions are capping domestic production expansion regardless of demand signals.
- Aqueous cleaning substitution:Water-based degreasing systems are displacing chlorinated solvents in automotive component pre-treatment operations.
Strategic Opportunities
- Closed-loop vapor recovery infrastructure:Captive recycling systems at dry cleaning service clusters are creating defensible local supply positions.
- India textile processing expansion:Surat and Tiruppur industrial zones are scaling solvent-based degreasing for synthetic fabric exports.
- OSHA exposure limit alignment:Workplace handling protocol investments are differentiating compliant suppliers from cost-only competitors.
Industry Challenges
- Closed-loop system engineering talent:Vapor recovery design specialists command scarcity premiums that compress project margins.
- Legacy equipment retrofit compatibility:Existing dry cleaning machinery requires costly adaptation for reduced-emission solvent formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perchloroethylene Market |
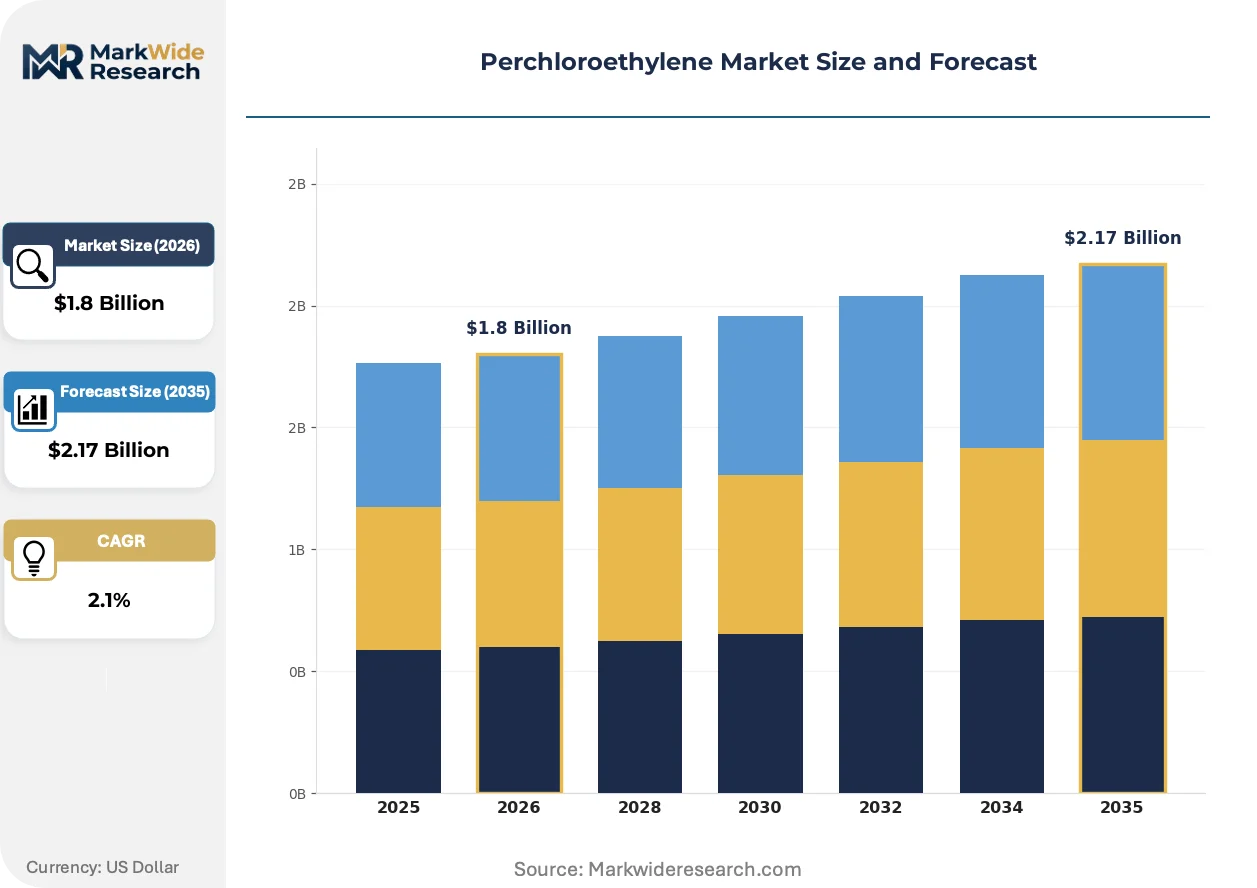
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Solvent, Cleaning Agent, Anesthetic, Chemical Intermediate Application: Textile Industry, Dry Cleaning, Degreasing, Adhesives End User: Manufacturers, Service Providers, Laboratories, Research Institutions Packaging Type: Drums, Bulk Containers, Cylinders, Bags |
| Companies Covered | Occidental Chemical Corporation, Olin Corporation, Westlake Chemical Corporation, AGC Inc., Kanto Denka Kogyo Co., Ltd., Arkema S.A., Dow Chemical Company, INEOS Group, Befar Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perchloroethylene Market Evolving Landscape
Closed-loop solvent recovery systems are compressing the effective supply chain by internalizing recycling within user facilities rather than external reprocessing, while regulatory pressure accelerates substitution economics across end-use verticals.
Membrane-based solvent purification technology is integrating into mid-scale dry cleaning operations, enabling on-site regeneration of spent perchloroethylene without external transport. Independent service providers in Germany and Japan are adopting these systems to deflect REACH and METI compliance costs. The technology is integrating distributed recycling capacity that fragments what was previously concentrated reprocessing demand.
EPA's ongoing reclassification review under the Toxic Substances Control Act is tightening permissible exposure benchmarks for chlorinated solvent facilities. Manufacturing sites in Texas and Louisiana are pre-emptively installing enhanced vapor capture infrastructure ahead of finalized rulemaking. Metal degreasing applications face the steepest compliance cost escalation as OSHA workplace limits converge with ambient air quality standards.
Multi-year solvent procurement contracts are fragmenting into shorter-term spot arrangements with certified recyclers. Electronics manufacturers in South Korea and Taiwan are unbundling chemical supply from waste disposal obligations, selecting suppliers based on documented recovery rates rather than unit pricing alone. This pattern is most visible in semiconductor fabrication clusters where MFDS chemical traceability requirements intersect with corporate sustainability commitments.
Perchloroethylene Market Segmentation
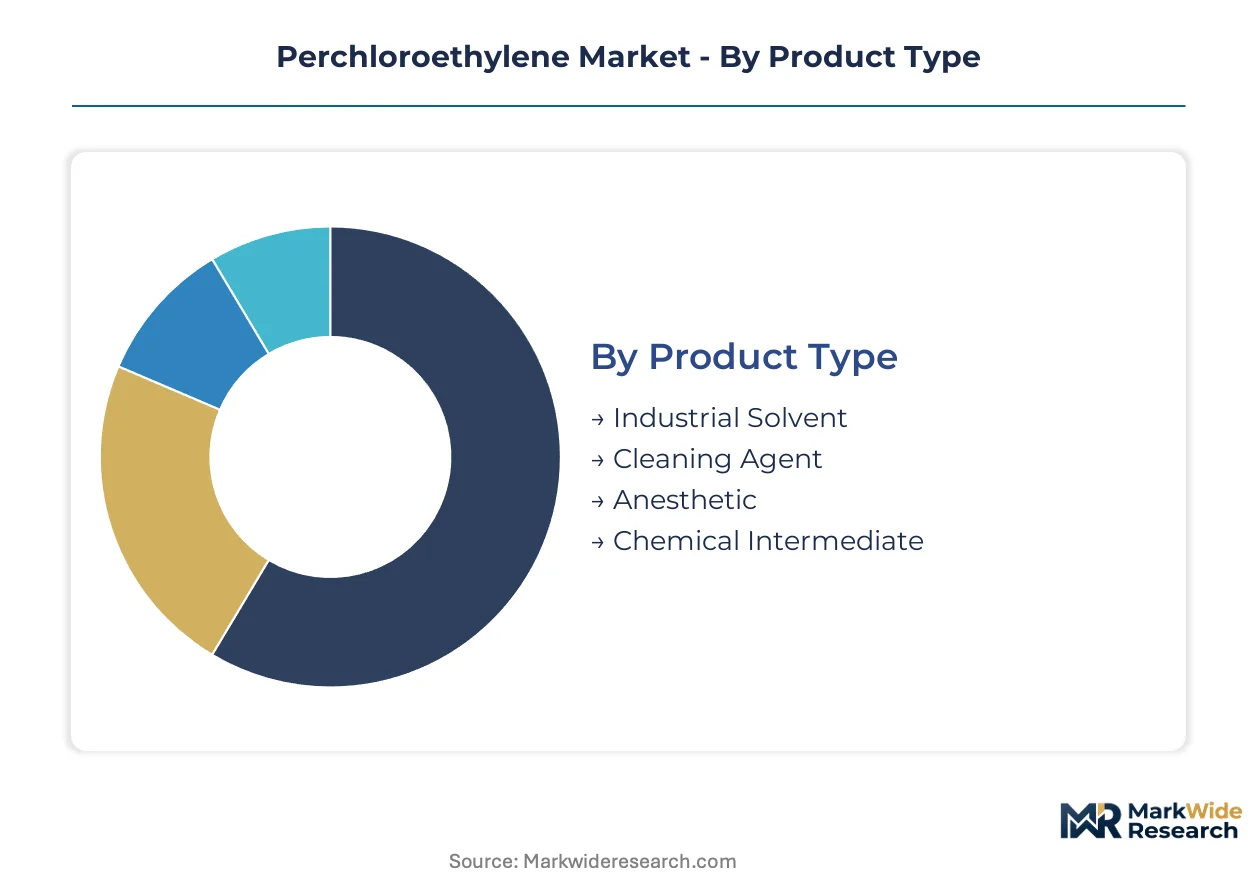
Perchloroethylene demand fragments across highly divergent use cases, from precision electronics cleaning to bulk fluoropolymer feedstock production. Understanding how capital requirements, regulatory exposure, and margin structures vary by segment enables suppliers to prioritize capacity allocation and compliance investments.
Product Type:
Industrial solvent grades demand the heaviest capital commitment, requiring dedicated chlorination reactors and integrated ethylene feedstock infrastructure that only integrated petrochemical players can sustain.
- Industrial Solvent:Technical-grade formulations with 99.9% purity specifications serve metal degreasing and heavy-duty cleaning operations. Chinese textile processing clusters in Zhejiang and Guangdong absorb the majority of volume as synthetic fabric production scales. EPA emissions thresholds under the Toxic Substances Control Act are compressing domestic manufacturing capacity and redirecting supply toward Asian markets.
- Cleaning Agent:Ultra-high purity grades with sub-10 ppm moisture content command premium positioning for semiconductor and precision electronics fabrication. South Korean semiconductor foundries in Pyeongtaek and Taiwanese fabrication clusters specify documented recovery rates as a procurement criterion alongside unit pricing.
- Anesthetic:Pharmaceutical-grade production requires GMP-compliant facilities with batch-level traceability systems. Limited active demand concentrates in specialized veterinary applications where regulatory approval pathways restrict supplier entry.
- Chemical Intermediate:Feedstock for refrigerant precursors and fluoropolymer production chains. Gulf Coast ethylene integration supports cost-advantaged output, though REACH registration requirements in Europe mandate downstream user communication documentation.
Industrial solvent absorbs the bulk of installed capacity; chemical intermediate is expanding most quickly.
Application:
Volume concentration varies sharply by end-use maturity, with legacy dry cleaning contracting under environmental pressure while precision degreasing climbs the fastest.
- Textile Industry:Synthetic fabric degreasing operations in Surat and Tiruppur industrial zones scale solvent procurement for export-oriented production. India's synthetic textile processing expansion is absorbing diverted supply as Chinese capacity rationalizes under environmental enforcement.
- Dry Cleaning:Traditional garment cleaning service providers face structural decline as aqueous and hydrocarbon alternatives displace chlorinated solvents. Closed-loop vapor recovery infrastructure investments now determine supplier viability in remaining solvent-based operations.
- Degreasing:Metal component pre-treatment for automotive and aerospace manufacturing commands stringent purity specifications. German automotive suppliers are retrofitting aqueous systems, compressing addressable market scope for chlorinated alternatives.
- Adhesives:Solvent-based formulation binders for industrial tape and sealant production. Moderate volume demand from packaging and construction adhesive manufacturers with limited growth momentum.
Degreasing claims the steepest expansion trajectory; dry cleaning sheds volume fastest.
End User:
Procurement sophistication separates large-scale manufacturers with integrated chemical management from fragmented service providers dependent on distributor networks.
- Manufacturers:Integrated chemical producers and downstream formulators with captive solvent recycling infrastructure. Electronics manufacturers in South Korea unbundle chemical supply from waste disposal obligations, selecting vendors on recovery documentation.
- Service Providers:Dry cleaning operators and contract degreasing facilities with distributed demand patterns. German independent service providers adopt membrane-based purification to deflect REACH compliance costs.
- Laboratories:Analytical and quality control facilities requiring small-batch, high-purity supply. Limited volume concentration with premium pricing tolerance for certified grades.
- Research Institutions:Academic and government research centers with irregular procurement patterns and extended qualification timelines.
Manufacturers concentrate procurement scale; service providers fragment demand geographically.
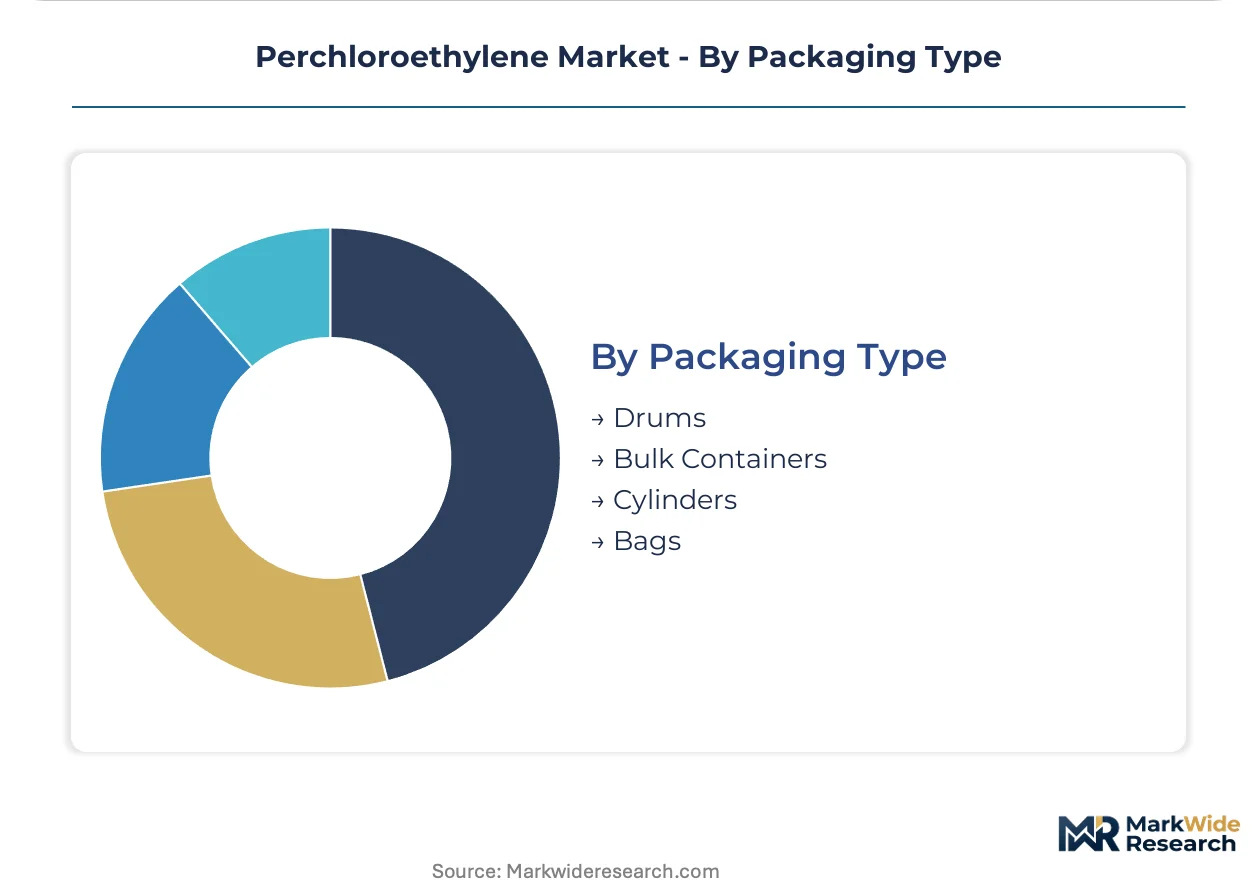
Packaging Type:
Logistics cost structures and handling safety requirements shape format selection across customer scale tiers.
- Drums:Standard 200-liter steel containers for mid-scale industrial users with moderate storage infrastructure. Balances unit economics against capital commitment for buyers without bulk handling systems.
- Bulk Containers:ISO tank and flexitank formats for high-volume manufacturers with integrated supply chain infrastructure. Antwerp-Rotterdam pipeline networks anchor European bulk distribution.
- Cylinders:Pressurized formats for specialized anesthetic and high-purity applications requiring inert atmosphere preservation. Limited demand concentration in pharmaceutical and electronics verticals.
- Bags:Flexible intermediate bulk containers for solid-phase precursor shipments and regional distributor repackaging operations.
Bulk containers dominate value concentration; drums retain widest customer reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast ethylene infrastructure anchors North American perchloroethylene production, while Chinese chlorination capacity absorbs diverted export volumes as EPA restrictions compress domestic manufacturing.
United States
Texas and Louisiana host the majority of domestic chlorocarbon production capacity, with Occidental Chemical Corporation leveraging integrated ethylene supply chains. EPA Toxic Substances Control Act reviews are tightening permissible emissions thresholds for chlorinated solvent facilities. Manufacturing sites in the Gulf Coast corridor are pre-emptively installing enhanced vapor capture infrastructure ahead of finalized rulemaking.
China
Zhejiang and Guangdong textile processing clusters drive solvent procurement for synthetic fabric degreasing operations. MEE environmental enforcement is rationalizing capacity in the Yangtze River Delta while permitting continues in coastal provinces. Surging fluoropolymer feedstock demand from refrigerant precursor production is redirecting chemical intermediate volumes toward domestic polymer chains.
Germany
Antwerp-Rotterdam pipeline networks anchor European bulk distribution, with INEOS Group sustaining supply through integrated chlor-alkali infrastructure. REACH registration requirements mandate downstream user communication chains that consolidate procurement through certified distributors. Independent service providers in the Ruhr industrial region are adopting membrane-based purification systems to deflect compliance costs.
India
Surat and Tiruppur industrial zones are scaling solvent-based degreasing for synthetic fabric exports to Middle Eastern and African markets. BIS quality standards for textile processing chemicals are tightening import specifications for chlorinated solvents. Gujarat's petrochemical corridor is attracting capacity expansion proposals from domestic chlor-alkali producers seeking backward integration into solvent manufacturing.
South Korea
Pyeongtaek semiconductor foundries specify ultra-low moisture cleaning agents with documented recovery rates as procurement criteria. MFDS chemical traceability requirements intersect with corporate sustainability commitments to fragment multi-year contracts into shorter-term spot arrangements. Electronics manufacturers in the Seoul Capital Area are unbundling chemical supply from waste disposal obligations.
Perchloroethylene Market Competitive Landscape
Global majors compete with regional champions across integrated feedstock access, with Gulf Coast ethylene infrastructure separating cost-advantaged producers from import-dependent operators. The vendor base concentrates around chlor-alkali specialists with captive chlorine supply and petrochemical players with backward integration into ethylene feedstocks. Three archetypes dominate: integrated majors with Gulf Coast infrastructure, European pipeline-network operators, and Asian textile-chemical conglomerates. Competitive moves center on vapor recovery infrastructure deployment and REACH-compliant distributor certification.
Among North American integrated producers, Occidental Chemical Corporation and Olin Corporation exemplify the ethylene-captive archetype, while INEOS Group occupies a parallel position in European bulk distribution. Dow Chemical Company represents the specialty-grade vector, with Kanto Denka Kogyo Co., Ltd. anchoring Japanese precision electronics supply. These named entities illustrate how geographic feedstock positioning and regulatory compliance capabilities stratify competitive access across end-use verticals.
| Leading Market Players |
|---|
| Occidental Chemical Corporation |
| Olin Corporation |
| Westlake Chemical Corporation |
| AGC Inc. |
| Kanto Denka Kogyo Co., Ltd. |
| Arkema S.A. |
| Dow Chemical Company |
| INEOS Group |
| Befar Group |
| Others |
Value Network & Pricing Analysis
Electronics manufacturers in South Korea and Taiwan concentrate procurement scale for ultra-high purity grades, anchoring a contract-based long-term offtake model that fragments into shorter spot arrangements with certified recyclers as unbundling of chemical supply from waste disposal obligations spreads.
Pricing Analysis
Warranty and service bundling separates integrated suppliers offering documented recovery rates from commodity traders selling bare solvent volumes. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity specification and certification grade, with semiconductor-grade formulations commanding substantial premiums over technical grades for textile degreasing. Cost compression in industrial solvent tiers is intensifying because EPA emissions thresholds are capping domestic manufacturing expansion regardless of demand signals. Dry cleaning service providers exhibit the highest price sensitivity as aqueous substitution accelerates, while semiconductor foundries tolerate premium positioning for ultra-low moisture specifications.
Supply Chain Analysis
Direct-to-manufacturer channels handle high-volume electronics and fluoropolymer feedstock demand, while distributor networks serve fragmented dry cleaning clusters. Production concentrates in the United States, China, and Germany, with Gulf Coast ethylene infrastructure anchoring North American chlorocarbon output. Chlorine feedstock, ethylene supply, and vapor recovery equipment constitute critical input dependencies. Single-source vulnerability runs through Gulf Coast ethylene corridors where weather disruptions transmit directly into perchloroethylene production cost structures. Distribution runs through certified distributors with verified REACH documentation in Europe and specialized chemical traders in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The perchloroethylene market sits in a technology-transition phase as membrane-based solvent purification systems displace centralized reprocessing infrastructure and aqueous cleaning alternatives erode chlorinated solvent demand across automotive pre-treatment operations.
For Market Incumbents: To counter aqueous substitution in metal degreasing applications, Occidental Chemical Corporation and integrated Gulf Coast producers should deepen captive ethylene integration to sustain cost-advantaged output while pre-emptively installing enhanced vapor capture infrastructure ahead of finalized EPA rulemaking. Certification investment in REACH-compliant distributor networks differentiates compliant suppliers from cost-only competitors facing margin compression. For New Entrants and Emerging Players: Certified recyclers with documented recovery rates present the most penetrable channel partner type for electronics manufacturers unbundling chemical supply from waste disposal obligations. White-space targets concentrate in India's Surat and Tiruppur textile processing clusters scaling solvent-based degreasing for synthetic fabric exports. A go-to-market angle emphasizing closed-loop vapor recovery infrastructure deployment at dry cleaning service clusters creates defensible local supply positions against integrated majors. For Investors and Strategic Acquirers: The window for entry favors membrane-based purification technology specialists with scalable distributed recycling systems. Long-term viability hinges on regulatory reclassification timelines rather than demand expansion, with acquisition targets clustering around vapor recovery design specialists commanding scarcity premiums. The signal to watch as inflection indicator is OSHA exposure limit alignment with ambient air quality standards, which would accelerate substitution economics across end-use verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstock | Gulf Coast infrastructure anchors cost-advantaged perchloroethylene output against import-dependent competitors. |
| Closed-Loop Vapor Recovery Deployment | Captive recycling systems at dry cleaning clusters create defensible local supply positions under EPA emissions thresholds. |
| Membrane-Based Purification Technology Adoption | German and Japanese service providers adopt on-site regeneration to deflect REACH and METI compliance costs. |
| REACH-Compliant Distributor Certification | European downstream user communication chains consolidate procurement through verified supply documentation channels. |
| Ultra-High Purity Grade Capacity Expansion | South Korean semiconductor foundries specify documented recovery rates alongside unit pricing for cleaning agents. |
Research Methodology
Independent corroboration across plant managers at chlor-alkali facilities, procurement leads at downstream electronics manufacturers, distribution channel partners in European solvent trade, and technical R&D directors at fluoropolymer producers underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical producers, and EPA Toxic Substances Control Act docket records. Bottom-up capacity assessments triangulate against top-down demand segmentation across the analysis window.
Rate-of-change decomposition separates volume drivers by grade tier, end-use industry vertical, packaging format, and regional production hub. CAGRs derive from modeled segment trajectories incorporating fluoropolymer feedstock demand expansion, aqueous substitution rates in automotive degreasing, and EPA emissions threshold impacts on domestic manufacturing capacity. Industry-specific forecast inputs include ethylene feedstock cost curves and semiconductor fabrication capacity buildouts in Pyeongtaek and Taiwanese clusters.
Several conditions sit outside the modeled scope, including abrupt regulatory reclassification under the Toxic Substances Control Act, ethylene supply disruptions from Gulf Coast weather events, and breakthrough aqueous cleaning technology performance improvements. Forecasts reflect assumptions about continued REACH registration compliance timelines and OSHA exposure limit convergence patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Metalworking Treating Fluid Market
Industrial Chemicals
Global Ethiprole Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
Global Dodecanedioic Acid Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Draft Tube Baffle (DTB) Crystallizers Market
Industrial Chemicals
Emulsion Explosive Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Global Plating on Plastics Market
Industrial Chemicals
Chemical Reactors Market
Industrial Chemicals
Adblue Market