
 PPG-20 Methyl Glucose Ether Market | 2026-2036
PPG-20 Methyl Glucose Ether Market Size, Share, and Industry Trends Forecast 2026-2036
PPG-20 Methyl Glucose Ether Market Insights
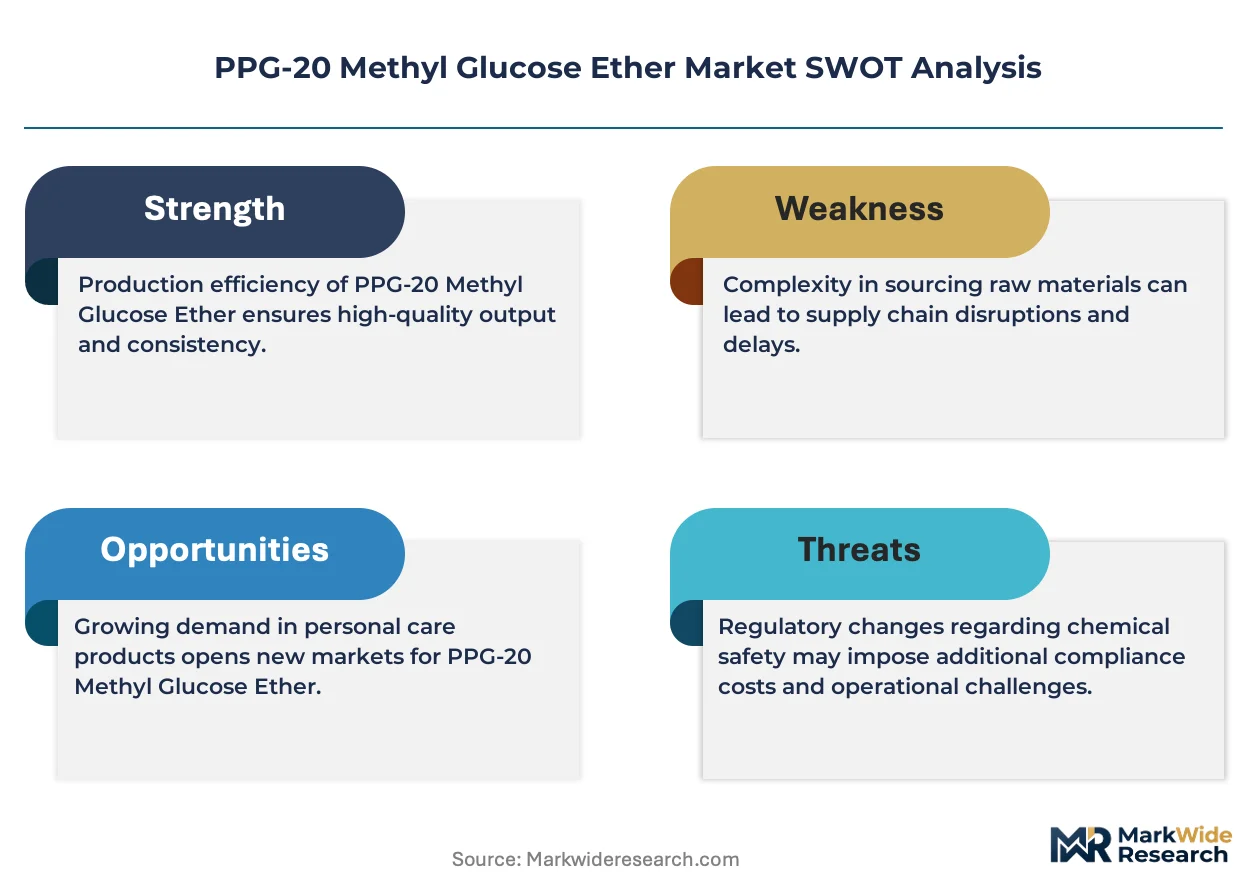
ISO 16128 natural origin certification is bifurcating supplier eligibility across the PPG-20 Methyl Glucose Ether value chain. Evonik Industries leverages its biotechnology heritage to sustain premium positioning in cosmetic-grade ethers. Lubrizol anchors North American supply through backward integration into propoxylation chemistry. Hangzhou Lingeba Technology competes on cost-engineered acetate variants for industrial cleaning segments.
PPG-20 Methyl Glucose Ether is a propoxylated glucose derivative with an average of twenty propylene oxide units, functioning as a non-ionic surfactant, solubilizer, and emollient in aqueous formulations. The molecule's hydroxyl functionality and controlled HLB range enable compatibility with both polar actives and lipid phases in skin and hair care products. Cosmetics applications command the dominant margin pool due to formulation premiumization and natural-origin claims. Household cleaning represents the fastest-growing application segment as brands replace ethoxylated surfactants amid biodegradability pressures. PPG-20 Methyl Glucose Ether Acetate occupies a specialized niche where reduced surface tension and faster drying kinetics justify higher unit economics.
REACH registration requirements in Europe and EPA Safer Choice program criteria in the United States are elevating analytical burden and documentation costs for producers seeking multi-regional access. China's SAMR cosmetic ingredient filing system adds a third compliance layer for suppliers targeting domestic formulators. India's BIS standards for surfactant purity create additional testing protocols for entrants to that market. Stakeholders must monitor regulatory divergence on natural-origin definitions as jurisdictions adopt incompatible percentage thresholds and carbon-14 testing methodologies.
Market Dynamics
ISO 16128 natural origin certification is bifurcating supplier eligibility across the PPG-20 Methyl Glucose Ether value chain, forcing formulators to requalify raw material sources and producers to invest in carbon-14 testing infrastructure.
Growth Catalysts
- REACH compliance in Europe:Tightening purity specifications for glucose-derived surfactants are accelerating replacement of petrochemical alternatives in premium cosmetic formulations.
- Biodegradability mandates:Household cleaning brands are substituting ethoxylated surfactants with PPG-20 Methyl Glucose Ether to meet EPA Safer Choice program criteria.
- Shanghai and Guangzhou manufacturing clusters:Cosmetics formulators in these hubs are expanding procurement of mildness-enhancing solubilizers for export-oriented personal care production.
Market Restraints
- Propylene oxide feedstock volatility:Price swings in propoxylation chemistry inputs compress margin predictability for ether producers without captive alkylene oxide supply.
- Supplier concentration risk:Backward-integrated specialty chemical majors control critical propoxylation capacity, limiting entry for independent glucose-ether specialists.
- Acetate variant substitution:PPG-20 Methyl Glucose Ether Acetate offers faster drying kinetics in industrial cleaning, threatening standard ether volumes in cost-sensitive segments.
Strategic Opportunities
- India's BIS standards gap:Domestic surfactant purity testing infrastructure remains underdeveloped, creating first-mover advantage for certified exporters establishing analytical partnerships.
- Clean-label convergence:Formulators seeking dual ISO 16128 and USDA BioPreferred qualification are driving specification premiums for fully traceable glucose-derived supply chains.
- SAMR cosmetic ingredient filing:China's ingredient disclosure system rewards pre-registered suppliers with accelerated formulator approval timelines versus unregistered competitors.
Industry Challenges
- Carbon-14 analytical capacity:ISO 17025-accredited labs capable of natural-origin verification face 12-16 week backlogs, delaying product launches.
- Multi-jurisdictional documentation:REACH registration, EPA Safer Choice dossiers, and SAMR filings require incompatible data formats, multiplying compliance headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PPG-20 Methyl Glucose Ether Market |
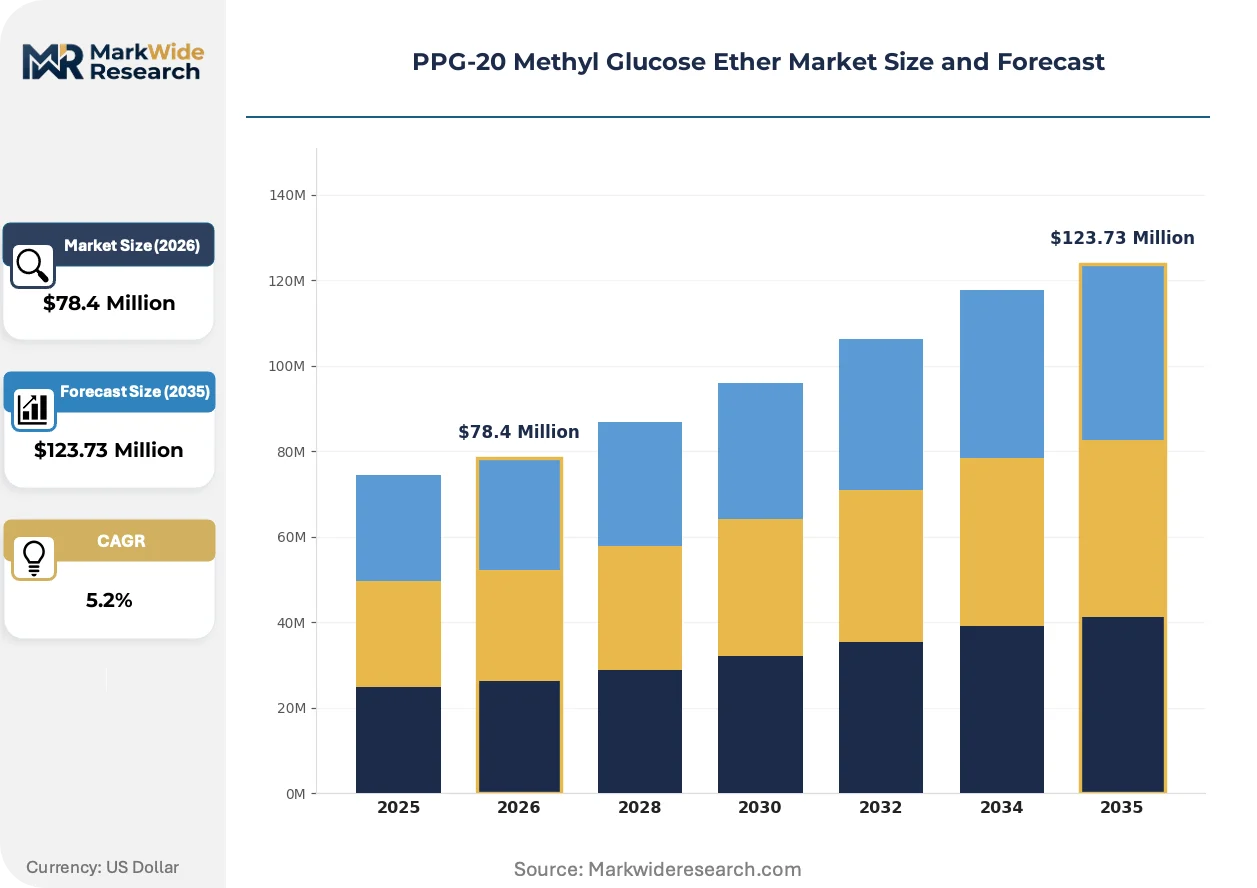
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $123.73 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PPG-20 Methyl Glucose Ether, PPG-20 Methyl Glucose Ether Acetate, PPG-20 Methyl Glucose Ether Ester, PPG-20 Methyl Glucose Ether Alcohol Application: Cosmetics, Personal Care, Household Cleaning, Industrial Cleaning End Use Industry: Cosmetics Industry, Pharmaceutical Industry, Agrochemical Industry, Food Industry Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Lubrizol, Kalichem, Hangzhou Lingeba Technology, Tinci, KCI, TIM Chemical, Hefei TNJ Chemical Industry, Evonik Industries, Reachin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PPG-20 Methyl Glucose Ether Market Trends and Innovations
Biotechnology-derived surfactants are compressing traditional petrochemical ether margins while regulatory fragmentation on natural-origin definitions forces producers to maintain parallel certification tracks.
Enzymatic propoxylation is miniaturizing reactor footprints for glucose ether production. Regional cosmetic compounders in Southeast Asia are adopting modular 50-100 liter batch systems to reduce working capital tied to imported bulk ether. This distributed manufacturing model is miniaturizing the traditional centralized propoxylation plant economics that favored integrated chemical majors.
REACH Annex XVII restrictions on microplastic-containing leave-on cosmetics are tightening solubilizer specifications. ECHA guidance documents now explicitly classify certain ethoxylated surfactants as microplastic precursors, redirecting formulator R&D budgets toward glucose-derived alternatives. German and French cosmetic brands are accelerating qualification timelines for PPG-20 Methyl Glucose Ether in rinse-off applications ahead of anticipated leave-on extensions.
Direct procurement from glucose ether producers is displacing distributor intermediaries in mid-scale cosmetic manufacturing. Third-party chemical distributors historically captured 15-20 point margins on specialty surfactants; formulators in South Korea and Taiwan now negotiate annual contracts directly with propoxylation specialists to secure lot-traceable supply. This channel compression is most visible in contract manufacturing organizations serving clean-label indie beauty brands with short formulation cycles.
PPG-20 Methyl Glucose Ether Market Segmentation
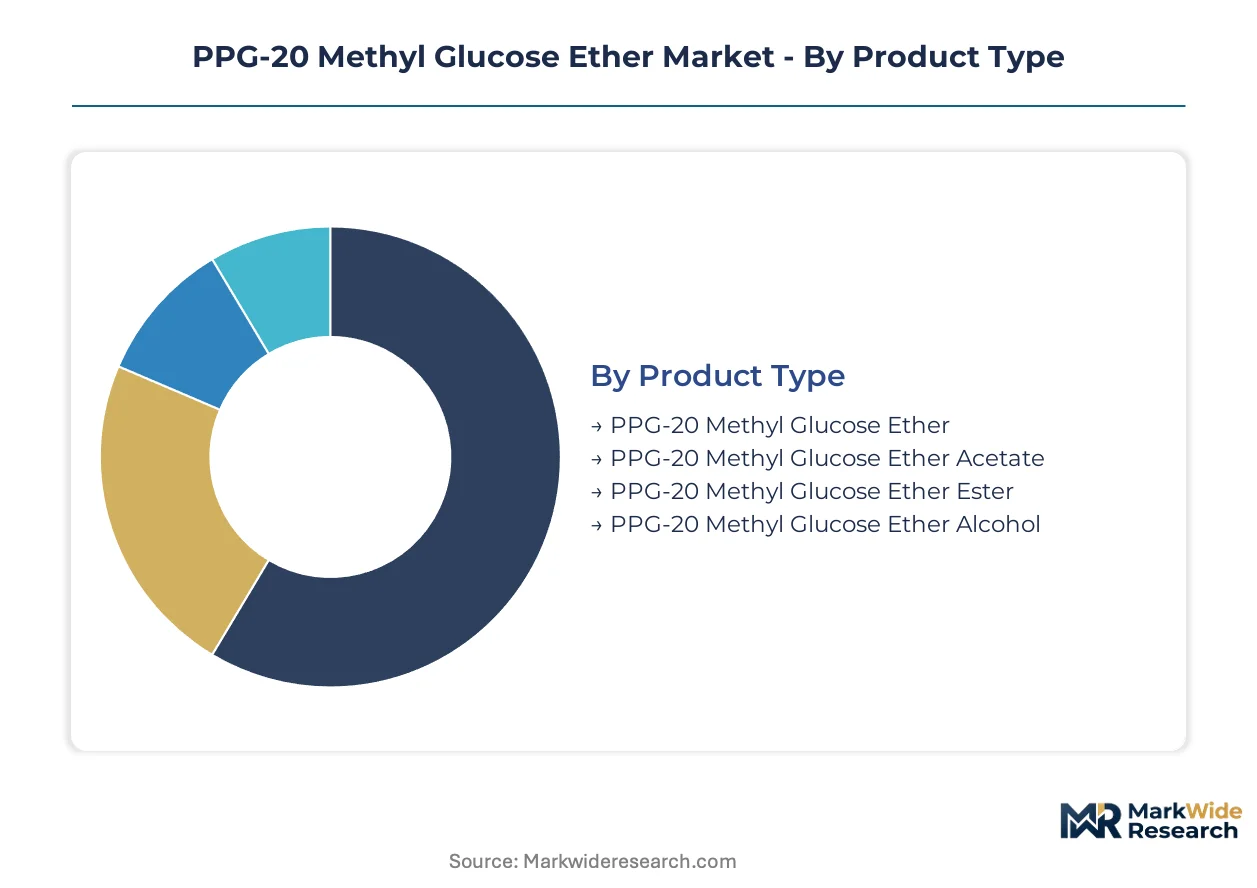
Segmentation in the PPG-20 Methyl Glucose Ether market reveals divergent margin structures across product chemistry variants and end-use specifications. Formulators prioritize ISO 16128-certified grades for cosmetic applications while industrial buyers optimize for solubility performance at lower unit costs.
Product Type:
Cosmetic-grade standard ethers capture premium margin pools due to certification overhead and lot-traceability requirements, while acetate variants compete on functional performance in speed-critical applications.
- PPG-20 Methyl Glucose Ether:The propoxylated glucose base molecule with twenty propylene oxide units delivers controlled HLB surfactancy for aqueous cosmetic formulations. Demand concentrates in Shanghai and Guangzhou manufacturing clusters serving export-oriented personal care brands facing REACH Annex XVII microplastic restrictions.
- PPG-20 Methyl Glucose Ether Acetate:Acetylated modification reduces surface tension and accelerates drying kinetics through lowered hydrogen bonding. Industrial cleaning compounders in cost-sensitive segments are rotating procurement toward this variant where speed of evaporation justifies higher unit economics versus standard ethers.
- PPG-20 Methyl Glucose Ether Ester:Esterified derivatives offer modified lipophilicity profiles for specialized emollient applications.
- PPG-20 Methyl Glucose Ether Alcohol:Hydroxyl-terminated variants serve niche solubilization requirements in pharmaceutical processing.
Standard ether grades hold installed capacity. Acetate variants are rotating up the share rankings.
Application:
Volume concentration follows regulatory pressure gradients, with biodegradability mandates in household cleaning driving substitution fastest while cosmetics maintains value concentration through formulation premiumization.
- Cosmetics:Leave-on and rinse-off skin and hair care formulations leverage the molecule's mildness profile and natural-origin compatibility. German and French brands are accelerating qualification timelines ahead of anticipated ECHA microplastic classification extensions.
- Household Cleaning:Brands substituting ethoxylated surfactants to meet EPA Safer Choice program criteria are expanding procurement fastest. This segment is climbing the fastest as biodegradability mandates tighten across multiple jurisdictions.
- Personal Care:Deodorants, oral care, and sun care applications demand high-purity grades with documented carbon-14 natural origin verification.
- Industrial Cleaning:Metal degreasing and parts washing formulations prioritize cost-engineered acetate variants over certified cosmetic grades.
Cosmetics commands specification premiums. Household cleaning is gaining share fastest.
End Use Industry:
Customer sophistication varies sharply across industries, with pharmaceutical and cosmetic buyers demanding ISO 17025-accompanied certificates of analysis while agrochemical purchasers prioritize bulk volume pricing.
- Cosmetics Industry:Formulators require full REACH registration documentation and SAMR pre-registration for China market access. Clean-label convergence toward dual ISO 16128 and USDA BioPreferred qualification is tightening supplier eligibility.
- Pharmaceutical Industry:Excipient-grade ethers for topical drug delivery face USP-NF and EP monograph compliance requirements with extended stability testing protocols.
- Agrochemical Industry:Surfactant adjuvants for pesticide formulations prioritize cost efficiency over certification overhead.
- Food Industry:Limited food-grade applications require FCC compliance and migration testing for indirect food contact scenarios.
Cosmetics industry holds qualification depth. Pharmaceutical is rotating up the share rankings.
Distribution Channel:
Channel economics are compressing as mid-scale manufacturers bypass traditional distributor markups through direct annual contracting with propoxylation specialists.
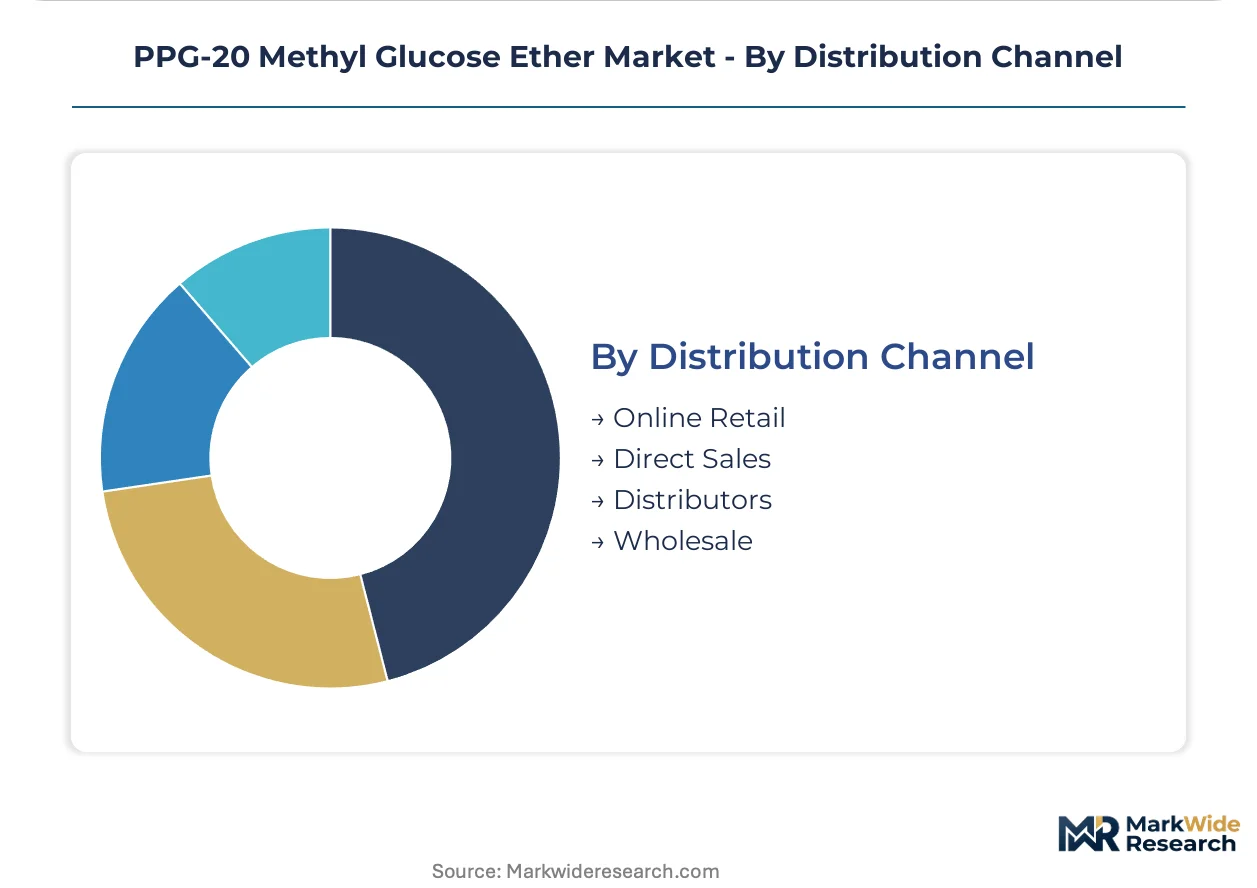
- Direct Sales:Annual volume contracts between ether producers and contract manufacturing organizations enable lot-traceable supply for clean-label indie beauty brands with short formulation cycles. South Korean and Taiwanese formulators have accelerated this channel shift.
- Distributors:Third-party chemical distributors historically captured fifteen to twenty point margins on specialty surfactants; this share is eroding fastest where direct procurement relationships mature.
- Online Retail:E-procurement platforms serve small-batch cosmetic compounders and research-scale buyers with reduced minimum order quantities.
- Wholesale:Bulk volume aggregation for industrial cleaning and agrochemical buyers maintains relevance where specification requirements remain standardized.
Direct sales holds relationship depth. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH Annex XVII microplastic restrictions and EPA Safer Choice program criteria are redirecting formulator procurement toward glucose-derived surfactants across multiple jurisdictions. SAMR cosmetic ingredient filing requirements and India's BIS surfactant purity standards add compliance layers that favor pre-registered suppliers. Manufacturing gravity concentrates in personal care production clusters where export-oriented brands face the strictest biodegradability mandates.
China
Shanghai and Guangzhou cosmetics manufacturing clusters are expanding procurement of mildness-enhancing solubilizers for export-oriented personal care production. SAMR cosmetic ingredient filing rewards pre-registered suppliers with accelerated formulator approval timelines. Yangtze River Delta and Pearl River Delta personal care hubs are rotating toward ISO 16128-certified glucose ether grades to serve European and North American brand specifications.
United States
Household cleaning brands are substituting ethoxylated surfactants to meet EPA Safer Choice program biodegradability criteria. The agency's explicit classification of certain ethoxylated surfactants as microplastic precursors redirects R&D budgets toward glucose-derived alternatives. New Jersey and Texas chemical manufacturing corridors are seeing elevated demand for propoxylated glucose ethers from contract manufacturers serving clean-label indie beauty brands.
Germany
ECHA guidance documents on microplastic-containing leave-on cosmetics are tightening solubilizer specifications for German cosmetic brands. Bavaria and North Rhine-Westphalia personal care formulators are accelerating qualification timelines for PPG-20 Methyl Glucose Ether in rinse-off applications ahead of anticipated leave-on extensions. REACH registration documentation requirements elevate analytical burden for ether producers seeking multi-regional access.
India
BIS standards for surfactant purity create additional testing protocols for glucose ether entrants to the domestic market. Maharashtra and Gujarat chemical processing corridors present first-mover advantage for certified exporters establishing analytical partnerships with ISO 17025-accredited labs. Domestic surfactant purity testing infrastructure remains underdeveloped, compressing approval timelines for foreign suppliers with pre-established certification tracks.
South Korea
MFDS cosmetic ingredient disclosure requirements align with global clean-label convergence toward dual ISO 16128 and USDA BioPreferred qualification. Seoul Capital Area contract manufacturing organizations are negotiating annual contracts directly with propoxylation specialists to secure lot-traceable supply for short formulation cycles. This channel compression displaces third-party chemical distributors that historically captured fifteen to twenty point margins on specialty surfactants.
PPG-20 Methyl Glucose Ether Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and propoxylation chemistry control. The vendor base spans backward-integrated multinational chemical majors and cost-engineered regional glucose ether specialists. Three archetypes dominate: biotechnology heritage players leveraging natural-origin positioning, propoxylation-integrated majors anchoring North American supply, and acetate-variant competitors targeting industrial cleaning speed requirements. Competitive moves concentrate on carbon-14 testing infrastructure investment and direct annual contracting relationships with mid-scale formulators.
Within the biotechnology heritage tier, Evonik Industries exemplifies premium positioning through natural-origin certification depth. Lubrizol anchors North American supply through captive propoxylation chemistry. Hangzhou Lingeba Technology occupies the cost-engineered acetate variant segment for industrial cleaning applications. These three represent the competitive spectrum from certification-intensive cosmetic grades to performance-optimized industrial formulations.
| Leading Market Players |
|---|
| Lubrizol |
| Kalichem |
| Hangzhou Lingeba Technology |
| Tinci |
| KCI |
| TIM Chemical |
| Hefei TNJ Chemical Industry |
| Evonik Industries |
| Reachin |
| Others |
Pricing and Supply Chain Analysis
ISO 16128 natural origin certification gates both supplier qualification and price differentiation simultaneously, bifurcating the PPG-20 Methyl Glucose Ether value chain into premium-credentialed and commodity-grade tiers. Formulators seeking dual USDA BioPreferred qualification face extended carbon-14 testing backlogs that compress procurement timelines while amplifying specification premiums for pre-certified inventory.
Pricing Analysis
Certification level creates the primary spread across the PPG-20 Methyl Glucose Ether market, with ISO 16128-compliant cosmetic grades commanding substantial premiums over industrial cleaning specifications. Three-tier pricing structure across premium, standard, and economy levels reflects lot-traceability depth, REACH registration completeness, and carbon-14 documentation status. Cost compression in standard ether grades is intensifying because acetate variants capture drying-speed-sensitive industrial segments. Household cleaning compounders exhibit highest price sensitivity, while pharmaceutical excipient buyers prioritize analytical burden over unit cost.
Supply Chain Analysis
Just-in-time inventory preferences dominate cosmetics formulators with short formulation cycles, while industrial cleaning buyers maintain strategic stockpiles against propylene oxide feedstock volatility. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta and North Rhine-Westphalia hubs serving export-oriented personal care brands. Propoxylation chemistry capacity rests on propylene oxide and glucose derivative feedstocks. Single-source vulnerability pervades backward-integrated alkylene oxide supply. Distribution runs through direct annual contracts displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation on natural-origin definitions fragments supplier eligibility, creating white-space opportunities for certification-fast specialists and modular production entrants across multiple geographies.
For Market Incumbents: Consolidate propoxylation capacity control through captive alkylene oxide supply or long-term offtake agreements with integrated chemical majors. Deepen ISO 17025-accredited carbon-14 testing infrastructure to defend margin position against biotechnology-derived surfactant substitutes threatening traditional petrochemical ether volumes. For New Entrants and Emerging Players: ISO 16128 pre-certification fast-tracks entry into South Korean and Taiwanese contract manufacturing channels where direct procurement relationships are displacing distributor intermediaries. Target India's BIS standards gap where domestic surfactant purity testing infrastructure remains underdeveloped. Lead with analytical partnership offers to compressed-approval-timeline positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic propoxylation miniaturization as modular 50-100 liter batch systems reduce working capital requirements for regional compounders. Five-to-ten year viability favors acquisition of acetate-variant specialists with industrial cleaning speed-performance positioning. Watch carbon-14 analytical capacity expansion rates as inflection indicator for certification-bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propoxylation | Lubrizol anchors North American supply through captive alkylene oxide chemistry control. |
| Carbon-14 Testing Infrastructure Investment | ISO 17025-accredited lab capacity resolves 12-16 week backlogs delaying product launches. |
| Direct Annual Contracting | South Korean formulators bypass distributor markups to secure lot-traceable supply for indie beauty brands. |
| Acetate Variant Capacity Expansion | Hangzhou Lingeba Technology captures industrial cleaning segments prioritizing drying kinetics. |
| SAMR Pre-Registration | Pre-registered suppliers gain accelerated approval timelines versus unregistered competitors in China. |
Research Methodology
A spread of perspectives from propoxylation plant managers, cosmetics procurement leads, ISO 17025 lab directors, and REACH registration consultants converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from customs trade data, SEC chemical sector filings, ECHA registration databases, and SAMR cosmetic ingredient disclosure records. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the analysis window.
Segmentation dimensions modeled include product chemistry variant, application specification tier, end-use industry sophistication level, and regional regulatory cluster. CAGRs were derived from slope-intercept fitting of validated data points across the projection horizon. Forecast inputs incorporated propylene oxide feedstock price trajectories and biodegradability mandate adoption curves.
Decision-makers should treat outputs as directional under stable regulatory divergence assumptions; material deviation in natural-origin definition harmonization would warrant model refresh. Revision becomes warranted when carbon-14 analytical capacity expansion crosses demand thresholds or when ECHA microplastic classification extends to leave-on cosmetics ahead of anticipated timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Sodium Ascorbyl Phosphate (SAP) Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Global Acrylic Processing Aid Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Global Aerosol Market