
 Caryophyllene Market | 2026-2036
Caryophyllene Market Size, Share, and Industry Trends Forecast 2026-2036
Caryophyllene Market Outlook
Specialty chemical distribution networks is reshaping how caryophyllene reaches end-users across fragrance and pharmaceutical channels. Givaudan SA leverages captive botanical sourcing to sustain supply security for high-purity grades. Symrise AG anchors European production capacity through specialized extraction infrastructure. Firmenich International SA competes on molecular distillation capabilities that isolate beta-caryophyllene from crude terpene streams.
Caryophyllene is a bicyclic sesquiterpene with the molecular formula C15H24, occurring naturally in clove oil, black pepper, and cannabis sativa at concentrations up to 35 percent by weight; manufacturers employ steam distillation or supercritical CO2 extraction to isolate it for commercial use. Essential oils and fragrance compounds command premium positioning due to complexity in achieving FCC-grade purity thresholds. Pharmaceutical applications represent the fastest-expanding segment as researchers isolate caryophyllene's selective CB2 receptor agonism for therapeutic development. Liquid form delivery dominates current volume given compatibility with solvent-based formulation processes across cosmetics and food applications.
The FDA oversees caryophyllene through GRAS self-determination pathways for food applications and botanical drug guidance for pharmaceutical candidates, while REACH compliance in Europe mandates full toxicological dossiers for fragrance compound registration. EFSA evaluations of clove-derived additives further constrain permissible daily exposure thresholds in EU food formulations. Stakeholders must monitor divergent regulatory timelines between US GRAS affirmation and European novel food authorization processes when prioritizing market entry sequencing.
Market Dynamics
Specialty chemical distributors are consolidating procurement channels for caryophyllene, compressing the path from Indonesian clove processors to German fragrance houses and pharmaceutical compounders into fewer intermediaries with certified cold-chain capabilities.
Growth Catalysts
- CB2 Agonism Research:Preclinical validation of beta-caryophyllene's selective cannabinoid receptor activity is opening formulation pipelines for neuropathic pain and anti-inflammatory therapeutics.
- REACH Registration Pathways:ECHA's consolidated dossier requirements for sesquiterpenes are streamlining market access for compliant producers across EU fragrance and cosmetic applications.
- Indonesian Feedstock Expansion:Cultivation intensification in Sulawesi and Maluku provinces is securing raw material throughput for steam distillation facilities serving export markets.
Market Restraints
- Feedstock Price Volatility:Clove bud oil prices fluctuate with monsoon patterns and harvest cycles in Indonesia, compressing margin predictability for distillers.
- Purity Threshold Escalation:FCC-grade specifications above 95 percent beta-caryophyllene content require molecular distillation infrastructure that smaller processors cannot access.
- Botanical Drug Guidance Friction:FDA's requirement for standardized botanical raw material characterization creates documentation burdens that delay IND submissions.
Strategic Opportunities
- Japanese Cosmetic Formulations:METI's encouragement of natural functional ingredients creates entry points for caryophyllene in premium skincare positioned around anti-inflammatory claims.
- Supercritical CO2 Convergence:Integration of CO2 extraction with inline chromatographic purification is collapsing batch-to-batch variability for pharmaceutical-grade output.
- Direct Sourcing Platforms:Digital procurement channels connecting Indonesian distillers to European compounders are disintermediating traditional spice trading houses.
Industry Challenges
- Analytical Chemist Scarcity:GC-MS method development for sesquiterpene quantification requires specialized expertise that contract laboratories struggle to retain.
- GRAS Timeline Compression:FDA's self-determination pathway demands toxicological data packages that stretch smaller ingredient suppliers' regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caryophyllene Market |
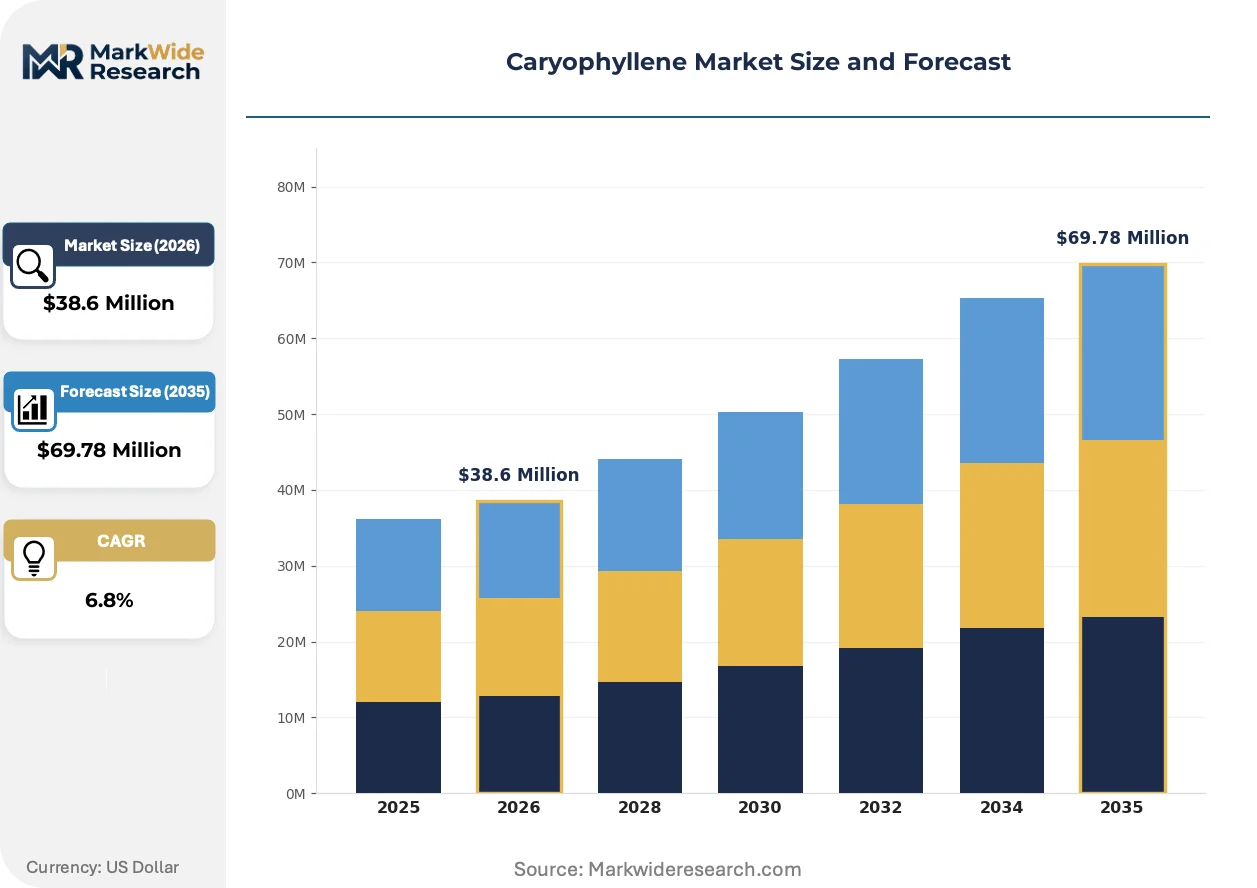
| Market Size in 2026 | $38.6 Million |
| Market Size in 2035 | $69.78 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Flavoring Agents, Fragrance Compounds, Additives Application: Food Industry, Cosmetics, Pharmaceuticals, Nutraceuticals End User: Retailers, Manufacturers, Wholesalers, Distributors Delivery Mode: Liquid Form, Solid Form, Gaseous Form, Others |
| Companies Covered | International Flavors & Fragrances Inc., Givaudan SA, Symrise AG, Firmenich International SA, Takasago International Corporation, Van Aroma, Vigon International, Penta Manufacturing Company, Shree Bankey Behari Lal Aromatics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caryophyllene Market Strategic Shifts
Extraction technology maturation and regulatory data requirements are converging to separate pharmaceutical-grade producers from commodity fragrance suppliers. Three developments are compressing competitive timelines.
Molecular distillation systems with fractional condensation stages are collapsing the cost differential between FCC-grade and technical-grade caryophyllene. German and Swiss fragrance houses are retrofitting existing terpene facilities with wiped-film evaporators to capture pharma contract manufacturing opportunities. Equipment lead times now determine which compounders can bid on CB2-targeting drug development programs.
EFSA's 2023 re-evaluation of clove-derived food additives tightened permissible daily exposure thresholds for eugenol and caryophyllene co-extracts. Reformulation activity in EU food flavoring applications is accelerating demand for purified beta-caryophyllene isolates with minimized phenolic carryover. Compounders with validated purification SOPs are capturing share from traditional essential oil blenders.
Certification-driven procurement is reshaping buyer-supplier relationships in North American cannabis-derived terpene markets. State-level testing mandates for residual solvents and pesticides are pushing extractors toward suppliers with ISO 17025-accredited laboratories. British Columbia and California processors now require chain-of-custody documentation that commodity traders cannot provide.
Caryophyllene Market Segmentation
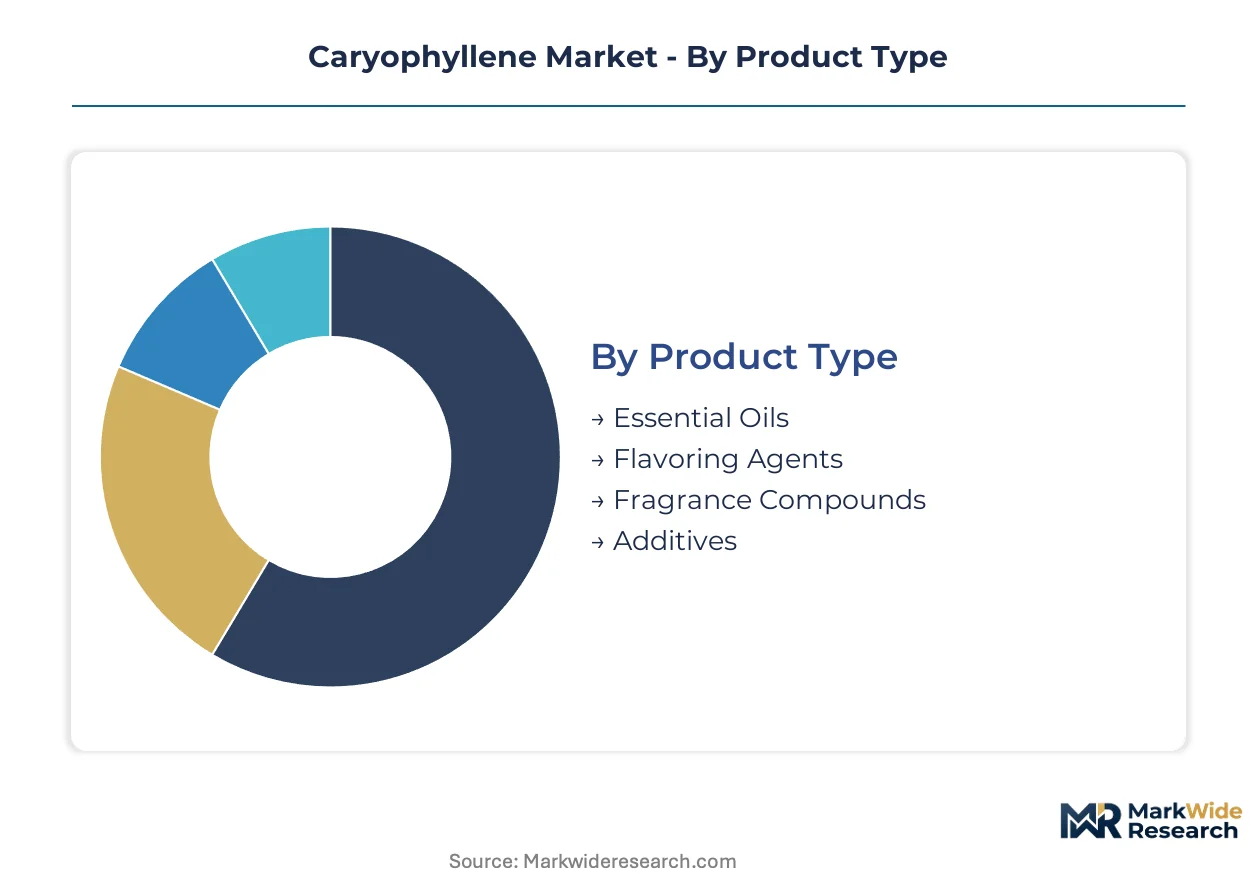
Segmentation in the caryophyllene market exposes how purity thresholds and regulatory pathways split procurement behavior. Pharmaceutical compounders, fragrance houses, and food formulators each demand distinct specification bundles that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply across product types, with pharmaceutical-grade suppliers embedding analytical support and batch documentation that commodity essential oil traders cannot replicate.
- Essential Oils:Crude steam-distilled outputs containing 30-60 percent beta-caryophyllene alongside eugenol and other terpenes. Demand clusters in Indonesian export markets serving German fragrance compounders who lack molecular distillation capacity.
- Flavoring Agents:FCC-grade isolates exceeding 95 percent purity with controlled phenolic carryover. EFSA's tightened daily exposure thresholds are accelerating reformulation activity in EU food applications toward these purified grades.
- Fragrance Compounds:Technical-grade concentrates for soap and detergent applications where olfactory performance tolerates broader terpene profiles.
- Additives:Functional ingredients for industrial applications including polymer stabilization and agricultural formulations.
By volume, essential oils lead. By growth pace, flavoring agents are ahead.
Application:
Application-driven cost tiers separate commodity fragrance use from premium pharmaceutical positioning, with CB2 receptor research commanding price multiples over food-grade formulations.
- Food Industry:GRAS-affirmed uses in spice blends, chewing gum, and beverage flavoring. FDA self-determination pathways dominate US market access, while EU novel food authorization creates compliance friction.
- Cosmetics:Anti-inflammatory claims in premium skincare, particularly Japanese formulations encouraged by METI's natural functional ingredient policies. Molecular distillation isolates command premium positioning here.
- Pharmaceuticals:CB2 agonist development for neuropathic pain and inflammatory conditions. Preclinical validation is opening formulation pipelines that demand ISO 17025-accredited supply chains.
- Nutraceuticals:Dietary supplement applications in capsule and tincture formats, with USP verification becoming a procurement differentiator.
Food industry volumes dominate current procurement, yet pharmaceutical applications are expanding most quickly.
End User:
End-user concentration patterns reveal how certified cold-chain capabilities filter market access, with direct sourcing platforms disintermediating traditional trading layers.
- Retailers:Specialty botanical and aromatherapy channels requiring consumer-facing labeling compliance.
- Manufacturers:Fragrance houses and pharmaceutical compounders in Germany, Switzerland, and France who specify purity certificates and chain-of-custody documentation.
- Wholesalers:Regional distributors consolidating Indonesian clove oil shipments for European fragrance clusters.
- Distributors:Specialty chemical networks with REACH-registered dossiers and ECHA-compliant handling infrastructure.
Manufacturers capture the steepest value-add, while distributors are gaining share fastest through regulatory bundling services.
Delivery Mode:
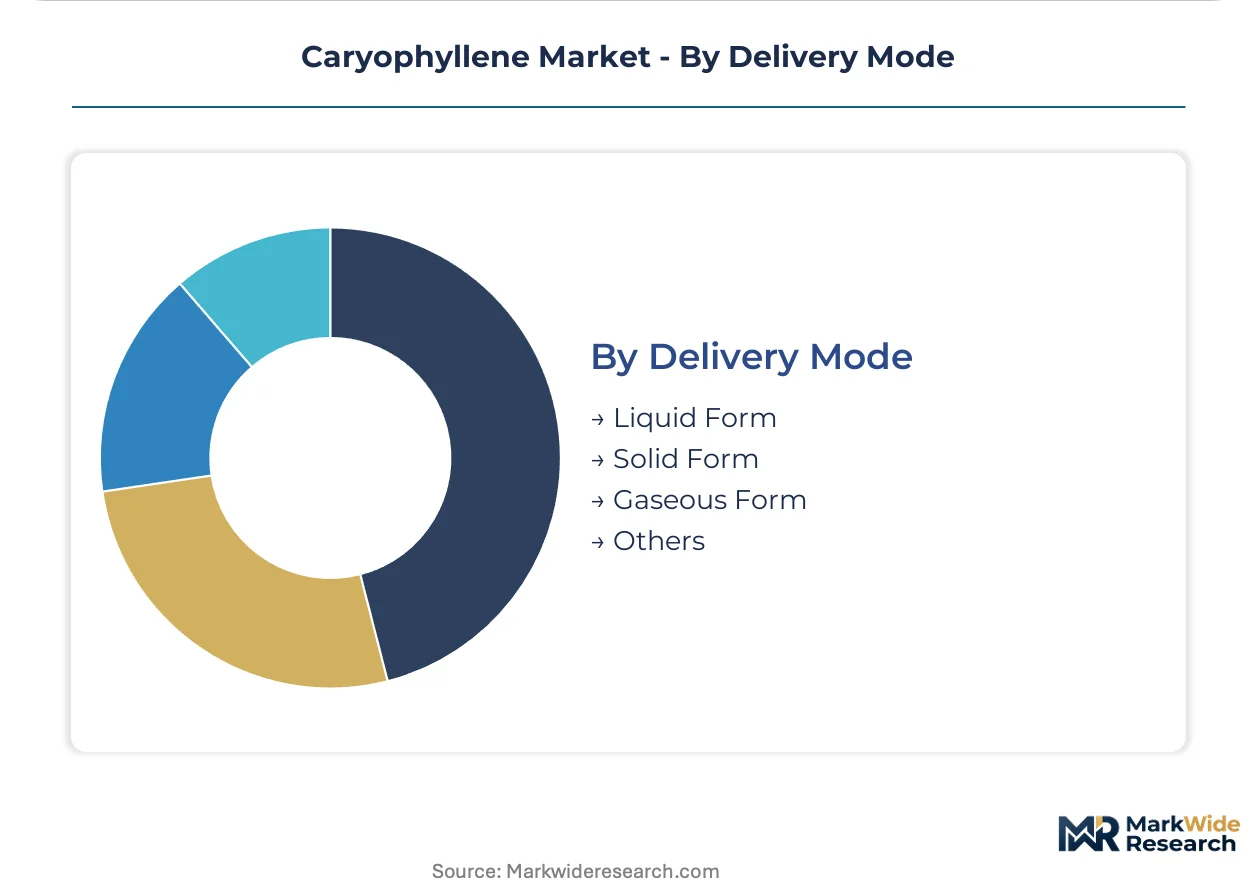
Delivery mode selection tracks formulation process compatibility, with solvent-based systems favoring liquid handling and solid-dose pharmaceuticals driving alternative formats.
- Liquid Form:Dominant volume compatible with solvent-based cosmetics and food applications. German fragrance houses prefer drum packaging with nitrogen blanketing.
- Solid Form:Microencapsulated powders for controlled-release pharmaceutical and nutraceutical tablets. Japanese cosmetic formulators are adopting these for powder-to-foam skincare systems.
- Gaseous Form:Limited use in specialized inhalation delivery research for respiratory applications.
- Others:Emulsion and liposomal formats emerging for enhanced bioavailability claims.
Liquid form leads by volume, while solid form is climbing the fastest on pharmaceutical formulation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA and ECHA regulatory frameworks in Europe anchor the dominant geography for caryophyllene demand, with German fragrance houses and pharmaceutical compounders driving specification intensity across the value chain.
Germany
Fragrance houses in Hamburg and Holzminden cluster around REACH-registered dossier expertise, sourcing FCC-grade isolates for cosmetic and pharmaceutical formulations. ECHA's consolidated sesquiterpene requirements streamline market access for compliant producers. The Rhine-Ruhr corridor hosts specialized extraction infrastructure serving both domestic compounders and export markets.
United States
FDA's GRAS self-determination pathway shapes food-grade procurement, while botanical drug guidance creates documentation burdens for pharmaceutical candidates. California and Colorado cannabis extractors demand ISO 17025-accredited supply chains with chain-of-custody documentation. Pacific Northwest processors are consolidating direct sourcing relationships with Indonesian distillers.
Indonesia
Sulawesi and Maluku cultivation zones supply clove bud feedstock for steam distillation facilities serving export markets. The national pharmaceutical regulator oversees export certification for botanical raw materials. Surabaya and Jakarta house processing infrastructure linking smallholder harvests to European fragrance clusters.
Japan
METI's encouragement of natural functional ingredients creates entry points for caryophyllene in premium skincare positioned around anti-inflammatory claims. PMDA oversight of cosmetic safety standards elevates documentation requirements for imported isolates. Osaka and Tokyo cosmetic formulators are adopting microencapsulated powder formats for powder-to-foam systems.
Switzerland
Swissmedic's pharmaceutical-grade standards attract CB2-targeting drug development programs seeking compliant supply chains. Basel and Geneva host molecular distillation capabilities isolating beta-caryophyllene from crude terpene streams. Swiss fragrance and pharma compounders leverage fractional condensation infrastructure to capture premium contract manufacturing opportunities.
Caryophyllene Market Competitive Environment
Vertically integrated fragrance houses and specialized botanical extractors split the market between captive supply security and flexible procurement services. Consolidation concentrates around German and Swiss production clusters where REACH compliance and molecular distillation capabilities create entry barriers. Three archetypes dominate: integrated flavor-fragrance conglomerates with captive sourcing, regional essential oil distillers with direct farm relationships, and pharmaceutical-grade specialists with chromatographic purification assets. Capacity expansion in Indonesian feedstock zones and retrofitting of European terpene facilities with wiped-film evaporators represent the dominant competitive moves.
Among integrated flavor-fragrance conglomerates, Givaudan SA, Symrise AG, and Firmenich International SA exemplify the archetype of players leveraging captive botanical sourcing and specialized extraction infrastructure to sustain supply security for high-purity grades. These Switzerland and Germany-based entities occupy positions where molecular distillation capabilities and REACH-registered dossiers create differentiation from commodity traders. Regional specialists such as Van Aroma and Shree Bankey Behari Lal Aromatics represent the distillery-tier archetype, anchoring procurement relationships closer to Indonesian clove cultivation zones.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Givaudan SA |
| Symrise AG |
| Firmenich International SA |
| Takasago International Corporation |
| Van Aroma |
| Vigon International |
| Penta Manufacturing Company |
| Shree Bankey Behari Lal Aromatics |
| Others |
Value Chain & Pricing Dynamics
Indonesian clove harvest volatility determines both pricing tier spreads and supply chain shape across the caryophyllene value chain. Monsoon-driven feedstock scarcity compresses margin predictability for European fragrance compounders while rewarding molecular distillation operators with captive sourcing relationships.
Pricing Analysis
The customization-premium spread separates FCC-grade pharmaceutical isolates from technical-grade fragrance concentrates. Three-tier pricing structure across premium, standard, and economy levels tracks purity thresholds and certification bundles, with ISO 17025-accredited batches commanding substantial premiums over commodity essential oil grades. Cost compression in standard-tier technical grades is intensifying because Indonesian smallholder harvest variability feeds spot market volatility. Contract fragrance houses exhibit lowest price sensitivity, while regional essential oil blenders face acute margin pressure from purity threshold escalation.
Supply Chain Analysis
Contract-manufacturing concentration sits with German and Swiss molecular distillation operators holding pharmaceutical-grade capacity. Feedstock draws from Indonesian clove cultivation zones in Sulawesi and Maluku, with secondary sourcing from Madagascar and Zanzibar. Single-source vulnerability concentrates in Indonesian monsoon exposure and port logistics chokepoints at Surabaya and Jakarta. Distribution runs through specialty chemical networks with REACH-registered dossiers and certified cold-chain capabilities serving Hamburg and Basel compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital procurement platforms are transforming caryophyllene sourcing into an ecosystem-economics inflection, with direct distiller-to-compounder interoperability collapsing traditional spice trading layers.
For Market Incumbents: Harden supply security through backward integration into Indonesian clove processing infrastructure and captive molecular distillation capacity additions in the Rhine-Ruhr corridor. EFSA's tightened daily exposure thresholds threaten commodity essential oil blenders lacking validated purification SOPs. Certification investment in ISO 17025-accredited laboratories defends positioning against emerging pharmaceutical-grade specialists.
For New Entrants and Emerging Players: Japanese cosmetic formulators represent the most penetrable geography, with METI's natural functional ingredient policies creating white-space for anti-inflammatory skincare positioning. Supercritical CO2 extraction with inline chromatographic purification offers technical differentiation against established steam distillation incumbents. Direct sourcing platform partnerships with Sulawesi distillers bypass entrenched trading house intermediaries.
For Investors and Strategic Acquirers: FDA botanical drug guidance finalization reshapes the acquisition landscape toward dossier-ready pharmaceutical-grade suppliers with standardized raw material characterization capabilities. Long-term viability centers on CB2-targeting therapeutic pipelines and REACH-registered European production assets. The signal to watch is IND submission acceleration for neuropathic pain formulations requiring compliant supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indonesian Feedstock | Captive clove sourcing from Sulawesi plantations secures margin control against monsoon volatility. |
| Molecular Distillation Capacity Expansion | Wiped-film evaporator retrofitting in Basel captures pharmaceutical contract manufacturing opportunities. |
| ISO 17025 Laboratory Accreditation | Certified analytical capabilities unlock cannabis-derived terpene markets in California and British Columbia. |
| Direct Sourcing Platform Development | Digital procurement channels disintermediate traditional spice trading houses serving European fragrance clusters. |
| REACH Dossier Consolidation | ECHA-compliant sesquiterpene registration streamlines market access across German and Swiss compounders. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Interviews covered extraction facility operators in Surabaya and Jakarta, procurement leads at German fragrance houses, regulatory affairs specialists navigating FDA botanical drug guidance, and technical directors at Swiss molecular distillation facilities. Secondary sources included ECHA registration dossiers, FDA GRAS notification filings, Indonesian customs export records, and EFSA food additive re-evaluation reports. Bottom-up volume triangulation from clove oil processing capacity was cross-checked against top-down demand aggregation from fragrance and pharmaceutical compounders.
Forecast inputs considered purity grade tier, end-use application segmentation, and regional regulatory cluster dynamics across the projection horizon. The analytical framework modeled pharmaceutical-grade isolates, FCC-grade flavoring agents, and technical-grade fragrance compounds as distinct demand pools with divergent growth trajectories. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion timelines. Industry-specific inputs incorporated CB2 agonism research pipeline progression and EFSA exposure threshold enforcement intensity.
Practitioners should monitor clove harvest forecasts, REACH registration timeline shifts, and FDA botanical drug guidance amendments for early signals of forecast revision. Quarterly review of Indonesian meteorological indicators, ECHA dossier submission rates, and preclinical CB2 study publication velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Global Vacuum Grease Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Organo-Modified Bentonite Market
Specialty Chemicals
Organosilicon Electrolyte Market
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Iron Phosphate Market
Specialty Chemicals
Global Molecular Weight Marker Market