
 Coating Solvents Market | 2026-2036
Coating Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Solvents Market Analysis
High-purity aromatic grades is reorganizing competitive dynamics across the coating solvents sector. BASF SE leverages integrated petrochemical complexes in Germany to sustain feedstock cost advantages. Dow Inc. anchors North American supply through proprietary alcohol solvent technologies. Exxon Mobil Corporation dominates aliphatic solvent production via captive refinery streams.
Coating solvents are liquid organic compounds—typically hydrocarbons, alcohols, esters, or ketones—that dissolve resin binders and control viscosity during paint application, then evaporate to leave a uniform cured film with specified gloss and adhesion properties. Acrylic resin systems lead architectural applications due to their weatherability and fast drying characteristics, while polyurethane solvents command premium positioning in automotive clearcoats where scratch resistance and optical clarity matter most. Marine coatings rely heavily on epoxy-compatible solvent blends formulated for saltwater corrosion protection and extended service intervals.
EPA regulations in the United States restrict volatile organic compound emissions from industrial coating operations, compelling reformulation toward exempt solvents. REACH registration requirements in Europe mandate toxicological data for solvent imports, raising compliance costs for non-European suppliers. China's MEE enforces emission standards at manufacturing clusters in Jiangsu and Zhejiang provinces. Stakeholders must monitor regulatory divergence across jurisdictions to align product portfolios with divergent compliance timelines.
Market Dynamics
REACH and the EU Green Deal are forcing a rapid pivot toward low-VOC and bio-based solvent formulations, compressing demand for traditional aromatic hydrocarbons while reshaping supplier R&D priorities and capital allocation across the value chain.
Growth Catalysts
- Automotive OEM clearcoat specifications:Premium polyurethane solvent systems are gaining preference in automotive assembly plants for scratch-resistant finishes. OEMs in Germany and Japan are expanding solvent specifications to meet durability targets.
- China's MEE emission enforcement:Manufacturing clusters in Jiangsu and Zhejiang provinces face tightened VOC limits, driving coating plants to reformulate with compliant solvent blends. This regulatory pressure is accelerating domestic solvent substitution programs.
- Marine coating service intervals:Epoxy-compatible solvent formulations for saltwater corrosion protection are extending maintenance cycles for commercial vessels. Shipyards in South Korea and Norway are specifying these systems for newbuild contracts.
Market Restraints
- Crude-linked naphtha feedstock volatility:Aromatic solvent margins compress when naphtha cracks widen, exposing formulators to input cost swings they cannot pass through immediately.
- European refinery rationalization:Captive aliphatic supply from integrated refineries is concentrating in fewer hands as older European units close, tightening spot availability for independent blenders.
- Waterborne technology substitution:High-solids and waterborne coating systems are capturing share in decorative applications where solvent performance is not critical, eroding volume in architectural segments.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic solvent manufacturing incentives are attracting investment in alcohol and ester production capacity to serve coating formulators targeting the subcontinent's infrastructure build-out.
- Exempt solvent regulatory carve-outs:Acetone and certain oxygenated solvents enjoy VOC-exempt status under EPA rules, creating formulation opportunities for US industrial coating suppliers seeking compliance without performance sacrifice.
- Bio-based glycol ether convergence:Fermentation-derived solvents are achieving purity parity with petrochemical grades, enabling blenders to market renewable content to sustainability-mandated buyers in Nordic countries.
Industry Challenges
- Formulation chemist specialization gap:Expertise in solvent-resin compatibility for emerging bio-based binders is scarce, slowing product development cycles at mid-sized coating houses.
- REACH data cost recovery:Toxicological dossier expenses for imported solvent categories must be amortized across shrinking volumes as buyers shift to registered alternatives, straining importer economics.
- Legacy equipment solvent transition:Existing spray lines and drying ovens require retrofitting to handle higher-boiling exempt solvents or faster-evaporating low-VOC blends, demanding capital commitments from job shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Solvents Market |
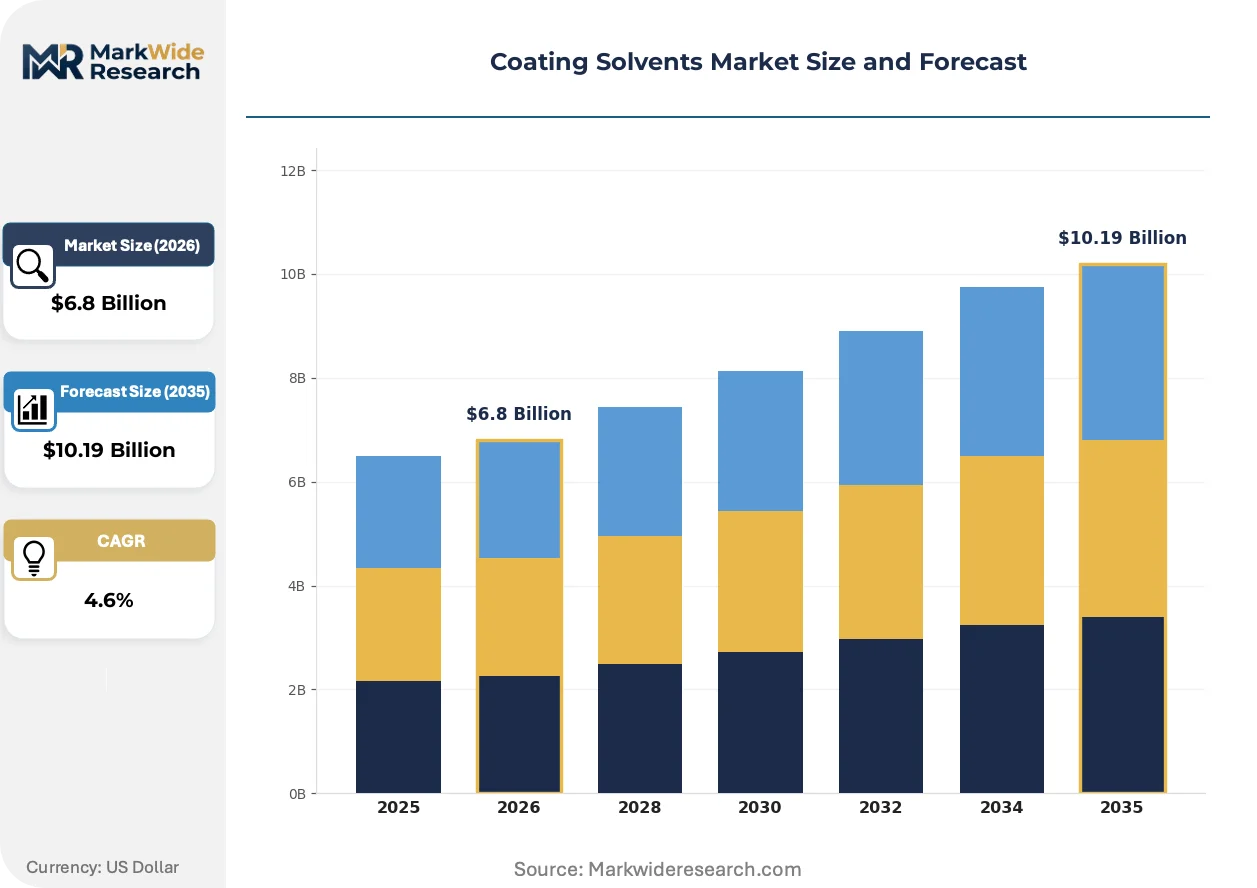
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
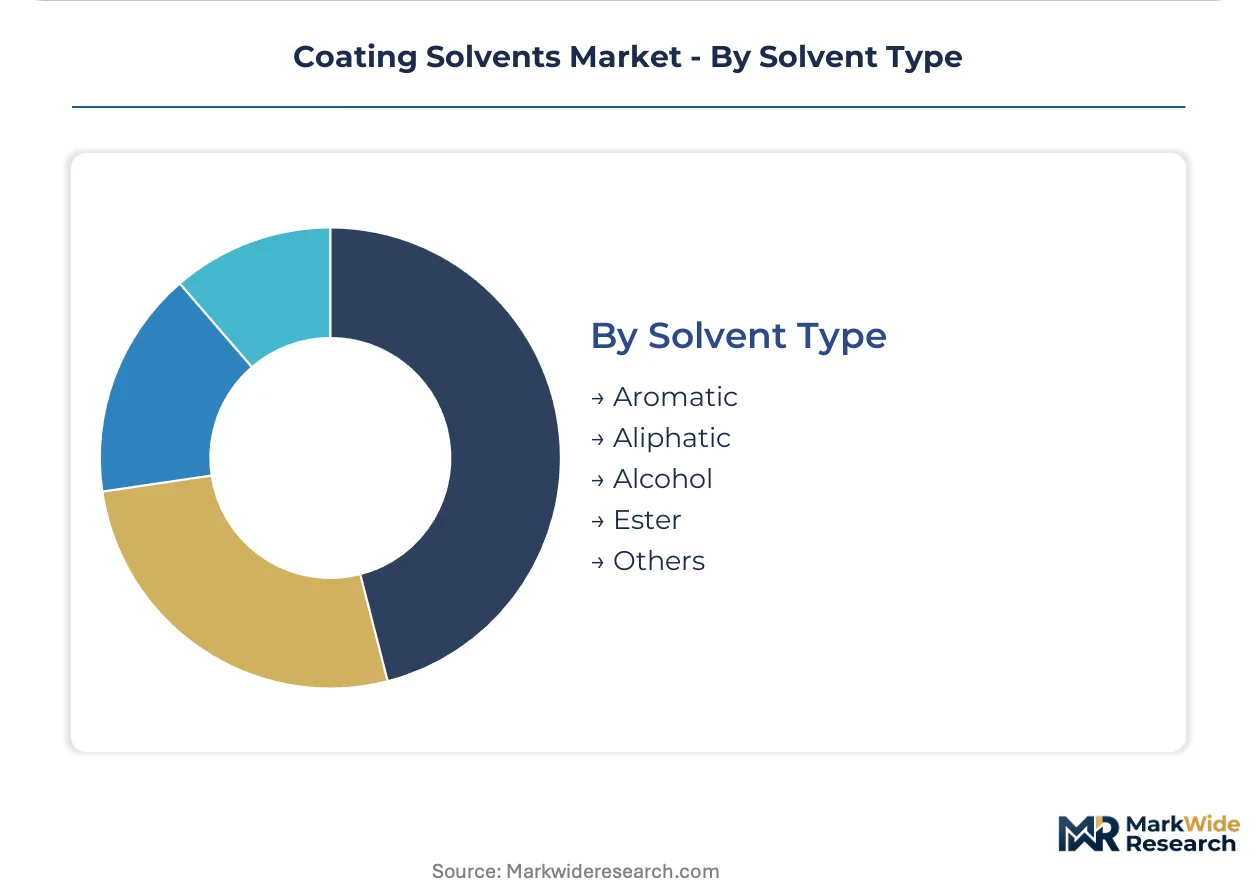
| Segmentation | Product Type: Acrylic, Alkyd, Epoxy, Polyurethane Application: Automotive Coatings, Marine Coatings, Industrial Coatings, Architectural Coatings End User: OEMs, Contractors, Manufacturers, Distributors Solvent Type: Aromatic, Aliphatic, Alcohol, Ester, Others |
| Companies Covered | BASF SE, Dow Inc., Exxon Mobil Corporation, Shell plc, Arkema S.A., Eastman Chemical Company, Clariant AG, Solvay SA, Ineos Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Solvents Market Emerging Trajectories
Formulation science is diverging along two paths: high-performance solvent systems for demanding industrial applications, and radically simplified solvent packages for regulated environments. This bifurcation is fragmenting R&D investment and creating distinct competitive arenas.
Bio-based ester solvents produced from agricultural feedstocks are supplanting petroleum-derived glycol ethers in decorative coating segments. European architectural paint manufacturers are adopting these alternatives at scale to meet retailer sustainability scorecards. The transition is compressing margins for conventional ether producers while rewarding integrated biorefinery operators with captive fermentation capacity.
REACH registration requirements for toxicological data are compelling non-European solvent exporters to establish EU-based legal entities or surrender market position. The industrial consequence is a thinning of import supply diversity, concentrating shelf space with registrants who absorbed compliance costs early. Automotive refinish shops in France and Germany are experiencing tighter solvent choice sets as specialty import grades withdraw.
Coating formulators are consolidating supplier relationships around fewer solvent vendors who can document carbon intensity through the value chain. Large industrial buyers in the Netherlands and California are demanding cradle-to-gate emissions data as a condition of contract renewal. This behavioral shift favors integrated producers with refinery-level carbon accounting systems over merchant traders lacking visibility into upstream emissions.
Coating Solvents Market Segmentation
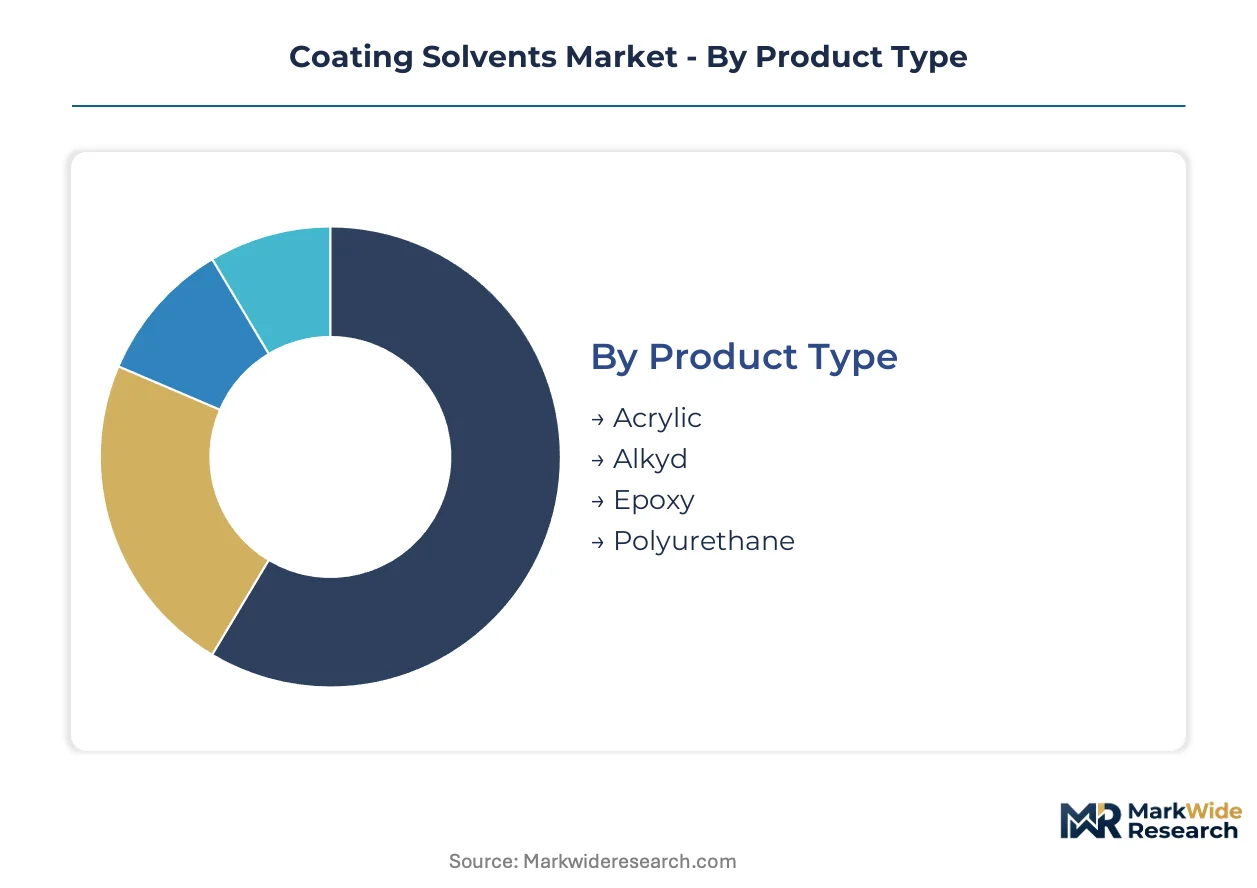
Coating solvents serve distinct performance requirements across resin chemistries and application environments. Segmentation reveals where formulation complexity commands premium pricing versus where commodity substitution erodes margins.
Product Type:
Channel flow varies sharply: polyurethane and epoxy solvents move through specialized industrial distributors with technical service support, while acrylic and alkyd grades flow through high-volume merchant channels.
- Polyurethane:High-performance oxygenated solvents with controlled evaporation profiles enable scratch-resistant automotive clearcoats. Demand concentrates at German and Japanese OEM assembly plants where durability specifications are tightening.
- Epoxy:Ketone and glycol ether blends formulated for extended pot life and saltwater corrosion resistance. Shipyards in South Korea and Norway specify these systems for commercial vessel newbuilds requiring decade-long service intervals.
- Acrylic:Fast-evaporating ester solvents serving weatherable architectural finishes through building materials retailers.
- Alkyd:Traditional hydrocarbon solvents for decorative enamels facing substitution pressure from waterborne alternatives in residential repaint segments.
Alkyd dominates installed base volume. Polyurethane is where expansion concentrates.
Application:
Margin structure separates protective industrial specifications from price-sensitive decorative volumes, with automotive and marine commanding formulation premiums.
- Automotive Coatings:OEM clearcoat and refinish applications requiring precise viscosity control and optical clarity. EPA VOC regulations and OEM durability warranties are driving solvent specification upgrades at US and German assembly plants.
- Marine Coatings:Immersion-grade epoxy and antifouling systems for saltwater exposure. Classification society rules at Lloyd's Register and DNV are mandating longer dry-dock intervals, favoring high-performance solvent packages.
- Industrial Coatings:Protective metal finishing for infrastructure and equipment with compliance-driven reformulation toward exempt solvents.
- Architectural Coatings:Decorative interior and exterior paints experiencing fastest displacement by waterborne and high-solids technologies in EU and California markets.
Architectural coatings represent the largest volume pool. Marine coatings are climbing the fastest.
End User:
Procurement scale and technical capability separate integrated manufacturers from fragmented downstream applicators.
- OEMs:Automotive and marine builders with captive formulation labs and direct solvent sourcing contracts. REACH registration requirements are consolidating their supplier panels toward registrants with EU legal entities.
- Manufacturers:Industrial coating producers blending for specialized protective applications with batch-scale solvent purchasing.
- Contractors:Application-focused buyers sourcing through distributors with limited formulation influence.
- Distributors:Merchant intermediaries stocking commodity grades for fragmented job shop demand.
OEMs dominate value capture. Manufacturers are where specification influence is shifting.
Solvent Type:
Feedstock integration and regulatory status create divergent margin profiles across hydrocarbon and oxygenated chemistries.
- Aromatic:Toluene and xylene derivatives from catalytic reforming with high solvency power for alkyd and epoxy systems. European refinery rationalization is tightening spot availability for independent blenders in Germany and the Netherlands.
- Aliphatic:Mineral spirits and hexane fractions from crude distillation serving low-odor decorative applications. Exxon Mobil's captive refinery streams dominate North American supply concentration.
- Alcohol:Butanol and propanol grades for waterborne coalescing and viscosity reduction.
- Ester:Bio-based glycol ether acetates gaining share in EU architectural segments under retailer sustainability mandates.
- Others:Ketone specialties including exempt acetone for compliant industrial formulations.
Aromatics dominate historical volume. Esters are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive refinery streams in the United States, Germany, and China concentrate aromatic and aliphatic solvent supply. Manufacturing clusters in these countries absorb the majority of coating solvent volumes for automotive and marine applications.
United States
Automotive OEMs in Michigan and Ohio are expanding solvent purchases for high-performance clearcoat finishes. EPA VOC regulations restrict emissions from industrial coating operations, compelling reformulation toward exempt solvents. The Gulf Coast petrochemical corridor sustains integrated supply of oxygenated and hydrocarbon solvents for domestic formulators.
Germany
Premium automotive assembly plants in Bavaria and Baden-Württemberg specify polyurethane solvent systems for scratch-resistant warranties. REACH registration requirements mandate toxicological data for solvent imports, raising compliance costs for non-European suppliers. The Ludwigshafen chemical complex anchors integrated production of high-purity aromatic grades.
China
Marine manufacturing bases in Jiangsu and Zhejiang provinces are expanding coating consumption for commercial vessel newbuilds. MEE emission enforcement at manufacturing clusters is accelerating domestic solvent substitution programs. The Yangtze River Delta concentrates demand for epoxy-compatible solvent blends in shipyard operations.
South Korea
Shipyards in Ulsan and Geoje specify high-performance solvent packages for classification society-mandated service intervals. The country's national environmental regulator enforces VOC limits at industrial coating facilities. The Busan-Ulsan corridor dominates marine coating formulation and solvent blending capacity.
India
Infrastructure build-out is driving coating formulators to expand solvent sourcing for protective industrial applications. The PLI scheme for specialty chemicals is attracting investment in alcohol and ester production capacity. Manufacturing clusters in Maharashtra and Gujarat are developing domestic solvent blending operations.
Coating Solvents Market Vendor Landscape
Concentration sits with integrated petrochemical majors possessing captive feedstock access. The market structure divides between refinery-integrated producers with cost advantages and specialized chemical companies with formulation expertise. Three archetypes dominate: integrated oil majors with captive aromatic streams, diversified chemical conglomerates with alcohol solvent technologies, and regional specialists in oxygenated grades. Competitive moves center on backward integration into fermentation-derived feedstocks and strategic partnerships with coating formulators for low-VOC co-development.
Among Germany-based integrated producers, BASF SE exemplifies the refinery-integrated archetype with Ludwigshafen complex advantages. Dow Inc. anchors North American positioning through proprietary solvent technologies. Exxon Mobil Corporation occupies a dominant position in aliphatic solvent production via Gulf Coast refinery integration. These three represent distinct competitive vectors: European aromatic supply concentration, North American oxygenated specialization, and global aliphatic scale.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Exxon Mobil Corporation |
| Shell plc |
| Arkema S.A. |
| Eastman Chemical Company |
| Clariant AG |
| Solvay SA |
| Ineos Group Limited |
| Others |
Supply Flow & Price Mechanics
REACH registration requirements gate both supplier qualification and price differentiation simultaneously, as non-European solvent exporters must absorb toxicological dossier costs to access German and French coating formulators, while compliant registrants command premium positioning over unregistered imports facing volume restrictions.
Pricing Analysis
EPA VOC regulations dictate the pricing tier structure across the United States coating solvents market. Three-tier pricing structure across premium, standard, and economy levels separates exempt oxygenated solvents from compliant reformulated grades and legacy high-VOC aromatic systems. Price differentiation rests on certification grade and volume scale, with automotive OEMs least sensitive due to warranty-driven specification lock-in, while architectural contractors face intensifying cost compression from waterborne substitution.
Supply Chain Analysis
Strait of Hormuz transit underwrites naphtha feedstock flows to Asian aromatic solvent crackers, creating systemic exposure to maritime disruption. Supply concentrates in the United States, Germany, and China through integrated petrochemical corridors. Raw material dependencies center on crude-linked naphtha, catalytic reformate streams, and fermentation-derived bio-feedstocks. Distribution runs through specialized industrial distributors for polyurethane and epoxy grades, with high-volume merchant channels handling alkyd and acrylic solvents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise for bio-based resin compatibility represents the critical capability gap constraining product development velocity at mid-sized coating houses, creating asymmetric advantage for integrated producers with captive R&D infrastructure.
For Market Incumbents: Compound technical service capabilities around solvent-resin compatibility testing to defend against merchant traders lacking formulation support infrastructure. Prioritize backward integration into fermentation-derived ester capacity to capture bio-based architectural demand under EU retailer sustainability mandates. Lock in long-term offtake agreements with automotive OEMs in Bavaria and Michigan before REACH registration deadlines thin competitor supply options. For New Entrants and Emerging Players: EU REACH fast-track registration for oxygenated solvent categories offers entry pathway into German automotive refinish segments abandoned by non-compliant importers. Target India's PLI-subsidized alcohol and ester production capacity to serve domestic infrastructure coating formulators in Maharashtra and Gujarat. Lead with exempt solvent formulation expertise to capture US industrial coating compliance-driven substitution demand. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional oxygenated solvent specialists in South Korea and the Netherlands holding technical service relationships with marine coating formulators. Long-term viability favors integrated producers with refinery-level carbon accounting systems over merchant traders facing scope 3 disclosure pressure. Watch for MEE enforcement intensity in Jiangsu province as inflection indicator for Chinese domestic substitution program acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Feedstocks | Fermentation-derived ester capacity captures EU Green Deal-compliant architectural demand from Nordic retailers. |
| REACH Registration Acceleration | Early toxicological dossier submission secures shelf space as non-European imports withdraw from German automotive refinish. |
| Exempt Solvent Formulation Partnerships | Acetone and oxygenated solvent co-development with US industrial coating suppliers bypasses EPA VOC restrictions. |
| Technical Service Infrastructure Expansion | Specialized solvent-resin compatibility laboratories differentiate integrated producers from commodity traders in polyurethane clearcoat segments. |
| Carbon Intensity Documentation Systems | Refinery-level cradle-to-gate emissions data satisfies Dutch and California industrial buyer contract renewal requirements. |
Methodological Framework
Initial hypotheses were tested against primary input from solvent plant managers, procurement leads at automotive and marine OEMs, distribution channel partners, and technical R&D directors at coating formulators, and refined through secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE enforcement bulletins. Bottom-up volume estimates from individual production facilities were triangulated with top-down demand aggregation across end-use segments.
Variance decomposition across the projection horizon isolates drivers by resin chemistry, application environment, and regulatory compliance tier. Segmentation dimensions modeled include solvent type, resin system compatibility, end-use industry, and regional production hub concentration. CAGRs were synthesized from facility-level capacity announcements, demand elasticity parameters, and substitution rate assumptions for waterborne and high-solids technologies.
Underlying assumptions cover sustained naphtha-crack spreads, REACH registration timelines, and MEE enforcement intensity, with deviation risk concentrated in European refinery rationalization pace and bio-based solvent purity achievement curves. Practitioners should keep alternative scenarios live as EU Green Deal implementation timelines and Chinese dual carbon policy stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Asia-Pacific Ethane Market
Solvents
Ethyl Acetate Market
Solvents
Global Solvent Evaporation Market
Solvents
Monochlorobenzene Market
Solvents
Chlorobenzene Market
Solvents
Global Acetonitrile Market
Solvents
Green Solvents Market
Solvents
Aliphatic Solvents and Thinners Market
Solvents
Global Xylenols Market
Solvents
Meta-Xylene Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
2 - Ethyl Anthraquinone Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Global Glycidol Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Crotonaldehyde Market