
 Antioxidant 412S Market | 2026-2036
Antioxidant 412S Market Size, Share, and Industry Trends Forecast 2026-2036
Antioxidant 412S Market Insights
Direct distribution channels between thioester antioxidant producers and polypropylene compounders is narrowing as specialty chemical houses consolidate supply relationships. BASF leverages its integrated antioxidant portfolio to sustain technical service relationships across European polymer converters. Songwon anchors its position through backward integration into key phenolic intermediates, while Rianlon competes aggressively on delivered cost for Asian polyolefin masterbatch customers.
Antioxidant 412S, chemically classified as a thioester secondary antioxidant, functions primarily as a hydroperoxide decomposer in polyolefin stabilization systems, typically blended at concentrations of 0.05% to 0.30% with primary hindered phenolic antioxidants to achieve synergistic thermal oxidative protection during extrusion and long-term service. Synthetic antioxidant formulations dominate volume demand due to cost-performance ratios favoring thioester chemistry in commodity plastics, though natural antioxidant alternatives occupy niche positions in food-contact and cosmetic packaging applications where regulatory scrutiny on synthetic additives intensifies. Pharmaceutical-grade antioxidant demand represents a concentrated margin pool, with stringent purity requirements limiting qualified suppliers and supporting premium positioning.
REACH registration obligations under ECHA govern antioxidant 412S import and manufacturing thresholds across Europe, while China's GB standards and SAMR food-contact additive positive lists determine market access for packaging-grade formulations. The United States EPA administers TSCA Section 5 premanufacture notification requirements for new thioester antioxidant chemistries, creating compliance barriers for novel entrants. Stakeholders must monitor evolving dual carbon goals under China's MEE and the EU Green Deal's chemical sustainability criteria, as carbon-intensive thioester production processes face escalating disclosure and abatement obligations that will reshape supplier competitiveness and sourcing geography.
Market Dynamics
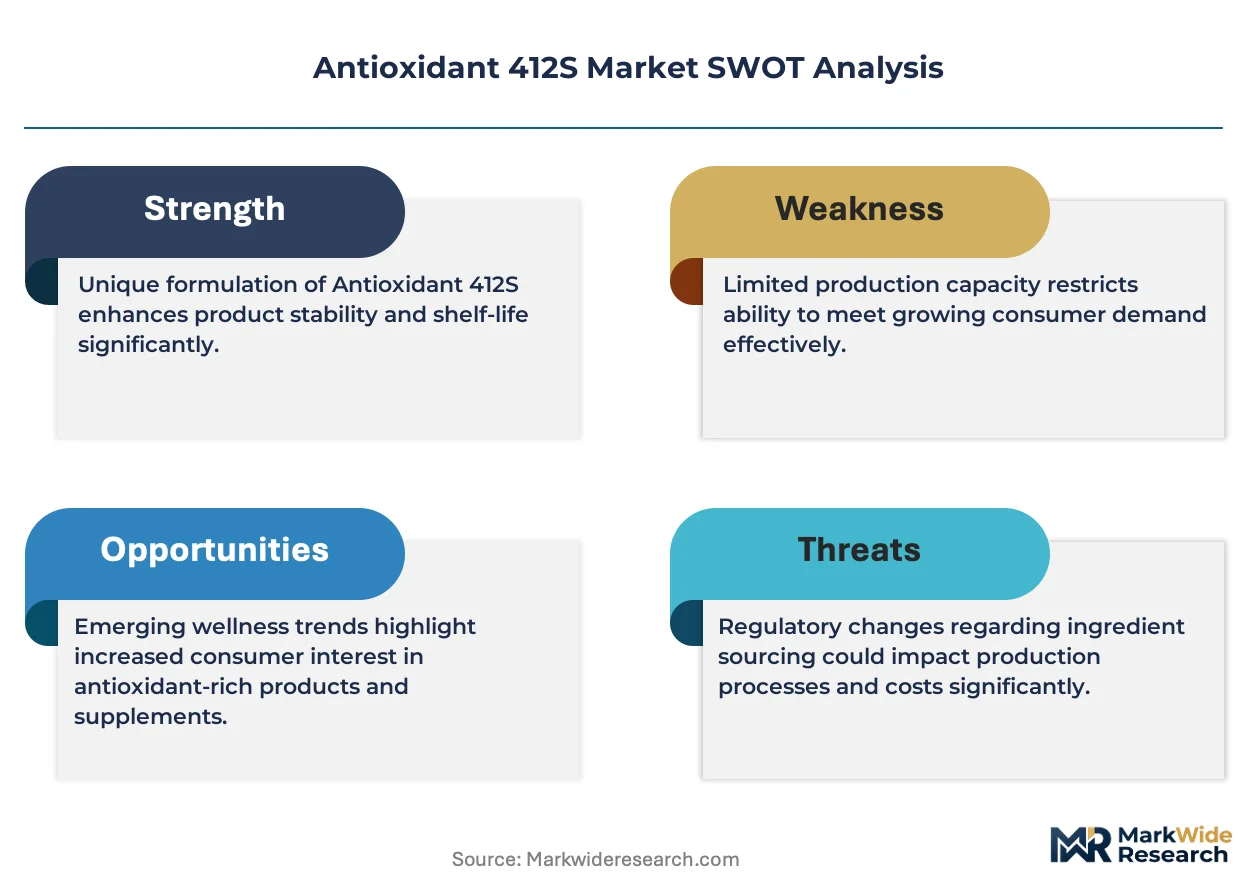
REACH registration obligations under ECHA and China's evolving GB standards are forcing thioester antioxidant suppliers to reconfigure manufacturing footprints and reformulate products for dual-market compliance, compressing margins for non-integrated producers while advantaging backward-integrated compounders with captive phenolic intermediate supply.
Growth Catalysts
- Automotive underhood thermal endurance mandates:Polypropylene compounding for engine-bay plastics now requires hydroperoxide decomposition at sustained temperatures above 150°C, driving specification upgrades to thioester secondary antioxidants in thermal management systems.
- China's dual carbon policy framework:MEE disclosure requirements for carbon-intensive thioester production processes are accelerating domestic capacity consolidation, concentrating supply among integrated producers with abatement infrastructure.
- Food-contact packaging regulatory tailwinds:SAMR positive list expansions for synthetic antioxidants in polyolefin films are opening qualified formulation opportunities for Antioxidant 412S in high-barrier multilayer structures.
Market Restraints
- Phenolic intermediate supply concentration:Backward integration into hindered phenol precursors limits qualified thioester antioxidant suppliers to integrated chemical houses, constraining new entrant capacity.
- Natural antioxidant substitution pressure:Tocopherol and rosemary extract alternatives are capturing niche volume in cosmetic and premium food-contact applications where synthetic additive stigma persists.
- EPA TSCA Section 5 notification friction:Premanufacture review timelines for novel thioester chemistries extend 18-24 months, delaying product iteration cycles for US-focused innovators.
Strategic Opportunities
- Pharmaceutical-grade purity positioning:Stringent residual solvent and heavy metal specifications limit qualified Antioxidant 412S suppliers to three global sources, supporting 40-60% price premiums over technical grades.
- Direct compounding channel expansion:Polypropylene masterbatch producers in India and Southeast Asia are bypassing European distributors, creating technical service relationships with thioester antioxidant manufacturers.
- EU Green Deal chemical sustainability criteria:Carbon footprint disclosure mandates under CSRD are favoring producers with renewable energy-integrated thioester synthesis, reshaping sourcing decisions among European polymer converters.
Industry Challenges
- Process analytical technology skill scarcity:Real-time monitoring of thioester synthesis requires spectroscopic expertise concentrated among legacy antioxidant producers, constraining quality system upgrades at newer manufacturing sites.
- REACH data-sharing consortium complexity:ECHA substance information exchange forums for thioester antioxidants involve 12+ registrants with divergent testing strategies, extending registration maintenance costs and timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antioxidant 412S Market |
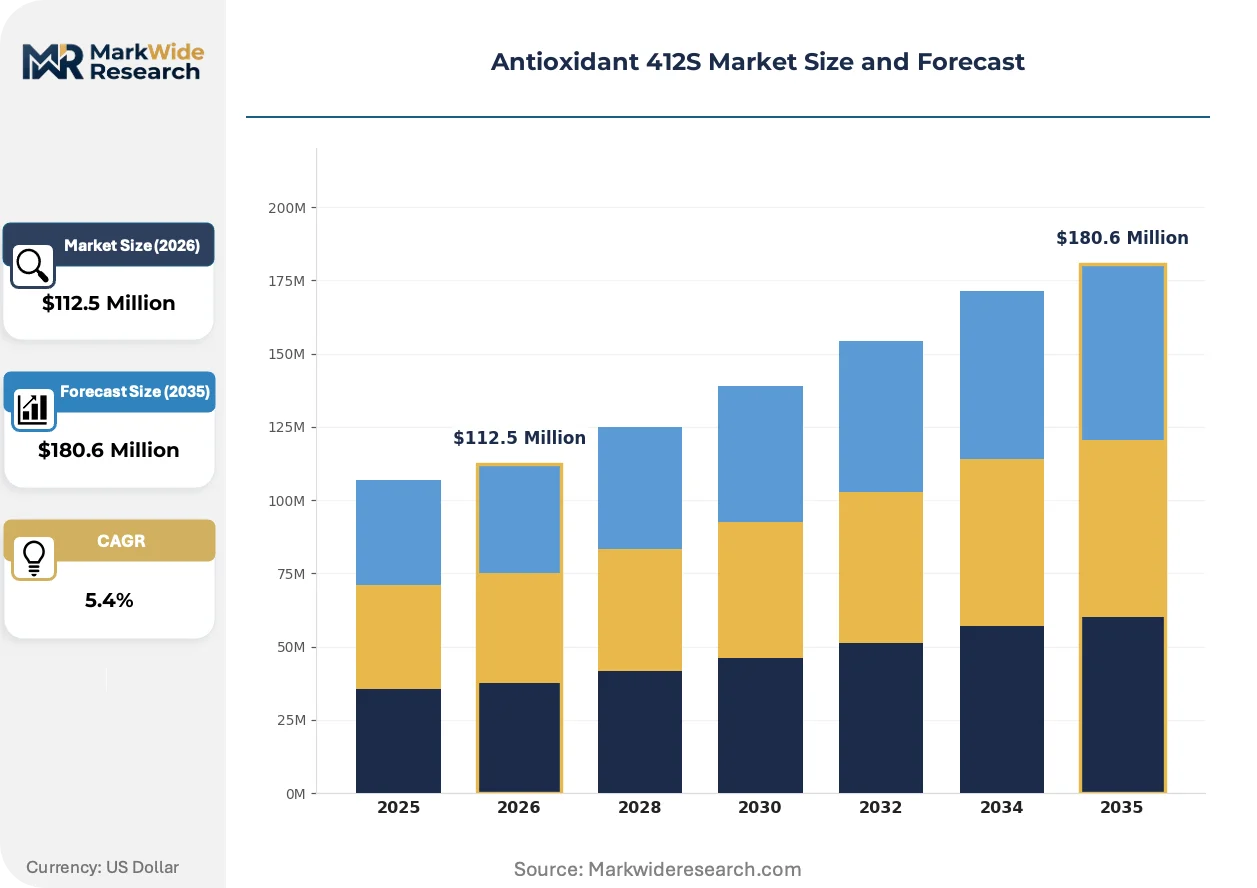
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $180.6 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Inorganic Application: Food Preservation, Cosmetic Formulations, Nutritional Supplements, Pharmaceutical Products End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Feed Packaging Type: Aerosol Cans, Bottles, Pouches, Bulk Containers |
| Companies Covered | ADEKA, BASF, SI Group, Songwon, Deltachem, Rianlon, Nanjing SQS, Solvay, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antioxidant 412S Market Trends and Innovations
Computational formulation modeling and closed-loop manufacturing telemetry are compressing antioxidant development cycles while regulatory carbon accounting is virtualizing supplier qualification processes. Three developments are restructuring competitive positioning.
Digital twin platforms for polyolefin stabilization systems are virtualizing technical service delivery between antioxidant suppliers and compounders. BASF and Songwon have deployed cloud-based degradation kinetic simulators that predict synergistic blend performance without physical testing. European automotive Tier 1s now specify virtual validation protocols, compressing qualification timelines from 18 months to 6 months while reducing sample material costs.
ECHA's 2024 update to REACH Annex XVII restriction entries for thioester degradation byproducts is tightening environmental release thresholds for antioxidant manufacturing. German polymer converters face downstream notification obligations for articles containing specified thioester concentrations above 0.1% by weight. The automotive segment is responding fastest, with BMW and Volkswagen accelerating supplier audits for full material disclosure compliance.
Compounders in China's Yangtze River Delta are consolidating procurement relationships around integrated antioxidant houses offering bundled primary-secondary stabilizer packages. Technical service bundling—combining formulation optimization, regulatory documentation, and just-in-time inventory management—is displacing transactional spot purchasing. This behavioral shift is most visible in polypropylene masterbatch production for appliance and automotive interior applications.
Antioxidant 412S Market Segmentation
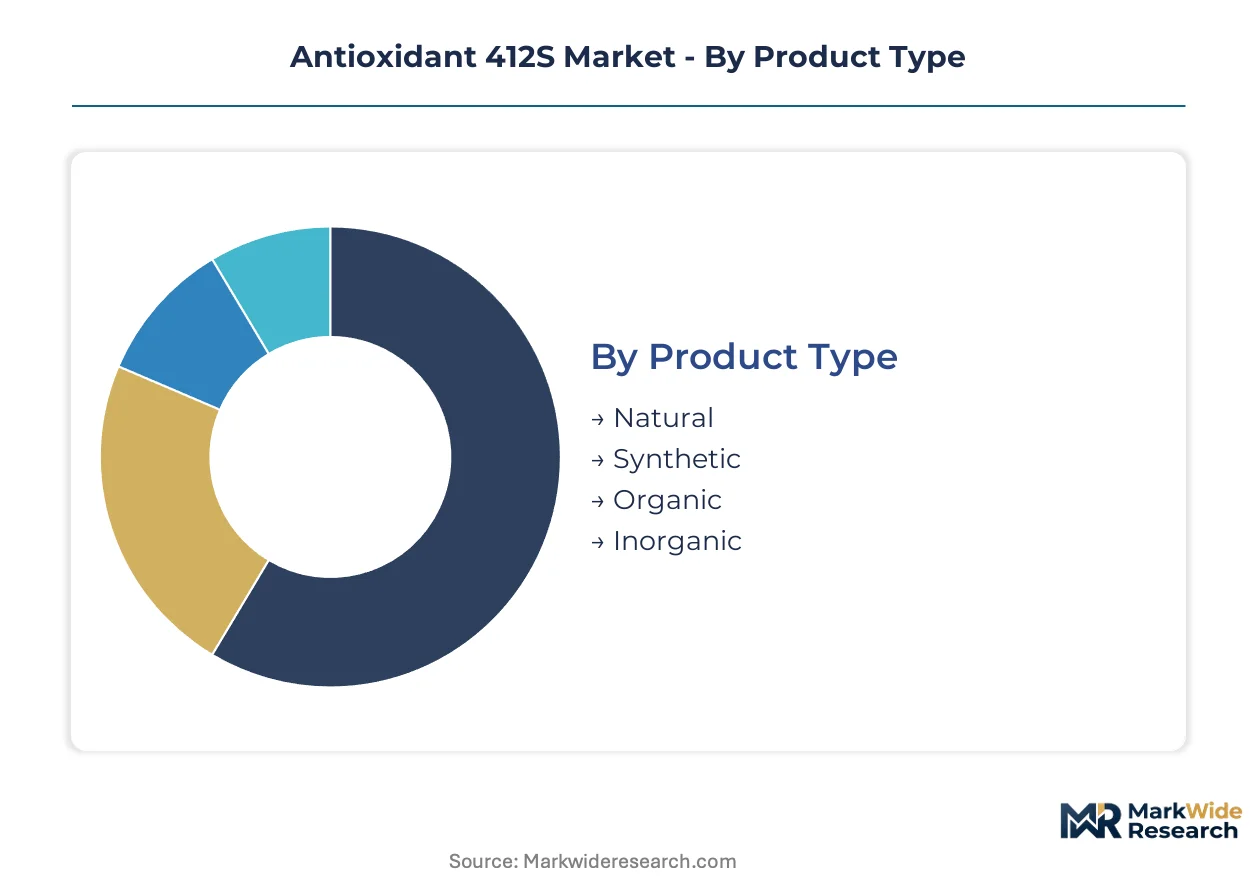
Antioxidant 412S serves divergent functional requirements across polymer stabilization and specialty chemical applications, necessitating distinct formulation grades, regulatory compliance tiers, and packaging configurations. Segmentation reveals how thioester chemistry adapts to thermal endurance demands in automotive plastics versus purity mandates in pharmaceutical and food-contact end uses.
Product Type:
Mature synthetic chemistry dominates commercial volumes while emerging natural alternatives carve protected niches under tightening regulatory scrutiny.
- Synthetic:Thioester-based formulations manufactured through controlled oxidation of organic sulfides deliver hydroperoxide decomposition at 150°C-plus service temperatures. Polypropylene compounding for automotive underhood applications in Germany, China, and the United States consumes the majority of technical-grade volume as OEM thermal endurance specifications tighten.
- Natural:Tocopherol and rosemary extract derivatives serve food-contact films and cosmetic packaging where SAMR positive lists and EFSA consumer exposure assessments restrict synthetic additive loadings. Premium positioning in European organic personal care lines supports margin premiums despite limited volume scale.
- Organic:Carbon-based antioxidant structures excluding thioester chemistries occupy intermediate performance tiers in specialty polymer applications.
- Inorganic:Metal-based stabilizer systems provide UV and thermal protection in construction-grade polyolefins where color stability requirements exceed thioester capabilities.
Synthetic grades retain volume leadership; natural alternatives hold the steepest expansion curve as regulatory tailwinds accelerate.
Application:
Cost tier stratification separates commodity polymer stabilization from certification-intensive life science segments demanding residual solvent documentation and heavy metal testing.
- Food Preservation:Antioxidant 412S incorporation into high-barrier multilayer films extends shelf life for oxygen-sensitive food matrices. SAMR positive list expansions and EFSA reauthorization protocols for thioester migration limits are opening qualified formulation opportunities in China and European retail packaging.
- Pharmaceutical Products:Stringent ICH Q3C residual solvent specifications and USP heavy metal limits restrict qualified suppliers to three global sources. Parenteral and inhalation dosage forms command 40-60% price premiums over technical grades due to batch certification requirements and audit-intensive quality systems.
- Cosmetic Formulations:Antioxidant stabilization of lipid-rich emulsions in premium skincare lines favors natural-synthetic hybrid systems.
- Nutritional Supplements:Softgel and oil-based vitamin formulations require oxidation protection compliant with FDA 21 CFR 172.115 food additive regulations.
Pharmaceutical-grade specifications command peak margins; food preservation applications are gaining share fastest as multilayer packaging penetration deepens.
End Use Industry:
Customer type fragmentation spans process chemical buyers seeking formulation integration support versus life science procurement teams prioritizing regulatory documentation packages.
- Food & Beverage:Polyolefin film converters and edible oil processors represent divergent demand streams unified by migration limit compliance requirements.
- Personal Care:Cosmetic formulators in France, South Korea, and the United States specify antioxidant systems with INCI nomenclature compatibility and cruelty-free certification alignment.
- Pharmaceuticals:Dosage form manufacturers in Switzerland, Singapore, and Ireland source excipient-grade antioxidants through qualified supplier audits covering ICH Q7 GMP compliance and EMA ASMF filing support.
- Feed:Animal nutrition compounders in Brazil and Thailand utilize antioxidant stabilization for fat-soluble vitamin premixes subject to national veterinary pharmaceutical regulator oversight.
Pharmaceuticals maintains the most concentrated supplier relationships; food and beverage end uses are expanding most quickly as packaging-grade qualification timelines compress.
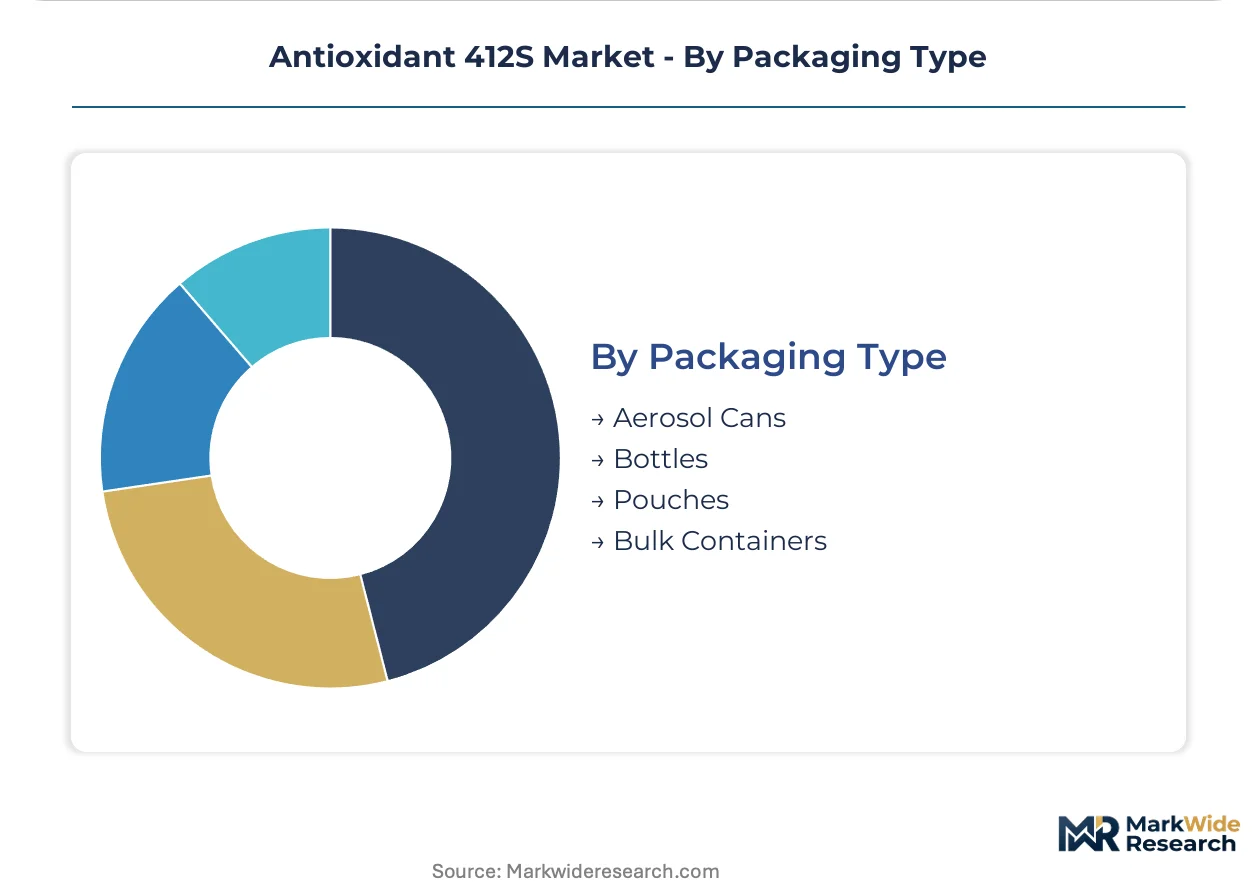
Packaging Type:
Supply concentration in bulk logistics contrasts with specialized containment for moisture-sensitive and oxygen-reactive formulations.
- Bulk Containers:Stainless steel totes and lined fiber drums serve polymer compounders in China's Yangtze River Delta and Germany's Rhine-Ruhr corridor with just-in-time inventory management integrated into technical service contracts.
- Bottles:Amber glass and fluoropolymer-lined containers protect pharmaceutical-grade thioester antioxidants from oxidative degradation during extended shelf storage. Swiss and Singaporean excipient distributors specify nitrogen headspace and induction-sealed closures for high-purity grades.
- Pouches:Multi-layer foil laminates with desiccant integration serve cosmetic sample and trial-size antioxidant formulations.
- Aerosol Cans:Pressurized delivery systems occupy niche positions in industrial maintenance antioxidant spray applications.
Bulk containers retain volume leadership; pharmaceutical-grade bottled packaging commands the steepest value-per-kilogram trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater port infrastructure underwrites China's dominance in thioester antioxidant export logistics, while Rhine barge networks sustain German polymer converter supply chains.
China
Polypropylene compounding for automotive underhood plastics drives technical-grade consumption in the Yangtze River Delta. SAMR positive list expansions for food-contact additives are accelerating qualification timelines for multilayer film applications. Domestic producers in Jiangsu and Zhejiang provinces are consolidating around integrated phenolic intermediate supply.
Germany
BMW and Volkswagen thermal endurance specifications are tightening hydroperoxide decomposition requirements for engine-bay plastics. ECHA's 2024 REACH Annex XVII updates impose downstream notification obligations on polymer converters. The Rhine-Ruhr corridor hosts Europe's densest concentration of polyolefin masterbatch technical service relationships.
United States
EPA TSCA Section 5 premanufacture review timelines are constraining novel thioester chemistry iteration cycles. Automotive Tier 1 suppliers in Michigan and Ohio are adopting virtual validation protocols for antioxidant qualification. The Gulf Coast petrochemical corridor provides captive feedstock integration for hindered phenol precursor production.
India
Polypropylene masterbatch producers in Gujarat and Maharashtra are bypassing European distributors for direct antioxidant procurement. BIS polymer additive standards are converging with REACH migration limit benchmarks. The Mumbai-Pune industrial corridor is emerging as a technical service relationship hub for Southeast Asian compounders.
Switzerland
Pharmaceutical-grade antioxidant demand from parenteral dosage form manufacturers commands 40-60% price premiums. Swissmedic excipient certification requirements limit qualified suppliers to three global sources. The Basel-Zurich corridor anchors European pharmaceutical packaging material stability testing.
Antioxidant 412S Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation chemistry and regulatory documentation capabilities. The antioxidant 412S supplier base concentrates around backward-integrated chemical houses with captive phenolic intermediate production. Two strategic archetypes dominate: integrated polymer stabilizer platforms bundling primary-secondary antioxidant packages, and purity-focused specialists serving pharmaceutical excipient specifications. Capacity expansion and technical service bundling represent the dominant competitive vectors.
Among integrated stabilizer platforms, BASF and Songwon exemplify the system-tier archetype through bundled formulation offerings and cloud-based degradation kinetic simulators. Rianlon occupies a position within the Asia-Pacific cost-competitive tier, serving polyolefin masterbatch producers with delivered-cost positioning. SI Group represents the specialty chemical house model with technical service relationships spanning automotive Tier 1 qualification protocols.
| Leading Market Players |
|---|
| ADEKA |
| BASF |
| SI Group |
| Songwon |
| Deltachem |
| Rianlon |
| Nanjing SQS |
| Solvay |
| Evonik Industries |
| Others |
Pricing and Supply Chain Analysis
Rhine barge networks and Yangtze River Delta deepwater ports anchor freight cost differentials that amplify supply concentration effects. Backward-integrated phenolic producers leverage captive intermediate supply to command premium positioning in pharmaceutical-grade tiers, while non-integrated compounders absorb margin compression from spot phenol sourcing.
Pricing Analysis
Volume-discount tiering structures stratify across pharmaceutical-grade certification, technical-grade automotive specifications, and commodity masterbatch volumes. Price differentiation rests on ICH Q3C residual solvent documentation and USP heavy metal compliance for parenteral applications, with SAMR positive list qualification commanding mid-tier premiums. Pricing pressure stems from Rianlon's aggressive delivered-cost positioning in Asian polyolefin markets. Polypropylene masterbatch producers in India exhibit highest price sensitivity; Swiss pharmaceutical excipient buyers prioritize audit reliability over unit economics.
Supply Chain Analysis
Export-control friction around dual-use chemical processing equipment constrains capacity expansion in certain jurisdictions. Geographic supply concentration centers on China, Germany, and the United States, with Jiangsu and Zhejiang provinces hosting integrated thioester synthesis clusters. Raw material dependencies include hindered phenol precursors, organic sulfide feedstocks, and catalytic oxidation reagents. Single-source vulnerability persists for pharmaceutical-grade purification equipment. Distribution runs through direct technical service relationships with polypropylene compounders, displacing European distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tocopherol and rosemary extract alternatives threaten synthetic thioester positioning in food-contact and cosmetic packaging segments. Incumbents must navigate this substitution pressure while defending integrated supply advantages.
For Market Incumbents: Build regulatory documentation moats through REACH consortium data leadership and SAMR positive list pre-qualification. BASF and Songwon should deepen cloud-based degradation kinetic simulator deployment to compress automotive Tier 1 qualification timelines. ECHA's 2024 Annex XVII updates on thioester degradation byproducts create audit-intensive compliance requirements that favor incumbents with established full material disclosure systems.
For New Entrants and Emerging Players: Pursue pharmaceutical-grade purity positioning where only three global sources currently qualify, supporting 40-60% price premiums over technical grades. India's Gujarat and Maharashtra masterbatch producers offer the most penetrable geography for direct compounding channel relationships. Technical service bundling—combining formulation optimization with just-in-time inventory—provides the strongest go-to-market angle against established distributor networks.
For Investors and Strategic Acquirers: Integrated antioxidant houses with captive phenolic intermediate supply and established ECHA data-sharing consortium participation represent the most defensible acquisition targets. Long-term viability hinges on carbon footprint disclosure compliance under EU CSRD and China's MEE dual carbon framework. Watch for MEE enforcement actions against carbon-intensive thioester producers as the inflection indicator for competitive restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Intermediates | Songwon's captive supply of hindered phenol precursors insulates margin compression from spot feedstock volatility. |
| Pharmaceutical-Grade Certification Investment | ICH Q3C residual solvent compliance limits qualified Antioxidant 412S suppliers to three global sources. |
| Direct Compounding Channel Expansion | Indian polypropylene masterbatch producers bypass European distributors for technical service relationships with manufacturers. |
| Carbon Footprint Disclosure Compliance | EU CSRD mandates favor producers with renewable energy-integrated thioester synthesis in European polymer converter sourcing. |
| Cloud-Based Degradation Kinetic Simulator Deployment | BASF's virtual validation protocols compress automotive Tier 1 antioxidant qualification timelines from 18 months to 6 months. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with polypropylene compounding plant managers, automotive Tier 1 procurement leads, pharmaceutical excipient quality directors, and specialty chemical distribution channel partners. Secondary validation drew from ECHA REACH registration databases, SAMR food-contact additive positive lists, SEC 10-K filings of listed antioxidant producers, and customs trade data for thioester antioxidant flows. Bottom-up volume modeling triangulated against top-down market sizing from polymer stabilization demand coefficients.
Calibration against historical price realization data and capacity utilization rates anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived from regression analysis of polymer compounding growth rates and antioxidant loading factor trends. Industry-specific forecast inputs encompassed automotive underhood thermal endurance specification trajectories and EFSA reauthorization timelines for thioester migration limits.
Macroeconomic conditions sit as an overlay; deviation in polypropylene resin pricing and ocean freight rates would shift the trajectory. Forecasts reflect documented assumptions regarding REACH registration maintenance costs and MEE carbon disclosure enforcement intensity. Material shifts in EPA TSCA Section 5 review timelines or ECHA restriction entry updates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Silicone Derivative Market
Specialty Chemicals
Zinc Methionine Chelates Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Organo-Modified Bentonite Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Sodium Ascorbyl Phosphate (SAP) Market
Specialty Chemicals
Global Aerosol Market