
 Phospholipid Market | 2026-2036
Phospholipid Market Size, Share, and Industry Trends Forecast 2026-2036
Phospholipid Market Analysis
Capital-intensity divergence between solvent extraction and enzymatic processing capabilities is unwinding legacy cost structures among established suppliers. Cargill, Incorporated leverages its integrated oilseed crushing network to secure raw lecithin feedstock at scale. Lipoid GmbH sustains pharmaceutical-grade phosphatidylcholine output through GMP-certified synthesis lines in Ludwigshafen. Croda International Plc differentiates via lipid nanoparticle expertise tied to mRNA delivery applications.
Phospholipids are amphipathic lipid molecules comprising glycerol-phosphate head groups esterified to two fatty acid tails, functioning as structural membrane components and drug delivery vehicles. Industrial production employs solvent extraction from soy or egg yolk, or enzymatic transphosphatidylation for custom head-group modifications. The nutraceuticals application segment anchors current volume as consumers seek phosphatidylserine for cognitive support. Pharmaceutical-grade phosphatidylcholine commands premium positioning due to parenteral emulsion requirements and injectable lipid nanoparticle demand. Powder and granular forms dominate bulk handling efficiency in food additive and animal nutrition channels.
FDA guidelines for parenteral lipid emulsions and EMA's GMP Annex 1 revisions on sterile manufacturing constrain entry for uncertified producers. The EU F-Gas Regulation and REACH compliance on solvent residues further elevate environmental handling costs for European facilities. China's NMPA import registration requirements for pharmaceutical excipients create procedural friction for non-domestic suppliers. Stakeholders must monitor enzymatic process yield improvements and regulatory reciprocity agreements between major jurisdictions to calibrate capacity investments.
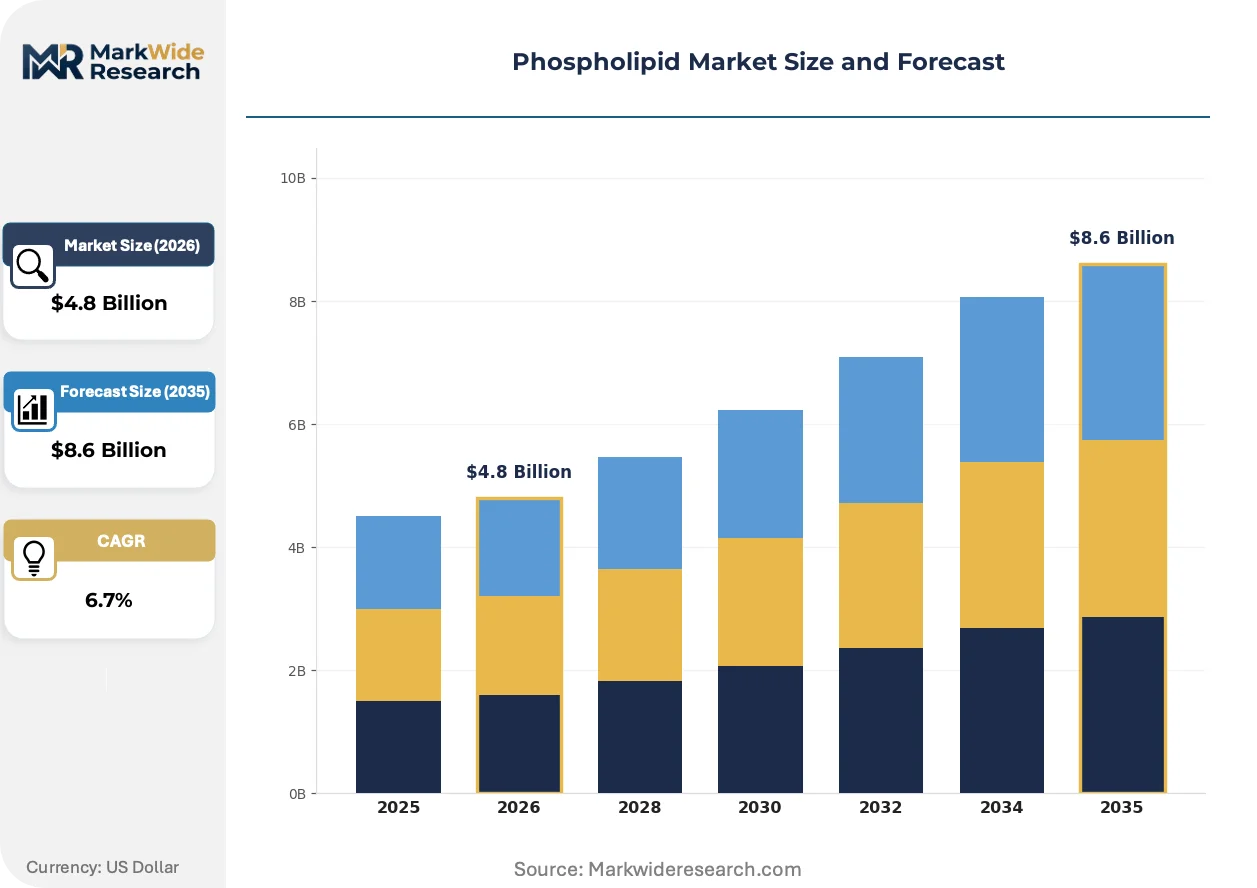
Market Dynamics
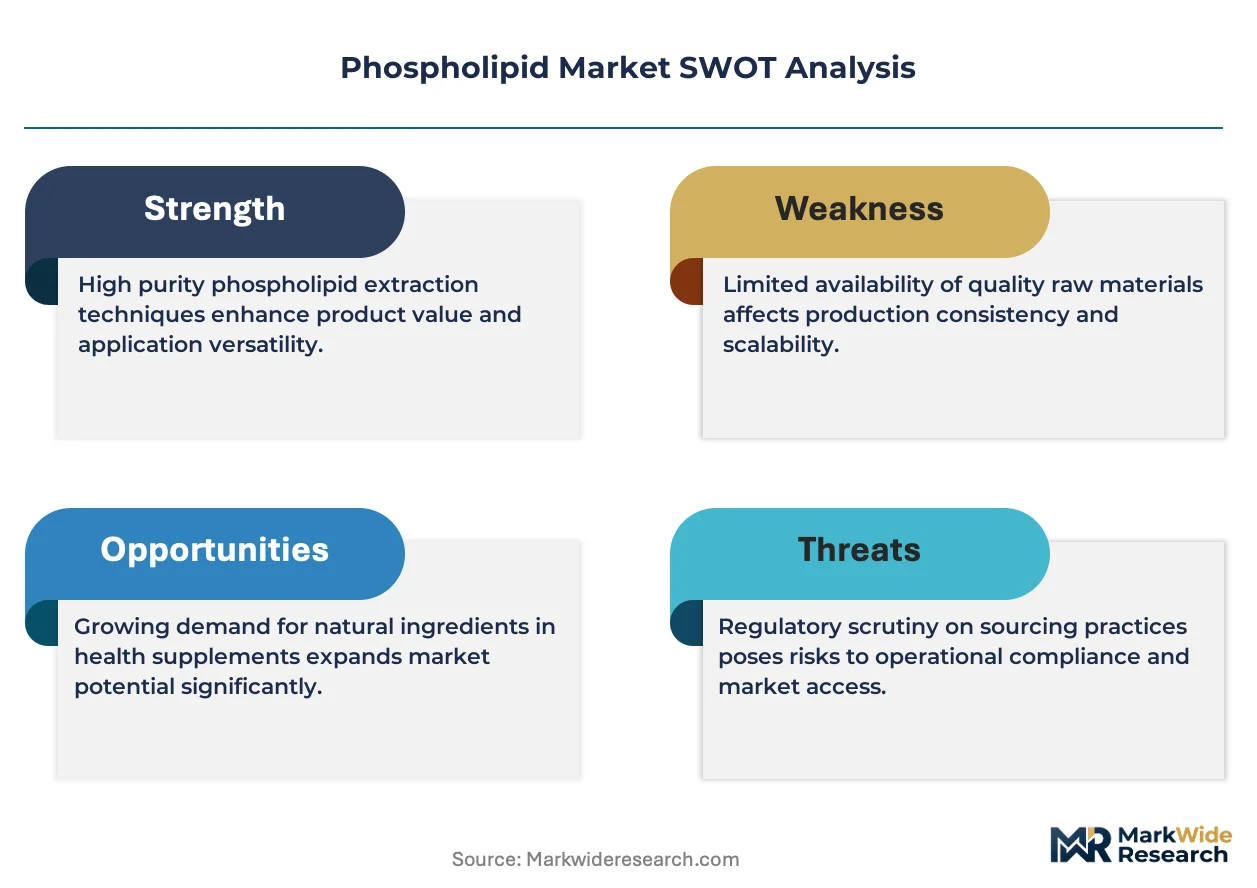
Enzymatic transphosphatidylation is displacing solvent extraction as the dominant production pathway, compressing legacy cost structures and forcing capacity reconfiguration among established suppliers. This technological transition interacts with tightening pharmaceutical-grade purity mandates to reshape competitive positioning.
Growth Catalysts
- Novel Food Regulation (EU):The European Union's tightening purity thresholds for marine-derived phospholipids is accelerating investment in advanced purification infrastructure among nutraceutical formulators.
- mRNA Delivery Applications:Lipid nanoparticle expertise tied to parenteral drug delivery is pulling pharmaceutical-grade phosphatidylcholine demand upward in sterile manufacturing channels.
- Germany Production Cluster:Concentrated contract manufacturing infrastructure around Ludwigshafen is generating network effects that attract downstream formulation investment.
Market Restraints
- Soy Lecithin Feedstock Volatility:Price instability in oilseed commodities transmits directly into raw material costs for solvent extraction operators lacking backward integration.
- REACH Solvent Residue Compliance:The EU's environmental handling requirements elevate facility costs for European producers relative to jurisdictions with less stringent chemical registration frameworks.
- Synthetic Phospholipid Substitution:Petrochemical-derived alternatives threaten to displace natural sources in cost-sensitive industrial applications where purity requirements remain modest.
Strategic Opportunities
- China NMPA Import Registration:Procedural friction for non-domestic pharmaceutical excipient suppliers creates first-mover advantages for registrants navigating the National Medical Products Administration pathway.
- Brain Health Formulation White Space:Phosphatidylserine positioning in cognitive support supplements remains underdeveloped relative to omega-3 fatty acids in Asian nutraceutical markets.
- ISO 13485 Convergence:Medical device quality management certification is opening adjacent revenue streams for GMP-certified phospholipid producers targeting drug-device combination products.
Industry Challenges
- EMA GMP Annex 1 Sterile Manufacturing Compliance:The revised guidance on contamination control strategy imposes capital-intensive facility upgrades that strain mid-scale producers.
- Enzymatic Process Yield Optimization:Biocatalytic head-group modification remains technically demanding, requiring specialized biochemistry talent scarce in traditional lipid processing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phospholipid Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphatidylcholine, Phosphatidylserine, Phosphatidylethanolamine, Lysolipid Application: Food Additives, Nutraceuticals, Pharmaceuticals, Cosmetics End User: Food Industry, Healthcare, Personal Care, Biotechnology Form: Liquid, Powder, Granular, Capsule |
| Companies Covered | Cargill, Incorporated, Archer-Daniels-Midland Company, Lipoid GmbH, Croda International Plc, Aker BioMarine, Lecico GmbH, VAV Life Sciences, DSM-Firmenich, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phospholipid Market Emerging Trajectories
Process intensification and regulatory harmonization are the dominant forces reshaping phospholipid manufacturing. These developments are compressing batch cycle times while elevating documentation burdens across supply chains.
Enzymatic transphosphatidylation is bifurcating the production landscape between commodity lecithin and custom phospholipid derivatives. Pharmaceutical formulators are adopting biocatalytic routes for tailored head-group modifications at accelerating pace. This technology is bifurcating supplier tiers into mass-market extractors and precision synthesis specialists with distinct margin profiles.
REACH compliance on solvent residues is forcing facility reconfiguration across European manufacturing sites. The European Chemicals Agency's registration requirements are compressing allowable volatile organic compound thresholds in extraction processes. Pharmaceutical-grade producers are responding by accelerating enzymatic platform investments to bypass solvent-dependent purification entirely.
Buyer concentration among contract development and manufacturing organizations is consolidating procurement leverage in phospholipid sourcing. Large CDMOs are unbundling excipient qualification from supplier selection, favoring vendors with dedicated regulatory affairs support. This pattern is most visible in Germany and Switzerland where parenteral emulsion manufacturing clusters dominate European pharmaceutical output.
Phospholipid Market Segmentation
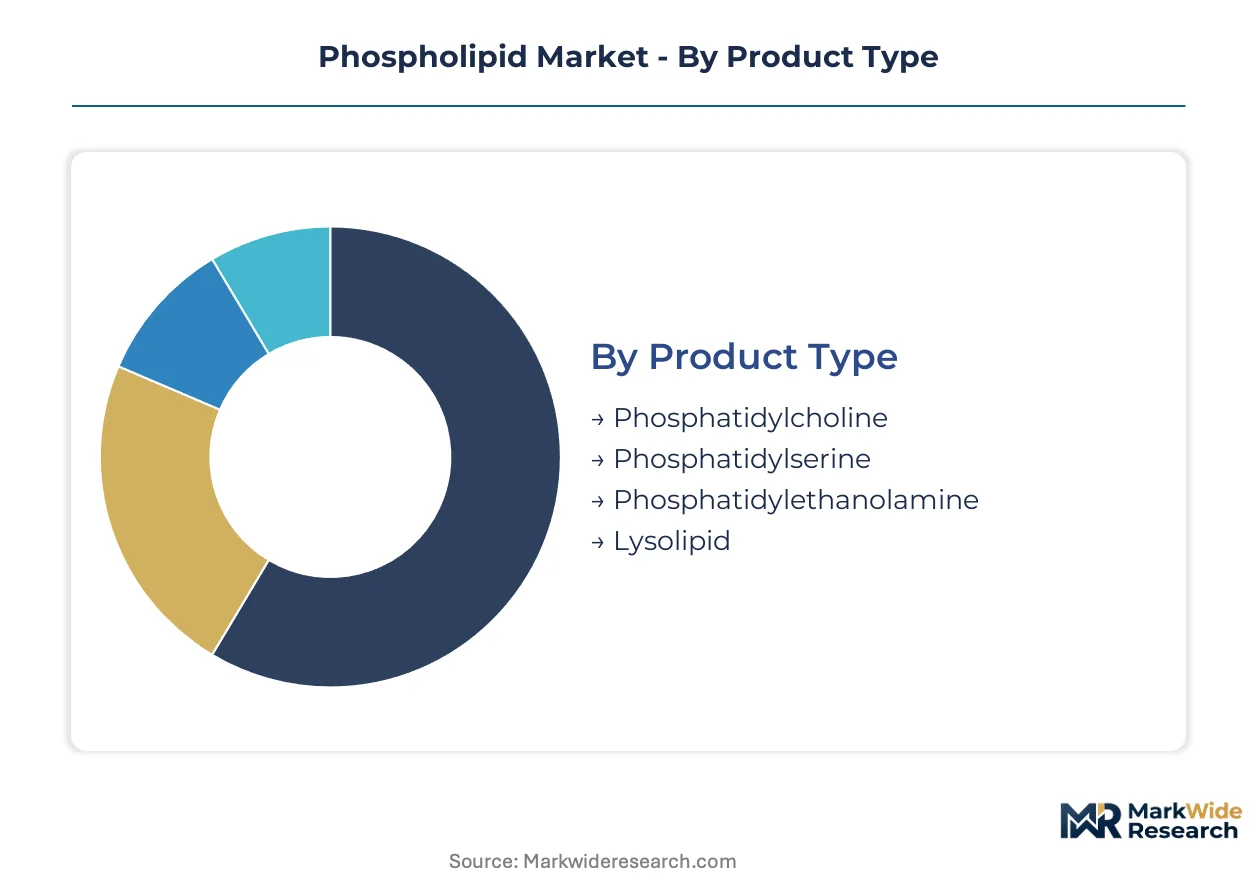
Phospholipid segmentation reveals divergent margin architectures across molecular species and formulation channels. Product chemistry dictates purification intensity, while end-use certification requirements fragment supplier tiers into pharmaceutical-grade and commodity processors.
Product Type:
Phosphatidylcholine production clusters in Germany and the Netherlands serve export-heavy pharmaceutical demand, while phosphatidylserine extraction concentrates in North American nutraceutical supply chains.
- Phosphatidylcholine:This zwitterionic phospholipid constitutes the primary structural component of cell membranes and lipoproteins. Demand concentrates in parenteral emulsion manufacturing across Ludwigshafen and Basel, driven by FDA and EMA sterile manufacturing mandates for injectable lipid formulations.
- Phosphatidylserine:An acidic phospholipid concentrated in neuronal tissue, valued for cortisol modulation and cognitive function claims. North American nutraceutical formulators in California and New Jersey anchor consumption, constrained by EFSA health claim substantiation requirements for European market access.
- Phosphatidylethanolamine:Abundant in inner mitochondrial membranes, this aminophospholipid supports fusion events in lipid bilayers. Industrial applications in Japan and South Korea utilize this grade for liposome construction in cosmetic delivery systems.
- Lysolipid:Single-fatty-acid derivatives function as emulsifiers and membrane permeabilization agents. Brazilian and Argentinian soy processing facilities generate regional supply for Latin American food additive channels.
Phosphatidylcholine commands the established base. The steepest expansion runs through phosphatidylserine as brain health positioning penetrates Asian nutraceutical markets.
Application:
Cost tier stratification separates pharmaceutical excipient qualification from commodity food additive procurement, with nutraceuticals occupying an intermediate certification band.
- Food Additives:Lecithin emulsification in chocolate and bakery applications demands minimal purity thresholds. European chocolate manufacturers in Belgium and Switzerland source fluid soy lecithin through backward-integrated oilseed processors.
- Nutraceuticals:Dietary supplement formulations require identity-preserved sourcing and heavy metal screening. US contract manufacturers in Utah and Florida drive powder phospholipid consumption for softgel encapsulation.
- Pharmaceuticals:Parenteral-grade phospholipids undergo endotoxin testing and particulate matter controls per USP <661> and EP 2.9.19. Sterile manufacturing sites in Germany, Switzerland, and Singapore concentrate demand for this tier.
- Cosmetics:Liposome encapsulation of active ingredients utilizes phosphatidylcholine for dermal penetration enhancement. French and Italian formulators in the luxury skincare segment specify hydrogenated grades for oxidative stability.
Food additives anchor volume throughput. Pharmaceuticals deliver the highest value-per-kilogram realization.
End User:
Customer type fragmentation separates multinational pharmaceutical procurement from regional food processor spot buying, with biotechnology emerging as a specification-intensive growth vector.
- Food Industry:Confectionery and margarine producers utilize fluid and de-oiled lecithin for viscosity modification and anti-spattering. German and Dutch oilseed crushers supply this channel through established distribution networks.
- Healthcare:Hospital nutrition and clinical enteral feeding formulations require pharmaceutical-grade phospholipid emulsions. Japanese and South Korean medical device manufacturers integrate these excipients into lipid-based drug delivery platforms.
- Personal Care:Skincare and haircare formulators specify hydrogenated phospholipids for lamellar gel network construction. Italian and French cosmetic compounders in the Lombardy and Île-de-France regions concentrate procurement leverage.
- Biotechnology:Cell culture media and transfection reagent manufacturers utilize synthetic and natural phospholipids for membrane modeling. Massachusetts and California biotech clusters drive specialized lysolipid demand for CRISPR delivery applications.
The food industry sustains baseline capacity utilization. Biotechnology applications are climbing the fastest as gene therapy manufacturing scales.
Form:
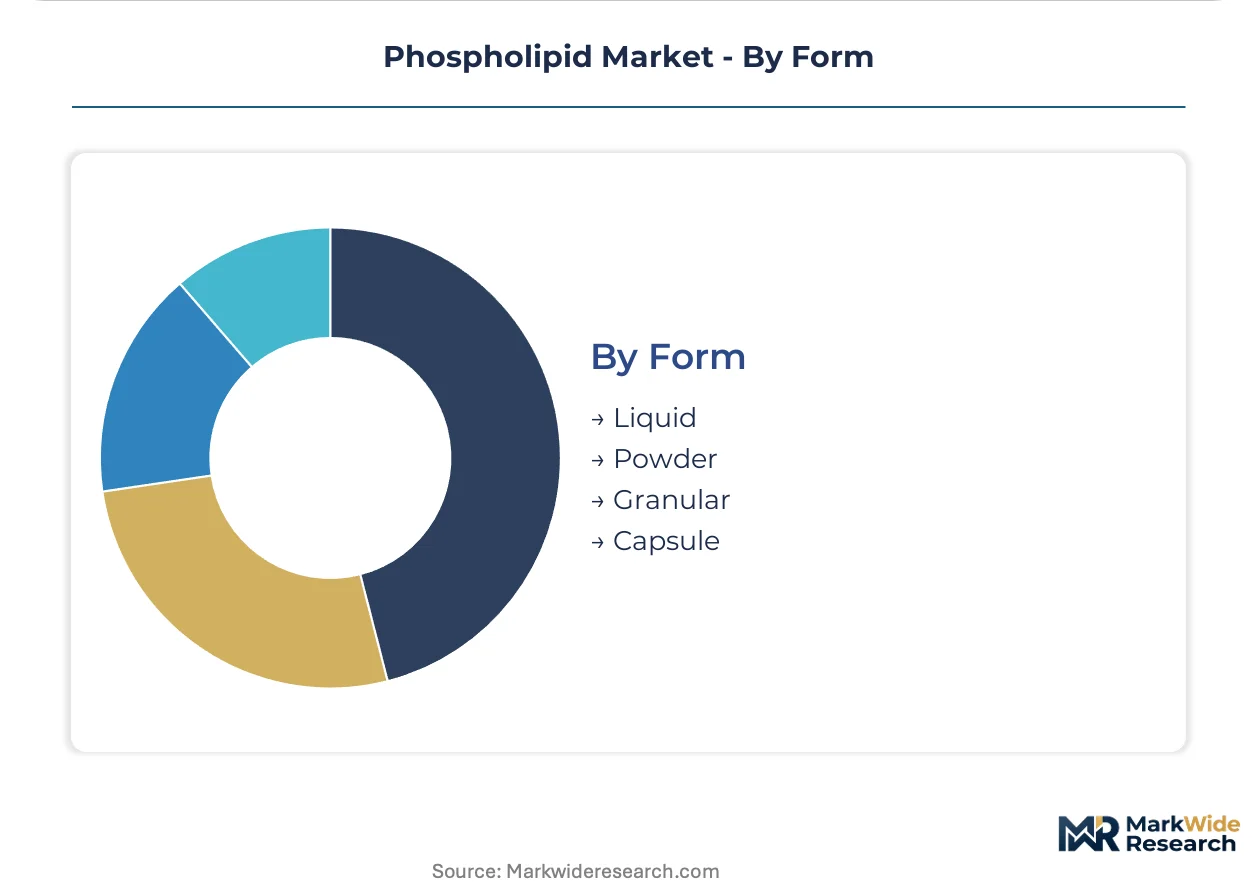
Supply concentration in powder processing facilities around Mannheim and Rotterdam shapes regional availability for bulk nutraceutical and animal nutrition channels.
- Liquid:Fluid lecithin from degummed vegetable oils serves chocolate concretion and margarine emulsification. Belgian and Swiss confectionery manufacturers source through Antwerp port logistics.
- Powder:Spray-dried and roller-dried formats optimize handling efficiency in premix and supplement manufacturing. German processors in Hamburg and Frankfurt supply European compound feed and human nutrition channels.
- Granular:Agglomerated particles reduce dusting and improve flow properties for high-speed tableting operations. Indian and Chinese nutraceutical contract manufacturers specify this grade for domestic and export formulation.
- Capsule:Pre-encapsulated phosphatidylserine and phosphatidylcholine target direct-to-consumer supplement positioning. US and Canadian brands utilize softgel and hard-shell formats for cognitive health and liver support claims.
Liquid and powder forms dominate industrial procurement. Capsule formats are expanding most quickly as finished supplement brands bypass bulk handling investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phospholipid buyers in Germany and Switzerland absorb pharmaceutical-grade premiums without volume elasticity, while food processors in Brazil and India negotiate aggressively on soy lecithin feedstock costs. This demand-elasticity contrast shapes regional investment patterns and supplier margin structures.
Germany
Pharmaceutical-grade phosphatidylcholine demand from Ludwigshafen and Frankfurt sterile manufacturing clusters anchors premium pricing. EMA GMP Annex 1 revisions on contamination control strategy force facility upgrades among mid-scale producers. Lipoid GmbH's GMP-certified synthesis lines in Ludwigshafen concentrate pharmaceutical output and attract adjacent contract manufacturing investment.
United States
Nutraceutical formulators in Utah and California drive powder phospholipid consumption for cognitive health softgels. FDA guidelines for parenteral lipid emulsions constrain uncertified producers from entering pharmaceutical channels. Massachusetts and California biotech clusters pull specialized lysolipid demand for gene therapy manufacturing applications.
China
Domestic nutraceutical brands accelerate phosphatidylserine sourcing for brain health positioning in tier-one cities. NMPA import registration requirements for pharmaceutical excipients create procedural friction for non-domestic suppliers. Yangtze River Delta processing facilities expand enzymatic production capacity to serve regional pharmaceutical formulators.
Switzerland
Basel-based parenteral emulsion manufacturers concentrate European pharmaceutical-grade procurement leverage. Swissmedic certification requirements for sterile manufacturing elevate supplier qualification barriers. The Basel-Ludwigshafen corridor generates network effects that consolidate excipient sourcing decisions among large CDMOs.
Brazil
Regional food additive processors in São Paulo and Paraná source fluid soy lecithin for confectionery and margarine applications. ANVISA regulatory alignment with FDA standards creates dual-qualification pathways for export-oriented suppliers. Argentinian and Brazilian soy crushing facilities generate captive regional supply for Latin American compound feed channels.
Phospholipid Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in phospholipid supply. Oilseed processors with backward integration into crushing operations command feedstock cost advantages over standalone extractors. The market stratifies into three archetypes: commodity lecithin suppliers, pharmaceutical-grade synthesis specialists, and lipid nanoparticle technology providers. Dominant competitive moves include enzymatic platform investments to bypass solvent-dependent purification and regulatory affairs capacity building to serve CDMO procurement requirements.
Among integrated agribusiness operators, Cargill, Incorporated and Archer-Daniels-Midland Company exemplify the commodity lecithin archetype with oilseed network leverage. Lipoid GmbH occupies a position within the pharmaceutical-grade synthesis specialist tier. Croda International Plc represents the lipid nanoparticle technology vector tied to mRNA delivery applications.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer-Daniels-Midland Company |
| Lipoid GmbH |
| Croda International Plc |
| Aker BioMarine |
| Lecico GmbH |
| VAV Life Sciences |
| DSM-Firmenich |
| Kemin Industries |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between pharmaceutical-grade phospholipid suppliers and Ludwigshafen-based CDMOs lock in both supply access and price visibility across multi-year horizons, insulating contract holders from soy lecithin spot volatility while constraining flexibility for uncertified entrants.
Pricing Analysis
Parts and service revenue from regulatory dossier support and excipient qualification documentation drives lifetime value for pharmaceutical-grade suppliers. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and food-additive levels separates sterile manufacturing certification from identity-preserved sourcing from commodity fluid lecithin. Pricing pressure stems from enzymatic process yield improvements compressing synthesis costs for precision phospholipid derivatives. Food processors in Brazil and India exhibit highest price sensitivity, while Basel-based parenteral emulsion manufacturers absorb premiums without volume elasticity.
Supply Chain Analysis
Germany and the Netherlands anchor pharmaceutical-grade phosphatidylcholine purification, while Brazil and Argentina dominate fluid soy lecithin extraction for regional food channels. Raw material flows draw from oilseed crushing networks, egg yolk powder processors, and marine biomass harvesters. Single-source vulnerability concentrates in Ludwigshafen GMP-certified synthesis lines serving European sterile manufacturing demand. Distribution runs through Antwerp port logistics for fluid lecithin, Mannheim powder processing facilities for bulk nutraceutical channels, and direct CDMO qualification pathways for pharmaceutical excipients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large CDMOs unbundling excipient qualification from supplier selection, with procurement leverage consolidating around Swiss and German parenteral manufacturing clusters.
For Market Incumbents: Shield pharmaceutical-grade margin tiers by accelerating enzymatic platform investments that bypass REACH solvent residue compliance costs entirely. Deepen backward integration into oilseed crushing or marine biomass harvesting to secure feedstock cost advantages against commodity lecithin volatility. Prioritize regulatory affairs capacity building to serve CDMO procurement requirements as buyer concentration intensifies. For New Entrants and Emerging Players: Regulatory dossier support for NMPA import registration creates white-space opportunity where established suppliers under-serve Chinese pharmaceutical formulators. Target enzymatic transphosphatidylation specialization for custom head-group modifications, as biocatalytic talent scarcity fragments precision synthesis supply. Penetrate through partnership with Yangtze River Delta processing facilities expanding enzymatic capacity. For Investors and Strategic Acquirers: Lipid nanoparticle technology providers with GMP-certified synthesis infrastructure represent the priority acquisition archetype, positioned at the intersection of mRNA delivery demand and sterile manufacturing qualification. Long-term viability hinges on enzymatic yield optimization capabilities and regulatory reciprocity navigation across FDA, EMA, and NMPA jurisdictions. Monitor EMA GMP Annex 1 compliance timelines as inflection indicator for facility upgrade capital requirements and mid-scale producer distress.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Platform Investment | Bypasses REACH solvent residue thresholds while enabling custom head-group modifications for lipid nanoparticle applications. |
| Backward Integration into Oilseed Crushing | Secures captive lecithin feedstock supply insulating against commodity price volatility in Brazilian and Argentinian soy markets. |
| NMPA Import Registration Navigation | Creates first-mover advantage in Chinese pharmaceutical excipient channels where procedural friction constrains non-domestic suppliers. |
| GMP Annex 1 Facility Upgrade | EMA contamination control strategy mandates strain mid-scale producers, consolidating supply among capital-rich sterile manufacturing specialists. |
| Lipid Nanoparticle Expertise Acquisition | mRNA delivery demand pulls pharmaceutical-grade phosphatidylcholine into sterile manufacturing channels with premium pricing power. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA parenteral lipid emulsion guidelines, EMA GMP Annex 1 revisions, and customs trade data for soy lecithin flows. Interviews with sterile manufacturing plant managers, nutraceutical contract manufacturer procurement leads, and lipid nanoparticle formulation scientists combined with SEC filings from integrated oilseed processors and ECHA REACH registration databases. Bottom-up demand modeling across application segments triangulated against top-down production capacity assessments from German and Dutch processing clusters.
Segmentation dimensions modeled include product chemistry tier, application certification grade, end-use industry, and regional regulatory cluster across the analysis window. CAGRs derived from elasticity-adjusted volume projections and value-per-kilogram realization trends by purity tier. Forecast inputs incorporate enzymatic process yield improvement trajectories and CDMO buyer concentration patterns in the Basel-Ludwigshafen corridor.
Forecasts assume regulatory continuity in FDA sterile manufacturing guidelines and EMA GMP Annex 1 implementation timelines; material policy shifts in EU F-Gas Regulation or NMPA excipient registration pathways would require re-modeling. Recalibration cycles align with material shifts in enzymatic platform commercialization rates and mRNA delivery application scaling.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Multimodal Chromatography Columns Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Zinc Eugenol Market
Specialty Chemicals
Global Foam Blowing Agents Market