
 Flame-Retardant Synergist Systems with Low Smoke Toxicity Market | 2026-2036
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market Size, Share, and Industry Trends Forecast 2026-2036
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market Insights
Asset-light leasing models for compounding equipment are reshaping how mid-size additive suppliers enter the flame-retardant synergist space. Clariant AG leverages its global technical service network to sustain specification relationships with wire and cable OEMs. BASF SE anchors European demand through backward integration into phosphorus chemistry. ICL Group competes on manufacturing scale in bromine-free platforms.
Flame-retardant synergist systems with low smoke toxicity combine two or more active agents—typically phosphorus, nitrogen, or metal hydroxide compounds—to achieve UL-94 V-0 ratings at reduced total additive loading while limiting carbon monoxide and hydrogen cyanide evolution during combustion. These formulations serve critical fire safety functions in enclosed infrastructure and passenger compartments where smoke inhalation poses greater lethality than direct flame exposure. Halogen-free synergists command expanding specification share as OEMs and electrical equipment manufacturers phase out legacy brominated systems under sustainability protocols. Wire and cable applications dominate current volume consumption, though automotive interiors represent the fastest-growing addressable segment as cabin fire safety standards tighten. Masterbatch and pellet forms capture premium positioning by reducing dust exposure and improving dosing precision in twin-screw extrusion.
REACH restrictions on halogenated flame retardants and the EU Green Deal's building renovation targets collectively redirect formulation demand toward phosphorus-based and intumescent alternatives in European construction. EPA assessments of persistent organic pollutants and evolving NFPA 130 transit standards in the United States impose parallel compliance burdens on domestic suppliers. China's GB standards for public building materials and MEE enforcement of dual carbon goals accelerate metal hydroxide adoption in East Asian projects. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D commitments.
Market Dynamics
Wire and cable OEMs in China, Germany, and the United States are consolidating specification authority around phosphorus-based synergist systems as municipal fire codes tighten smoke toxicity ceilings for enclosed infrastructure. This procurement concentration is compressing supplier margins while elevating technical service capabilities as the primary competitive differentiator.
Growth Catalysts
- NFPA 130 Transit Standards:Updated evacuation safety mandates in US rail and bus systems are forcing material upgrades in passenger compartment wiring, expanding addressable volume for low-smoke phosphorus formulations.
- Automotive Interior Fire Safety:Cabin material specifications under UN ECE R118 and parallel China GB standards are accelerating metal hydroxide adoption in seat fabrics and dashboard substrates across East Asian vehicle assembly.
- EU Green Deal Building Renovation:Renovation targets for commercial and residential structures are redirecting construction material procurement toward REACH-compliant halogen-free alternatives in German and French public projects.
Market Restraints
- Phosphorus Feedstock Concentration:Captive phosphate rock reserves and processing capacity cluster in Morocco, China, and Florida, exposing formulation costs to geopolitical supply disruptions and export quota volatility.
- Metal Hydroxide Loading Requirements:Achieving equivalent UL-94 V-0 ratings with aluminum or magnesium hydroxide demands 40-60% higher additive loadings than phosphorus alternatives, increasing compound density and material cost per finished part.
- REACH Registration Burden:Novel synergist chemistries face extended ECHA evaluation timelines and testing cost recovery requirements that deter mid-size suppliers from European market entry.
Strategic Opportunities
- India Building Code Modernization:BIS adoption of international fire safety standards for high-rise construction creates first-mover positioning for phosphorus-nitrogen intumescent systems in Mumbai and Delhi commercial developments.
- Masterbatch Distribution Innovation:Pre-compounded pellet formats reduce dust exposure and dosing variance for mid-size wire and cable extruders, opening specification access beyond tier-one compounders.
- EV Battery Enclosure Materials:Thermal runaway containment requirements in lithium-ion pack designs are redirecting automotive supplier R&D toward ceramic-enhanced synergist layers with simultaneous flame and smoke suppression functions.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in phosphorus-nitrogen char formation kinetics and polymer compatibility testing concentrates among legacy additive houses, constraining new entrant product development velocity.
- Multi-Jurisdiction Certification Complexity:Divergent UL, IEC, and GB testing protocols for smoke density and toxicity metrics force redundant qualification runs that extend commercialization timelines by 12-18 months for single product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame-Retardant Synergist Systems with Low Smoke Toxicity Market |
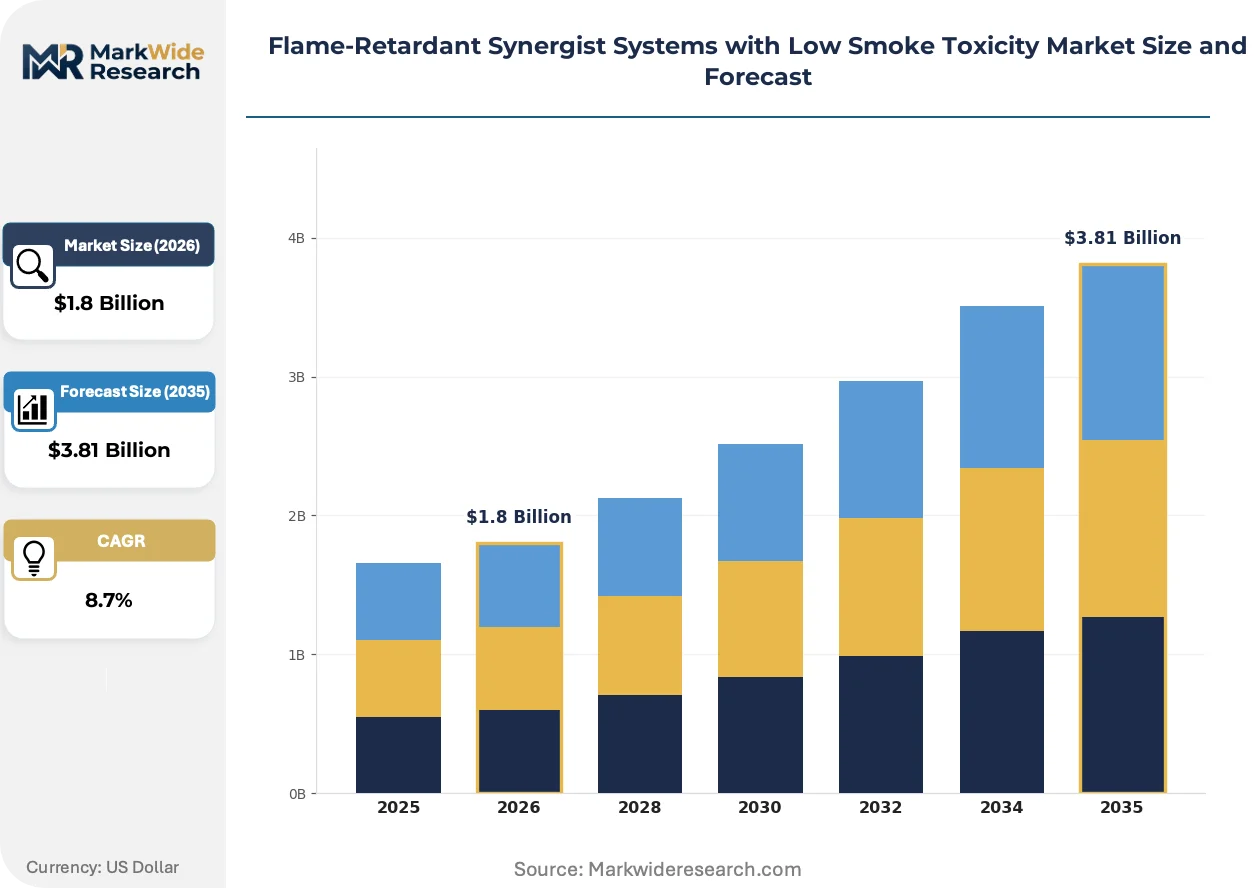
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent Additives, Halogen-Free Synergists, Phosphorus-Based Systems, Metal Hydroxides, Nitrogen-Based Agents Application: Wire & Cable, Electronics Housings, Building Materials, Textile Coatings, Automotive Interiors End User: OEMs, Electrical Equipment Manufacturers, Construction Firms, Textile Producers, Transportation Component Suppliers Form: Powder, Pellet, Granules, Liquid Concentrate, Masterbatch |
| Companies Covered | Clariant AG, BASF SE, LANXESS AG, ICL Group, ADEKA Corporation, SONGWON Industrial Group, Budenheim, Momentive Performance Materials, Albemarle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market Trends and Innovations
Formulation science is converging with digital compounding controls to enable precise char-layer engineering in next-generation synergist systems. Three developments are compressing legacy technical boundaries while redrawing competitive positioning among additive suppliers.
Micro-encapsulated phosphorus architectures with controlled release kinetics are rendering obsolete conventional surface-coated ammonium polyphosphate in thin-wall electrical conduit applications. Tier-one wire and cable compounders in Germany and the United States are transitioning specification approvals toward these engineered particle systems. The shift is compressing acceptable loading thresholds by 15-20% while maintaining equivalent fire performance.
REACH Annex XIV authorization procedures for legacy halogenated retardants are accelerating substitution timelines in European construction and transportation materials. ECHA's 2024-2025 sunset date cluster for decabromodiphenyl ether and hexabromocyclododecane is forcing compounders to validate phosphorus-alternative drop-in formulations ahead of stockpile depletion. French and Italian cable manufacturers are advancing qualification programs most aggressively to secure construction tender eligibility.
Asset-light equipment leasing for twin-screw compounding lines is fragmenting procurement authority toward mid-size additive distributors. Chinese and Indian regional suppliers are bypassing traditional masterbatch houses by offering technical service bundled with production capacity rental. The model is most visible in East Asian wire and cable clusters where capital constraints previously locked smaller compounders out of specification-driven segments.
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market Segmentation
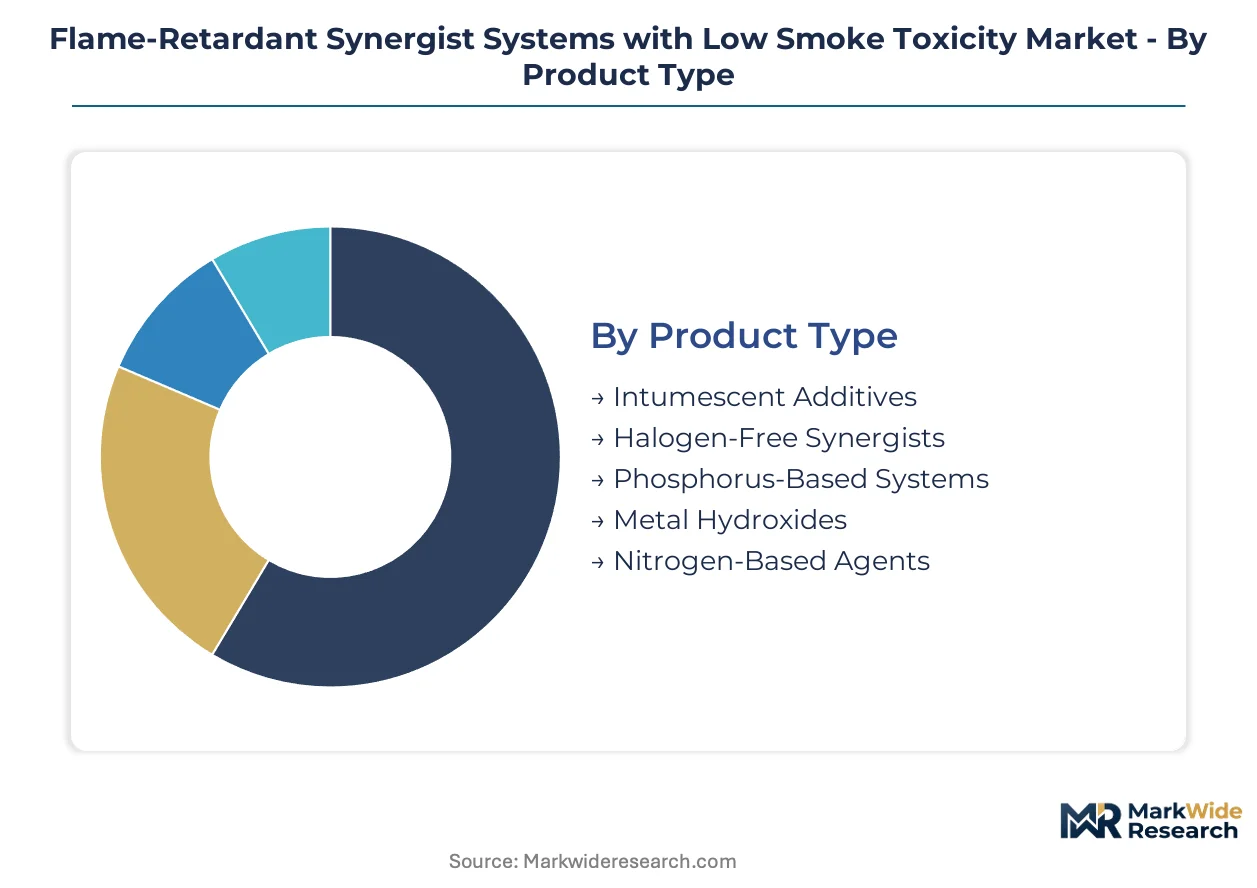
Segmentation in this market tracks how formulation chemistry, physical form, and end-use specifications intersect with procurement authority across regulated industries. Understanding these divides exposes where technical service capabilities translate into specification lock-in versus commodity competition.
Product Type:
Mature intumescent platforms coexist with emerging metal hydroxide architectures as suppliers balance char-formation reliability against loading efficiency pressures.
- Phosphorus-Based Systems:Ammonium polyphosphate and phosphinate salts dominate wire and cable compounding through established UL-94 V-0 qualification pathways. German and Chinese electrical OEMs are consolidating procurement specifications around these systems as REACH deadlines eliminate legacy halogenated alternatives.
- Halogen-Free Synergists:Phosphorus-nitrogen combinations and metal hydroxide blends serve automotive interior mandates under UN ECE R118 and China GB standards. Cabin fire safety upgrades across East Asian vehicle assembly lines are accelerating specification shifts toward these platforms.
- Intumescent Additives:Expandable graphite and pentaerythritol-based char formers target construction steel coatings and public infrastructure applications.
- Metal Hydroxides:Aluminum and magnesium hydroxide systems compete on raw material cost despite 40-60% higher loading requirements versus phosphorus alternatives.
- Nitrogen-Based Agents:Melamine derivatives and guanidine compounds function primarily as secondary synergists in intumescent formulations rather than standalone solutions.
Phosphorus-based systems retain volume leadership; halogen-free synergists hold the steepest expansion curve.
Application:
Application segmentation reveals how enclosure geometry and evacuation dynamics dictate smoke toxicity thresholds across infrastructure categories.
- Wire & Cable:Insulation and jacketing compounds for electrical conduit represent the established consumption base where NFPA 130 transit standards and IEC cable fire performance protocols drive material upgrades. Procurement concentrates among tier-one compounders in China, Germany, and the United States with backward integration into phosphorus chemistry.
- Automotive Interiors:Seat fabrics, dashboard substrates, and headliner foams face tightening cabin fire safety regulations under UN ECE R118 and parallel China GB standards. East Asian vehicle assembly expansion is expanding addressable volume faster than wire and cable replacement cycles.
- Building Materials:Insulation boards, structural panels, and interior finishes serve EU Green Deal renovation targets and China's public building material GB standards.
- Electronics Housings:Server chassis, consumer appliance enclosures, and industrial control housings demand thin-wall UL-94 V-0 ratings at minimal additive loading.
- Textile Coatings:Protective workwear and transportation seating fabrics require flexible char layers without compromising fabric hand or durability.
Wire and cable commands procurement scale; automotive interiors are climbing the fastest.
End User:
End user categories track where specification authority concentrates versus where technical service relationships determine supplier selection.
- Electrical Equipment Manufacturers:Transformer housings, switchgear enclosures, and distribution panel components require halogen-free alternatives as European utilities enforce sustainability procurement protocols. These buyers possess in-house compounding expertise that compresses supplier margins while demanding customized formulation support.
- OEMs:Appliance, electronics, and automotive original equipment manufacturers integrate flame-retardant specifications into tiered supplier qualification systems. REACH compliance documentation and UL certification maintenance function as entry barriers that favor established additive houses with regulatory affairs infrastructure.
- Construction Firms:Public infrastructure contractors in France, Germany, and China face mandatory green building certification requirements that redirect material selection.
- Transportation Component Suppliers:Seat manufacturers, interior trim producers, and wiring harness specialists serve as specification intermediaries between raw additive suppliers and vehicle OEMs.
- Textile Producers:Technical fabric mills and coating operations seek pre-dispersed masterbatch formats to avoid powder handling complexity.
Electrical equipment manufacturers anchor procurement volume; OEMs present the most demanding technical service requirements.
Form:
Physical form segmentation separates dust-exposure compliance solutions from cost-minimized bulk delivery.
- Masterbatch:Concentrated pellet formats with polymer carrier resins reduce dust exposure and dosing variance for mid-size wire and cable extruders. Asset-light leasing models for twin-screw compounding lines are fragmenting procurement authority toward regional distributors offering technical service bundled with production capacity.
- Pellet:Pre-compounded additive-resin blends capture premium positioning by eliminating in-house dispersion equipment requirements. Chinese and Indian regional suppliers are bypassing traditional masterbatch houses through equipment rental partnerships.
- Powder:Uncompounded active ingredients retain cost advantage for large compounders with captive dust containment infrastructure.
- Granules:Intermediate particle sizes bridge powder cost efficiency and pellet handling convenience for medium-batch operations.
- Liquid Concentrate:Dispersed slurries serve textile coating and spray-applied construction applications where dry dispersion is impractical.
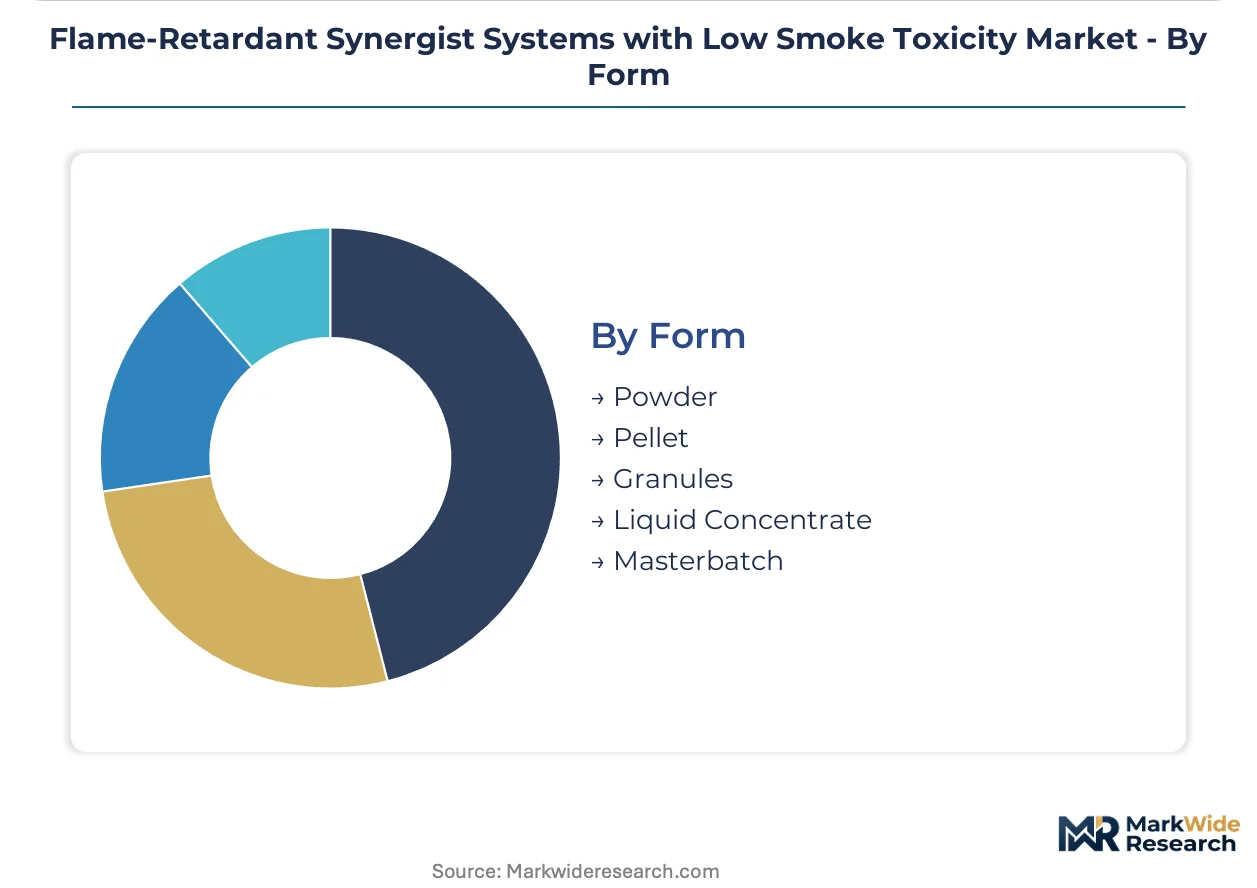
Masterbatch formats gain specification share; pellet forms are expanding most quickly through distributor channel innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage concentrates in German wire and cable clusters where REACH compliance deadlines compress supplier margins, while Chinese additive houses capture volume through asset-light equipment leasing models that fragment procurement authority toward regional distributors.
United States
NFPA 130 transit standards are forcing material upgrades in passenger compartment wiring across rail and bus systems. EPA assessments of persistent organic pollutants impose parallel compliance burdens on domestic suppliers. Wire and cable OEMs in the Midwest and Northeast are consolidating specification authority around phosphorus-based synergist systems.
Germany
EU Green Deal building renovation targets redirect construction material procurement toward REACH-compliant halogen-free alternatives. ECHA sunset dates for decabromodiphenyl ether and hexabromocyclododecane accelerate substitution timelines. French and Italian cable manufacturers are advancing qualification programs most aggressively to secure construction tender eligibility.
China
GB standards for public building materials and MEE enforcement of dual carbon goals accelerate metal hydroxide adoption in East Asian projects. Electrical equipment manufacturers across the Yangtze River Delta are scaling procurement of phosphorus-based systems. Regional suppliers bypass traditional masterbatch houses through equipment rental partnerships.
India
BIS adoption of international fire safety standards for high-rise construction creates first-mover positioning for phosphorus-nitrogen intumescent systems. Mumbai and Delhi commercial developments face mandatory green building certification requirements. Mid-size additive distributors are fragmenting procurement authority through technical service bundled with production capacity.
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in phosphorus chemistry and metal hydroxide processing. The market structures around three tiers: global additive houses with regulatory affairs infrastructure, regional compounders with backward integration into phosphorus chemistry, and asset-light distributors leveraging leased compounding capacity. Consolidation concentrates among European and East Asian players with REACH documentation capabilities. Dominant competitive moves include strategic partnerships with wire and cable OEMs and geographic expansion through masterbatch distribution networks.
Among European chemical conglomerates, Clariant AG, BASF SE, and LANXESS AG occupy positions that exemplify the integrated platform archetype. Clariant AG leverages global technical service networks to sustain specification relationships. BASF SE anchors European demand through backward integration into phosphorus chemistry. LANXESS AG represents the specialty chemicals tier with regulatory compliance infrastructure. These three sit within the premium specification tier where REACH registration and UL certification maintenance function as entry barriers.
| Leading Market Players |
|---|
| Clariant AG |
| BASF SE |
| LANXESS AG |
| ICL Group |
| ADEKA Corporation |
| SONGWON Industrial Group |
| Budenheim |
| Momentive Performance Materials |
| Albemarle Corporation |
| Others |
Pricing and Supply Chain Analysis
Phosphate rock export quota volatility in Morocco and China determines both three-tier pricing stratification across premium, standard, and economy levels and supply chain configuration for flame-retardant synergist systems. This feedstock concentration exposes formulation costs to geopolitical disruption while compressing margins for non-integrated compounders.
Pricing Analysis
Industrial OEM buyers anchor pricing stratification across premium, standard, and economy tiers differentiated by REACH registration completeness and UL-94 certification tier. Cost compression in standard-grade phosphorus systems is intensifying because wire and cable OEMs in China and Germany are consolidating procurement volume around qualified suppliers. Tier-one electrical equipment manufacturers show least price sensitivity due to sustainability mandate compliance requirements, while mid-size construction contractors face acute margin pressure from metal hydroxide loading cost premiums.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Moroccan and Chinese phosphate suppliers serving European compounders, reshaping working capital requirements across the value chain. Captive phosphate processing capacity clusters in Morocco, China, and Florida, with aluminum hydroxide feedstock drawing from Australian bauxite and Chinese alumina refining. Single-source vulnerability concentrates in Moroccan phosphate rock exports, which feed from mine-to-compounder distribution through Rotterdam and Shanghai hub terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among wire and cable OEMs across China, Germany, and the United States has shifted bargaining power toward buyers, fragmenting supplier margins while elevating technical service capabilities as the primary retention mechanism.
For Market Incumbents: Build regulatory affairs infrastructure as a certification moat against mid-size entrants lacking ECHA registration bandwidth. Deepen backward integration into phosphorus chemistry to defend margin position against feedstock volatility from Moroccan export quotas. Prioritize masterbatch format expansion through equipment leasing partnerships that lock regional distributors into specification relationships. For New Entrants and Emerging Players: Mid-market commercial buildings in India represent the most penetrable entry point given BIS adoption timelines and absence of entrenched incumbents with REACH-equivalent documentation. Asset-light compounding equipment rental bundled with technical service opens specification access without capital-intensive masterbatch infrastructure. Target phosphorus-nitrogen intumescent systems for Mumbai and Delhi high-rise developments where green building certification mandates are newly enforced. For Investors and Strategic Acquirers: ECHA sunset date clusters for decabromodiphenyl ether and hexabromocyclododecane reshape the acquisition landscape toward phosphorus-alternative formulation specialists with validated drop-in qualifications. Five-to-ten-year viability favors regional compounders with backward integration into phosphate processing and established UL-94 V-0 certification maintenance infrastructure. Monitor qualification program completion rates at French and Italian cable manufacturers as inflection indicators for substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Chemistry | BASF SE's captive phosphate processing insulates margin from Moroccan export quota volatility. |
| Masterbatch Distribution Network Expansion | Clariant AG's pellet format reduces dust exposure for mid-size wire and cable extruders. |
| Equipment Leasing Partnership Model | Chinese regional suppliers fragment procurement authority through technical service bundled with production capacity. |
| REACH Registration Infrastructure Investment | LANXESS AG's ECHA documentation capabilities function as entry barriers against non-European entrants. |
| Automotive Interior Specification Qualification | ICL Group's UN ECE R118 certification opens cabin material procurement across East Asian vehicle assembly. |
Research Methodology
A spread of perspectives from wire and cable procurement directors, automotive interior material engineers, construction specification consultants, and regulatory affairs leads at additive houses converged on the working assumptions. Primary fieldwork combined structured interviews with downstream OEMs and masterbatch compounders, validated against customs trade data, ECHA registration databases, SEC 10-K chemical segment disclosures, and IEC cable fire performance protocol documentation. Bottom-up volume estimates from end-use application sizing and top-down cross-checks against phosphorus derivative consumption statistics established analytical triangulation.
Demand-supply balance modeling across the projection horizon tracked phosphorus-based systems, halogen-free synergists, intumescent additives, metal hydroxides, and nitrogen-based agents by physical form and end-use industry. CAGRs derived from regression analysis of historical qualification timelines, regulatory deadline clustering effects, and substitution elasticity parameters. Forecast inputs incorporated NFPA 130 transit standard adoption curves, EU Green Deal building renovation procurement trajectories, and China GB standard enforcement intensity by provincial MEE office.
Macroeconomic conditions sit as an overlay; deviation in phosphate rock pricing, construction activity indices, or automotive production schedules would shift the trajectory. Forecasts reflect documented assumptions about regulatory deadline adherence, qualification timeline compression, and feedstock supply continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
North America Aerosol Cans Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Cubeb Oil Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Demethylase Inhibitor Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
Cellulose Esters and Ethers Market