
 Global Bio Based Esters Market | 2026-2036
Global Bio Based Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio Based Esters Market Intelligence
Procurement patterns for bio-based esters are shifting as large chemical manufacturers and consumer goods companies consolidate their supplier lists to ensure feedstock consistency and traceability. BASF SE leverages its extensive production scale to serve multinational clients across diverse end-uses from paints to personal care. Cargill Inc. specializes in sourcing agricultural feedstocks, controlling a critical part of the upstream value chain. Meanwhile, Vertec Bio-Solvents competes on the basis of its specialized, high-purity formulations for niche industrial cleaning applications.
Bio-based esters are chemical compounds derived from the esterification of renewable sources, such as vegetable oils, animal fats, and fatty acids. They function as high-performance, biodegradable alternatives to traditional petroleum-derived solvents, plasticizers, and lubricants, offering a lower carbon footprint. Within the product portfolio, methyl esters and ethyl esters command significant volume due to their versatile application profiles and cost-effectiveness. While industrial lubricants represent a mature application, the use of these esters in cosmetics and personal care formulations is expanding due to consumer preference for green ingredients.
Regulatory frameworks like the European Union's REACH legislation and the US EPA's Safer Choice Standard directly impact product formulation and market access. These regulations promote the use of low-VOC (Volatile Organic Compound) and non-toxic ingredients, creating favorable conditions for bio-based esters over their petrochemical counterparts. Securing stable, long-term access to cost-competitive bio-based feedstocks remains the central strategic challenge for producers seeking to gain market share.
Market Dynamics
The market's central dynamic is the tension between volatile agricultural feedstock costs and intensifying regulatory mandates for petrochemical substitution. This pressure shapes all strategic decisions, from securing upstream supply chains for vegetable oils to investing in process technologies that improve yield and cost-competitiveness against petroleum-derived esters.
Growth Catalysts
- Regulatory Frameworks:Policies like the European Union's REACH legislation and the US EPA's Safer Choice Standard create market access advantages for bio-based esters by restricting or disincentivizing traditional solvents with high VOC content or unfavorable toxicological profiles.
- Consumer Demand for Green Cosmetics:The personal care sector's shift toward sustainable and "natural" ingredients provides a significant pull for bio-based esters, which function as emollients, solubilizers, and texture modifiers in cosmetic formulations.
- Feedstock Availability in Agricultural Hubs:Geographic concentration of agricultural processing in regions like the US Midwest and Southeast Asia provides scalable sources for key feedstocks such as soy, palm, and rapeseed oils, enabling large-scale production.
Market Restraints
- Feedstock Price Volatility:Prices for vegetable oils and animal fats are subject to agricultural commodity market fluctuations, weather events, and food-versus-fuel debates, creating input cost instability for ester producers and complicating long-term pricing.
- Performance Gaps in Niche Applications:In certain high-pressure or high-temperature industrial lubricant applications, some bio-based esters do not yet match the full performance and durability spectrum of their synthetic petrochemical counterparts.
- Competition from Petrochemicals:Incumbent petroleum-derived esters, particularly in price-sensitive, high-volume applications, present a significant barrier due to their established production scale, lower cost base, and deeply integrated supply chains.
Strategic Opportunities
- Biodegradable Polymer Additives:The expanding market for biodegradable plastics like PLA and PHA creates a demand for compatible bio-based plasticizers and process aids, representing a significant new application category beyond traditional solvents and lubricants.
- Emerging Market Adoption:As countries in South America and Southeast Asia begin to implement stricter environmental regulations, there is an opportunity to introduce bio-based ester solutions into markets currently dominated by petrochemicals.
- Advanced Esterification Processes:The development of enzymatic catalysis and continuous-flow reaction technologies offers a path to improve production efficiency, reduce energy consumption, and lower the manufacturing costs of bio-based esters.
Industry Challenges
- Supply Chain Traceability:Establishing and certifying end-to-end traceability for bio-based feedstocks to meet corporate sustainability goals and prevent greenwashing claims is a complex logistical and data management challenge for producers.
- Standardization of Bio-Content:A lack of globally harmonized standards and certification schemes for defining and measuring "bio-based" content can lead to market confusion, trade barriers, and difficulties in comparing products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio Based Esters Market |
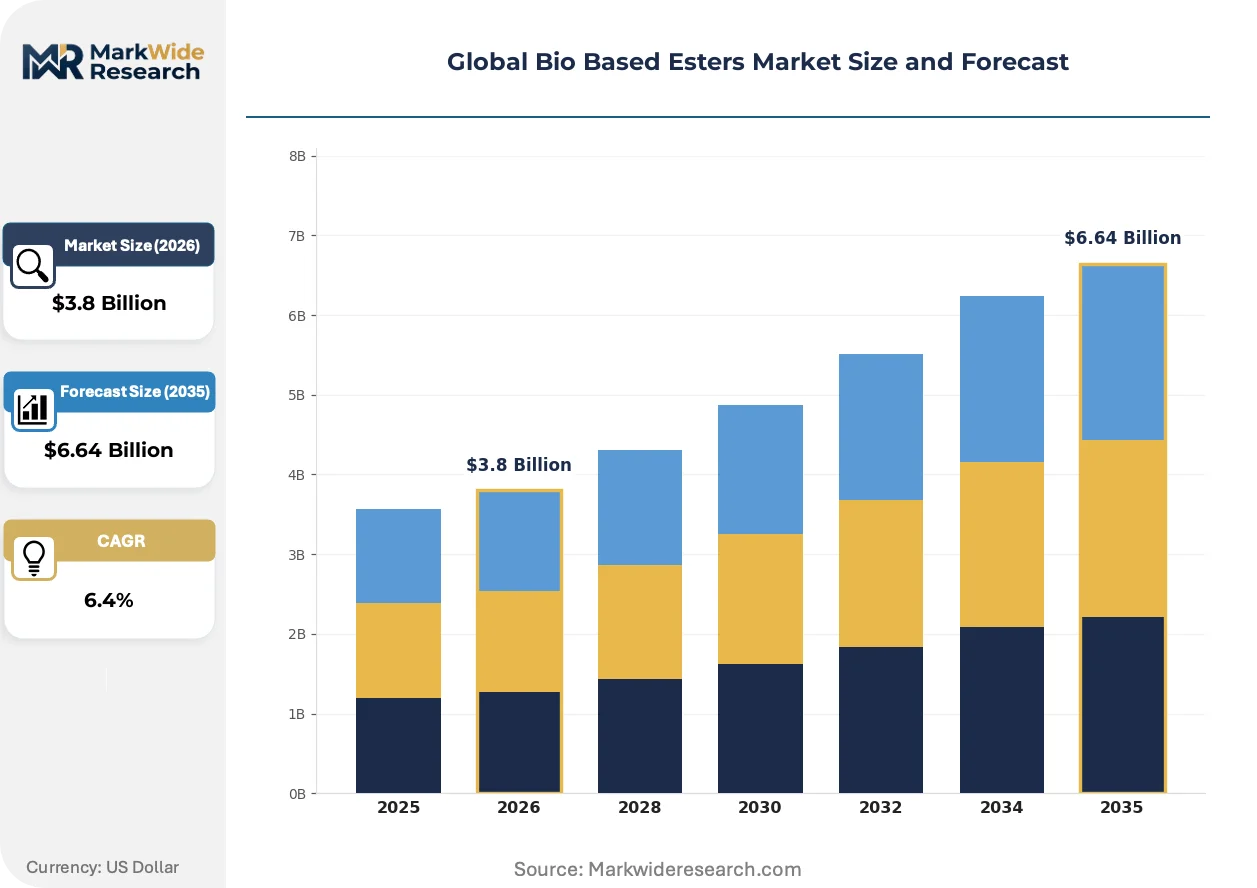
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butyl Esters, Ethyl Esters, Methyl Esters, Propyl Esters Application: Cosmetics, Industrial Lubricants, Food Additives, Personal Care End User: Automotive, Chemical Manufacturers, Paints & Coatings, Food Industry Form: Liquid, Solid, Gel, Powder |
| Companies Covered | Cargill Inc., Arkema Inc., BASF SE, Vertec Bio-Solvents, Solvay, Huntsman Corporation, Spak Orgochem, Mangalam Organic Ltd., Ester Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio Based Esters Market Strategic Shifts & Innovations
Product development is pivoting from direct substitution of petrochemicals to creating novel esters with unique functional properties unattainable with traditional chemistry. This shift is driven by formulators in high-value sectors seeking performance differentiation through sustainable ingredients.
Advanced enzymatic catalysis provides a highly selective method for producing specific ester structures under mild reaction conditions. Formulators in the cosmetics and food ingredient sectors are adopting this technology to create high-purity esters without the byproducts common in chemical catalysis. This technology is decentralizing production capabilities, enabling smaller, specialized batches tailored to specific customer performance requirements.
The EU Green Deal and its associated Circular Economy Action Plan are forcing a fundamental reassessment of material sourcing across the continent. These policies incentivize the use of renewable, bio-based feedstocks and promote designing products for biodegradability, directly benefiting the bio-based esters market. The industrial lubricants and solvents segments in Germany and France are most affected, facing pressure to reformulate products to align with circularity principles.
Buyer requirements are evolving to include mandatory supply chain transparency and third-party sustainability certifications. This change disrupts the conventional, price-driven commodity procurement model for esters, favoring suppliers who can provide verifiable data on feedstock origin and carbon footprint. This behavior is most prominent among multinational consumer goods companies headquartered in Europe, which are embedding these criteria into their global supplier contracts.
Global Bio Based Esters Market Segmentation
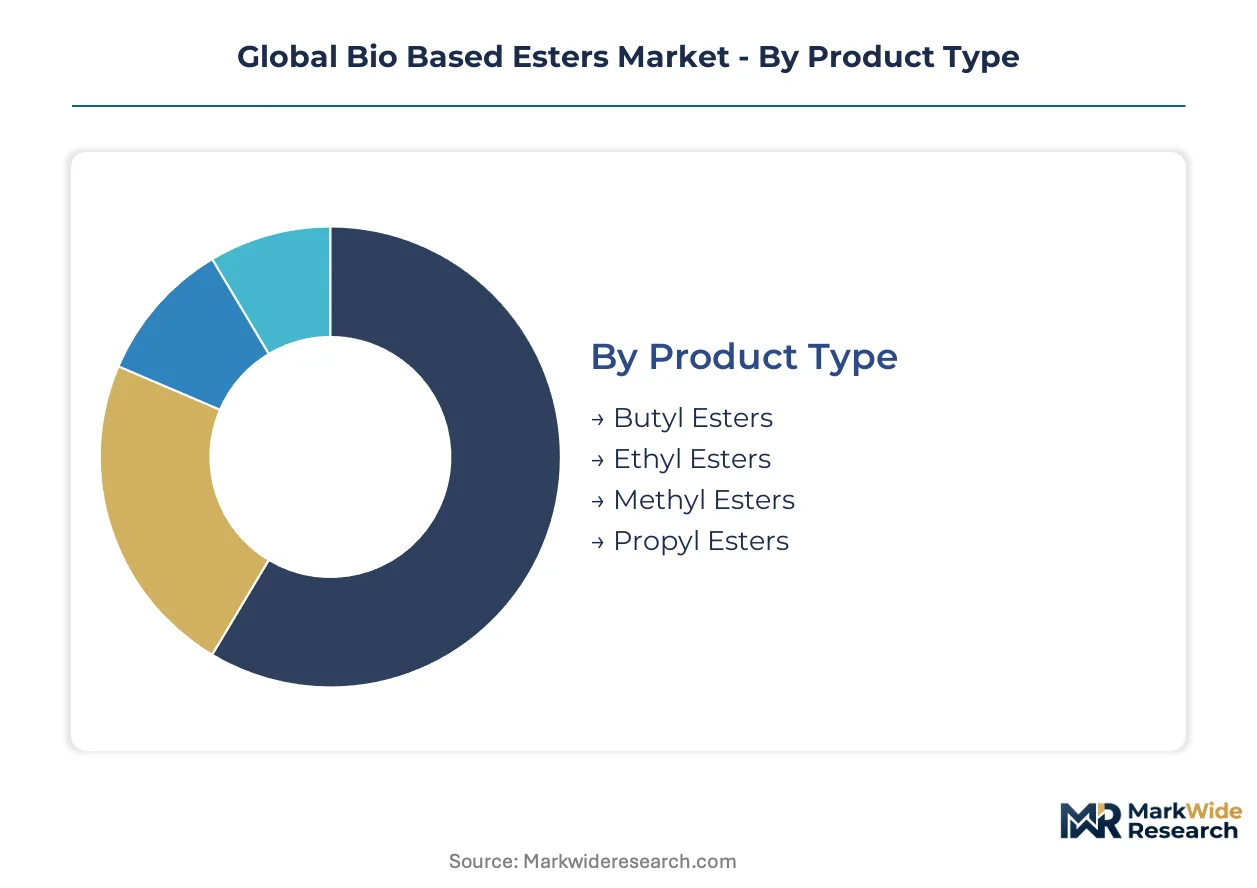
The global bio-based esters market exhibits diverse segmentation, driven by varying functional requirements, feedstock availability, and end-user preferences. Understanding these segments is critical for producers to strategically allocate resources, optimize production processes, and tailor product offerings to specific demand pockets across industries.
Product Type:
The initial investment required for manufacturing different bio-based ester product types varies significantly based on feedstock processing and purification technologies.
- Butyl Esters:These esters, derived from butanol and fatty acids, often serve as solvents and plasticizers in coatings and inks. Their performance properties are balanced for general industrial applications.
- Ethyl Esters:Formed from ethanol and fatty acids, ethyl esters offer excellent solvency and biodegradability, finding expanded use as emollients in cosmetics and as fuel additives due to their clean-burning characteristics. Demand is increasing in personal care formulations across Europe.
- Methyl Esters:These esters, typically derived from methanol and vegetable oils, are high-volume, cost-effective compounds widely utilized as biodiesel, solvents, and chemical intermediates. Their versatile application profile drives significant demand from chemical manufacturers in Germany.
- Propyl Esters:Propyl esters, synthesized from propanol and fatty acids, function as industrial solvents and plasticizers. Their slightly higher boiling points compared to ethyl esters make them suitable for specific coating applications.
Methyl Esters absorbs the bulk of installed capacity; Ethyl Esters is expanding most quickly.
Application:
The margin profiles across bio-based ester applications diverge, reflecting varying performance requirements and regulatory hurdles.
- Cosmetics:Bio-based esters function as emollients, solubilizers, and texture modifiers in cosmetic formulations, driven by consumer preference for natural and sustainable ingredients. Demand for these green ingredients is particularly strong in the European personal care market.
- Industrial Lubricants:These esters serve as high-performance, biodegradable alternatives to petroleum-derived lubricants, especially in environmentally sensitive areas and applications requiring low toxicity. While a mature segment, performance gaps in extreme conditions remain a restraint for some bio-based options.
- Food Additives:Bio-based esters act as emulsifiers, flavor carriers, and dough conditioners in the food industry. Their natural origin and functional properties make them suitable for clean-label food products.
- Personal Care:Within personal care, bio-based esters are utilized in skin care, hair care, and sun care products, offering moisturizing and conditioning benefits. Formulators seek these sustainable components to meet brand sustainability goals.
Industrial Lubricants command the largest market share; Cosmetics is climbing the fastest.
End User:
Customer procurement sophistication varies significantly among end-users, influencing demand for traceability and specialized formulations.
- Automotive:The automotive sector uses bio-based esters in lubricants, coolants, and some interior components, driven by sustainability mandates and the need for high-performance, biodegradable fluids. OEMs in Germany are increasingly evaluating these materials.
- Chemical Manufacturers:Large chemical manufacturers utilize bio-based esters as intermediates for synthesizing other chemicals, as solvents, and as plasticizers. Their extensive production capabilities allow for volume procurement and integration into diverse product lines.
- Paints & Coatings:Bio-based esters serve as low-VOC solvents and coalescents in paints, coatings, and adhesives, helping manufacturers comply with environmental regulations. Reformulation pressure from the US EPA's Safer Choice Standard drives adoption.
- Food Industry:The food industry incorporates bio-based esters into various products as emulsifiers, stabilizers, and processing aids, aligning with consumer demand for natural and sustainably sourced ingredients.
Chemical Manufacturers represent the largest volume consumers; the Food Industry is adopting bio-based esters at an accelerated rate.
Form:
The physical form of bio-based esters often dictates their handling, storage, and integration into diverse manufacturing processes.
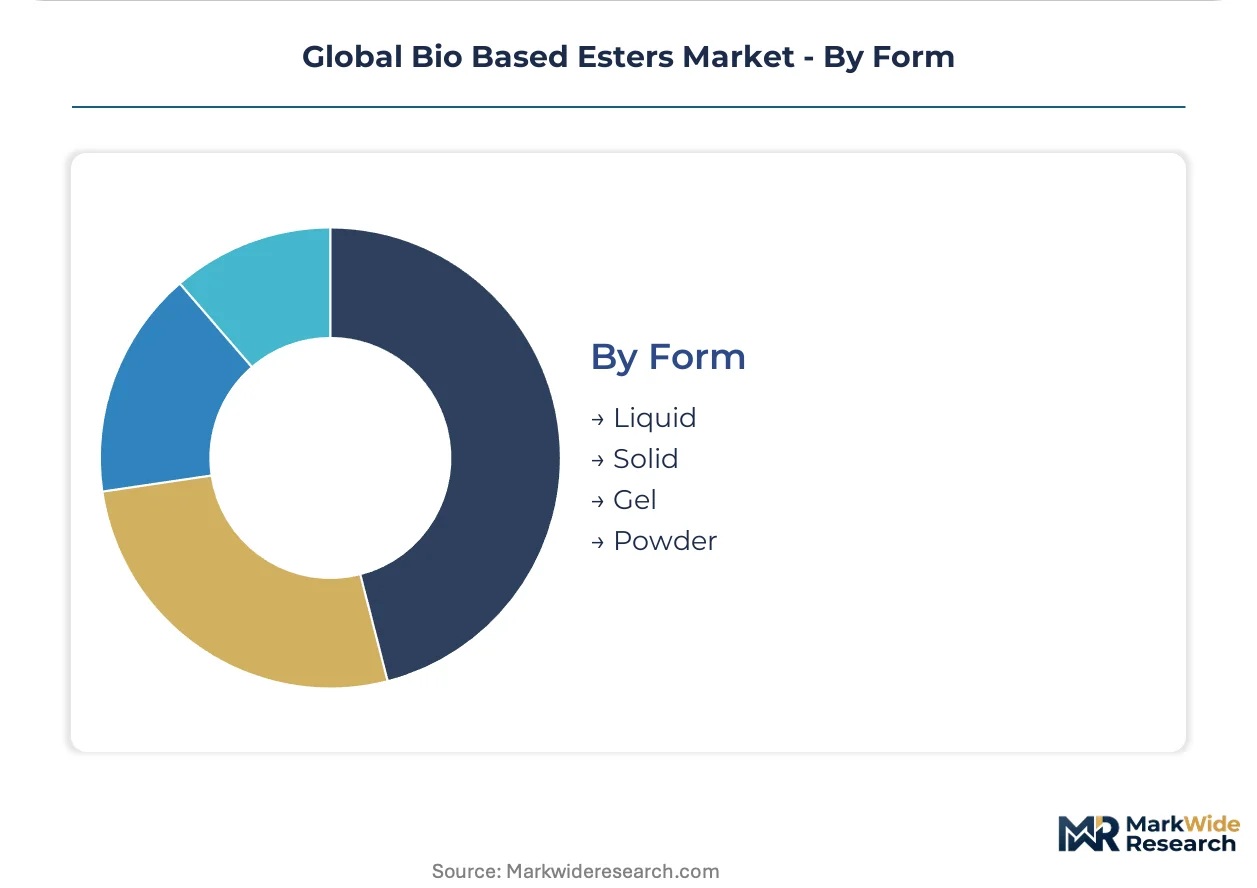
- Liquid:Liquid bio-based esters are the predominant form, widely used as solvents, lubricants, and emollients due to their ease of handling and blending. This form is versatile for most industrial and personal care applications.
- Solid:Solid bio-based esters often function as waxes, thickeners, or consistency agents in various formulations. Their solid state at room temperature offers specific textural and structural benefits.
- Gel:Gel forms of bio-based esters provide unique rheological properties, often used in personal care products and specialized industrial applications where controlled release or specific viscosity is required.
- Powder:Powdered bio-based esters are emerging for applications requiring dry blending, encapsulation, or targeted release. Their use is expanding in biodegradable polymer additives and specialized cosmetic powders for performance differentiation.
Liquid forms dominate current market consumption; Powder forms are evolving for specialized functional uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentration for bio-based esters is pronounced within specific geographic clusters. Germany's chemical manufacturing hubs and the US Midwest's agricultural processing centers drive significant consumption. Emerging markets in South America and Southeast Asia also present opportunities.
United States
The United States market benefits from demand for low-VOC solvents and personal care products. The US EPA's Safer Choice Standard promotes these sustainable alternatives. Agricultural processing hubs across the US Midwest supply critical feedstocks for methyl ester production.
Germany
German chemical manufacturers exhibit strong demand for bio-based esters as intermediates and in industrial lubricants. The EU Green Deal and REACH legislation incentivize the shift from petrochemicals. Major chemical manufacturing clusters, like Ludwigshafen, reformulate products to align with circularity principles.
France
France shows increasing uptake of bio-based esters within its prominent cosmetics and personal care sector. Regulatory pressures from the EU Green Deal and REACH accelerate reformulation. Formulators in the Île-de-France region prioritize sustainable ingredients for high-value cosmetic lines.
Brazil
Brazil represents a significant emerging market for bio-based esters, driven by its large agricultural sector and increasing environmental awareness. Evolving national environmental regulations create new opportunities. Agricultural processing centers in states like São Paulo expand feedstock availability for local ester production.
Indonesia
Indonesian producers benefit from abundant local palm oil feedstocks, positioning the country for increased bio-based ester production. National sustainability initiatives encourage biodegradable industrial solvents. Processing facilities in Sumatra and Kalimantan expand capacity to meet regional and international demand.
Global Bio Based Esters Market Key Industry Players
European chemical producers anchor one tier; US-based agricultural specialists hold another significant position within the global bio-based esters market. The market structure exhibits a tiered consolidation, with large multinational chemical companies and specialized bio-solvent manufacturers. Scale-driven players focus on high-volume methyl esters for industrial applications, while niche formulators target high-purity ethyl esters for personal care. Dominant competitive moves include strategic partnerships for feedstock security and continuous investment in advanced esterification technologies to improve yield and cost-competitiveness.
At the scale-driven end, BASF SE, a German chemical producer, exemplifies the multinational integration of bio-based esters into diverse product lines, serving multiple end-uses. Cargill Inc., a US-based agricultural processor, anchors the upstream value chain through its extensive feedstock sourcing capabilities and global distribution network. Vertec Bio-Solvents, a specialized North American manufacturer, represents the high-purity formulation segment, catering to niche industrial cleaning applications with tailored solutions.
| Leading Market Players |
|---|
| Cargill Inc. |
| Arkema Inc. |
| BASF SE |
| Vertec Bio-Solvents |
| Solvay |
| Huntsman Corporation |
| Spak Orgochem |
| Mangalam Organic Ltd. |
| Ester Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Advanced enzymatic catalysis, a named technology shift, simultaneously reshapes cost economics and supply concentration by enabling decentralized production and specialized, high-purity formulations. This innovation allows smaller producers to compete on performance rather than solely on scale, influencing pricing. It also creates new supply hubs closer to specialized feedstock sources or end-use markets.
Pricing Analysis
Volume-driven applications like methyl esters for chemical intermediates operate on commodity spot pricing, while specialized, high-purity ethyl esters for cosmetics command value-based pricing. Price differentiation stems from certification levels like the US EPA's Safer Choice Standard and the specific quality grade of the ester. Pricing softness reflects competition from established petrochemical alternatives, particularly in high-volume industrial segments. Chemical manufacturers exhibit the highest price sensitivity for bulk purchases, whereas personal care formulators prioritize performance and sustainability, showing less price sensitivity for specialized ingredients.
Supply Chain Analysis
National sustainability initiatives in countries like Indonesia, which encourage biodegradable industrial solvents, reshape sourcing by prioritizing local feedstock use. Geographic supply concentration for bio-based esters centers on agricultural hubs in the US Midwest and Southeast Asia, particularly for palm oil. Raw material dependencies include vegetable oils such as soy, palm, and rapeseed, alongside fatty acids and alcohols like methanol. Agricultural commodity price volatility represents a significant structural supply chain risk. Distribution runs through direct sales channels to large chemical manufacturers and specialized distributors serving niche industrial or personal care markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play, with intensifying regulatory mandates for petrochemical substitution placing pressure on smaller, less agile producers. Weaker players struggle to secure consistent feedstock or invest in advanced process technologies.
For Market Incumbents: To counter volatile agricultural feedstock costs, incumbents should deepen strategic partnerships with major agricultural processors for long-term supply agreements. Investing in advanced esterification technologies, such as continuous-flow reactors, improves yield and reduces energy consumption, enhancing cost-competitiveness against petrochemicals. Securing feedstock consistency through backward integration or long-term contracts is paramount for maintaining market share.
For New Entrants and Emerging Players: Begin with targeting high-value, niche applications where performance differentiation outweighs price sensitivity. Biodegradable polymer additives for PLA and PHA plastics, along with specialized cosmetic formulations, present significant white-space opportunities. A go-to-market angle focusing on high-purity, enzymatically produced esters for specific functional properties can attract formulators seeking performance differentiation in sustainable ingredients.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized bio-solvent manufacturers possessing proprietary process technologies or strong feedstock integration capabilities. The market demonstrates long-term viability, driven by global regulatory shifts towards bio-based materials and increasing consumer demand for sustainable products. A signal to watch is the expansion of circular economy principles, like those in the EU Green Deal, into major Asian and South American economies, indicating broader market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing methyl ester production in the US Midwest serves growing demand from chemical manufacturers. |
| Backward Integration | Securing captive supply of vegetable oils in Southeast Asia mitigates feedstock price volatility for ester producers. |
| Green Manufacturing Transition | Adopting enzymatic catalysis in Europe enables high-purity ester production for cosmetic and food applications. |
| Long-term Supply Agreement | Establishing stable fatty acid procurement ensures consistent input for personal care formulators. |
| Joint Venture | Developing biodegradable polymer additives with plastics companies creates new application categories. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market insights. Primary interviews engaged chemical plant managers, procurement leads from consumer goods companies, R&D directors in personal care, and agricultural feedstock suppliers. This approach combined bottom-up and top-down triangulation to validate market size and growth projections.
Granularity-level framing involved modeling market dynamics across product type, application, end-user, and key regional production hubs. Compound annual growth rates were derived through historical trend analysis, incorporating anticipated technological advancements and regulatory impacts over the projection horizon. Forecast inputs included agricultural feedstock price trends and evolving environmental policy changes, such as stricter VOC limits.
Underlying measurement precision varies by segment; industrial lubricants and methyl esters carry tighter precision than emerging applications like powdered bio-based esters. Forecasts reflect assumptions on technology adoption rates and evolving market dynamics. Geopolitical events affecting agricultural supply or sudden shifts in petrochemical pricing represent specific risk factors that could revise forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Stearates Market
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Monomethylsilanetriol Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Carnauba Wax Market
Specialty Chemicals
Organo-Modified Siloxanes Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Biodegradable Chelating Agents Market